
 Europe Textile Chemicals Market | 2026-2036
Europe Textile Chemicals Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Textile Chemicals Market Analysis
Modular formulation packaging is repositioning how textile manufacturers procure dyes and finishing agents, shifting bulk orders toward pre-blended, application-specific kits. Archroma leverages its specialty dyes portfolio to dominate premium apparel segments across Western Europe. CHT Group anchors its position through deep technical service ties to industrial textile producers in Germany and Switzerland. Huntsman Textile Effects competes on fluorine-free water repellency chemistry aligned with tightening environmental standards.
Europe textile chemicals encompass dyes, surfactants, coatings, and additives formulated for fiber processing, finishing, and functional performance enhancement, typically applied through padding, exhaust, or spray methods at controlled pH and temperature parameters. These substances impart colorfastness, durability, flame resistance, or antimicrobial properties to natural and synthetic substrates across apparel, home furnishing, and technical textile end uses. Dyes and coatings capture the largest value share, sustained by replacement demand in mature Western European markets, while technical textiles represent the fastest-expanding application as automotive interior specifications and medical barrier fabrics intensify functional chemical requirements. Water-soluble formulations lead volume consumption, though concentrated chemistries gain share as processors seek freight and storage efficiency.
REACH registration obligations and the EU Green Deal's chemical sustainability targets are forcing reformulation of azo dyes, perfluorinated compounds, and formaldehyde-based finishes, directly elevating R&D costs and reshaping supplier qualification criteria. ECHA substance restriction proposals and the EU Textile Strategy's circularity mandates further constrain permissible chemistries while creating market access barriers for non-compliant imports. Stakeholders must monitor evolving restricted substance lists and invest in bio-based precursor development to preserve supply relationships with major European apparel brands and technical textile OEMs.
Market Dynamics
REACH substance restrictions and the EU Green Deal's chemical sustainability targets are forcing wholesale reformulation of azo dyes, perfluorinated compounds, and formaldehyde-based finishes across European textile chemical supply chains.
Growth Catalysts
- Automotive Interior Specifications:Technical textile demand for flame-retardant and antimicrobial cabin fabrics is expanding chemical consumption across Germany's vehicle manufacturing belt.
- EU Green Deal Mandates:The EU Textile Strategy's circularity requirements are accelerating bio-based precursor development among compliant suppliers.
- Digital Textile Printing:Water-based inkjet dye systems are displacing conventional rotary screen methods in Italian fashion manufacturing clusters.
Market Restraints
- Petrochemical Feedstock Volatility:Naphtha and benzene derivative costs swing unpredictably, compressing margin stability for European dye manufacturers.
- ECHA Registration Burden:REACH compliance costs for novel substances create disproportionate barriers for mid-scale specialty chemical producers.
- Perfluorinated Compound Phase-Out:C6 and C8 fluorocarbon water repellents face accelerating substitution pressure from silicone and hydrocarbon alternatives.
Strategic Opportunities
- Medical Barrier Fabrics:Antimicrobial and fluid-resistant finishing chemistry for surgical gowns and drapes represents underpenetrated demand in Turkey's growing technical textile sector.
- CSRD Reporting Alignment:The Corporate Sustainability Reporting Directive creates first-mover advantage for chemical suppliers offering verified lifecycle data to apparel brands.
- Modular Formulation Kits:Pre-blended, application-specific dye and finishing packages are opening direct supply relationships with small-batch textile processors bypassing traditional distributors.
Industry Challenges
- Formulation Chemist Scarcity:Expertise in bio-based polymer synthesis and enzymatic finishing processes remains concentrated among aging specialist workforces in Germany and Switzerland.
- Legacy Equipment Retrofit Costs:Exhaust dyeing vessels and padding lines require capital-intensive modification to handle low-liquor ratio and supercritical CO2 processing chemistries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Textile Chemicals Market |
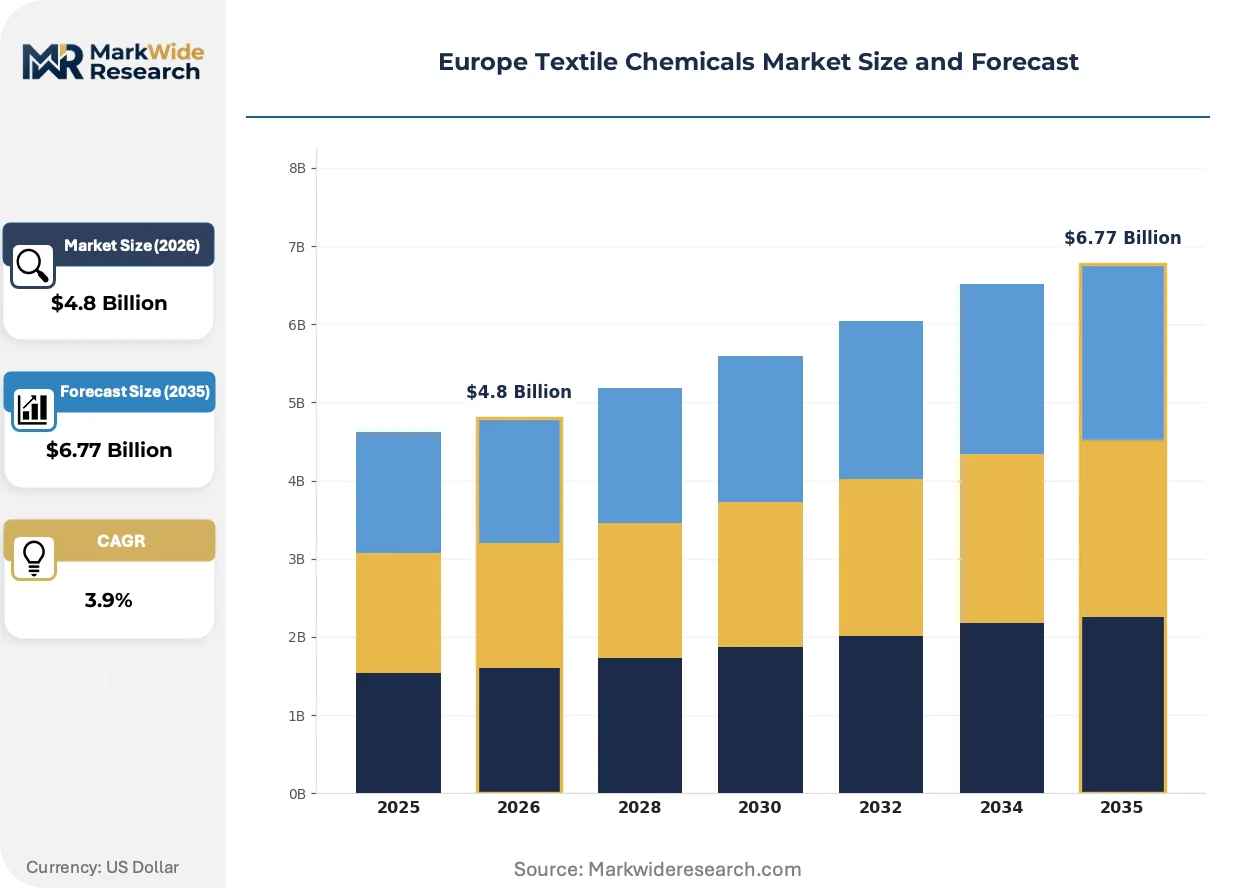
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.77 Billion |
| CAGR (2026 – 2036) | 3.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dyes, Surfactants, Coatings, Additives Application: Apparel, Home Furnishing, Technical Textiles, Industrial Textiles End User: Textile Manufacturers, Apparel Brands, Retailers, Distributors Formulation: Water-Soluble, Powdered, Concentrated, Granulated |
| Companies Covered | Archroma, CHT Group, Huntsman Textile Effects, BASF SE, Evonik Industries, Wacker Chemie AG, Rudolf GmbH, DyStar Group, Lanxess AG, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Textile Chemicals Market Emerging Trajectories
Digital formulation platforms and closed-loop chemical recovery systems are compressing traditional supply relationships while elevating transparency requirements across European textile processing value chains.
Supercritical carbon dioxide dyeing technology is electrifying coloration processes by eliminating water consumption entirely. Automotive seating manufacturers in Germany and medical textile producers in Switzerland are piloting these systems at commercial scale. The technology is electrifying competitive positioning by decoupling dyehouse operations from wastewater treatment infrastructure and regional water scarcity constraints.
REACH authorization requirements for Substances of Very High Concern are tightening entry criteria for chromium-based mordants and certain disperse dye categories. Chemical suppliers must now submit comprehensive substitution plans or cease importation into EU manufacturing zones. Italian wool finishers and Portuguese denim processors are most affected, accelerating partnerships with bio-mordant developers to preserve supply relationships with pan-European apparel brands.
Textile processors are consolidating chemical procurement through platform-based tendering systems that benchmark formulation performance against total cost-in-use metrics. Small and mid-scale dye houses in Turkey and Eastern Europe are displacing long-term supplier contracts with spot purchasing through these digital marketplaces. The shift is most visible in commodity disperse and reactive dye categories where specification standardization enables direct price competition.
Europe Textile Chemicals Market Segmentation
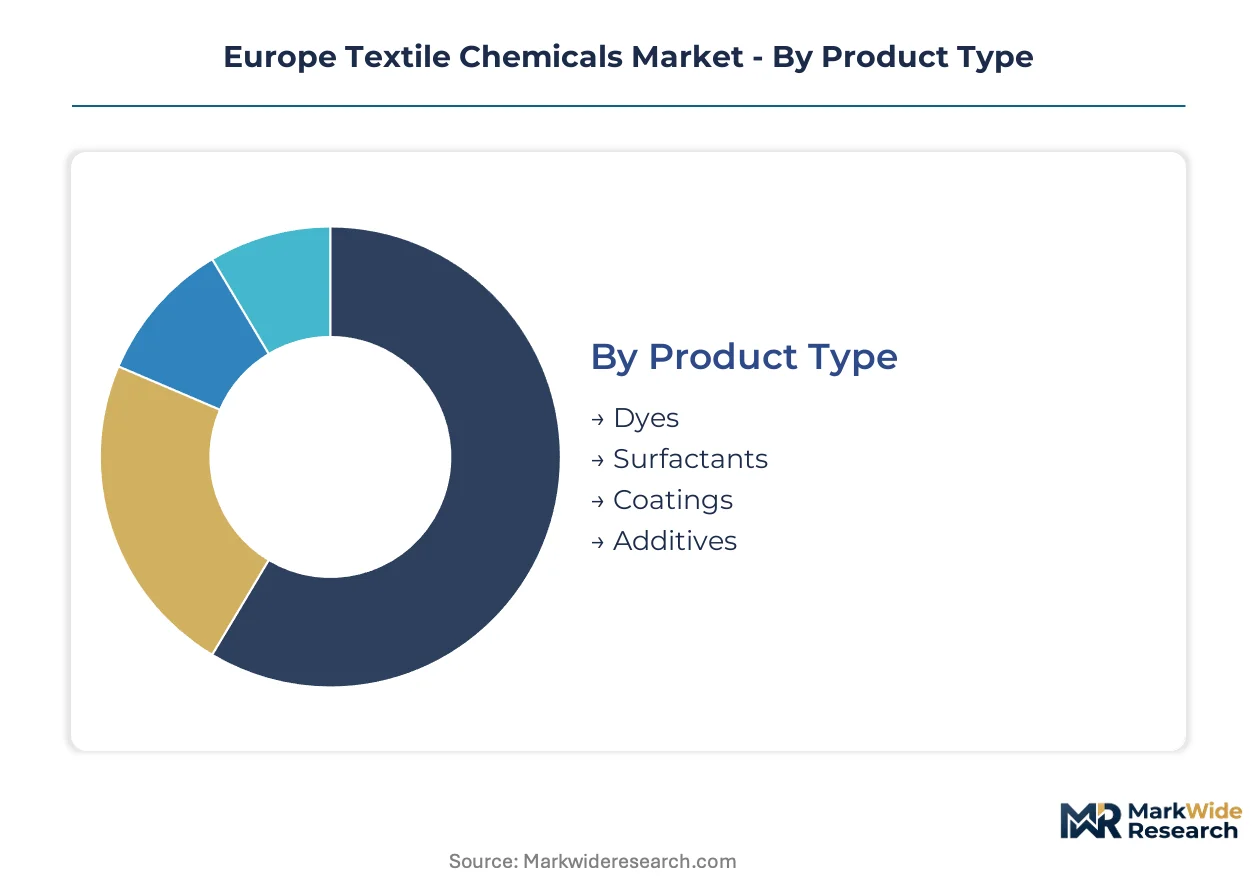
Segmentation reveals where capital deployment and regulatory compliance burdens concentrate across European textile chemical value chains. Product formulation choices directly determine REACH registration obligations and water treatment infrastructure requirements for processors.
Product Type:
Capital intensity peaks in coating synthesis facilities requiring explosion-proof reactors and solvent recovery systems, while dye manufacturing demands substantial wastewater treatment investment.
- Coatings:Polymer-based protective films and functional layers applied through padding or exhaustion methods. German automotive textile suppliers in Baden-Württemberg drive flame-retardant and antimicrobial coating specifications for seating and interior panels. REACH restrictions on perfluorinated compounds are forcing reformulation of water-repellent coating chemistries toward silicone and hydrocarbon alternatives.
- Dyes:Chromophoric compounds formulated for exhaust, padding, or digital inkjet application across natural and synthetic fiber substrates. Italian fashion manufacturing clusters around Como and Biella sustain premium reactive and acid dye consumption despite rotary screen displacement by digital printing systems. ECHA authorization requirements for chromium-based mordants are accelerating bio-based precursor partnerships among wool finishers.
- Surfactants:Wetting agents, emulsifiers, and dispersants enabling uniform chemical distribution in aqueous processing baths. Turkey's expanding denim washing sector imports substantial surfactant volumes for enzyme-based finishing.
- Additives:Performance enhancers including UV stabilizers, softeners, and anti-static agents. Swiss technical textile producers specify additive packages for medical barrier fabric certification.
Most installed capacity flows through Dyes. Expansion is steepest in Coatings.
Application:
Application mix determines customer concentration and contract duration, with technical textiles commanding multi-year supply agreements versus spot purchasing in apparel.
- Technical Textiles:Functional fabrics engineered for performance criteria rather than aesthetics, spanning automotive interiors, medical barriers, and industrial filtration. German vehicle manufacturers specify flame-retardant cabin fabrics meeting ECE R118 standards. Medical textile demand in Switzerland and Turkey for surgical gowns and drapes intensifies antimicrobial and fluid-resistant finishing requirements.
- Apparel:Fashion and basic clothing applications where colorfastness and hand feel drive chemical selection. Portuguese denim processors and Italian luxury knitwear producers represent fragmented, price-sensitive demand pools.
- Home Furnishing:Upholstery, curtains, and bedding textiles requiring durability and stain resistance. Polish and Romanian upholstery manufacturers supply Western European furniture brands.
- Industrial Textiles:Geotextiles, conveyor belts, and filtration media where chemical resistance and dimensional stability predominate. Mining and construction applications concentrate in Eastern European manufacturing zones.
Technical Textiles command the highest formulation premiums. Apparel delivers the largest absolute volume.
End User:
End-user structure shapes distribution economics, with direct supply relationships to large textile manufacturers displacing traditional distributor channels for standardized chemistries.
- Textile Manufacturers:Integrated fiber-to-fabric processors operating dyeing and finishing facilities. Germany's industrial textile belt and Turkey's growing technical textile sector represent concentrated demand nodes with substantial chemical procurement leverage.
- Apparel Brands:Design houses and retail labels specifying chemical inputs through restricted substance lists and sustainability certifications. ZDHC compliance requirements from major European fashion brands are filtering supplier qualification criteria.
- Retailers:Mass-market chains and specialty stores influencing upstream chemical standards through private label specifications. Nordic retailers enforce stringent chemical safety protocols exceeding baseline REACH requirements.
- Distributors:Chemical traders and technical service providers maintaining regional inventory and blending operations. Eastern European distributors face margin compression from platform-based tendering systems.
Textile Manufacturers absorb the majority of volume. Apparel Brands are gaining specification authority fastest.
Formulation:
Formulation choice determines freight economics, storage requirements, and dosing precision at the processing line.
- Water-Soluble:Liquid preparations dispersing readily in aqueous processing baths without pre-dissolution. Standard for continuous dyeing ranges and exhaust applications across Western European wet processing facilities with established wastewater treatment infrastructure.
- Concentrated:High-strength liquid or paste formulations reducing transport volumes and storage footprints. Gaining share among Turkish and Eastern European processors seeking logistics efficiency.
- Powdered:Solid granular preparations requiring dissolution prior to application. Remains economical for commodity reactive dyes in high-volume apparel processing.
- Granulated:Low-dust solid forms improving handling safety and dosing accuracy. Preferred for automated dispensing systems in German technical textile operations.
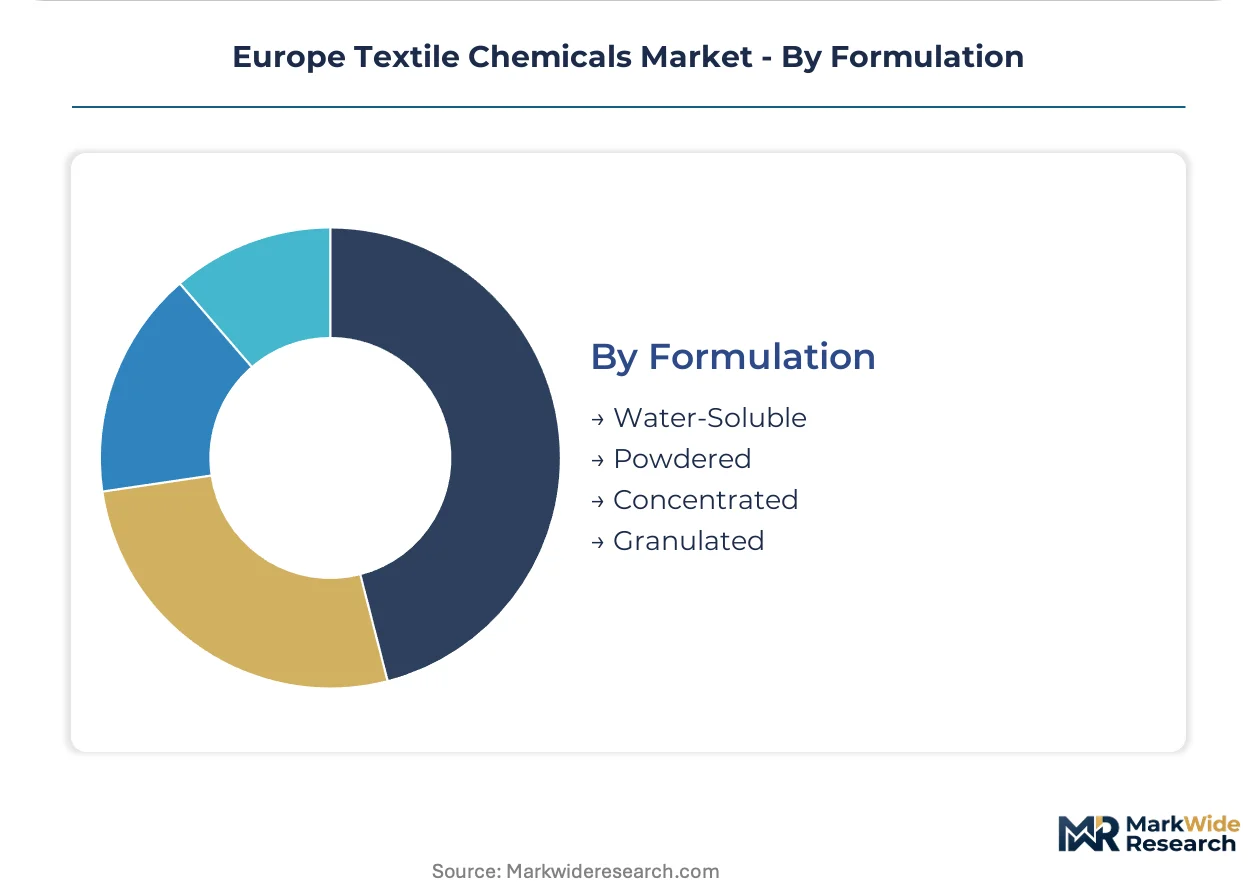
Water-Soluble formulations dominate current installed base. Concentrated chemistries are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Textile chemical manufacturing in Europe traces its modern lineage to German industrialization of synthetic dye synthesis in the late 19th century. Basel's chemical corridor and the Ruhr industrial belt established the continent's foundational production infrastructure. Contemporary demand concentrates in manufacturing clusters tied to automotive supply chains, technical medical textiles, and fashion production centers.
Germany
Automotive interior specifications from BMW, Mercedes-Benz, and Volkswagen drive flame-retardant and antimicrobial coating consumption across Baden-Württemberg and Lower Saxony. The EU Green Deal's chemical sustainability targets force reformulation of perfluorinated water repellents in Stuttgart-area technical textile operations. REACH authorization requirements for chromium-based mordants are accelerating bio-based precursor partnerships among wool finishers in the Biella-Como corridor supply chain.
Italy
Luxury fashion manufacturing around Como and Biella sustains premium reactive and acid dye demand despite rotary screen displacement by digital inkjet systems. ECHA substance restriction proposals constrain azo dye formulations used in Lombardy's silk and wool processing heritage. The Veneto region's denim finishing cluster imports substantial surfactant volumes for enzyme-based stone washing and laser finishing alternatives.
Turkey
Technical textile expansion for automotive and medical applications concentrates chemical demand in Bursa and Istanbul's industrial zones. REACH-equivalent KKDIK registration obligations create compliance barriers for imported formulations serving denim washing and home furnishing exporters. The country's national chemical regulator enforces alignment with EU restricted substance lists to preserve customs union market access for textile manufacturers.
Switzerland
Medical barrier fabric producers around Zurich and Basel specify additive packages meeting stringent antimicrobial and fluid-resistant certification requirements. Swissmedic and federal chemical safety offices coordinate with ECHA on substance authorization timelines affecting textile finishing chemistry. The Basel chemical corridor maintains specialty coating synthesis for technical textile OEMs serving German automotive and Swiss medical device manufacturers.
Poland
Upholstery and home furnishing textile manufacturing in Łódź and Silesia supplies Western European furniture brands with stain-resistant and durability-enhancing chemical finishes. The country's environmental inspectorate enforces REACH-aligned wastewater discharge standards for wet processing facilities. Polish distributors face margin compression from platform-based tendering systems displacing long-term chemical supply contracts.
Europe Textile Chemicals Market Vendor Landscape
The competitive structure tilts toward integrated specialty chemical conglomerates with deep technical service capabilities. Three tiers populate the vendor base: multinational diversified chemical groups with textile divisions, mid-scale European specialists with regional formulation expertise, and niche technology licensors focused on single-process innovations. M&A activity concentrates on acquiring bio-based precursor platforms and digital formulation software capabilities. Strategic partnerships between chemical suppliers and textile machinery OEMs are locking in process chemistry specifications.
Within the specialty chemical tier, Archroma, CHT Group, and Huntsman Textile Effects exemplify distinct competitive positioning archetypes. Archroma represents the premium dye and finishing specialist with heritage Swiss technical service depth. CHT Group anchors the German-speaking industrial textile segment through captive supply relationships with machinery-integrated process systems. Huntsman Textile Effects occupies the sustainability-transition vector, reformulating fluorine-free water repellency chemistry aligned with tightening ECHA restrictions. These three entities collectively demonstrate how European textile chemical competition fragments across application-specific expertise rather than consolidating around commodity scale.
| Leading Market Players |
|---|
| Archroma |
| CHT Group |
| Huntsman Textile Effects |
| BASF SE |
| Evonik Industries |
| Wacker Chemie AG |
| Rudolf GmbH |
| DyStar Group |
| Lanxess AG |
| Others |
Supply Flow & Price Mechanics
Automotive OEM procurement offices in Stuttgart and Munich anchor pricing power through multi-year technical textile supply agreements that index formulation costs to petrochemical feedstock baskets. REACH compliance investments and bio-based precursor development costs flow directly into contract pricing, while spot purchasers in Turkish denim washing face volatile surfactant quotations tied to naphtha derivative movements.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates Swiss-certified medical barrier additives from commodity reactive dyes and unbranded surfactant blends. Price differentiation hinges on ZDHC compliance certification and volume scale, with premium tiers capturing automotive interior specifications. Cost compression in standard dye categories is intensifying because Turkish processors are consolidating procurement through digital tendering platforms. Apparel brands demonstrate highest price sensitivity, while German technical textile OEMs prioritize performance guarantees over unit economics.
Supply Chain Analysis
REACH authorization and KKDIK alignment requirements gate market access, forcing non-EU suppliers to establish EU-based formulation facilities or surrender share to compliant domestic producers. Manufacturing concentrates in Germany, Switzerland, and Turkey, with raw material dependencies on naphtha derivatives, benzene intermediates, and bio-based polymer precursors. Single-source vulnerability runs through Chinese disperse dye intermediates subject to EU anti-dumping scrutiny. Distribution runs through machinery-integrated technical service partnerships for automotive OEMs and platform-based spot purchasing for apparel processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe textile chemicals constitute a late-cycle quality story as automotive interior specifications and medical barrier fabric certifications elevate premium formulation demand above commodity replacement cycles. The shift from rotary screen to digital inkjet printing in Italian fashion manufacturing concentrates value capture among suppliers with water-based inkjet dye expertise.
For Market Incumbents: Cement technical service relationships with German automotive textile suppliers through co-development of flame-retardant coating specifications aligned with ECE R118 standards. Expand captive supply arrangements with Swiss medical barrier fabric producers to defend against Huntsman Textile Effects' fluorine-free water repellency positioning. Prioritize backward integration into bio-based precursor synthesis to offset petrochemical feedstock volatility.
For New Entrants and Emerging Players: Digital formulation platforms offering closed-loop chemical recovery analytics represent the most penetrable wedge into established supply relationships. Target Turkey's expanding technical textile sector for antimicrobial finishing chemistry partnerships with Bursa-based automotive suppliers. Pursue direct supply relationships with small-batch processors through modular formulation kits bypassing traditional distributor markups.
For Investors and Strategic Acquirers: Specialty chemical conglomerates with textile divisions are the most active acquirers in this space, seeking bio-based precursor platforms and enzymatic finishing process IP. Long-term viability favors suppliers with verified lifecycle data alignment to CSRD reporting requirements and machinery-integrated process chemistry specifications. Watch ECHA substance restriction proposal timelines for chromium-based mordants as inflection indicators for bio-mordant developer valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bio-Based Precursors | Reduces REACH registration exposure while securing supply relationships with ZDHC-compliant apparel brands. |
| Long-term Supply Agreement with Automotive OEM | Locks in multi-year coating volumes indexed to ECE R118 specification updates from Stuttgart manufacturers. |
| Joint Venture for Supercritical CO2 Dyeing Scale-Up | Positions partners ahead of wastewater treatment infrastructure constraints in water-scarce manufacturing zones. |
| Acquisition of Digital Formulation Platform | Captures procurement consolidation trend among Turkish and Eastern European spot-purchasing processors. |
| Green Manufacturing Transition Certification | Aligns supplier qualification criteria with EU Green Deal circularity mandates and CSRD disclosure requirements. |
Methodological Framework
Direct dialogue with technical R&D directors at specialty chemical manufacturers, procurement leads at German automotive textile suppliers, plant managers in Italian fashion manufacturing clusters, and distribution channel partners across Eastern Europe grounded qualitative assessment. Secondary validation drew from ECHA substance restriction proposals, Cefic chemical industry reports, SEC 10-K filings of listed specialty chemical groups, and customs data on dye and surfactant trade flows. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators across European manufacturing output.
Projected value trajectories across the analysis window reflect demand elasticity modeling by application segment, regulatory compliance cost pass-through coefficients, and substitution dynamics between conventional and bio-based formulations. Segmentation dimensions encompassed product type, end-use industry, formulation concentration, and regional production hub. CAGRs were derived from weighted average of historical growth patterns and forward-looking capacity expansion announcements. Forecast inputs incorporated automotive production schedules from BMW and Volkswagen, plus medical textile certification timelines from Swissmedic.
The model holds under stable REACH authorization timelines and continued EU-Turkey customs union alignment; deviation in ECHA substance restriction acceleration or KKDIK enforcement intensity would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Global Photoresist Chemicals Market
Chemicals
Hydrogenated Dimer Acid Market
Chemicals
Global Cresols Market
Chemicals
Nonanoic Acid Market
Chemicals
Lime Sulfur Market
Chemicals
Biphenyltetracarboxylic Dianhydride Market
Chemicals
Spirodiclofen Market
Chemicals
Amyl Nitrite Market
Chemicals
RO Membrane Chemicals Market
Chemicals
Global Lactate Salts Market
Chemicals
Ferric Oxide Market
Chemicals
Household Insecticides Market
Chemicals
Methyldiisopropanolamine Market
Chemicals
Heptaldehyde Market
Chemicals
Trichloroisocyanuric Acid Market
Chemicals
Natural Fatty Alcohols Market