
 Silver Sulfate Market | 2026-2036
Silver Sulfate Market Size, Share, and Industry Trends Forecast 2026-2036
Silver Sulfate Market Analysis
ISO 9001 quality management certification is unwinding competitive access for smaller silver sulfate suppliers unable to document batch-level traceability. Merck KGaA leverages its integrated reagent portfolio to dominate laboratory-grade supply chains. Thermo Fisher Scientific Inc. anchors North American distribution through direct sales channels serving academic institutions. American Elements specializes in high-purity crystal production for semiconductor electroplating applications.
Silver sulfate is an inorganic compound with the formula Ag₂SO₄, typically synthesized through the reaction of silver nitrate with sulfuric acid or sodium sulfate, yielding a white crystalline solid that decomposes at 1085°C and exhibits low solubility in water. The compound serves primarily as an oxidizing agent, electroplating bath constituent, and analytical reagent across industrial and research settings. Silver sulfate powder commands the largest product type share due to its handling convenience in bulk chemical processing, while silver sulfate solution is gaining traction in automated electroplating lines where precise concentration control reduces waste. Among applications, electroplating generates the deepest margin pools as electronics manufacturers specify ultra-high-purity grades for connector and contact fabrication.
EPA oversight of silver discharge limits shapes wastewater treatment requirements for electroplating facilities using silver sulfate, while REACH registration mandates in Europe compel full toxicological dossiers for import authorization. OSHA permissible exposure limits for silver compounds influence workplace handling protocols and personal protective equipment specifications across manufacturing and laboratory end users. Stakeholders must monitor evolving semiconductor fabrication subsidies and associated purity requirements as these policy instruments redirect demand toward certified suppliers capable of sub-ppm impurity documentation.
Market Dynamics
Semiconductor fabrication subsidies in China are compressing supply timelines for ultra-high-purity silver sulfate, forcing electroplating chemical suppliers to accelerate batch certification cycles from months to weeks.
Growth Catalysts
- REACH Registration Mandates:ECHA's full toxicological dossier requirements for import authorization are filtering out uncertified competitors, consolidating demand among documented suppliers capable of sub-ppm impurity traceability.
- Silver Sulfate Solution Adoption:Automated electroplating lines in connector manufacturing are specifying liquid delivery formats for precise concentration control, reducing chemical waste and rework rates.
- Domestic Semiconductor Scaling:China's NMPA-aligned fabrication incentives are expanding captive consumption of high-purity plating chemicals for advanced node production.
Market Restraints
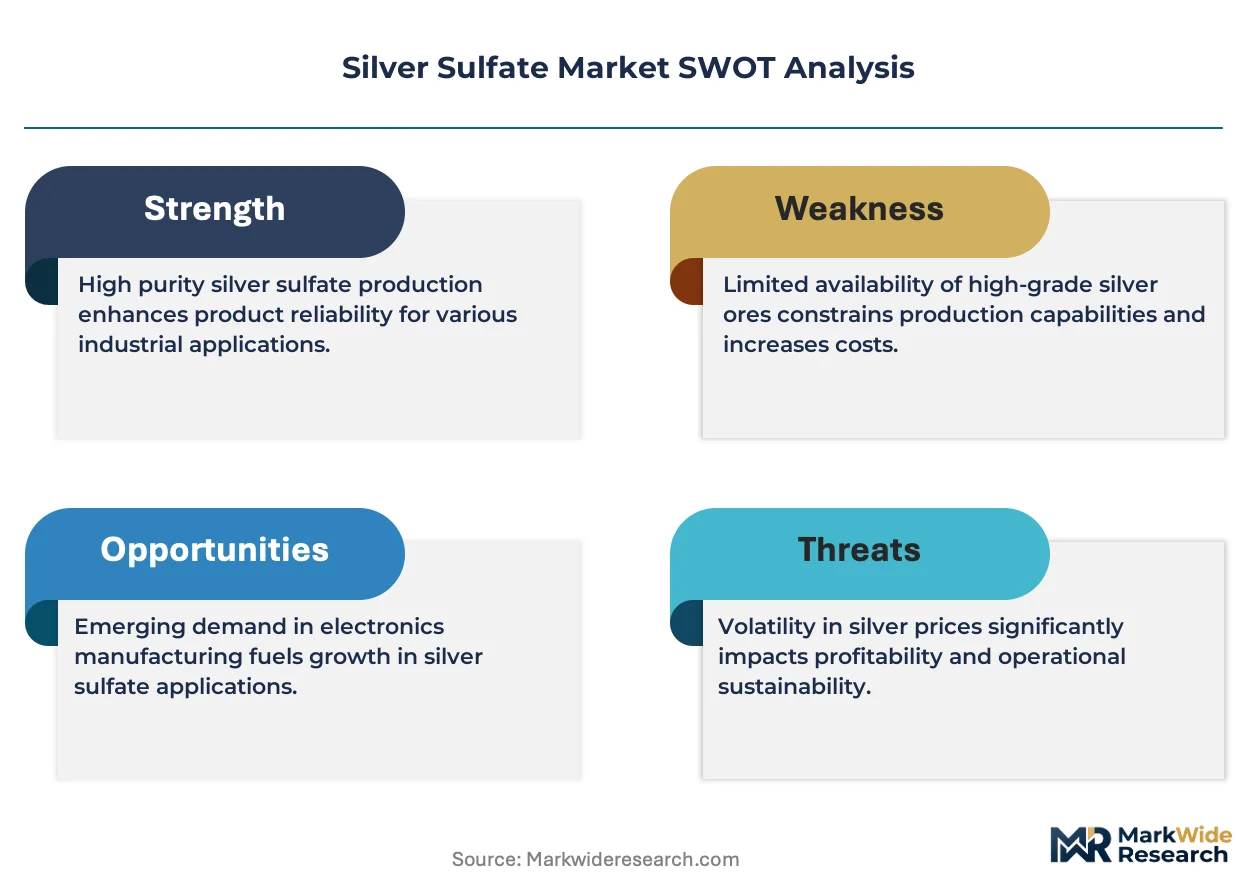
- Silver Price Volatility:London Bullion Market Association spot pricing fluctuations directly compress margin pools for electroplating bath operators locked into annual supply contracts.
- ISO 9001 Documentation Burden:Batch-level traceability requirements impose fixed compliance costs that disproportionately burden smaller crystal production specialists.
- Substitution Pressure from Silver Cyanide:Legacy connector plating facilities in cost-sensitive automotive supply chains continue specifying cyanide-based baths for thick deposit applications.
Strategic Opportunities
- India PLI Scheme Alignment:India's production-linked incentive framework for electronics manufacturing is attracting electroplating chemical distributors to establish localized blending facilities.
- Closed-Loop Recovery Systems:EPA silver discharge limits are creating aftermarket service revenue streams for wastewater treatment integrators serving plating facilities.
- Academic Direct Distribution:Laboratory-grade silver sulfate procurement is bypassing traditional chemical distributors through manufacturer-direct portals serving research institutions.
Industry Challenges
- Analytical Chemist Scarcity:ICP-MS operators capable of validating sub-ppm impurity specifications command premium wages, constraining quality control throughput at mid-scale producers.
- Legacy ERP Integration:Batch-level serialization systems required for REACH compliance are forcing manual workarounds at facilities running pre-2010 manufacturing execution software.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Silver Sulfate Market |
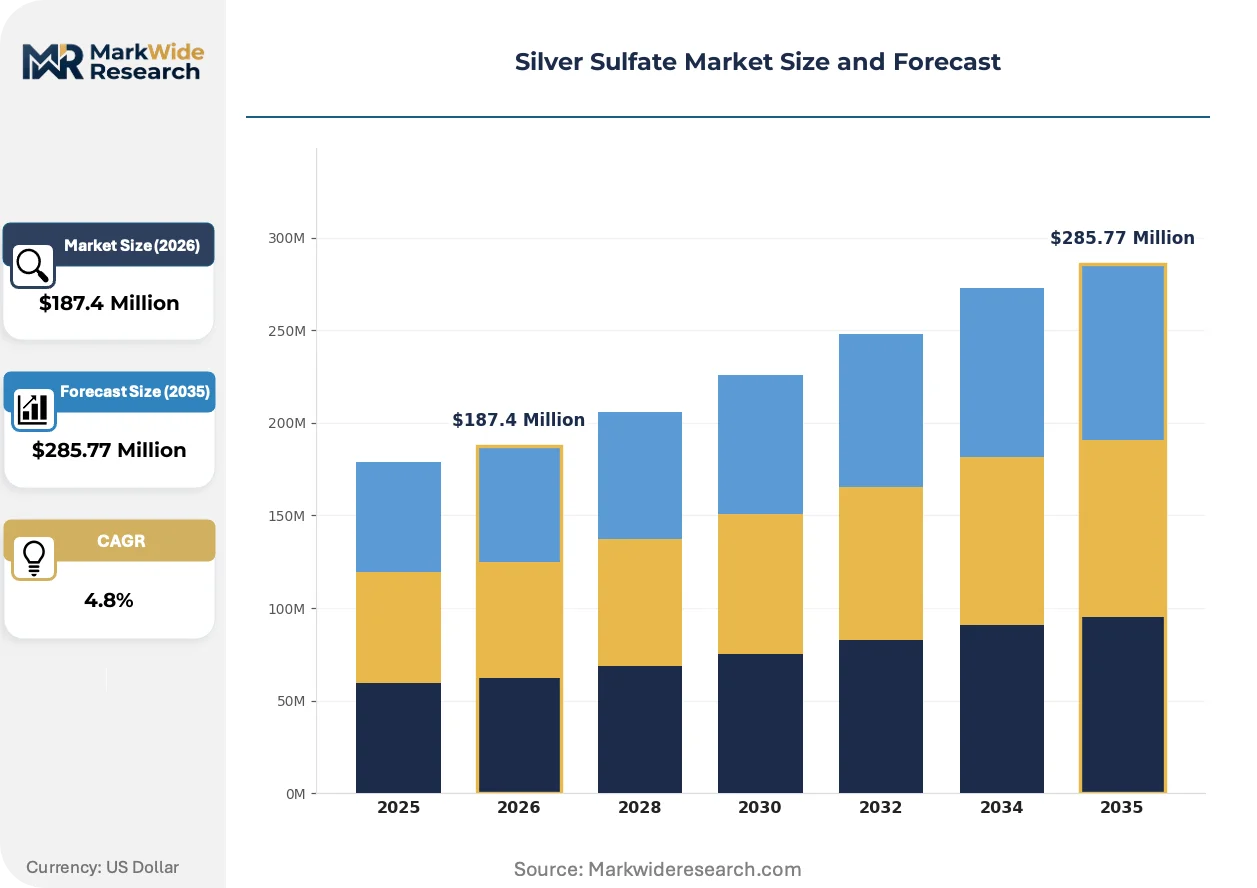
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silver Sulfate Crystals, Silver Sulfate Powder, Silver Sulfate Solution, Silver Sulfate Coating Application: Electroplating, Photography, Antiseptic, Chemical Reagent End User: Healthcare, Manufacturing, Laboratory, Academic Institutions Distribution Channel: Online Retail, Direct Sales, Distributors, Wholesalers |
| Companies Covered | Merck KGaA, Thermo Fisher Scientific Inc., American Elements, Honeywell Research Chemicals, Avantor Inc., Schwitz Biotech, Silvershine Chemicals, Modison Metals Ltd., Jiodine Chemical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Silver Sulfate Market Emerging Trajectories
Electroplating chemistry is pivoting from commodity bulk supply toward specification-driven partnership models, with purity documentation and regulatory pre-certification becoming primary competitive differentiators ahead of price.
Membrane electrolysis recovery systems are decomposing traditional silver waste disposal economics for high-volume plating operations. Connector manufacturers in Germany's automotive supply chain are adopting these units to convert spent bath solutions into reclaimable metal feedstock. The technology is decomposing the historical separation between chemical supplier and precious metal recycler, compressing the effective supply chain into single-source accountability structures.
EPA's revised silver discharge limits under the Clean Water Act are mandating zero-liquid-discharge configurations for new electroplating facility permits. Plating operators in Ohio and Michigan are retrofitting evaporative crystallizers to meet these thresholds ahead of compliance deadlines. The regulatory pressure is accelerating capital deployment toward closed-loop infrastructure, particularly among job shops serving aerospace connector specifications.
Specification-driven procurement contracts are displacing spot-market purchasing for ultra-high-purity grades. Electronics OEMs in South Korea's semiconductor cluster are locking three-year supply agreements with embedded purity escalation clauses. The contractual shift is most visible among MEMS device manufacturers where traceability documentation supports downstream customer audit requirements.
Silver Sulfate Market Segmentation
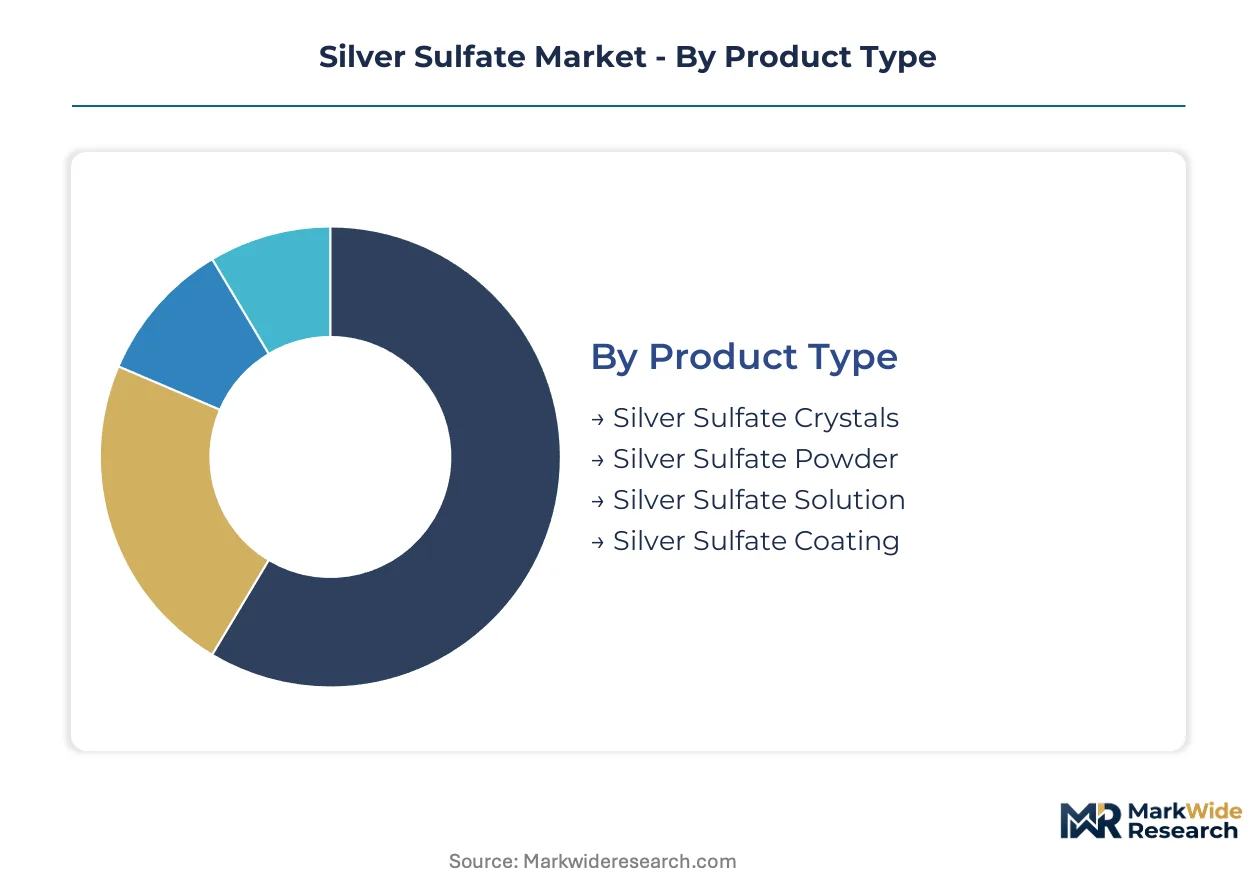
Silver sulfate procurement patterns diverge sharply across product formats and end-use specifications. Purity grades and handling requirements create distinct margin architectures that reward specialized suppliers over commodity distributors.
Product Type:
Margin pools concentrate in formats offering handling efficiency and concentration precision for automated process integration.
- Silver Sulfate Powder:White crystalline solid produced through silver nitrate-sulfuric acid precipitation, commanding the largest volume share due to bulk chemical processing convenience. Demand concentrates in electroplating facilities across China's semiconductor fabrication corridor where powder handling infrastructure already exists for legacy bath preparation.
- Silver Sulfate Solution:Pre-dissolved aqueous formulation enabling precise concentration control in automated plating lines. Connector manufacturers in South Korea's electronics cluster specify liquid delivery formats to minimize chemical waste and reduce rework rates from concentration drift.
- Silver Sulfate Crystals:High-purity monoclinic crystal structures serving analytical reagent specifications with documented batch traceability.
- Silver Sulfate Coating:Thin-film deposition formats for specialized antimicrobial surface treatments in medical device applications.
The dominant share belongs to Silver Sulfate Powder, while Silver Sulfate Solution is closing the gap fastest.
Application:
End-use specifications stratify around purity documentation requirements and regulatory exposure intensity.
- Electroplating:Bath constituent for connector, contact, and semiconductor lead-frame fabrication requiring sub-ppm impurity documentation. Electronics OEMs in Germany's automotive supply chain lock multi-year contracts with embedded purity escalation clauses to satisfy downstream audit requirements.
- Chemical Reagent:Analytical-grade oxidizing agent for laboratory quality control and research protocols. Academic institutions in North America bypass traditional distributors through manufacturer-direct procurement portals to secure ISO 9001-certified batch documentation.
- Photography:Legacy emulsion chemistry application facing substitution pressure from digital imaging technologies.
- Antiseptic:Medical-grade silver ion release formulations for wound care and coating applications subject to FDA device classification requirements.
Electroplating generates the deepest margin pools, though Chemical Reagent procurement is expanding most quickly through direct distribution channels.
End User:
Customer sophistication determines willingness to absorb certification premiums and long-term contract structures.
- Manufacturing:Electronics fabrication and connector production facilities specifying REACH-compliant supply chains with full toxicological dossiers. China's domestic semiconductor scaling under NMPA-aligned incentives is compressing supplier certification timelines from months to weeks.
- Laboratory:Research institutions and quality control facilities requiring documented traceability for analytical method validation. Thermo Fisher Scientific anchors North American supply through direct sales channels serving academic end users with embedded technical support.
- Healthcare:Medical device manufacturers and pharmaceutical formulators subject to FDA oversight and antimicrobial claim substantiation.
- Academic Institutions:University research programs with decentralized procurement authority and price-sensitive volume requirements.
Manufacturing commands the dominant revenue position, while Laboratory procurement is gaining share fastest through specification-driven partnership models.
Distribution Channel:
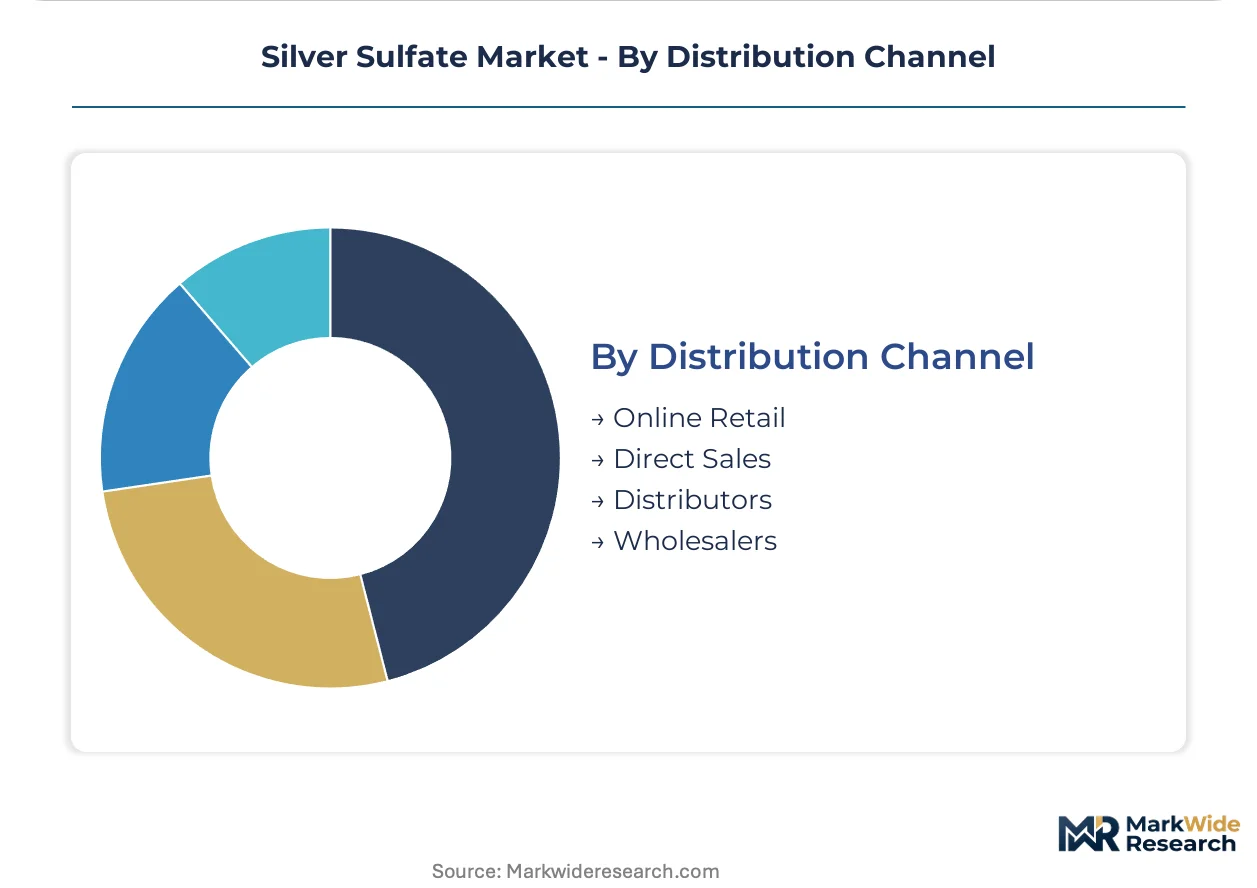
Channel economics reflect customer scale, technical service requirements, and regulatory documentation burdens.
- Direct Sales:Manufacturer-to-end-user relationships for high-purity grades with embedded technical consultation and batch certification. Merck KGaA leverages integrated reagent portfolios to dominate laboratory-grade supply chains through dedicated account management.
- Distributors:Regional chemical distributors serving mid-scale plating facilities with inventory buffering and localized logistics. India's PLI scheme for electronics manufacturing is attracting distributors to establish localized blending facilities near emerging fabrication clusters.
- Online Retail:E-commerce platforms for standard-grade laboratory quantities with expedited fulfillment and transparent pricing.
- Wholesalers:Bulk volume aggregation for commodity-grade applications with minimal technical service requirements.
Direct Sales holds the dominant position, though Distributors are expanding most quickly through regional blending investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's NMPA-aligned semiconductor fabrication subsidies are redirecting regional procurement patterns toward ultra-high-purity grades. Electroplating chemical suppliers face compressed certification timelines as domestic wafer production scales.
China
Yangtze River Delta fabrication clusters drive concentrated consumption of plating-grade silver sulfate. MEE discharge standards for electroplating wastewater force zero-liquid-discharge retrofits in Suzhou and Wuxi job shops. Shenzhen connector manufacturers specify REACH-equivalent purity documentation for export-bound semiconductor components.
United States
EPA Clean Water Act silver discharge limits mandate closed-loop recovery systems for new plating permits. Ohio and Michigan aerospace connector suppliers retrofit evaporative crystallizers ahead of compliance deadlines. Greater Boston laboratory procurement bypasses distributors through manufacturer-direct portals.
Germany
Automotive supply chain electroplaters adopt membrane electrolysis recovery to convert spent baths into reclaimable feedstock. ECHA REACH registration filters uncertified competitors from import channels. Bavarian connector manufacturers lock multi-year supply agreements with embedded purity escalation clauses.
South Korea
Seoul Capital Area MEMS device manufacturers drive specification-driven procurement with three-year supply contracts. MFDS oversight of medical-grade antimicrobial applications tightens documentation requirements. Busan-Ulsan electronics clusters specify liquid delivery formats for automated plating line integration.
India
PLI scheme incentives for electronics manufacturing attract electroplating chemical distributors to establish localized blending facilities. BIS quality certification requirements filter laboratory-grade imports. Maharashtra and Gujarat fabrication corridors scale silver sulfate consumption for smartphone component plating.
Silver Sulfate Market Vendor Landscape
Player mix skews toward diversified chemical conglomerates with integrated reagent portfolios. Consolidation pressure intensifies as REACH documentation burdens and ISO 9001 certification requirements filter smaller crystal specialists. Three archetypes dominate: integrated life science conglomerates leveraging cross-portfolio account management, regional distributors establishing localized blending capacity, and high-purity crystal specialists serving semiconductor electroplating. Competitive moves concentrate on strategic partnerships for closed-loop recovery integration and geographic expansion through distributor acquisition.
Within the integrated conglomerate tier, Merck KGaA and Thermo Fisher Scientific Inc. exemplify portfolio-driven market access. Merck KGaA anchors European laboratory-grade supply chains through dedicated account management structures. Thermo Fisher Scientific Inc. occupies a parallel position in North American distribution via direct sales channels serving academic end users. American Elements represents the high-purity specialization archetype, with crystal production capabilities aligned to semiconductor electroplating specifications.
| Leading Market Players |
|---|
| Merck KGaA |
| Thermo Fisher Scientific Inc. |
| American Elements |
| Honeywell Research Chemicals |
| Avantor Inc. |
| Schwitz Biotech |
| Silvershine Chemicals |
| Modison Metals Ltd. |
| Jiodine Chemical |
| Others |
Supply Flow & Price Mechanics
REACH registration mandates gate both supply qualification and price differentiation simultaneously, filtering uncertified competitors from European import channels while embedding purity documentation premiums into contract structures. ECHA toxicological dossier requirements impose fixed compliance costs that stratify the supplier base between documented batch-traceability providers and commodity-grade alternatives, compressing margin pools for electroplating bath operators unable to pass certification premiums downstream.
Pricing Analysis
Certification level creates the primary spread between laboratory-grade and industrial-grade supply tiers, with ISO 9001-documented batches commanding substantial premiums over standard crystalline formats. Contract-based long-term offtake structures dominate ultra-high-purity procurement, particularly among South Korean MEMS manufacturers locking multi-year agreements with embedded purity escalation clauses. Price differentiation hinges on sub-ppm impurity validation capabilities and after-sales technical consultation, with academic institutions showing lowest price sensitivity due to grant-funded procurement authority while cost-sensitive automotive connector suppliers drive aggressive spot-market negotiation.
Supply Chain Analysis
China and Germany anchor silver sulfate crystal production, with Yangtze River Delta fabrication clusters and Bavarian chemical corridors serving distinct purity-grade specifications. Raw material dependencies center on silver nitrate feedstock from London Bullion Market Association-certified refiners, sulfuric acid from integrated chemical complexes, and sodium sulfate from chlor-alkali co-production streams. Single-source vulnerability concentrates in high-purity crystal production where ICP-MS validation capabilities remain scarce. Distribution runs through direct sales channels for laboratory-grade supply and regional distributors with localized blending capacity for electroplating applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Closed-loop recovery system integration represents the fastest-expanding service-attach layer, with membrane electrolysis units converting spent bath solutions into reclaimable metal feedstock and generating recurring aftermarket revenue streams beyond chemical supply margins.
For Market Incumbents: Consolidate quality control throughput through automated ICP-MS validation investments to offset analytical chemist scarcity compressing batch certification timelines. Deepen backward integration into silver nitrate feedstock supply to buffer London Bullion Market Association spot price volatility eroding electroplating bath operator margins. Lock exclusive distribution partnerships with wastewater treatment integrators serving EPA-regulated plating facilities to preempt closed-loop recovery competition. For New Entrants and Emerging Players: Lead with localized blending facilities in India's PLI scheme corridors where electronics manufacturing subsidies are attracting fabrication investment ahead of established chemical distributor presence. Target Maharashtra and Gujarat smartphone component plating clusters with REACH-equivalent purity documentation for export-bound semiconductor supply chains. Differentiate through manufacturer-direct procurement portals bypassing traditional distributor markups for academic institution segments. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional distributors establishing localized blending capacity near emerging fabrication clusters but lacking integrated reagent portfolios for cross-selling. Five-to-ten year viability favors suppliers with captive ICP-MS validation capabilities and pre-submitted REACH dossiers. Watch semiconductor fabrication subsidy announcements in secondary Asian markets as inflection indicators for regional demand redirection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Silver Nitrate Feedstock | Captive supply of LBMA-certified silver buffers spot price volatility eroding plating bath margins. |
| Closed-Loop Recovery System Partnership | Membrane electrolysis integration with EPA-regulated plating facilities generates recurring aftermarket service revenue. |
| REACH Dossier Pre-Submission | ECHA toxicological documentation accelerates European import authorization timelines against uncertified competitors. |
| Localized Blending Facility Deployment | India PLI scheme alignment positions inventory near emerging electronics fabrication corridors. |
| Manufacturer-Direct Portal Development | Academic institution procurement bypasses traditional chemical distributor markups for laboratory-grade supply. |
Methodological Framework
A spread of perspectives from electroplating facility managers, semiconductor procurement leads, analytical chemists, wastewater treatment integrators, and laboratory purchasing officers converged on the working assumptions underlying this analysis. Primary fieldwork combined with secondary validation from customs trade data, SEC 10-K filings of diversified chemical conglomerates, ECHA registration databases, and semiconductor fabrication subsidy announcements. Bottom-up volume estimates from product-format consumption patterns triangulated against top-down value projections from purity-grade pricing structures.
Segmentation dimensions modeled include product format, application specification, end-user sophistication tier, and distribution channel across the analysis window. CAGRs derive from regression analysis of historical consumption patterns adjusted for subsidy-driven demand inflections and regulatory compliance cost trajectories. Forecast inputs incorporate silver price volatility scenarios from London Bullion Market Association spot data and semiconductor fabrication capacity expansion timelines from NMPA-aligned incentive disclosures.
Forecasts assume regulatory continuity in REACH, EPA Clean Water Act, and NMPA semiconductor incentive regimes; material policy shifts would require re-modeling of supply qualification timelines and purity documentation requirements. Recalibration cycles align with material shifts in silver price volatility, semiconductor fabrication subsidy announcements, and ECHA registration deadline implementations.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Chemicals
Marine Hyaluronic Acid Market
Specialty Chemicals
Salicylate Market
Specialty Chemicals
Stearates Market
Specialty Chemicals
North America Sugarcane Wax Market
Specialty Chemicals
Preparative and Process Chromatography Market
Specialty Chemicals
Textile Flame Retardants Market
Specialty Chemicals
Dehazer Market
Specialty Chemicals
Organic Sulfur Market
Specialty Chemicals
Hyaluronic Acid Products Market
Specialty Chemicals
Global Immersion Oil Market
Specialty Chemicals
Global Optical Brighteners Market
Specialty Chemicals
Lithium Difluoro(Oxalato)Borate Market
Specialty Chemicals
Silicone Oil Market
Specialty Chemicals
Myrcene Market
Specialty Chemicals
Viscoelastic Agents Market
Specialty Chemicals
Global Water Based Acrylates Copolymer Rheology Modifiers Market