
 Iso Nonanol Market | 2026-2036
Iso Nonanol Market Size, Share, and Industry Trends Forecast 2026-2036
Iso Nonanol Market Intelligence
Custom formulation support is realigning the basis of competition from pure volume to application-specific performance. This shift favors producers with deep technical expertise in plasticizer and surfactant chemistries. BASF SE leverages its extensive production network and R&D capabilities to offer tailored solutions. Evonik Industries AG specializes in high-purity grades for sensitive applications, while ExxonMobil Corporation dominates the market with its large-scale, cost-efficient manufacturing of oxo alcohols.
Iso nonanol is a branched-chain nine-carbon alcohol, primarily produced through the hydroformylation of octene isomers in the oxo process. This chemical intermediate's main industrial function is as a precursor for producing high-molecular-weight plasticizers, such as diisononyl phthalate (DINP). The application segment for plastics, therefore, constitutes the largest share of consumption. Within product types, nonyl alcohol grades are standard, with the material predominantly supplied in liquid form for ease of handling in chemical synthesis.
The regulatory environment is governed by chemical safety frameworks that vary significantly by region. In Europe, compliance with ECHA's REACH regulation is mandatory for market access, requiring extensive substance registration and data submission. Similarly, the United States Environmental Protection Agency (EPA) manages chemical risks under the Toxic Substances Control Act (TSCA). Decisions on feedstock sourcing and compliance with these evolving chemical safety mandates will define future competitive advantage.
Market Dynamics
The market's central tension lies between automotive industry demand for high-performance lubricants and plasticizers, and mounting regulatory scrutiny on chemical feedstocks and intermediates under frameworks like REACH. This dynamic forces producers to balance cost-efficient production with significant investment in compliance and product stewardship.
Growth Catalysts
- Automotive Sector Demand:Expansion of the global vehicle parc drives consumption of iso nonanol-derived esters in engine oils and transmission fluids, which require high thermal stability and lubricity for modern engines.
- Chinese Manufacturing Base:China's vast chemical production infrastructure requires large, steady volumes of iso nonanol as a precursor for diisononyl phthalate (DINP) used in a wide array of PVC applications.
- Material Performance Standards:Demand for low-volatility plasticizers in consumer goods and building materials to meet stringent indoor air quality standards favors higher-molecular-weight, iso nonanol-based products over alternatives.
Market Restraints
- Feedstock Volatility:Octene, the primary feedstock for iso nonanol, is derived from crude oil, exposing producers to significant raw material price fluctuations and subsequent margin pressure.
- Regulatory Scrutiny:The European Union's REACH regulation subjects downstream products like DINP to continuous evaluation, creating market uncertainty and significant compliance costs for manufacturers.
- Substitution Risk:Alternative plasticizers, particularly dioctyl terephthalate (DOTP), compete directly with DINP in many flexible PVC applications, effectively capping the pricing power of iso nonanol derivatives.
Strategic Opportunities
- Bio-based Feedstocks:Developing production pathways for iso nonanol from renewable sources presents an opportunity to meet corporate sustainability goals and appeal to green-conscious buyers in end-use markets.
- Southeast Asia Expansion:Growing plastics processing and automotive assembly in countries like Vietnam and Indonesia represents an underpenetrated market for iso nonanol and its derivatives.
- Non-Phthalate Plasticizers:Leveraging iso nonanol chemistry to create novel, non-phthalate plasticizers enables producers to preemptively address regulatory trends and capture value in high-performance segments.
Industry Challenges
- Capital Intensity:The construction of new oxo process facilities for iso nonanol production requires substantial capital investment, long project timelines, and specialized engineering expertise.
- Compliance Burden:Securing registration under ECHA's REACH framework involves extensive, time-consuming toxicological testing and data submission for market access into the European Union.
- Logistics Complexity:Managing the bulk transport of a liquid chemical intermediate across international borders involves navigating complex, region-specific hazardous material regulations and specialized handling requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Iso Nonanol Market |
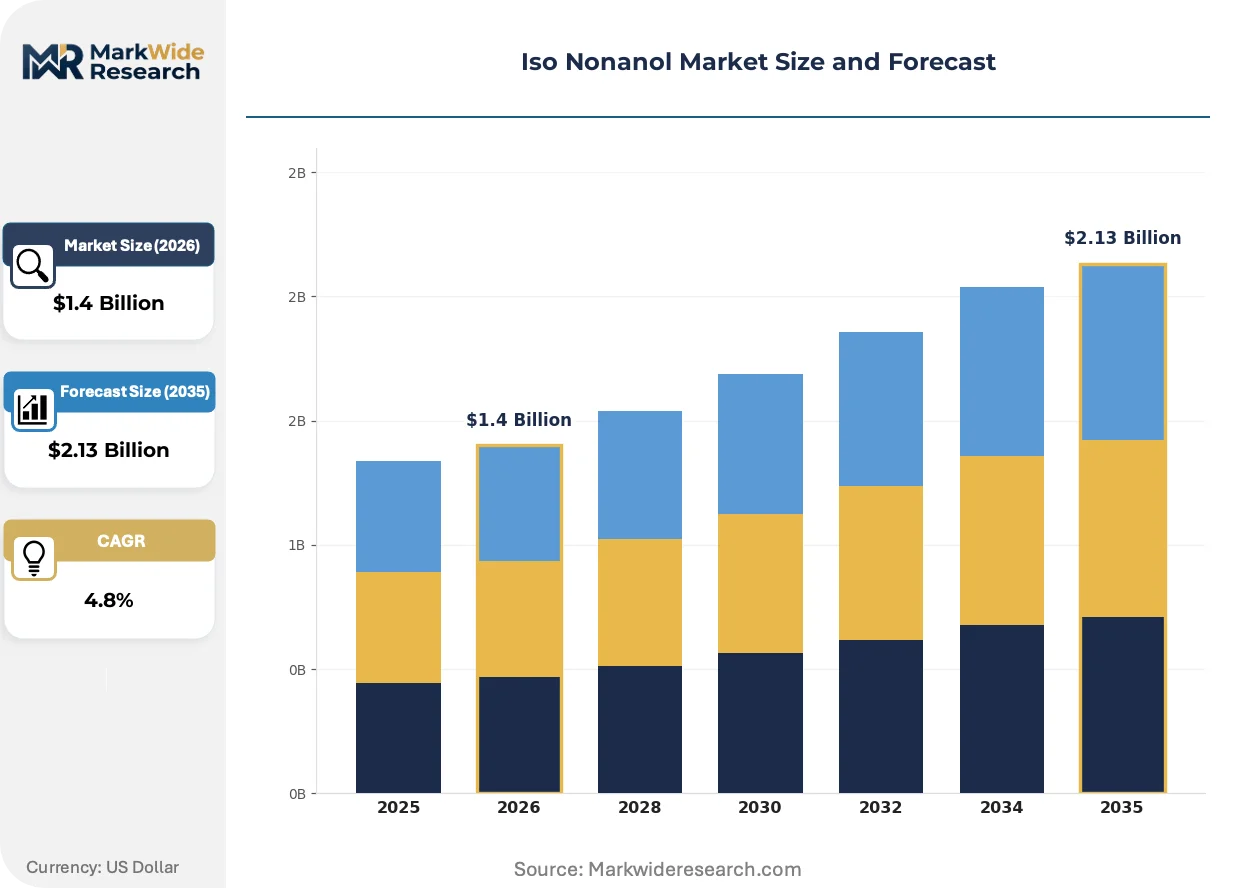
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.13 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Caprylic Alcohol, Nonyl Alcohol, Decanol, Octanol Application: Cosmetics, Detergents, Lubricants, Plastics Form: Liquid, Solid, Powder, Emulsion End User: Chemical Manufacturers, Personal Care, Food Processors, Automotive |
| Companies Covered | BASF SE, Evonik Industries AG, ExxonMobil Corporation, The Dow Chemical Company, Sinopec, Nan Ya Plastics Corporation, KH Neochem Co., Ltd., Johnson Matthey, OXEA GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Iso Nonanol Market Strategic Shifts & Innovations
Process intensification and the pursuit of alternative feedstocks are actively reshaping the production landscape. These shifts are driven by a dual mandate to control manufacturing costs and comply with evolving chemical safety regulations across multiple jurisdictions.
Advanced hydroformylation catalysts improve selectivity and yield in the oxo process, which is the primary route to iso nonanol. Chemical producers adopt these catalysts to reduce energy inputs and minimize the formation of unwanted by-products. This catalyst technology is converging with digital twin modeling of chemical reactors, enabling real-time optimization of feedstock conversion and waste stream reduction.
The European Union's REACH regulation continues its systematic evaluation of phthalates, impacting the major downstream product DINP. This action forces producers to generate extensive toxicological data to maintain market access for their products. The plasticizer segment is most affected, with some firms investing in reformulation strategies to mitigate future regulatory risk.
A demand-side shift toward circular economy principles is altering material specification criteria in key end-use markets. Buyers in the construction and automotive sectors are increasingly requesting plasticizers and lubricants with certified recycled or bio-based content. This trend is most visible in Europe, disrupting traditional procurement patterns based solely on fossil-fuel-derived feedstocks.
Iso Nonanol Market Segmentation
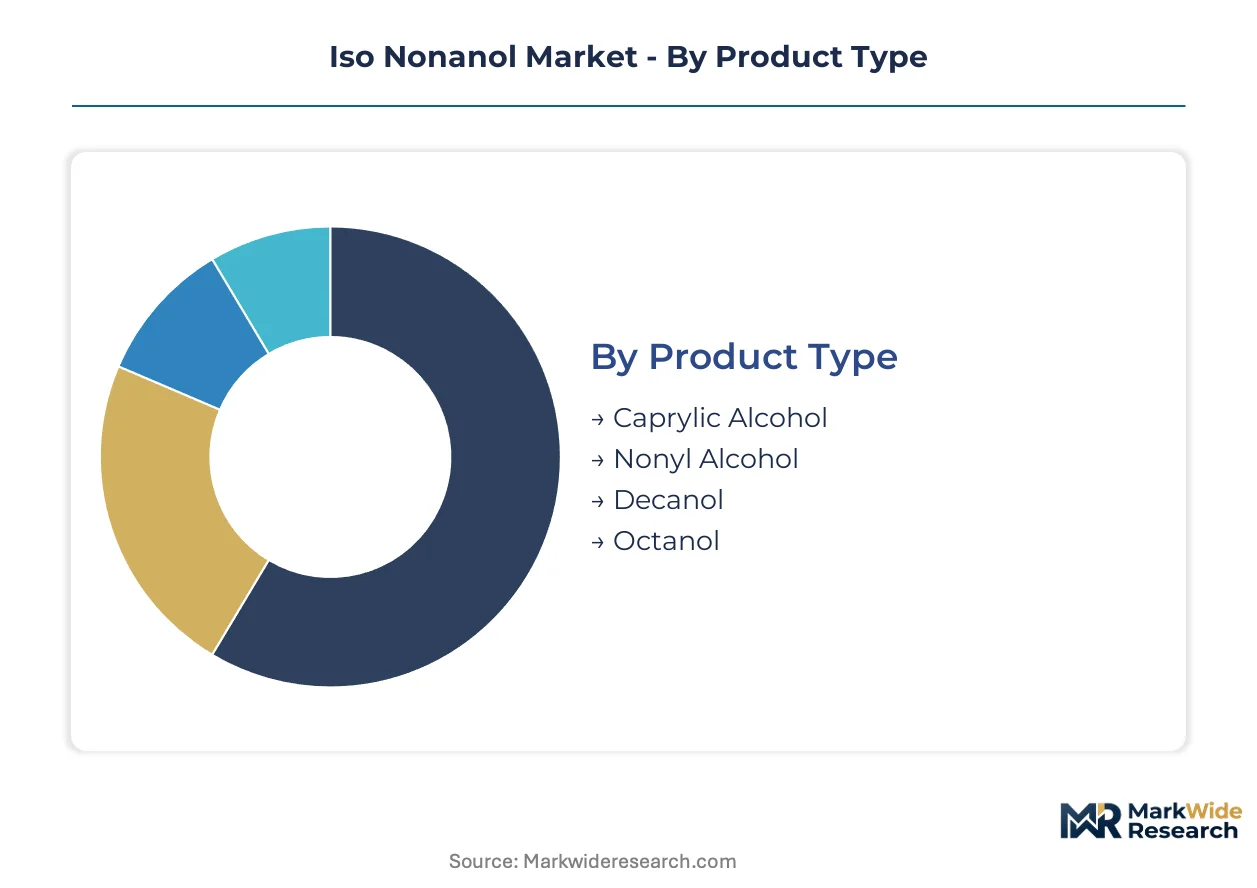
Segmentation analysis within the iso nonanol market offers crucial insights into product differentiation and demand drivers. It highlights specific performance requirements across various end-use sectors. This detailed breakdown helps market participants optimize production strategies and tailor product offerings to capture distinct value pools.
Product Type:
The iso nonanol market's product type segmentation reveals how different alcohol grades support varying upgrade and replacement cycles in downstream industries.
- Nonyl Alcohol:This branched-chain nine-carbon alcohol serves primarily as a precursor for high-molecular-weight plasticizers like diisononyl phthalate (DINP). Demand concentrates in China due to its extensive PVC manufacturing base, driven by infrastructure development.
- Octanol:Octanol, an eight-carbon alcohol, finds extensive use in the production of plasticizers such as dioctyl phthalate (DOP) and dioctyl terephthalate (DOTP). It sees strong demand in flexible PVC applications, especially in North America, where it competes directly with nonyl alcohol derivatives.
- Caprylic Alcohol:This straight-chain eight-carbon alcohol is utilized in personal care products and as a chemical intermediate for esters and flavors.
- Decanol:Decanol, a ten-carbon alcohol, functions as a precursor for plasticizers, surfactants, and lubricants, offering enhanced thermal stability.
Nonyl Alcohol sits at the top of the volume ranking, with Octanol climbing the fastest.
Application:
Application segmentation delineates the functional roles iso nonanol derivatives play across diverse industrial sectors.
- Plastics:Iso nonanol is a critical precursor for diisononyl phthalate (DINP), a high-molecular-weight plasticizer used in flexible PVC products like wire and cable insulation, and flooring. This segment holds the largest share of consumption, particularly in Asian manufacturing hubs.
- Lubricants:Iso nonanol-derived esters enhance the thermal stability and lubricity of engine oils and transmission fluids in the automotive sector. Demand for these high-performance lubricants is driven by the expansion of the global vehicle parc.
- Cosmetics:Iso nonanol derivatives serve as emollients, emulsifiers, and thickeners in various personal care and cosmetic formulations.
- Detergents:Iso nonanol is used in the synthesis of surfactants, which are essential components in industrial and household cleaning agents.
This category's structure highlights the plastics segment as the dominant consumer, with lubricants demonstrating strong expansion.
Form:
The form in which iso nonanol is supplied reflects operational efficiencies and handling requirements across the chemical value chain.
- Liquid:Iso nonanol is predominantly supplied in liquid form, facilitating ease of handling, mixing, and transport in chemical synthesis processes. Bulk liquid delivery optimizes cost-efficiency for large-scale industrial users.
- Emulsion:Emulsion forms of iso nonanol derivatives are developed for specialized applications requiring enhanced dispersion or specific interfacial properties. This form often targets niche markets within personal care or industrial formulations.
- Powder:Powder forms of iso nonanol derivatives are less common but find use in specific applications where solid-state incorporation is required.
- Solid:Solid forms of iso nonanol are rare, typically appearing as intermediates or in highly specialized, low-volume chemical reactions.
Liquid form constitutes the standard delivery method, driven by its inherent handling advantages and broad industrial applicability.
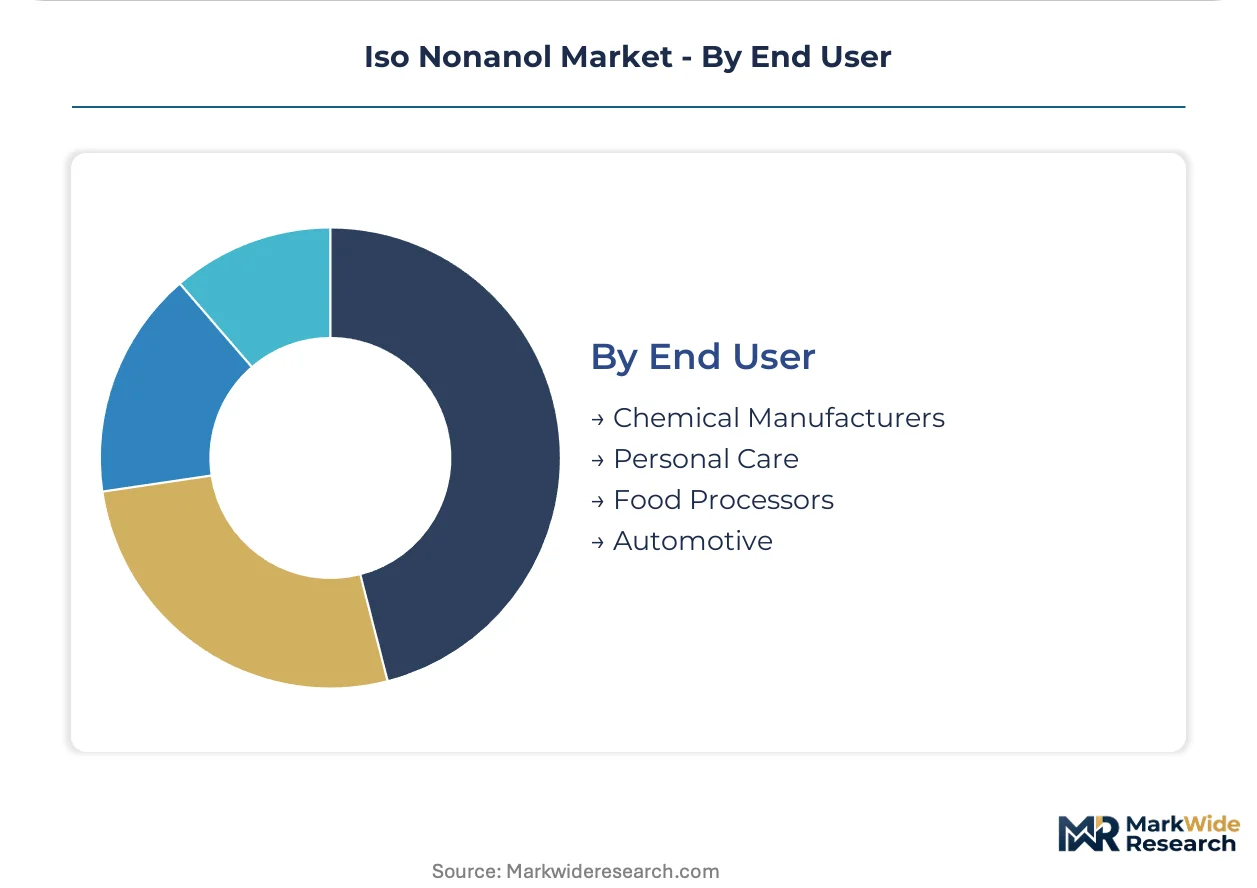
End User:
End-user segmentation illustrates how different industries integrate iso nonanol into their manufacturing processes and product portfolios.
- Chemical Manufacturers:These entities consume iso nonanol as a key chemical intermediate for synthesizing plasticizers like DINP, as well as surfactants and other specialty chemicals. Their demand is directly tied to the production volumes of downstream derivatives.
- Automotive:The automotive sector utilizes iso nonanol-derived esters in performance lubricants and plasticized components requiring high thermal stability and durability. This segment's demand is closely linked to vehicle production and maintenance cycles.
- Personal Care:Personal care companies incorporate iso nonanol derivatives into cosmetics and toiletries for their emollient and emulsifying properties.
- Food Processors:Food processors may use iso nonanol derivatives in specific food contact materials or as processing aids, adhering to strict regulatory guidelines.
Chemical manufacturers represent the primary demand source for iso nonanol, with the automotive sector exhibiting robust growth in specialized applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The differential in chemical safety regulations across jurisdictions influences iso nonanol production and market dynamics. Producers seek locations balancing cost-efficient manufacturing with evolving compliance mandates. This regional divergence shapes investment decisions and supply chain configurations.
China
China's vast chemical and plastics manufacturing base drives significant iso nonanol consumption for DINP production. The Ministry of Ecology and Environment (MEE) enforces stringent environmental protection policies. Major chemical parks in the Yangtze River Delta and Pearl River Delta expand capacity for downstream derivatives.
Germany
German chemical manufacturers require iso nonanol for high-performance lubricants and specialty plasticizers in automotive and construction. ECHA's REACH regulation mandates extensive substance registration and data submission for market access. Chemical clusters in the Rhine-Main region focus on advanced material development and sustainable production.
United States
The United States automotive industry generates consistent demand for iso nonanol-derived esters in engine oils and transmission fluids. The Environmental Protection Agency (EPA) manages chemical risks under TSCA, influencing production processes. The Gulf Coast region, particularly Houston, remains a hub for petrochemical production and derivative manufacturing.
India
India's expanding construction sector and automotive industry fuel demand for iso nonanol in PVC plasticizers and performance lubricants. The Bureau of Indian Standards (BIS) sets quality benchmarks for chemical intermediates. Chemical manufacturing hubs in Gujarat and Maharashtra increase capacity to meet domestic and regional requirements.
Vietnam
Vietnam's rapidly developing plastics processing and automotive assembly industries create new opportunities for iso nonanol consumption. The Ministry of Natural Resources and Environment (MONRE) oversees environmental compliance for industrial chemicals. Industrial zones near Ho Chi Minh City attract foreign investment in chemical and plastics manufacturing.
Iso Nonanol Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments within the iso nonanol market. The competitive structure features a mix of large, integrated petrochemical players and niche chemical producers. Strategic archetypes include upstream feedstock specialists, midstream chemical intermediate manufacturers, and downstream derivative formulators. Dominant competitive moves involve global capacity expansion and portfolio diversification into higher-value applications.
Among integrated chemical producers, ExxonMobil Corporation exemplifies large-scale, cost-efficient manufacturing of oxo alcohols. BASF SE represents a global chemical conglomerate leveraging extensive production networks and R&D capabilities for tailored solutions across various industries. Evonik Industries AG occupies a position as a specialist in high-purity grades, particularly for sensitive applications. These companies anchor the market with their broad product portfolios and global distribution channels, supplying iso nonanol as a critical chemical intermediate to diverse end-users.
| Leading Market Players |
|---|
| BASF SE |
| Evonik Industries AG |
| ExxonMobil Corporation |
| The Dow Chemical Company |
| Sinopec |
| Nan Ya Plastics Corporation |
| KH Neochem Co., Ltd. |
| Johnson Matthey |
| OXEA GmbH |
| Others |
Cost & Logistics Intelligence
Octene feedstock price volatility directly impacts iso nonanol production costs, influencing downstream plasticizer and lubricant pricing structures. This upstream input variability flows through the chemical value chain to end-use markets.
Pricing Analysis
Distributor margins for iso nonanol are often negotiated under long-term contract-based offtake agreements. Pricing differentiation stems from quality grade, particularly for high-purity applications, and large volume scale. Pricing softness reflects persistent feedstock volatility and competition from alternative plasticizers like DOTP. Chemical manufacturers exhibit high price sensitivity, while the automotive sector often prioritizes performance over marginal cost differences.
Supply Chain Analysis
Regulatory qualification under ECHA's REACH framework gates market access into Europe for iso nonanol and its derivatives. Supply concentration centers on China, the United States, and Germany, leveraging established petrochemical infrastructure. The supply chain relies heavily on octene feedstock, derived from crude oil, introducing significant commodity price volatility. Logistics complexity and hazardous material regulations govern bulk liquid distribution across international borders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The iso nonanol market offers geographic arbitrage opportunities, particularly given the stringent compliance costs imposed by Europe's REACH regulation compared to less regulated regions. Producers can optimize production footprints based on regional cost and regulatory environments.
For Market Incumbents:Cement technical expertise in plasticizer and surfactant chemistries to counter regulatory scrutiny on DINP. Invest in advanced hydroformylation catalysts to improve process efficiency and reduce reliance on volatile octene feedstock. Leverage extensive production networks for global distribution, mitigating regional supply chain disruptions. Develop novel non-phthalate plasticizers derived from iso nonanol chemistry to preempt future regulatory shifts.
For New Entrants and Emerging Players:Local distributors in Southeast Asia represent a penetrable channel for iso nonanol and its derivatives. Target growing plastics processing and automotive assembly in countries like Vietnam and Indonesia, which have increasing demand. Offer custom formulation support for application-specific performance, shifting away from pure volume competition. Focus on developing bio-based iso nonanol to appeal to green-conscious buyers and meet sustainability goals.
For Investors and Strategic Acquirers:Consolidation pressure builds where compliance costs and capital intensity favor larger, integrated players. Long-term viability across the next decade hinges on navigating evolving chemical safety mandates and feedstock volatility. Target niche chemical producers specializing in advanced catalyst technology or bio-based chemical intermediates. A key signal to watch is significant patent activity or commercialization of novel, non-phthalate plasticizers.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in China | Increases supply to meet strong DINP demand from the expansive Chinese manufacturing base. |
| R&D into Non-Phthalate Plasticizers | Addresses regulatory scrutiny on traditional phthalates, capturing value in high-performance segments. |
| Bio-based Feedstock Development | Aligns with corporate sustainability goals and appeals to environmentally conscious end-users. |
| Advanced Catalyst Adoption | Enhances oxo process efficiency, reducing energy consumption and minimizing unwanted by-products. |
| Southeast Asia Market Entry | Captures underpenetrated demand from rapidly expanding plastics processing and automotive industries. |
Research Approach
Multiple input streams — primary interviews, regulatory filings, and trade association reports — were reconciled to build a robust market perspective. Interviews included plant managers, procurement leads at chemical manufacturers, R&D directors, and regulatory affairs specialists. Secondary validation drew from customs data, chemical industry reports, and company annual statements. This approach utilized both bottom-up market sizing and top-down validation for comprehensive data triangulation.
Data-stream reconciliation formed the basis of the analytical framework applied across the analysis window. The model segmented demand by product type, application, form, and end user, alongside regional regulatory clusters. Compound Annual Growth Rates (CAGRs) were derived from historical trends and projected future demand. Key forecast inputs included anticipated octene price fluctuations and evolving regulatory timelines for chemical intermediates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to geopolitical events affecting crude oil prices and regulatory policy shifts. Forecasts reflect assumptions regarding economic growth and technological advancements. A model refresh is warranted upon material change in feedstock availability or chemical safety mandates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Morpholine Market
Chemicals
Ethylenediamine (EDA) Market
Chemicals
Paint Stripper Market
Chemicals
Chloroplatinic Acid Market
Chemicals
Global Chiral Chemicals Market
Chemicals
Potassium Hydrogen Phthalate Market
Chemicals
Phosgene Market
Chemicals
Photographic Film Processing Chemicals Market
Chemicals
Diethylenetriamine (DETA) Market
Chemicals
Peroxyacetic Acid Market
Chemicals
5 Dinitroaniline Market
Chemicals
Global Cysteine Market
Chemicals
South America Construction Chemicals Market
Chemicals
Malic Acid Market
Chemicals
Lauryl Myristyl Alcohol Market
Chemicals
Global Aluminum Hydroxide Market