
 Sodium Methoxide Market | 2026-2036
Sodium Methoxide Market Size, Share, and Industry Trends Forecast 2026-2036
Sodium Methoxide Market Analysis
Maintenance contracts for catalyst regeneration and spent methoxide recovery is broadening what chemical processors purchase alongside virgin material. BASF SE leverages its integrated methanol-to-alkoxide pipeline to sustain margin control across European pharmaceutical and agrochemical accounts. Evonik Industries anchors high-purity liquid production for biodiesel transesterification in Germany and export markets. Jiangsu Tianhong Chemical dominates solid-grade manufacturing scale for domestic Chinese chemical synthesis demand.
Sodium methoxide is an alkoxide salt of sodium and methanol, typically manufactured through metallic sodium reaction with anhydrous methanol or via sodium hydroxide and methanol dehydration, yielding a highly hygroscopic white solid or colorless to pale yellow liquid solution with methanol concentrations ranging from 25% to 30% by weight. It functions primarily as a strong base and nucleophile in transesterification reactions for biodiesel production, condensation reactions in pharmaceutical active ingredient synthesis, and as a catalyst in fine chemical manufacturing. Liquid sodium methoxide leads volume consumption due to its direct pumpability into continuous biodiesel reactors, while anhydrous solid grades command premium positioning in pharmaceutical manufacturing where moisture-sensitive reactions demand sub-100 ppm water content. Biodiesel production application segments exhibit the fastest structural expansion as renewable fuel mandates in multiple jurisdictions require methyl ester pathways over alternative ethyl routes.
EPA renewable fuel standard obligations in the United States and EU Green Deal Fit-for-55 targets shape biodiesel demand trajectories by enforcing blending percentages that cascade into methoxide catalyst procurement. REACH registration requirements and ECHA substance evaluation protocols govern anhydrous grade market access for European pharmaceutical and chemical end users. India's BIS purity specifications and CDSCO excipient guidelines direct import and domestic quality benchmarks for research laboratory and drug manufacturing applications. Stakeholders must monitor evolving renewable diesel tax credit structures and carbon intensity scoring methodologies that could redirect methoxide demand between first-generation biodiesel and emerging sustainable aviation fuel pathways.
Market Dynamics
The sodium methoxide market is being fundamentally reshaped by renewable fuel mandate cascades that convert blending percentage obligations into methoxide catalyst procurement volumes, with regulatory enforcement intensity in the United States and European Union determining quarterly demand pulses.
Growth Catalysts
- EPA Renewable Fuel Standard obligations:Blending mandates in the United States enforce methyl ester pathways that directly translate into sodium methoxide procurement for transesterification reactors.
- Biodiesel production expansion:Renewable diesel tax credit structures favor first-generation biodiesel facilities requiring continuous methoxide catalyst feed.
- Pharmaceutical purity requirements:CDSCO-mandated standards for active pharmaceutical ingredient synthesis in India drive high-grade anhydrous sodium methoxide adoption.
Market Restraints
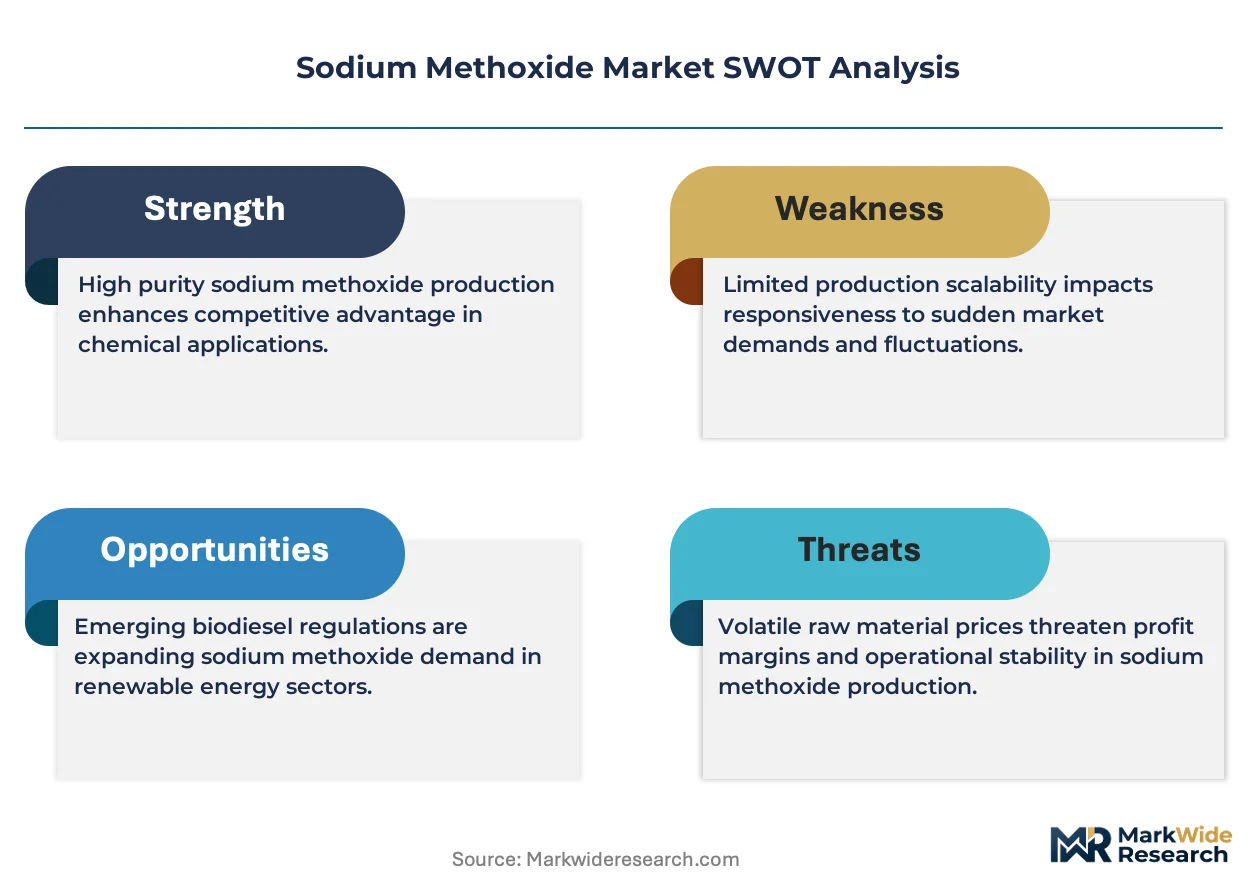
- Metallic sodium supply concentration:Production of sodium methoxide depends on metallic sodium availability concentrated among chlor-alkali producers in select geographies.
- Anhydrous methanol cost volatility:Feedstock methanol pricing ties to natural gas and coal markets, creating margin compression for methoxide manufacturers.
- REACH registration friction:ECHA substance evaluation protocols create compliance timelines and cost barriers for European market access.
Strategic Opportunities
- Sustainable aviation fuel pathways:Emerging hydroprocessed esters and fatty acids production creates new methoxide catalyst demand distinct from conventional biodiesel.
- Maintenance contract bundling:Catalyst regeneration and spent methoxide recovery services represent attach-rate expansion for virgin material suppliers.
- India laboratory reagent segment:Research institution procurement outside pharmaceutical manufacturing remains underpenetrated relative to synthesis-scale demand.
Industry Challenges
- Moisture control certification:Sub-100 ppm water content validation requires specialized handling infrastructure and analytical capability investment.
- Spent catalyst logistics:Methanol recovery and sodium salt disposal from biodiesel facilities demands hazardous materials transportation coordination.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sodium Methoxide Market |
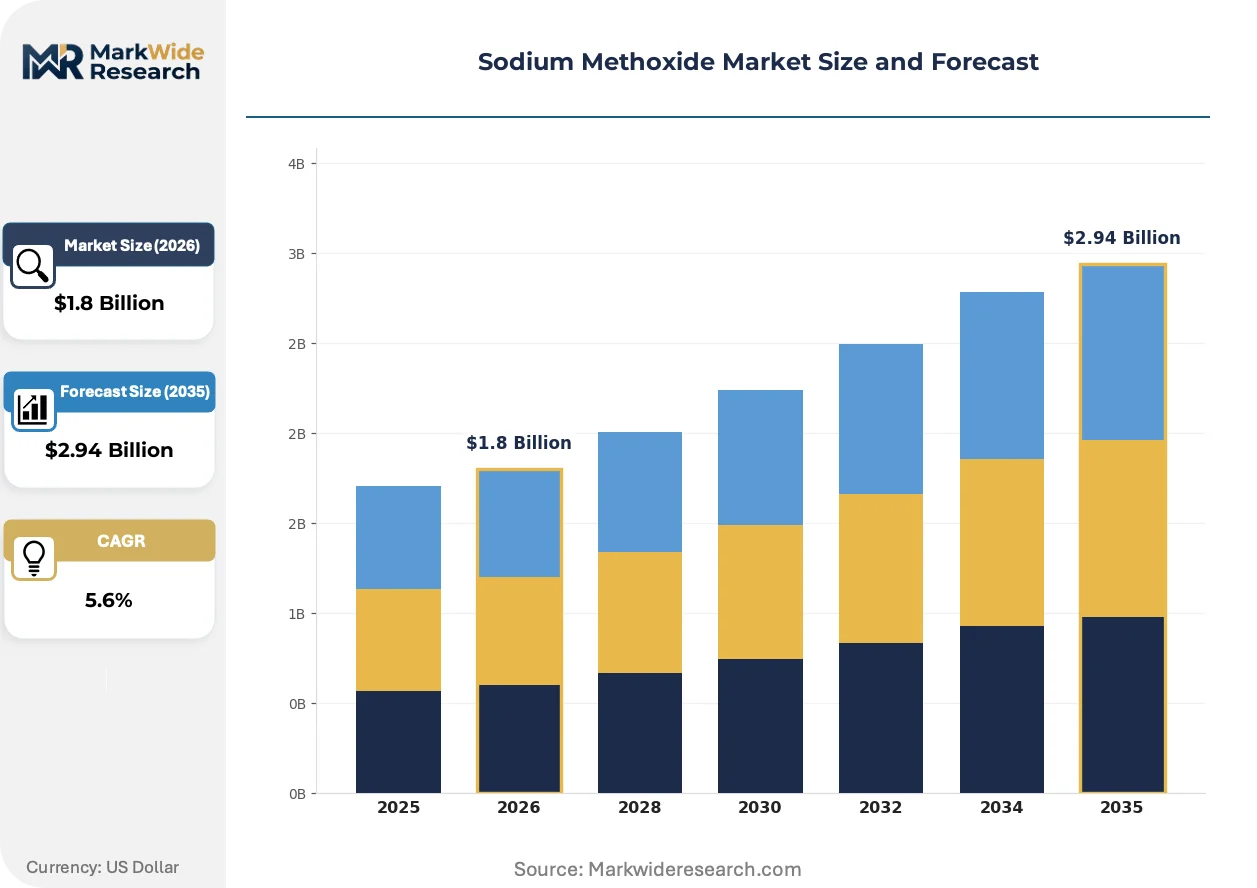
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.94 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solid, Liquid, Powder, Anhydrous Application: Biodiesel Production, Chemical Synthesis, Pharmaceutical Manufacturing, Catalyst End User: Energy Sector, Chemical Industry, Research Laboratories, Food Industry Distribution Channel: Direct Sales, Online Sales, Distributors, Retail |
| Companies Covered | Jiangsu Tianhong Chemical, Anhui Jinbang Medicine Chemical, Evonik Industries, Zibo Xusheng Chemical, Inner Mongolia Lantai Industries, BASF SE, Shilpa Medicare, SMOTEC Plus, DuPont, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sodium Methoxide Market Emerging Trajectories
Continuous processing technology and regulatory carbon intensity scoring are compressing batch reactor economics while opening pathway differentiation for methoxide suppliers capable of certifying lifecycle emissions.
Membrane-based methanol dehydration is electrifying solid-grade production economics by reducing thermal energy requirements in anhydrous sodium methoxide manufacturing. Pharmaceutical manufacturers in Switzerland and Germany are adopting membrane-processed material for moisture-sensitive condensation reactions. This technology is electrifying competitive positioning among European suppliers previously constrained by energy-intensive conventional drying.
EU Green Deal Fit-for-55 targets are tightening carbon intensity thresholds for transport fuels, forcing biodiesel producers to document methoxide catalyst supply chain emissions. The European Commission's delegated acts on renewable energy sustainability criteria now extend to chemical inputs. Biodiesel facilities in Germany and the Netherlands are responding by demanding supplier-specific carbon footprint declarations.
Buyers are consolidating procurement volumes through multi-year offtake agreements that bundle virgin catalyst, regeneration services, and spent material recovery. Chemical processors in the United States are displacing spot purchasing with integrated supply contracts covering full catalyst lifecycle management. This pattern is most visible among large biodiesel refiners seeking to lock in methoxide supply security against metallic sodium market volatility.
Sodium Methoxide Market Segmentation
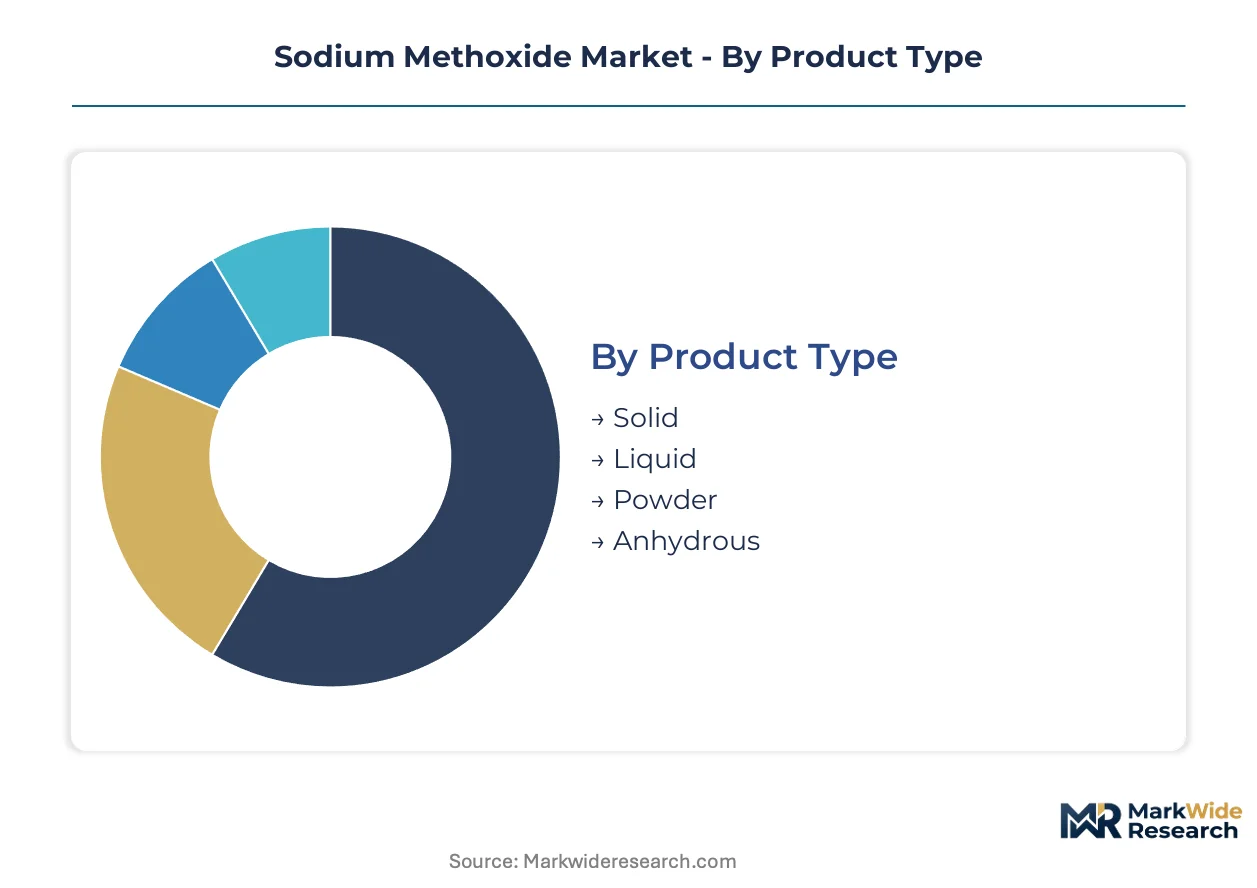
Sodium methoxide procurement patterns diverge sharply across physical form, end-use chemistry, and customer sophistication. Specification requirements for moisture content, methanol concentration, and handling protocols create distinct commercial segments with limited substitutability.
Product Type:
Physical state and residual moisture content define handling infrastructure requirements and pricing tiers across industrial buyers.
- Liquid:Solutions containing 25-30% methanol by weight pump directly into continuous biodiesel transesterification reactors. German biodiesel facilities in Hamburg and Rostock anchor European demand due to direct feed compatibility with existing infrastructure.
- Anhydrous:Sub-100 ppm water content solid grades command premium positioning for moisture-sensitive pharmaceutical condensation reactions. Swiss and German API manufacturers specify membrane-processed material to eliminate thermal degradation risks in high-value synthesis steps.
- Solid:Standard-grade hygroscopic white solid serves batch chemical synthesis operations with less stringent moisture tolerances.
- Powder:Finely divided form facilitates rapid dissolution in laboratory-scale reactions and specialized coating applications.
Mature deployment sits with liquid formulations in continuous biodiesel processing. Newer deployment is concentrated in anhydrous grades for pharmaceutical manufacturing.
Application:
Reaction chemistry and regulatory compliance intensity segment demand by value capture potential and technical service requirements.
- Biodiesel Production:Transesterification catalyst demand scales directly with EPA renewable fuel standard blending obligations and EU Green Deal Fit-for-55 enforcement. US facilities in Iowa and Texas purchase methoxide in railcar quantities tied to RIN generation economics.
- Pharmaceutical Manufacturing:CDSCO-mandated purity standards for active pharmaceutical ingredient synthesis in India drive high-grade specification adoption. Mumbai and Hyderabad formulation facilities require certificate-of-analysis documentation for every lot.
- Chemical Synthesis:Base-catalyzed condensation and alkylation reactions in agrochemical and fine chemical production.
- Catalyst:Regeneration and recovery services bundled with virgin material supply in maintenance contracts.
Volume concentration remains in biodiesel catalyst applications. Value expansion is climbing fastest in pharmaceutical-grade material.
End User:
Operational scale and technical capability determine whether buyers self-handle methoxide or outsource logistics and waste management.
- Energy Sector:Biodiesel refiners in the United States and Germany negotiate multi-year offtake agreements bundling virgin catalyst, spent recovery, and regeneration services to secure supply against metallic sodium volatility.
- Chemical Industry:Agrochemical and specialty chemical manufacturers in China purchase solid grades through distributors for batch synthesis operations.
- Research Laboratories:Indian academic and government research institutions represent underpenetrated demand relative to synthesis-scale procurement.
- Food Industry:Limited application in edible oil processing and food-grade ester production.
Contract sophistication concentrates in energy sector procurement. Spot purchasing persists in research laboratory segments.
Distribution Channel:
Customer scale and geographic density shape channel economics for hazardous material handling requirements.
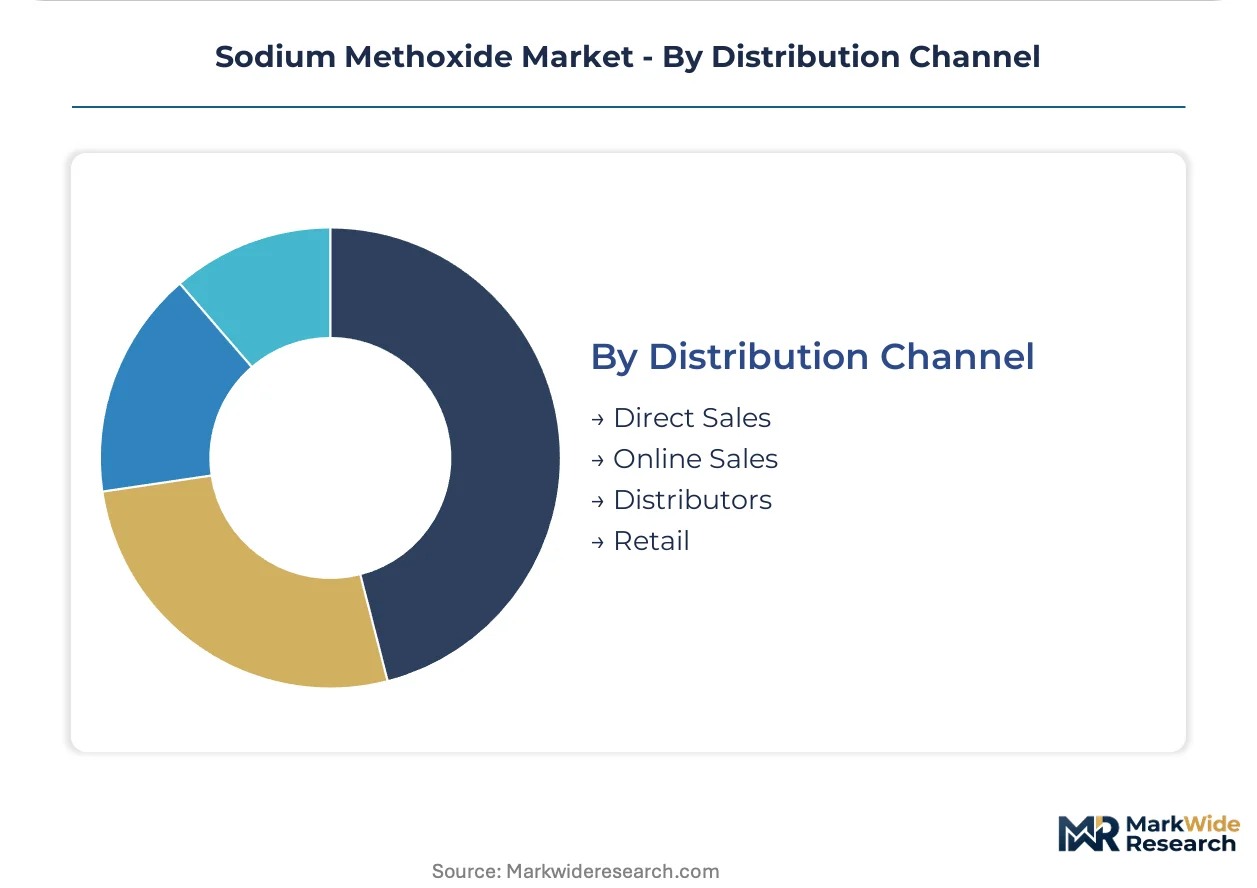
- Direct Sales:Large biodiesel refiners and pharmaceutical manufacturers contract directly with BASF SE, Evonik Industries, and Jiangsu Tianhong Chemical for volume security and technical service integration.
- Distributors:Regional chemical distributors stock liquid and solid grades for mid-scale chemical synthesis customers requiring shorter lead times.
- Online Sales:Laboratory-scale quantities for research institutions and small synthesis operations.
- Retail:Minimal presence given hazardous material shipping restrictions and customer sophistication requirements.
Direct relationships dominate high-volume biodiesel and pharmaceutical procurement. Distributor penetration is expanding in mid-tier chemical synthesis accounts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hamburg anchors European sodium methoxide demand through its biodiesel refining corridor, while Mumbai and Hyderabad drive pharmaceutical-grade consumption in India. The market clusters around port cities with methanol import infrastructure and regions with concentrated chemical synthesis activity.
United States
Biodiesel refiners in Iowa and Texas purchase methoxide in railcar quantities tied to RIN generation economics under EPA renewable fuel standard obligations. The EPA enforces blending mandates that cascade directly into sodium methoxide procurement volumes for transesterification reactors. Facilities in the Midwest corn belt and Gulf Coast petrochemical corridor represent the densest concentration of continuous-process demand.
Germany
Evonik Industries anchors high-purity liquid production for European biodiesel and fine chemical customers from its German manufacturing base. EU Green Deal Fit-for-55 targets and ECHA REACH registration requirements govern market access for pharmaceutical and chemical end users. The Hamburg-Rostock port corridor hosts the continent's largest biodiesel transesterification capacity, driving methoxide consumption at scale.
India
Pharmaceutical manufacturers in Mumbai and Hyderabad drive adoption through CDSCO-mandated purity standards for active pharmaceutical ingredient synthesis. BIS specifications and CDSCO excipient guidelines direct import and domestic quality benchmarks for drug manufacturing applications. The underpenetrated research laboratory segment outside pharmaceutical manufacturing represents expansion opportunity in Bangalore and Delhi-NCR academic institutions.
China
Jiangsu Tianhong Chemical dominates solid-grade manufacturing scale for domestic chemical synthesis demand across the Yangtze River Delta. The country's dual carbon goals and MIIT industrial policy shape methanol feedstock economics that cascade into methoxide production costs. Shandong and Zhejiang provinces concentrate batch chemical synthesis operations consuming standard-grade hygroscopic solid material.
Switzerland
Pharmaceutical manufacturers in Basel adopt membrane-processed anhydrous material for moisture-sensitive condensation reactions. Swissmedic regulates active pharmaceutical ingredient quality standards that exceed baseline REACH requirements for European market access. The country's precision chemical cluster sources sub-100 ppm water content grades for high-value synthesis steps where thermal degradation risks dominate specification decisions.
Sodium Methoxide Market Vendor Landscape
Capital-heavy producers compete with asset-light distributors across tiered supply relationships. The market structure concentrates around integrated chlor-alkali players with captive metallic sodium supply and regional specialists serving laboratory-scale demand. Three archetypes dominate: integrated chemical majors controlling methanol-to-alkoxide pipelines, Chinese solid-grade manufacturers achieving scale through coal-chemistry integration, and European high-purity specialists certifying pharmaceutical grades. Competitive moves center on multi-year offtake bundling and membrane-based dehydration technology licensing.
Within the integrated chemical major tier, BASF SE and Evonik Industries occupy positions defined by methanol-to-alkoxide pipeline control and European pharmaceutical account relationships. Among Chinese solid-grade fabricators, Jiangsu Tianhong Chemical exemplifies scale-driven positioning through Yangtze River Delta manufacturing concentration. DuPont represents diversified materials science positioning that sits adjacent to pure-play methoxide specialization.
| Leading Market Players |
|---|
| Jiangsu Tianhong Chemical |
| Anhui Jinbang Medicine Chemical |
| Evonik Industries |
| Zibo Xusheng Chemical |
| Inner Mongolia Lantai Industries |
| BASF SE |
| Shilpa Medicare |
| SMOTEC Plus |
| DuPont |
| Others |
Supply Flow & Price Mechanics
Family-owned chlor-alkali specialists in Germany and China anchor metallic sodium supply, translating captive feedstock control into pricing discipline that resists margin erosion from methanol volatility. Their integrated production economics cascade into contract structures that favor multi-year offtake over spot purchasing.
Pricing Analysis
Value-based pricing anchored to biodiesel reactor throughput and pharmaceutical batch yield dominates contract negotiations. Three-tier pricing structure across membrane-processed anhydrous, standard liquid, and solid grades reflects certification intensity and moisture validation costs. Cost compression in standard liquid grades is intensifying because German biodiesel facilities are consolidating procurement volumes. Research laboratories in India exhibit highest price sensitivity; Swiss API manufacturers show lowest sensitivity due to yield-critical synthesis requirements.
Supply Chain Analysis
Spent catalyst recovery and methanol regeneration flows now constitute mandatory reverse logistics for European biodiesel facilities under ECHA waste framework obligations. Metallic sodium supply concentrates in Germany, China, and the United States among integrated chlor-alkali producers. Production draws from anhydrous methanol and metallic sodium feedstocks tethered to natural gas and coal chemistry economics. Single-source vulnerability in metallic sodium procurement represents structural risk. Distribution runs through direct sales for high-volume biodiesel and pharmaceutical accounts, with regional distributors serving mid-tier chemical synthesis.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where ECHA REACH registration timelines create barrier-to-entry moats favoring incumbent European suppliers with established substance dossiers.
For Market Incumbents: To counter metallic sodium supply volatility, BASF SE and Evonik Industries should deepen backward integration into chlor-alkali feedstocks and expand membrane-based dehydration licensing to pharmaceutical accounts. Securing multi-year offtake agreements with Iowa and Texas biodiesel refiners locks volume against spot market erosion. For New Entrants and Emerging Players: E-commerce channels for laboratory-scale anhydrous grades offer the most penetrable entry vector. Target underpenetrated research institutions in Bangalore and Delhi-NCR with certified small-batch supply. Lead with CDSCO documentation support to differentiate from established distributor relationships. For Investors and Strategic Acquirers: Distressed-cycle entries favor membrane-technology specialists in Switzerland with pharmaceutical-grade certification infrastructure. Long-term viability hinges on carbon intensity scoring alignment for EU Green Deal compliance. Monitor delegated acts on renewable energy sustainability criteria for inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Metallic Sodium | Captive chlor-alkali supply insulates BASF SE from feedstock volatility in European pharmaceutical accounts. |
| Membrane-Based Dehydration Licensing | Technology transfer to Swiss API manufacturers electrifies competitive positioning against thermal-process competitors. |
| Multi-Year Offtake Agreement Expansion | Bundled catalyst-regeneration contracts secure volume for Evonik Industries against spot market displacement. |
| Carbon Footprint Certification Program | Supplier-specific declarations meet EU Green Deal Fit-for-55 requirements for German biodiesel facilities. |
| Laboratory-Scale E-Commerce Channel | Direct digital sales penetrate underpenetrated Indian research institutions outside pharmaceutical manufacturing. |
Methodological Framework
Trade databases, ECHA substance registration filings, and CDSCO pharmaceutical excipient guidelines formed the secondary backbone for supply-side and regulatory validation. Primary interviews with biodiesel refinery procurement managers, pharmaceutical API manufacturing directors, chlor-alkali plant managers, and specialty chemical distributors combined with bottom-up and top-down triangulation across customs data and industry association reports.
Historical trendline analysis of metallic sodium pricing and methanol feedstock costs informed volume and value projections across the analysis window. Segmentation modeling incorporated physical form grade, end-use application chemistry, and regional regulatory cluster dimensions. CAGRs derived from transesterification capacity buildout trajectories and pharmaceutical synthesis expansion patterns in India and Switzerland.
The model holds under stable EPA renewable fuel standard enforcement and EU Green Deal implementation; deviation in biodiesel tax credit structures or carbon intensity scoring methodologies would shift catalyst demand between first-generation biodiesel and sustainable aviation fuel pathways. Practitioners should monitor delegated acts on renewable energy sustainability criteria and renewable diesel tax credit eligibility for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
3-Dimethylacrylic Acid Methyl Ester Market
Chemicals
Glyoxylic Acid Market
Chemicals
Global Waterproofing Chemicals Market
Chemicals
Hydrazine Hydrate Market
Chemicals
US Methanol Market
Chemicals
Gold Plating Chemicals Market
Chemicals
1-Methylimidazole Market
Chemicals
Aluminum Chemicals Market
Chemicals
Resorcinol Market
Chemicals
Sunscreen Ingredients Market
Chemicals
Airbag Propellant Chemicals Market
Chemicals
Potassium Zirconium Fluoride Market
Chemicals
Hydrogen Fluoride Pyridine Market
Chemicals
Chromium Trioxide Market
Chemicals
Chlorosilane Market
Chemicals
Imaging Chemicals and Materials Market