
 Para Cresol Market | 2026-2036
Para Cresol Market Size, Share, and Industry Trends Forecast 2026-2036
Para Cresol Market Outlook
Phenol is decoupling from traditional para cresol economics as bio-based feedstock pathways gain process viability. Merck KGaA leverages pharmaceutical-grade purification infrastructure to command premium positioning in European healthcare supply chains. Mitsui Chemicals Inc. anchors Asian supply through integrated cresol derivative complexes in Japan and China. Atul Ltd. specializes in technical-grade para cresol for agrochemical intermediates, competing on scale within India's domestic pesticide formulation sector.
Para cresol, or 4-methylphenol (CAS 106-44-5), is an aromatic organic compound with a melting point of 35.5°C and characteristic phenolic odor, manufactured primarily via sulfonation of toluene followed by alkali fusion or through cumene oxidation byproduct recovery. The compound serves as a critical building block for antioxidants, disinfectants, and pharmaceutical precursors including the synthetic vitamin E intermediate 2,3,5-trimethylhydroquinone. Pharmaceutical-grade para cresol commands the highest margin pool due to stringent purity thresholds and qualification barriers for active pharmaceutical ingredient synthesis. Chemical intermediates represent the fastest-expanding application segment as downstream demand for antioxidant additives in polymer stabilization accelerates across automotive and construction end markets.
REACH registration requirements and the EU Green Deal's chemical sustainability framework are tightening purity and traceability standards for para cresol imports into Europe. The EPA's Toxic Substances Control Act oversight in the United States shapes manufacturing process disclosures and emission controls for cresol derivative facilities. China's MEE environmental compliance protocols and GB standards for hazardous chemical production are elevating capital requirements for new para cresol capacity additions. Stakeholders must monitor regulatory divergence between jurisdictions to optimize multi-region manufacturing footprints and qualification investments.
Market Dynamics
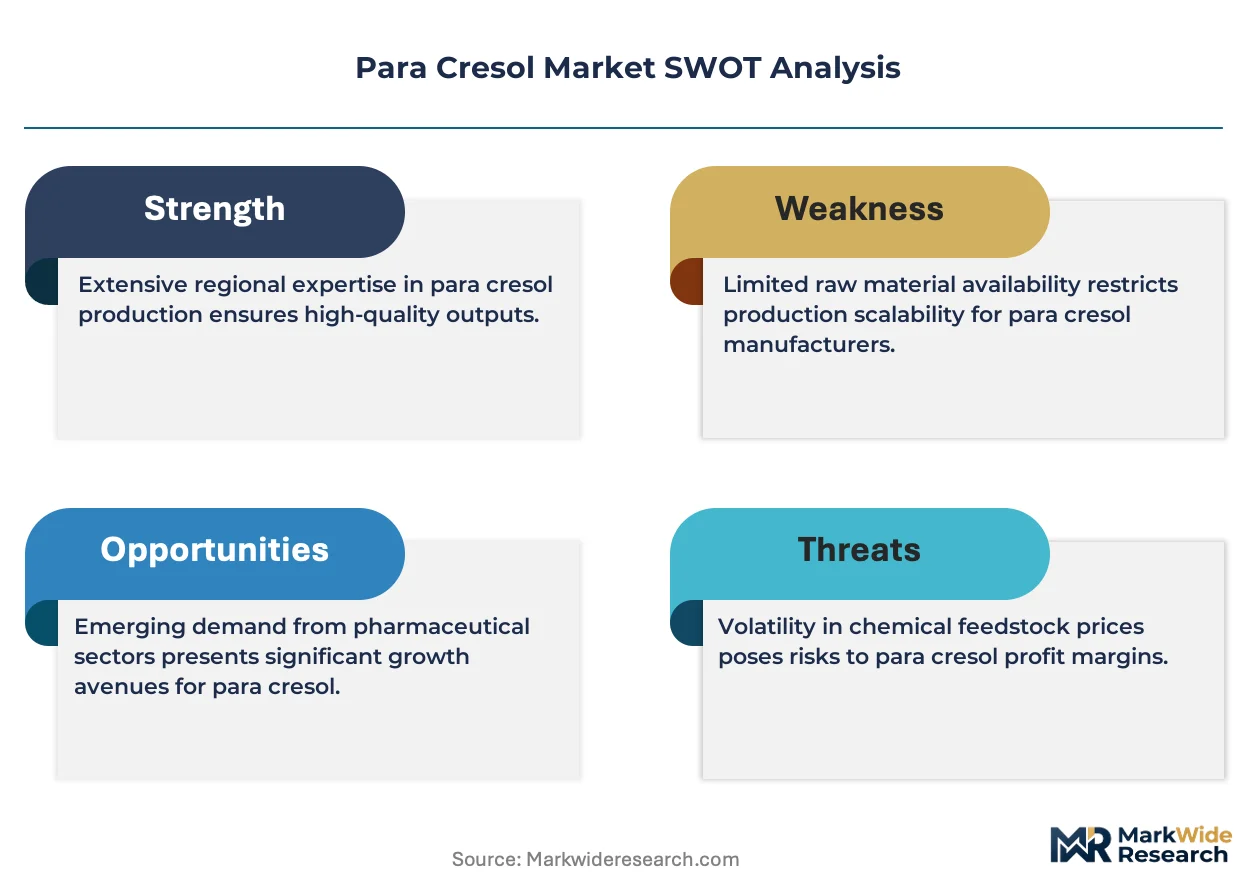
REACH registration dossiers and the EU Green Deal's chemical sustainability framework are forcing para cresol manufacturers to reconfigure purification and traceability systems, compressing margin structures for non-integrated suppliers while rewarding asset-heavy European producers with captive pharmaceutical-grade infrastructure.
Growth Catalysts
- Antioxidant additive demand:Polymer stabilization requirements in automotive underhood applications and construction sealants are pulling technical-grade para cresol through BHT and antioxidant derivative channels.
- EU Green Deal chemical protocols:The EU's sustainable chemistry mandate is accelerating reformulation of active pharmaceutical ingredients, expanding demand for high-purity para cresol as a synthetic vitamin E precursor intermediate.
- Germany's integrated production clusters:Merck KGaA and Lanxess AG maintain contiguous toluene-to-derivative supply chains that reduce qualification friction for REACH-compliant pharmaceutical buyers.
Market Restraints
- Toluene feedstock volatility:Crude oil price swings transmit directly into para cresol variable costs, squeezing margin predictability for non-backward-integrated manufacturers lacking captive aromatics supply.
- Chinese supply concentration:Over half of global technical-grade capacity sits in Shandong and Jiangsu provinces, creating single-geography exposure for antioxidant intermediate buyers.
- Bio-based phenol substitution:Fermentation-derived aromatic feedstocks are achieving pilot-scale viability for select antioxidant applications, threatening long-term petrochemical para cresol demand in polymer additives.
Strategic Opportunities
- Indian agrochemical formulation:Domestic pesticide production under the PLI scheme is expanding technical-grade para cresol consumption for herbicide and fungicide intermediates.
- Pharmaceutical-grade certification:USP and EP qualification for para cresol unlocks premium positioning in FDA-regulated active ingredient synthesis, with qualification timelines creating defensive moats.
- Continuous sulfonation technology:Microreactor process intensification is converging with automated alkali fusion control systems to reduce solvent waste and energy intensity in European production assets.
Industry Challenges
- Process analytical chemistry talent:Real-time purity monitoring for pharmaceutical-grade output requires scarce spectroscopy and chromatography expertise, extending commissioning timelines for new capacity.
- MEE environmental compliance in China:GB standard upgrades for hazardous chemical wastewater treatment are forcing 18-24 month retrofit cycles on legacy toluene sulfonation facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Para Cresol Market |
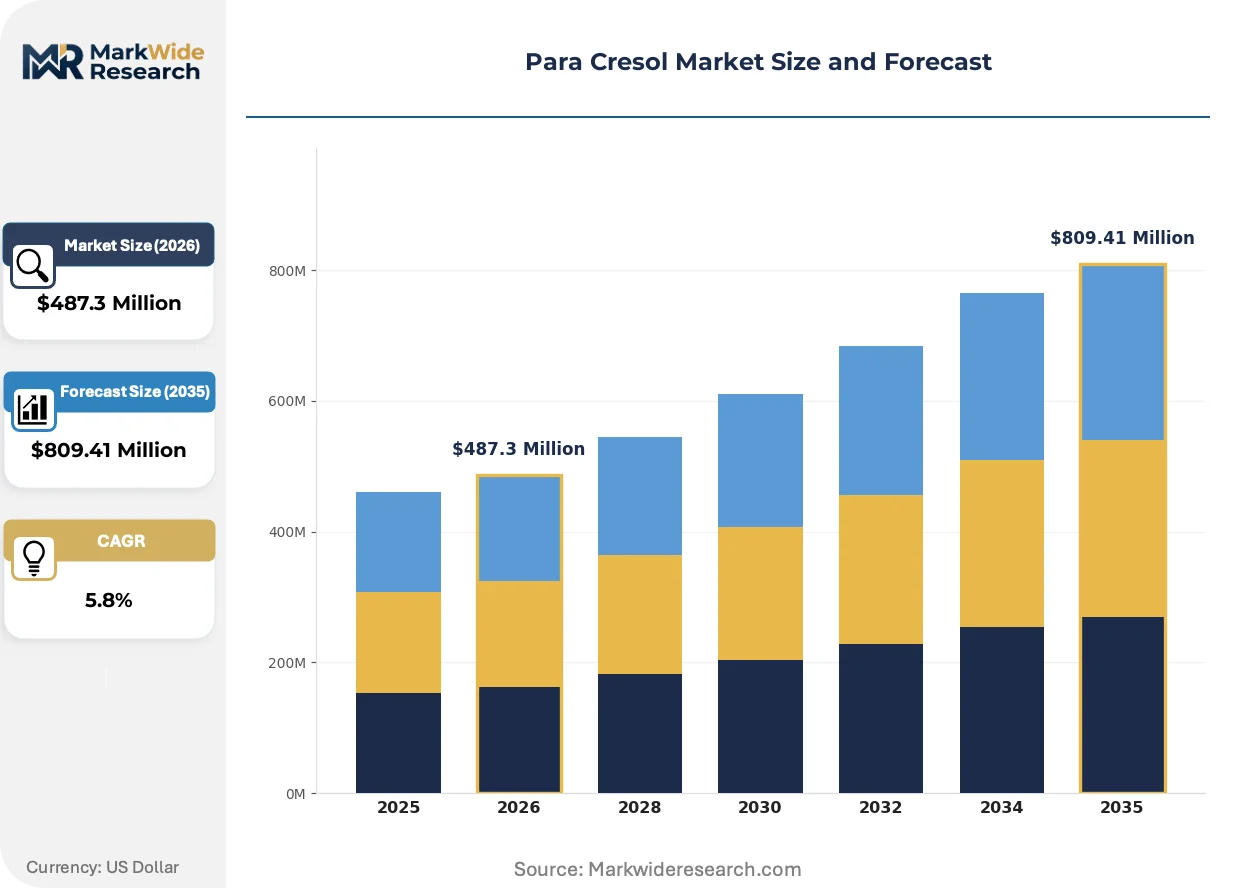
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $809.41 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Technical Grade, Pharmaceutical Grade, Industrial Grade, Research Grade Application: Pesticides, Antiseptics, Pharmaceuticals, Chemical Intermediates End User: Agriculture, Healthcare, Chemical Manufacturing, Research Labs Distribution Channel: Direct Sales, Distributors, Online Sales, Wholesale |
| Companies Covered | Merck KGaA, Mitsui Chemicals Inc., Atul Ltd., Konan Chemical Manufacturing Co., Ltd., Lanxess AG, Sasol Limited, RÜTGERS Group, Nanjing Datang Chemical Co., Ltd., Xiamen Hisunny Chemical Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Para Cresol Market Strategic Shifts
Process intensification and regulatory data transparency are restructuring competitive advantage in para cresol manufacturing, separating asset-light traders from integrated producers with in-house analytical and environmental compliance capabilities.
Continuous flow microreactor sulfonation is replacing batch toluene processing in European installations. Lanxess AG and Merck KGaA have commissioned demonstration units that cut solvent volumes by two-thirds. This hardware is converging with inline Raman spectroscopy for real-time conversion monitoring, compressing batch release timelines from days to hours for pharmaceutical-grade output.
REACH Article 33 supply chain communication obligations now mandate disclosure of para cresol content above 0.1% weight in articles placed on the EU market. The ECHA SCIP database requirement is forcing downstream formulators to map antioxidant additive origins through polymer compounders. Automotive OEMs in Germany are responding by qualifying dual-source para cresol supply for underhood polymer specifications.
Specification-driven procurement is displacing spot-market purchasing for pharmaceutical-grade material. Multi-year offtake agreements with fixed purity bands and audit rights now dominate EU and US buyer behavior. This contracting shift is most visible among generic API manufacturers in India, who are locking in three-year supply frames with European producers to secure EP-grade qualification continuity.
Para Cresol Market Segmentation
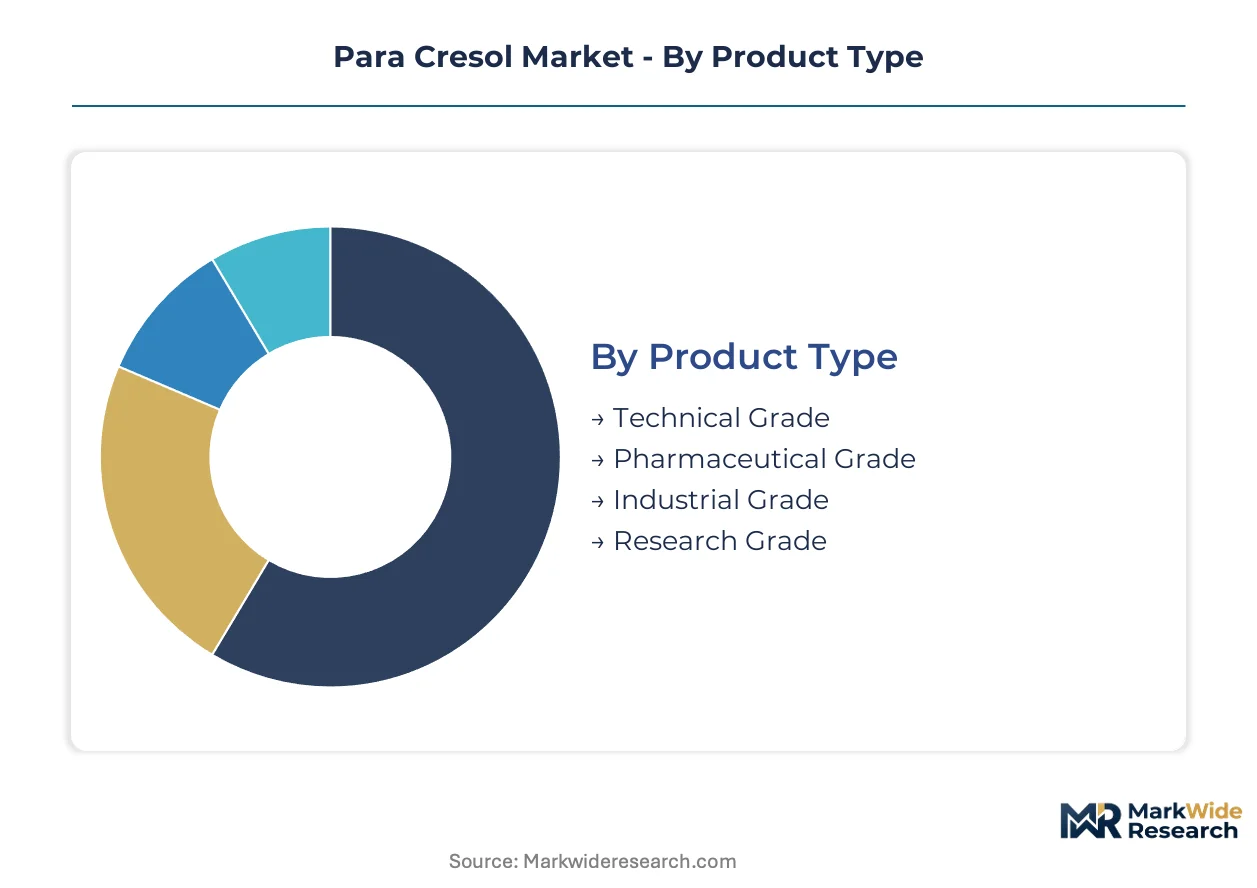
Para cresol segmentation reflects divergent purity thresholds and regulatory burdens across pharmaceutical, industrial, and research applications. Certification requirements fragment procurement patterns, with EP-grade and USP-grade specifications commanding multi-year qualification timelines that lock in supplier relationships.
Product Type:
Pharmaceutical-grade material carries the heaviest certification load, requiring EP, USP, and FDA DMF submissions that stretch 18-36 months, while technical-grade para cresol moves under standard chemical handling protocols with minimal regulatory friction.
- Technical Grade:Purity specifications typically range 98-99% with controlled moisture and sulfur content for antioxidant intermediate synthesis. Agrochemical formulators in India and polymer stabilizer producers in China absorb the largest volumes, though feedstock volatility squeezes margin predictability for non-integrated suppliers.
- Pharmaceutical Grade:Demands 99.5%+ purity with full impurity profiling per ICH Q3C guidelines and metal catalyst residue limits below 10 ppm. Synthetic vitamin E precursor manufacturers and API houses in Germany and Switzerland pay premiums exceeding 40% over technical grades to secure locked supply frames.
- Industrial Grade:Standard 95-98% purity band serves disinfectant and general chemical synthesis applications with minimal certification overhead.
- Research Grade:Ultra-high purity lots with comprehensive COAs and batch traceability for analytical standards and method development in academic and contract research settings.
Leading the category by volume: Technical Grade. Growing fastest: Pharmaceutical Grade.
Application:
Application segments split along end-market regulatory intensity, with pharmaceutical and antiseptic channels demanding full supply chain documentation while pesticide and intermediate applications prioritize cost efficiency.
- Pesticides:Herbicide and fungicide intermediate consumption concentrates in India's domestic formulation sector under PLI scheme expansion. Atul Ltd. and UPL anchor technical-grade offtake for chlorpyrifos and glyphosate derivative synthesis.
- Antiseptics:Disinfectant formulations leverage para cresol's phenolic biocidal properties in institutional and household cleaning products, with EPA registration requirements shaping US market access.
- Pharmaceuticals:Synthetic vitamin E intermediate 2,3,5-trimethylhydroquinone production drives EP-grade demand, with Merck KGaA and DSM-Firmenich maintaining captive purification infrastructure to serve European healthcare supply chains.
- Chemical Intermediates:BHT antioxidant and polymer stabilizer synthesis represents the steepest expansion trajectory, with automotive underhood specifications and construction sealant formulations pulling volume through Mitsui Chemicals' integrated derivative complexes.
Dominant by volume: Chemical Intermediates. Climbing the fastest: Pharmaceuticals.
End User:
End-user procurement patterns stratify by qualification depth, with healthcare and research buyers demanding audit rights and fixed purity bands while agriculture and chemical manufacturing favor spot-market flexibility.
- Agriculture:Domestic pesticide producers in India and Brazil absorb technical-grade volumes through distributor networks with seasonal purchasing patterns tied to planting cycles.
- Healthcare:Generic API manufacturers and vitamin E producers lock in three-year supply agreements with European producers to secure EP-grade qualification continuity and FDA inspection readiness.
- Chemical Manufacturing:Polymer compounders and antioxidant blenders in Germany, Japan, and China source through direct sales channels with specification-driven procurement displacing spot-market purchasing.
- Research Labs:Academic institutions and CROs purchase research-grade material through specialized distributors with small-lot flexibility and expedited COA turnaround.
Largest volume share: Chemical Manufacturing. Fastest procurement shift: Healthcare.
Distribution Channel:
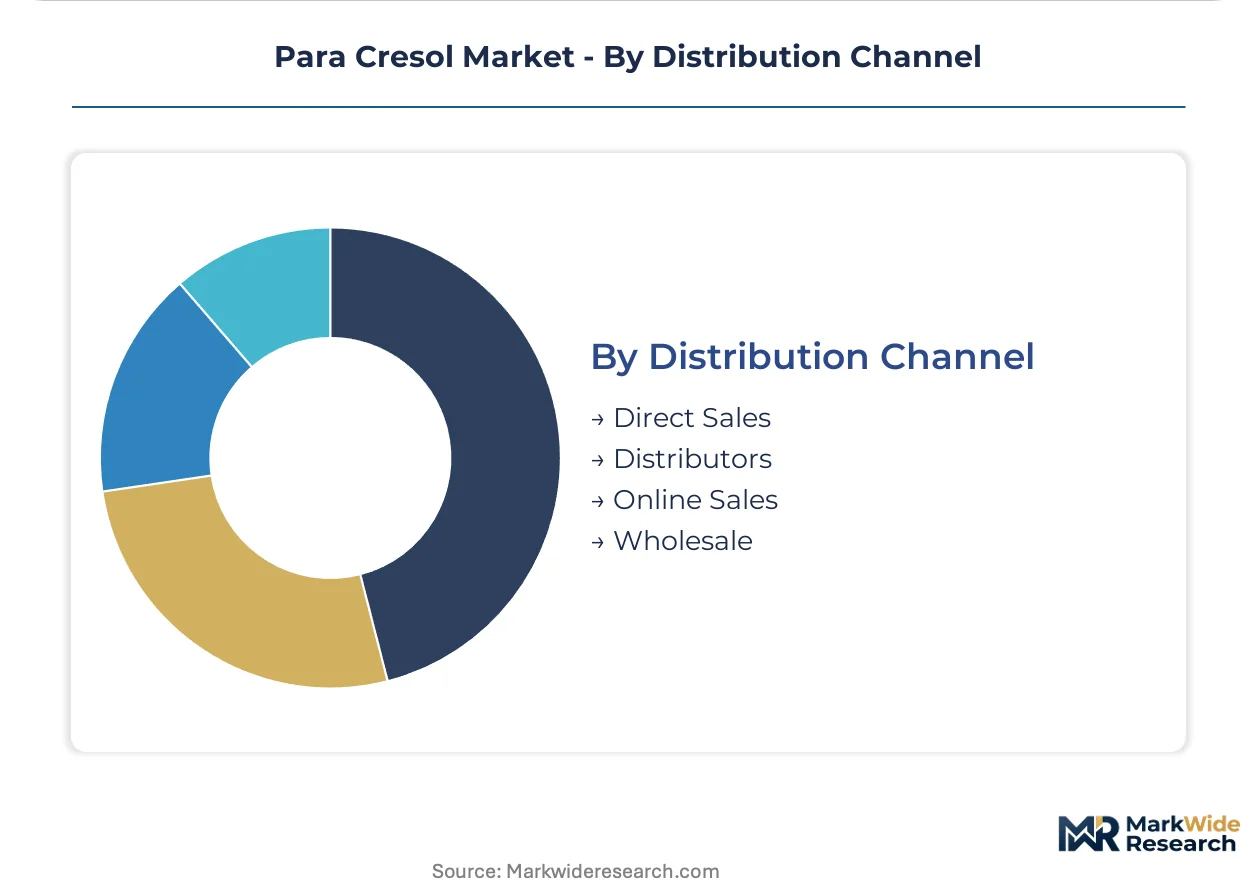
Channel selection correlates with grade tier and buyer scale, with pharmaceutical-grade material bypassing distributors entirely while technical-grade flows through fragmented wholesale networks.
- Direct Sales:Pharmaceutical-grade and large-volume industrial accounts contract directly with producers like Merck KGaA, Lanxess, and Mitsui Chemicals to secure multi-year frames with fixed pricing and audit provisions.
- Distributors:Regional chemical distributors stock technical-grade material for mid-tier agrochemical and polymer customers in India, China, and Southeast Asia with 30-60 day inventory cycles.
- Online Sales:Research-grade and small-lot industrial purchases migrate to B2B platforms for specification comparison and rapid fulfillment, though pharmaceutical buyers avoid this channel due to qualification requirements.
- Wholesale:Bulk technical-grade volumes move through commodity chemical wholesalers with minimal value-add, serving price-sensitive pesticide intermediate producers.
Highest volume flow: Direct Sales. Channel shift gaining momentum: Online Sales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pharmaceutical-grade para cresol demand concentrates in Germany, where integrated toluene-to-derivative supply chains serve European healthcare manufacturers under REACH compliance mandates. Technical-grade consumption clusters in China and India for antioxidant intermediate and agrochemical synthesis. Regional regulatory divergence is fragmenting procurement patterns as buyers seek qualified supply within jurisdiction-specific compliance frameworks.
Germany
Merck KGaA and Lanxess AG anchor European pharmaceutical-grade supply through contiguous production clusters in Darmstadt and Cologne. The EU Green Deal's chemical sustainability protocols and REACH Article 33 disclosure requirements are tightening traceability standards for para cresol imports. The Rhine-Ruhr industrial corridor hosts integrated sulfonation and purification assets serving synthetic vitamin E precursor manufacturers.
China
Shandong and Jiangsu provinces contain over half of global technical-grade capacity, supplying antioxidant intermediate demand for polymer stabilizer producers. The MEE's GB standard upgrades for hazardous chemical wastewater treatment are forcing extended retrofit cycles on legacy toluene sulfonation facilities. Nanjing and Xiamen chemical parks concentrate para cresol derivative manufacturing for domestic BHT and agrochemical channels.
India
Domestic pesticide formulation under the PLI scheme is expanding technical-grade para cresol consumption for herbicide and fungicide intermediates. CDSCO and BIS certification requirements are elevating entry barriers for pharmaceutical-grade imports. Gujarat and Maharashtra industrial zones host agrochemical formulators sourcing through regional distributor networks with seasonal purchasing tied to planting cycles.
United States
EPA Toxic Substances Control Act oversight shapes manufacturing process disclosures and emission controls for cresol derivative facilities serving polymer compounders. The Gulf Coast petrochemical corridor provides captive toluene feedstock integration for antioxidant intermediate producers. FDA-regulated API manufacturers source pharmaceutical-grade material through multi-year supply agreements with European producers to secure USP qualification continuity.
Japan
Mitsui Chemicals anchors Asian pharmaceutical-grade supply through integrated cresol derivative complexes serving regional healthcare and electronics manufacturers. METI chemical management regulations and JIS standards govern purity specifications for polymer stabilizer applications. The Chubu industrial region around Nagoya concentrates antioxidant additive production for automotive underhood specifications.
Para Cresol Market Competitive Environment
Capacity expansion dominates the current landscape as integrated producers commission continuous flow microreactor sulfonation units to reduce solvent volumes and energy intensity. The vendor base splits between asset-heavy European pharmaceutical-grade specialists with captive purification infrastructure and scale-driven Asian technical-grade producers serving commodity antioxidant channels. Three strategic archetypes define positioning: integrated toluene-to-derivative manufacturers, pharmaceutical-grade purification specialists, and regional technical-grade volume players. M&A activity concentrates on acquiring REACH-compliant European assets, while strategic partnerships lock in multi-year offtake agreements with fixed purity bands and audit rights.
Within the integrated pharmaceutical-grade tier, Merck KGaA and Lanxess AG exemplify European producers leveraging contiguous supply chains to reduce qualification friction for REACH-compliant buyers. Atul Ltd. occupies a position within the technical-grade specialist archetype, serving India's domestic agrochemical formulation sector. Mitsui Chemicals Inc. anchors Asian supply through integrated derivative complexes in Japan and China. These three company structures—German AG, Indian Ltd., and Japanese Inc.—represent the geographic and regulatory segmentation shaping procurement patterns across pharmaceutical and industrial end markets.
| Leading Market Players |
|---|
| Merck KGaA |
| Mitsui Chemicals Inc. |
| Atul Ltd. |
| Konan Chemical Manufacturing Co., Ltd. |
| Lanxess AG |
| Sasol Limited |
| RÜTGERS Group |
| Nanjing Datang Chemical Co., Ltd. |
| Xiamen Hisunny Chemical Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Toluene feedstock volatility transmits directly through para cresol manufacturing economics, with crude oil-linked aromatics pricing stratifying downstream tiers from pharmaceutical-grade premiums to technical-grade commodity levels. REACH compliance investments and purification infrastructure costs widen spreads between EP-certified supply and standard industrial material.
Pricing Analysis
Volume concentration in technical-grade antioxidant intermediates runs against margin concentration in pharmaceutical-grade synthetic vitamin E precursors. Three-tier pricing structure across pharmaceutical, technical, and industrial grades reflects purity thresholds and certification burdens, with EP-grade material commanding substantial premiums over standard specifications. Pricing pressure stems from Chinese technical-grade oversupply and bio-based phenol substitution threats in polymer additives. Agrochemical formulators in India exhibit highest price sensitivity, while European healthcare manufacturers prioritize qualification continuity over unit economics.
Supply Chain Analysis
India's PLI scheme domestic-content mandates for pesticide intermediates are reshaping sourcing patterns for technical-grade material, redirecting volumes from Chinese exporters toward local producers. Supply concentrates in Germany for pharmaceutical-grade, China for technical-grade antioxidant intermediates, and India for agrochemical channels. Toluene sulfonation capacity, cumene oxidation byproduct recovery systems, and alkali fusion infrastructure constitute critical input dependencies. Single-geography exposure in Shandong and Jiangsu provinces creates structural vulnerability for global antioxidant intermediate buyers. Distribution runs through direct sales for pharmaceutical-grade and fragmented wholesale networks for technical-grade commodity volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH compliance costs and purification infrastructure requirements are forcing consolidation among non-integrated para cresol suppliers, eliminating marginal players lacking captive toluene supply or pharmaceutical-grade certification capabilities.
For Market Incumbents: Extend qualification moats by commissioning continuous flow microreactor sulfonation units with inline spectroscopic monitoring, cutting batch release timelines from days to hours. Lock in multi-year offtake agreements with fixed purity bands and audit rights to defend against emerging bio-based phenol substitutes in polymer stabilization applications. Prioritize backward integration into captive toluene supply to insulate margin structures from crude oil volatility. For New Entrants and Emerging Players: The 40%-plus price gap between pharmaceutical-grade and technical-grade para cresol opens viable entry space for mid-purity specialists serving agrochemical intermediate demand in India's PLI-supported pesticide formulation sector. Target Gujarat and Maharashtra industrial zones with seasonal purchasing patterns tied to planting cycles, leveraging regional distributor relationships rather than direct sales infrastructure. Pursue CDSCO certification pathways to access domestic pharmaceutical intermediate demand as European import barriers tighten. For Investors and Strategic Acquirers: Commissioning announcements for REACH-compliant European purification assets is the leading indicator that pharmaceutical-grade supply scarcity is intensifying, signaling acquisition timing for qualified production infrastructure. Frame long-term viability around synthetic vitamin E precursor demand durability and antioxidant additive growth in automotive underhood applications. Monitor MEE environmental compliance retrofit cycles in China as inflection signals for technical-grade supply disruption and price volatility.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Toluene Supply | Captive aromatics sourcing insulates Merck KGaA and Lanxess AG from crude oil volatility. |
| Continuous Flow Microreactor Sulfonation | Lanxess AG demonstration units cut solvent volumes by two-thirds for REACH-compliant output. |
| Pharmaceutical-Grade Certification Investment | EP and USP qualification creates 18-36 month defensive moats against technical-grade competitors. |
| Long-Term Supply Agreement Structuring | Multi-year frames with fixed purity bands dominate EU and US generic API manufacturer procurement. |
| Joint Venture in Indian Agrochemical Corridor | PLI scheme expansion in Gujarat and Maharashtra opens technical-grade volume opportunities. |
Study Parameters
Multi-period observation of toluene feedstock pricing, REACH registration timelines, and MEE environmental compliance cycles anchored the trend analysis, supplemented by interviews with plant managers at European sulfonation facilities, procurement leads at polymer compounders, distribution channel partners in India, and technical R&D directors at antioxidant derivative manufacturers. Secondary validation drew from customs and trade data, Cefic chemical industry reports, SEC 10-K filings of listed producers, and ECHA registration dossiers. Bottom-up capacity modeling and top-down demand segmentation were triangulated to cross-validate volume estimates.
Input-output matrices mapped toluene consumption through sulfonation and cumene oxidation pathways to para cresol output across pharmaceutical, technical, and industrial grade tiers, with segmentation by end-use industry, regional production hub, and certification level. CAGRs were derived from regression analysis against polymer stabilization demand, synthetic vitamin E precursor consumption, and agrochemical formulation growth across the projection horizon. Forecast inputs incorporated bio-based phenol substitution trajectories and regulatory compliance cost escalations.
Inputs from ECHA registration databases and Indian customs records were available through the study window; gaps in real-time Chinese MEE enforcement data introduce uncertainty bands around technical-grade capacity utilization assumptions. Forecasts reflect documented assumptions regarding REACH implementation timelines and PLI scheme disbursement rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemicals
Phenothiazine Market
Chemicals
Chemical As a Service Market
Chemicals
Malic Acid Market
Chemicals
(S)-(+)-2-Amino-1-Propanol Market
Chemicals
Peracetic Acid Market
Chemicals
Sodium Cyanide Market
Chemicals
Rocket Propellant Chemicals Market
Chemicals
Fluoroantimonic Acid Market
Chemicals
Hydrophobing Agents Market
Chemicals
Global Organobromine Market
Chemicals
Lauryl Myristyl Alcohol Market
Chemicals
1,3-Dibromoadamantane Market
Chemicals
RO Membrane Chemicals Market
Chemicals
Cupric Chloride Market
Chemicals
Global Aluminum Hydroxide Market
Chemicals
Pyrimidine Market