
 Fat Replacers Salt Reducers and Replacers Market | 2026-2036
Fat Replacers Salt Reducers and Replacers Market Size, Share, and Industry Trends Forecast 2026-2036
Fat Replacers Salt Reducers and Replacers Market Intelligence
The increasing influence of nutraceutical companies and private labelers over large, established food manufacturers is redrawing the competitive landscape for ingredient sourcing. Large-scale producers like Cargill leverage their extensive global supply chains to serve multinational food conglomerates. In contrast, Kerry Group specializes in customized, functional ingredient systems tailored for mid-sized and specialty food producers. Ingredion differentiates through its strong R&D focus on plant-based and carbohydrate-based replacers.
Fat replacers and salt reducers are functional food ingredients designed to mimic the sensory and physical properties of fats and sodium chloride in processed foods. Carbohydrate-based fat replacers often utilize hydrocolloids to build viscosity and mouthfeel, while salt replacers may use potassium chloride or yeast extracts to deliver a savory taste. Carbohydrate-based products command the largest volume share due to cost-effectiveness and versatility. Protein-based and microbial-derived ingredients are expanding quickly, driven by formulation needs in meat alternatives and dairy products.
Regulations from bodies such as the US Food and Drug Administration (FDA), the European Food Safety Authority (EFSA), and the Food Safety and Standards Authority of India (FSSAI) directly shape market dynamics. These agencies influence the market by setting limits on sodium content and defining labeling requirements for "low-fat" or "reduced sodium" claims. Navigating the trade-off between achieving authentic taste profiles with advanced replacers and managing formulation costs remains the central challenge for food manufacturers.
Market Dynamics
Intensifying regulatory pressure on sodium and fat content in processed foods serves as the central force shaping the market. Mandates from agencies like the FDA and public health initiatives in the United Kingdom are compelling manufacturers to prioritize reformulation, driving consistent demand.
Growth Catalysts
- Sodium Reduction Mandates:Government-led initiatives and WHO recommendations to lower sodium intake are pushing food processors in the bakery, sauces, and processed meat sectors to adopt salt replacers like potassium chloride and yeast extracts.
- Clean Label Movement:Consumer preference for simple, recognizable ingredients is boosting demand for plant-based fat replacers, such as starches, fibers, and gums, which can be listed with familiar names on product labels.
- Fermentation Technology:Advances in microbial fermentation are enabling the cost-effective production of novel protein-based replacers and savory yeast extracts, providing new tools for formulators in the dairy and meat alternative segments.
Market Restraints
- Cost-Performance Trade-Off:Advanced protein-based and microbial-derived replacers carry a significant cost premium over traditional fats and salt, limiting their use in price-sensitive product categories and emerging economies.
- Sensory Challenges:Many replacers introduce undesirable sensory attributes, such as the metallic off-taste of potassium chloride or the altered mouthfeel from certain hydrocolloids, which can negatively impact consumer acceptance.
- Ingredient Sourcing Bottlenecks:The supply of specialized ingredients, including certain novel fibers and highly functional yeast extracts, is concentrated among a few suppliers, creating potential for price volatility and supply chain disruptions.
Strategic Opportunities
- Plant-Based Formulations:The rapidly expanding market for plant-based meat and dairy alternatives presents a significant opportunity for functional replacers that can mimic the texture, mouthfeel, and juiciness of animal-derived fats.
- Synergistic Ingredient Systems:Developing and marketing blended systems that combine different types of replacers, such as a hydrocolloid with a yeast extract, offers a path to overcome individual ingredient limitations and achieve superior sensory profiles.
- Expansion in Southeast Asia:Markets like Indonesia and Vietnam, with their rising processed food consumption and nascent health and wellness trends, represent underpenetrated regions for both fat and salt reduction ingredients.
Industry Challenges
- Complex Reformulation Cycles:Replacing fat and salt without compromising taste, texture, and shelf-life requires extensive R&D, prolonged testing, and significant investment, posing a major operational hurdle for food manufacturers.
- Navigating Global Labeling Laws:Adhering to disparate international regulations from bodies like the FDA, EFSA, and FSSAI regarding "low-fat" or "reduced-sodium" claims adds complexity and cost to product development and export strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fat Replacers Salt Reducers and Replacers Market |
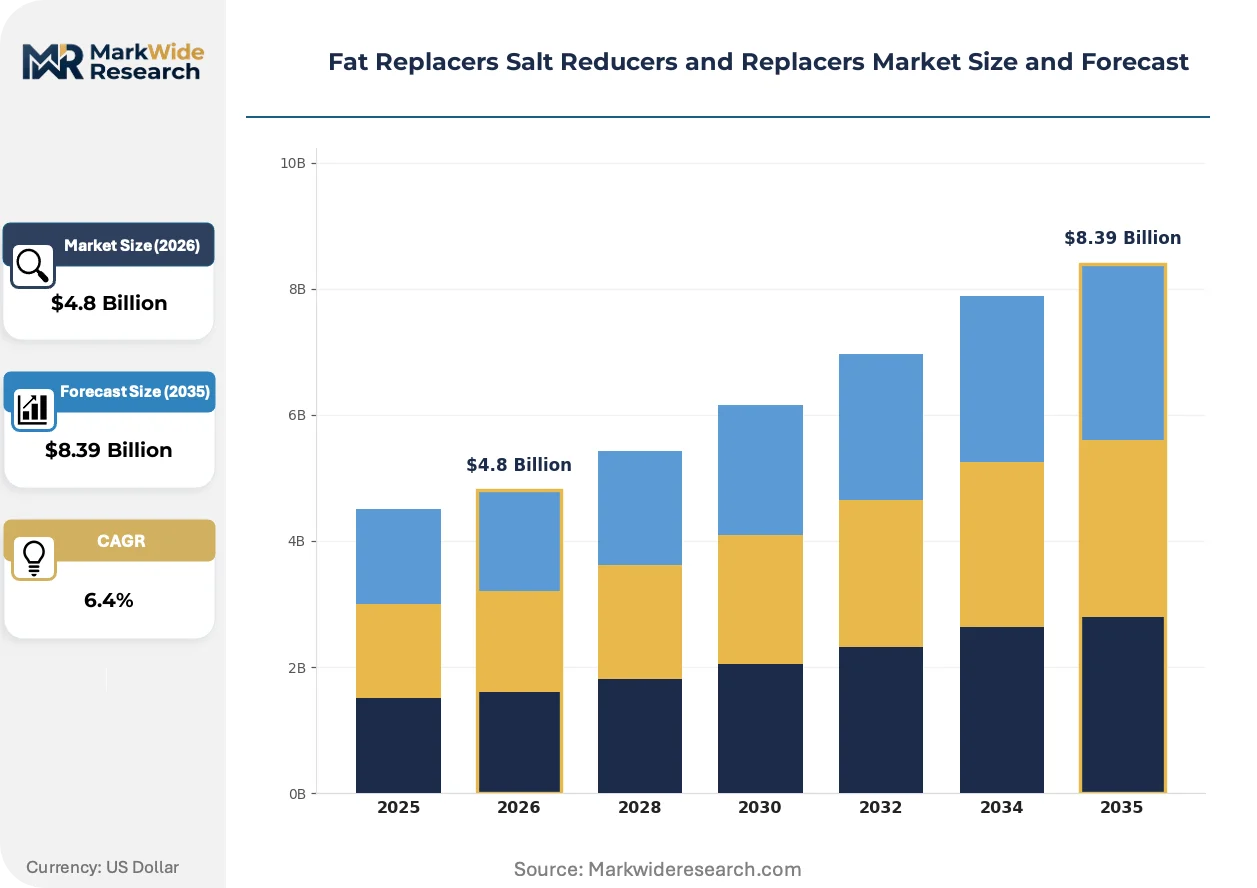
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carbohydrate-Based, Protein-Based, Fat-Based, Emulsions, Microbial-Derived Application: Dairy Products, Bakery & Confectionery, Meat Alternatives, Beverages, Sauces & Dressings End User: Food Manufacturers, Nutraceutical Companies, Ingredient Suppliers, Foodservice Providers, Private Labelers Distribution Channel: Direct Sales, Distributors, Online Retail, Specialty Stores, Food Ingredient Traders |
| Companies Covered | Cargill, Tate & Lyle, Archer Daniels Midland, Ingredion, International Flavors & Fragrances, Symrise, Givaudan, dsm-firmenich, Kerry Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fat Replacers Salt Reducers and Replacers Market Strategic Shifts & Innovations
The market's evolution is defined by a move away from simple, single-ingredient substitution toward the adoption of multi-functional systems. These advanced ingredients are designed not only to reduce fat or salt but also to improve texture, enhance flavor, and support clean-label declarations.
Enzymatic modification of starches and fibers is a key innovation creating sophisticated fat mimetics. Food producers in the bakery and dairy sectors are increasingly adopting these ingredients to achieve specific textures and a creamy mouthfeel while maintaining a clean label. This technology is decomposing the traditional boundary between a simple texturizer and a functional fat replacer, leading to the creation of versatile, high-performance ingredients.
Front-of-pack labeling (FOPL) systems, such as the warning labels used in Chile and Mexico, are becoming a powerful regulatory trend. These policies directly inform consumers about high levels of sodium, sugar, and fats, creating a strong incentive for manufacturers to reformulate their products. The prepared meals and savory snacks categories are most affected, experiencing accelerated demand for effective salt and fat reduction solutions to avoid negative labeling.
A distinct behavioral shift is occurring in how food manufacturers source these ingredients, moving from transactional purchasing to seeking integrated formulation partnerships. This change disrupts the conventional distributor model that focuses on component sales, favoring suppliers who offer application expertise and co-development services. This trend is most prominent among mid-sized food companies in Europe and North America that lack extensive internal R&D capabilities for complex reformulation projects.
Fat Replacers Salt Reducers and Replacers Market Segmentation
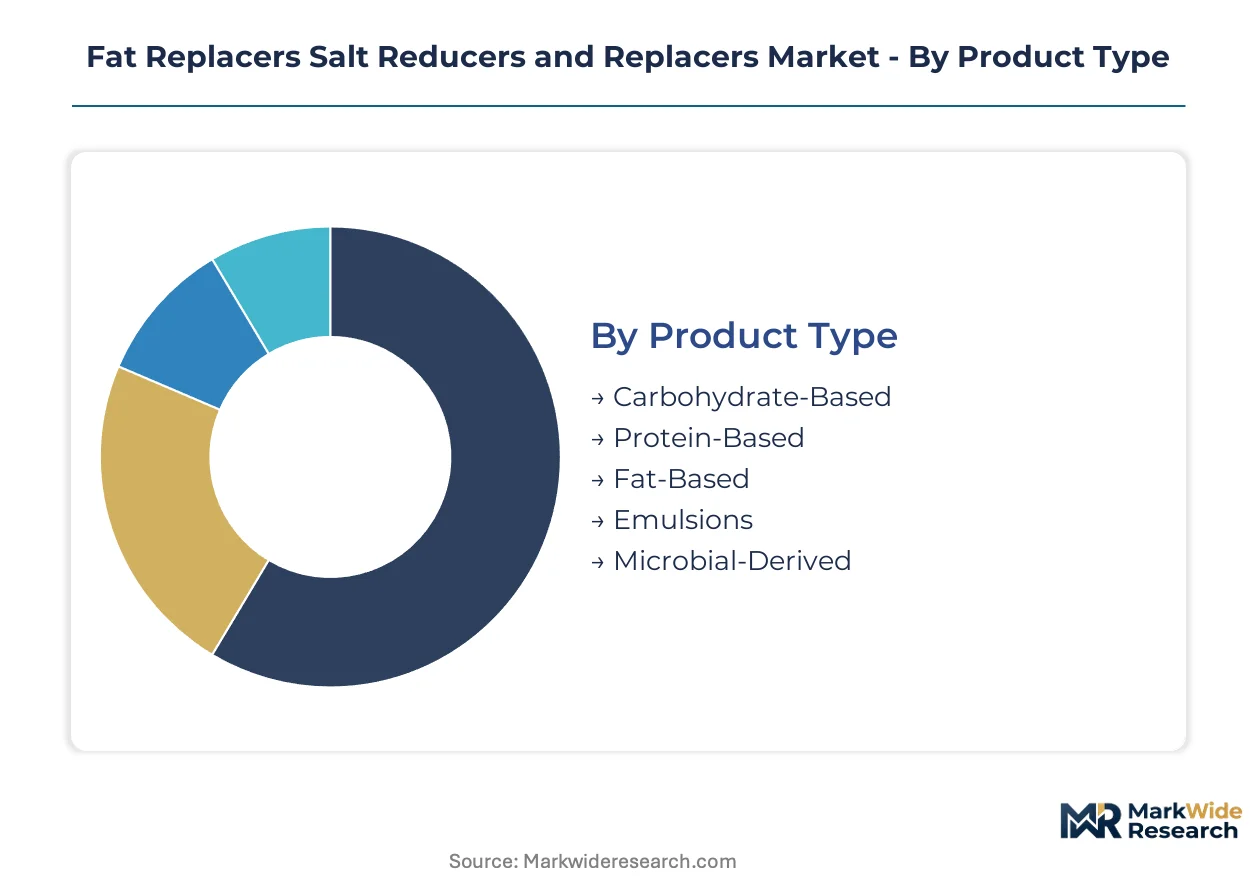
The Fat Replacers Salt Reducers and Replacers Market demonstrates diverse needs across various product types and end-user segments. Understanding this segmentation is crucial for manufacturers to effectively address specific reformulation challenges and target growth opportunities within the processed food industry.
Product Type:
The market for fat replacers and salt reducers faces significant pressure to provide substitutes that maintain sensory attributes while meeting health targets.
- Carbohydrate-Based:These ingredients, often derived from starches, fibers, and hydrocolloids, build viscosity and mouthfeel in food products. Demand concentrates in cost-sensitive markets and the bakery & confectionery sector due to their versatility and clean label potential.
- Microbial-Derived:Produced through advanced fermentation, this category includes novel proteins and savory yeast extracts. Their functional properties are increasingly sought after in meat alternatives and dairy products to enhance flavor and texture.
- Protein-Based:These replacers contribute to texture and nutritional profiles, finding application primarily in dairy and meat alternative formulations.
- Fat-Based:This segment includes structured lipids and modified fats designed to mimic traditional fat properties with reduced caloric content.
- Emulsions:Comprising water-in-oil or oil-in-water systems, emulsions are engineered to provide specific mouthfeel and stability in various food matrices.
Carbohydrate-Based products retain volume leadership; Microbial-Derived ingredients hold the steepest expansion curve.
Application:
Different food applications present unique formulation challenges for integrating fat and salt reduction ingredients.
- Bakery & Confectionery:This sector requires replacers that can maintain texture, moisture, and sweetness profiles in products like cakes, cookies, and chocolates. Global processed food consumption drives consistent demand for these solutions.
- Meat Alternatives:Formulations in this rapidly expanding segment demand sophisticated replacers to mimic the juiciness, texture, and mouthfeel of animal-derived fats and proteins. Plant-based trends significantly influence ingredient selection here.
- Dairy Products:Replacers in dairy focus on maintaining creaminess, texture, and mouthfeel while enabling fat reduction claims for yogurts and cheeses.
- Beverages:Ingredients in beverages primarily address sugar reduction, mouthfeel improvement, and flavor masking in various drink formulations.
- Sauces & Dressings:This application utilizes replacers for viscosity control, emulsification, and significant sodium reduction without compromising flavor.
The bakery and confectionery sector drives significant volume; meat alternatives show the most dynamic expansion.
End User:
The varied strategic priorities of different end-users shape their procurement and application of fat and salt reduction ingredients.
- Food Manufacturers:These large-scale entities require broad ingredient portfolios for diverse product lines and face consistent pressure for reformulation due to regulatory compliance. Managing the cost-performance trade-off is a central concern.
- Private Labelers:Focused on brand differentiation and cost-effectiveness for retailer-owned brands, private labelers seek tailored solutions for healthier product options. Retailer pressure for healthier options drives their ingredient choices.
- Nutraceutical Companies:These companies integrate functional ingredients for specific health claims, focusing on the nutritional benefits of replacers.
- Ingredient Suppliers:These entities develop and supply a wide range of functional ingredients, often offering custom solutions and technical support to manufacturers.
- Foodservice Providers:Foodservice operations require bulk solutions for menu reformulation and operational efficiency in large-scale culinary applications.
Food manufacturers represent the core demand; private labelers are gaining share rapidly.
Distribution Channel:
Supply chain efficiency and access to specialized ingredients are managed through various distribution channels.
- Direct Sales:This channel facilitates direct collaboration between large ingredient suppliers and major food conglomerates, often involving custom formulations and extensive technical support. It is favored for high-volume, strategic partnerships.
- Distributors:Distributors provide essential market reach and logistics efficiency for mid-sized food producers and regional markets. They offer broad product portfolios and local inventory management.
- Online Retail:This channel serves niche ingredient needs and smaller manufacturers, offering transparency and accessibility for specialized products.
- Specialty Stores:These outlets cater to premium ingredient demands from artisan food producers and smaller-batch manufacturers.
- Food Ingredient Traders:Traders focus on commodity ingredients, facilitating price negotiation and bulk procurement for various industrial buyers.
Direct sales channels dominate for large-scale procurement; online retail is expanding quickly for specialized ingredients.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil's extensive agricultural infrastructure and export capabilities underwrite its prominent role in the global food ingredient market. This infrastructure supports a rapidly expanding processed food industry, driving significant demand for fat replacers and salt reducers. Regulatory shifts and consumer health trends further shape ingredient procurement across key geographies.
United States
Consumer preference for healthier options drives demand for clean-label fat replacers and sodium reduction solutions. The US Food and Drug Administration (FDA) sets strict guidelines for "low-fat" and "reduced sodium" claims. California's food innovation hubs actively develop novel plant-based alternatives and functional ingredients.
United Kingdom
Public health campaigns targeting obesity and high blood pressure accelerate the adoption of salt reducers and fat replacers. The UK's Food Standards Agency (FSA) promotes voluntary sodium reduction targets across food categories. London and the Midlands house numerous food manufacturers focusing on product reformulation for healthier offerings.
Germany
Strong R&D capabilities and a sophisticated food processing industry generate demand for advanced functional ingredients. The European Food Safety Authority (EFSA) ensures ingredient safety and regulates health claims for fat and salt reduction. Bavaria's food technology centers collaborate on developing innovative protein-based and carbohydrate-based replacers.
India
Rising processed food consumption and a growing middle class fuel demand for healthier food options, including fat and salt reduced products. The Food Safety and Standards Authority of India (FSSAI) implements regulations to address nutritional content in packaged foods. Maharashtra and Gujarat's food processing zones witness a surge in ingredient adoption for snacks.
Brazil
The country's expanding processed food industry, particularly in bakery and confectionery, creates substantial demand for cost-effective replacers. Brazil's national health surveillance agency (ANVISA) increasingly focuses on front-of-pack labeling for high-sodium and high-fat products. São Paulo's industrial clusters integrate these ingredients into local food production.
Fat Replacers Salt Reducers and Replacers Market Key Industry Players
Listed leaders compete with private specialists across ingredient innovation and global supply chain optimization. The market exhibits a tiered structure, with large multinational ingredient suppliers alongside specialized functional ingredient providers. Strategic archetypes include broad-portfolio suppliers leveraging scale and niche players focusing on specific application expertise. Dominant competitive moves involve strategic partnerships for co-development and continuous portfolio diversification into plant-based and microbial-derived solutions.
Within the global ingredient supply landscape, Cargill and Ingredion exemplify large-scale, diversified ingredient suppliers leveraging extensive global supply chains. Cargill, a US-based corporation, anchors the segment requiring broad ingredient portfolios for multinational food conglomerates. Ingredion, another US-based company, occupies a position through its strong research and development focus on plant-based and carbohydrate-based replacers. Kerry Group, an Ireland-based public limited company, represents specialists providing customized, functional ingredient systems tailored for mid-sized and specialty food producers.
| Leading Market Players |
|---|
| Cargill |
| Tate & Lyle |
| Archer Daniels Midland |
| Ingredion |
| International Flavors & Fragrances |
| Symrise |
| Givaudan |
| dsm-firmenich |
| Kerry Group |
| Others |
Cost & Logistics Intelligence
US Food and Drug Administration (FDA) guidelines and European Food Safety Authority (EFSA) safety regulations gate both ingredient supply qualification and subsequent price differentiation. This ensures only approved functional ingredients enter the market, creating distinct pricing tiers based on regulatory compliance and functional performance.
Pricing Analysis
Contract-based long-term offtake agreements, often with volume-based discounts, dominate large-scale ingredient procurement. Pricing stratifies across high-performance customized functional systems and more commoditized carbohydrate-based replacers. Price differentiation stems from the customization level required for specific food applications and the certification level for clean-label claims. Cost compression in generic carbohydrate-based replacers intensifies due to widespread availability. Private labelers exhibit the highest price sensitivity, while nutraceutical companies prioritize functional benefits over cost.
Supply Chain Analysis
Extended inventory cycles for specialized ingredients and long lead times for novel microbial-derived solutions characterize the supply chain. Supply concentrates in Brazil for agricultural inputs, Germany for advanced functional ingredient R&D, and specific regions of China for basic raw materials. The market draws from specific plant-based proteins, starches, hydrocolloids, and specialized yeast strains. Ingredient sourcing bottlenecks for highly functional yeast extracts represent a structural risk. Distribution runs through direct sales channels for major food conglomerates and through distributors for mid-sized producers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The increasing influence of nutraceutical companies and private labelers over large, established food manufacturers is reshaping buyer power. This shift compels ingredient suppliers to adapt their offerings and engagement models.
For Market Incumbents:
Secure long-term supply agreements for critical raw materials, such as specialized plant proteins and hydrocolloids, to mitigate commodity price volatility. Invest in proprietary fermentation technologies to differentiate microbial-derived solutions, countering the rapid expansion of specialized ingredient providers. Expand global supply chain capabilities to support diverse ingredient sourcing and optimize logistics for multinational food conglomerates. Focus R&D on synergistic ingredient systems that deliver superior sensory attributes.
For New Entrants and Emerging Players:
Application expertise and co-development services represent a significant service-layer gap where incumbents under-serve mid-sized food manufacturers. Target the rapidly expanding plant-based meat and dairy alternative segments with novel protein-based and microbial-derived replacers. Offer customized, blended ingredient systems that address specific taste and texture challenges. A go-to-market angle focused on integrated formulation partnerships can accelerate market penetration.
For Investors and Strategic Acquirers:
Stricter sodium reduction guidelines from the FDA and public health campaigns in the UK reshape the acquisition landscape for functional ingredient providers. Long-term viability rests on sustained demand for health-focused food reformulation over the next decade. Target niche players with patented microbial-derived or enzymatically modified ingredients demonstrating proven sensory performance. Increased M&A activity in plant-based ingredient technology serves as a key signal to watch.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand fermentation R&D | Accelerates cost-effective production of novel protein-based replacers. |
| Form co-development alliances | Integrates application expertise, overcoming complex reformulation hurdles. |
| Invest in plant-based ingredient platforms | Captures growth in rapidly expanding meat and dairy alternative segments. |
| Strengthen supply chain resilience | Mitigates price volatility and sourcing bottlenecks for specialized inputs. |
| Develop synergistic ingredient systems | Addresses sensory challenges by combining functional properties effectively. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through primary interviews with R&D heads, ingredient procurement managers, nutraceutical formulators, and regulatory compliance officers. This primary research is validated against extensive secondary sources including FDA guidance documents, EFSA scientific opinions, FSSAI regulations, and industry association reports. A bottom-up approach, complemented by top-down market sizing, ensures comprehensive data triangulation.
The analytical framework projects market dynamics across the analysis window, modeling segmentation dimensions such as product type, application, end-user, and regional regulatory clusters. Compound annual growth rates (CAGRs) are derived from historical data analysis and projected market drivers, including processed food consumption trends and regulatory changes in sodium and fat content. Forecast inputs reflect evolving consumer health preferences.
Forecasts assume regulatory continuity in the US FDA, UK FSA, European EFSA, and Indian FSSAI regimes; material policy shifts would require re-modeling. These projections reflect assumptions regarding technological advancements in ingredient science and market adoption rates. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Italy Food Acidulants Market
Food Additives and Ingredients
Germany Food Colorants Market
Food Additives and Ingredients
Mexico Anti Caking Market
Food Additives and Ingredients
Food Fungal Enzyme Market
Food Additives and Ingredients
Natural Food and Beverage Preservatives Market
Food Additives and Ingredients
Transglutaminase Market
Food Additives and Ingredients
Global Food Release Agents Market
Food Additives and Ingredients
Cetyl Palmitate Market
Food Additives and Ingredients
Russia Anti Caking Market
Food Additives and Ingredients
Yeast Extract and Beta Glucan Market
Food Additives and Ingredients
South America Food Enzymes Market
Food Additives and Ingredients
Spain Food Colorants Market
Food Additives and Ingredients
France Anti Caking Market
Food Additives and Ingredients
Global Flaked Shortenings Market
Food Additives and Ingredients
Anti-Caking Market
Food Additives and Ingredients
Scrambled Egg Mix Market