
 Cetyl Palmitate Market | 2026-2036
Cetyl Palmitate Market Size, Share, and Industry Trends Forecast 2026-2036
Cetyl Palmitate Market Analysis
Personal care demand is hardening as the dominant end-use vertical for cetyl palmitate, displacing traditional industrial lubricant offtake. Croda International Plc leverages its oleochemical expertise to dominate high-purity cosmetic grade supply chains. BASF SE anchors European production through integrated fatty acid ester operations. Evonik Industries differentiates via specialized pharmaceutical grade cetyl palmitate for topical drug delivery systems.
Cetyl palmitate is a wax ester synthesized from cetyl alcohol and palmitic acid, exhibiting a melting point of approximately 49°C and serving primarily as an emollient, opacifier, and rheology modifier in formulated products. Cosmetic grade output leads volume, though pharmaceutical grade commands superior margins due to USP-NF compliance requirements. The emulsifier application segment sustains the largest share, while thickening agent demand accelerates in clean-label personal care formulations. Powder form dominates industrial procurement, whereas flakes and granules prevail in cosmetic batching operations.
REACH registration through ECHA governs European market access, while FDA cosmetic ingredient safety assessments under MoCRA reshape U.S. formulation standards. India's CDSCO and BIS frameworks are tightening import specifications for pharmaceutical grade material. Stakeholders must monitor regulatory divergence between jurisdictions to optimize grade portfolios and avoid reformulation costs.
Market Dynamics
Cosmetic formulators are consolidating cetyl palmitate procurement around high-purity grades as REACH registration costs and MoCRA compliance timelines squeeze mid-tier suppliers from European and North American supply chains.
Growth Catalysts
- Clean-label personal care expansion:Formulators in Germany and France are substituting petroleum-derived emollients with plant-based wax esters to meet EU Green Deal cosmetic ingredient benchmarks.
- REACH registration consolidation:ECHA's 2024 updated dossier requirements for fatty acid esters are filtering out unregistered importers, tightening legitimate supply channels for compliant producers.
- Topical drug delivery systems:Pharmaceutical manufacturers are expanding cetyl palmitate use in transdermal patches and dermatological creams requiring USP-NF certification.
Market Restraints
- Palmitic acid feedstock volatility:Palm oil price swings in Malaysia and Indonesia transmit directly to cetyl palmitate production economics, compressing margin stability for non-integrated producers.
- German supply concentration:Specialty chemical manufacturing clusters around Ludwigshafen and Hamburg create geographic single-point vulnerability for European cosmetic grade supply.
- Silicone emollient substitution:Dimethicone and cyclomethicone formulations retain cost advantages in mass-market personal care, limiting cetyl palmitate penetration in economy-tier products.
Strategic Opportunities
- Indian pharmaceutical grade demand:CDSCO's tightened import specifications for excipients are creating first-mover advantages for suppliers achieving BIS certification ahead of domestic capacity buildout.
- Biotechnology-derived palmitic acid:Fermentation-based fatty acid production is converging with cosmetic formulator sustainability mandates, enabling carbon footprint claims unavailable to palm-derived supply.
- Direct-to-manufacturer digital procurement:Specialty chemical platforms are disintermediating traditional distributors, allowing cetyl palmitate producers to capture margin previously allocated to regional chemical traders.
Industry Challenges
- USP-NF certification timeline compression:Pharmaceutical grade qualification requires 18-24 month stability studies, delaying revenue recognition for new production capacity.
- Multi-jurisdiction regulatory divergence:Simultaneous compliance with FDA MoCRA, REACH, and India's BIS frameworks demands dedicated regulatory affairs staffing that mid-scale producers struggle to resource.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cetyl Palmitate Market |
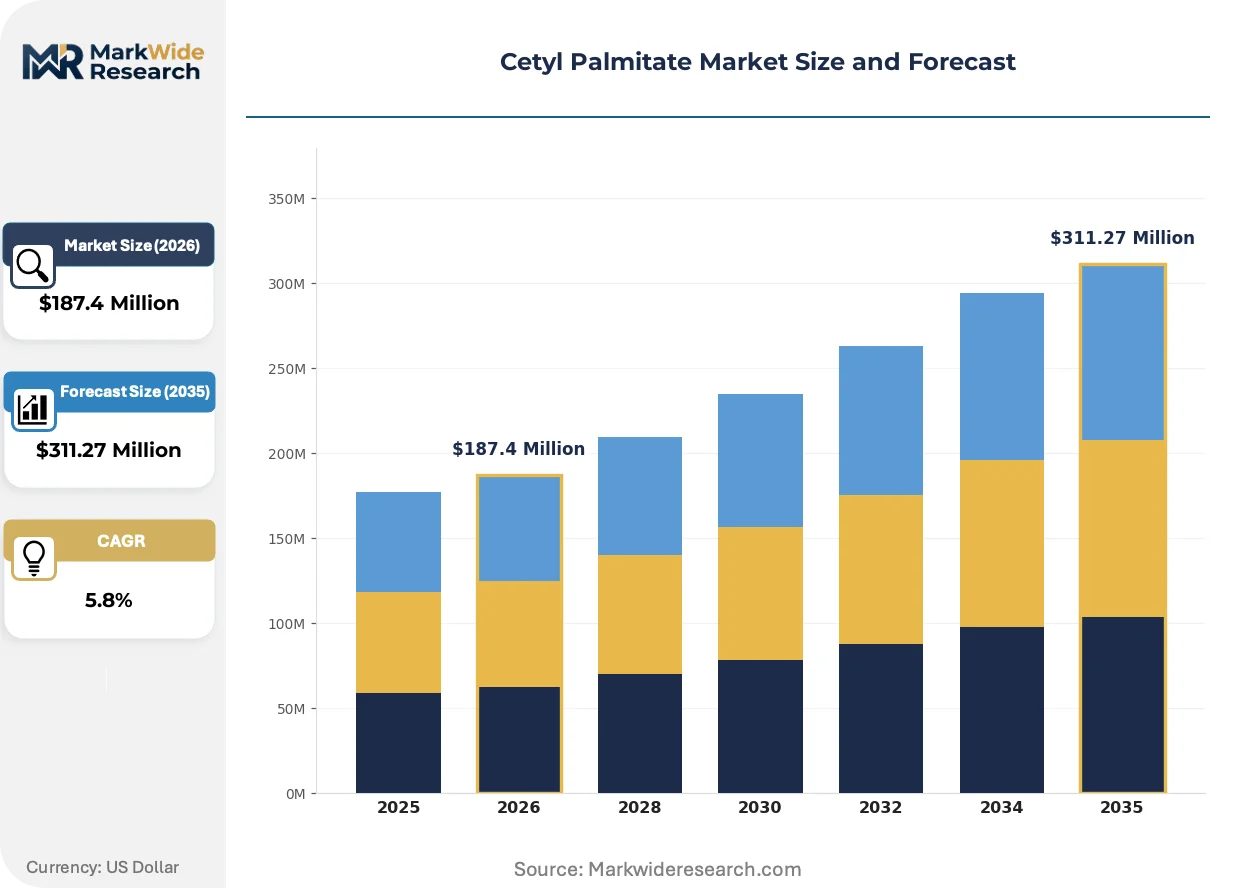
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cosmetic Grade, Pharmaceutical Grade, Food Grade, Industrial Grade Application: Emulsifier, Thickening Agent, Stabilizer, Lubricant End User: Personal Care, Pharmaceuticals, Food Industry, Chemical Manufacturing Form: Powder, Granules, Flakes, Liquid |
| Companies Covered | Croda International Plc, BASF SE, Evonik Industries, Sigma-Aldrich Co. LLC, Fine Organics, Oleon NV, BioCell Technology, Ashland, Lubrizol Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cetyl Palmitate Market Emerging Trajectories
Biotechnology and enzymatic synthesis are rewriting cetyl palmitate production economics while regulatory digitization and procurement platformization compress traditional supply chain layers.
Enzymatic esterification using immobilized lipase catalysts is integrating into commercial production workflows at Croda International and specialty chemical houses in Germany. Cosmetic formulators seeking RSPO-certified supply chains are adopting enzymatic routes for their traceability advantages and milder processing conditions. This technology is integrating carbon accounting directly into batch records, enabling Scope 3 emissions reporting that customers now require for ESG disclosure.
MoCRA's fragrance allergen labeling requirements and ECHA's extended safety data sheet obligations are forcing reformulation audits across personal care portfolios. Manufacturers must now document cetyl palmitate impurity profiles at parts-per-million thresholds previously unregulated. Small and mid-tier formulators in the United States are responding by consolidating supplier bases to reduce qualification burden, privileging established REACH-registered European producers over Asian alternatives.
Long-term supply agreements are displacing spot market purchasing as cosmetic brand owners seek price predictability amid palm oil volatility. Procurement teams at L'Oréal, Unilever, and Beiersdorf are locking 24-36 month contracts directly with fatty acid ester manufacturers. This pattern is most pronounced in Germany and France, where sustainability scorecard requirements favor supplier relationships auditable across multiple reporting cycles.
Cetyl Palmitate Market Segmentation
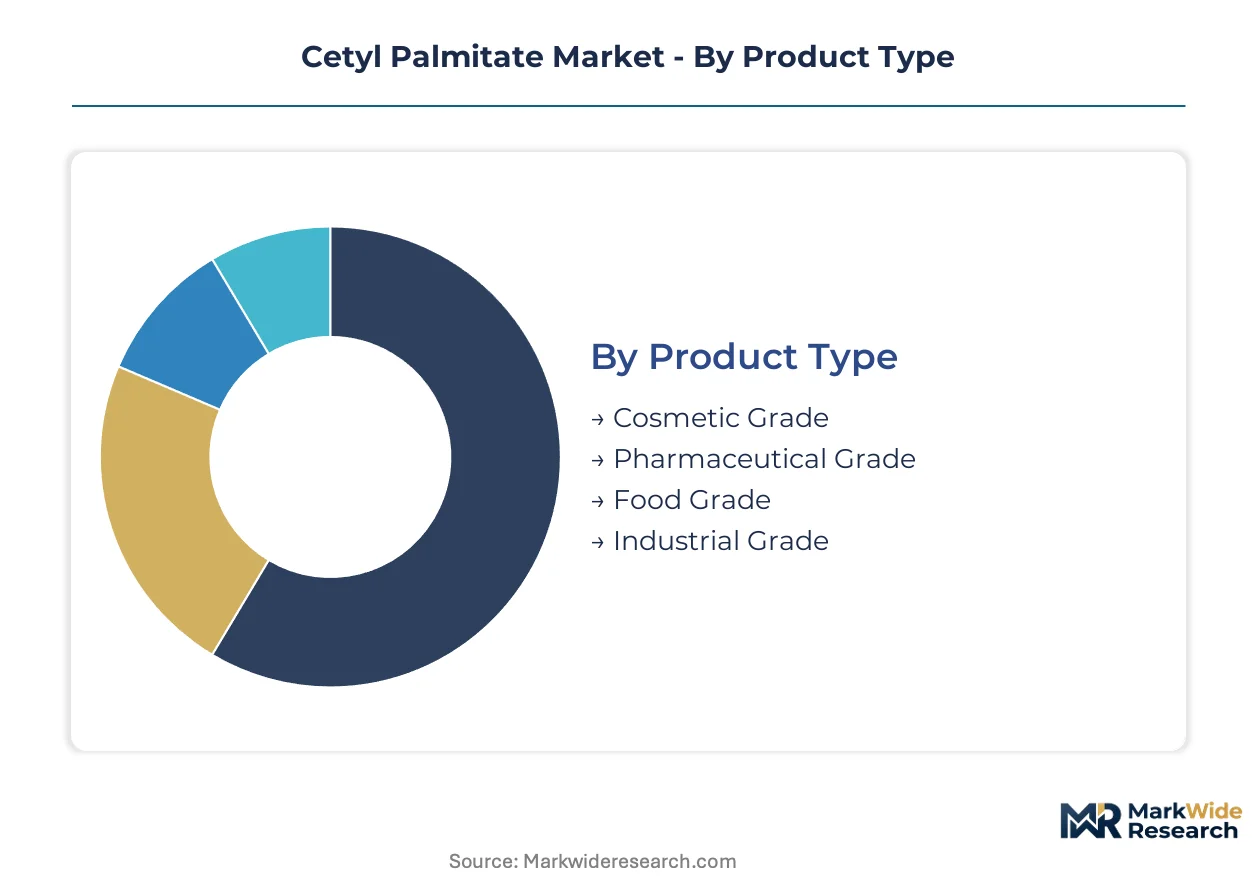
Grade certification requirements fragment cetyl palmitate procurement strategies across end-use verticals. Formulators must align supplier qualification timelines with product development cycles, creating segmentation-driven sourcing hierarchies.
Product Type:
REACH dossier obligations and USP-NF stability studies impose divergent cost burdens across purity tiers, reshaping competitive positioning within each grade.
- Cosmetic Grade:This segment requires ECHA REACH registration for European market access and compliance with MoCRA fragrance allergen thresholds in the United States. Personal care formulators in Germany and France are consolidating procurement around RSPO-certified cosmetic grade supply to meet EU Green Deal cosmetic ingredient benchmarks.
- Pharmaceutical Grade:USP-NF certification demands 18-24 month stability studies, compressing revenue recognition timelines for new capacity. Transdermal patch manufacturers in India are driving demand acceleration as CDSCO tightens excipient import specifications.
- Food Grade:FSSAI compliance in India and EFSA safety assessments in Europe govern market access for food additive applications.
- Industrial Grade:Lower purity thresholds reduce regulatory burden but expose margins to palm oil feedstock volatility in Malaysia and Indonesia.
Leading the category by volume: Cosmetic Grade. Growing fastest: Pharmaceutical Grade.
Application:
Functional performance requirements determine formulation substitution patterns and pricing differentiation across use cases.
- Emulsifier:This application sustains the largest volume share as personal care formulators replace petroleum-derived emulsifiers with plant-based wax esters. L'Oréal and Unilever procurement teams are locking 24-36 month supply contracts directly with fatty acid ester manufacturers.
- Thickening Agent:Clean-label personal care expansion is accelerating thickening agent demand in Germany and France. Enzymatic esterification routes are integrating carbon accounting into batch records for ESG disclosure compliance.
- Stabilizer:Food industry applications require FSSAI or EFSA clearance depending on target market jurisdiction.
- Lubricant:Industrial lubricant offtake is contracting as personal care demand displaces traditional end-uses.
Dominant by formulation share: Emulsifier. Expanding most quickly: Thickening Agent.
End User:
Customer procurement sophistication varies from direct-manufacturer digital platforms to distributor-mediated spot purchasing.
- Personal Care:This vertical commands premium pricing as sustainability scorecard requirements favor auditable supplier relationships across multiple reporting cycles. Procurement consolidation at Beiersdorf and similar brand owners is squeezing mid-tier suppliers from European supply chains.
- Pharmaceuticals:Topical drug delivery systems are expanding cetyl palmitate use in dermatological creams requiring multi-jurisdiction regulatory compliance. Simultaneous FDA MoCRA, REACH, and BIS framework adherence demands dedicated regulatory affairs staffing.
- Food Industry:Food additive applications face EFSA safety data sheet obligations and extended impurity profile documentation.
- Chemical Manufacturing:Industrial chemical producers prioritize feedstock cost predictability over certification burden.
Highest margin capture: Personal Care. Steepest demand trajectory: Pharmaceuticals.
Form:
Physical state determines batching workflow compatibility and logistics cost structures across customer segments.
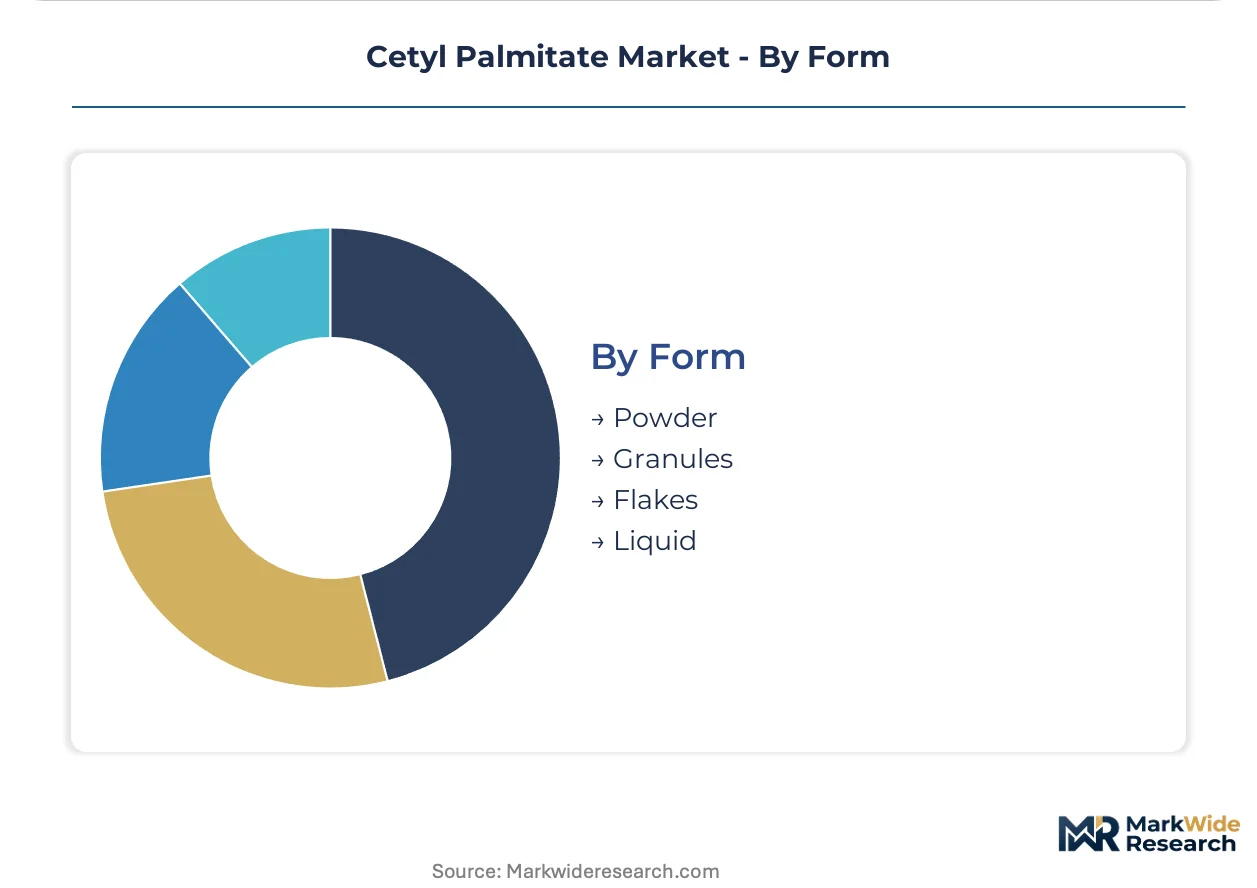
- Powder:This form dominates industrial procurement due to handling efficiency in bulk chemical manufacturing. Powder specifications face less stringent impurity documentation than cosmetic or pharmaceutical grades.
- Flakes:Cosmetic batching operations in Germany prefer flakes for controlled melting and rheology modification. Flake form enables precise dosing in clean-label personal care formulations.
- Granules:Intermediate flow properties serve pharmaceutical tablet compression and food processing applications.
- Liquid:Limited commercial penetration due to stability and shipping cost disadvantages versus solid forms.
Volume leadership: Powder. Gaining share fastest: Flakes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialty chemical parks in Ludwigshafen and Hamburg concentrate European cetyl palmitate manufacturing capacity. Tax incentives for green chemistry investments in Germany's Chemical Triangle are accelerating plant modernization. REACH registration costs are filtering unregistered importers from legitimate supply channels.
Germany
Personal care formulators at Beiersdorf and similar brand owners are consolidating procurement around RSPO-certified supply. ECHA's updated dossier requirements for fatty acid esters are tightening purity benchmarks for market access. The Ludwigshafen chemical cluster anchors integrated fatty acid ester operations serving premium cosmetic brands across Europe.
United States
MoCRA compliance timelines are squeezing mid-tier suppliers from North American supply chains. FDA cosmetic ingredient safety assessments under MoCRA are reshaping formulation standards and documentation requirements. Procurement teams in New Jersey and California are locking long-term contracts directly with REACH-registered European producers.
India
Transdermal patch manufacturers are driving pharmaceutical grade demand acceleration. CDSCO's tightened import specifications for excipients are creating first-mover advantages for BIS-certified suppliers. Pharmaceutical manufacturing clusters in Hyderabad and Mumbai are expanding dermatological cream production requiring USP-NF certification.
France
Clean-label personal care expansion is accelerating thickening agent demand in formulation hubs. EU Green Deal cosmetic ingredient benchmarks are mandating substitution of petroleum-derived emollients with plant-based wax esters. L'Oréal procurement operations in Clichy are negotiating 24-36 month supply contracts for price predictability.
China
Cosmetic grade output is scaling to serve domestic personal care brand expansion. NMPA cosmetic ingredient regulations are converging with international purity standards for imported formulations. Manufacturing capacity in the Yangtze River Delta is integrating carbon accounting into batch records for ESG disclosure compliance.
Cetyl Palmitate Market Vendor Landscape
Top-tier vendors anchor integrated oleochemical operations, while mid-scale specialists concentrate on grade-specific certification tiers. The vendor base stratifies between multinational chemical conglomerates with backward integration into palm oil supply and regional esterification houses serving niche pharmaceutical applications. Three archetypes dominate: REACH-registered European majors, USP-NF-certified pharmaceutical specialists, and fermentation-based biotechnology entrants. Competitive moves center on long-term procurement contract capture and enzymatic production route licensing.
Among European-headquartered conglomerates, Croda International Plc, BASF SE, and Evonik Industries occupy positions reflecting distinct strategic vectors. Croda exemplifies the oleochemical expertise archetype leveraging integrated supply chains. BASF SE anchors scale-driven manufacturing through chemical park clustering. Evonik Industries represents the pharmaceutical-grade specialization tier with topical drug delivery system focus. These three entities collectively illustrate how certification depth and feedstock integration separate premium-tier positioning from commodity competition.
| Leading Market Players |
|---|
| Croda International Plc |
| BASF SE |
| Evonik Industries |
| Sigma-Aldrich Co. LLC |
| Fine Organics |
| Oleon NV |
| BioCell Technology |
| Ashland |
| Lubrizol Corporation |
| Others |
Supply Flow & Price Mechanics
Backward integration into palm oil supply chains anchors pricing power for cetyl palmitate producers, as Malaysian and Indonesian feedstock sourcing determines margin stability across cosmetic and pharmaceutical grades. Integrated oleochemical operators in Germany leverage captive supply to resist volatility that compresses non-integrated competitors.
Pricing Analysis
Short lead-time premiums for USP-NF certified pharmaceutical grade separate pricing tiers, while spot inventory of industrial-grade powder trades at discounts. Three-tier pricing structure across premium, standard, and economy levels reflects certification burden divergence, with cosmetic grade commanding mid-tier positioning. Cost compression in industrial grade is intensifying because palm oil price swings transmit directly to non-integrated producers. Mass-market personal care formulators exhibit highest price sensitivity, whereas transdermal patch manufacturers prioritize certification compliance over unit economics.
Supply Chain Analysis
Workforce availability constraints in Ludwigshafen and Hamburg chemical parks limit capacity expansion for European specialty ester producers. Manufacturing concentrates in Germany, Malaysia, and India, with feedstock sourcing drawing from Indonesian and Malaysian palm oil estates. Supply chain risk centers on single-source vulnerability for RSPO-certified sustainable palm derivatives. Distribution runs through direct-to-manufacturer digital platforms disintermediating regional chemical traders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
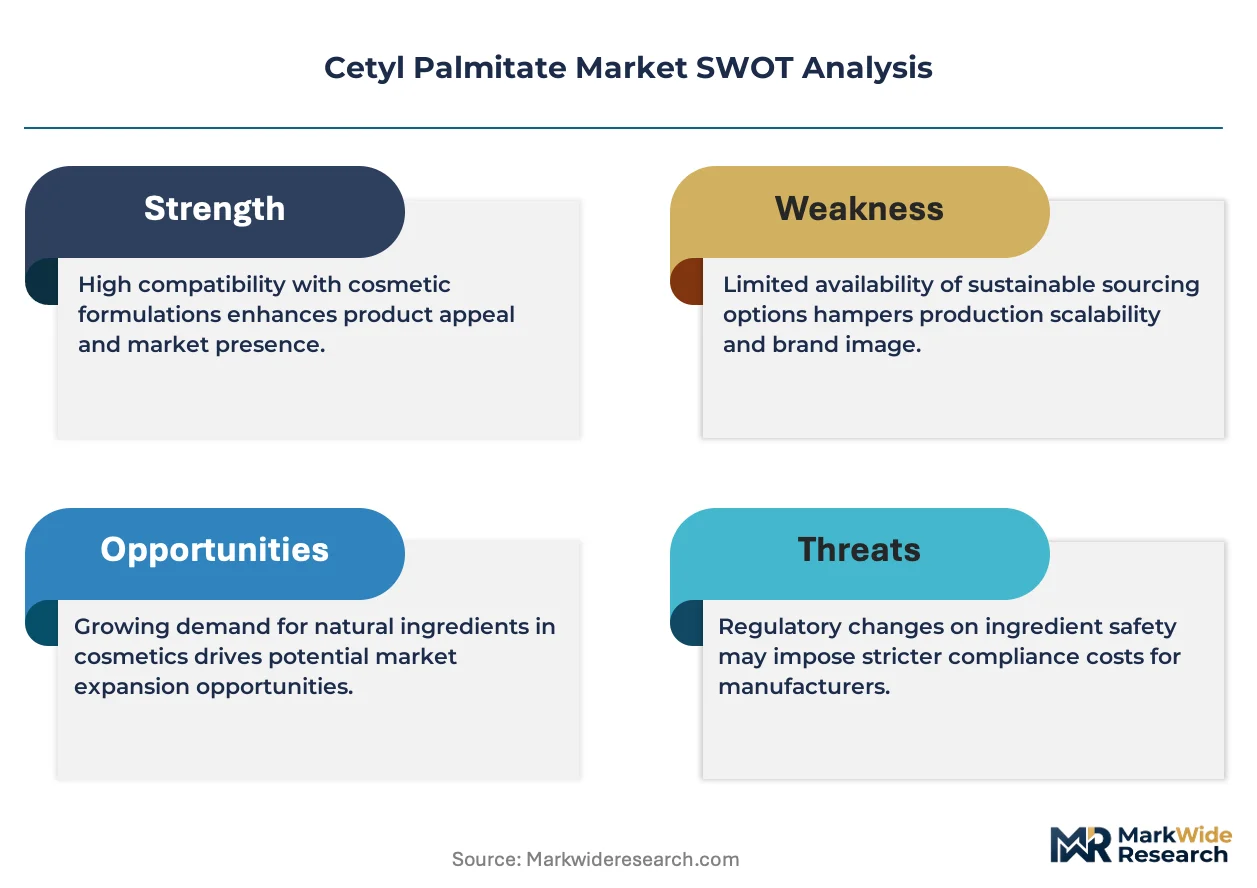
This market reads as a cost-of-compliance story where ECHA's updated REACH dossier requirements for fatty acid esters erect barrier-to-entry moats favoring established registrants over unregistered importers.
For Market Incumbents: Extend certification depth into pharmaceutical grade USP-NF tiers to capture margin expansion from transdermal patch demand. Deepen backward integration into Malaysian palm oil supply through long-term offtake agreements mitigating feedstock volatility. Consolidate supplier relationships with L'Oréal and Unilever procurement teams seeking auditable sustainability scorecards across multiple reporting cycles.
For New Entrants and Emerging Players: Begin with enzymatic esterification technology licensing to serve clean-label personal care formulators in France and Germany seeking carbon footprint traceability. Target Indian pharmaceutical manufacturing clusters in Hyderabad and Mumbai where CDSCO's tightened excipient specifications create first-mover windows for BIS-certified suppliers ahead of domestic capacity buildout.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition of REACH-registered European specialty ester houses with established cosmetic brand relationships. Long-term viability over the projection horizon hinges on regulatory compliance infrastructure rather than commodity scale. Watch biotechnology-derived palmitic acid fermentation scale-up as inflection signal for sustainability-driven supply chain displacement.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock | Captive palm oil supply insulates German producers from Malaysian price volatility. |
| Pharmaceutical Grade Certification | USP-NF qualification opens transdermal patch revenue streams in Indian manufacturing. |
| Enzymatic Production Licensing | Immobilized lipase routes enable Scope 3 carbon accounting for ESG disclosure. |
| Long-term Supply Agreements | Direct contracts with Beiersdorf procurement reduce spot market exposure. |
| Digital Procurement Platform Integration | Specialty chemical platforms capture margin from disintermediated regional traders. |
Methodological Framework
Trade databases, ECHA registration filings, and SEC 10-K disclosures formed the secondary backbone, supplemented by customs records tracking Malaysian and Indonesian palm oil derivatives. Primary interviews with specialty chemical plant managers, cosmetic procurement leads at European brand owners, pharmaceutical excipient regulatory affairs directors, and distribution channel partners validated supply chain configurations. Bottom-up grade-level volume estimates triangulated against top-down oleochemical industry aggregates.
Historical trendline analysis of fatty acid ester pricing and volume trajectories informed projection modeling across the analysis window. Segmentation dimensions included grade tier, end-use vertical, physical form, and regional production hub. CAGRs derived from weighted average of demand driver elasticities and capacity expansion timelines. Forecast inputs incorporated REACH registration cost amortization schedules and MoCRA compliance timeline assumptions for U.S. market access.
Underlying measurement precision varies by segment; pharmaceutical grade carries tighter precision than industrial grade due to documented USP-NF certification pathways. Forecasts reflect assumptions about regulatory enforcement continuity and palm oil supply sustainability certification penetration. Material deviation in ECHA dossier requirements or Malaysian export policy warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Global Fatty Acids Market
Food Additives and Ingredients
North America Food Stabilizers Market
Food Additives and Ingredients
Italy Food Preservatives Market
Food Additives and Ingredients
Curcumin Food Color Market
Food Additives and Ingredients
China Food Emulsifiers Market
Food Additives and Ingredients
Global Yeast and Yeast Ingredients Market
Food Additives and Ingredients
Feed Anti-Caking Agents Market
Food Additives and Ingredients
South Africa Food Preservatives Market
Food Additives and Ingredients
Asia-Pacific Fermented Ingredient Market
Food Additives and Ingredients
Food Grade Sodium Hydroxide Market
Food Additives and Ingredients
Japan Food Enzymes Market
Food Additives and Ingredients
Vinasse Market
Food Additives and Ingredients
Africa Anti Caking Agent Market
Food Additives and Ingredients
Australia Food Colorants Market
Food Additives and Ingredients
UK Food Enzymes Market
Food Additives and Ingredients
United Kingdom Food Preservatives Market