
 Yeast Extract and Beta Glucan Market | 2026-2036
Yeast Extract and Beta Glucan Market Size, Share, and Industry Trends Forecast 2026-2036
Yeast Extract and Beta Glucan Market Outlook
Synthetic hydrolyzed vegetable protein is consolidating market share in savory flavor bases, forcing yeast extract suppliers to emphasize natural positioning and umami intensity benchmarks. Lesaffre Group leverages its century-old fermentation infrastructure to anchor European supply security. Angel Yeast Co., Ltd. dominates autolysis technology for high-nucleotide extracts. Kerry Group PLC differentiates through integrated taste modulation systems that pair yeast extracts with masking technologies.
Yeast extract comprises soluble components derived from Saccharomyces cerevisiae autolysis, typically containing amino acids, peptides, nucleotides, and B-vitamins at concentrations varying by strain and processing conditions; beta glucan refers to polysaccharide glucose polymers, notably beta-1,3/1,6-D-glucan from yeast cell walls, valued for immunomodulatory and rheological properties in food and therapeutic applications. The powder form of yeast extract leads volume due to shelf stability and ease of dosing in industrial food manufacturing, while liquid concentrates command premium placement in ready-to-use broth systems. Beta glucan from the nutraceuticals application segment shows the fastest trajectory as dietary supplement companies seek structure-function claims supported by clinical validation.
FDA GRAS self-affirmation pathways and EFSA novel food assessments shape market access timelines for yeast-derived ingredients in the United States and European Union, while China's NMPA and SAMR enforce dual carbon compliance standards that raise energy costs for fermentation facilities. USDA organic certification and EU organic regulation create parallel premium supply chains with distinct documentation requirements. Stakeholders must monitor evolving immunomodulatory health claim frameworks across major jurisdictions to anticipate reformulation mandates and competitive positioning shifts.
Market Dynamics
Clean-label disclosure mandates from EFSA and Germany's BfR are compressing formulation timelines for savory flavor developers, forcing yeast extract suppliers to validate natural-origin positioning through accelerated autolysis optimization and nucleotide concentration benchmarking.
Growth Catalysts
- EFSA additive transparency mandates:Food manufacturers across the European Union reformulate savory applications to eliminate E-number declarations, creating pull-through demand for yeast-derived umami compounds that require no additive labeling.
- Fermentation biotechnology clusters in Germany:Concentrated R&D infrastructure around Hamburg and Munich enables rapid strain development and process scale-up for high-nucleotide extract variants serving nutraceutical compounders.
- Dual carbon compliance standards in China:SAMR enforcement raises energy costs for competing hydrolyzed vegetable protein facilities, improving relative cost positioning for yeast extract producers with biomass cogeneration capabilities.
Market Restraints
- Molasses and sugar beet feedstock volatility:Input cost swings for Saccharomyces cerevisiae fermentation media compress margin predictability for extract producers without long-term agricultural supply contracts.
- Supply concentration in Rhine-Ruhr industrial corridor:Dependence on a limited geographic cluster for pharmaceutical-grade beta glucan creates vulnerability to regional energy disruption or logistics congestion.
- EFSA novel food assessment timelines:Extended safety evaluation protocols for new yeast strains delay market access by 18-24 months versus GRAS self-affirmation pathways available in the United States.
Strategic Opportunities
- Underpenetrated immunomodulatory applications in Brazil:ANVISA's evolving dietary supplement framework creates first-mover potential for clinically validated beta glucan structure-function claims in Latin America's largest nutraceutical market.
- Cell-culture media convergence:Hybrid bioprocessing approaches combining yeast extract with recombinant protein feeds address precision fermentation nutrient requirements in cultivated meat and microbial biomass production.
- USDA organic certification tailwinds:Premium supply chain segregation for certified organic yeast extract captures price multiples in North American natural and organic retail channels with distinct documentation requirements.
Industry Challenges
- Autolysis process engineer scarcity:Specialized expertise in controlled enzymatic hydrolysis for nucleotide preservation commands premium compensation and limits facility expansion velocity.
- IP fragmentation around beta-1,3/1,6-D-glucan extraction:Overlapping patent estates covering cell wall disruption methods create licensing complexity and litigation exposure for new market entrants.
- Legacy ERP integration with batch traceability systems:Food safety documentation requirements strain IT infrastructure at mid-scale extract producers upgrading from paper-based records.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Yeast Extract and Beta Glucan Market |
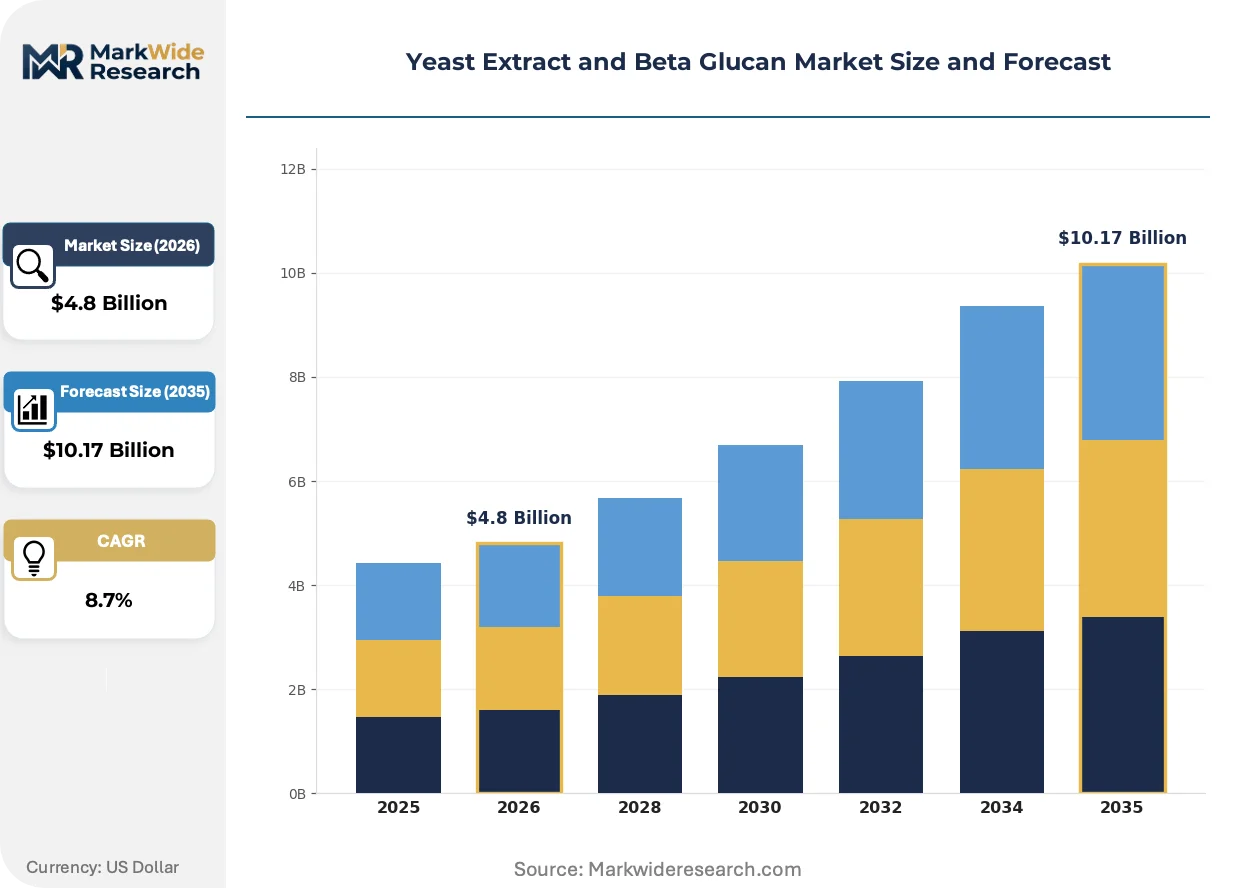
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Yeast Extract, Beta Glucan, Powder, Liquid Application: Food & Beverage, Animal Feed, Nutraceuticals, Pharmaceuticals Form: Granules, Flakes, Extracts, Concentrates End User: Food Manufacturers, Dietary Supplement Companies, Animal Health Providers, Research Institutions |
| Companies Covered | Chr. Hansen Holding A/S, Associated British Foods PLC, Archer Daniels Midland Company, Alltech, Inc., Lesaffre Group, Angel Yeast Co., Ltd., Lallemand, Inc., Specialty Biotech Co., Ltd., Kerry Group PLC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Yeast Extract and Beta Glucan Market Strategic Shifts
Electroporation-assisted autolysis is compressing processing cycles while preserving nucleotide integrity, enabling suppliers to meet accelerated clean-label reformulation deadlines from European savory manufacturers without capital-intensive facility expansion.
Continuous flow fermentation with real-time metabolite monitoring is electrifying yield consistency for high-nucleotide yeast extracts. Mid-scale European flavor houses adopt these systems to reduce batch-to-batch variation in umami intensity benchmarks. The technology is enabling smaller producers to defend position against hydrolyzed vegetable protein consolidation through quality parity at lower volume thresholds.
REACH registration requirements for novel yeast-derived bioactives are extending compliance timelines for beta glucan suppliers targeting cosmetic and therapeutic applications. Industrial consequence includes diversion of R&D expenditure from strain innovation to toxicology dossier preparation. Nutraceutical segment players with existing REACH registrations capture defensive advantage as new entrants face 36-month minimum assessment windows.
Direct procurement relationships between beta glucan suppliers and dietary supplement contract manufacturers are displacing traditional ingredient distributor intermediaries. This channel compression reflects buyer demand for technical collaboration on structure-function claim substantiation. North American sports nutrition verticals exhibit the most visible disintermediation, with brands sourcing immunomodulatory ingredients through qualified supplier audits rather than catalog distributors.
Yeast Extract and Beta Glucan Market Segmentation
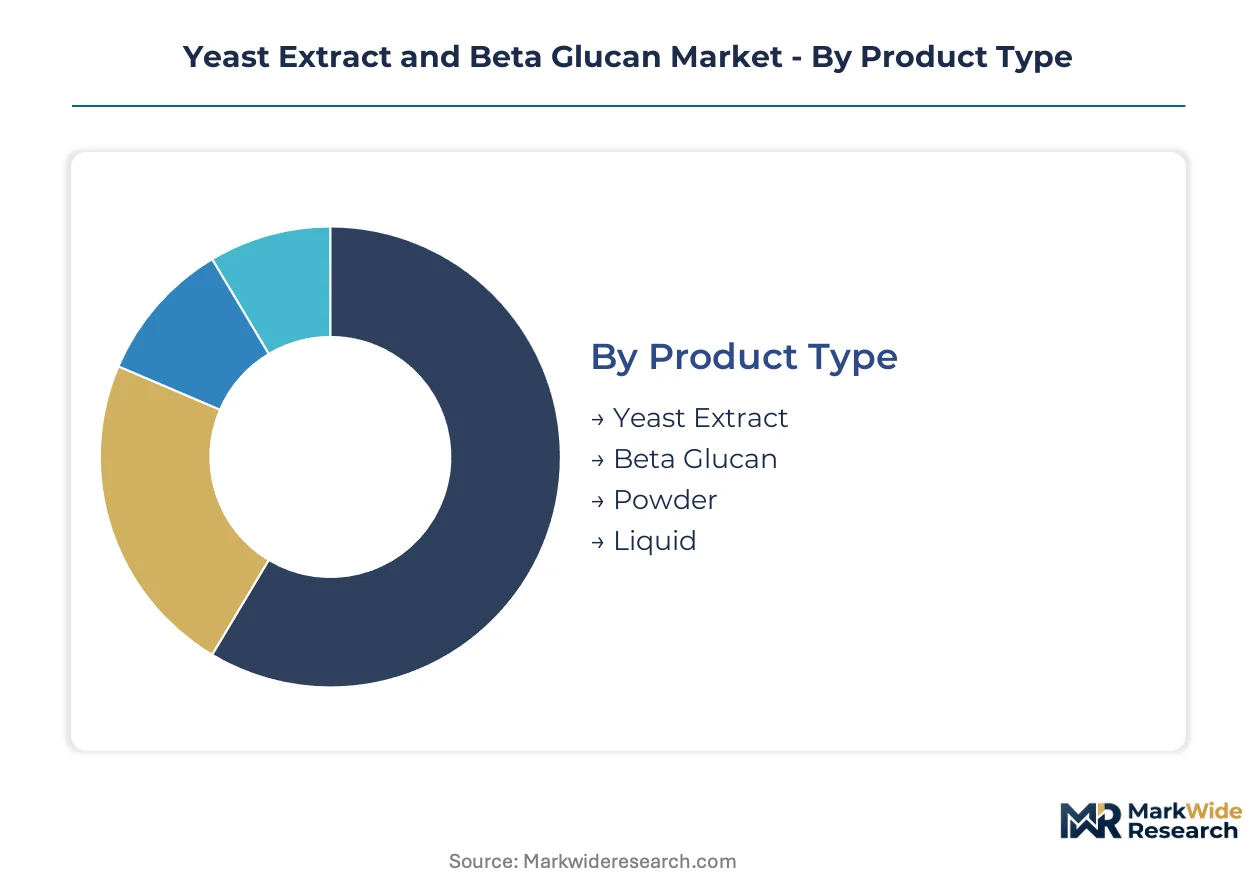
Yeast extract and beta glucan suppliers face divergent technical specifications across end-use verticals. Buyers prioritize nucleotide concentration benchmarks in savory applications versus immunomodulatory potency validation in nutraceutical procurement.
Product Type:
Cost tier differentiation separates commodity-grade materials from pharmaceutical-specification products with distinct fermentation and purification overhead.
- Yeast Extract:Soluble autolysate containing amino acids, peptides, and nucleotides from Saccharomyces cerevisiae. Food manufacturers in Germany drive specification tightening around natural-origin umami intensity as EFSA disclosure mandates eliminate synthetic additive alternatives.
- Beta Glucan:Beta-1,3/1,6-D-glucan polysaccharide extracted from yeast cell walls. Dietary supplement contract manufacturers in North America source this segment for structure-function claims requiring clinical dossiers.
- Powder:Shelf-stable format with standardized dosing precision for industrial food manufacturing.
- Liquid:Ready-to-use concentrates commanding placement in broth systems and beverage applications.
Volume sits with yeast extract; growth tilts toward beta glucan.
Application:
Application maturity determines margin structure, with established food uses defending share against emerging therapeutic verticals.
- Food & Beverage:Clean-label savory formulations leverage yeast extract for E-number-free umami delivery. European savory flavor houses compress reformulation timelines under EFSA and BfR transparency mandates.
- Nutraceuticals:Immunomodulatory supplements require beta glucan with validated beta-linkage specifications. This vertical gains share fastest as ANVISA frameworks evolve in Brazil and contract manufacturers bypass traditional distributors.
- Animal Feed:Yeast-derived ingredients support gut health claims in livestock and aquaculture nutrition.
- Pharmaceuticals:Cell-culture media and therapeutic applications demand endotoxin-controlled, GMP-certified supply chains.
Revenue concentrates in food and beverage; margin expansion favors nutraceuticals.
Form:
Processing intensity and handling characteristics shape procurement decisions across manufacturing environments.
- Granules:Free-flowing format optimized for automated dosing in high-volume food production.
- Flakes:Visual differentiation supports premium positioning in specialty retail channels.
- Extracts:Standardized soluble preparations for consistent formulation integration.
- Concentrates:Reduced water content minimizes logistics cost for international supply.
Granules dominate industrial procurement; concentrates capture export-intensive supply relationships.
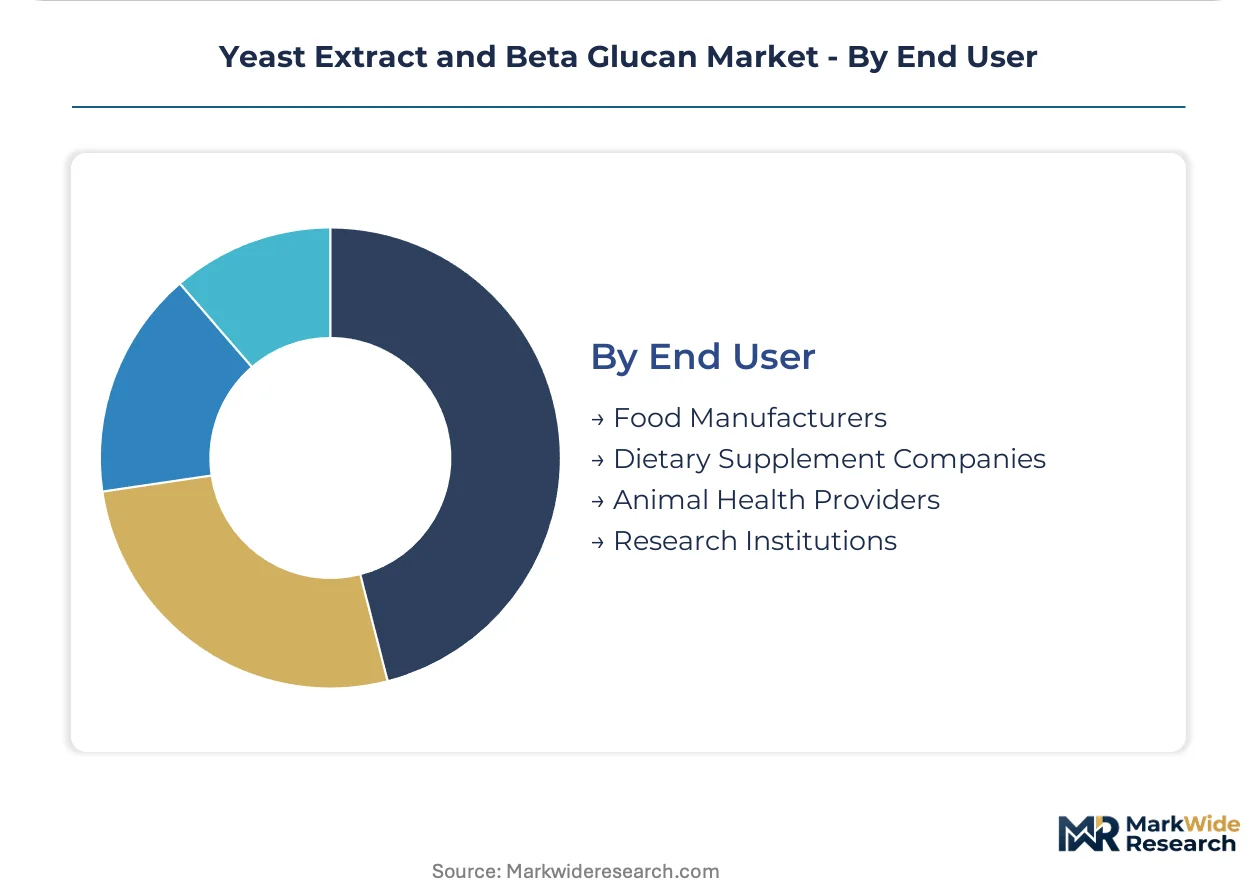
End User:
Customer technical sophistication determines service requirements and contract structures.
- Food Manufacturers:Savory and plant-based protein developers specify nucleotide-rich extracts for clean-label positioning. Hamburg and Munich biotechnology clusters supply strain optimization support.
- Dietary Supplement Companies:Sports nutrition and immune health brands demand batch-specific beta glucan certificates with structure-function substantiation. Direct supplier audits displace catalog distribution in North America.
- Animal Health Providers:Feed compounders seek yeast derivatives for antibiotic reduction claims.
- Research Institutions:Cell-culture media developers source precision fermentation nutrients including hybrid yeast extract formulations.
Food manufacturers anchor volume throughput; dietary supplement companies drive specification innovation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for yeast extract concentrates in Germany's savory flavor sector pulls regional supply chains toward Hamburg and Munich biotechnology corridors. Beta glucan procurement from North American dietary supplement contract manufacturers accelerates as direct supplier audits displace traditional distribution channels.
United States
Dietary supplement brands in the sports nutrition vertical source beta glucan through qualified supplier audits rather than catalog distributors. FDA GRAS self-affirmation pathways enable faster market access for novel yeast-derived ingredients compared to European assessment timelines. Chicago and Minneapolis fermentation facilities supply both domestic nutraceutical compounders and export channels to Latin America.
Germany
Food manufacturers accelerate yeast extract adoption in clean-label formulations as EFSA and BfR tighten additive disclosure rules. REACH registration requirements for novel yeast-derived bioactives extend compliance timelines for suppliers targeting cosmetic applications. The Rhine-Ruhr industrial corridor concentrates pharmaceutical-grade beta glucan production, creating vulnerability to regional energy disruption.
China
SAMR and NMPA enforce dual carbon compliance standards that raise energy costs for competing hydrolyzed vegetable protein facilities. Angel Yeast Co., Ltd. anchors autolysis technology development in Zhengzhou, supplying high-nucleotide extract variants. Yangtze River Delta fermentation clusters serve both domestic food manufacturers and export markets across Southeast Asia.
Brazil
ANVISA's evolving dietary supplement framework creates first-mover potential for clinically validated beta glucan structure-function claims. Sports nutrition brands in São Paulo source immunomodulatory ingredients through direct procurement relationships with international suppliers. Local feed compounders seek yeast derivatives for antibiotic reduction claims in livestock nutrition.
Japan
PMDA oversight of functional food claims drives demand for batch-specific beta glucan certificates with validated beta-linkage specifications. METI support for precision fermentation nutrients positions Japanese yeast extract suppliers for cell-culture media applications. Osaka-based flavor houses integrate yeast-derived umami compounds into clean-label savory formulations for domestic and export markets.
Yeast Extract and Beta Glucan Market Competitive Environment
Capacity expansion dominates the current landscape as suppliers retrofit fermentation infrastructure for continuous flow processing with real-time metabolite monitoring. The vendor base stratifies across three tiers: century-old fermentation houses with captive agricultural supply contracts, mid-scale autolysis specialists serving regional flavor markets, and nutraceutical-focused beta glucan purifiers with clinical validation capabilities. Technology licensing and portfolio diversification represent the two most visible competitive moves, with electroporation-assisted autolysis patents commanding premium valuation in M&A discussions.
Within the integrated fermentation tier, Lesaffre Group and Angel Yeast Co., Ltd. exemplify divergent geographic anchoring strategies, with the former leveraging European biotechnology clusters and the latter dominating Asian autolysis capacity. Kerry Group PLC occupies a position at the taste modulation frontier, pairing yeast extract positioning with adjacent masking technologies. Among diversified ingredient conglomerates, Associated British Foods PLC and Archer Daniels Midland Company represent scale-driven procurement leverage across multiple fermentation-derived categories.
| Leading Market Players |
|---|
| Chr. Hansen Holding A/S |
| Associated British Foods PLC |
| Archer Daniels Midland Company |
| Alltech, Inc. |
| Lesaffre Group |
| Angel Yeast Co., Ltd. |
| Lallemand, Inc. |
| Specialty Biotech Co., Ltd. |
| Kerry Group PLC |
| Others |
Value Chain & Pricing Dynamics
Clean-label reformulation mandates from EFSA and Germany's BfR are compressing procurement timelines for savory flavor developers, forcing yeast extract suppliers to accelerate autolysis optimization investments that elevate processing costs and compress margin predictability for mid-scale producers without long-term feedstock contracts.
Pricing Analysis
Volume concentrates in commodity-grade yeast extract powders while margin expansion sits with pharmaceutical-specification beta glucan. Three-tier pricing structure across premium, standard, and economy levels separates GMP-certified, endotoxin-controlled supply from industrial food-grade materials and commodity feed inputs. Cost compression in standard-tier extracts is intensifying because molasses and sugar beet feedstock volatility erodes contract pricing stability. Dietary supplement contract manufacturers exhibit lowest price sensitivity due to structure-function claim substantiation requirements, while animal feed compounders defend procurement leverage through volume aggregation.
Supply Chain Analysis
Single-source vulnerability sits with the Rhine-Ruhr industrial corridor's concentration of pharmaceutical-grade beta glucan production, creating exposure to regional energy disruption or logistics congestion. Manufacturing draws from fermentation biotechnology clusters in Germany, the Yangtze River Delta in China, and the Chicago-Minneapolis corridor in the United States. Critical inputs include Saccharomyces cerevisiae biomass, molasses fermentation media, and enzymatic hydrolysis reagents. Tariff exposure on yeast-derived ingredients between major trade blocs elevates landed cost uncertainty. Distribution runs through direct procurement relationships that displace traditional ingredient distributor intermediaries in North American sports nutrition verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electroporation-assisted autolysis is displacing legacy batch hydrolysis methods, compressing processing cycles while preserving nucleotide integrity and enabling smaller European flavor houses to defend quality parity against hydrolyzed vegetable protein consolidation.
For Market Incumbents: Lock in long-term agricultural supply contracts for molasses and sugar beet feedstock to insulate margin predictability from input cost swings. Deepen backward integration into strain development capabilities around Hamburg and Munich biotechnology clusters to accelerate high-nucleotide extract variants. Certify organic production lines under USDA and EU organic regulations to capture premium price multiples in North American natural retail channels.
For New Entrants and Emerging Players: Dietary supplement contract manufacturers in Brazil's sports nutrition vertical represent the most penetrable buyer archetype as ANVISA's evolving framework creates first-mover potential for clinically validated beta glucan structure-function claims. Target immunomodulatory applications with validated beta-linkage specifications that incumbent suppliers underserve. Pursue direct supplier audit qualification pathways rather than catalog distributor relationships to establish technical collaboration credibility.
For Investors and Strategic Acquirers: The window for entry favors mid-scale autolysis specialists with electroporation-assisted processing patents and existing REACH registrations for novel yeast-derived bioactives. Long-term viability rests on capturing defensive positioning as EFSA novel food assessment timelines extend compliance windows for new entrants. Watch for ANVISA framework finalization as the inflection indicator for Latin American nutraceutical market access acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Electroporation Patent Acquisition | Secures processing cycle compression technology that preserves nucleotide integrity for clean-label deadlines. |
| REACH Registration Completion | Captures 36-month defensive advantage as EFSA extends novel bioactive assessment timelines for cosmetic applications. |
| Organic Certification Investment | Enables premium supply chain segregation capturing price multiples in USDA and EU organic retail channels. |
| Direct Procurement Channel Development | Bypasses traditional distributor intermediaries in North American sports nutrition verticals for margin capture. |
| Continuous Flow Fermentation Retrofit | Reduces batch-to-batch variation in umami intensity benchmarks for European savory flavor house defense. |
Study Parameters
Multi-period observation of nucleotide concentration benchmarks, autolysis technology adoption rates, and regulatory assessment timeline trajectories anchored the trend analysis, supplemented by interviews with fermentation plant managers, savory flavor house procurement leads, dietary supplement contract manufacturing directors, and EFSA regulatory affairs specialists. Secondary validation drew from customs and trade data for yeast-derived ingredient flows, SEC 10-K filings of diversified ingredient conglomerates, REACH registration databases, and ANVISA dietary supplement framework proceedings. Bottom-up volume modeling across product type, application, and form segments triangulated against top-down macroeconomic indicators.
Segment-weighting approaches distributed value and volume projections across yeast extract versus beta glucan product categories, food and beverage versus nutraceutical application verticals, and powder versus liquid form factors, with additional stratification by certification tier and geographic production cluster. CAGRs were derived from regression analysis of historical volume trajectories and elasticity-adjusted demand projections. Industry-specific forecast inputs included EFSA disclosure mandate implementation schedules, SAMR dual carbon compliance enforcement intensity, and ANVISA structure-function claim framework evolution.
Revisions become necessary when EFSA accelerates additive transparency mandates beyond current timelines, when SAMR dual carbon standards tighten energy cost differentials for competing hydrolyzed vegetable protein facilities, or when molasses and sugar beet agricultural supply contracts experience widespread renegotiation. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Food Grade Sodium Hydroxide Market
Food Additives and Ingredients
Salt Substitutes Market
Food Additives and Ingredients
Xanthan Gum Market
Food Additives and Ingredients
Europe Food Enzymes Market
Food Additives and Ingredients
Europe Food Acidulants Market
Food Additives and Ingredients
Food Grade Dipotassium Phosphate Market
Food Additives and Ingredients
Spain Food Additives Market
Food Additives and Ingredients
Sri Lanka Starch and Starch Derivative Market
Food Additives and Ingredients
Middle East and Africa Food Anti Caking Agents Market
Food Additives and Ingredients
UK Food Enzymes Market
Food Additives and Ingredients
Global Oleate Esters Market
Food Additives and Ingredients
Africa Food Acidulants Market
Food Additives and Ingredients
China Food Enzymes Market
Food Additives and Ingredients
Food Fungal Enzyme Market
Food Additives and Ingredients
Food Additives Market
Food Additives and Ingredients
Lactose Monohydrate Market