
 Germany Food Colorants Market | 2026-2036
Germany Food Colorants Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Food Colorants Market Foresight
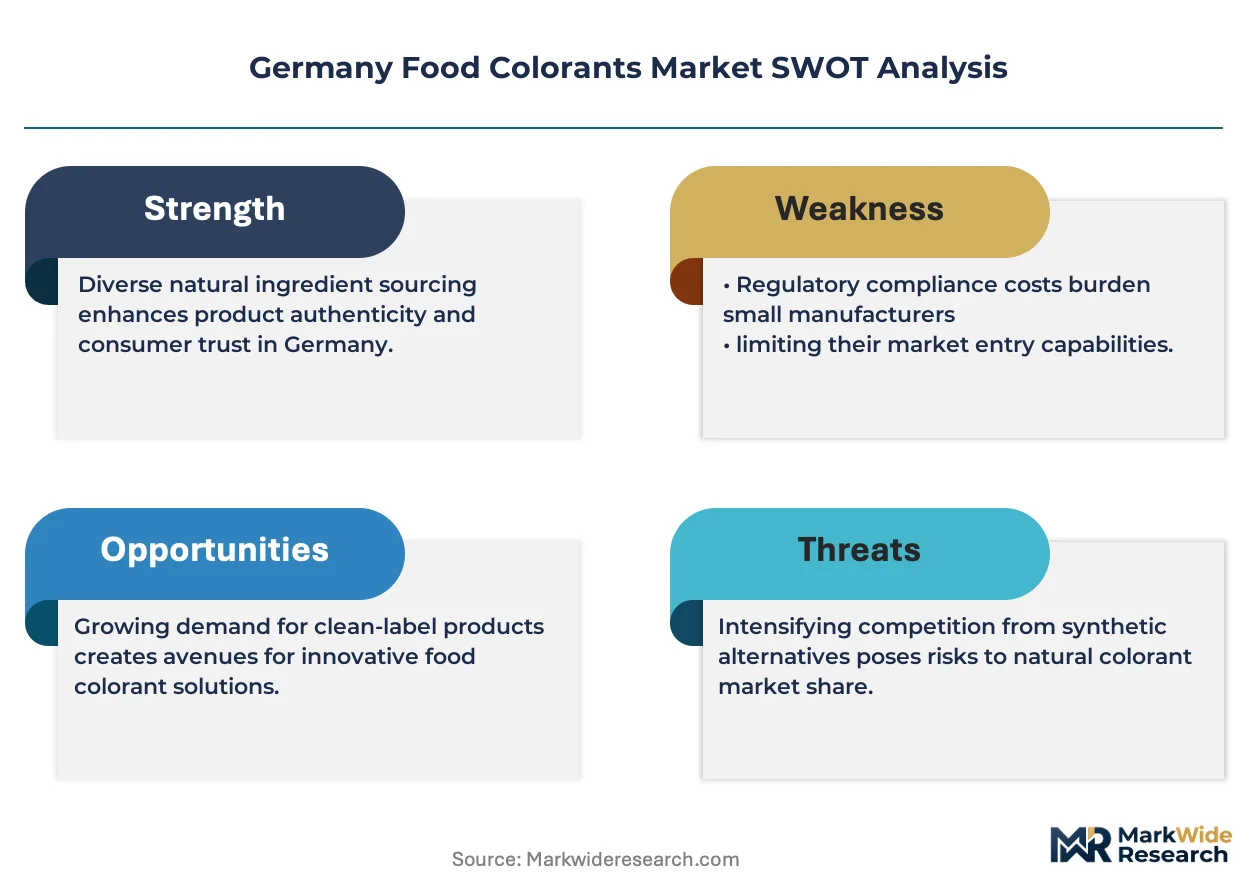
EU Green Deal compliance is repositioning the cost-of-entry calculus for new entrants seeking synthetic pigment market share. Chr. Hansen Holding A/S leverages its fermentation-derived portfolio to anchor premium positioning in natural colorants. BASF SE sustains manufacturing scale across lake colorant production, while GNT Group specializes in plant-based concentrates that navigate tightening clean-label specifications.
Food colorants comprise dyes, pigments, and lakes that impart, enhance, or restore color in processed foods, typically formulated at concentrations between 0.01% and 0.5% by weight depending on substrate and desired intensity. These additives serve critical functions in product differentiation, flavor perception modulation, and shelf-appeal maintenance across packaged food categories. Natural colorants command widening margin pools as beverage producers reformulate away from azo dyes, while synthetic colorants retain volume dominance in confectionery applications where heat stability and cost thresholds predominate. Lake colorants occupy a specialized niche in fat-based systems where water-soluble alternatives fail.
BfR evaluates colorant safety profiles under EU food additive frameworks, while EFSA establishes acceptable daily intake thresholds that directly constrain formulation choices for German manufacturers. The German Lebensmittel- und Futtermittelgesetzbuch transposes EU regulations into federal enforcement, creating a dual-layer compliance environment that elevates testing and documentation burdens. Stakeholders must monitor evolving EFSA re-evaluations of titanium dioxide and certain azo dyes, as these assessments will force immediate formulation pivots across multiple application segments.
Market Dynamics
Clean-label reformulation mandates from the EU Green Deal are forcing German food processors to rebuild colorant supply chains around fermentation-derived and plant-based alternatives, elevating procurement costs while compressing synthetic pigment margins.
Growth Catalysts
- EU Green Deal bio-transition mandates:Binding targets for bio-based feedstocks in food additives accelerate manufacturer migration from petrochemical pigments toward agricultural-derived colorants.
- Bavaria's food processing density:Concentrated demand from Munich-Nuremberg confectionery and beverage clusters creates localized economies of scale for natural colorant distribution.
- Fermentation technology maturation:Precision fermentation now delivers carotenoid and anthocyanin yields that narrow the cost gap with synthetic azo dyes.
Market Restraints
- Beetroot and spirulina input volatility:Weather-dependent harvests and agricultural commodity swings destabilize natural colorant cost structures against petroleum-based alternatives.
- EFSA re-evaluation timelines:Pending safety assessments for titanium dioxide and select azo dyes force formulation holds and inventory pre-buying that strains working capital.
- Heat stability limitations:Anthocyanin degradation above 80°C restricts natural colorant penetration in extruded snack and baked goods applications.
Strategic Opportunities
- Baden-Württemberg organic food corridor:Stuttgart-centered premium organic processors represent underserved demand for clean-label colorants certified beyond EU baseline requirements.
- Encapsulation-fermentation convergence:Liposomal and microencapsulation technologies paired with fermentation outputs enable natural colorant performance in high-heat confectionery applications.
- E-commerce ingredient platforms:Direct-procurement channels connecting mid-sized processors with specialty colorant suppliers bypass traditional distributor markups.
Industry Challenges
- Natural colorant formulation expertise scarcity:Shortage of food chemists trained in pH-sensitive pigment stabilization and oxidation prevention slows clean-label product development cycles.
- Dual-layer compliance documentation:Manufacturers must maintain parallel EFSA submission files and BfR enforcement records, multiplying regulatory affairs headcount requirements.
- Legacy synthetic inventory stranding:Reformulation timelines risk obsolescence of held stocks as EFSA publishes negative opinions on specific azo dye variants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Food Colorants Market |
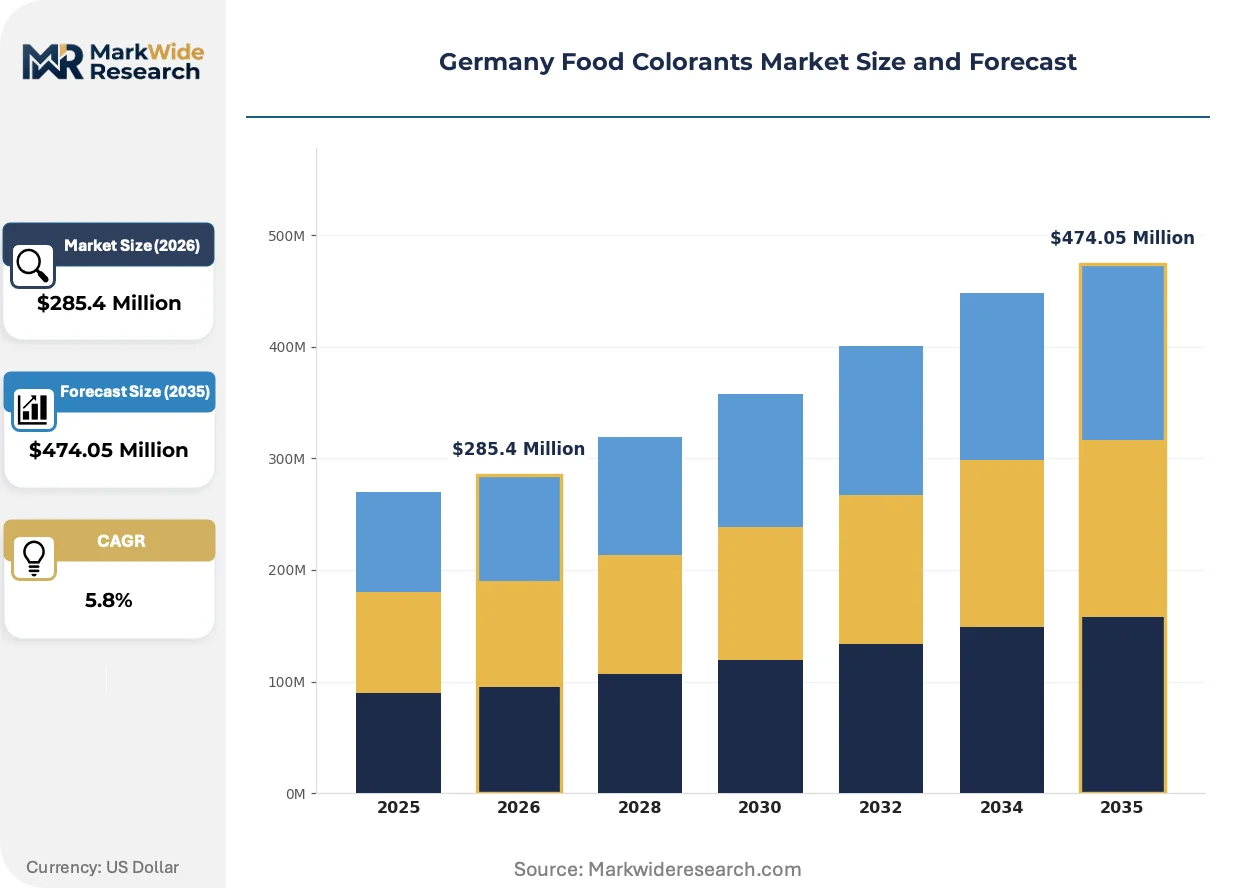
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $474.05 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Colorants, Synthetic Colorants, Lake Colorants, Pigments, Caramel Color Application: Beverages, Confectionery, Bakery Products, Dairy Alternatives, Snack Foods, Sauces End User: Food & Beverage Manufacturers, Beverage Producers, Confectionery Makers, Bakery Operators Packaging Type: Powder, Liquid, Granules, Tablets, Capsules |
| Companies Covered | Chr. Hansen Holding A/S, BASF SE, Givaudan, Döhler GmbH, Sensient Technologies Corporation, Symrise AG, GNT Group, Koninklijke DSM N.V., ROHA Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Food Colorants Market Shifts & Advancements
Fermentation-derived colorants are converging with precision agriculture traceability systems to create verified supply chains that command premium positioning in German retail channels.
Microencapsulation technology is converging with high-pressure processing methods to extend anthocyanin stability in heat-treated beverages. Mid-sized German juice processors are piloting these systems at commercial scale. The convergence is compressing the performance gap between natural and synthetic colorants in pasteurized applications.
EFSA's ongoing titanium dioxide re-evaluation is forcing immediate formulation pivots across German confectionery and chewing gum segments. Manufacturers are accelerating alternative submissions for calcium carbonate and starch-based whitening agents. The candy segment faces compressed reformulation windows as negative opinions approach finalization.
Ingredient sourcing decisions now prioritize verified supply chain documentation over unit cost minimization. German private-label retailers are mandating blockchain-traceable colorant certificates for shelf placement. This behavioral shift concentrates procurement volume with suppliers offering farm-to-factory transparency, particularly visible in Bavaria's organic dairy and plant-based beverage sectors.
Germany Food Colorants Market Segmentation
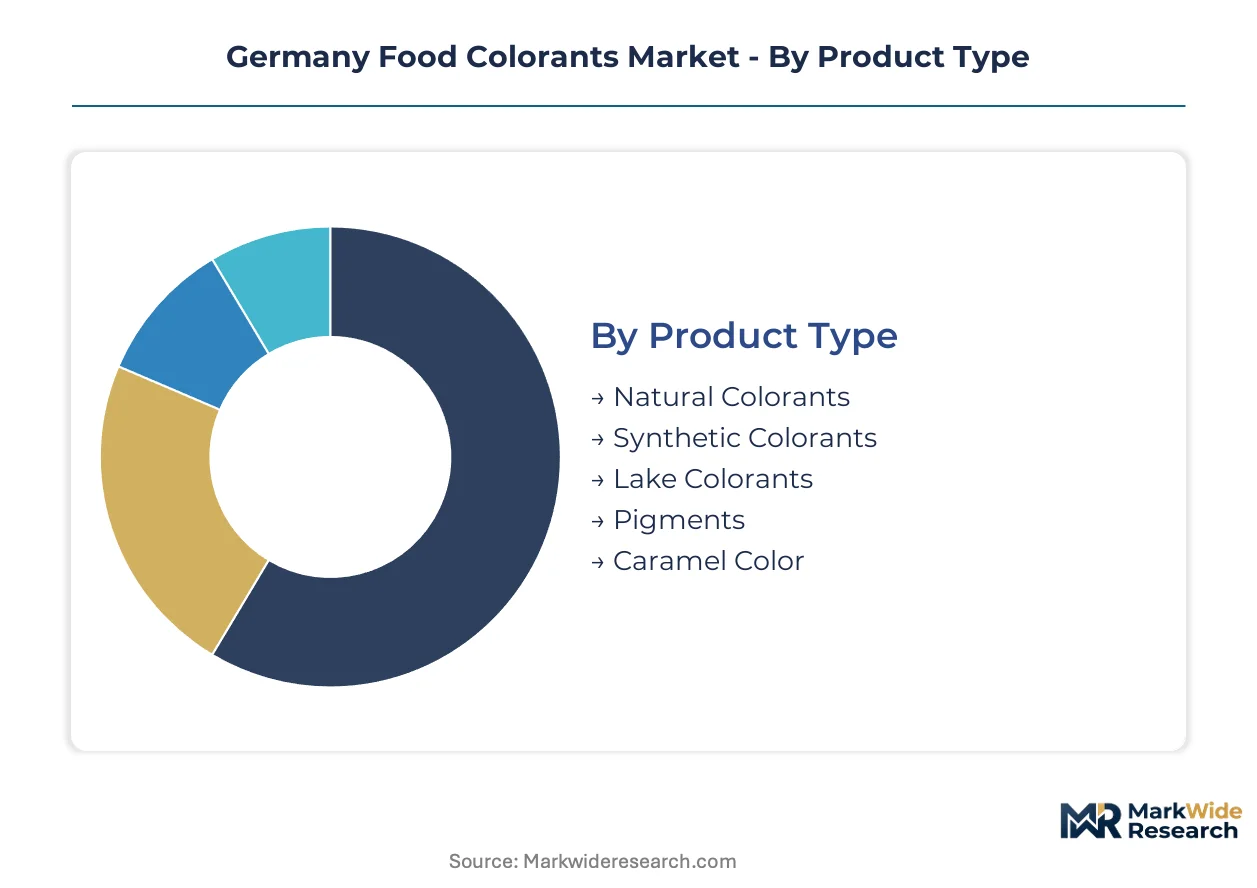
Colorant procurement patterns in Germany diverge sharply between commodity-scale beverage operations and precision-driven confectionery specialists, forcing suppliers to maintain parallel formulation portfolios. Segmentation reveals how regulatory pressure from EFSA and the EU Green Deal reshapes demand concentration across product categories and end-use channels.
Product Type:
Standardization dominates commodity synthetic pigments while natural alternatives require bespoke stabilization protocols for each application substrate.
- Natural Colorants:Anthocyanin, carotenoid, and spirulina-based formulations extracted through aqueous or solvent methods. Bavarian dairy alternatives processors drive procurement volume as clean-label mandates intensify, though heat sensitivity above 80°C limits penetration in baked goods.
- Synthetic Colorants:Azo dyes and triphenylmethane compounds manufactured through controlled diazotization reactions. Confectionery clusters in Munich-Nuremberg sustain demand despite EFSA re-evaluation pressure on specific azo variants, prioritizing cost stability and batch consistency.
- Lake Colorants:Aluminum-calcium complexes adsorbing dyes onto insoluble substrates for fat-based systems.
- Pigments:Titanium dioxide and iron oxide preparations delivering opacity and mineral-based coloration.
- Caramel Color:Heat-treated carbohydrates producing Class I-IV color intensities for beverage applications.
Leading the category by volume: Synthetic Colorants. Growing fastest: Natural Colorants.
Application:
Volume concentration tracks Bavaria's processing corridor density while margin capture favors premium organic segments in Baden-Württemberg.
- Beverages:Liquid colorants formulated for pH stability across acidic juices and neutral plant-based milks. Stuttgart-centered organic processors command premium positioning through blockchain-traceable anthocyanin certificates, though pasteurization requirements drive encapsulation technology adoption.
- Confectionery:Heat-stable lakes and synthetic dyes for hard candies, chewing gum, and chocolate coatings. EFSA's titanium dioxide re-evaluation forces immediate calcium carbonate substitution trials across German gum manufacturers.
- Bakery Products:Encapsulated natural colorants resisting Maillard reaction degradation in high-temperature ovens.
- Dairy Alternatives:Oat, almond, and soy milk whitening and tinting formulations.
- Snack Foods:Extruded product coloration requiring thermal stability above 120°C.
- Sauces:Emulsion-stable pigments for mayonnaise and dressing applications.
Volume leadership: Beverages. Steepest expansion trajectory: Dairy Alternatives.
End User:
Procurement sophistication stratifies between multinational scale operations and mid-sized regional processors.
- Food & Beverage Manufacturers:Integrated procurement functions negotiating multi-year supply agreements across colorant categories. Direct fermentation-derived partnerships with Chr. Hansen and GNT Group bypass traditional distributor channels.
- Beverage Producers:Specialized juice and soft drink operations prioritizing natural colorant migration ahead of regulatory deadlines.
- Confectionery Makers:Munich-Nuremberg cluster specialists balancing reformulation speed against legacy synthetic inventory positions.
- Bakery Operators:Regional Mittelstand processors with limited in-house formulation expertise.
Procurement volume concentration: Food & Beverage Manufacturers. Fastest capability upgrade: Confectionery Makers.
Packaging Type:
Logistics economics favor concentrated formats for long-haul distribution while ready-to-use liquids dominate just-in-time operations.
- Powder:Spray-dried or crystallized colorants offering maximum concentration and shelf stability. Bulk rail and truck shipments from BASF Ludwigshafen facilities supply northern German beverage bottlers.
- Liquid:Pre-dispersed aqueous or propylene glycol solutions eliminating hydration steps. Baden-Württemberg organic processors favor liquid natural colorants for batch flexibility in small-volume premium runs.
- Granules:Agglomerated powders for dust-free handling in high-volume operations.
- Tablets:Compressed dosage forms for precise small-batch weighing.
- Capsules:Encapsulated formats protecting oxidation-sensitive natural pigments.
Transport efficiency leader: Powder. Gaining share fastest: Liquid.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bavaria's food processing corridor operates as Germany's dominant tax-incentive zone for colorant procurement, with Munich-Nuremberg clusters concentrating confectionery and beverage demand that shapes national distribution economics.
Bavaria
Dairy alternatives processors in Munich drive anthocyanin procurement volume as clean-label mandates intensify across organic oat and almond milk production. The EU Green Deal bio-transition targets bind Bavarian manufacturers to agricultural-derived feedstock quotas by 2030. Ingolstadt-centered beverage bottlers pilot blockchain-traceable spirulina certificates for premium retail placement.
Baden-Württemberg
Stuttgart's premium organic food corridor generates underserved demand for colorants certified beyond baseline EU requirements. EFSA acceptable daily intake thresholds constrain formulation choices for regional juice processors reformulating away from azo dyes. Freiburg-based encapsulation technology firms enable natural pigment stability in high-heat applications.
North Rhine-Westphalia
Düsseldorf-Cologne chemical complexes sustain synthetic pigment manufacturing scale despite regulatory pressure on petrochemical feedstocks. The German Lebensmittel- und Futtermittelgesetzbuch transposes EU additive frameworks into federal enforcement here. Leverkusen-area lake colorant production supplies fat-based confectionery systems nationwide.
Lower Saxony
Hannover-Braunschweig snack food extruders demand thermal-stable colorants above 120°C where anthocyanin degradation limits natural alternatives. BfR safety evaluations under EU frameworks directly constrain regional formulation development. Wolfsburg-centered automotive-adjacent packaging firms drive demand for opacity agents in processed food logistics.
Hesse
Frankfurt-Rhine-Main logistics hubs concentrate colorant import and redistribution for central German processors. EFSA re-evaluation timelines for titanium dioxide force formulation holds among regional chewing gum manufacturers. Darmstadt specialty chemical research clusters support fermentation-derived pigment yield optimization.
Germany Food Colorants Market Competitive Landscape
German producers anchor one tier; Danish and Swiss specialists hold premium positioning through fermentation-derived portfolios. The vendor base stratifies across three functional tiers: multinational chemical conglomerates with lake colorant scale, mid-sized natural extract specialists, and fermentation technology platform operators. Strategic moves concentrate on backward integration into agricultural feedstocks and technology licensing for encapsulation processes.
Within the fermentation-derived tier, Chr. Hansen Holding A/S exemplifies precision biotechnology positioning, while BASF SE occupies a scale-driven archetype rooted in Ludwigshafen chemical manufacturing infrastructure. GNT Group represents the plant-based concentrate specialization vector that navigates tightening clean-label specifications. These three entities collectively illustrate how geographic origin—Danish, German, and Dutch respectively—correlates with distinct technology platform choices in the colorant supply base.
| Leading Market Players |
|---|
| Chr. Hansen Holding A/S |
| BASF SE |
| Givaudan |
| Döhler GmbH |
| Sensient Technologies Corporation |
| Symrise AG |
| GNT Group |
| Koninklijke DSM N.V. |
| ROHA Group |
| Others |
Supply & Pricing Matrix
Family-owned mid-caps in Bavaria's extraction corridor anchor supply discipline through generational agricultural landholdings, translating beetroot and spirulina cultivation control into pricing power that resists spot-market volatility. Their captive feedstock positions compress procurement costs for natural colorants while forcing synthetic pigment specialists toward volume discounting to retain confectionery accounts.
Pricing Analysis
Short lead-time premiums of 15-25% apply to encapsulated anthocyanin orders from Baden-Württemberg organic processors requiring sub-48-hour turnaround, while spot inventory discounts of 8-12% clear excess synthetic dye stocks ahead of EFSA re-evaluations. Three-tier pricing structure across premium fermentation-derived, standard plant-extract, and economy synthetic tiers segments buyer archetypes, with Bavarian dairy alternatives manufacturers least price-sensitive due to clean-label certification requirements and snack extruders most sensitive given thermal stability constraints. Pricing pressure stems from agricultural commodity swings destabilizing natural colorant cost structures against petroleum-based alternatives.
Supply Chain Analysis
Reverse-logistics flows for expired natural colorant batches concentrate in North Rhine-Westphalia's chemical reprocessing hubs, where BASF Ludwigshafen facilities recover aluminum substrates from lake colorant returns. Supply concentrates in Germany, Denmark, and the Netherlands, with raw material dependencies on Chinese spirulina cultivation, Indian annatto extraction, and domestic sugar beet processing. Single-source vulnerability from Chinese spirulina concentration creates exposure to export license disruptions. Distribution runs through Düsseldorf-Cologne chemical distributors serving Mittelstand processors alongside direct-procurement platforms connecting mid-sized buyers with fermentation specialists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race. Players are pursuing upstream agricultural feedstock control to secure supply certainty and margin capture as EFSA re-evaluations accelerate formulation pivots.
For Market Incumbents: Lock in fermentation-derived capacity through captive biotechnology partnerships before precision agriculture traceability becomes mandatory for retail placement. Defend against Chr. Hansen's premium positioning by accelerating Baden-Württemberg encapsulation technology licensing. Backward integration into Bavarian organic beetroot cultivation secures supply certainty against harvest volatility. For New Entrants and Emerging Players: Begin with Stuttgart-centered premium organic processors underserved by existing natural colorant certification tiers. Target dairy alternatives applications where blockchain-traceable spirulina certificates command shelf placement. A direct-procurement platform bypassing traditional distributor markups offers immediate cost advantage for mid-sized juice processors. For Investors and Strategic Acquirers: EFSA's titanium dioxide negative opinion finalization is the leading indicator that whitening agent substitution demand will concentrate acquisition value in calcium carbonate and starch-based alternative specialists. Five-to-ten-year viability favors fermentation technology platform operators with precision agriculture traceability integration. Monitor BfR enforcement record publication timelines for early signals of compliance cost escalation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Agricultural Feedstocks | Captive beetroot and spirulina cultivation in Bavaria insulates margin structures from commodity volatility. |
| Encapsulation Technology Licensing | Freiburg-based microencapsulation partnerships enable natural pigment stability in high-heat confectionery applications. |
| Fermentation Capacity Expansion | Precision biotechnology scale-up narrows cost gaps with synthetic azo dyes for beverage reformulation. |
| Blockchain Traceability Certification | Verified supply chain documentation satisfies German private-label retailer shelf-placement mandates. |
| Direct-Procurement Platform Launch | E-commerce ingredient channels bypass traditional distributor markups for mid-sized Mittelstand processors. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with food chemists, procurement leads at Bavarian dairy alternatives processors, BfR regulatory affairs officers, encapsulation technology R&D directors, and Stuttgart-centered organic brand managers. EFSA additive safety assessments, German Lebensmittel- und Futtermittelgesetzbuch enforcement records, EU Green Deal bio-transition target documentation, and beverage industry association procurement surveys furnished validation layers. Bottom-up volume modeling across colorant categories triangulated against top-down market sizing from chemical manufacturing disclosures.
Granularity extended to product type, application substrate, end-user procurement sophistication, and packaging format across the projection horizon. CAGRs derived from segment-level volume trajectories weighted by EFSA re-evaluation timing and EU Green Deal compliance deadlines. Forecast inputs incorporated fermentation yield improvement curves, agricultural commodity price indices, and thermal stability performance benchmarks for natural versus synthetic alternatives.
Underlying measurement precision varies by segment; synthetic colorant volumes carry tighter precision due to standardized manufacturing disclosures while natural colorant projections reflect greater uncertainty from harvest variability. Forecasts reflect assumptions regarding EFSA opinion finalization schedules and EU Green Deal enforcement intensity. Practitioners should monitor BfR additive safety reassessment calendars and Bavarian organic processor procurement tender announcements for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Plant-Based Emulsifiers Market
Food Additives and Ingredients
Natural Food Additives Market
Food Additives and Ingredients
India Food Color Industry Market
Food Additives and Ingredients
Italy Food Preservatives Market
Food Additives and Ingredients
Wheat & Rice Flour Substitute-Resistant Starch Market
Food Additives and Ingredients
Edible and Soluble Films Market
Food Additives and Ingredients
United States Food Additives Market
Food Additives and Ingredients
Canada Food Enzymes Market
Food Additives and Ingredients
Food Grade Magnesium Derivatives Market
Food Additives and Ingredients
Africa Microbial Food Culture Market
Food Additives and Ingredients
Spain Food Preservatives Market
Food Additives and Ingredients
Canada Food Colorants Market
Food Additives and Ingredients
Monostarch Phosphate Market
Food Additives and Ingredients
Beverage Encapsulants Market
Food Additives and Ingredients
Fish Tank Water Additives Market
Food Additives and Ingredients
South Africa Food Additives Market