
 Transglutaminase Market | 2026-2036
Transglutaminase Market Size, Share, and Industry Trends Forecast 2026-2036
Transglutaminase Market Outlook
Plant-based protein formulation is recalibrating transglutaminase demand as meat alternatives require stronger protein cross-linking. Ajinomoto Co., Inc. leverages decades of fermentation expertise to dominate microbial strain development. Nagase Group anchors Japanese supply chains through specialized enzyme distribution networks. AB Enzymes competes on bakery and dairy application breadth across European food manufacturers.
Transglutaminase is a transferase enzyme that catalyzes covalent bond formation between protein-bound glutamine and lysine residues, typically operating at pH 5-8 and temperatures between 40-60°C for optimal cross-linking activity in food matrices. Microbial transglutaminase leads volume production due to lower immunogenicity concerns and scalable submerged fermentation manufacturing. Plant-based transglutaminase represents the fastest-growing product category as clean-label formulations displace animal-derived alternatives in vegan product lines. Meat processing applications concentrate margin pools where texture modification commands premium enzyme dosing per unit output.
EFSA evaluates novel enzyme safety dossiers for European market authorization while the FDA maintains GRAS notification pathways for food-grade transglutaminase in the United States. China's SAMR enforces GB standards for food additive enzyme purity and labeling transparency. Stakeholders must monitor regulatory divergence between jurisdictions where microbial source documentation requirements are tightening.
Market Dynamics
Microbial transglutaminase production is consolidating around submerged fermentation facilities with scale advantages, while plant-based protein formulation creates divergent purity requirements that strain legacy supply configurations.
Growth Catalysts
- Clean-label enzyme demand:Vegan product lines in Germany and France require documented non-animal transglutaminase sourcing, creating premium positioning for microbial and plant-derived variants.
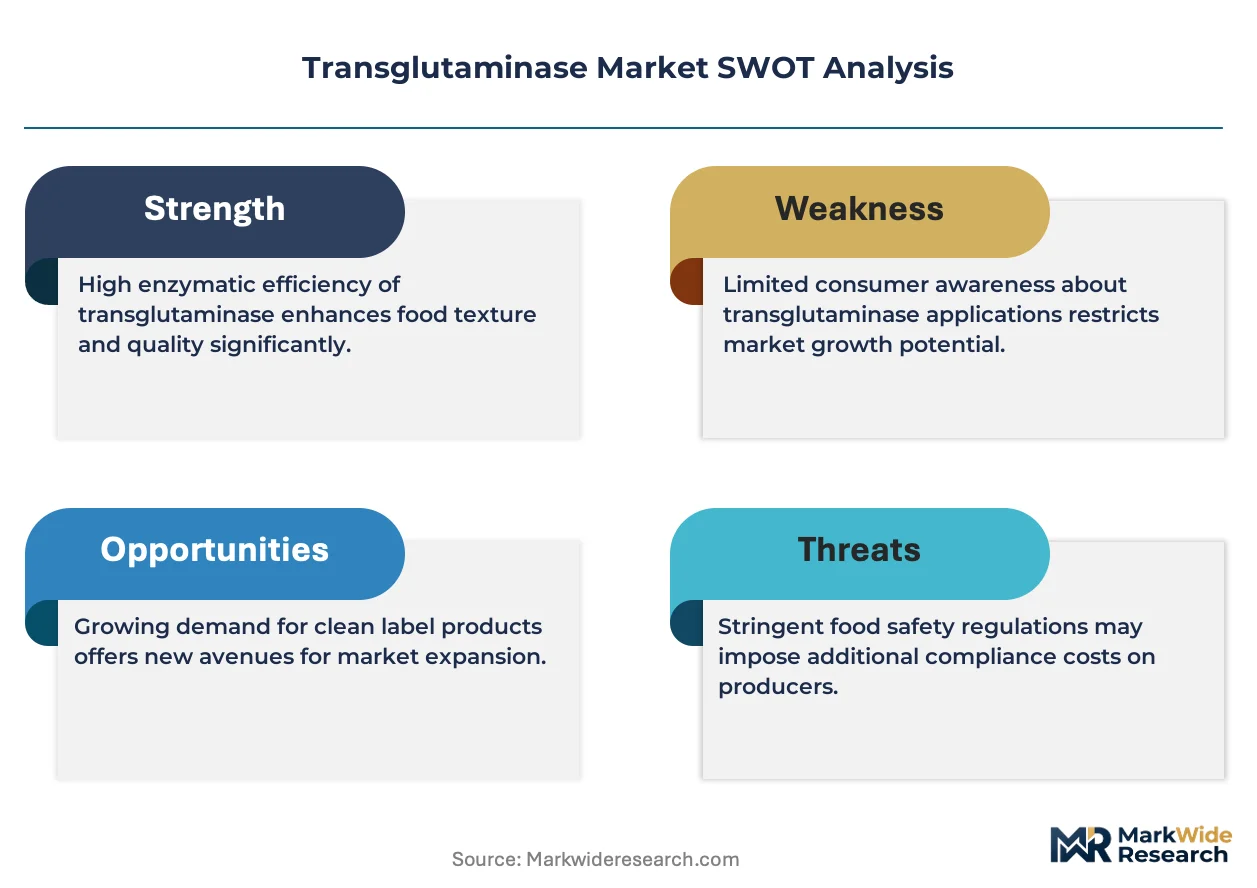
- EU Green Deal compliance:REACH framework revisions on enzymatic additives are accelerating substitution of chemical binders with food-grade transglutaminase in processed meat applications.
- Biotech zone expansion:MIIT-backed industrial clusters in Jiangsu and Shandong provinces are scaling fermentation capacity for export-grade enzyme production.
Market Restraints
- Input cost volatility:Corn-derived glucose and nitrogen sources for microbial fermentation face agricultural commodity price swings that compress enzyme manufacturer margins.
- Supply concentration risk:A single Japanese fermentation technology provider controls critical strain IP for high-activity transglutaminase, creating single-source dependency for European and North American formulators.
- Regulatory friction:EFSA novel enzyme dossier requirements impose 18-24 month approval timelines that delay market entry for improved microbial variants.
Strategic Opportunities
- Underpenetrated bakery segment:Artisan and industrial bread manufacturers in Italy and Spain remain below 15% transglutaminase adoption for dough conditioning versus meat processing saturation.
- Regulatory tailwind:China's SAMR GB standard updates on food additive enzyme labeling create first-mover advantage for producers with transparent supply chain documentation.
- Technology convergence:Precision fermentation combined with AI-guided strain optimization is opening pathways to custom enzyme activity profiles for specific protein substrates.
Industry Challenges
- Fermentation scale-up complexity:Translating bench-scale titers to industrial bioreactor output requires specialized biochemical engineering talent that concentrates in Basel and Boston metro areas.
- Cross-jurisdiction compliance:Divergent documentation requirements between FDA GRAS notification and EFSA full dossier pathways force dual-track regulatory investment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Transglutaminase Market |
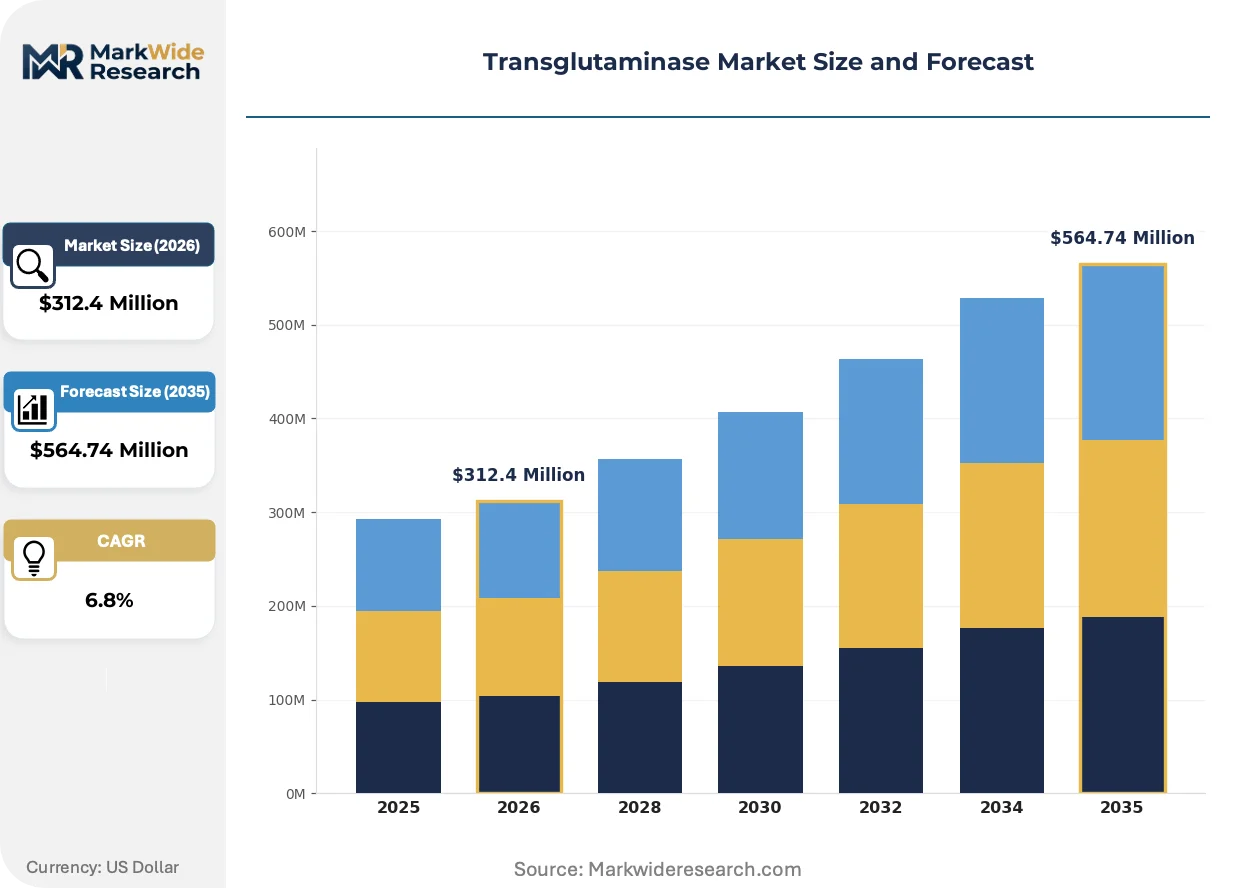
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Microbial Transglutaminase, Plant-Based Transglutaminase, Animal-Based Transglutaminase, Synthetic Transglutaminase Application: Meat Processing, Dairy Products, Bakery Products, Seafood Processing End User: Food Manufacturers, Restaurants, Food Service Providers, Retail Chains Distribution Channel: Online, Direct Sales, Wholesale, Specialty Stores |
| Companies Covered | Ajinomoto Co., Inc., Nagase Group, AB Enzymes, Amano Enzyme, DSM, Novozymes, Micro-Tech Foods Ingredients, Jiangsu Yiming Biological, Pangbo Biological, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Transglutaminase Market Strategic Shifts
Transglutaminase markets are experiencing accelerated product architecture shifts as clean-label mandates and precision biomanufacturing capabilities rewrite formulation economics across food manufacturing verticals.
Microbial transglutaminase derived from Streptomyces mobaraensis is consolidating position as the dominant commercial format due to calcium-independent activity and superior thermostability. Meat alternative manufacturers in the Netherlands and California are adopting this variant at accelerated rates. The technology is consolidating supply chains around a smaller set of fermentation specialists with validated pharmaceutical-grade production infrastructure.
REACH authorization requirements for enzymatic processing aids are tightening purity thresholds and traceability documentation across European food manufacturing. Industrial enzyme users must now submit full toxicological dossiers for novel transglutaminase variants. Bakery and dairy application segments are responding by consolidating supplier relationships toward established players with existing EFSA positive opinions.
Direct procurement from fermentation producers is displacing traditional enzyme distribution intermediaries among large meat processors. Cargill and JBS-scale operators are negotiating volume contracts that bypass regional distributors entirely. This pattern is most visible in Brazil and US Midwest protein processing clusters where buyer concentration enables supply chain compression.
Transglutaminase Market Segmentation
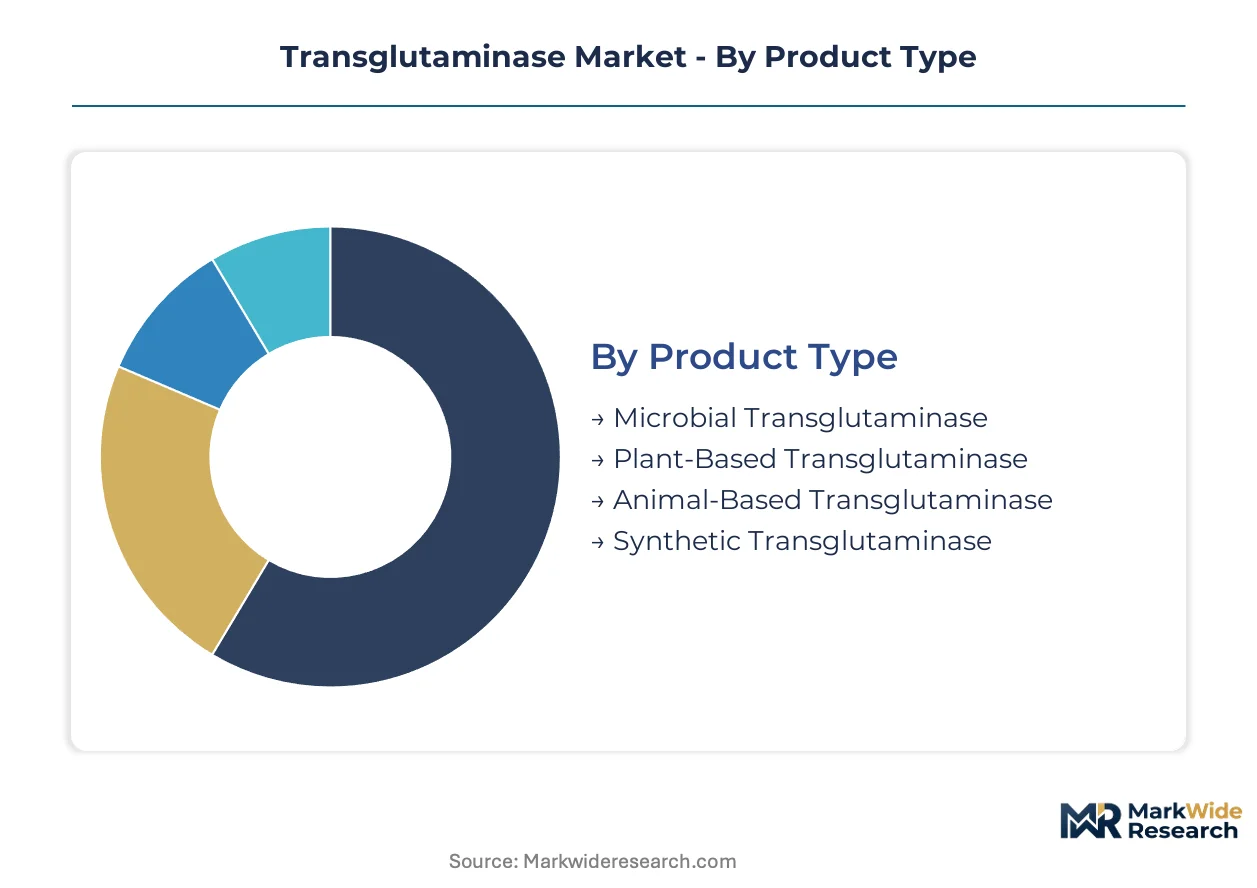
Transglutaminase procurement decisions hinge on enzymatic activity profiles, regulatory compliance documentation, and protein substrate compatibility. Manufacturers segment demand across production technologies, application matrices, and supply chain configurations to optimize dosing economics and clean-label positioning.
Product Type:
Buyers prioritize calcium independence, thermostability thresholds, and source traceability when selecting enzymatic formats for food matrix integration.
- Microbial Transglutaminase:Derived from Streptomyces mobaraensis fermentation, this variant operates without calcium cofactors and withstands thermal processing up to 60°C. Meat processors in Germany and the Netherlands specify this format for standardized texture modification in restructured products. EFSA's positive opinions on strain safety documentation accelerate procurement approvals for European formulators.
- Plant-Based Transglutaminase:Extracted from leguminous sources or precision-fermented plant hosts, this category addresses vegan certification requirements and allergen-free labeling mandates. Clean-label bakery manufacturers in France and California are shifting specifications toward this format as animal-derived enzymes face exclusion from plant-forward product lines.
- Animal-Based Transglutaminase:Tissue-derived variants from guinea pig liver or bovine plasma retain niche use in pharmaceutical research applications.
- Synthetic Transglutaminase:Chemically synthesized analogs remain experimental with limited commercial scale due to cost and activity consistency challenges.
Volume sits with Microbial Transglutaminase; growth tilts toward Plant-Based Transglutaminase.
Application:
End-use concentration varies sharply by protein matrix complexity and texture modification intensity requirements.
- Meat Processing:Restructured meat, surimi analogs, and cold-set binding applications consume the highest enzyme dosing per ton of finished product. Brazilian and US Midwest processors negotiate direct fermentation contracts to secure volume pricing for high-activity formulations. FDA GRAS notification pathways streamline incorporation into standardized meat products.
- Dairy Products:Yogurt texture stabilization and cheese curd firming drive moderate dosing requirements with emphasis on calcium-independent activity for acidified matrices.
- Bakery Products:Artisan and industrial bread manufacturers in Italy and Spain remain below saturation thresholds for dough conditioning applications, creating expansion headroom.
- Seafood Processing:Surimi and fish paste applications in Japan and South Korea utilize transglutaminase for gel strength enhancement in processed seafood matrices.
Margin pools concentrate in Meat Processing; Bakery Products show the steepest expansion trajectory as adoption rates normalize toward meat-sector benchmarks.
End User:
Procurement scale and formulation expertise determine supplier relationship structures across the value chain.
- Food Manufacturers:Industrial-scale operators with in-house R&D capabilities specify custom activity profiles and negotiate direct fermentation supply agreements. Cargill-scale meat processors bypass distribution intermediaries entirely.
- Restaurants:Fine-dining and chain operators utilize transglutaminase for molecular gastronomy and standardized texture applications with small-batch procurement patterns.
- Food Service Providers:Institutional caterers and contract food service operators source through wholesale distributors with limited technical specification involvement.
- Retail Chains:Private-label product development teams engage enzyme suppliers for clean-label formulation support in store-brand meat and bakery lines.
Procurement volume aggregates with Food Manufacturers; technical service requirements expand most quickly among Retail Chains developing private-label capabilities.
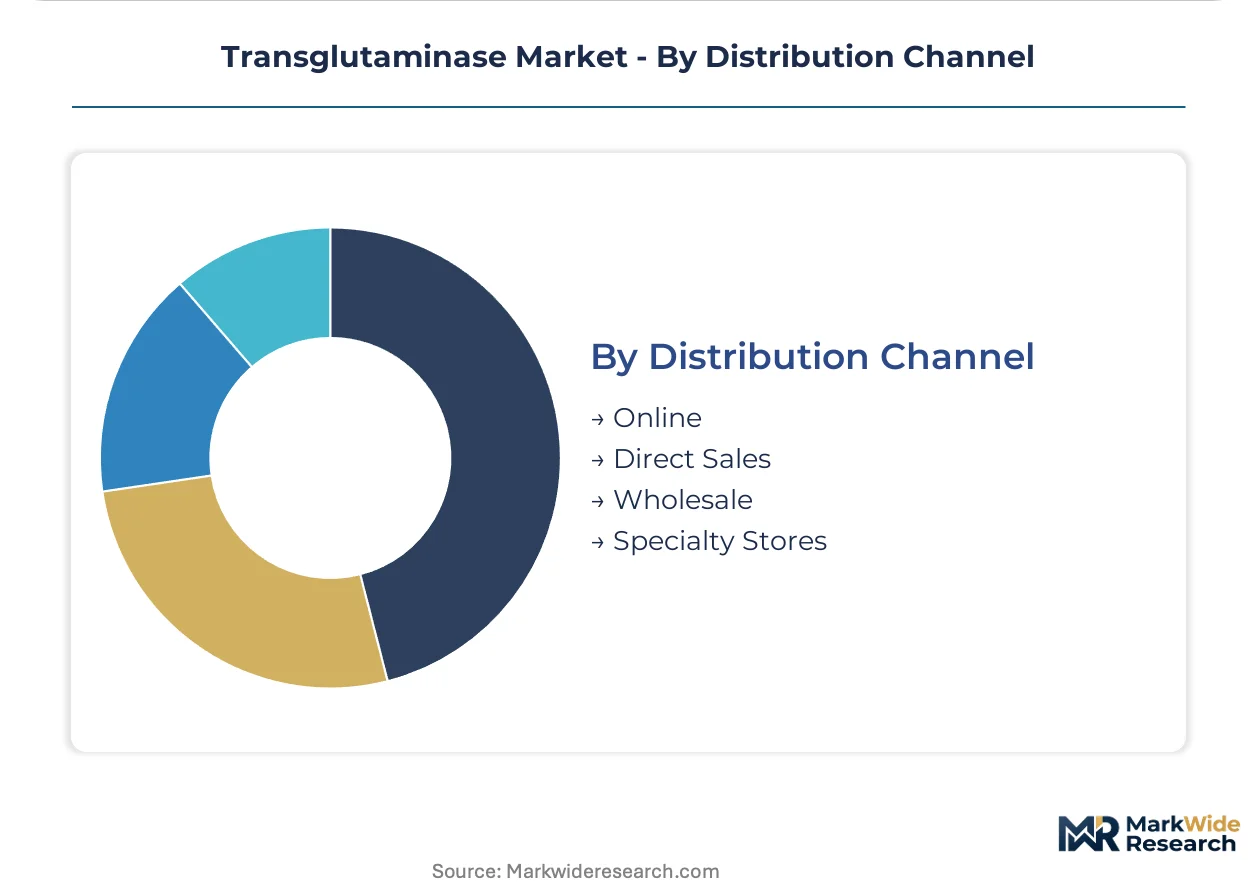
Distribution Channel:
Supply chain compression and regulatory documentation needs are reshaping channel economics for enzymatic ingredients.
- Direct Sales:Fermentation producers engage large meat processors and multinational food manufacturers through technical account management and co-development partnerships. This channel captures the highest-margin contracts with full traceability documentation.
- Wholesale:Regional distributors serve mid-tier food manufacturers and food service operators with standardized enzyme formulations and technical support.
- Online:E-procurement platforms facilitate small-volume orders from research institutions, specialty food producers, and restaurant operators with limited supplier negotiation leverage.
- Specialty Stores:Ingredient boutiques and culinary supply retailers cater to artisan producers and experimental chefs with premium-priced small packaging.
Revenue concentrates in Direct Sales; channel diversification accelerates fastest through Online platforms serving fragmented demand segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
MIIT-backed biotech zones in Jiangsu and Shandong provinces anchor transglutaminase production capacity expansion, while REACH framework revisions in Europe and FDA GRAS pathways in North America reshape regulatory compliance costs across regional markets.
China
Microbial fermentation capacity concentrates in Jiangsu and Shandong provinces where MIIT-designated industrial clusters scale submerged bioreactor infrastructure for export-grade enzyme output. SAMR enforces GB standards on food additive enzyme purity and labeling transparency, tightening documentation requirements for both domestic consumption and export shipments. Qingdao and Nanjing host the dominant fermentation facilities supplying European and North American formulators with calcium-independent transglutaminase variants.
Germany
Meat processors in Bavaria and North Rhine-Westphalia specify high-activity microbial transglutaminase for restructured product lines, driving premium enzyme dosing per ton of finished output. REACH authorization requirements for enzymatic processing aids impose full toxicological dossier submissions on industrial users, extending procurement timelines. The Frankfurt-Rhine-Main corridor anchors distribution networks serving Central European bakery and dairy manufacturers with EFSA-cleared formulations.
United States
Midwest protein processing clusters in Iowa and Nebraska negotiate direct fermentation contracts with producers, bypassing traditional enzyme distributors entirely. FDA GRAS notification pathways streamline incorporation of food-grade transglutaminase into standardized meat products, reducing regulatory friction versus European counterparts. Chicago and Minneapolis-St. Paul serve as procurement hubs for Cargill-scale operators seeking volume pricing on custom activity profiles.
Japan
Streptomyces mobaraensis strain development expertise concentrates in the Kanto region, where decades of fermentation IP accumulation creates single-source dependency for high-activity variants. METI industrial biotechnology programs subsidize precision fermentation scale-up for next-generation enzyme optimization. Tokyo-Yokohama anchors specialized distribution networks that Nagase Group leverages to supply domestic surimi and processed seafood manufacturers.
Netherlands
Meat alternative manufacturers in Noord-Brabant and Gelderland adopt microbial transglutaminase at accelerated rates for plant-based protein cross-linking applications. EFSA novel enzyme dossier requirements impose 18-24 month approval timelines that delay market entry for improved variants, favoring established suppliers with existing positive opinions. The Eindhoven-Rotterdam corridor hosts R&D facilities testing precision fermentation combined with AI-guided strain optimization for custom substrate compatibility.
Transglutaminase Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with fermentation scale determining pricing power in meat processing while application breadth wins in bakery and dairy. The vendor base concentrates around submerged fermentation specialists with pharmaceutical-grade production infrastructure, creating tiered supply dynamics. Three archetypes dominate: Japanese strain developers with proprietary IP, European application specialists with regulatory dossier depth, and Chinese volume producers with MIIT-backed capacity expansion. Competitive moves center on direct procurement relationships with large protein processors and co-development partnerships for custom activity profiles.
Within the strain development tier, Ajinomoto Co., Inc. and Amano Enzyme exemplify Japanese fermentation specialists whose decades of Streptomyces mobaraensis expertise anchor global supply for calcium-independent variants. Among European application specialists, AB Enzymes occupies a position emphasizing bakery and dairy formulation breadth across EFSA-cleared product lines. At the volume-driven end, Jiangsu Yiming Biological represents Chinese producers scaling MIIT-backed bioreactor capacity for export-grade output.
| Leading Market Players |
|---|
| Ajinomoto Co., Inc. |
| Nagase Group |
| AB Enzymes |
| Amano Enzyme |
| DSM |
| Novozymes |
| Micro-Tech Foods Ingredients |
| Jiangsu Yiming Biological |
| Pangbo Biological |
| Others |
Value Chain & Pricing Dynamics
Corn-derived glucose and nitrogen feedstocks cascade from agricultural commodity markets through fermentation economics into tiered enzyme pricing. Japanese strain developers extract premiums for calcium-independent variants while Chinese volume producers compress mid-market tiers through MIIT-backed capacity scale.
Pricing Analysis
Short lead-time premiums attach to EFSA-cleared microbial transglutaminase with full dossier documentation, while spot inventory of unvalidated strains trades at discounts. Three-tier pricing structure across premium, standard, and economy levels separates pharmaceutical-grade fermentation output from industrial-grade bulk and generic alternatives. Pricing pressure stems from agricultural input volatility compressing manufacturer margins. Large meat processors in Brazil and the US Midwest exhibit lowest price sensitivity due to volume contract leverage, while artisan bakery operators in Italy face acute cost constraints.
Supply Chain Analysis
Streptomyces mobaraensis strain IP rests on Japanese fermentation specialists in the Kanto region, while production capacity concentrates in China's Jiangsu and Shandong provinces. Critical inputs include pharmaceutical-grade bioreactor infrastructure, corn-derived glucose substrates, and specialized nitrogen sources. Single-source vulnerability around high-activity strain development creates dependency risk for European and North American formulators. Distribution runs through direct technical account relationships with Cargill-scale processors, supplemented by regional wholesale networks serving mid-tier manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Precision fermentation combined with AI-guided strain optimization is displacing legacy submerged fermentation approaches, rewriting competitive economics across protein cross-linking applications.
For Market Incumbents: Lock in direct procurement relationships with JBS-scale meat processors through co-development partnerships for custom activity profiles. Secure EFSA positive opinions on next-generation variants before REACH framework revisions tighten documentation requirements. Backward integration into pharmaceutical-grade bioreactor infrastructure in Basel and Boston metro areas defends against Chinese volume competition. For New Entrants and Emerging Players: Enter via underpenetrated bakery segments in Italy and Spain where transglutaminase adoption remains below meat-sector benchmarks. Target plant-based transglutaminase certification for vegan product lines in France and California where clean-label premiums offset scale disadvantages. Co-brand with precision fermentation platforms to bypass legacy strain IP barriers. For Investors and Strategic Acquirers: Distressed-cycle entries favor European application specialists with EFSA dossier depth during REACH compliance cost spikes. Long-term viability hinges on positioning for precision fermentation scale-up across the analysis window. Watch MIIT subsidy intensity in Jiangsu and Shandong as inflection indicator for Chinese export pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | AI-guided strain optimization at Eindhoven-Rotterdam R&D facilities accelerates custom substrate development. |
| EFSA Dossier Investment | Full toxicological documentation secures 18-24 month approval advantages under REACH framework revisions. |
| Direct Procurement Contracts | Bypassing Nagase Group distribution intermediaries captures margin from Cargill-scale Midwest processors. |
| Plant-Based Certification | Clean-label positioning in French and Californian vegan lines displaces animal-derived alternatives. |
| MIIT Zone Capacity Expansion | Jiangsu and Shandong bioreactor clusters scale export-grade output for European and North American formulators. |
Study Parameters
Multi-period observation of fermentation capacity utilization, regulatory dossier timelines, and procurement contract structures anchored the trend analysis, supplemented by interviews with submerged fermentation plant managers, enzyme procurement leads at meat processing OEMs, technical R&D directors at bakery manufacturers, and regulatory affairs specialists navigating EFSA and FDA pathways. Secondary validation drew from SAMR GB standard filings, REACH authorization databases, SEC 10-K disclosures by listed enzyme producers, and customs trade data on fermentation equipment imports. Bottom-up volume modeling triangulated against top-down market sizing across product type, application matrix, and supply chain configuration dimensions.
Segment-weighting approaches distributed value estimates across microbial, plant-based, animal-derived, and synthetic transglutaminase categories, with further disaggregation by meat processing, dairy, bakery, and seafood end-uses. CAGRs were derived from elasticity-adjusted demand projections and capacity expansion schedules throughout the forecast period. Industry-specific inputs included Streptomyces mobaraensis strain productivity curves and REACH compliance cost trajectories.
Forecast precision tightens around the base case; tail outcomes carry wider variance under EFSA dossier rejection scenarios or MIIT subsidy withdrawal conditions. Agricultural commodity price spikes and single-source strain IP concentration represent specific revision triggers. A small set of regulatory approval timelines and biotech zone policy shifts warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Fatty Esters Market
Food Additives and Ingredients
Japan Food Additives Market
Food Additives and Ingredients
Italy Sodium Reduction Ingredients Market
Food Additives and Ingredients
Global Organic Feed Additives Market
Food Additives and Ingredients
Natural Food Preservatives Market
Food Additives and Ingredients
Global Canthaxanthin Market
Food Additives and Ingredients
Food Supplement Ingredients Market
Food Additives and Ingredients
Food Grade Ammonium Carbonate Market
Food Additives and Ingredients
Lipase Food Enzymes Market
Food Additives and Ingredients
Locust Bean Gum Market
Food Additives and Ingredients
North America Dehydrated Onion Market
Food Additives and Ingredients
Flour Treatment Agent Market
Food Additives and Ingredients
United States Food Acidulants Market
Food Additives and Ingredients
Fermented Chymosin Market
Food Additives and Ingredients
Food Starch Market
Food Additives and Ingredients
Amaranth (E123) Market