
 Scrambled Egg Mix Market | 2026-2036
Scrambled Egg Mix Market Size, Share, and Industry Trends Forecast 2026-2036
Scrambled Egg Mix Market Analytics
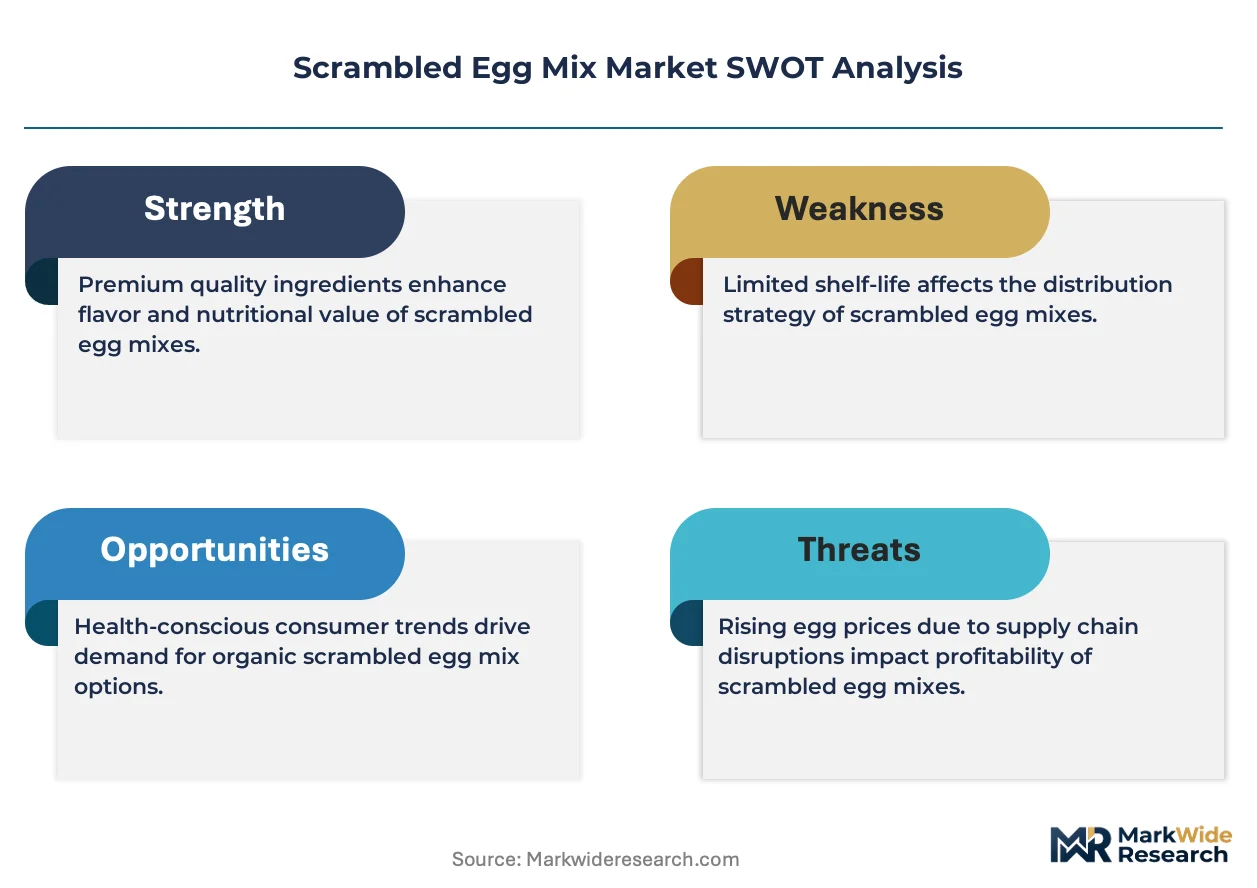
The gap between premium cage-free and commodity conventional scrambled egg mix is hardening into a durable price architecture. Sonstegard Foods Company leverages its Midwest processing footprint to anchor supply contracts with institutional buyers. Michael Foods (Papetti's) sustains volume leadership through backward integration into shell-egg operations. NestFresh differentiates on certified humane and organic positioning, commanding shelf-space premiums in specialty retail channels.
Scrambled egg mix comprises blended whole eggs or egg solids formulated with stabilizers, emulsifiers, and optional dairy extenders, then processed into powder, liquid, frozen, or ready-to-cook formats for commercial and household preparation. The powder segment leads in shelf-stable logistics, while liquid formats capture margin pools from quick-service restaurants seeking speed-of-prep consistency. Frozen scrambled egg mix occupies the fastest-expanding tier, driven by catering companies and centralized kitchen models requiring batch scalability with minimal labor.
FDA egg-product inspection rules and USDA organic standards govern labeling claims and processing sanitation, directly influencing which formulations qualify for school nutrition and federal food-purchase programs. State-level cage-free mandates in California and Massachusetts further bifurcate supply chains, forcing processors to maintain parallel conventional and premium production lines. Stakeholders must monitor evolving state animal-welfare legislation and its cascading impact on raw-material sourcing costs and customer certification requirements.
Market Dynamics
Centralized kitchen models and cage-free mandates are forcing processors to split production lines and absorb higher raw-material costs while maintaining price-competitive supply to quick-service chains.
Growth Catalysts
- California Proposition 12:State-level animal-welfare mandates expand the addressable premium segment by requiring cage-free sourcing for in-state sales, creating certified supply pull-through.
- Quick-service restaurant speed-of-prep requirements:Liquid and frozen formats reduce labor minutes per breakfast serving, driving bulk procurement from national distributors.
- Freeze-thaw stabilization chemistry:Advanced cryoprotectant formulations extend frozen product shelf life, opening catering and institutional channels previously closed to egg-based proteins.
Market Restraints
- Feed cost volatility:Corn and soybean meal price swings compress processor margins, particularly for conventional shell-egg backward integration.
- Midwest processing concentration:Iowa, Minnesota, and Ohio house over sixty percent of US breaking capacity, creating geographic supply risk during weather or disease events.
- Plant-based egg substitutes:Mung bean and chickpea protein isolates achieve functional parity in scrambled applications, threatening commodity mix volumes in cost-sensitive channels.
Strategic Opportunities
- School nutrition programs:USDA commodity purchasing specifications favor domestically processed egg products, creating stable offtake for certified suppliers.
- Direct-to-foodservice e-commerce:Platforms connecting processors with independent restaurants bypass traditional distributor markups and capture margin pool redistribution.
- EU Green Deal farm-to-fork targets:Carbon footprint labeling requirements favor lower-emission egg production systems, positioning certified humane supply for export premiumization.
Industry Challenges
- Dual-line sanitation protocols:Maintaining segregated conventional and cage-free processing streams doubles cleaning downtime and labor allocation complexity.
- Organic certification timeline:Three-year pasture conversion requirements delay supply response to organic scrambled egg mix demand spikes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Scrambled Egg Mix Market |
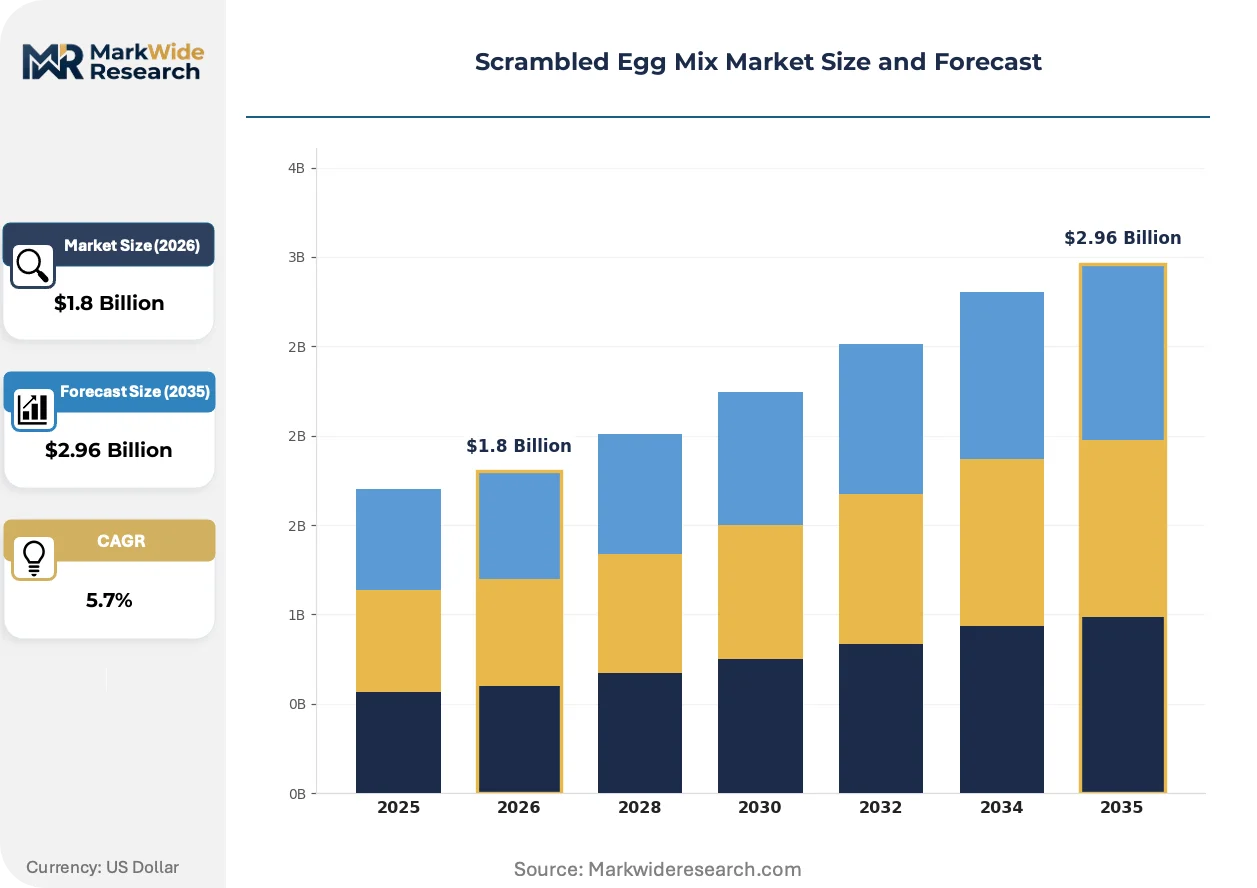
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.96 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Liquid, Ready-to-Cook, Frozen End User: Household Consumers, Restaurants, Food Service, Catering Companies Packaging Type: Bags, Boxes, Pouches, Tubs Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Food Distributors |
| Companies Covered | Sonstegard Foods Company, GCF Corporation, Augason Farms, Rembrandt Foods, Nutriom OvaEasy, Michael Foods (Papetti's), National Food Group, NestFresh, Cargill, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Scrambled Egg Mix Market Evolving Landscape
Formulation science and regulatory compliance are converging to reshape how scrambled egg mix is produced, labeled, and distributed across foodservice channels.
High-pressure processing is absorbing pathogen reduction requirements without thermal degradation of functional proteins. Quick-service chains with strict food-safety scorecards are adopting HPP-treated liquid eggs at accelerating rates. This technology is absorbing the cost premium previously assigned to pasteurized shell eggs, compressing the price gap between commodity and safety-assured supply tiers.
Massachusetts Question 3 extends cage-free mandates to the Northeast corridor, forcing processors to redirect conventional inventory to states without such requirements. The regulation creates logistical complexity for national distributors serving multi-state operators. Foodservice buyers with footprints spanning compliant and non-compliant states are consolidating suppliers with dual-certification capabilities.
Foodservice distributors are consolidating purchasing through national account structures, displacing the fragmented regional broker networks that historically managed egg-product procurement. This concentration shifts pricing power toward buyers with volume commitments exceeding ten thousand cases annually. The phenomenon is most visible in the United States, where Sysco and US Foods negotiate direct processor contracts bypassing traditional egg-marketing cooperatives.
Scrambled Egg Mix Market Segmentation
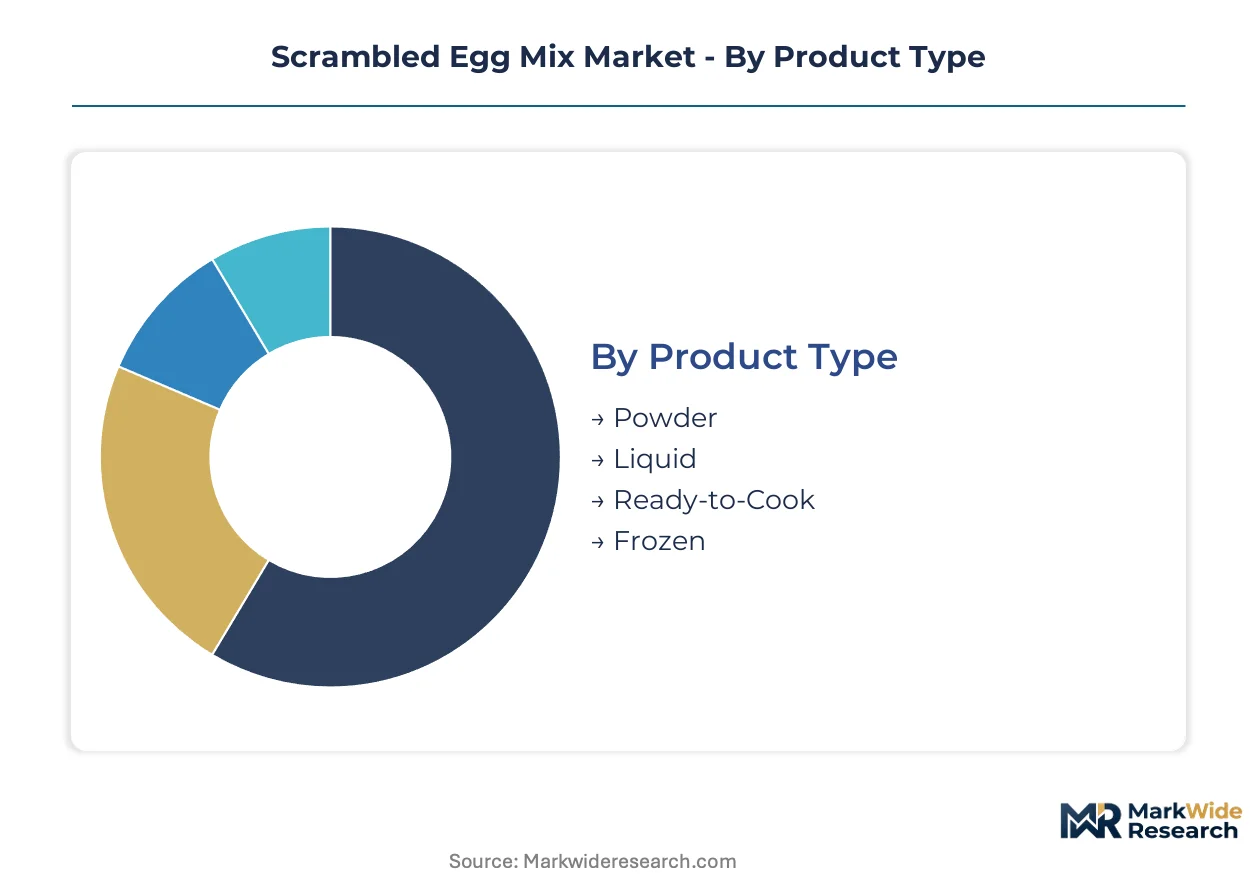
Segmentation in scrambled egg mix reveals how formulation, packaging, and channel choices map to distinct operational requirements across foodservice and retail buyers. Each dimension carries specific cost, shelf-life, and regulatory implications that determine supplier selection criteria.
Product Type:
Format selection tracks directly to kitchen equipment profiles and labor cost structures, with buyers upgrading from powder to liquid or frozen as throughput requirements intensify.
- Powder:Dehydrated whole egg or yolk solids blended with anti-caking agents deliver 12-24 month ambient stability. Institutional buyers in remote locations and military procurement channels favor this format for inventory flexibility and reduced cold-chain dependency.
- Liquid:Pasteurized blended whole eggs in aseptic bag-in-box or bulk tank configurations enable direct pump dispensing onto griddles. Quick-service restaurants with high-throughput breakfast dayparts concentrate demand here for speed-of-prep consistency and portion control precision.
- Ready-to-Cook:Pre-seasoned or pre-cooked formats reduce final preparation to reheating or minimal finishing steps. Convenience-focused retail channels and limited-service hotel breakfast programs drive adoption.
- Frozen:IQF or block-frozen scrambled egg products with cryoprotectant stabilization extend distribution radius for catering and centralized kitchen models. Batch scalability with minimal skilled labor positions this format for institutional expansion.
Liquid sits at the top of the volume ranking, with Frozen climbing the fastest as catering companies adopt centralized production models.
End User:
Customer type determines order frequency, certification requirements, and price sensitivity thresholds, with foodservice distributors managing divergent specification portfolios across account types.
- Household Consumers:Retail-packaged formats in smaller unit sizes emphasize convenience and extended refrigerator stability. Cage-free and organic claims command shelf-space premiums in specialty grocery channels.
- Restaurants:Independent and chain operators source through broadline distributors with strict HACCP documentation requirements. Speed-of-prep specifications favor liquid or frozen formats over powder reconstitution.
- Food Service:Institutional accounts including healthcare, corrections, and military facilities prioritize cost containment and nutritional compliance over premium positioning. USDA commodity specifications govern procurement for federal nutrition programs.
- Catering Companies:Event-based volume spikes require batch-scalable formats with hold-time stability. Frozen scrambled egg mix with extended thaw-and-serve windows reduces on-site labor and equipment requirements.
Food Service captures the largest order volumes, with Catering Companies expanding most quickly as event formats recover and centralized kitchen outsourcing accelerates.
Packaging Type:
Container selection balances shelf appeal, portion control, and logistics efficiency, with sustainability pressures reshaping material specifications across channels.
- Bags:Flexible multi-ply laminates for powder formats optimize cube utilization in palletized shipments. Institutional buyers prioritize cost efficiency over shelf presentation.
- Boxes:Corrugated cases with inner liners protect liquid bag-in-box configurations during distribution. Quick-service chain specifications increasingly require recyclable outer materials.
- Pouches:Stand-up or flat pouches with reseal features target retail convenience positioning. Portion-control single-serve formats reduce waste in household and small commercial settings.
- Tubs:Rigid plastic or paperboard containers support ready-to-cook and frozen formats requiring structural protection. Deli and prepared-food retail channels favor this presentation for cold-case visibility.
Bags dominate institutional procurement by volume, with Pouches gaining share fastest as retail brands emphasize sustainability credentials and portion flexibility.
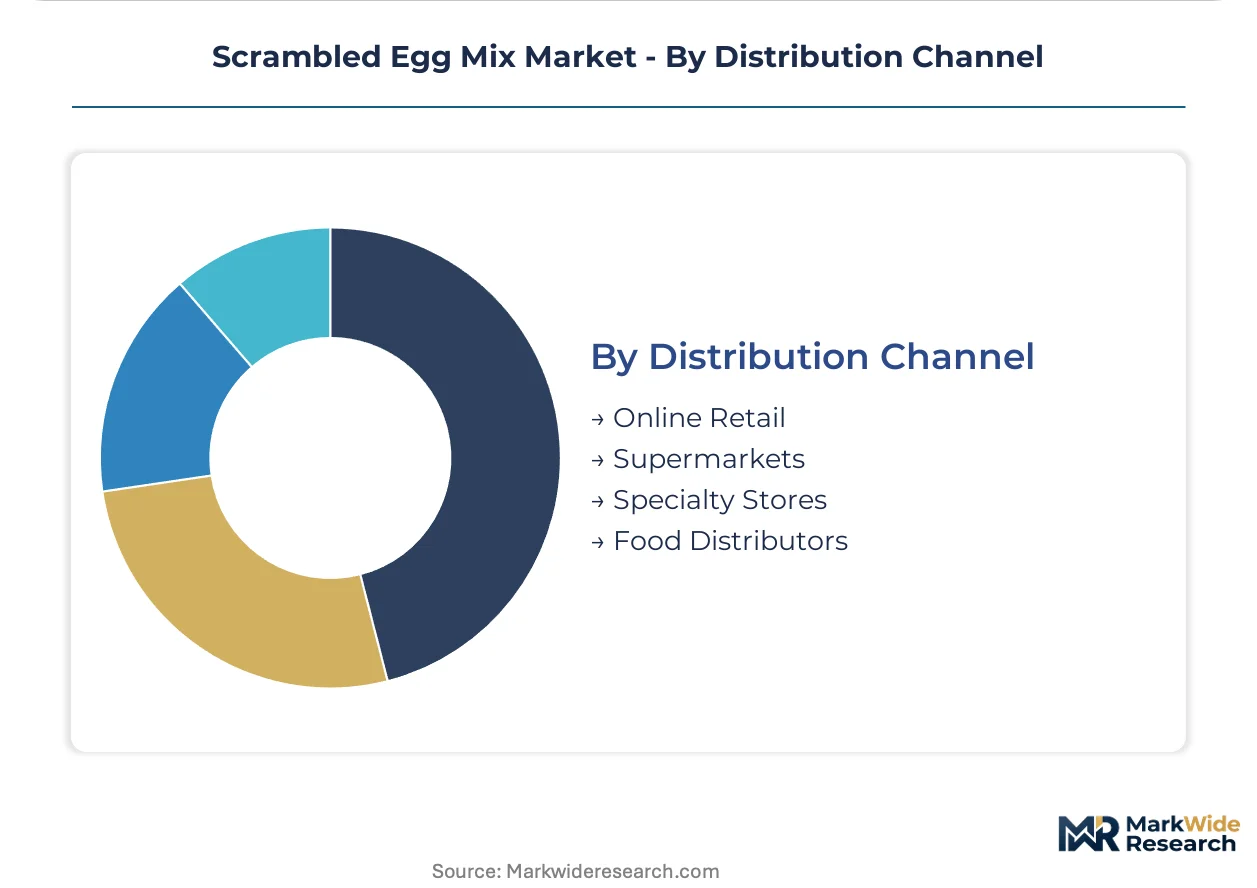
Distribution Channel:
Channel structure determines margin capture, with direct relationships displacing traditional broker networks as account consolidation accelerates.
- Online Retail:Direct-to-consumer and B2B platforms enable smaller processors to access independent restaurants without distributor markup. Subscription and auto-replenishment models build recurring revenue in household segments.
- Supermarkets:Mass retail placement requires slotting fee investment and promotional support for category entry. Cage-free and organic variants secure differentiated positioning in perimeter dairy cases.
- Specialty Stores:Natural food and gourmet retailers emphasize certified humane, pasture-raised, and local sourcing claims. Smaller pack sizes and premium price points align with consumer willingness to pay for welfare transparency.
- Food Distributors:Sysco, US Foods, and regional broadliners consolidate purchasing through national account structures. Volume commitments exceeding ten thousand cases annually unlock direct processor pricing and customized formulation services.
Food Distributors command the highest throughput, with Online Retail showing the steepest expansion trajectory as procurement digitization penetrates independent restaurant segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Midwest egg-breaking specialists and California-based cage-free processors anchor the workforce concentration driving regional supply patterns. Talent pools in Iowa, Minnesota, and Ohio sustain over sixty percent of domestic breaking capacity. Processing expertise clusters around feed-milling and shell-egg logistics corridors.
United States
Quick-service restaurant chains and institutional foodservice distributors drive bulk procurement of liquid and frozen formats. FDA egg-product inspection rules and USDA organic standards govern labeling claims for school nutrition programs. Iowa, Minnesota, and Ohio house the majority of breaking capacity, with processors maintaining dual conventional and cage-free production lines to serve bifurcated state mandates.
Germany
Industrial bakeries and ready-meal manufacturers absorb powder and liquid egg volumes for processed food applications. EU Green Deal farm-to-fork targets and carbon footprint labeling requirements favor lower-emission production systems. The Lower Saxony poultry corridor concentrates breaking and processing operations serving northwestern European distribution networks.
China
Centralized kitchen models for chain restaurants and airline catering services expand demand for frozen scrambled egg formats. SAMR food safety regulations and GB standards for egg products shape import requirements and domestic processing protocols. The Yangtze River Delta region clusters food manufacturing campuses with integrated egg-product supply chains.
United Kingdom
Hotel breakfast programs and contract catering operations source liquid and ready-to-cook formats for labor efficiency. EFSA welfare labeling guidelines and post-Brexit import certification requirements complicate cross-border sourcing from EU suppliers. The East Midlands poultry belt maintains processing infrastructure serving London and southeast England foodservice channels.
Brazil
Export-oriented processed food manufacturers and domestic quick-service chains drive powder and liquid egg demand. ANVISA sanitary surveillance standards govern processing facility licensing and product registration for institutional channels. The São Paulo state hinterland concentrates integrated poultry operations with breaking capacity serving Mercosur trade corridors.
Scrambled Egg Mix Market Competitive Landscape
Top-tier vendors anchor national account structures with broadline distributors, while mid-scale processors compete on certified humane and organic positioning. The vendor base stratifies across three tiers: commodity volume suppliers with backward integration into shell-egg operations, specialty certifiers capturing welfare-premium pools, and private-label converters serving distributor house brands. Strategic archetypes include cage-free specialists, freeze-thaw stabilization innovators, and direct-to-foodservice platform operators. Competitive moves center on dual-certification capacity expansion and direct processor contracting that bypasses traditional egg-marketing cooperatives.
Among US-based processors, Sonstegard Foods Company exemplifies the Midwest volume archetype with its Iowa processing footprint, while Michael Foods anchors the integrated commodity tier through its Papetti's shell-egg operations. NestFresh occupies the specialty certifier position, representing the humane and organic premium segment in retail and foodservice channels.
| Leading Market Players |
|---|
| Sonstegard Foods Company |
| GCF Corporation |
| Augason Farms |
| Rembrandt Foods |
| Nutriom OvaEasy |
| Michael Foods (Papetti's) |
| National Food Group |
| NestFresh |
| Cargill, Inc. |
| Others |
Value Network & Pricing Analysis
High-pressure processing adoption simultaneously compresses pasteurization costs and concentrates supplier power among processors with capital-intensive equipment investments. Cage-free mandate compliance across California and Massachusetts forces parallel production lines that reshape cost economics while locking in geographic supply clustering around Midwest breaking capacity.
Pricing Analysis
The bundled-vs-unbundled service split separates commodity powder formats from value-added liquid and frozen tiers with cryoprotectant stabilization and direct-to-griddle dispensing. Three-tier pricing structure across premium cage-free, standard conventional, and economy extended formulations tracks certification grade and volume commitment scale. Pricing pressure stems from feed cost volatility in corn and soybean markets, compressing margins for backward-integrated shell-egg operators. Quick-service restaurant chains with national account structures exhibit lowest price sensitivity, while independent restaurants and institutional buyers in federal nutrition programs face highest cost containment pressure.
Supply Chain Analysis
Single-source vulnerability sits with Iowa, Minnesota, and Ohio housing over sixty percent of domestic egg-breaking capacity, creating geographic concentration risk during weather or disease events. Raw material flows draw from corn and soybean meal feed inputs, shell-egg logistics corridors, and cryoprotectant chemical supplies. Supply chain risk centers on regulatory restriction from state-level cage-free mandates fragmenting distribution networks across compliant and non-compliant jurisdictions. Distribution runs through consolidated national account structures with Sysco and US Foods displacing traditional regional broker networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between Midwest production cost advantages and coastal premium pricing driven by California Proposition 12 and Massachusetts Question 3 compliance requirements.
For Market Incumbents: Cement dual-certification capacity across conventional and cage-free production streams to capture national account consolidation with distributors spanning multi-state footprints. Expand freeze-thaw stabilization R&D to extend frozen product shelf life and defend against plant-based egg substitute encroachment in cost-sensitive channels. Prioritize backward integration into shell-egg operations to buffer feed cost volatility exposure. For New Entrants and Emerging Players: Independent restaurant operators underserved by direct-to-foodservice e-commerce platforms represent the most penetrable buyer archetype for bypassing traditional distributor markups. Target certified organic scrambled egg mix demand spikes with three-year pasture conversion timeline planning to capture supply response delays from incumbent processors. Lead with sustainability credential transparency and carbon footprint labeling aligned with EU Green Deal export requirements. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale processors lacking dual-certification capacity but holding geographic positioning in cage-free mandate corridors. Long-term viability hinges on regulatory arbitrage capture across state animal-welfare legislation trajectories and federal nutrition program offtake stability. Watch for inflection signals in plant-based egg substitute functional parity announcements threatening commodity tier volumes.| Strategic Initiative | Industry Significance |
|---|---|
| Dual-Certification Capacity Expansion | California Proposition 12 and Massachusetts Question 3 compliance enables multi-state distributor contracts. |
| Freeze-Thaw Stabilization R&D Investment | Advanced cryoprotectant chemistry extends frozen product shelf life for catering channel penetration. |
| Direct-to-Foodservice E-Commerce Platform Launch | Bypassing Sysco and US Foods markups captures margin pool redistribution from independent restaurants. |
| Backward Integration into Shell-Egg Operations | Captive supply from Iowa and Ohio production buffers corn and soybean feed cost volatility. |
| EU Green Deal Carbon Labeling Certification | Lower-emission production systems unlock export premiumization into German and UK foodservice channels. |
Research Methodology
Coverage spans North America, Western Europe, and Asia-Pacific, with primary inputs from each region combining executive interviews with quick-service restaurant procurement directors, foodservice distributor category managers, egg-processor operations heads, and agricultural commodity traders. Secondary validation draws from FDA egg-product inspection filings, USDA organic certification databases, state-level cage-free mandate legislative records, and customs trade data on egg-product imports. Bottom-up volume modeling triangulates against top-down market sizing across the analysis window.
Granularity-level framing applies country-specific regulatory cluster modeling for the United States, Germany, China, United Kingdom, and Brazil with product format segmentation at powder, liquid, frozen, and ready-to-cook tiers. End-user segmentation distinguishes household, restaurant, foodservice, and catering company demand patterns. CAGRs derive from historical trajectory analysis adjusted for state mandate implementation timelines and quick-service restaurant expansion patterns. Forecast inputs incorporate feed cost futures curves and plant-based substitute penetration scenarios.
Underlying measurement precision varies by segment; liquid and frozen formats carry tighter precision than powder given distributor national account transparency, while organic certification tiers exhibit wider uncertainty bands due to pasture conversion timeline variability. Forecasts reflect documented assumptions around state mandate adoption cascades and federal nutrition program funding stability. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Asia Pacific Food Acidulants Market
Food Additives and Ingredients
Meat Stabilizers Blends Market
Food Additives and Ingredients
Egypt Feed Additives Market
Food Additives and Ingredients
Ascorbyl Palmitate Market
Food Additives and Ingredients
Food Humectants Market
Food Additives and Ingredients
Filling Fat Market
Food Additives and Ingredients
Food Protein Ingredient Market
Food Additives and Ingredients
Olestra Market
Food Additives and Ingredients
Canada Food Acidulants Market
Food Additives and Ingredients
Calcium Inosinate Market
Food Additives and Ingredients
Feed Anti-Caking Agents Market
Food Additives and Ingredients
North America Microencapsulation Market
Food Additives and Ingredients
Fruit Ripening Agents Market
Food Additives and Ingredients
North America Food Coating Ingredients Market
Food Additives and Ingredients
India Food Emulsifiers Market
Food Additives and Ingredients
Methyl Oleate Market