
 Spain Food Colorants Market | 2026-2036
Spain Food Colorants Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Food Colorants Market Analytics
Beverage applications is expanding faster than legacy bakery segments as Spanish consumers shift toward clean-label drinks and functional beverages. Chr. Hansen Holding A/s leverages its fermentation-derived pigment portfolio to dominate the natural colorant tier. GNT International B.V. sustains supply chain proximity through its Dutch-Spanish distribution network. Döhler GmbH specializes in integrated beverage ingredient systems that bundle colorants with flavor and stabilization components.
Food colorants comprise dyes, pigments, and lakes that impart, enhance, or restore color in processed foods, typically stable between pH 3.0 and 8.0 and resistant to thermal degradation up to 120°C during pasteurization. Their primary commercial purpose is to standardize visual appeal across production batches and offset color loss from light, air, moisture, or temperature extremes during manufacturing. Natural Dyes command premium positioning as EU consumers reject synthetic additives, while Synthetic Dyes retain cost-sensitive volume in private-label snack manufacturing. Caramel colorants occupy a mature, high-volume niche across the Spanish beer and soft drink industries where E150 stability remains non-negotiable.
EFSA evaluates all food additive safety dossiers before EU-wide authorization, while Spain's AESAN enforces national labeling compliance and monitors cross-border ingredient shipments. REACH chemical registration requirements constrain imported synthetic dye formulations, tilting procurement toward EU-certified natural alternatives. Stakeholders must track pending EFSA re-evaluations of titanium dioxide and azo dyes to anticipate reformulation mandates before supply contracts lock in multi-year pricing.
Market Dynamics
EU REACH chemical registration requirements and EFSA additive re-evaluations are compressing synthetic dye availability while Catalonia's beverage processing cluster pulls procurement toward fermentation-derived natural alternatives.
Growth Catalysts
- Clean-label beverage demand:Spanish consumers reject artificial additives in functional drinks. Manufacturers reformulate with plant-based pigments to secure retail shelf placement.
- EU Green Deal alignment:National sustainability mandates reward processors adopting bio-based colorants through streamlined permitting.
- Fermentation technology maturation:Biotech-derived pigments achieve cost parity with synthetic equivalents in high-volume applications.
Market Restraints
- Beetroot and spirulina input volatility:Agricultural commodity swings compress margins for natural colorant producers dependent on crop yields.
- Synthetic dye supply concentration:Three Asian chemical conglomerates control azo dye precursor manufacturing, exposing Spanish importers to tariff and logistics risk.
- EFSA authorization timelines:Novel natural pigment approvals require 18-24 month safety dossier reviews, delaying product launches.
Strategic Opportunities
- Andalusian citrus pigment extraction:Valencia's orange processing waste streams offer untapped carotenoid feedstock for regional colorant production.
- Direct-to-brewery distribution:Bypassing ingredient distributors, colorant suppliers build captive relationships with Madrid's craft beer sector.
- Ecolabelling premium capture:EU organic certification unlocks 15-20% price premiums in export-oriented Spanish food manufacturing.
Industry Challenges
- Natural pigment stability expertise:Formulation chemists capable of managing pH and thermal degradation in plant-based colorants command scarce talent premiums.
- Legacy equipment retrofit costs:Synthetic-optimized filling and pasteurization lines require capital outlay to prevent natural pigment oxidation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Food Colorants Market |
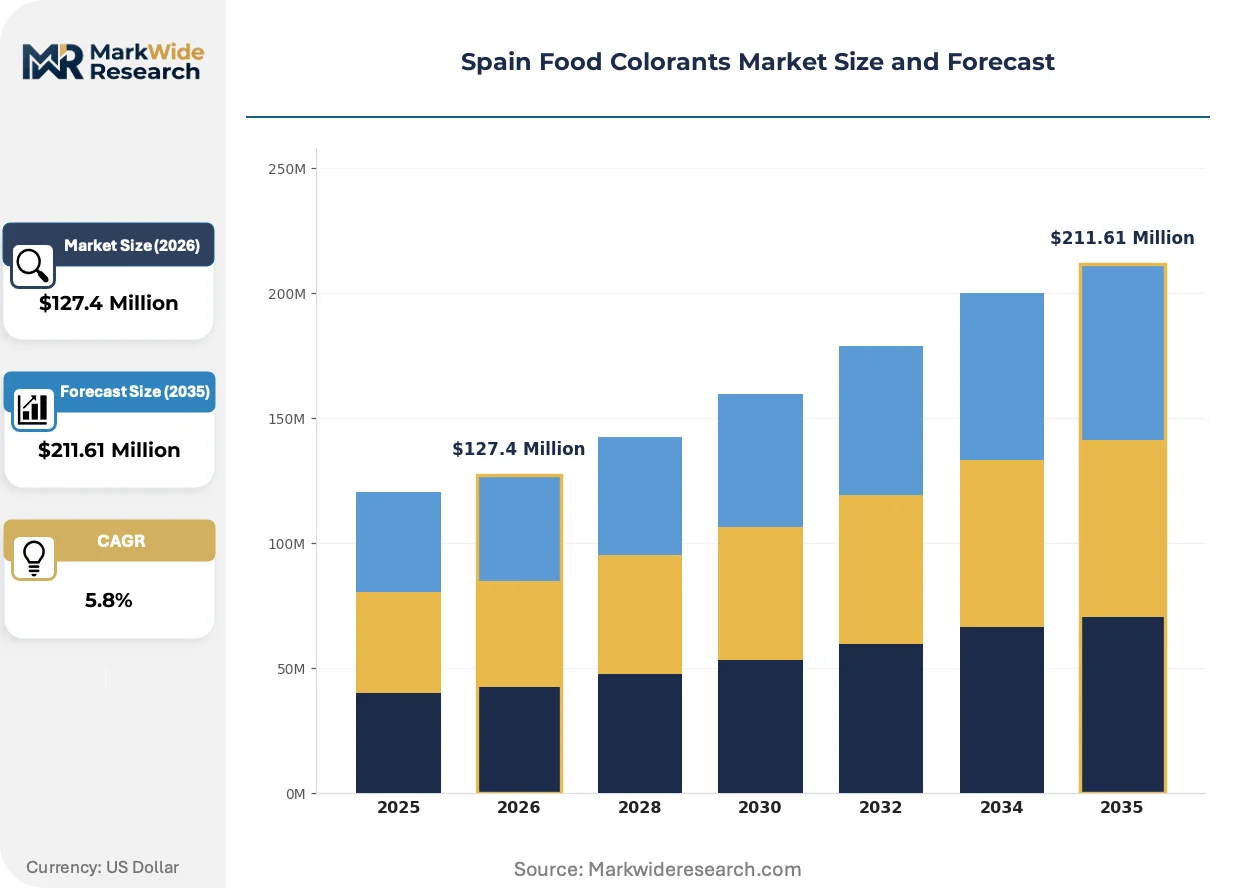
| Market Size in 2026 | $127.4 Million |
| Market Size in 2035 | $211.61 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Natural Dyes, Synthetic Dyes, Lakes, Caramel Application: Beverages, Bakery Products, Snacks, Dairy End User: Food Industry, Beverage Industry, Snack Manufacturers, Dairy Producers Packaging Type: Bottles, Bulk Packs, Sachets, Jars |
| Companies Covered | Koninklijke DSM N.V., BASF SE, Chr. Hansen Holding A/S, Sensient Technologies Corporation, Döhler GmbH, Givaudan, Archer Daniels Midland Company, Symrise AG, GNT International B.V., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Food Colorants Market Evolving Landscape
Fermentation-based pigment production, regulatory pressure on titanium dioxide, and procurement directness are restructuring how Spanish food processors source and apply colorants across beverage and bakery segments.
Precision fermentation is integrating microbially derived betalains and carotenoids into industrial-scale colorant supply. Spanish beverage manufacturers adopt these bio-identical pigments at accelerating rates. The technology is compressing reliance on agricultural crop cycles while standardizing batch-to-batch color consistency.
EFSA's ongoing titanium dioxide safety re-evaluation is forcing reformulation across Spanish confectionery and chewing gum sectors. Manufacturers face 12-18 month transition windows to replace E171 with calcium carbonate or starch-based alternatives. The bakery segment absorbs the highest compliance costs due to whitener-dependent product lines.
Spanish processors are shortening their supplier rosters, consolidating colorant procurement with ingredient-system providers bundling stabilizers and flavors. This disintermediation of standalone dye distributors concentrates volume with integrated suppliers capable of technical service support. Catalonia's food processing cluster exhibits the most pronounced consolidation behavior.
Spain Food Colorants Market Segmentation
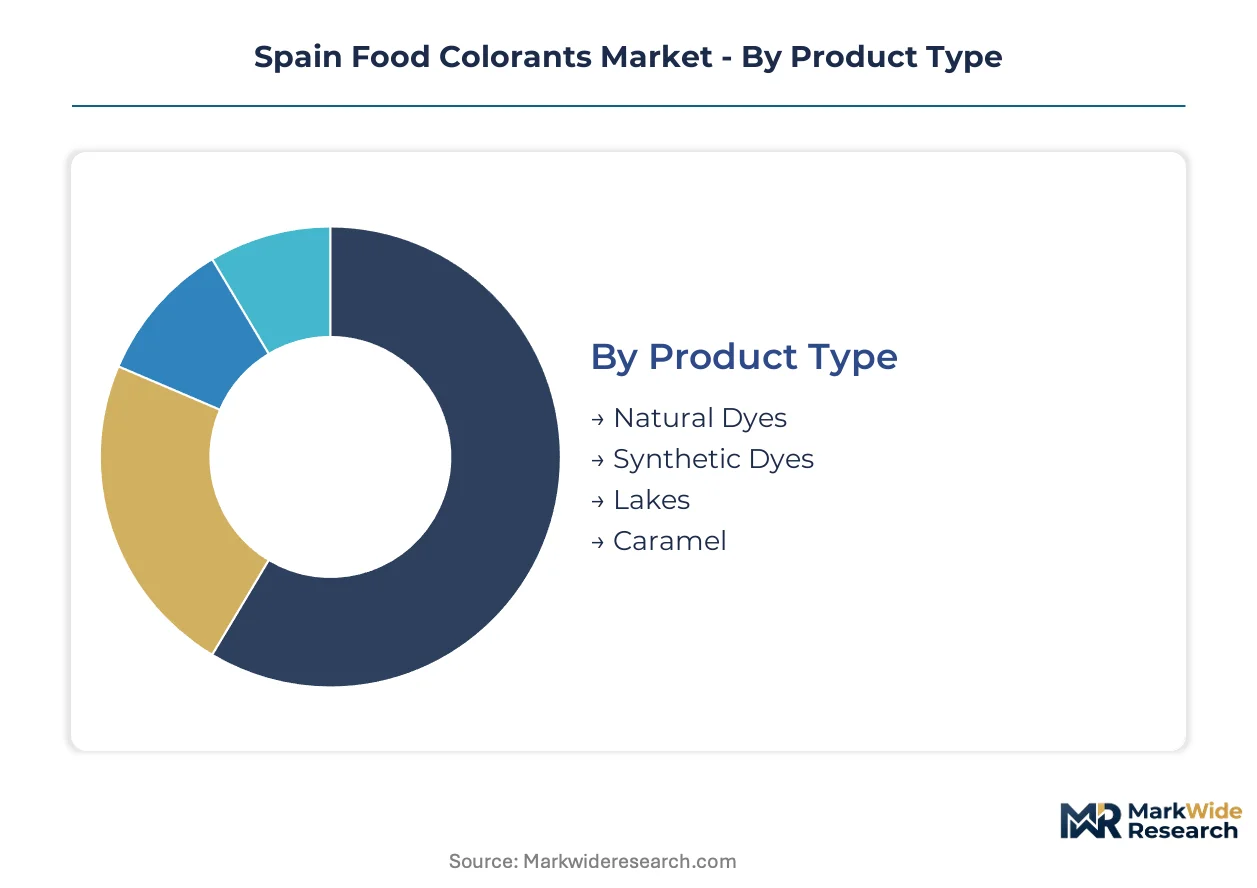
Food colorant procurement in Spain fragments across technical specifications, application requirements, and supply chain configurations. Understanding these segment boundaries reveals where formulation complexity drives premium pricing versus where commodity purchasing dominates.
Product Type:
Technical differentiation in pigment chemistry determines stability profiles, regulatory pathways, and manufacturing integration requirements across Spanish food processing.
- Natural Dyes:Plant and mineral-derived pigments including anthocyanins, carotenoids, and curcuminoids, typically requiring pH buffering and antioxidant protection during thermal processing. Catalonia's beverage manufacturers prioritize these for clean-label positioning as EFSA scrutiny intensifies on synthetic alternatives.
- Synthetic Dyes:Petroleum-derived azo compounds and triphenylmethane dyes engineered for extreme pH and temperature stability. Private-label snack manufacturers in Valencia retain volume demand here where cost-per-unit-colorant remains the dominant procurement metric.
- Lakes:Aluminum or calcium salt complexes of water-soluble dyes, creating oil-dispersible pigments for fat-based applications. Spanish confectionery producers leverage lake formulations for coating uniformity in chocolate and compound applications.
- Caramel:Heat-treated carbohydrates producing Class I through IV colorants with varying sulfur dioxide content and charge density. Madrid's brewing sector and Andalusian soft drink bottlers specify E150d for its negative charge stability in acidic beverages.
Natural Dyes leads on scale; Caramel leads on momentum.
Application:
End-use processing conditions dictate colorant selection criteria from thermal stability thresholds to regulatory exposure.
- Beverages:Liquid applications demanding light stability, acid compatibility, and no sedimentation across shelf life. Barcelona's functional drink startups are driving fermentation-derived pigment adoption faster than legacy categories.
- Bakery Products:Heat-processed goods requiring Maillard-stable pigments that survive oven temperatures exceeding 180°C. Reformulation pressure from titanium dioxide restrictions is forcing Spanish bakers toward calcium carbonate and starch-based alternatives.
- Snacks:Extruded and fried products where oil migration and surface adhesion determine visual consistency. Valencia's potato chip and corn snack manufacturers balance cost targets against EU labeling transparency requirements.
- Dairy:pH-neutral applications requiring dispersion stability in protein matrices without flocculation. Asturian cheese processors and Catalan yogurt manufacturers specify carotenoid blends for standardized yellow intensity.
Beverages leads on scale; Dairy leads on momentum.
End User:
Customer scale and technical capability create divergent procurement patterns from commodity spot buying to integrated ingredient system partnerships.
- Food Industry:Broad category encompassing ready meal, sauce, and processed meat manufacturers with varying technical sophistication. Mid-sized Spanish processors increasingly bundle colorant procurement with stabilization and flavor systems.
- Beverage Industry:High-volume liquid processors with dedicated QA labs and formulation chemists capable of managing natural pigment variability. This segment exhibits the shortest supplier rosters as technical service requirements concentrate spend.
- Snack Manufacturers:High-speed extrusion and frying operations prioritizing batch-to-batch consistency and supply security over innovation. Andalusian and Murcian production clusters dominate volume.
- Dairy Producers:Fermentation-experienced processors with existing microbial cultivation capabilities, creating adjacency opportunities for precision-fermentation pigment suppliers.
Food Industry leads on scale; Beverage Industry leads on momentum.
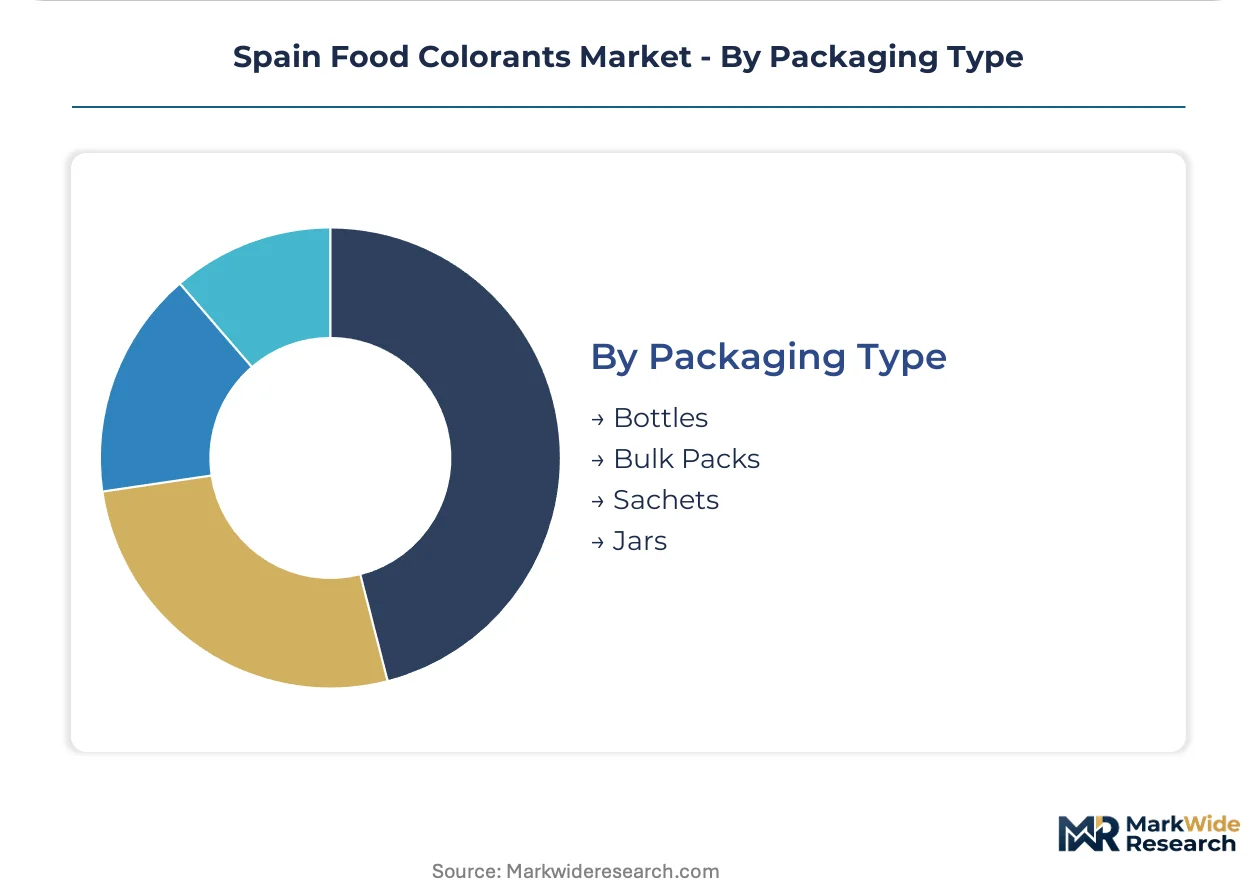
Packaging Type:
Logistics configuration and handling requirements segment colorant supply between industrial-scale bulk and precision-dosed retail formats.
- Bottles:Liquid colorant concentrates in polyethylene or glass containers for mid-volume processors with metered dosing equipment. Standard across Catalonia's mid-tier beverage co-packers.
- Bulk Packs:Intermediate bulk containers and drum shipments for high-volume manufacturers with dedicated storage and handling infrastructure. Madrid's industrial dairy and brewing operations specify this format exclusively.
- Sachets:Pre-measured single-use portions for small-batch processors, artisan producers, and food service applications. Galician and Basque craft food startups prefer this format for inventory flexibility.
- Jars:Wide-mouth containers for powdered pigments requiring scoop measurement, common in bakery and confectionery settings where precise gram-scale addition matters.
Bulk Packs leads on scale; Sachets leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Catalonia's food processing cluster around Barcelona anchors Spanish colorant demand as beverage manufacturers accelerate clean-label reformulation. Regional procurement patterns diverge sharply between fermentation-adopting coastal processors and cost-focused inland snack producers.
Madrid
Madrid's brewing sector and industrial dairy operations sustain bulk caramel colorant demand through dedicated storage infrastructure. Spain's AESAN enforces national labeling compliance from its capital base, monitoring cross-border ingredient shipments. The metropolitan area's craft beer startups are testing direct-to-brewery distribution models for natural pigments.
Catalonia
Barcelona's functional beverage startups drive the fastest adoption of fermentation-derived pigments in Europe. EFSA additive re-evaluations push Catalan manufacturers toward bio-identical alternatives ahead of regulatory deadlines. The region exhibits the most pronounced supplier roster consolidation, with technical service requirements concentrating spend among integrated ingredient-system providers.
Valencia
Valencia's orange processing waste streams offer untapped carotenoid feedstock for regional colorant production. EU Green Deal sustainability mandates reward processors adopting bio-based extraction methods. Private-label snack manufacturers in the region retain volume demand for synthetic dyes where cost-per-unit-colorant dominates procurement.
Andalusia
Andalusian soft drink bottlers specify E150d caramel for its negative charge stability in acidic beverages. REACH chemical registration requirements constrain imported synthetic dye formulations, tilting procurement toward EU-certified alternatives. The region's potato chip and corn snack production clusters prioritize batch-to-batch consistency over innovation.
Basque Country
Basque craft food startups prefer sachet-format colorants for inventory flexibility in small-batch operations. Spain's national sustainability mandates reward processors adopting bio-based colorants through streamlined permitting. Galician and Basque artisan producers are consolidating procurement with regional distributors capable of technical formulation support.
Spain Food Colorants Market Competitive Landscape
Portfolio diversification dominates the current landscape as suppliers bundle colorants with stabilizers and flavors to capture consolidated procurement. The vendor base splits between integrated ingredient-system providers and standalone pigment specialists. Three strategic archetypes emerge: fermentation-technology leaders, agricultural-extraction traditionalists, and synthetic-dye cost optimizers. M&A activity and geographic expansion through Dutch-Spanish distribution networks represent the dominant competitive vectors.
Within the fermentation-technology tier, Chr. Hansen Holding A/S and GNT International B.V. exemplify the shift toward microbial-derived pigments. Döhler GmbH anchors the integrated-systems archetype, bundling colorants with adjacent ingredient categories. These three companies occupy positions that reflect broader industry restructuring around clean-label compliance and supply chain proximity.
| Leading Market Players |
|---|
| Koninklijke DSM N.V. |
| BASF SE |
| Chr. Hansen Holding A/S |
| Sensient Technologies Corporation |
| Döhler GmbH |
| Givaudan |
| Archer Daniels Midland Company |
| Symrise AG |
| GNT International B.V. |
| Others |
Value Network & Pricing Analysis
Beetroot and spirulina commodity indices cascade through Spanish colorant supply chains, compressing margins for agricultural-extraction specialists while fermentation-derived alternatives achieve cost parity. Procurement officers in Catalonia's beverage cluster now segment supplier rosters by input-source stability, not merely unit economics.
Pricing Analysis
Input-cost pass-through from agricultural commodity swings dominates pricing dynamics for natural dye producers. Three-tier pricing structure across premium fermentation-derived, standard plant-extracted, and economy synthetic tiers reflects certification grade and volume scale differentials. Pricing pressure stems from EFSA re-evaluation timelines forcing premature reformulation investments. Private-label snack manufacturers in Valencia exhibit highest price sensitivity; Barcelona functional beverage startups absorb premiums for clean-label positioning.
Supply Chain Analysis
Direct-to-brewery channels handle craft beer demand in Madrid while integrated ingredient-system providers serve Catalonia's consolidated beverage cluster. Raw material dependencies rest on Chinese azo dye precursors, Indian spirulina cultivation, and Dutch fermentation infrastructure. Tariff exposure on Asian chemical imports creates vulnerability for synthetic-dependent processors. Distribution runs through regional distributors in Andalusia and direct technical-service relationships in Barcelona.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Spain's food colorant market offers margin expansion through fermentation technology scale-down and premium-tier capture in clean-label beverage applications. Precision-fermentation cost curves are flattening faster than agricultural extraction benchmarks.
For Market Incumbents: Extend technical service capabilities into formulation chemistry support to lock in Catalan beverage accounts facing EFSA-driven reformulation deadlines. Deepen backward integration into Valencia citrus waste-stream carotenoid extraction to secure regional feedstock advantages against Dutch and Danish fermentation competitors.
For New Entrants and Emerging Players: Basque craft food startups represent an underserved buyer archetype requiring sachet-format flexibility and regional distributor partnerships. Andalusian soft drink bottlers offer white-space opportunity for E150d caramel alternatives with improved sulfur dioxide profiles. Lead with direct technical consultation, not commodity spot pricing.
For Investors and Strategic Acquirers: Asymmetric upside sits with precision-fermentation pigment specialists possessing scalable microbial platforms and existing EU regulatory dossiers. Five-to-ten year viability hinges on bio-identical pigment adoption curves outpacing agricultural commodity volatility. Monitor EFSA authorization velocity for novel natural pigments as inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Fermentation Capacity Expansion | Chr. Hansen and GNT are scaling microbial pigment production to match synthetic dye unit economics. |
| Backward Integration into Citrus Extraction | Valencia orange waste-stream processing secures carotenoid feedstock independence from agricultural commodity markets. |
| Direct-to-Brewery Distribution | Madrid craft beer startups are bypassing ingredient distributors for captive supplier relationships. |
| EFSA Regulatory Dossier Investment | Novel natural pigment approvals require 18-24 month safety reviews, creating first-mover barriers. |
| Integrated Ingredient System Bundling | Döhler's colorant-flavor-stabilizer combinations are consolidating procurement in Catalonia's beverage cluster. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with formulation chemists at Catalan beverage manufacturers, procurement leads at Madrid brewing operations, technical directors at Valencia snack processors, and distribution channel partners across Andalusia with secondary validation from AESAN regulatory filings, EFSA safety dossier databases, EU customs trade records, and Spanish food industry association reports. Bottom-up volume estimates triangulated against top-down market sizing.
Segment-weighting approaches modeled natural versus synthetic dye splits, application-specific thermal stability requirements, and end-user procurement sophistication tiers across the projection horizon. CAGRs derived from historical trajectory analysis and forward-looking regulatory impact assessment incorporated fermentation technology cost curves and EFSA re-evaluation timelines as industry-specific inputs.
Inputs from EFSA safety dossier databases and Spanish customs records were available through the study window; gaps in proprietary fermentation yield data introduce uncertainty bands around bio-identical pigment penetration forecasts. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Food Bleaching Agents Market
Food Additives and Ingredients
Asia Food Emulsifiers Market
Food Additives and Ingredients
Food Protein Ingredient Market
Food Additives and Ingredients
Germany Anticaking Market
Food Additives and Ingredients
Calcium Inosinate Market
Food Additives and Ingredients
Cream Emulsifier Market
Food Additives and Ingredients
Gellan Gum Market
Food Additives and Ingredients
Locust Bean Gum Market
Food Additives and Ingredients
Japan Food Acidulants Market
Food Additives and Ingredients
Russia Food Emulsifiers Market
Food Additives and Ingredients
Annatto Food Colors Market
Food Additives and Ingredients
Natural Ferulic Acid Market
Food Additives and Ingredients
Germany Food Acidulants Market
Food Additives and Ingredients
Canada Food Additives Market
Food Additives and Ingredients
South America Food Stabilizers Market
Food Additives and Ingredients
Neohesperidine DC Market