
 Italy Food Acidulants Market | 2026-2036
Italy Food Acidulants Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Food Acidulants Market Foresight
The specialty ingredient distribution channel is narrowing as consolidation among Italian food chemical distributors reduces supplier access points. Tate & Lyle PLC leverages its European blending network to sustain direct relationships with mid-sized pasta sauce manufacturers. Corbion NV anchors its position through fermentation-derived lactic acid capacity positioned near northern Italian dairy clusters. Jungbunzlauer Suisse AG competes on citric acid purity grades that meet Italian bottlers' specifications for clear-label beverages.
Food acidulants comprise organic acids and their salts that lower pH, enhance flavor profiles, and preserve shelf stability in processed foods; citric acid dominates production through Aspergillus niger fermentation with titratable acidity typically ranging between 99.5% and 100.5% purity on an anhydrous basis. Lactic acid from the product type category leads volume consumption due to its extensive use in dairy applications and olive brining operations across southern Italy. Malic acid represents the fastest-expanding segment as Italian confectioners reformulate sour candies to replace synthetic acid combinations with clean-label alternatives.
Italy's Ministry of Health implements EU Regulation 1333/2008 on food additives while EFSA evaluates safety renewals for citric and malic acid authorizations that determine permitted use levels in infant foods and dietary supplements. FSSAI-aligned importers face parallel scrutiny when sourcing acidulants from Indian suppliers, creating dual compliance burdens for traders operating across Mediterranean trade lanes. Stakeholders must monitor pending EFSA re-evaluations of lactic acid in meat preparations and decide whether to advance buffer stock positions ahead of potential purity requirement tightening.
Market Dynamics
Acidulant procurement in Italy is tightening around fermentation-derived supply chains as beverage and dairy processors seek domestic purity certifications under EFSA renewal timelines. This structural compression favors suppliers with captive biorefinery capacity over traders dependent on Asian import flows.
Growth Catalysts
- EFSA Re-evaluation Cycles:Pending safety renewals for citric acid in infant foods are accelerating buffer stock builds among Emilia-Romagna sauce manufacturers ahead of potential purity requirement tightening.
- Clean-Label Confectionery:Italian candy producers are replacing synthetic acid blends with malic acid in sour formulations to meet retailer clean-label mandates.
- Northern Beverage Corridor:Carbonated and functional drink expansion across Lombardy and Veneto is pulling citric acid volumes through direct supplier relationships bypassing distributor consolidation.
Market Restraints
- Input Cost Volatility:Molasses and corn steep liquor prices for Aspergillus niger fermentation fluctuate with agricultural commodity cycles, squeezing margin predictability for domestic blenders.
- Supply Concentration Risk:Fermentation-derived lactic acid capacity clusters near northern Italian dairy zones, creating geographic vulnerability to regional logistics disruptions.
- Regulatory Friction:FSSAI-aligned importers face dual compliance burdens when sourcing from Indian suppliers, adding documentation overhead and customs clearance delays.
Strategic Opportunities
- Southern Olive Brining:Lactic acid penetration in Apulia and Calabria olive processing remains underdeveloped relative to northern dairy applications, offering volume expansion potential.
- Direct Channel Development:Mid-sized pasta sauce manufacturers are bypassing consolidating distributors to establish direct procurement relationships with European acidulant blenders.
- EU Green Deal Alignment:Fermentation-based production pathways qualify for sustainability-linked financing incentives, rewarding capital investment in biorefinery modernization.
Industry Challenges
- Specialized Fermentation Expertise:Industrial microbiology talent capable of optimizing Aspergillus niger strain performance for titratable acidity targets is scarce in Italian chemical engineering pipelines.
- Certification Timeline Compression:EU Regulation 1333/2008 compliance documentation for new acidulant grades requires 18-24 month EFSA evaluation windows, delaying product commercialization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Food Acidulants Market |
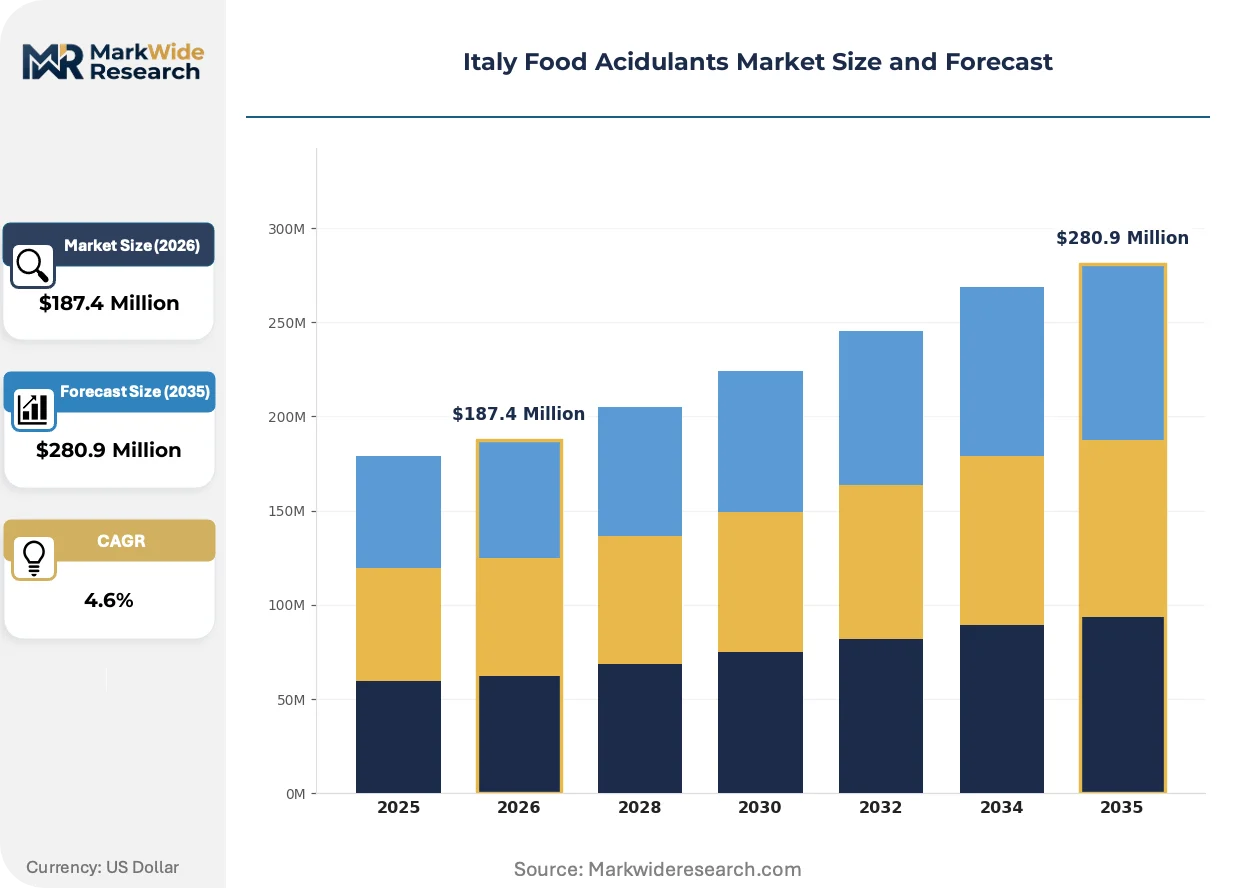
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $280.9 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Citric Acid, Lactic Acid, Malic Acid, Acetic Acid Application: Beverages, Dairy Products, Confectionery, Processed Foods Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Direct Sales End User: Food Manufacturers, Beverage Companies, Catering Services, Restaurants |
| Companies Covered | Tate & Lyle PLC, Archer Daniels Midland Company, Corbion NV, Vexim srl, Polynt SpA, Arkema, Prayon S A, Cargill, Jungbunzlauer Suisse AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Food Acidulants Market Shifts & Advancements
Italian food acidulant markets are pivoting toward fermentation transparency and regional supply security as processors confront distributor consolidation and regulatory renewal uncertainty. These shifts are reshaping both production technology choices and procurement relationship structures.
Biorefinery process control systems are hybridizing traditional batch fermentation with continuous monitoring analytics to stabilize citric acid titratable acidity within the 99.5-100.5% purity band. Northern Italian dairy clusters are adopting these integrated platforms to reduce batch rejection rates. This technology convergence is compressing quality variance premiums that previously separated commodity and food-grade acidulant pricing tiers.
EU Regulation 1333/2008 implementation through Italy's Ministry of Health is tightening additive purity documentation requirements for infant food and dietary supplement applications. Manufacturers must now submit expanded toxicological dossiers ahead of EFSA scheduled renewals. The dietary supplement segment is responding by advancing qualification timelines for alternative acidulant suppliers with existing EU-approved master files.
Acidulant buyers in the Emilia-Romagna processing corridor are consolidating purchase volumes through cooperative procurement consortia to offset distributor consolidation. These pooled arrangements are displacing fragmented spot-market purchasing that dominated pre-2020 procurement patterns. The pasta sauce manufacturing vertical exhibits the most visible consolidation of buying power, with mid-tier processors achieving volume thresholds previously accessible only to multinational beverage operators.
Italy Food Acidulants Market Segmentation
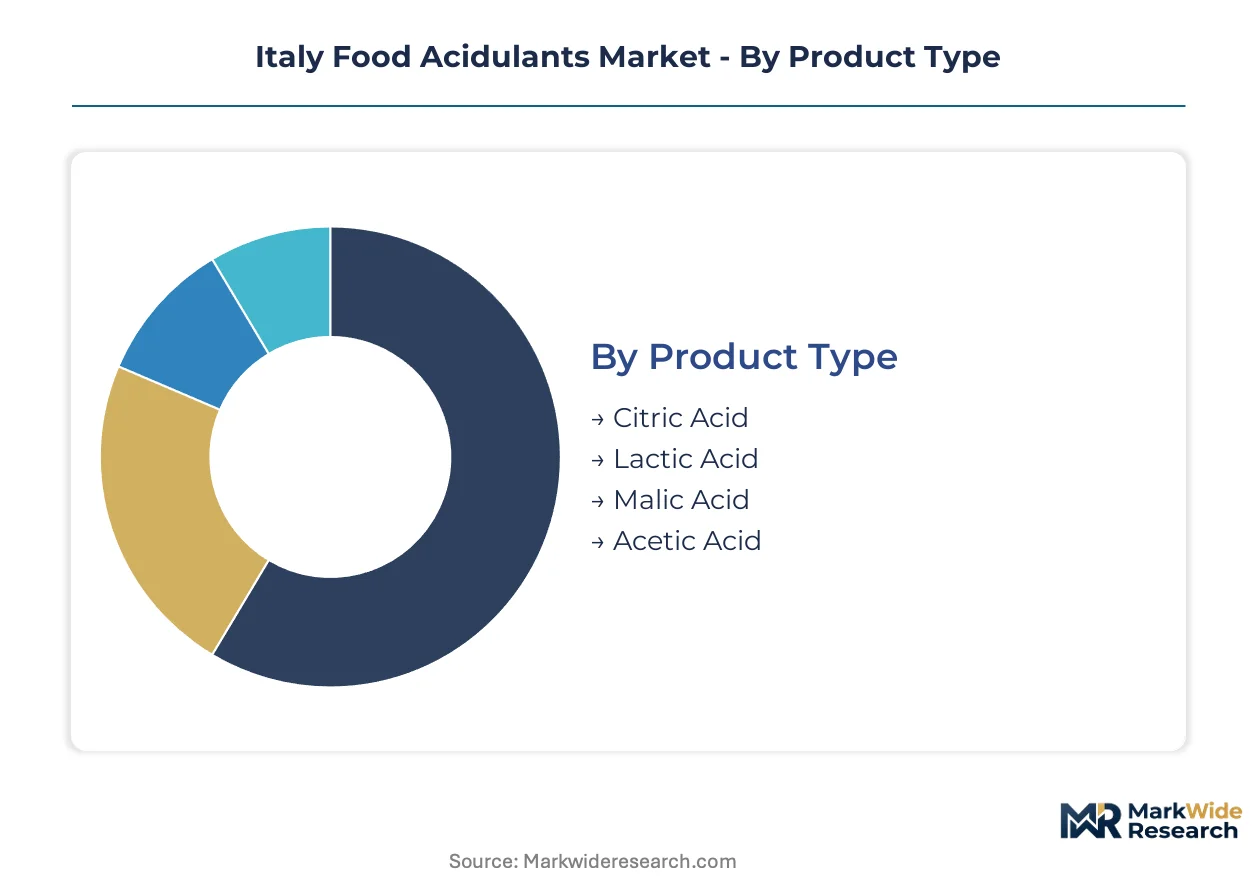
Acidulant procurement patterns in Italy diverge sharply across product chemistry and end-use specifications. Each segment carries distinct purity certifications, application constraints, and channel economics that reshape supplier relationships.
Product Type:
After-sales service intensity runs highest for fermentation-derived acids where batch consistency failures trigger immediate production line stoppages at dairy and beverage plants.
- Citric Acid:Aspergillus niger fermentation yields titratable acidity between 99.5% and 100.5% on an anhydrous basis. Northern Italian bottlers in Lombardy and Veneto specify this grade for clear-label carbonated drinks, with EFSA renewal timelines accelerating buffer stock builds among processors.
- Lactic Acid:Fermentation-derived capacity clusters near Emilia-Romagna dairy zones, serving pasta sauce manufacturers and olive brining operations across Apulia. Geographic concentration creates vulnerability to regional logistics disruptions.
- Malic Acid:Italian confectioners reformulate sour candies with this clean-label alternative, displacing synthetic acid blends under retailer mandates.
- Acetic Acid:Vinegar-sector applications in Modena and Reggio Emilia DOP production anchor steady demand.
By volume, lactic acid leads through dairy dominance. By growth pace, malic acid climbs fastest on clean-label confectionery conversion.
Application:
Cost tier separation distinguishes premium infant-food grades from commodity industrial applications, with certification overhead creating 40-60% price spreads.
- Beverages:Carbonated and functional drink expansion across northern Italy pulls citric acid through direct supplier relationships, bypassing consolidating distributors.
- Dairy Products:Lactic acid stabilizes pH in yogurt and fresh cheese production; Emilia-Romagna processors demand domestic purity certifications under EFSA timelines.
- Confectionery:Sour candy reformulation drives malic acid penetration as synthetic alternatives face clean-label exclusion.
- Processed Foods:Pasta sauce manufacturers consolidate purchase volumes through cooperative procurement consortia to offset distributor consolidation.
Beverages generate the largest absolute volumes. Confectionery posts the steepest expansion trajectory on regulatory-driven formulation shifts.
Distribution Channel:
Customer type fragmentation separates multinational beverage operators with direct blender contracts from mid-tier processors dependent on distributor networks.
- Direct Sales:Tate & Lyle PLC and Corbion NV sustain relationships with Emilia-Romagna pasta sauce manufacturers, bypassing consolidating intermediaries.
- Specialty Stores:Small-batch acidulant grades for artisanal food producers move through regional chemical distributors in Bologna and Milan.
- Supermarkets:Limited to consumer vinegar and culinary acid formats, not industrial procurement.
- Online Retail:Emerging for sample qualification and small-volume orders from startup food manufacturers.
Direct sales capture the highest-value transactions. Online retail is gaining share fastest among new market entrants.
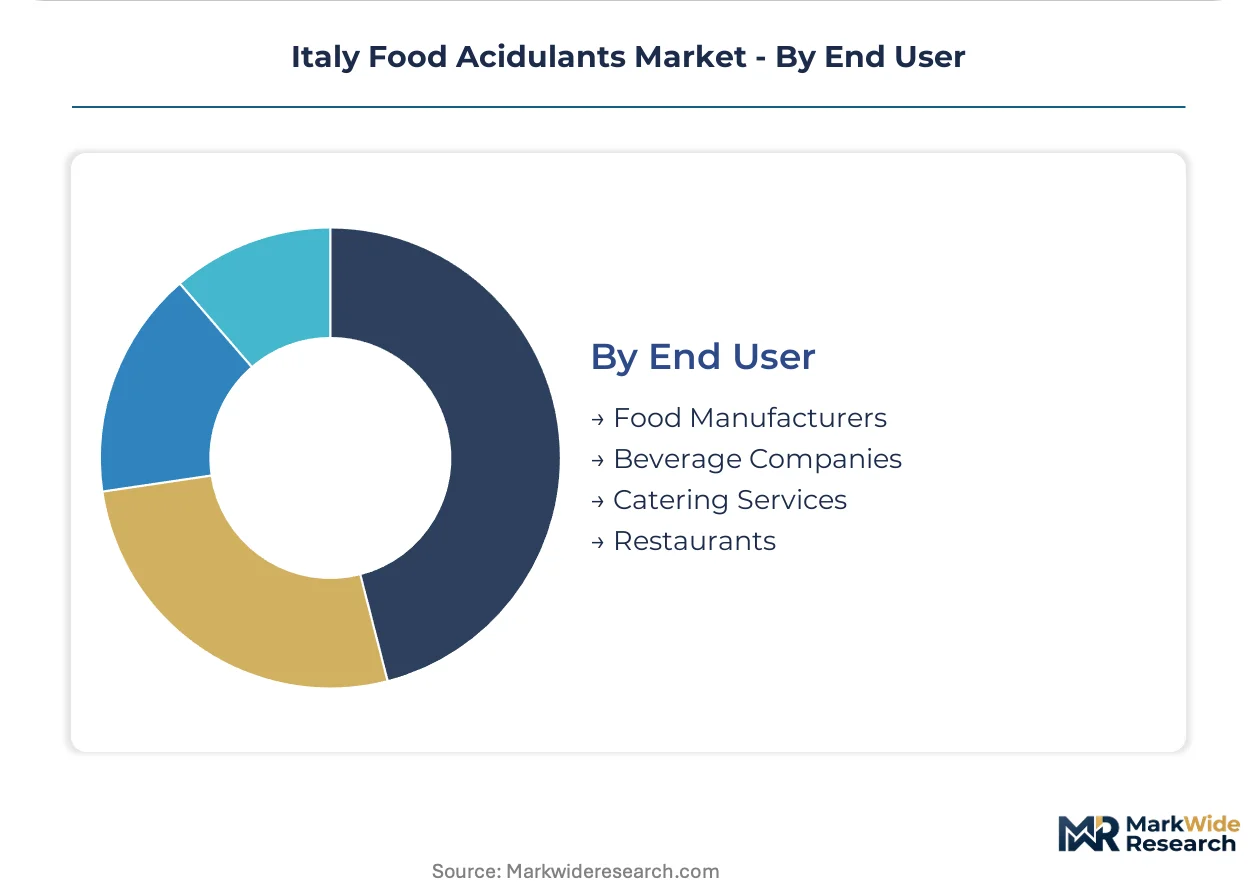
End User:
Supply concentration shapes procurement power, with food manufacturers achieving cooperative scale previously accessible only to multinational beverage operators.
- Food Manufacturers:Emilia-Romagna pasta sauce and ready-meal processors drive lactic acid volume through pooled procurement arrangements.
- Beverage Companies:Lombardy and Veneto carbonated drink producers specify citric acid purity grades for clear-label positioning.
- Catering Services:Bulk vinegar and acidulant sourcing for central kitchen operations in Rome and Milan hospitality chains.
- Restaurants:Minimal direct acidulant procurement; primarily indirect through prepared ingredient suppliers.
Food manufacturers dominate volume absorption. Beverage companies command the most stringent purity specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EFSA anchors regulatory oversight across Italian food acidulant procurement, with regional demand clustering in northern industrial corridors and southern agricultural processing zones. Sub-regional specialization drives divergent acidulant chemistry requirements.
Lombardy
Beverage manufacturers in Milan and Brescia expand citric acid procurement for carbonated and functional drink portfolios. Italy's Ministry of Health enforces EU Regulation 1333/2008 purity documentation for these applications. The Milan hinterland hosts direct supplier relationships that bypass consolidating distributor networks.
Emilia-Romagna
Pasta sauce and ready-meal manufacturers drive lactic acid volume through cooperative procurement consortia. EFSA renewal timelines for food additive authorizations accelerate buffer stock builds among processors. Bologna anchors this processing corridor with pooled purchasing arrangements displacing fragmented spot-market buying.
Veneto
Clear-label beverage producers specify high-purity citric acid grades for premium positioning. The national pharmaceutical regulator evaluates safety dossiers for acidulant use in dietary supplements. Verona and Padua bottling clusters pull fermentation-derived supply through direct blender contracts.
Apulia
Olive brining operations in Bari and Lecce present underdeveloped lactic acid penetration relative to northern dairy applications. EU Green Deal sustainability incentives reward fermentation-based production pathway investments. Regional processors remain dependent on distributor networks rather than direct supplier relationships.
Piedmont
Confectionery manufacturers in Turin reformulate sour candy portfolios with malic acid to meet retailer clean-label mandates. EFSA scheduled renewals for acidulant authorizations determine permitted use levels in these formulations. The Torino industrial zone exemplifies synthetic acid displacement trends.
Italy Food Acidulants Market Competitive Landscape
Fermentation specialists and diversified chemical conglomerates split the market into capability-driven competitive tiers. Supplier relationships concentrate around biorefinery proximity and purity certification depth rather than price alone. Three archetypes dominate: European fermentation houses with captive strain libraries, global agribusiness traders with commodity acid flows, and regional blenders serving artisanal food producers. Consolidation among Italian distributors is forcing acidulant suppliers to deepen direct engagement with mid-sized processors.
Among European fermentation specialists, Tate & Lyle PLC and Corbion NV exemplify the biorefinery-anchored archetype with proximity to northern Italian dairy clusters. Jungbunzlauer Suisse AG occupies a position within the purity-grade specialist tier. These three represent the competitive vanguard as distributor consolidation compresses channel access for commodity traders.
| Leading Market Players |
|---|
| Tate & Lyle PLC |
| Archer Daniels Midland Company |
| Corbion NV |
| Vexim srl |
| Polynt SpA |
| Arkema |
| Prayon S A |
| Cargill |
| Jungbunzlauer Suisse AG |
| Others |
Supply & Pricing Matrix
The Brenner Pass freight corridor into northern Italy carries molasses and corn steep liquor feedstocks for Aspergillus niger fermentation, with its cost volatility compressing margin buffers for domestic acidulant blenders while amplifying price differentiation between commodity traders and biorefinery-anchored suppliers serving Emilia-Romagna pasta sauce manufacturers.
Pricing Analysis
The customization-premium spread between configured-to-order fermentation batches and standard commodity grades runs 40-60% across Italian acidulant procurement. Three-tier pricing structure across pharmaceutical-grade, food-grade, and technical-grade certifications separates infant-food compliant citric acid from industrial vinegar applications. Pricing pressure stems from distributor consolidation squeezing intermediary margins in the specialty chemical channel. Mid-sized pasta sauce manufacturers exhibit highest price sensitivity through cooperative procurement consortia, while Lombardy beverage bottlers absorbing purity premiums show lowest sensitivity.
Supply Chain Analysis
EU dual-use export controls on fermentation biotechnology limit strain transfer documentation for Aspergillus niger optimization, constraining domestic capacity expansion. Supply concentrates in China, Thailand, and Belgium for citric acid fermentation capacity, while lactic acid production clusters in the Netherlands, Spain, and northern Italy itself. Raw material dependencies center on molasses feedstock, corn steep liquor nutrients, and calcium carbonate precipitation agents. Single-source vulnerability runs through the Brenner Pass logistics chokepoint for feedstock deliveries. Distribution runs through consolidating specialty chemical distributors in Bologna and Milan, with direct sales bypass gaining share among mid-tier processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity emerges as clean-label confectionery reformulation splinters demand across malic acid purity grades, creating niche entry points for fermentation specialists outside dominant dairy and beverage supply relationships.
For Market Incumbents: Entrench biorefinery proximity advantages through captive strain library investments near Emilia-Romagna dairy clusters, while deepening direct procurement relationships with pasta sauce manufacturers to offset distributor consolidation. Buffer stock positioning ahead of EFSA renewal timelines provides defensive leverage against purity requirement tightening. Certification investment in infant-food grade documentation creates switching costs for beverage bottlers. For New Entrants and Emerging Players: Southern olive brining operations in Apulia and Calabria represent the most penetrable entry point, given underdeveloped lactic acid penetration relative to northern dairy saturation. Mid-volume confectionery processors in Piedmont offer secondary white-space for malic acid qualification. A go-to-market angle anchored in EU Green Deal sustainability financing eligibility differentiates against commodity traders lacking fermentation transparency credentials. For Investors and Strategic Acquirers: European fermentation houses with existing EU-approved master files and captive biorefinery capacity near northern Italian demand clusters present the most defensible acquisition archetype. Long-term viability rests on regulatory renewal cycles tightening purity documentation requirements that favor incumbent dossier depth. The signal to watch is EFSA acceleration of citric acid safety re-evaluation timelines, which would compress qualification windows for alternative suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Supply | Molasses procurement control insulates margin volatility from agricultural commodity cycles. |
| EFSA Master File Investment | Pre-submitted toxicological dossiers accelerate infant-food grade commercialization timelines. |
| Direct Channel Development | Bypassing Bologna distributor networks captures margin previously lost to consolidating intermediaries. |
| Southern Regional Capacity Expansion | Apulia proximity reduces logistics vulnerability for olive brining lactic acid penetration. |
| Continuous Fermentation Technology Adoption | Hybrid batch-continuous systems stabilize titratable acidity within 99.5-100.5% purity bands. |
Research Methodology
A spread of perspectives from fermentation plant managers, pasta sauce procurement leads at Emilia-Romagna processors, specialty chemical distribution channel partners, and EFSA regulatory affairs specialists converged on the working assumptions underlying demand projections. Primary interview intelligence combined with secondary validation from EU Regulation 1333/2008 implementation documentation, Italian Ministry of Health additive purity filings, customs trade data on acidulant imports, and Cefic chemical industry reports. Bottom-up volume builds across product type and application segments triangulated against top-down market sizing from production capacity assessments.
Demand-supply-balance dynamics across the analysis window anchored the forecast framework, with segmentation modeling across citric acid, lactic acid, malic acid, and acetic acid chemistries; beverage, dairy, confectionery, and processed food applications; and direct sales versus distributor channel structures. CAGRs derived from regression analysis against historical volume trends and projected EFSA regulatory renewal impacts. Industry-specific forecast inputs included molasses price elasticity coefficients and cooperative procurement consortium formation rates among mid-tier processors.
Macroeconomic conditions sit as an overlay; deviation in eurozone agricultural commodity prices or Brenner Pass logistics capacity would shift the trajectory. Forecasts reflect documented assumptions on EFSA renewal timing and distributor consolidation pace. Material shifts in EU Green Deal sustainability incentive allocation or purity requirement tightening would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Flour Whiteners Market
Food Additives and Ingredients
Food Antifoaming Agents Market
Food Additives and Ingredients
Ellagic Acid Market
Food Additives and Ingredients
Egypt Food Emulsifiers Market
Food Additives and Ingredients
Aluminum-Free Natural Food Color Market
Food Additives and Ingredients
Carrageenan Market
Food Additives and Ingredients
Food Humectants Market
Food Additives and Ingredients
Carmine Alternatives Market
Food Additives and Ingredients
US Food Emulsifiers Market
Food Additives and Ingredients
Food Preservatives Market
Food Additives and Ingredients
Spain Food Colorants Market
Food Additives and Ingredients
Firming Agents Market
Food Additives and Ingredients
Beverage Clouding Agent Market
Food Additives and Ingredients
Africa Anti Caking Agent Market
Food Additives and Ingredients
Food Fungal Enzyme Market
Food Additives and Ingredients
Argentina Food Emulsifiers Market