
 Natural Food and Beverage Preservatives Market | 2026-2036
Natural Food and Beverage Preservatives Market Size, Share, and Industry Trends Forecast 2026-2036
Natural Food and Beverage Preservatives Market Foresight
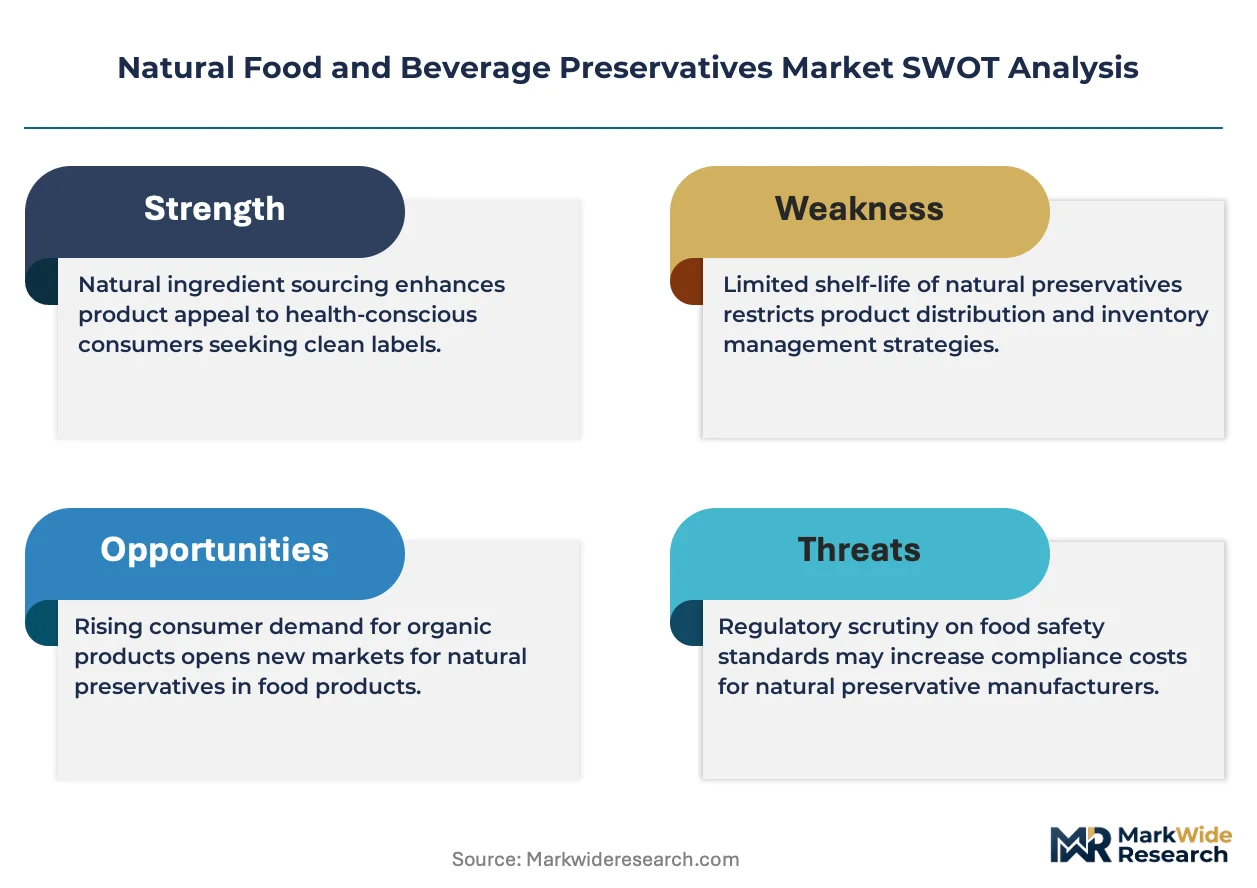
The EU Green Deal is shifting procurement standards across European food manufacturing, compelling reformulation away from synthetic additives. Cargill, Incorporated leverages its integrated supply chain from botanical sourcing to finished acidulants. Kerry Group Plc anchors its position through specialized clean-label preservation systems for meat and dairy applications. Chr. Hansen Holding A/S dominates microbial-derived protective cultures, competing on fermentation technology depth rather than commodity scale.
Natural food and beverage preservatives comprise biologically active compounds extracted from plants, microorganisms, or fermentation processes, typically characterized by minimum inhibitory concentrations against spoilage organisms and defined pH stability ranges. These substances function primarily to extend shelf life while meeting consumer expectations for recognizable ingredient declarations. Acidulants from plant sources command the largest volume share due to cost parity with synthetic alternatives and broad pH-adjustment utility across applications. Essential oils represent the fastest-expanding category, driven by their dual function as flavoring and antimicrobial agents in premium beverage lines. Fermented products concentrate margin pools where specialized strain IP creates supply scarcity.
EMA food contact guidelines, EFSA novel food assessments, and REACH chemical safety registrations collectively determine which natural preservation pathways achieve commercial scale in Europe. Formulators must navigate EFSA's evolving stance on botanical extract safety thresholds, which directly gates market access for new plant-derived entrants. Stakeholders should monitor how the EU AI Act's risk classification framework eventually extends to automated quality control in fermentation-based preservation manufacturing.
Market Dynamics
The EU Green Deal's ingredient transparency mandates are forcing European food manufacturers into accelerated reformulation cycles, compressing development timelines for clean-label preservation systems while elevating procurement scrutiny on botanical sourcing documentation.
Growth Catalysts
- REACH chemical safety registrations:ECHA's streamlined natural substance pathways reduce time-to-market for plant-derived acidulants versus novel synthetic approvals. Dairy processors leverage this regulatory efficiency to meet clean-label commitments.
- Fermentation technology depth:Specialized strain IP in protective cultures creates supply scarcity that commands premium positioning. Meat and dairy applications drive capacity expansion in microbial-derived preservation.
- Germany's bakery cluster:Concentrated demand from industrial bakers accelerates plant-derived acidulant uptake. Regional formulation expertise spreads adoption patterns across adjacent Central European markets.
Market Restraints
- Botanical raw material volatility:Citrus and rosemary extract supplies face climate-driven harvest fluctuations. Input cost swings compress margins for acidulant producers lacking captive agricultural assets.
- EFSA novel food assessment timelines:Botanical extract safety threshold evaluations create 18-36 month market access gates. New plant-derived entrants stall at pre-commercial stages awaiting positive opinions.
- Synthetic preservative cost parity:Benzoates and sorbates maintain 40-60% price advantages in mass-market applications. Budget-conscious foodservice operators resist natural alternative premiums.
Strategic Opportunities
- EU AI Act risk classification:Automated quality control in fermentation manufacturing will require compliance infrastructure. Early movers capture vendor relationships with bioprocess automation specialists.
- Premium beverage lines:Essential oils' dual function as flavoring and antimicrobial agents opens formulation white space. Botanical water and functional drink categories seek differentiated preservation stories.
- EMA food contact guidelines:Evolving migration limits for packaging-adjacent preservatives create specification gaps. Active packaging integration with natural antimicrobials addresses unmet technical needs.
Industry Challenges
- Fermentation scale-up expertise:Industrial microbiology talent scarcity constrains protective culture production expansion. Specialized bioprocess engineers command compensation premiums that inflate facility staffing costs.
- Cross-border botanical documentation:EFSA's evolving stance on extract safety thresholds demands country-of-origin traceability systems. Suppliers struggle to harmonize documentation across fragmented agricultural sourcing networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Natural Food and Beverage Preservatives Market |
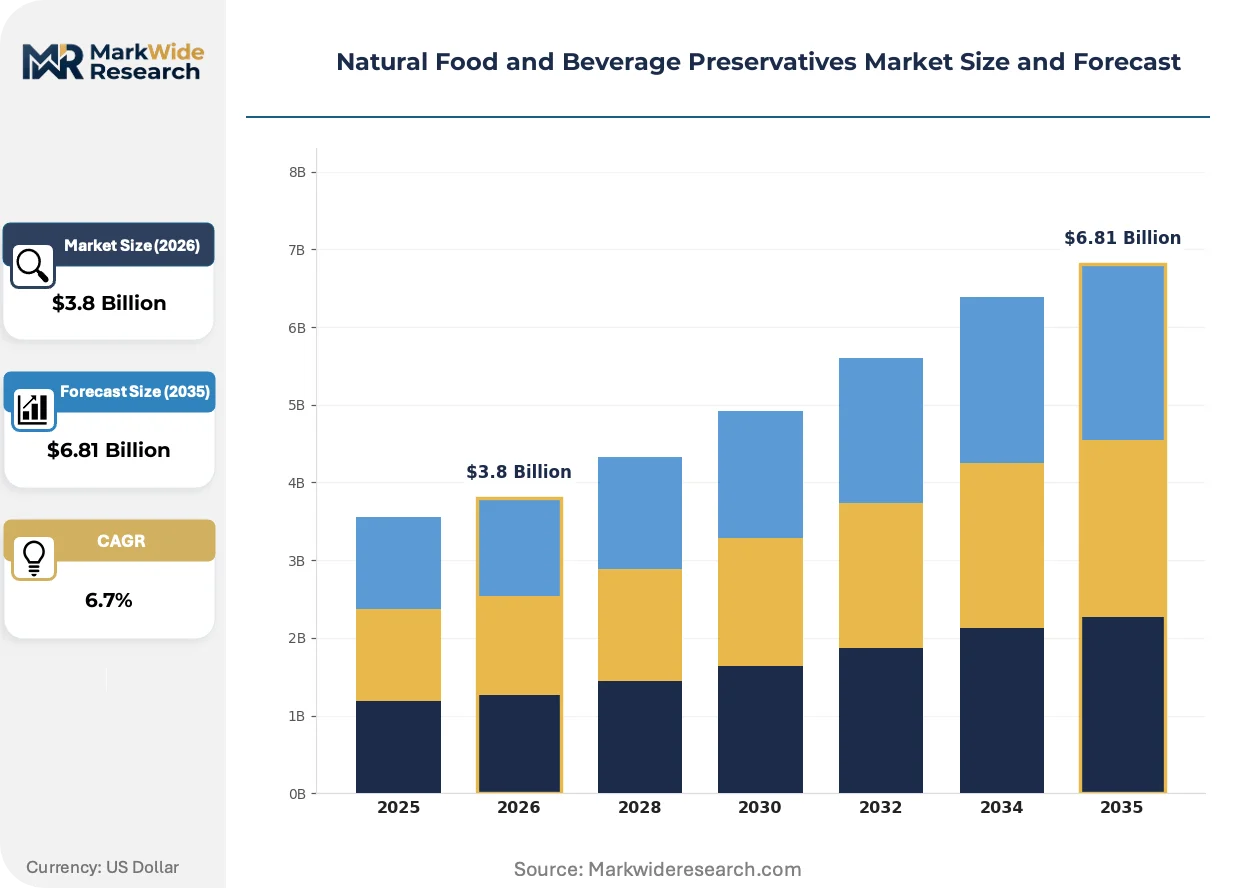
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Antioxidants, Acidulants, Flavoring Agents, Essential Oils Application: Meat Processing, Dairy Products, Bakery, Beverages Source: Plants, Microorganisms, Animal Sources, Fermented Products End User: Food Manufacturers, Beverage Producers, Retailers, Food Service Providers |
| Companies Covered | Cargill, Incorporated, Kerry Group Plc, Koninklijke DSM N.V., Tate & Lyle PLC, Kemin Industries, Inc., Corbion N.V., Archer Daniels Midland Company, Chr. Hansen Holding A/S, Handary S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Natural Food and Beverage Preservatives Market Shifts & Advancements
Clean-label preservation is fragmenting into specialized technology tracks, with fermentation-based systems diverging from plant extraction methods and each attracting distinct investor and buyer profiles.
Encapsulation technology for essential oils is modularizing delivery formats across beverage applications. Premium sparkling water and botanical soda manufacturers adopt lipid-based shell systems to stabilize antimicrobial activity through pasteurization. This modularizing architecture enables flavor houses to license preservation modules separately from complete flavor systems.
EFSA's novel food assessment framework is tightening botanical extract safety documentation requirements. Manufacturers must now submit comprehensive toxicological dossiers for concentrated plant acids previously grandfathered under traditional use exemptions. German and French ingredient suppliers accelerate investment in in-vitro safety screening capabilities to preempt regulatory objections.
Direct supplier relationships are displacing distributor intermediaries in acidulant procurement. Large dairy and meat processors negotiate volume commitments directly with botanical extract producers to secure batch consistency and origin traceability. This disintermediation concentrates most visibly in the Netherlands and Denmark, where cooperative purchasing structures enable collective bargaining power against fragmented agricultural supply bases.
Natural Food and Beverage Preservatives Market Segmentation
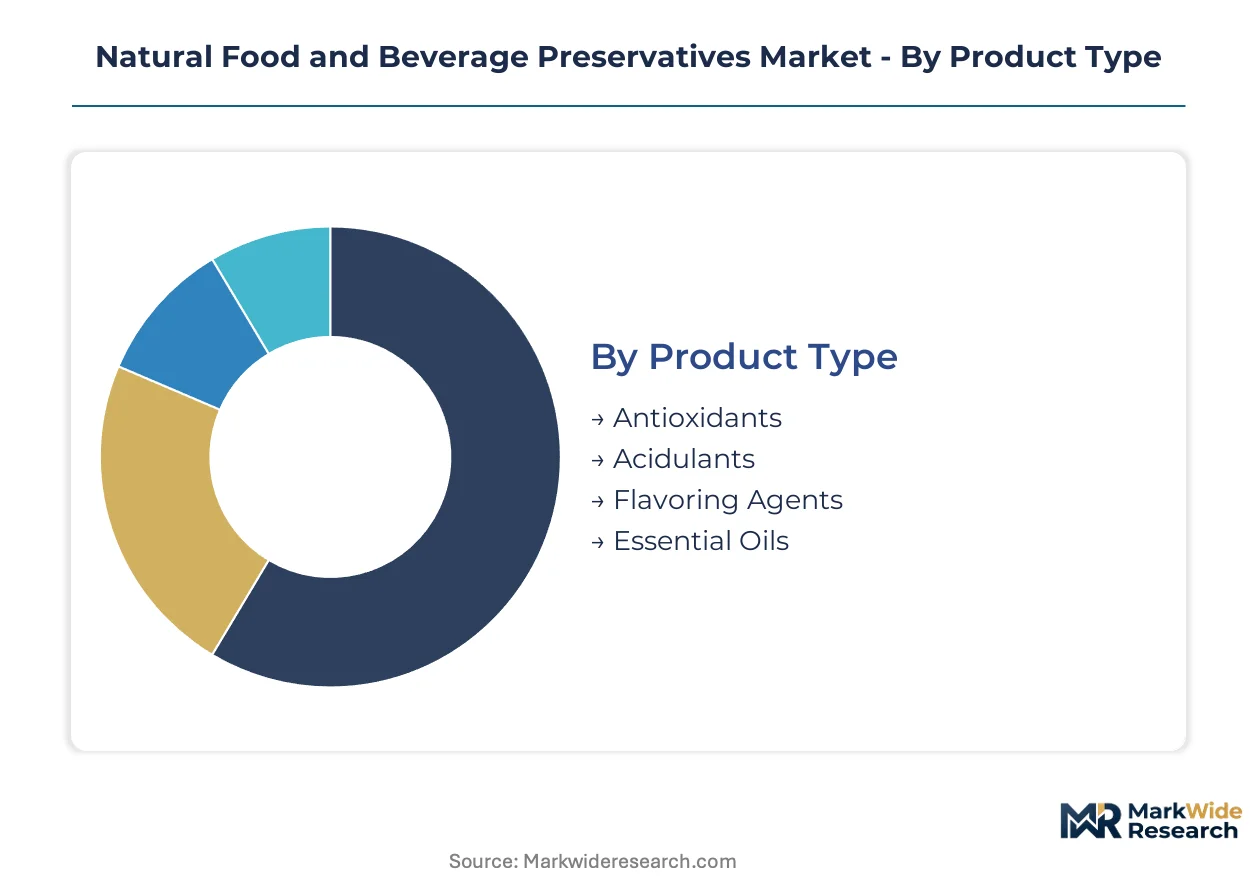
Preservation technology selection hinges on pH stability requirements and clean-label positioning. Formulators balance antimicrobial efficacy against consumer ingredient recognition thresholds. Each segment category reflects distinct procurement logic and margin architecture.
Product Type:
Volume leadership concentrates in commodity acidulants, while essential oils command the steepest price premiums per active unit.
- Acidulants:Citric, malic, and tartaric acids derived from citrus and sugar fermentation dominate tonnage. Dairy processors in Germany and the Netherlands drive procurement volumes for pH-adjustment applications where cost parity with synthetic alternatives matters.
- Essential Oils:Thyme, oregano, and rosemary extracts deliver dual antimicrobial and aromatic functionality. Premium beverage lines in France and Italy absorb supply for botanical water and functional drink categories seeking differentiated preservation positioning.
- Antioxidants:Tocopherols and ascorbic acid variants extend lipid shelf life in meat and bakery applications.
- Flavoring Agents:Botanical extracts with secondary preservation properties serve clean-label reformulation needs.
Mature deployment sits with Acidulants. Newer deployment is concentrated in Essential Oils.
Application:
Meat and dairy applications generate the highest strain-IP premiums, while bakery represents the most price-sensitive procurement segment.
- Dairy Products:Yogurt, cheese, and plant-based alternatives require protective cultures with precise fermentation kinetics. Scandinavian cooperatives anchor demand for Chr. Hansen's microbial-derived systems where specialized strain documentation satisfies EFSA traceability mandates.
- Meat Processing:Fermented antimicrobials replace nitrite curing in clean-label deli and sausage categories. Spanish and Italian cured meat producers drive uptake of celery-derived nitrate alternatives despite 30-50% cost premiums over conventional curing salts.
- Bakery:Plant-derived acidulants combat mold in sliced bread and ambient pastries. Germany's industrial baker cluster spreads adoption patterns through formulation expertise transfer to Austria and Poland.
- Beverages:Essential oil encapsulation stabilizes antimicrobial activity through pasteurization in premium carbonated and still water segments.
Established preservation protocols dominate Meat Processing. Emerging reformulation investment flows into Dairy Products.
Source:
Plant extraction commands volume scale, while fermentation technology creates the deepest margin moats through proprietary strain libraries.
- Plants:Citrus, rosemary, and green tea extracts supply acidulants and antioxidants at industrial scale. Climate-driven harvest volatility in Spain and Italy creates input cost swings that compress margins for non-integrated extractors lacking captive agricultural assets.
- Fermented Products:Protective cultures and bacteriocins from controlled fermentation deliver targeted antimicrobial spectra. Danish and Dutch biotech facilities concentrate specialized bioprocess engineering talent that constrains competitor replication.
- Microorganisms:Live and inactivated bacterial preparations function in dairy and meat matrices.
- Animal Sources:Lysozyme from egg white and other protein-derived antimicrobials serve niche applications.
Commercial maturity rests with Plants. Technology investment and capacity expansion cluster in Fermented Products.
End User:
Direct manufacturer relationships displace distributor channels where batch consistency and origin documentation carry regulatory weight.
- Food Manufacturers:Large dairy and meat processors negotiate volume commitments directly with botanical extract producers. Netherlands-based cooperatives leverage collective purchasing structures against fragmented Mediterranean agricultural supply bases.
- Beverage Producers:Sparkling water and botanical soda manufacturers adopt modular encapsulation systems from flavor houses. Premium positioning demands antimicrobial stories that support clean-label ingredient declarations.
- Food Service Providers:Industrial kitchens and catering operations seek cost-competitive natural alternatives for prepared meal preservation.
- Retailers:Private-label clean-label commitments drive specification pressure on contract manufacturers.
Procurement sophistication concentrates in Food Manufacturers. Emerging specification pressure originates from Beverage Producers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Düsseldorf's industrial corridor anchors European natural preservative procurement, with concentrated acidulant demand from dairy cooperatives and meat processors driving formulation expertise clusters across the Rhine-Ruhr region.
Germany
Industrial bakers in Lower Saxony and Bavaria drive plant-derived acidulant volumes for sliced bread applications. The EU Green Deal's ingredient transparency mandates compress reformulation timelines for clean-label commitments. The Rhine-Ruhr corridor concentrates procurement sophistication, with dairy cooperatives negotiating direct supply relationships bypassing traditional distribution channels.
Netherlands
Fermented protective culture demand concentrates around Wageningen's food science cluster and Rotterdam's port logistics. REACH chemical safety registrations streamline natural substance pathways versus synthetic alternatives. Cooperative purchasing structures in the Randstad enable collective bargaining power against fragmented Mediterranean botanical supply bases.
France
Premium beverage manufacturers in Île-de-France absorb essential oil supplies for botanical water and functional drink positioning. EFSA novel food assessment timelines create 18-36 month gates for new plant-derived entrants. The Provence-Alpes-Côte d'Azur region supplies rosemary and thyme extracts, though climate-driven harvest volatility compresses margins for non-integrated processors.
Italy
Cured meat producers in Emilia-Romagna drive uptake of celery-derived nitrate alternatives despite cost premiums over conventional curing salts. EMA food contact guidelines shape migration limit specifications for packaging-adjacent preservatives. The Po Valley agricultural belt anchors citrus extract sourcing, though input cost swings challenge acidulant producers lacking captive assets.
Denmark
Scandinavian dairy cooperatives anchor demand for microbial-derived protective cultures with specialized strain documentation satisfying EFSA traceability mandates. Fermentation technology depth creates supply scarcity commanding premium positioning. Copenhagen's biotech corridor concentrates specialized bioprocess engineering talent that constrains competitor replication.
Natural Food and Beverage Preservatives Market Competitive Landscape
The competitive structure tilts toward integrated supply chain operators with captive agricultural assets and fermentation technology specialists with proprietary strain libraries. Tier-one positions concentrate among diversified ingredient conglomerates with backward integration into botanical sourcing, while mid-tier slots fragment across regional extractors and niche fermentation houses. Strategic moves center on direct procurement relationships displacing distributor intermediaries, and capacity expansion in protective culture manufacturing constrained by bioprocess engineering scarcity.
Within the integrated supply chain tier, Cargill, Incorporated exemplifies archetype positioning through its botanical sourcing-to-acidulant production span. Kerry Group Plc and Chr. Hansen Holding A/S occupy differentiated specialist positions, with the former representing clean-label preservation system integration and the latter anchoring microbial-derived protective culture technology depth. These three entities collectively illustrate the competitive divergence between commodity-scale acidulant operations and fermentation-based premium positioning.
| Leading Market Players |
|---|
| Cargill, Incorporated |
| Kerry Group Plc |
| Koninklijke DSM N.V. |
| Tate & Lyle PLC |
| Kemin Industries, Inc. |
| Corbion N.V. |
| Archer Daniels Midland Company |
| Chr. Hansen Holding A/S |
| Handary S.A. |
| Others |
Supply & Pricing Matrix
Captive agricultural sourcing anchors supply positions for leading acidulant producers while simultaneously underwriting pricing power through batch consistency guarantees that command premium positioning in EFSA-regulated procurement channels.
Pricing Analysis
Value-based pricing anchored to shelf-life extension outcomes separates fermentation-derived protective cultures from commodity acidulants. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation and specialized strain documentation depth. Cost compression in mass-market acidulants is intensifying because synthetic benzoates and sorbates maintain substantial cost advantages. Budget-conscious foodservice operators exhibit highest price sensitivity, while Scandinavian dairy cooperatives demonstrate lowest sensitivity due to traceability mandate compliance requirements.
Supply Chain Analysis
EU Green Deal domestic-content mandates are reshaping sourcing patterns toward verified European botanical origins with comprehensive documentation trails. Supply concentration centers on Spain and Italy for citrus and rosemary extracts, Denmark and the Netherlands for fermentation-derived protective cultures, and Germany for industrial acidulant processing. Raw material flows draw from Mediterranean agricultural belts, Wageningen-area biotech facilities, and Rhine-Ruhr chemical processing corridors. Single-source vulnerability runs through climate-exposed harvest regions where drought impacts create input volatility. Distribution runs through direct manufacturer relationships displacing traditional distributor channels in regulated dairy and meat segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure from EFSA novel food assessment timelines and bioprocess engineering talent scarcity will force weaker regional extractors and undercapitalized fermentation houses toward exit or acquisition.
For Market Incumbents: Anticipate regulatory documentation demands by investing in in-vitro safety screening capabilities and captive agricultural assets before EFSA tightens botanical extract safety thresholds. Defensive positioning requires securing specialized bioprocess engineering talent pools in Copenhagen and Wageningen corridors while building direct procurement relationships with German dairy cooperatives to lock in volume commitments against emerging competitors. For New Entrants and Emerging Players: Premium beverage producers seeking differentiated antimicrobial stories represent the most penetrable buyer archetype currently underserved by incumbent flavor house offerings. White-space concentration appears in essential oil encapsulation systems for botanical water categories and active packaging integration with natural antimicrobials. Go-to-market positioning should emphasize modular preservation licensing separate from complete flavor systems. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by diversified ingredient conglomerates seeking fermentation technology depth and proprietary strain libraries. Long-term viability favors targets with demonstrated EFSA novel food approvals and established direct relationships with Netherlands-based cooperative purchasing structures. The signal to watch is accelerated direct supplier relationship formation bypassing distributor intermediaries, indicating consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Agricultural Assets | Mediterranean citrus and rosemary sourcing secures batch consistency against climate-driven harvest volatility. |
| Fermentation Capacity Expansion | Wageningen and Copenhagen biotech corridor investments capture scarce specialized bioprocess engineering talent. |
| Direct Procurement Relationship Formation | German dairy cooperative volume commitments displace distributor intermediaries in EFSA-regulated channels. |
| In-Vitro Safety Screening Capability Investment | Preemptive toxicological dossier preparation accelerates EFSA novel food assessment pathway navigation. |
| Essential Oil Encapsulation Technology Licensing | Modular preservation modules enable separate licensing from complete flavor systems to beverage manufacturers. |
Research Methodology
Independent corroboration across EFSA novel food assessment databases, REACH registration filings, and EU Green Deal implementation directives underwrites the qualitative findings on regulatory pathway efficiency. Primary interviews with fermentation technology directors, dairy procurement leads, botanical extract plant managers, and flavor house R&D heads combined with secondary validation from ECHA substance registrations, customs trade data, and cooperative purchasing disclosure records. Bottom-up volume triangulation against top-down regulatory constraint modeling ensures analytical consistency.
Comparable-period anchoring to historical EFSA assessment timeline patterns and REACH registration throughput rates calibrated the forecast framework across the projection horizon. Segmentation dimensions modeled include preservation technology type, application matrix, source origin, and end-user procurement sophistication tier. CAGRs were derived from demand elasticity analysis against synthetic preservative price differentials and clean-label commitment acceleration curves. Industry-specific inputs incorporated climate-driven harvest volatility patterns and bioprocess engineering labor market tightness indicators.
Revisions become necessary when EFSA substantially alters botanical extract safety threshold methodologies, when EU AI Act implementation disrupts fermentation quality control automation compliance, or when Mediterranean climate patterns shift harvest reliability assumptions. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Salt Substitutes Market
Food Additives and Ingredients
Chymosine Market
Food Additives and Ingredients
Argentina Sodium Reduction Ingredient Market
Food Additives and Ingredients
Gellan Gum Market
Food Additives and Ingredients
Bread Emulsifier Market
Food Additives and Ingredients
Biscuit Shortening Flakes Market
Food Additives and Ingredients
Xanthan Gum Market
Food Additives and Ingredients
South America Food Emulsifiers Market
Food Additives and Ingredients
North America Food Preservatives Market
Food Additives and Ingredients
Asia-Pacific Food Additives Market
Food Additives and Ingredients
South America Food Colorants Market
Food Additives and Ingredients
Emulsifiers Market
Food Additives and Ingredients
Fat-Replacing Starch Market
Food Additives and Ingredients
Food Grade Dipotassium Phosphate Market
Food Additives and Ingredients
Canada Food Acidulants Market
Food Additives and Ingredients
Africa Food Enzymes Market