
 North America Fat Replacers Market | 2026-2036
North America Fat Replacers Market Size, Share, and Industry Trends Forecast 2026-2036
North America Fat Replacers Market Analytics
The United States is rewriting competitive dynamics in fat replacer manufacturing as domestic starch and hydrocolloid capacity expands across Iowa and Illinois processing corridors. Cargill Incorporated leverages its corn-derived ingredient infrastructure to anchor supply for carbohydrate-based fat mimetics. Ingredion Incorporated competes through waxy maize and tapioca specialization, while CP Kelco U.S., Inc. dominates pectin and gellan gum applications with its San Diego-based fermentation expertise.
North America fat replacers encompass ingredient systems engineered to replicate the mouthfeel, lubricity, and flavor-release properties of conventional fats while delivering substantially reduced caloric density, typically through modified starches, protein microparticulates, or cellulosic fibers with particle sizes below 10 microns. These formulations serve commercial food manufacturers seeking to maintain sensory parity in reduced-fat products without compromising shelf stability or process tolerance. Carbohydrate-based systems occupy the largest volume position given their cost efficiency and clean-label alignment, while protein-based alternatives command premium positioning in dairy applications where emulsion stability proves critical. Powder delivery modes sustain dominant share across industrial bakeries, though liquid emulsified formats are gaining traction in sauce and dressing segments requiring seamless pumpability.
The FDA governs fat replacer safety through GRAS self-affirmation pathways and updated Nutrition Facts panel requirements that amplify manufacturer reformulation incentives, while Health Canada mandates compositional standards under the Food and Drug Regulations that directly influence permitted fat reduction claims. USDA dietary guidelines and the FDA's voluntary sodium and saturated fat reduction targets further shape product development priorities across the region. Stakeholders must monitor evolving clean-label enforcement thresholds and state-level front-of-package labeling initiatives that could recalibrate formulation investments faster than federal timelines anticipate.
Market Dynamics
The FDA's updated Nutrition Facts panel mandates and Health Canada's front-of-package labeling regulations are forcing simultaneous reformulation across dairy, bakery, and sauce categories, compressing development timelines while expanding approved ingredient lists.
Growth Catalysts
- Carbohydrate-Based Systems:Modified starches and maltodextrins from Midwest corn processing corridors deliver cost-efficient clean-label solutions for industrial bakeries seeking saturated fat reduction without sensory compromise.
- Health Canada's Food and Drug Regulations:Compositional standards for fat reduction claims create compliant formulation pathways that accelerate manufacturer adoption of pectin and cellulosic fiber systems.
- Protein Microparticulates:Dairy processors leverage whey and micellar casein technologies to maintain emulsion stability in reduced-fat cheese and yogurt applications where mouthfeel parity proves critical.
Market Restraints
- Input Cost Volatility:Corn and tapioca starch prices fluctuate with Midwest agricultural yields and Brazilian export dynamics, squeezing margin structures for carbohydrate-based fat mimetics.
- Supply Concentration Risk:Fermentation-derived hydrocolloids depend on limited San Diego-area bioprocessing capacity, creating single-point vulnerability for pectin and gellan gum sourcing.
- Clean-Label Enforcement Thresholds:State-level front-of-package initiatives in California and New York impose stricter disclosure requirements than federal timelines, fragmenting compliance investments.
Strategic Opportunities
- Underpenetrated Dressing and Sauce Segments:Liquid emulsified fat replacer formats address pumpability requirements in Midwest condiment manufacturing clusters currently reliant on full-fat bases.
- USDA Dietary Guidelines:Voluntary saturated fat reduction targets create procurement pull from institutional foodservice operators seeking reformulated products for school and hospital nutrition programs.
- Cellulosic-Protein Convergence:Microcrystalline cellulose combined with pea protein isolates enables next-generation texture systems for plant-based dairy alternatives in California's alternative protein corridor.
Industry Challenges
- Particle Engineering Expertise Gap:Formulation chemists capable of optimizing sub-10 micron particle size distributions for lipid-mimetic mouthfeel remain scarce across US food science programs.
- Legacy Equipment Retrofit Costs:Industrial bakeries must reconfigure extrusion and sheeting lines to handle hydrocolloid hydration profiles that differ from conventional fat incorporation protocols.
- GRAS Self-Affirmation Documentation:Novel protein-based fat replacers require extensive safety dossiers for FDA notification, extending commercialization timelines beyond typical ingredient development cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Fat Replacers Market |
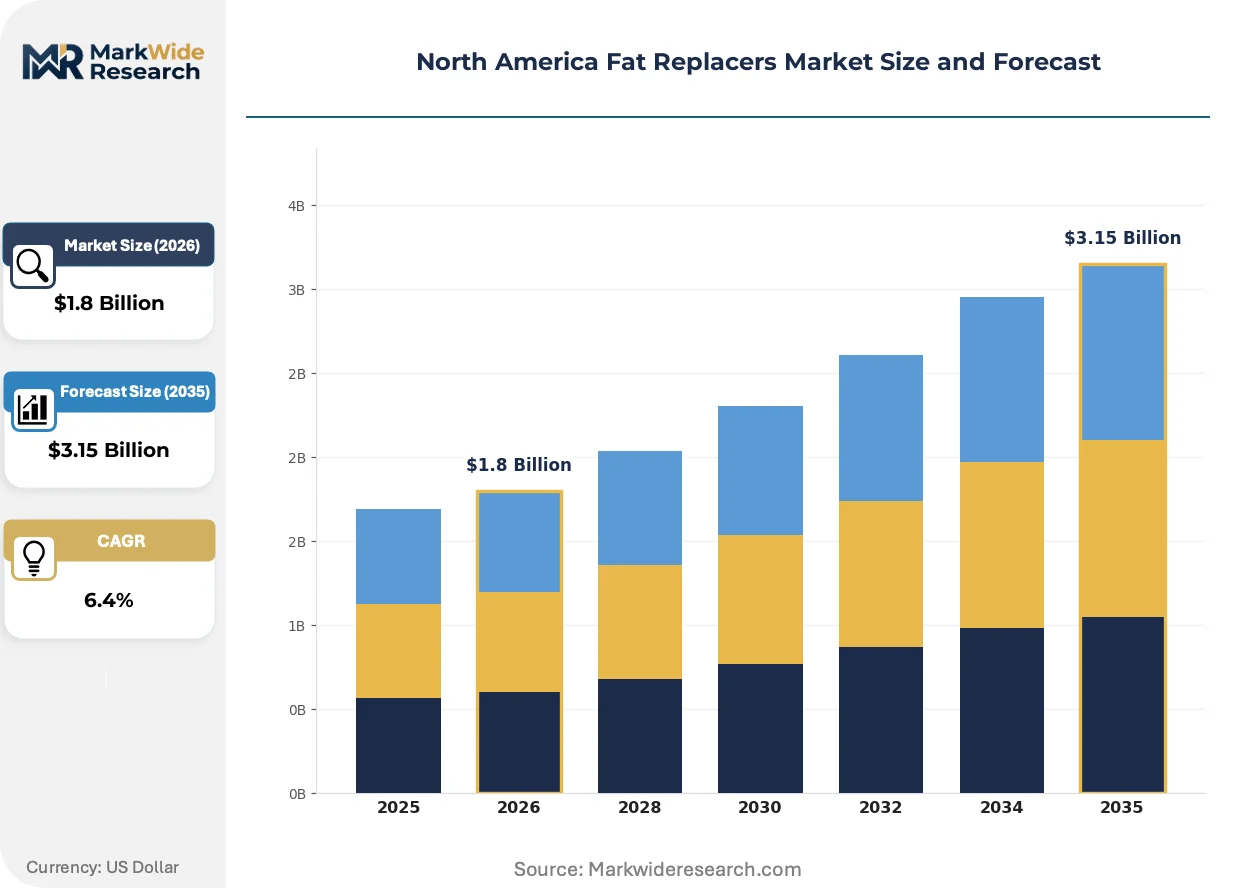
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carbohydrate-Based, Protein-Based, Fat-Based, Fiber-Based Application: Dairy Products, Baked Goods, Snacks, Sauces Delivery Mode: Powder, Liquid, Granular, Emulsified Source: Plant-Based, Animal-Based, Synthetic, Others |
| Companies Covered | Cargill Incorporated, Ingredion Incorporated, Tate & Lyle PLC, Corbion N.V., CP Kelco U.S., Inc., Archer-Daniels-Midland Company, Kerry Group plc, FMC Corporation, Ashland Global Holdings, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Fat Replacers Market Evolving Landscape
Formulation science is converging with regulatory pressure to accelerate ingredient system evolution. Three developments are restructuring how manufacturers approach fat reduction without sensory trade-offs.
Microencapsulation technology is hybridizing lipid and carbohydrate functionalities into single-ingredient systems. Encapsulated omega-3 oils combined with modified starch shells enable dual-purpose fat replacers that deliver both texture and nutritional enhancement. Mid-sized dairy processors in Wisconsin and New York are piloting these systems for reduced-fat cheese applications. This convergence is compressing the traditional separation between functional and nutritional ingredient categories.
The FDA's voluntary sodium and saturated fat reduction targets are reshaping procurement specifications across food manufacturing. Large-scale processors must now document progressive fat reduction across product portfolios to maintain retail distribution relationships. The baked goods segment faces the steepest compliance curve, driving accelerated starch-based fat mimetic adoption in Midwest production facilities.
Clean-label preference is shortening ingredient lists and favoring recognizable component names. Industrial buyers now reject multi-syllable chemical identifiers in favor of "corn fiber" or "citrus fiber" declarations that consumers understand. This behavioral shift most visibly impacts sauce and dressing manufacturers in California, where front-of-package disclosure requirements amplify formulation transparency demands.
North America Fat Replacers Market Segmentation
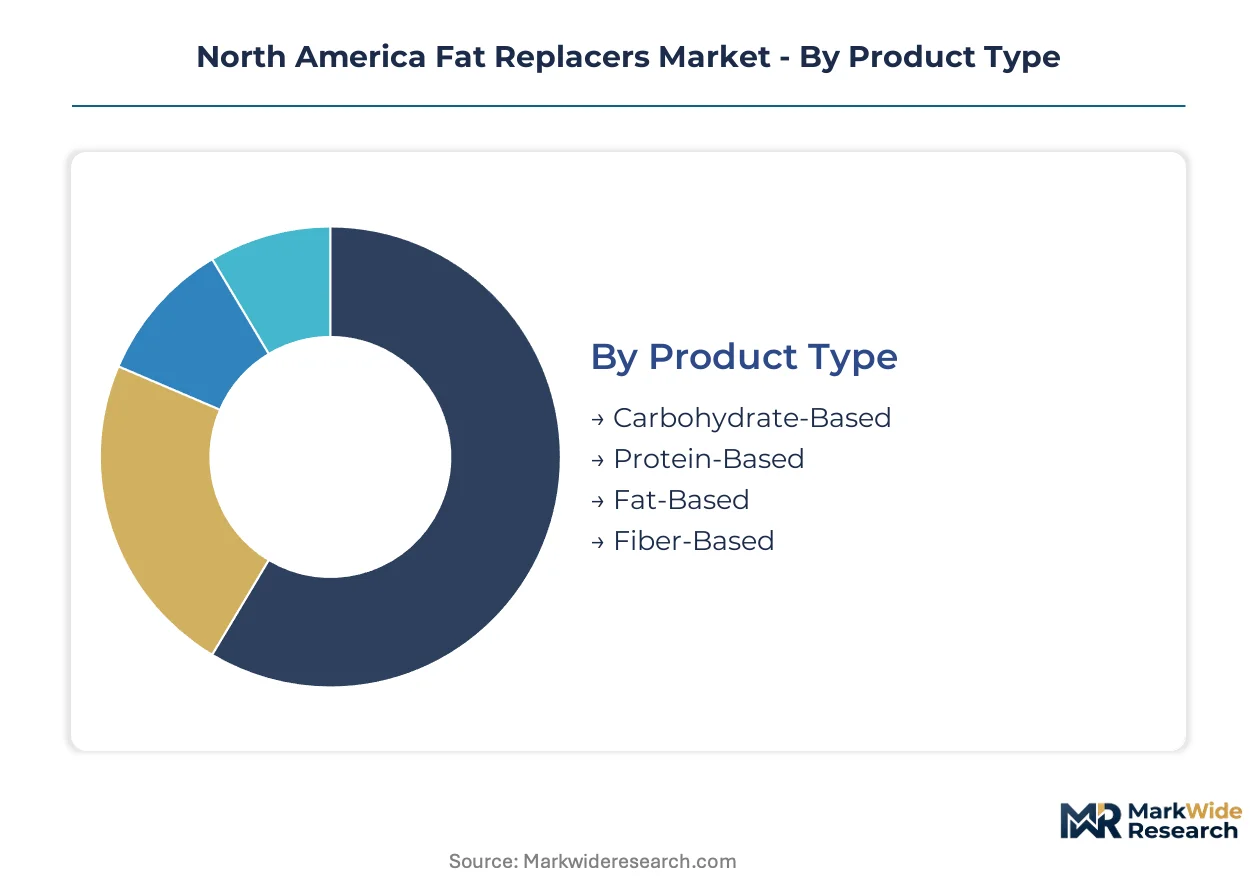
Ingredient functionality varies sharply across fat replacer categories, with formulation chemistry dictating viable end-use applications. Manufacturers align procurement decisions with specific texture targets, regulatory constraints, and processing equipment capabilities.
Product Type:
Cost tier differentiation separates commodity starch systems from premium protein technologies, with mid-range fiber formulations capturing reformulation budgets in health-positioned products.
- Carbohydrate-Based:Modified starches and maltodextrins derived from corn and tapioca deliver lipid-mimetic mouthfeel through sub-10 micron particle engineering. Midwest industrial bakeries in Iowa and Illinois deploy these systems for saturated fat reduction in cookies and crackers, though input cost volatility from Brazilian export dynamics squeezes margin structures.
- Protein-Based:Whey and micellar casein microparticulates maintain emulsion stability through controlled denaturation and size reduction. Wisconsin and New York dairy processors leverage these technologies for reduced-fat cheese and yogurt applications where FDA GRAS documentation requirements extend commercialization timelines.
- Fat-Based:Structured lipids and emulsified shortenings replicate conventional fat crystallization behavior.
- Fiber-Based:Cellulosic and pectin systems from citrus and oat sources provide water-binding capacity.
Carbohydrate-Based holds installed capacity. Protein-Based is rotating up the share rankings.
Application:
Application selection tracks regulatory pressure intensity, with baked goods and dairy facing the steepest FDA sodium and saturated fat reduction compliance curves.
- Dairy Products:Reduced-fat cheese, yogurt, and ice cream formulations demand emulsion stability and freeze-thaw tolerance. California processors combine microcrystalline cellulose with pea protein isolates for plant-based alternatives, responding to Health Canada compositional standards that influence cross-border product development.
- Baked Goods:Cakes, pastries, and cookies require fat replacers that sustain aeration and crumb structure during high-shear mixing. Midwest production facilities accelerate starch-based mimetic adoption to meet USDA dietary guideline procurement specifications for institutional foodservice.
- Snacks:Extruded and fried products utilize low-calorie fat barriers.
- Sauces:Pumpable liquid emulsified formats address Midwest condiment manufacturing requirements.
Dairy Products commands premium positioning. Baked Goods is climbing the fastest as reformulation mandates tighten.
Delivery Mode:
Volume throughput requirements determine format selection, with powder systems dominating high-speed industrial lines and liquid formats penetrating sauce processing.
- Powder:Spray-dried and agglomerated particles enable precise dosing in automated bakery and dairy processing lines. Industrial facilities across the U.S. Midwest sustain dominant share through established pneumatic conveying infrastructure and extended shelf stability.
- Liquid:Pre-hydrated emulsified suspensions eliminate dispersion steps in continuous sauce manufacturing. California and New York dressing producers adopt these formats for seamless pumpability, though refrigerated distribution adds logistics complexity.
- Granular:Free-flowing particles suit tabletop and small-batch applications.
- Emulsified:Stabilized oil-in-water systems target specific mouthfeel replication.
Powder holds installed capacity. Liquid is gaining share fastest in condiment processing corridors.
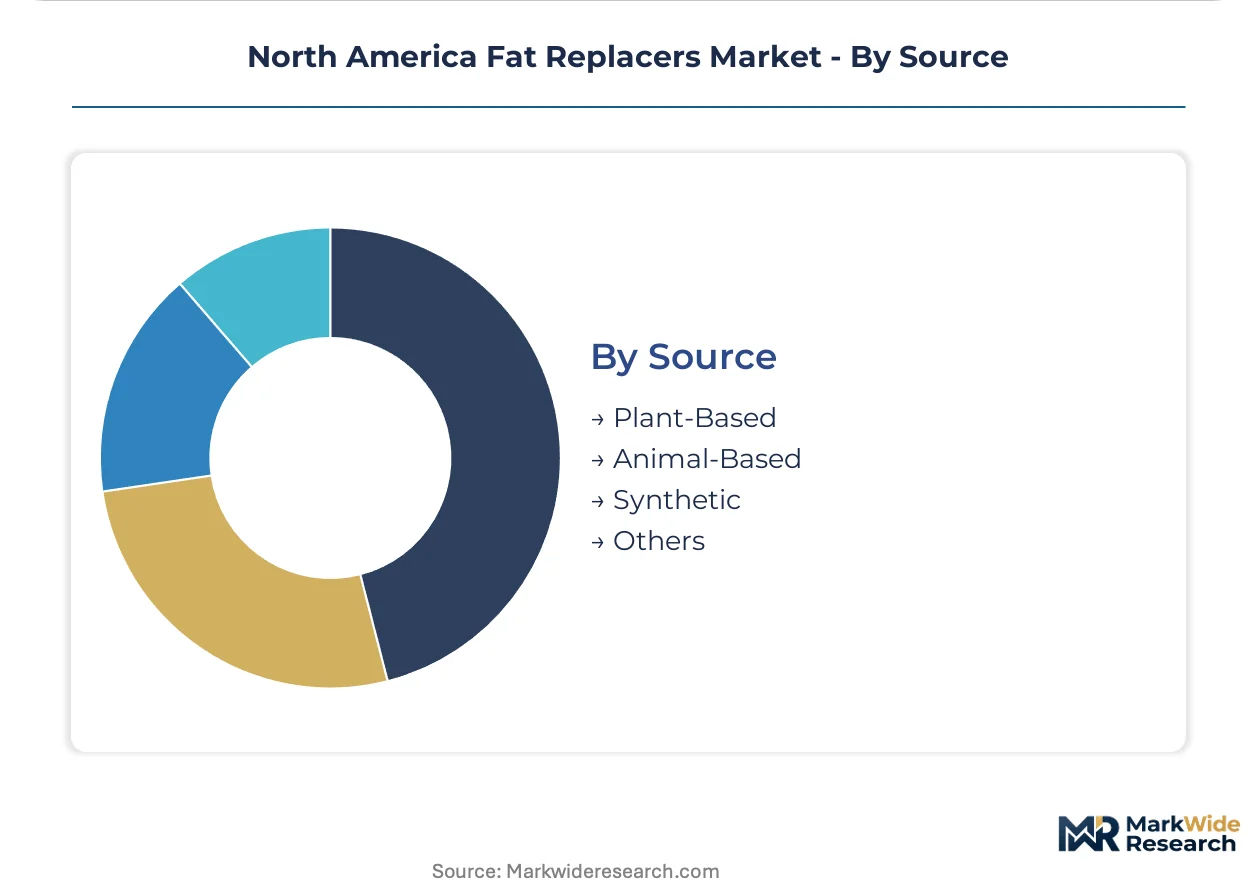
Source:
Supply concentration shapes source selection, with plant-based systems leveraging Midwest agricultural infrastructure and animal-based alternatives tied to dairy processing co-location.
- Plant-Based:Corn, tapioca, citrus, and oat-derived ingredients align with clean-label consumer preferences and FDA GRAS self-affirmation pathways. Iowa and Illinois starch processing corridors anchor supply for carbohydrate-based systems, while California's alternative protein corridor drives pea and oat fiber innovation.
- Animal-Based:Whey and casein fractions from cheese manufacturing bystreams deliver superior emulsion functionality. Wisconsin and New York dairy clusters provide captive supply for protein microparticulate production, though lactose intolerance positioning limits certain applications.
- Synthetic:Chemically modified compounds offer precise functional tuning.
- Others:Fermentation-derived and hybrid systems occupy emerging niches.
Plant-Based holds installed capacity. Animal-Based is rotating up the share rankings in premium dairy applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Midwest corn processing infrastructure anchors supply for carbohydrate-based fat mimetics, while coastal fermentation clusters concentrate hydrocolloid production. FDA and Health Canada regulations compress reformulation timelines across dairy and bakery corridors.
United States
Iowa and Illinois starch processing corridors supply modified corn starches to industrial bakeries facing USDA dietary guideline procurement mandates. The FDA's updated Nutrition Facts panel requirements accelerate saturated fat reduction timelines for cookies and crackers. Wisconsin dairy clusters deploy protein microparticulates for reduced-fat cheese applications.
Canada
Ontario and Quebec food manufacturers navigate Health Canada's front-of-package labeling regulations for fat reduction claims. Compositional standards under the Food and Drug Regulations shape permitted ingredient systems for cross-border product development. Prairie province agricultural infrastructure supports oat fiber sourcing for clean-label formulations.
Mexico
Bajío Region snack and sauce processors adopt liquid emulsified fat replacer formats for pumpability in condiment manufacturing. Mexican regulatory alignment with North American trade frameworks facilitates ingredient importation from U.S. Midwest suppliers. Mexico City Metro foodservice operators drive demand for reduced-fat bakery applications in institutional channels.
North America Fat Replacers Market Competitive Landscape
Agricultural-commodity processors and fermentation-derived hydrocolloid specialists split the market into distinct capability tiers. The structure favors players with captive raw material access or proprietary bioprocessing expertise. Vertically integrated agribusiness conglomerates and specialized biotech ingredient developers represent the dominant archetypes. Competitive moves concentrate on backward integration into corn and tapioca sourcing, plus capacity expansion in San Diego-area fermentation corridors.
Within the agricultural-commodity tier, Cargill Incorporated and Archer-Daniels-Midland Company occupy positions anchored to Midwest corn processing infrastructure. Ingredion Incorporated exemplifies the specialized starch refiner archetype with waxy maize and tapioca capabilities. CP Kelco U.S., Inc. represents the fermentation-derived hydrocolloid specialist model, situating its expertise within San Diego bioprocessing clusters for pectin and gellan gum applications.
| Leading Market Players |
|---|
| Cargill Incorporated |
| Ingredion Incorporated |
| Tate & Lyle PLC |
| Corbion N.V. |
| CP Kelco U.S., Inc. |
| Archer-Daniels-Midland Company |
| Kerry Group plc |
| FMC Corporation |
| Ashland Global Holdings, Inc. |
| Others |
Value Network & Pricing Analysis
Midwest corn processing corridors in Iowa and Illinois concentrate modified starch supply for carbohydrate-based fat mimetics, anchoring margin pools downstream with industrial bakeries facing USDA dietary guideline procurement mandates. This upstream concentration transfers pricing power to agribusiness conglomerates with captive raw material access, while coastal dairy processors absorb premium differentials for protein microparticulate systems.
Pricing Analysis
FDA's updated Nutrition Facts panel requirements dictate the pricing tier structure across the North America fat replacers market. Three-tier pricing structure across premium, standard, and economy levels separates protein-based whey and micellar casein systems from modified corn starches and commodity maltodextrins. Price differentiation stems from clean-label certification thresholds and volume scale commitments in Midwest bakery procurement. Cost compression in carbohydrate-based tiers is intensifying because Brazilian tapioca export volatility squeezes margin structures. Industrial bakeries in Iowa and Illinois demonstrate highest price sensitivity, while California plant-based dairy processors accept premium positioning for cellulosic-protein hybrid systems.
Supply Chain Analysis
Export-control regimes on fermentation-derived bioprocessing equipment limit pectin and gellan gum capacity expansion outside established San Diego-area clusters. Geographic supply concentration centers on the United States for corn-derived starches, Brazil for tapioca feedstock, and limited coastal U.S. zones for hydrocolloid fermentation. Raw material dependencies rest on Midwest agricultural yields, Brazilian export dynamics, and citrus fiber sourcing from Florida and California. Single-source vulnerability pervades hydrocolloid supply given San Diego bioprocessing concentration. Distribution runs through direct industrial supply agreements with large-scale food manufacturers, bypassing traditional ingredient distributor networks for volume commitments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America fat replacers market is cycling through a reformulation-driven recovery as FDA and Health Canada labeling mandates force simultaneous product redevelopment across dairy and bakery categories.
For Market Incumbents: Harden backward integration into Midwest corn processing corridors to secure modified starch supply against Brazilian tapioca price volatility. Expand San Diego-area fermentation capacity for pectin and gellan gum to eliminate single-point hydrocolloid vulnerability. Cargill Incorporated and Ingredion Incorporated must defend against emerging pea protein isolates from California's alternative protein corridor by accelerating GRAS documentation for novel protein microparticulate systems. For New Entrants and Emerging Players: Build out liquid emulsified fat replacer production for underpenetrated Midwest sauce and dressing manufacturing clusters currently reliant on full-fat bases. Target Wisconsin and New York dairy processors with hybrid cellulosic-protein texture systems for reduced-fat cheese applications. Establish co-manufacturing partnerships with existing San Diego fermentation facilities rather than greenfield capacity investment. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed specialty starch refiners lacking hydrocolloid diversification. The five-to-ten-year viability window favors acquisition targets with dual carbohydrate-protein technology platforms and established FDA GRAS documentation libraries. Watch for inflection signals in California front-of-package labeling enforcement that could accelerate clean-label ingredient transitions faster than federal timelines anticipate.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Corn Processing | Cargill Incorporated secures captive supply for modified starch fat mimetics against Brazilian export volatility. |
| Fermentation Capacity Expansion | CP Kelco U.S., Inc. eliminates single-point vulnerability for pectin and gellan gum hydrocolloid sourcing. |
| GRAS Documentation Investment | Novel protein microparticulate developers compress commercialization timelines for reduced-fat dairy applications. |
| Liquid Emulsion Format Development | Midwest condiment manufacturers gain pumpable fat replacer systems for continuous sauce processing lines. |
| Hybrid Texture System Partnerships | California plant-based dairy processors combine microcrystalline cellulose with pea protein isolates for clean-label alternatives. |
Research Methodology
A standing panel of food formulation chemists, dairy processing engineers, and industrial bakery procurement managers provided ongoing calibration across primary research phases. Ingredient supplier technical directors and regulatory affairs specialists at FDA-notified facilities contributed operational data on GRAS self-affirmation pathways. Secondary validation drew from FDA GRAS notices, USDA dietary guideline documentation, Health Canada Food and Drug Regulations filings, and SEC 10-K disclosures from publicly traded agribusiness conglomerates. Bottom-up volume modeling from individual production facilities was triangulated against top-down category spending estimates from institutional foodservice operators.
Scenario-bracketing framed projections across the analysis window, with segmentation dimensions spanning product type, application, delivery mode, and source. Modeled variables included carbohydrate-based versus protein-based system adoption curves, powder versus liquid format penetration in sauce processing, and plant-based versus animal-based sourcing shifts in dairy applications. CAGRs were derived from regression analysis against historical reformulation cycle data and regulatory compliance timeline acceleration. Industry-specific forecast inputs incorporated Midwest corn yield projections and San Diego fermentation capacity utilization rates.
Stress conditions across Brazilian tapioca export restrictions, California front-of-package labeling enforcement thresholds, and San Diego bioprocessing disruption were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about FDA voluntary sodium and saturated fat reduction target adherence rates and Health Canada cross-border regulatory alignment. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Food Sources
Gluten-Free Meat Substitutes Market
Alternative Food Sources
Asia-Pacific Meal Replacement Products Market
Alternative Food Sources
Edible Packaging Market
Alternative Food Sources
North America Precision Fermentation Market
Alternative Food Sources
Mycoprotein Products Market
Alternative Food Sources
South American Algae Protein Market
Alternative Food Sources
Artificial Meat Market
Alternative Food Sources
Konjac Market
Alternative Food Sources
Food Cultures Market
Alternative Food Sources
Asia-Pacific Meat Substitutes Market
Alternative Food Sources
Flour Substitutes Market
Alternative Food Sources
Carragean Alternatives Market
Alternative Food Sources
Europe Upcycled Food Products Market
Alternative Food Sources
Hemp-Based Products Market
Alternative Food Sources
Sugar Alternative Market
Alternative Food Sources
Mock Meat Market