
 Global Flaked Shortenings Market | 2026-2036
Global Flaked Shortenings Market Size, Share, and Industry Trends Forecast 2026-2036
Global Flaked Shortenings Market Intelligence
The US Food and Drug Administration's final determination on partially hydrogenated oils (PHOs) is hardening the technical and compliance barrier for market entry. Cargill, Inc. leverages its extensive oilseed processing infrastructure to offer a range of non-PHO solutions. Bunge Ltd. competes through its control over palm and soy supply chains, ensuring consistent feedstock for its shortening products. AAK AB specializes in high-value, functional fat solutions for specific baking applications.
Flaked shortenings are solid fats, typically derived from vegetable oils like palm or soy, that have been solidified and flaked. Their chip-like form facilitates easy blending into dry mixes, creating a flaky texture in baked goods like pastries and biscuits. Vegetable-based products dominate the market due to cost and versatility, with the baking application representing the largest volume segment. Large-scale industrial bakeries and food processing units constitute the primary end-user base.
Beyond the FDA's actions in the United States, the European Food Safety Authority (EFSA) sets strict limits on trans fatty acids, influencing product formulation across the EU. Food labeling regulations from bodies like India's FSSAI and China's SAMR mandate clear disclosure of fat content and origin. Navigating these divergent regional standards for fat composition and sourcing remains the central challenge for manufacturers seeking broad market access.

Market Dynamics
The global flaked shortenings market is defined by regulatory pressure to eliminate partially hydrogenated oils (PHOs). This pressure, led by agencies like the US FDA and Europe's EFSA, is bifurcating the market and concentrating R&D on compliant, functional fat formulations.
Growth Catalysts
- Industrial Baking Expansion:Volume is driven by the expansion of large-scale industrial bakeries, particularly for laminated dough products like pastries and croissants that require the specific textural properties imparted by flaked fats.
- Clean Label Formulations:Consumer demand for transparent and "clean" ingredients pushes food manufacturers to adopt non-PHO, non-GMO, and sustainably sourced shortenings, creating a distinct premium product tier.
- Regulatory Compliance:The US FDA's determination on PHOs and EFSA's strict limits on trans fatty acids act as a powerful catalyst, forcing a market-wide transition to alternative fat systems like palm and soy blends.
Market Restraints
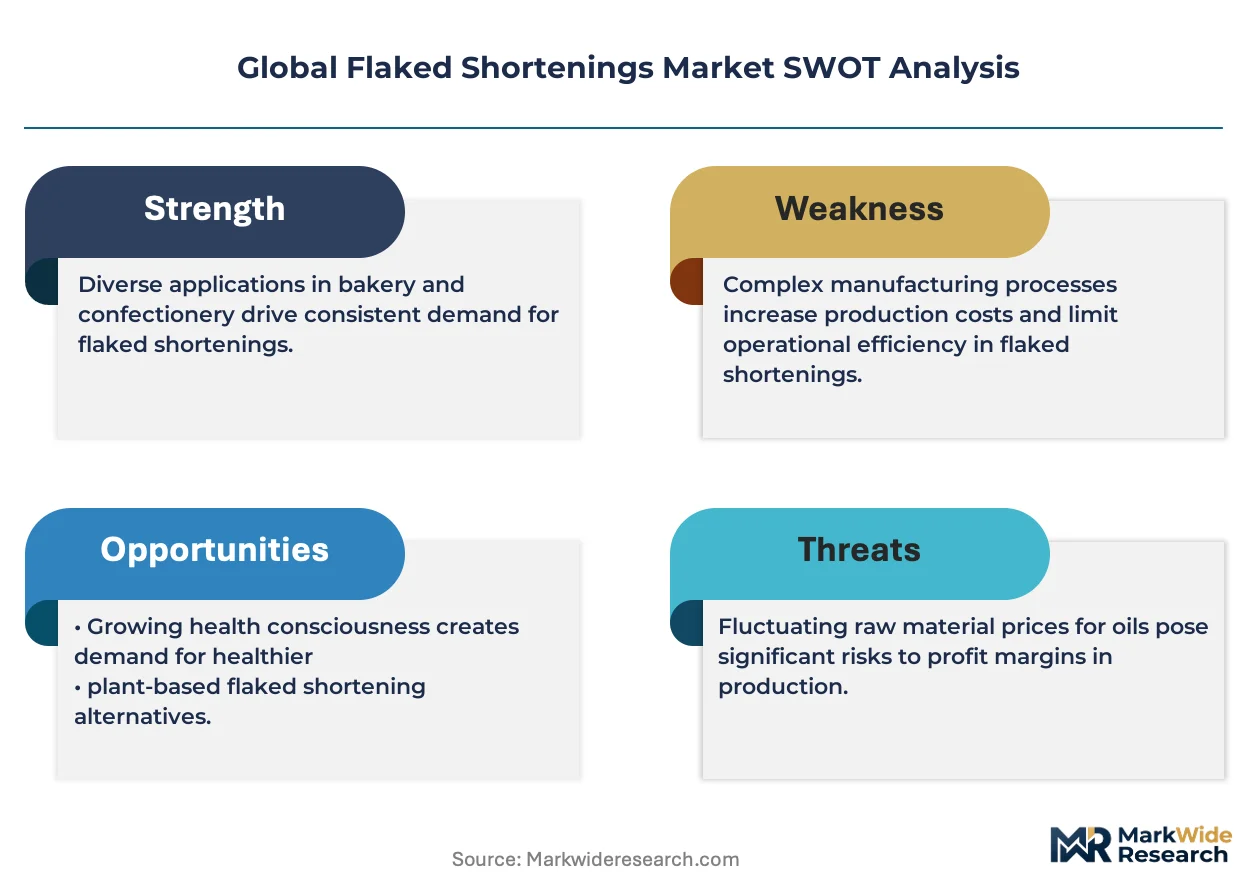
- Feedstock Price Volatility:The market is exposed to price fluctuations in key vegetable oils like palm and soy, which are influenced by global agricultural yields, weather events, and international trade policies.
- Threat from Liquid Alternatives:Innovations in emulsification and oil structuring technologies are enabling liquid oils to perform functions previously exclusive to solid fats, presenting a substitution threat in certain baking applications.
- High Cost of R&D:Developing non-PHO shortenings that perfectly mimic the functional attributes of legacy PHOs, such as melting profile and crystal structure, requires significant investment in lipid science and processing technology.
Strategic Opportunities
- Plant-Based Baking Segment:The rapid growth of the vegan and plant-based food sector creates a clear opportunity for flaked shortenings derived exclusively from vegetable sources and free from animal-based emulsifiers.
- Functional Fortification:Incorporating health-oriented additives such as omega-3 fatty acids, vitamins, or plant sterols into shortening flakes allows manufacturers to create value-added products for health-conscious market segments.
- Expansion in Southeast Asia:Rising disposable incomes and the proliferation of modern food processing facilities in countries like Vietnam and Indonesia represent a significant volume growth frontier for shortening suppliers.
Industry Challenges
- Supply Chain Traceability:Meeting strict certification requirements, such as those from the Roundtable on Sustainable Palm Oil (RSPO), demands complex, costly, and transparent traceability systems from plantation to final product.
- Replicating Functionality:A persistent technical challenge is the difficulty in precisely replicating the crystallization behavior and sharp melting point of PHO-based shortenings using palm, soy, or cottonseed oil blends.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Flaked Shortenings Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vegetable-based, Animal-based, Blended, Synthetic Application: Baking, Confectionery, Frying, Dairy Alternatives, Snack Foods Packaging Type: Block, Pail, Drum, Bulk Bags End User: Bakeries, Food Processing Units, Catering Services, Food Service Providers |
| Companies Covered | Archer Daniels Midland Company, Cargill, Inc., Bunge Ltd., Ventura Foods, LLC, ConAgra Brands, Associated British Foods, AAK AB, Wilmar International Ltd., Ingredion Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Flaked Shortenings Market Strategic Shifts & Innovations
Formulation science is advancing rapidly in response to the dual demands of regulatory compliance and functional performance. The primary focus is on developing non-PHO solutions that do not compromise texture or shelf life in finished baked goods, driving innovation in oil blending and processing.
Enzymatic interesterification is a key processing technology that restructures triglyceride molecules in vegetable oils to create solid fats without generating trans fats. Industrial food processors and ingredient manufacturers are adopting this method to produce high-performance, PHO-free shortenings. This technology is integrating advanced lipid chemistry with bulk oil processing, enabling the creation of customized fat systems that meet precise melt-point and textural specifications for applications like puff pastry.
India's FSSAI regulations mandating clear labeling of trans-fat content and the origin of edible oils are influencing product development and sourcing strategies. This policy compels manufacturers to reformulate products and enhance supply chain transparency to meet new disclosure requirements. The packaged snacks and industrial bakery segments are most affected, accelerating the domestic shift toward compliant palm and soy-based shortening formulations.
A notable behavioral shift is occurring as industrial bakeries increasingly select shortenings based on specific functional outcomes rather than on cost alone. This disrupts the traditional commodity sales model, favoring suppliers who provide strong application support for achieving precise textures in lamination or superior aeration in creams. This trend is most pronounced in the quality-driven European pastry market, especially in France and Germany, where product texture is a critical differentiator.
Global Flaked Shortenings Market Segmentation
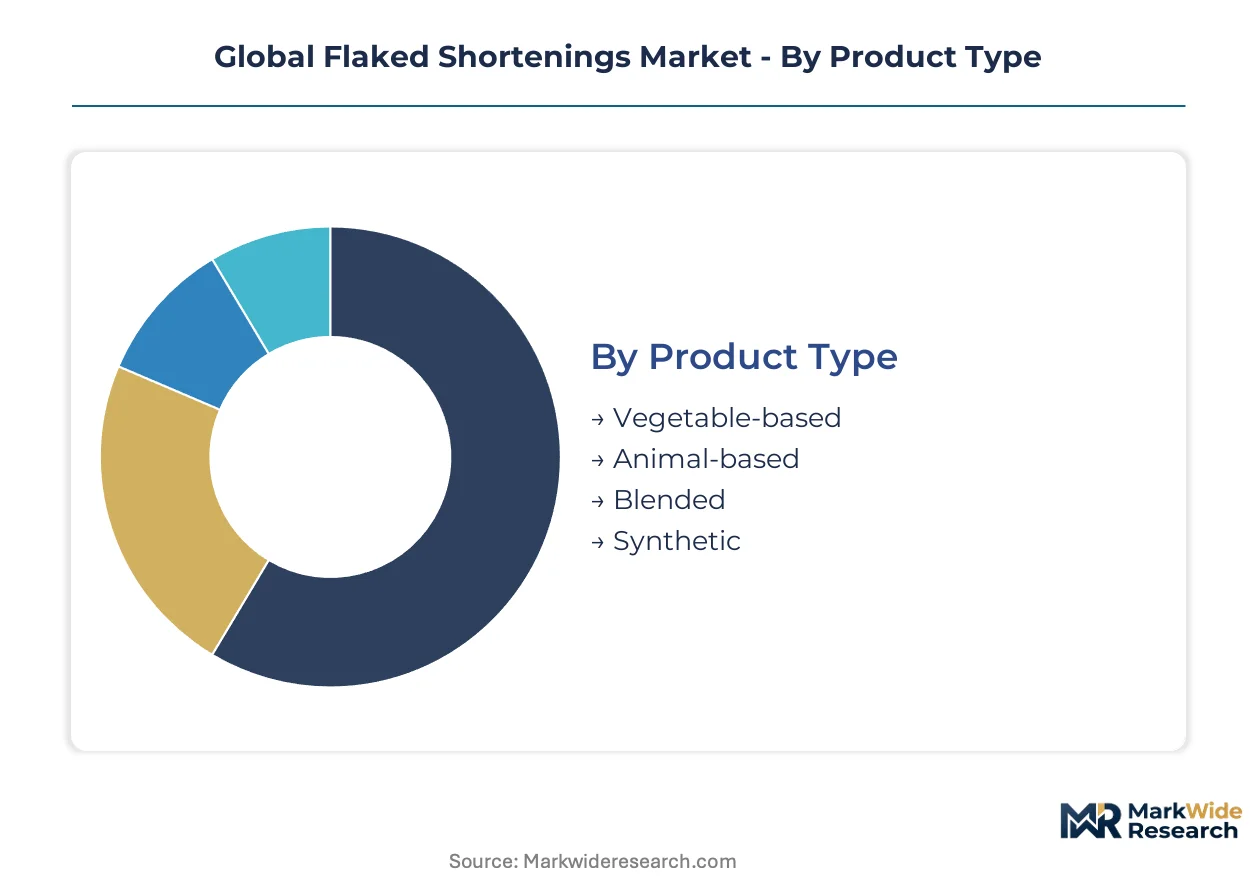
Segmentation within the global flaked shortenings market provides a granular view of product types, applications, packaging formats, and end-user categories, reflecting distinct demand patterns and regulatory compliance challenges. Understanding these divisions helps manufacturers tailor formulations and distribution strategies for optimal market penetration.
Product Type:
The regulatory landscape heavily influences the product type segment, particularly concerning compliance with non-PHO mandates from agencies like the US FDA and Europe's EFSA.
- Vegetable-based:These shortenings are predominantly derived from palm, soy, and sunflower oils, offering a versatile and cost-effective alternative to animal fats. Demand is concentrating in markets like the United States and Germany as food manufacturers transition away from partially hydrogenated oils to meet evolving food safety regulations.
- Blended:Formulations combine various vegetable oils and fats, often incorporating emulsifiers, to achieve specific functional properties like improved plasticity and melting profiles. The industrial baking sector, particularly for laminated doughs, drives demand for these customized blends to ensure consistent product texture.
- Animal-based:Historically used, these shortenings are derived from animal fats but face declining demand due to health concerns and the rise of plant-based alternatives.
- Synthetic:This category includes highly engineered fat replacers or structured lipids designed for specific functional attributes, often for niche applications.
Leading the category by volume: Vegetable-based. Growing fastest: Blended.
Application:
Application segmentation highlights where the specific functional attributes of flaked shortenings deliver the most significant value to end products.
- Baking:This segment includes pastries, biscuits, cookies, and laminated dough products, where flaked shortenings are critical for imparting flakiness, tenderness, and structure. Industrial bakeries in Europe and North America represent the largest consumption base, seeking consistent performance for high-volume production.
- Confectionery:Flaked shortenings provide desirable mouthfeel, texture, and melt characteristics in chocolates, fillings, and various sweet treats. Manufacturers prioritize specific melting profiles to prevent bloom and ensure product stability in diverse climatic conditions.
- Frying:While less common for flaked formats, some applications utilize specialized flaked shortenings for deep-frying, offering extended shelf life for fried products.
- Dairy Alternatives:Flaked shortenings contribute to texture and richness in plant-based dairy substitutes like vegan butters and creams.
- Snack Foods:Incorporated into crackers, savory biscuits, and various extruded snacks to enhance texture and crunch.
The Baking application commands the largest share of consumption, while Dairy Alternatives are experiencing the steepest expansion trajectory.
Packaging Type:
The choice of packaging type for flaked shortenings directly correlates with the scale of operations and distribution logistics of the end-user.
- Block:Solid blocks of shortening are common for smaller-scale bakeries and foodservice, offering ease of handling and portion control.
- Pail:Intermediate-sized pails, usually 15-20kg, serve medium-sized bakeries, catering services, and smaller food manufacturing operations. Their manageable size balances bulk purchasing benefits with ease of storage and dispensing in professional kitchens.
- Drum:Larger drums provide a more economical solution for industrial users with higher volume requirements, reducing packaging waste per unit of product.
- Bulk Bags:These large-volume containers, typically holding hundreds of kilograms, cater primarily to large-scale industrial food processing units and bakeries for efficient material handling. Cost-effectiveness and reduced packaging waste make them preferred for high-volume, continuous production lines.
Bulk Bags constitute the primary packaging format for industrial buyers, while Pail packaging remains a strong choice for mid-sized operations.
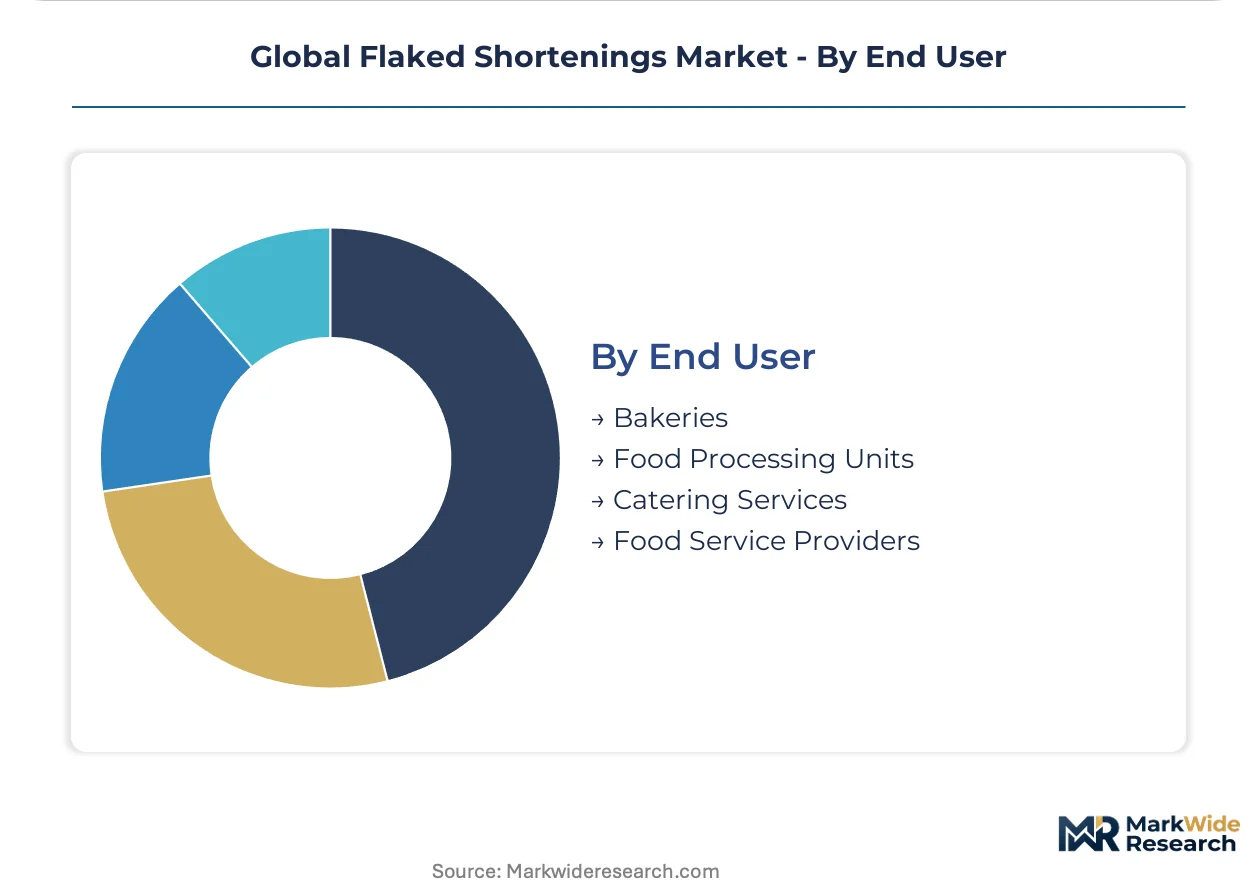
End User:
End-user segmentation reflects the diverse operational requirements and value chain positions of businesses utilizing flaked shortenings.
- Bakeries:This segment includes both industrial and artisanal bakeries producing a wide range of goods from bread to intricate pastries. They demand shortenings that deliver consistent flakiness, texture, and mouthfeel, especially in laminated products like croissants.
- Food Processing Units:These large-scale facilities incorporate flaked shortenings into snack foods, ready meals, and specialized food ingredients. Their procurement emphasizes consistent supply, bulk pricing, and compliance with stringent food safety standards for mass production.
- Catering Services:Professional kitchens and institutional caterers use flaked shortenings for various culinary preparations, valuing convenience and functional performance.
- Food Service Providers:Restaurants, cafes, and other commercial food establishments utilize shortenings in their kitchens for baking and cooking applications.
Food Processing Units represent the largest segment by volume, with Catering Services showing a notable increase in demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for flaked shortenings concentrates in industrialized nations, driven by large-scale food processing and bakery sectors. Regulatory shifts away from partially hydrogenated oils in countries like the United States and Germany are reshaping product formulations. This transition creates distinct regional market dynamics.
United States
Industrial baking expansion, particularly for laminated dough products, fuels demand in the United States. The US Food and Drug Administration's (FDA) final determination on partially hydrogenated oils (PHOs) necessitates non-PHO compliant formulations. Midwest food processing hubs, like those in Illinois and Ohio, are actively reformulating products to meet these standards.
Germany
Germany's quality-driven European pastry market requires flaked shortenings for precise textural outcomes in products like croissants. The European Food Safety Authority (EFSA) imposes strict limits on trans fatty acids, influencing local product formulation. Bavaria's specialized bakeries and food ingredient manufacturers prioritize high-performance, compliant fat solutions.
China
China's expanding packaged snacks and industrial bakery segments drive significant volume demand for flaked shortenings. The State Administration for Market Regulation (SAMR) mandates clear disclosure of fat content and origin, compelling manufacturers to enhance supply chain transparency. The Yangtze River Delta region, a major food manufacturing cluster, is accelerating its shift to compliant formulations.
India
India's domestic shift towards compliant palm and soy-based shortening formulations is propelled by robust growth in the packaged food sector. The Food Safety and Standards Authority of India (FSSAI) regulations explicitly mandate clear labeling of trans-fat content. Maharashtra's food processing industry is a key area for adopting new shortening technologies to meet these requirements.
Brazil
Brazil's growing food processing sector and bakery expansion contribute to rising demand for functional flaked shortenings. The national health surveillance agency (ANVISA) sets standards for food additives and fat composition, influencing local product development. São Paulo's large industrial bakeries represent a significant consumption base, seeking consistent product quality.
Global Flaked Shortenings Market Key Industry Players
North American producers anchor one tier; European specialists hold another, creating a tiered market structure. The competitive landscape features a mix of large-scale agribusiness conglomerates and specialized functional fat providers. Strategic archetypes include integrated oilseed processors, dedicated shortening manufacturers, and niche ingredient suppliers. Companies are pursuing portfolio diversification and strategic partnerships to navigate regulatory shifts.
At the scale-driven end of the market, Cargill, Inc. represents a major integrated agribusiness player, leveraging extensive oilseed processing infrastructure. This company provides a broad range of non-PHO solutions for industrial clients. Bunge Ltd. also occupies a significant position, controlling vast palm and soy supply chains to ensure consistent feedstock delivery for its shortening products. AAK AB, conversely, exemplifies a specialized functional fat provider, focusing on high-value, functional fat solutions for specific baking applications across various global markets. These companies anchor distinct segments of the supply chain.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Cargill, Inc. |
| Bunge Ltd. |
| Ventura Foods, LLC |
| ConAgra Brands |
| Associated British Foods |
| AAK AB |
| Wilmar International Ltd. |
| Ingredion Incorporated |
| Others |
Cost & Logistics Intelligence
Industrial bakeries' high-volume procurement of flaked shortenings establishes a contract-based pricing model. This approach prioritizes long-term supply stability over spot market fluctuations for critical ingredients.
Pricing Analysis
Short lead times for specialty flaked shortenings command premium pricing, while standard formulations often trade on commodity spot rates. The market primarily operates on a hybrid model, combining long-term contract-based pricing for bulk volumes with transactional spot pricing for urgent or niche requirements. Quality grade, determined by specific melt profiles, and certification level, such as RSPO for sustainable palm oil, drive price differentiation. Pricing softness reflects intense competition among large-scale producers like Cargill and Bunge for high-volume industrial contracts. Industrial food processing units are highly price-sensitive for standard formulations, whereas artisanal bakeries prioritize functional performance over cost.
Supply Chain Analysis
India's FSSAI regulations, mandating clear labeling of fat origin, are reshaping sourcing strategies for flaked shortenings within the country. Production of key vegetable oils concentrates in Southeast Asian nations like Malaysia and Indonesia for palm, and Brazil and the United States for soy. The supply chain relies heavily on crude palm oil and soybean oil as primary feedstocks. Commodity price volatility, influenced by global agricultural yields and geopolitical events, represents a significant structural risk. Distribution runs through a network of large ingredient distributors and direct sales channels to industrial end-users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The flaked shortenings market is currently engaged in a vertical-integration race, driven by manufacturers seeking upstream control over vegetable oil supply chains. This ensures consistent feedstock quality and compliance with sustainability mandates like RSPO certification.
For Market Incumbents:Anticipate continued regulatory pressure from agencies like the US FDA and EFSA, necessitating ongoing R&D into non-PHO compliant formulations. Incumbents should invest in enzymatic interesterification technologies to replicate PHO functionality and deepen partnerships with industrial bakeries for application support. The threat from liquid alternatives, enabled by advanced emulsification, requires continuous product innovation. Expanding certified sustainable palm oil sourcing in Indonesia and Malaysia strengthens market position.
For New Entrants and Emerging Players:Launch via direct-to-customer e-commerce platforms targeting specialized artisanal bakeries and plant-based food startups. Focus on the plant-based baking segment with exclusively vegetable-derived, non-GMO shortenings. Another target is functional fortification, incorporating omega-3s into flakes. The dairy alternatives application in Western Europe, particularly Germany, offers high penetrability due to strong consumer demand for vegan products. Emphasize clean label formulations and superior textural performance in niche applications like vegan puff pastry.
For Investors and Strategic Acquirers:The window for entry favors strategic acquirers with deep pockets and expertise in lipid science. This market presents long-term viability over the next 5-10 years, driven by sustained industrial baking growth and evolving health regulations. Target specialized functional fat providers like AAK AB, or mid-sized players with proprietary enzymatic interesterification technology. The signal to watch is the widespread commercial adoption of advanced oil structuring technologies that perfectly mimic PHO functionality.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Southeast Asia | Secures supply of palm oil, critical for non-PHO formulations. |
| Investment in Enzymatic Interesterification | Enables precise replication of desired melt profiles in shortenings. |
| RSPO Certification Program Expansion | Meets growing consumer and regulatory demand for sustainable sourcing. |
| Development of Fortified Flaked Shortenings | Captures health-conscious market segments with value-added products. |
| Strategic Partnerships with Industrial Bakeries | Provides application support, ensuring optimal product performance for clients. |
Research Approach
Trade association data, regulatory filings from the US FDA and EFSA, and customs records anchored secondary inputs for this analysis. This was combined with primary interviews involving R&D directors at shortening manufacturers, procurement leads at industrial bakeries, and food safety compliance officers. Insights from lipid scientists, supply chain managers for vegetable oils, and product development specialists further informed the market understanding. Bottom-up data aggregation and top-down market sizing provided robust triangulation of market estimates.
Product type, application, and end-user segments were modeled at granular country levels across the projection horizon. Compound annual growth rates were derived from historical growth trends, regulatory impact assessments, and projected demand shifts in industrial baking. Key dimensions included vegetable-based vs. blended shortenings, baking vs. confectionery applications, and industrial food processing units vs. bakeries. Forecast inputs included global vegetable oil production forecasts and regional packaged food consumption trends.
Global agricultural yields, evolving trans fat regulations, and technological breakthroughs in oil structuring are the dominant revision risks for market forecasts. Forecasts reflect assumptions regarding feedstock availability and the pace of non-PHO adoption. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Food Grade Ammonium Carbonate Market
Food Additives and Ingredients
Food Grade Release Agent Market
Food Additives and Ingredients
India Anti Caking Market
Food Additives and Ingredients
India Food Emulsifiers Market
Food Additives and Ingredients
Meat Stabilizers Blends Market
Food Additives and Ingredients
Europe Clean Label Ingredient Market
Food Additives and Ingredients
Food Antifoaming Agents Market
Food Additives and Ingredients
Noodles Preservatives Market
Food Additives and Ingredients
Japan Food Preservatives Market
Food Additives and Ingredients
Food Blue 5 Market
Food Additives and Ingredients
Egg Wash Substitute Market
Food Additives and Ingredients
Lipase Food Enzymes Market
Food Additives and Ingredients
South Africa Food Enzymes Market
Food Additives and Ingredients
Italy Food Preservatives Market
Food Additives and Ingredients
Fat Replacers Salt Reducers and Replacers Market
Food Additives and Ingredients
Activated Cake Emulsifier Market