
 Anti-Caking Market | 2026-2036
Anti-Caking Market Size, Share, and Industry Trends Forecast 2026-2036
Anti-Caking Market Outlook
REACH is pivoting the European anti-caking landscape toward comprehensive toxicological dossiers for synthetic silica variants. Evonik Industries AG leverages its precipitated silica expertise to sustain premium positioning in pharmaceutical-grade supply chains. BASF SE anchors the agricultural segment through controlled-release fertilizer coatings that incorporate anti-caking functionality.
Anti-caking agents are hygroscopicity-modifying compounds, typically comprising silicates, carbonates, or metallic stearates, that prevent particulate agglomeration through moisture absorption or physical barrier formation; manufacturers dose them at 0.5-2.0% w/w to maintain free-flow properties in bulk solids handling. Sodium silicate dominates industrial applications where alkaline pH tolerance and cost efficiency matter, while magnesium stearate commands pharmaceutical formulations demanding lubricity alongside anti-caking performance. Powder forms retain the largest volume footprint, though liquid blends are gaining traction in automated spray-coating systems for fertilizer and feed processing.
The FDA's GRAS designation framework and the EPA's pesticide inert ingredient listings jointly determine which chemistries qualify for food and agricultural use in the United States. EFSA's re-evaluation program for food additives is compressing approval timelines for novel silica variants across European markets. Stakeholders must monitor evolving purity standards in multiple jurisdictions to avoid reformulation costs and supply disqualification.
Market Dynamics
REACH's tightening toxicological dossier requirements for synthetic silica variants is compressing supplier qualification timelines and forcing reformulation investments across European food and pharmaceutical supply chains.
Growth Catalysts
- Feed-grade demand concentration:India and Vietnam are scaling animal nutrition manufacturing, driving procurement of calcium carbonate and magnesium stearate formulations for pelleted feed processing.
- EU purity mandates:The updated Food Additive Regulation is disqualifying legacy silica suppliers and creating volume openings for EFSA-compliant precipitated silica producers.
- Automated coating systems:Liquid anti-caking blends are displacing powder dosing in fertilizer processing lines, reducing dust exposure and enabling precision application rates.
Market Restraints
- Input cost volatility:Sodium silicate production depends on soda ash and quartz sand, both subject to energy-linked price swings and Chinese export quota fluctuations.
- Supplier concentration risk:Pharmaceutical-grade magnesium stearate supply concentrates among German and Japanese specialty chemical producers, creating single-source vulnerabilities.
- Substitution pressure:Natural zeolites and rice hull ash are gaining traction in organic-certified food applications, displacing synthetic silicates in premium seasoning segments.
Strategic Opportunities
- Underpenetrated feed markets:Brazil's expanding poultry and aquaculture sectors lack localized anti-caking formulation capacity, creating import substitution openings for regional compounders.
- Regulatory tailwind:India's PLI scheme for specialty chemicals subsidizes domestic precipitated silica capacity, reducing import dependence for food and pharmaceutical manufacturers.
- Technology convergence:Encapsulation technologies combining anti-caking with controlled-release functionality are penetrating agricultural micronutrient coatings, commanding price premiums over commodity silicates.
Industry Challenges
- Certification timeline compression:EFSA's accelerated re-evaluation program is compressing dossier preparation windows, straining regulatory affairs capacity at mid-tier suppliers.
- Legacy equipment retrofit costs:Powder-to-liquid transition in fertilizer processing requires spray system installation and operator retraining, delaying adoption at smaller compounders.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti-Caking Market |
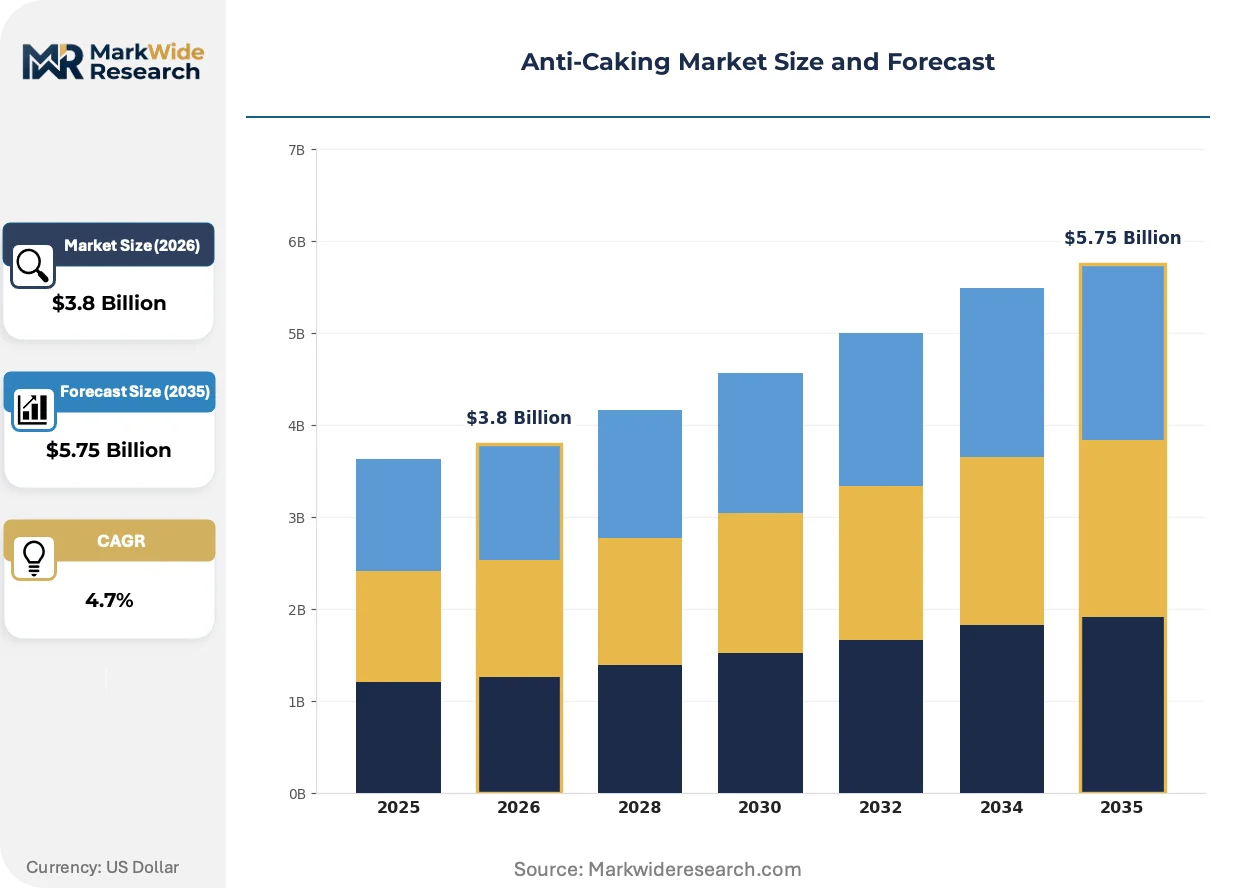
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.75 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sodium Silicate, Calcium Carbonate, Talc, Magnesium Stearate Application: Food Processing, Pharmaceuticals, Agriculture, Animal Feed Form: Powder, Granules, Liquid, Blends End User: Food Manufacturers, Chemical Producers, Pharmaceutical Companies, Feed Manufacturers |
| Companies Covered | Evonik Industries AG, Brenntag AG, PPG Industries, Inc., Cargill, Incorporated, Solvay S.A., Huber Engineered Materials, Kao Corporation, Univar Solutions Inc., BASF SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti-Caking Market Strategic Shifts
Formulation science is pivoting toward multi-functional agents that combine flowability, moisture control, and nutrient protection in single-ingredient solutions, collapsing the traditional additive stack.
Modified starch complexes engineered for hygroscopicity control are expanding into dairy powder and beverage premix applications, displacing silica in clean-label formulations. European infant nutrition manufacturers are adopting these systems to meet retailer-driven "no synthetic additives" specifications. This expansion is compressing volume share for conventional silicates in premium food segments while opening formulation partnerships between starch suppliers and dairy processors.
REACH's 2023 update to nanomaterial registration thresholds is reclassifying precipitated silica particle size distributions, triggering toxicological re-testing for sub-micron grades. German and Dutch chemical producers are accelerating dossier submissions to maintain pharmaceutical excipient qualifications. The agricultural segment faces the steepest compliance burden, as fertilizer coatings lack the margin structure to absorb extended registration timelines.
Seasoning and condiment manufacturers are consolidating supplier relationships from transactional spot purchasing to multi-year formulation partnerships, locking in technical support and regulatory documentation. This consolidation disadvantages commodity traders and favors integrated producers with in-house application laboratories. The shift is most pronounced in Southeast Asian processed food clusters, where export compliance requirements are intensifying.
Anti-Caking Market Segmentation
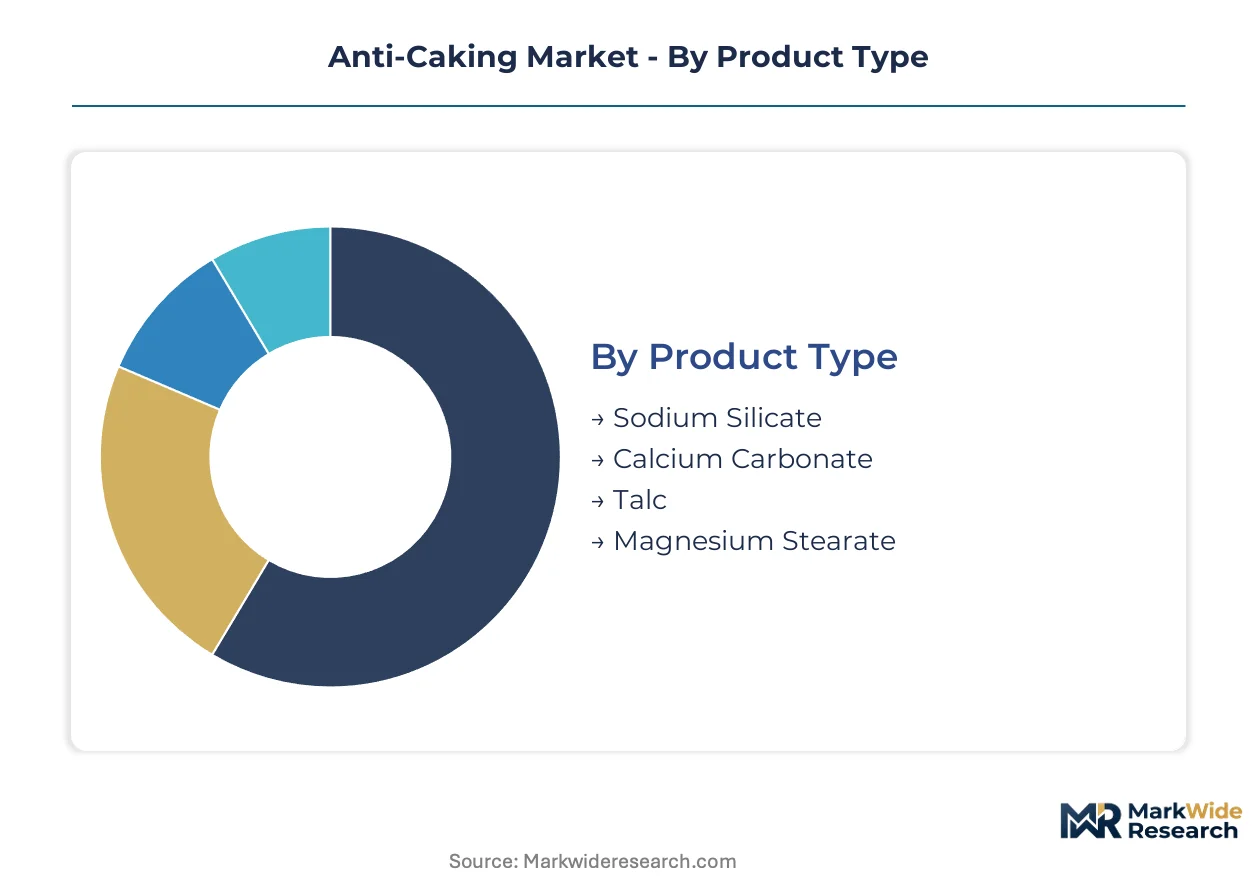
Anti-caking agent selection hinges on hygroscopicity requirements, processing equipment compatibility, and regulatory jurisdiction. Formulators balance cost efficiency against performance thresholds across divergent end-use specifications.
Product Type:
Sodium silicate commands volume leadership through alkaline tolerance and raw material abundance, while magnesium stearate captures pharmaceutical premiums through dual functionality.
- Sodium Silicate:Alkaline silicate manufactured from soda ash and quartz sand. Indian and Vietnamese feed compounders are scaling procurement for pelleted animal nutrition, though energy-linked input volatility constrains margin stability.
- Magnesium Stearate:Metallic stearate combining lubricity with moisture barrier properties. German and Japanese specialty chemical producers dominate pharmaceutical-grade supply, creating single-source vulnerabilities for tablet manufacturers.
- Calcium Carbonate:Naturally sourced carbonate with pH-neutral profile. Agricultural fertilizer coatings in Brazil and Southeast Asia absorb significant volume.
- Talc:Hydrated magnesium silicate with lamellar structure. Seasoning blend processors favor its physical barrier formation in high-humidity climates.
Today's leader: Sodium Silicate. Tomorrow's challenger: Magnesium Stearate.
Application:
Food processing retains installed base dominance, though agricultural automation is rewiring growth trajectories across formulation categories.
- Food Processing:Seasoning blends, powdered dairy, and beverage premixes require hygroscopicity control. European infant nutrition manufacturers are displacing synthetic silicates with modified starch complexes to meet clean-label retailer specifications.
- Agriculture:Controlled-release fertilizer coatings incorporate anti-caking functionality. Automated spray-coating systems in Brazilian compounders are accelerating liquid blend adoption over powder dosing.
- Pharmaceuticals:Tablet and capsule formulations demand excipient-grade purity. EFSA's accelerated re-evaluation program is compressing dossier timelines for silica variants.
- Animal Feed:Pelleted feed processing in India and Vietnam concentrates demand for calcium carbonate and magnesium stearate formulations.
Food Processing anchors current revenue. Agriculture climbs the fastest on automation investment.
Form:
Powder maintains equipment compatibility legacy, while liquid formats capture precision-application premiums in automated processing lines.
- Powder:Free-flowing particulate with established bulk handling infrastructure. Dust exposure and dosing inconsistency drive displacement in modern fertilizer facilities.
- Liquid:Spray-compatible suspensions enabling precision application rates. Southeast Asian processed food clusters are consolidating toward multi-year formulation partnerships with integrated producers.
- Granules:Agglomerated particles reducing dust generation. Intermediate option for compounders transitioning between powder and liquid systems.
- Blends:Pre-formulated combinations with carriers or active ingredients. Encapsulation technologies combining anti-caking with controlled-release functionality command agricultural micronutrient premiums.
Powder dominates installed base. Liquid gains share fastest on automation retrofit cycles.
End User:
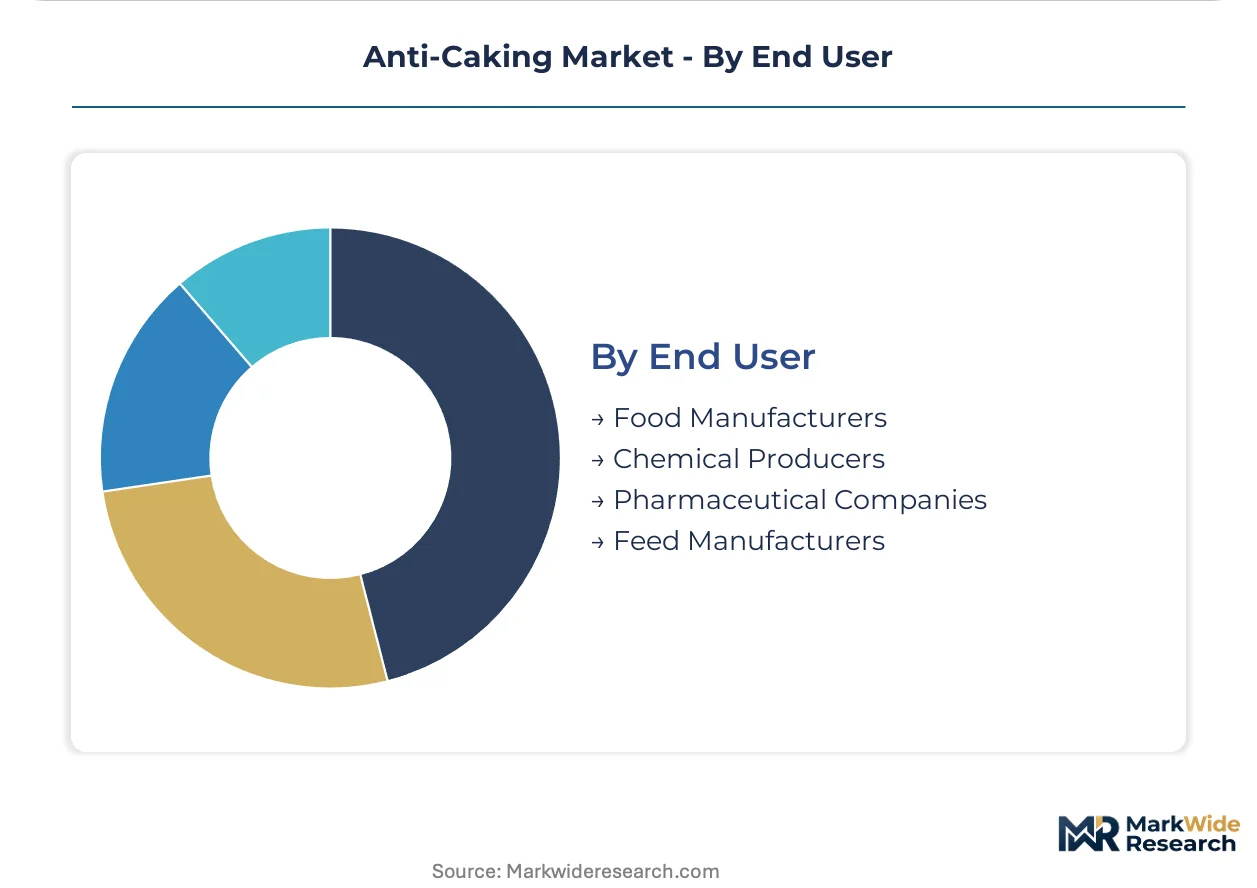
Food manufacturers drive specification intensity, while feed manufacturers expand volume procurement on protein sector growth.
- Food Manufacturers:Seasoning, dairy, and condiment processors. REACH's nanomaterial registration updates are reclassifying precipitated silica particle sizes, triggering toxicological re-testing costs.
- Feed Manufacturers:Poultry, aquaculture, and ruminant nutrition compounders. Brazil's expanding protein sectors lack localized formulation capacity, creating import substitution openings.
- Pharmaceutical Companies:Tablet excipient and capsule lubricant purchasers. German and Dutch producers are accelerating dossier submissions to maintain excipient qualifications.
- Chemical Producers:Intermediate formulators supplying downstream blenders. India's PLI scheme for specialty chemicals subsidizes domestic precipitated silica capacity.
Food Manufacturers set specification standards. Feed Manufacturers represent steepest volume expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German chemical engineers and Dutch regulatory specialists anchor European formulation expertise, while Indian process chemists and Vietnamese compounders concentrate procurement decision-making in Asia-Pacific feed processing corridors.
Germany
Pharmaceutical excipient demand concentrates in Ludwigshafen and Leverkusen chemical clusters, where tablet lubricant specifications drive magnesium stearate procurement. REACH's 2023 nanomaterial registration update triggers toxicological re-testing for sub-micron precipitated silica grades. Evonik Industries AG maintains pharmaceutical-grade supply chain dominance through accelerated dossier submissions to ECHA.
India
Animal nutrition manufacturing scales in Gujarat and Maharashtra, absorbing calcium carbonate and sodium silicate for pelleted poultry feed. The PLI scheme for specialty chemicals subsidizes domestic precipitated silica capacity expansion. Mumbai-Pune chemical corridor attracts Japanese and German joint ventures seeking feed-grade formulation partnerships.
Vietnam
Aquaculture feed compounders in Ho Chi Minh City and Dong Nai Province scale anti-caking procurement for shrimp and pangasius nutrition. FSSAI-equivalent import standards tighten as domestic regulators align with ASEAN harmonization protocols. Binh Duong industrial zone concentrates spray-drying capacity for liquid anti-caking blend processing.
Brazil
Poultry and soybean processing expansion in São Paulo and Paraná states outpaces localized anti-caking formulation capacity. ANVISA's food additive purity thresholds compress supplier qualification timelines for seasoning blend exporters. Campinas chemical hub attracts import substitution investment from European precipitated silica producers.
United States
Seasoning and dairy powder processors in Chicago and Minneapolis metro areas drive hygroscopicity control specifications. FDA's GRAS designation framework and EPA pesticide inert ingredient listings jointly determine agricultural coating chemistries. New Jersey chemical corridor concentrates pharmaceutical excipient blending and regulatory documentation services.
Anti-Caking Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across formulation tiers, creating a bifurcated structure where scale-driven commodity silicates coexist with premium pharmaceutical-grade stearates. The vendor base organizes around three strategic archetypes: integrated chemical conglomerates with backward integration into soda ash and quartz sand; specialty excipient houses concentrating pharmaceutical and food-grade certifications; and regional compounders serving feed and fertilizer processing with localized blending capacity. Competitive dynamics center on regulatory dossier acceleration and spray-system formulation partnerships for automated agricultural coating lines.
Among German chemical producers, Evonik Industries AG and BASF SE exemplify the integrated conglomerate archetype, anchoring pharmaceutical and agricultural supply chains respectively through precipitated silica expertise and controlled-release fertilizer coating systems. Solvay S.A. occupies a parallel position in European specialty chemical supply, representing the Belgian-heritage tier of multi-segment material science providers.
| Leading Market Players |
|---|
| Evonik Industries AG |
| Brenntag AG |
| PPG Industries, Inc. |
| Cargill, Incorporated |
| Solvay S.A. |
| Huber Engineered Materials |
| Kao Corporation |
| Univar Solutions Inc. |
| BASF SE |
| Others |
Value Chain & Pricing Dynamics
EFSA's accelerated re-evaluation program for silica variants is compressing supplier qualification timelines and forcing buyers to absorb premium pricing for ECHA-compliant precipitated grades, while legacy compounders face reformulation costs or disqualification.
Pricing Analysis
Bundled formulation partnerships command 15-25% premiums over transactional spot purchasing by incorporating regulatory documentation, technical support, and multi-year supply security. Three-tier pricing structure across pharmaceutical-grade, food-grade, and feed-grade certifications anchors differentiation, with magnesium stearate pharmaceutical excipients capturing the widest spreads. Cost compression in commodity sodium silicate is intensifying because Indian and Vietnamese feed compounders are consolidating procurement volumes. Feed manufacturers exhibit the highest price sensitivity due to protein sector margin pressures, while pharmaceutical tablet producers prioritize supply security over unit economics.
Supply Chain Analysis
Dual-sourcing mandates from European food and pharmaceutical manufacturers are forcing qualification of secondary precipitated silica suppliers in Germany and the Netherlands alongside primary Japanese and German specialty chemical houses. Manufacturing concentration rests on Germany, China, and India for synthetic silicate production, with Brazilian and Vietnamese markets dependent on import flows. Soda ash, quartz sand, and metallic stearate feedstocks draw from energy-intensive chlor-alkali and oleochemical chains. Single-source vulnerability concentrates in pharmaceutical-grade magnesium stearate, where German and Japanese producers control excipient qualifications. Distribution runs through regional compounders in Southeast Asian feed corridors and direct technical sales for pharmaceutical applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through encapsulation technology premiums and regulatory-compliant grade differentiation, as automation investments in agricultural processing displace commodity powder volumes.
For Market Incumbents: Acquire spray-drying and liquid formulation assets to capture fertilizer automation retrofit cycles. Lock in multi-year partnerships with Southeast Asian seasoning processors facing export compliance intensification. Backward integration into precipitated silica manufacturing insulates against ECHA registration timeline compression and soda ash volatility. For New Entrants and Emerging Players: Brazilian poultry and aquaculture feed compounders lack localized anti-caking formulation capacity and present import substitution openings. Target India's PLI-subsidized specialty chemicals corridor for joint venture precipitated silica production. Lead with regulatory dossier acceleration services to differentiate from commodity traders. For Investors and Strategic Acquirers: Asymmetric upside sits with mid-tier encapsulation technology specialists combining anti-caking with controlled-release functionality in agricultural micronutrients. Five-to-ten year viability hinges on regulatory compliance infrastructure rather than commodity scale. Watch EFSA's nanomaterial threshold enforcement as the inflection signal for sub-micron grade requalification costs.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precipitated Silica | ECHA dossier control reduces regulatory disqualification risk for pharmaceutical supply chains. |
| Liquid Blend Formulation Partnerships | Spray-system compatibility captures Brazilian fertilizer automation retrofit demand. |
| Encapsulation Technology Development | Multi-function coatings command agricultural micronutrient premiums over commodity silicates. |
| Multi-Year Supply Agreements | Technical support bundling displaces spot purchasing in Southeast Asian processed food clusters. |
| Regional Compounding Capacity Expansion | Localized production in India PLI zones reduces import dependence for feed manufacturers. |
Study Parameters
Coverage spans Europe, Asia-Pacific, and the Americas, with primary inputs from each region combined with secondary validation. Interviews with plant managers at precipitated silica facilities, procurement leads at seasoning and dairy processors, distribution channel partners in feed corridors, and regulatory affairs directors at pharmaceutical excipient houses informed demand-side modeling. Secondary sources included EFSA additive re-evaluation databases, ECHA registration dossiers, customs trade flow data for soda ash and metallic stearates, and SEC filings from diversified chemical conglomerates. Bottom-up volume builds across grade tiers and applications triangulated against top-down market sizing from production capacity assessments.
Granularity extends to product type, application, form, and end-user dimensions, with additional modeling of regulatory compliance tier and automation equipment compatibility. Value projections across the analysis window derived from price-volume relationships segmented by certification grade and geographic delivery cost. CAGR derivation incorporated input cost trajectories for energy-linked soda ash production, PLI subsidy impacts on Indian manufacturing economics, and encapsulation technology adoption curves in agricultural coatings.
Underlying measurement precision varies by segment; pharmaceutical-grade magnesium stearate and ECHA-compliant precipitated silica carry tighter precision than commodity feed-grade sodium silicate. Forecasts reflect assumptions regarding EFSA evaluation timeline adherence, Brazilian fertilizer automation investment continuity, and Indian PLI scheme extension. Deviation in REACH nanomaterial enforcement stringency or ASEAN regulatory harmonization pace would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
South America Food Emulsifiers Market
Food Additives and Ingredients
Titanium-Free Food Color Alternatives Market
Food Additives and Ingredients
Dairy Starter Culture Market
Food Additives and Ingredients
Pea Starch Concentrate Market
Food Additives and Ingredients
Asia-Pacific Food Emulsifier Market
Food Additives and Ingredients
Europe Leavening Agents Market
Food Additives and Ingredients
India Food Colorants Market
Food Additives and Ingredients
Argentina Gellan Gum Market
Food Additives and Ingredients
Clean Label Emulsifiers Market
Food Additives and Ingredients
Protein Films Market
Food Additives and Ingredients
France Food Emulsifiers Market
Food Additives and Ingredients
Europe Food Enzymes Market
Food Additives and Ingredients
Beverage Stabilizer Market
Food Additives and Ingredients
Lime Oil Market
Food Additives and Ingredients
Flavor Encapsulation Market
Food Additives and Ingredients
China Emulsifiers Market