
 France Anti Caking Market | 2026-2036
France Anti Caking Market Size, Share, and Industry Trends Forecast 2026-2036
France Anti Caking Market Foresight
Technical advisory and formulation support is broadening what suppliers deliver beyond commodity powders. BASF SE leverages its polymer science heritage to anchor premium positions in pharmaceutical-grade silicas. Roquette Frères sustains channel control through plant-derived alternatives that appeal to clean-label formulators. Evonik Industries AG dominates specialized precipitated silica for hygroscopic drug matrices.
Anti-caking agents are powdered or granular additives, typically composed of silica-based compounds, stearate salts, or aluminosilicates, that absorb moisture or coat particle surfaces to prevent agglomeration in bulk solids. These materials function through capillary action, surface film formation, or electrostatic charge modification, with primary commercial purpose spanning food powders, detergent granules, pharmaceutical tablets, and fertilizer blends. Calcium silicate and silica gel command the largest volume positions due to established cost-performance ratios in food and detergent applications, while sodium aluminosilicate captures expanding share in pharmaceutical formulations where inertness and flow enhancement carry premium value. Magnesium stearate occupies a mature niche in tablet lubrication, with margin pools concentrating in compendial-grade certifications rather than commodity supply.
ANSM enforces pharmacopeial standards for excipient purity that filter subscale suppliers from pharmaceutical channels, while REACH compliance through ECHA governs chemical registration and hazard communication for all imported and manufactured anti-caking substances. The EU Green Deal's chemical sustainability targets are pressuring formulators to document biodegradability profiles and reduce synthetic additive loadings. Stakeholders must monitor how CSRD disclosure requirements reshape procurement criteria for food processing and pharmaceutical buyers evaluating supplier environmental footprints.
Market Dynamics
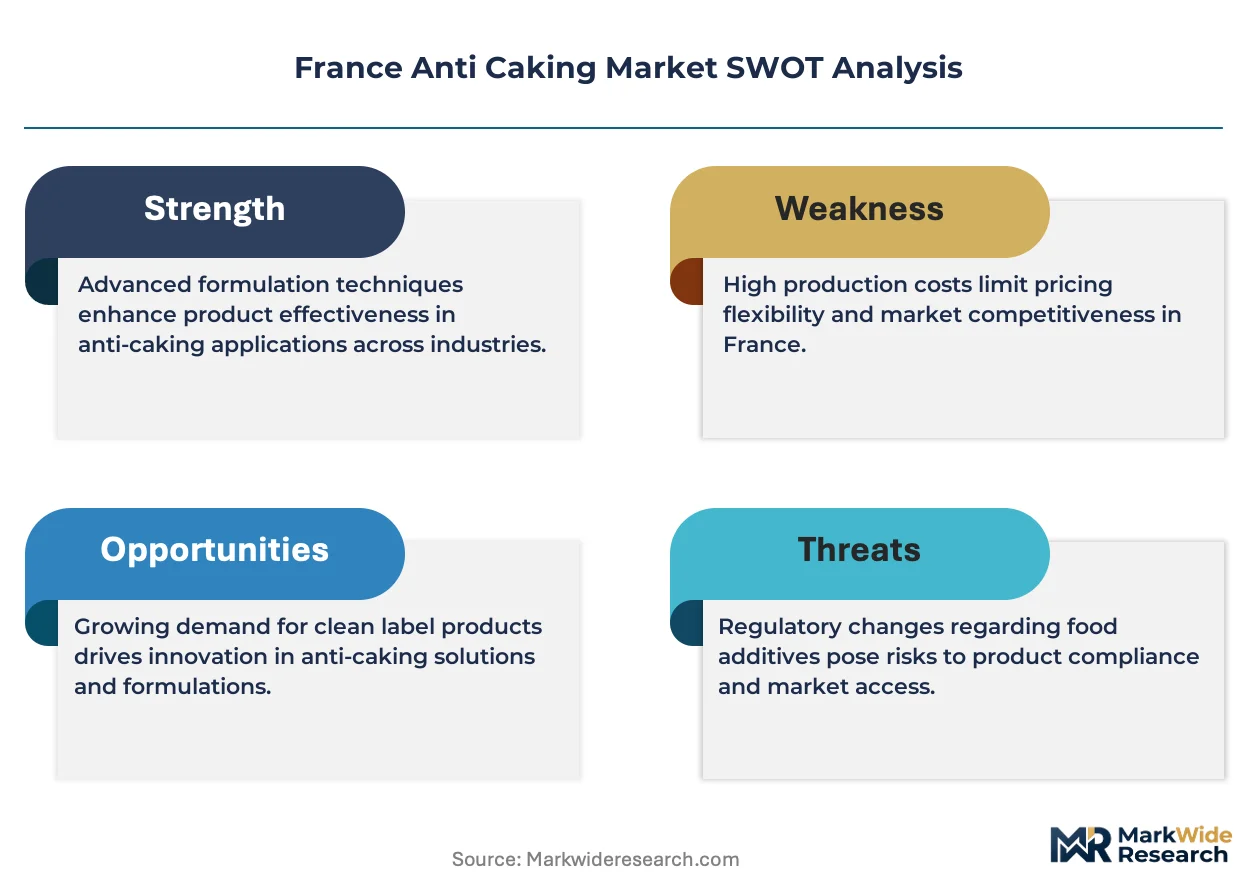
ANSM's tightening pharmacopeial purity benchmarks for pharmaceutical-grade excipients are compressing supplier margins while filtering subscale producers from Lyon corridor procurement channels. Food processors in Île-de-France simultaneously demand cleaner-label formulations, bifurcating procurement criteria across France's dual-use anti-caking market.
Growth Catalysts
- EU Green Deal chemical sustainability targets:Biodegradability documentation requirements are accelerating formulator investment in plant-derived alternatives for dairy and seasoning applications.
- Pharmaceutical corridor expansion:Lyon-based drug manufacturers are scaling hygroscopic matrix production, pulling specialized precipitated silica through ANSM-certified channels.
- Clean-label formulation mandates:Major retail chains across Auvergne-Rhône-Alpes are delisting synthetic additive SKUs, redirecting procurement toward mineral-salt and rice-husk based anti-caking solutions.
Market Restraints
- Petrochemical feedstock volatility:Synthetic silica production costs fluctuate with natural gas pricing, squeezing margin pools for commodity-grade suppliers serving detergent manufacturers.
- REACH registration concentration:ECHA compliance costs favor incumbent chemical conglomerates, raising barriers for regional French producers seeking pharmaceutical-grade market entry.
- Technical performance ceiling:Plant-derived alternatives exhibit inferior moisture absorption kinetics versus precipitated silica, limiting substitution rates in high-humidity pharmaceutical storage conditions.
Strategic Opportunities
- CSRD disclosure tailwinds:Mandatory environmental footprint reporting is creating preference premiums for suppliers with verified lifecycle assessments across pharmaceutical and food processing buyer segments.
- Provence-Alpes-Côte d'Azur food manufacturing:Underpenetrated seasoning and spice processing clusters offer expansion vectors for technical advisory-led formulation services.
- Biopolymer-silica hybrid convergence:Chitosan-coated silica particles are opening clean-label pharmaceutical applications previously closed to synthetic excipients.
Industry Challenges
- ANSM certification timelines:Pharmaceutical-grade excipient approval cycles now extend 18-24 months, freezing working capital and delaying revenue recognition for reformulated products.
- Compounding talent scarcity:Formulation chemists with dual expertise in food-grade mineral salts and pharmaceutical compendial standards command premium compensation in the Paris manufacturing belt.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Anti Caking Market |
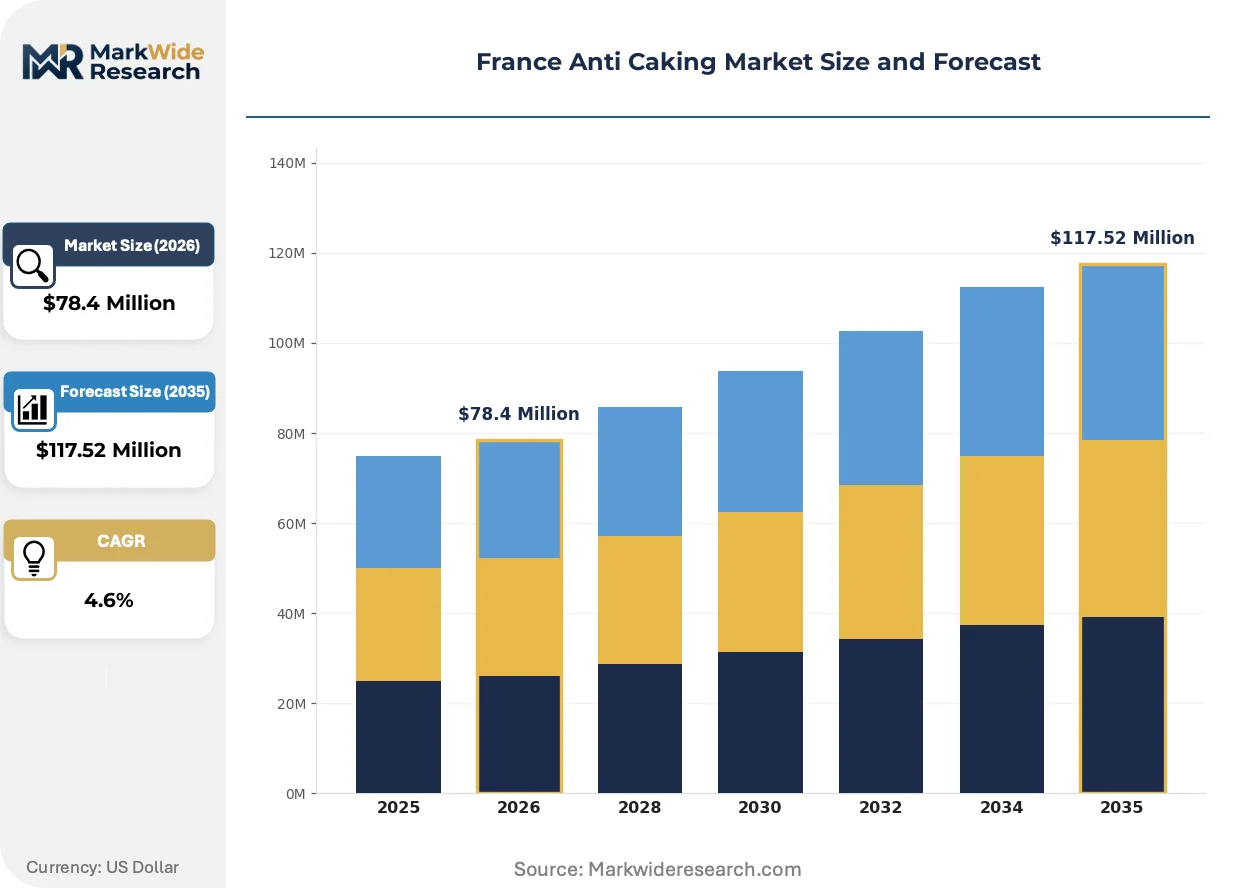
| Market Size in 2026 | $78.4 Million |
| Market Size in 2035 | $117.52 Million |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Calcium Silicate, Silica Gel, Talc, Magnesium Stearate, Sodium Aluminosilicate Application: Food Additives, Detergents, Pharmaceuticals, Fertilizers, Animal Feed End User Industry: Food Processing Companies, Chemical Manufacturers, Pharmaceutical Firms, Agriculture Suppliers, Feed Producers Packaging Type: Bulk Bags, Paper Bags, Plastic Containers, Drums, Cartons |
| Companies Covered | Merck KGaA, BASF SE, Kao Corporation, Roquette Frères, Evonik Industries AG, Arkema S.A., Tate & Lyle, Ingredion, Archer Daniels Midland Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Anti Caking Market Shifts & Advancements
Formulation science is converging with sustainability mandates across France's anti-caking supply base. Technical service bundling is displacing commodity trading, while regulatory disclosure requirements reshape how buyers evaluate supplier partnerships.
Surface-modified precipitated silica is consolidating its position as the dominant platform for hygroscopic pharmaceutical matrices. Lyon-based drug manufacturers are adopting these materials at accelerated pace for moisture-sensitive active ingredients. The technology is consolidating supplier relationships around technical advisory capabilities rather than spot purchasing.
ANSM's alignment with European Pharmacopoeia monograph updates is tightening heavy metal and microbial contamination thresholds for excipient-grade silicas. French pharmaceutical contract manufacturers now require batch-specific certificates of analysis exceeding baseline REACH documentation. Pediatric and geriatric tablet formulations face the steepest compliance cost escalations under revised purity benchmarks.
Ingredient co-development partnerships are replacing transactional procurement in major food processing accounts. Seasoning blenders in the Paris manufacturing belt now embed supplier technologists within NPD teams for accelerated clean-label reformulation. Auvergne-Rhône-Alpes dairy powder processors exhibit the most advanced collaborative sourcing models, with multi-year formulation agreements displacing annual tender cycles.
France Anti Caking Market Segmentation
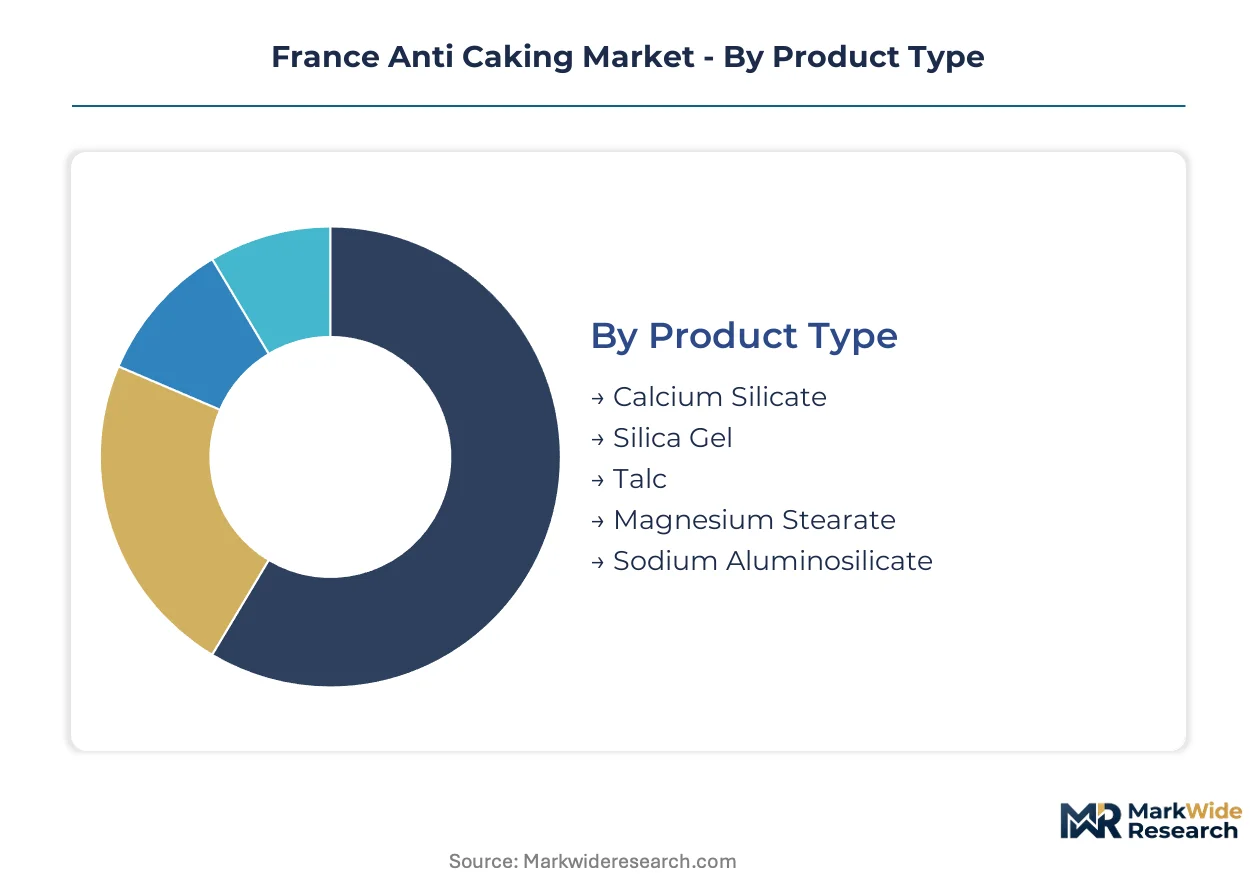
Anti-caking procurement in France fragments across certification tiers that reshape supplier economics. Pharmaceutical-grade channels demand ANSM-validated excipient purity, while food-grade segments prioritize clean-label positioning over compendial compliance.
Product Type:
ANSM pharmacopeial certification burdens concentrate on precipitated silicas and stearate salts, whereas mineral silicates face lighter REACH documentation through ECHA.
- Calcium Silicate:Porous calcium silicate absorbs moisture through capillary action in powdered seasonings and dairy blends. Seasoning processors in Île-de-France specify this mineral salt for cost-stable moisture control in high-throughput blending operations.
- Silica Gel:Amorphous precipitated silica delivers superior surface area for hygroscopic pharmaceutical matrices. Lyon corridor drug manufacturers pull specialized grades through ANSM-certified channels for moisture-sensitive active ingredients.
- Talc:Hydrous magnesium silicate serves as a glidant in tablet formulations with moderate moisture sensitivity.
- Magnesium Stearate:Compendial-grade stearate lubricant commands premium pricing tied to USP-NF certification cycles.
- Sodium Aluminosilicate:Synthetic zeolite structures expand in pharmaceutical flow enhancement where inertness carries formulation value.
Leading the category by volume: Calcium Silicate. Growing fastest: Silica Gel.
Application:
Margin pools diverge sharply between commodity detergent volumes and pharmaceutical excipient premiums.
- Food Additives:Clean-label mandates from Auvergne-Rhône-Alpes retail chains are delisting synthetic additive SKUs, redirecting procurement toward rice-husk and mineral-salt alternatives.
- Detergents:Synthetic silica loadings in powder detergents face margin compression from natural gas feedstock volatility.
- Pharmaceuticals:ANSM alignment with European Pharmacopeia monographs tightens heavy metal thresholds for excipient-grade materials.
- Fertilizers:Bulk mineral silicates prevent caking in ammonium nitrate and urea blends during humid storage.
- Animal Feed:Feed-grade anti-caking agents require veterinary regulatory clearance distinct from food additive pathways.
Highest volume concentration: Food Additives. Steepest expansion trajectory: Pharmaceuticals.
End User Industry:
Procurement sophistication separates pharmaceutical contract manufacturers from commodity agriculture buyers.
- Food Processing Companies:Paris manufacturing belt seasoning blenders now embed supplier technologists within NPD teams for accelerated clean-label reformulation cycles.
- Chemical Manufacturers:Detergent formulators in northern France negotiate silica supply on spot pricing indexed to natural gas benchmarks.
- Pharmaceutical Firms:Lyon-based drug manufacturers require batch-specific certificates of analysis exceeding baseline REACH documentation.
- Agriculture Suppliers:Fertilizer distributors prioritize bulk logistics efficiency over formulation technical service.
- Feed Producers:Compound feed manufacturers face distinct regulatory pathways through the country's veterinary pharmaceutical regulator.
Dominant demand source: Food Processing Companies. Procurement sophistication leader: Pharmaceutical Firms.
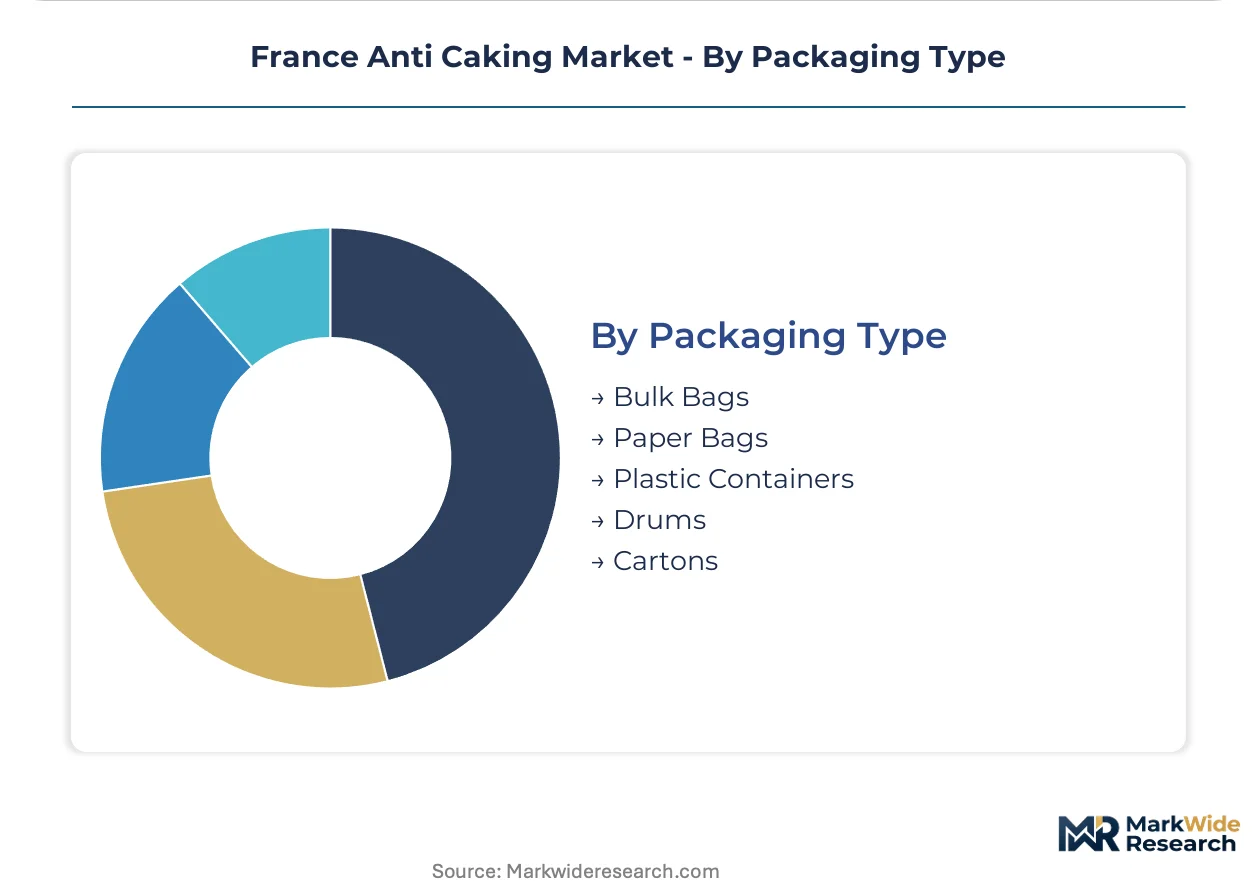
Packaging Type:
Packaging selection tracks handling automation levels and contamination risk thresholds across user segments.
- Bulk Bags:Flexible intermediate bulk containers dominate fertilizer and detergent volume movements through Rouen port logistics.
- Paper Bags:Multi-wall paper sacks serve food-grade mineral salts where moisture barrier requirements remain moderate.
- Plastic Containers:Sealed polypropylene pails protect pharmaceutical-grade silicas from humidity ingress during extended storage.
- Drums:Steel and fiber drums handle liquid anti-caking suspensions and high-purity excipient powders.
- Cartons:Retail-format cartons package consumer-facing seasoning blends with pre-metered additive sachets.
Volume leader: Bulk Bags. Premium positioning: Plastic Containers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France produces anti-caking agents at concentrated chemical manufacturing sites while consumption clusters around pharmaceutical and food processing corridors. This production-consumption divide shapes logistics networks and supplier technical service deployment.
Île-de-France
Seasoning blenders and dairy powder processors in the Paris manufacturing belt drive food-grade silica demand. ANSM food additive regulations intersect with EU Green Deal sustainability targets here. Major retail chains headquartered in the region enforce clean-label procurement standards that filter supplier pools.
Auvergne-Rhône-Alpes
Lyon-based pharmaceutical contract manufacturers scale hygroscopic matrix production for moisture-sensitive active ingredients. REACH compliance through ECHA governs excipient-grade material imports. The pharmaceutical corridor concentrates specialized precipitated silica procurement through ANSM-certified channels.
Provence-Alpes-Côte d'Azur
Underpenetrated seasoning and spice processing clusters offer expansion vectors for technical advisory-led formulation services. CSRD disclosure requirements reshape how regional food manufacturers evaluate supplier environmental footprints. Marseille port logistics support bulk mineral silicate movements for fertilizer applications.
Hauts-de-France
Detergent manufacturers negotiate synthetic silica supply on spot pricing indexed to natural gas benchmarks. Petrochemical feedstock volatility squeezes margin pools for commodity-grade suppliers. Lille chemical processing sites anchor northern production capacity for calcium silicate.
Nouvelle-Aquitaine
Agricultural fertilizer distributors prioritize bulk logistics efficiency over formulation technical service. The country's veterinary pharmaceutical regulator oversees distinct feed-grade anti-caking pathways. Bordeaux agribusiness clusters sustain steady mineral silicate consumption for compound feed manufacturing.
France Anti Caking Market Competitive Landscape
Top-tier vendors anchor pharmaceutical-grade excipient supply, while regional mineral salt processors serve commodity food and fertilizer segments. The market exhibits tiered concentration around certification capabilities rather than scale alone. Strategic archetypes include polymer science heritage conglomerates, plant-derived alternative specialists, and precipitated silica technology leaders. Capacity expansion and formulation co-development partnerships represent the dominant competitive moves reshaping supplier relationships.
Within the polymer science tier, BASF SE and Evonik Industries AG occupy positions reflecting German chemical engineering heritage applied to pharmaceutical-grade silica platforms. Roquette Frères exemplifies the plant-derived alternative archetype rooted in French agro-industrial expertise. Merck KGaA anchors the premium excipient segment through compendial-grade certification depth. These three entities represent distinct strategic vectors—synthetic precision, botanical sourcing, and pharmacopeial compliance—that structure competitive positioning across ANSM-regulated channels.
| Leading Market Players |
|---|
| Merck KGaA |
| BASF SE |
| Kao Corporation |
| Roquette Frères |
| Evonik Industries AG |
| Arkema S.A. |
| Tate & Lyle |
| Ingredion |
| Archer Daniels Midland Company |
| Others |
Supply & Pricing Matrix
Captive silica production by German chemical conglomerates anchors supply positions and pricing power across ANSM-regulated pharmaceutical channels. This integration choice insulates premium-grade suppliers from feedstock volatility while compressing margins for commodity mineral salt processors serving Île-de-France food manufacturers.
Pricing Analysis
Margin tightening in pharmaceutical-grade silicas reflects ANSM certification cost escalation and extended approval timelines. Three-tier pricing structure across compendial, food-grade, and technical mineral tiers separates buyers by purity requirements and documentation depth. Cost-down pressure on synthetic silica accelerates because natural gas feedstock volatility squeezes detergent-grade suppliers in Hauts-de-France. Chemical manufacturers exhibit highest price sensitivity; Lyon-based drug manufacturers accept premium positioning for batch-specific analytical certificates.
Supply Chain Analysis
Single-source vulnerability sits with German precipitated silica suppliers dominating ANSM-certified pharmaceutical channels. Manufacturing concentrates in Germany, Belgium, and domestic sites near Lille. Raw material flows draw from sodium silicate feedstocks, natural gas energy inputs, and specialized precipitation reagents. Tariff exposure on imported excipient-grade materials threatens margin stability for French pharmaceutical contract manufacturers. Distribution runs through certified chemical distributors with cold-chain humidity controls for hygroscopic matrices.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story. ANSM pharmacopeial certification cycles create an 18-24 month barrier-to-entry moat that filters subscale competitors and concentrates margin pools among established excipient suppliers.
For Market Incumbents: Hedge against plant-derived substitution by embedding formulation chemists within Auvergne-Rhône-Alpes dairy processor NPD teams. Deepen backward integration into sodium silicate feedstocks to insulate margin pools from natural gas volatility threatening Hauts-de-France commodity production. Prioritize CSRD-compliant lifecycle documentation to capture preference premiums from Paris-based retail procurement committees. For New Entrants and Emerging Players: The premium-to-economy price gap in pharmaceutical-grade silicas creates entry space for hybrid biopolymer-mineral platforms. Provence-Alpes-Côte d'Azur seasoning clusters offer the most penetrable geography with underdeveloped technical advisory coverage. Lead with chitosan-coated silica co-development partnerships rather than commodity spot supply to bypass ANSM certification timeline disadvantages. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to polymer science conglomerates seeking ANSM-certified channel access. Long-term viability hinges on differentiation through regulatory compliance depth rather than scale alone. Watch for CSRD disclosure mandate acceleration as the inflection signal that reweights procurement criteria toward verified environmental footprint suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| ANSM Certification Investment | Extended approval timelines filter competitors and lock in pharmaceutical corridor relationships. |
| Plant-Derived Alternative Development | Roquette Frères demonstrates channel control through rice-husk silica appealing to clean-label formulators. |
| Technical Advisory Service Bundling | Paris manufacturing belt seasoning blenders now embed supplier technologists within NPD teams. |
| CSRD-Compliant Lifecycle Documentation | Mandatory environmental footprint reporting creates preference premiums across buyer segments. |
| Provence-Alpes-Côte d'Azur Expansion | Underpenetrated spice processing clusters offer technical advisory-led formulation service vectors. |
Research Methodology
Multi-period observation of ANSM certification timelines, REACH registration concentrations, and clean-label procurement shifts anchored the trend analysis, supplemented by interviews with pharmaceutical excipient procurement managers, food processing R&D directors, chemical distributor account executives, and detergent manufacturing plant managers. Secondary validation drew from ECHA registration databases, ANSM pharmacopeial monograph updates, EU Green Deal policy documentation, and SEC filings of listed chemical conglomerates. Bottom-up volume modeling triangulated against top-down value estimates from trade flow analysis.
Segment-weighting across product type, application, end-user industry, and packaging format structured the analytical framework. Grade tier, regional production hub, and certification level provided cross-cutting segmentation dimensions. CAGRs were derived from fitted growth curves applied to base-year observations, with pharmaceutical-grade silica premiums and natural gas feedstock indices serving as key forecast inputs across the projection horizon.
Inputs from ECHA registration databases and ANSM approval records were available through the study window; gaps in real-time pharmaceutical contract manufacturer inventory data introduce uncertainty bands around near-term volume estimates. Forecasts reflect documented assumptions about regulatory timeline stability and feedstock price regime continuity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Europe Food Enzymes Market
Food Additives and Ingredients
Brazil Food Additives Market
Food Additives and Ingredients
Trans Fatty Acids Market
Food Additives and Ingredients
Food Phosphate Market
Food Additives and Ingredients
United States Feed Additives Market
Food Additives and Ingredients
Tapioca Starch Market
Food Additives and Ingredients
China Food Acidulants Market
Food Additives and Ingredients
Disodium Cocoamphodiacetate Market
Food Additives and Ingredients
United States Anti-Caking Market
Food Additives and Ingredients
Agar Agar Gum Market
Food Additives and Ingredients
Oleic Acid Market
Food Additives and Ingredients
Plant-Based Emulsifiers Market
Food Additives and Ingredients
Global Crystalline Maltitol Market
Food Additives and Ingredients
Protein Films Market
Food Additives and Ingredients
Canada Food Preservatives Market
Food Additives and Ingredients
South America Food Acidulants Market