
 Russia Anti Caking Market | 2026-2036
Russia Anti Caking Market Size, Share, and Industry Trends Forecast 2026-2036
Russia Anti Caking Market Analytics
TR CU 029/2012 is consolidating the cost-of-entry calculus for foreign and domestic anti-caking suppliers seeking Russian food-grade certification. BASF SE leverages its global R&D infrastructure to sustain compliance with evolving Eurasian Economic Union technical regulations. Evonik Industries AG anchors its position through specialized silica manufacturing capabilities aligned with Russian industrial standards.
Anti-caking agents are powdered or granular substances, typically composed of silicon dioxide, calcium carbonate, or sodium-based compounds, that prevent particle agglomeration by absorbing moisture or creating physical barriers between crystalline surfaces. These materials maintain free-flowing properties in hygroscopic products during storage, transport, and processing across food, pharmaceutical, and agricultural applications. Silica dominates product-type revenue due to its superior moisture-absorption capacity and broad regulatory acceptance, while calcium carbonate segments expand fastest among fertilizer manufacturers seeking cost-effective flow control. Food Industry applications command premium positioning through stringent purity requirements, whereas Chemicals applications operate on volume-driven margin structures with lower specification thresholds.
Russia's Federal Service for Surveillance on Consumer Rights Protection and Human Wellbeing (Rospotrebnadzor) enforces TR CU standards for food-contact substances, while the Ministry of Industry and Trade oversees domestic chemical production quotas affecting anti-caking raw material availability. Compliance with GOST national standards and EAC conformity marking determines market access for imported formulations. Stakeholders must monitor proposed amendments to technical regulations governing food additive purity thresholds and anticipate how import substitution policies reshape competitive dynamics for domestic versus foreign supply sources.
Market Dynamics
TR CU 029/2012 compliance requirements are restructuring certification pathways for food-grade anti-caking agents, elevating technical barriers while creating protected niches for domestic manufacturers with established GOST laboratory networks.
Growth Catalysts
- Fertilizer sector expansion:Silica-based anti-caking consumption accelerates in the Volga Federal District as nitrogen and compound fertilizer producers scale output for Black Sea export corridors.
- TR CU 029/2012 harmonization:Unified Eurasian Economic Union technical regulations reduce duplicate testing costs for cross-border formulations entering Belarus and Kazakhstan markets.
- Moscow Oblast food processing:Concentrated demand from dairy powder and seasoning manufacturers drives premium-grade silica purchases with stringent moisture-absorption specifications.
Market Restraints
- Import dependency for high-purity silica:Domestic precipitated silica capacity remains concentrated among three specialized producers, creating supply vulnerability during equipment maintenance cycles.
- TR CU certification timeline:Rospotrebnadzor food-contact substance approvals require 14-18 month evaluation periods, freezing product launches for reformulated grades.
- Calcium carbonate substitution:Fertilizer manufacturers in cost-sensitive segments increasingly blend lower-cost mineral carriers, compressing silica volume in non-critical flow applications.
Strategic Opportunities
- Siberian Federal District underpenetration:Grain processing and oilseed crushing facilities in Novosibirsk and Omsk oblasts lack localized anti-caking distribution, creating first-mover advantages for regional logistics investments.
- Organic-certified food additives:EAC conformity marking for organic-grade anti-caking agents opens premium positioning as Russian retailers expand natural product assortments under federal organic labeling law.
- Pharmaceutical excipient crossover:Tablet disintegrant and powder flow applications in St. Petersburg's generic drug manufacturing cluster represent adjacent demand with higher margin structures than agricultural segments.
Industry Challenges
- Analytical chemistry talent scarcity:GOST method proficiency for silica purity verification requires specialized spectroscopy training unavailable in regional technical universities.
- Legacy equipment retrofit costs:Soviet-era mixing and coating infrastructure in mid-tier fertilizer plants cannot achieve TR CU-mandated contamination thresholds without capital-intensive pneumatic system upgrades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Russia Anti Caking Market |
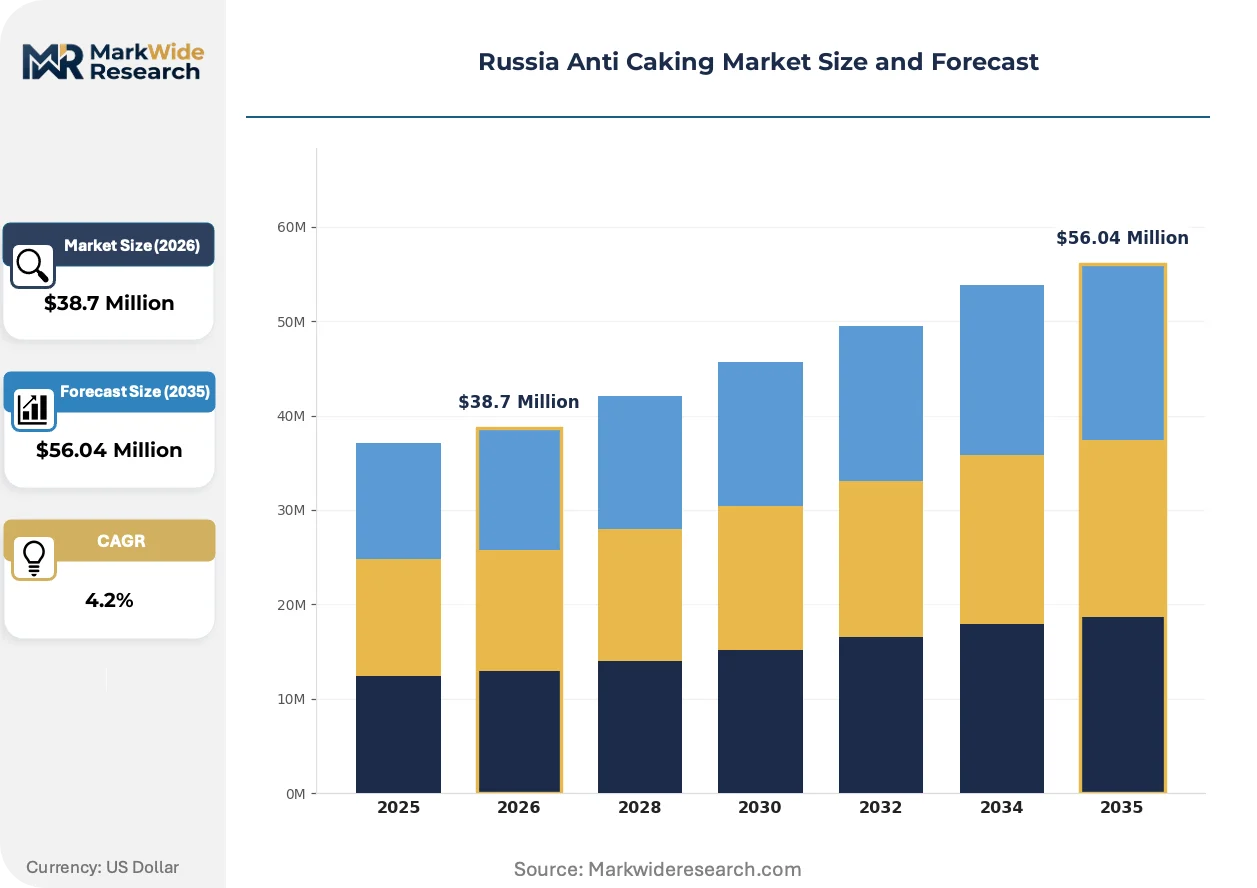
| Market Size in 2026 | $38.7 Million |
| Market Size in 2035 | $56.04 Million |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silica, Talc, Sodium Bicarbonate, Calcium Carbonate Application: Food Industry, Pharmaceuticals, Chemicals, Coatings End User: Manufacturers, Distributors, Retailers, Exporters Distribution Channel: Online Retail, Wholesale, Direct Sales, Third-Party Retail |
| Companies Covered | Corbion NV, BASF SE, Kao Corporation, Huber Engineered Materials, Kerry Group plc, Zhengzhou Natural Chemical Co Ltd, Evonik Industries AG, PPG Industries, Solvay, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Russia Anti Caking Market Evolving Landscape
Surface-modified silica technologies and regulatory harmonization across the Eurasian Economic Union are reconfiguring product development priorities and procurement specifications for Russian anti-caking suppliers.
Nano-structured precipitated silica with controlled pore distribution is expanding into instant beverage and soup powder applications. Moscow-based food technologists are adopting these grades to replace conventional fumed silica in hygroscopic formulations. This material transition is expanding into premium export-oriented production lines as manufacturers seek EFSA-recognized additive codes for EU-bound goods.
TR CU 029/2012 amendments proposed by the Eurasian Economic Commission are tightening residual solvent limits for anti-caking agent manufacturing processes. Russian producers must validate drying and purification protocols against revised maximum permissible concentrations. Food-grade silica manufacturers in the Central Federal District are pre-emptively retrofitting spray-dryer exhaust systems to secure uninterrupted certification continuity.
Direct procurement relationships between fertilizer conglomerates and silica producers are displacing layered distributor networks in the Volga region. Large nitrogen compound manufacturers now negotiate annual volume contracts with technical specifications attached. This channel consolidation is most visible in Tatarstan and Samara Oblast, where three processors account for the majority of agricultural-grade anti-caking offtake.
Russia Anti Caking Market Segmentation
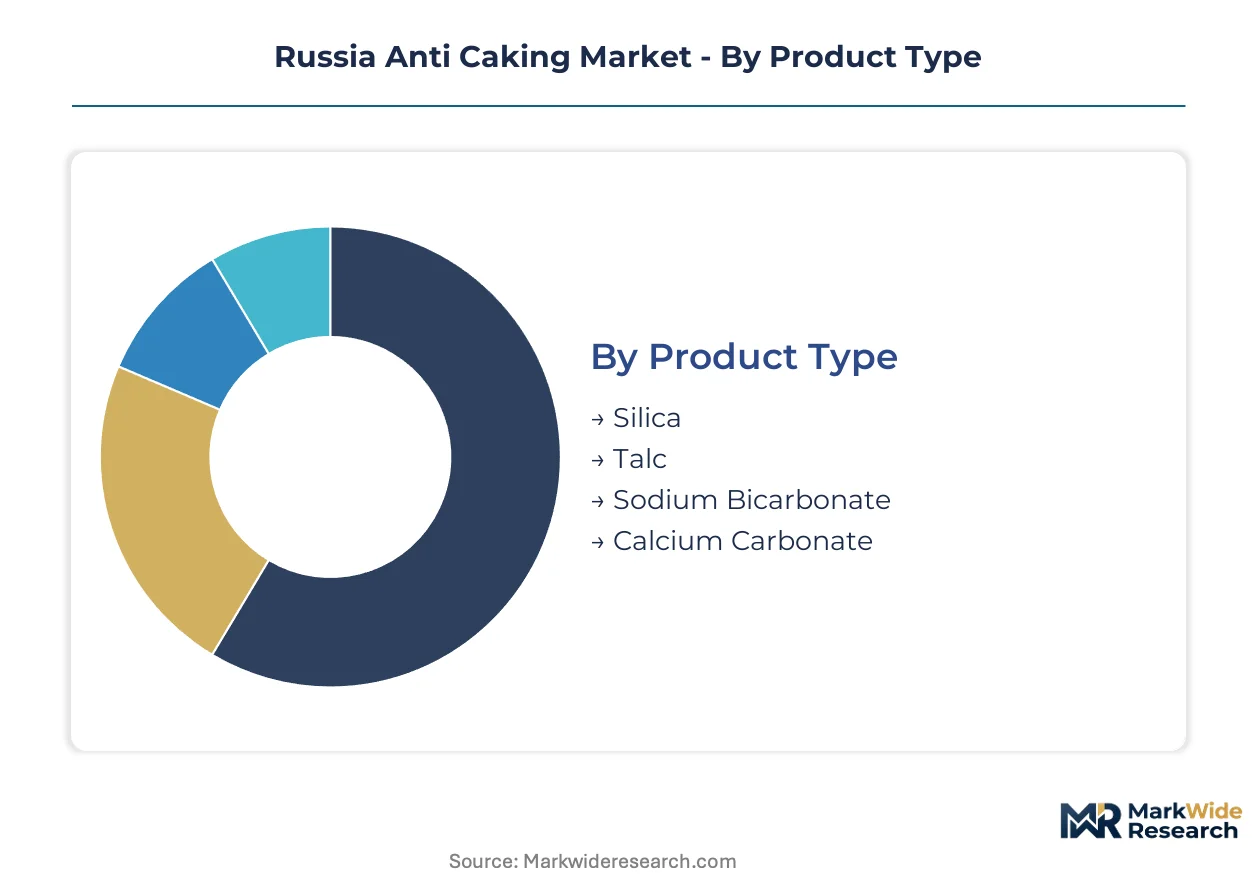
Segmentation in Russia's anti-caking market reveals how capital deployment, regulatory compliance, and logistics infrastructure fragment procurement patterns across product grades and customer tiers. Understanding these divisions exposes where margin pools concentrate and which channels offer defensible positioning.
Product Type:
Capital intensity varies sharply across manufacturing technologies, with precipitated silica requiring spray-dryer investments that dwarf mineral grinding operations.
- Silica:Precipitated and fumed grades dominate premium food and pharmaceutical applications through superior moisture-absorption capacity. Moscow Oblast dairy powder processors specify silica with controlled pore distribution for instant formulation stability.
- Calcium Carbonate:Ground and precipitated variants serve cost-sensitive fertilizer flow control in the Volga Federal District. Samara and Tatarstan nitrogen compound manufacturers blend this mineral carrier to reduce per-ton anti-caking expenditure.
- Talc:Lamellar magnesium silicate structures provide physical barrier properties in agricultural coatings and select food applications requiring inert mineral certification.
- Sodium Bicarbonate:Water-soluble anti-caking functionality targets specialty seasoning and leavening agent formulations with dissolution-rate specifications.
Silica absorbs the bulk of installed capacity; calcium carbonate is expanding most quickly.
Application:
Margin structures diverge based on purity thresholds and certification burden, with food and pharmaceutical commanding triple-digit basis point premiums over industrial segments.
- Food Industry:TR CU 029/2012 mandates Rospotrebnadzor approval for all food-contact silica grades. Instant beverage and soup powder manufacturers in the Central Federal District drive specification intensity for nano-structured precipitated variants.
- Chemicals:Fertilizer anti-caking operates on volume-driven procurement with lower moisture-absorption thresholds. Volga Federal District nitrogen producers negotiate annual contracts directly with silica manufacturers, displacing distributor layers.
- Pharmaceuticals:Tablet disintegrant and powder flow applications in St. Petersburg's generic drug cluster require GMP-aligned excipient documentation with higher analytical chemistry overhead.
- Coatings:Agricultural seed and industrial surface treatments utilize talc and calcium carbonate blends where optical properties and cost minimization outweigh absorption performance.
Food industry applications capture the widest margin spread; pharmaceutical represents the steepest expansion trajectory.
End User:
Procurement sophistication scales with formulation complexity and export orientation, separating price-takers from specification-setters.
- Manufacturers:Integrated food and chemical processors with in-house quality laboratories negotiate technical specifications directly. These buyers dominate silica offtake in Moscow Oblast and Tatarstan.
- Distributors:Regional logistics specialists bridge supply gaps in Siberian Federal District grain processing clusters where localized anti-caking distribution remains underdeveloped.
- Retailers:Private-label seasoning and baking mix brands procure blended anti-caking systems through formulated ingredient suppliers rather than raw material direct.
- Exporters:Black Sea corridor fertilizer producers and EU-bound food manufacturers dual-certify against TR CU and EFSA additive codes, adding compliance cost layers.
Manufacturers command the deepest supplier relationships; exporters are gaining share fastest through certification-differentiated sourcing.
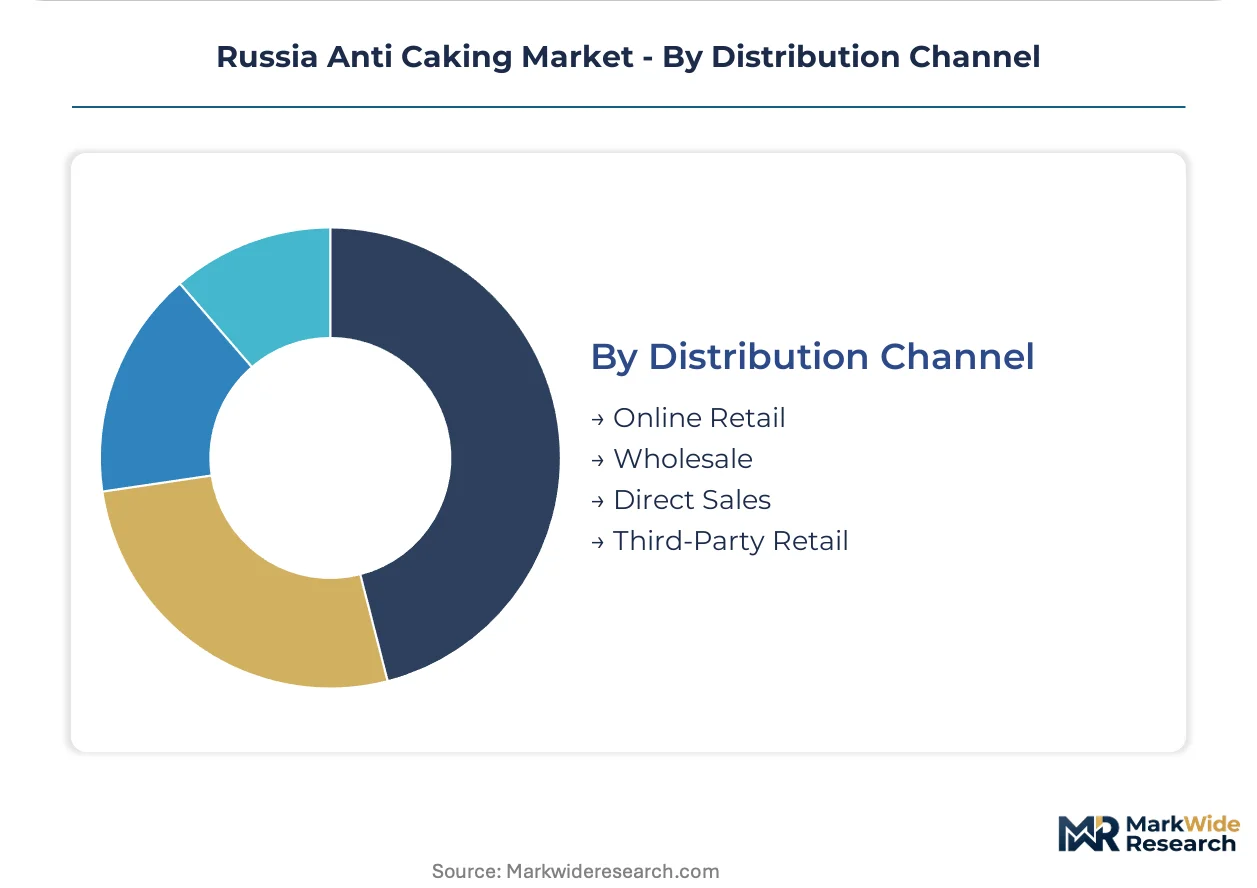
Distribution Channel:
Channel economics reflect shipment density, technical service requirements, and working capital intensity across customer tiers.
- Direct Sales:Annual volume contracts with attached technical specifications dominate agricultural-grade silica movement in the Volga region. Tatarstan and Samara Oblast fertilizer conglomerates consolidated procurement through this channel.
- Wholesale:Regional distributors maintain inventory positions for mid-tier food processors lacking laboratory infrastructure for incoming material verification.
- Online Retail:Specialty chemical marketplaces serve small-batch pharmaceutical and R&D customers with documented COA availability and fractional tonnage flexibility.
- Third-Party Retail:Formulated ingredient suppliers bundle anti-caking agents into complete seasoning and leavening systems for retail private-label programs.
Direct sales lock in the majority of tonnage movement; online retail is climbing the fastest among channel investments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Technopolis Moscow and special economic zones in Tatarstan concentrate anti-caking agent distribution infrastructure through tax-incentivized logistics hubs serving Central Federal District food processors.
Central Federal District
Moscow Oblast dairy powder and instant beverage manufacturers drive premium-grade silica consumption with stringent moisture-absorption specifications. Rospotrebnadzor enforces TR CU 029/2012 certification timelines averaging 14-18 months for new food-contact formulations. Technopolis Moscow hosts consolidated distribution centers supplying seasoning and leavening agent processors in the capital region.
Volga Federal District
Tatarstan and Samara Oblast nitrogen compound fertilizer producers anchor agricultural-grade anti-caking demand for Black Sea export corridors. The Ministry of Industry and Trade oversees domestic chemical production quotas affecting precipitated silica raw material flows. Kazan and Tolyatti industrial clusters direct procurement through annual volume contracts displacing traditional distributor networks.
Northwestern Federal District
St. Petersburg's generic drug manufacturing cluster generates pharmaceutical excipient demand for tablet disintegrant and powder flow applications. GMP-aligned documentation requirements from the Federal Service for Surveillance in Healthcare impose higher analytical chemistry overhead than agricultural segments. The city anchors crossover opportunities between food-grade and pharmaceutical anti-caking specifications.
Siberian Federal District
Novosibirsk and Omsk oblasts grain processing and oilseed crushing facilities lack localized anti-caking distribution networks. Federal programs targeting import substitution in agricultural inputs create procurement incentives for regional logistics investments. First-mover advantages accrue to suppliers establishing inventory positions in underpenetrated Siberian markets.
Southern Federal District
Rostov Oblast fertilizer blending operations and food processing clusters near Black Sea ports dual-certify against TR CU and EFSA additive codes for EU-bound exports. Customs infrastructure at Novorossiysk supports time-sensitive silica shipments requiring documentation alignment across regulatory jurisdictions. The region captures cross-border trade flows linking Eurasian Economic Union and international markets.
Russia Anti Caking Market Competitive Landscape
German producers anchor one tier; Chinese specialists hold cost-advantaged positions in mineral-grade supply. The vendor base separates into three tiers: multinational chemical conglomerates with integrated silica manufacturing, regional distributors bridging supply gaps in underpenetrated federal districts, and commodity mineral processors serving price-sensitive fertilizer applications. Competitive dynamics center on TR CU certification speed and direct procurement relationship cultivation with Volga fertilizer conglomerates.
Within the multinational tier, BASF SE and Evonik Industries AG exemplify integrated producers leveraging global R&D infrastructure for Eurasian Economic Union regulatory alignment. Kerry Group plc occupies a position representing food ingredient specialists bundling anti-caking agents into complete formulation systems. Huber Engineered Materials and Solvay sit within the mineral processing archetype serving agricultural flow-control applications where cost minimization outweighs absorption performance thresholds.
| Leading Market Players |
|---|
| Corbion NV |
| BASF SE |
| Kao Corporation |
| Huber Engineered Materials |
| Kerry Group plc |
| Zhengzhou Natural Chemical Co Ltd |
| Evonik Industries AG |
| PPG Industries |
| Solvay |
| Others |
Value Network & Pricing Analysis
Direct procurement consolidation among Volga Federal District fertilizer conglomerates is compressing distributor margins and forcing silica manufacturers toward annual volume contracts with technical specifications attached. This buyer-driven restructuring elevates price transparency while penalizing spot-market premiums for non-contracted tonnage.
Pricing Analysis
Short lead-time premiums for food-grade silica in Moscow Oblast run above standard contract pricing as Rospotrebnadzor certification delays create supply bottlenecks for urgent formulations. Three-tier pricing structure across pharmaceutical-grade, food-grade, and agricultural-grade silica separates premium moisture-absorption specifications from cost-minimized fertilizer flow control. Price differentiation hinges on TR CU 029/2012 compliance status and GOST laboratory verification capacity. Cost compression in agricultural-grade segments is intensifying because calcium carbonate substitution erodes silica volume in non-critical applications. Fertilizer manufacturers exhibit highest price sensitivity; pharmaceutical excipient buyers accept premium positioning for GMP-aligned documentation.
Supply Chain Analysis
Specialized spectroscopy talent scarcity in Central Federal District manufacturing clusters constrains domestic precipitated silica expansion and perpetuates import dependency for high-purity grades. Supply concentrates in Germany, China, and domestic Central Federal District production facilities. Raw material flows draw from sodium silicate feedstock, sulfuric acid reagents, and specialized filtration membranes. Single-source vulnerability persists for pharmaceutical-grade precipitated silica where three domestic producers control installed capacity. Distribution runs through direct annual contracts with Volga fertilizer conglomerates, displacing layered distributor networks in agricultural segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Russia's anti-caking market sits in a technology-transition phase as nano-structured precipitated silica displaces conventional fumed silica in instant beverage and soup powder applications. This material substitution demands recalibrated certification pathways and manufacturing protocols.
For Market Incumbents: Extend GOST laboratory network capabilities to preempt TR CU 029/2012 amendment compliance deadlines and secure certification continuity for surface-modified silica grades. Anchor backward integration into sodium silicate feedstock production to insulate margin structures from raw material volatility. Threat of calcium carbonate substitution in fertilizer segments demands premium positioning reinforcement through technical service bundling. For New Entrants and Emerging Players: E-commerce chemical marketplaces offer fractional tonnage flexibility and documented COA availability for small-batch pharmaceutical and R&D customers lacking legacy distributor relationships. White-space targets concentrate in Siberian Federal District grain processing clusters where localized anti-caking distribution remains underdeveloped. Novosibirsk and Omsk oblasts present first-mover logistics advantages for regional inventory positioning. For Investors and Strategic Acquirers: The window for entry favors domestic manufacturers with established GOST verification infrastructure and Rospotrebnadzor regulatory relationships. Long-term viability rests on certification speed advantages and direct procurement consolidation with Volga fertilizer conglomerates. Signal to monitor: proposed TR CU 029/2012 residual solvent limit amendments and their capital intensity implications for spray-dryer retrofit requirements.| Strategic Initiative | Industry Significance |
|---|---|
| TR CU Certification Pre-Investment | Spray-dryer exhaust retrofits in Central Federal District secure uninterrupted food-grade silica approval continuity. |
| Siberian Distribution Network Buildout | Regional logistics investments in Novosibirsk capture grain processing demand lacking localized supply infrastructure. |
| Pharmaceutical Excipient Crossover | GMP-aligned documentation investments in St. Petersburg unlock higher-margin tablet disintegrant applications. |
| Direct Procurement Relationship Cultivation | Annual volume contracts with Tatarstan nitrogen producers displace distributor layers and lock in agricultural offtake. |
| Organic-Certified Grade Development | EAC conformity marking for organic-grade variants aligns with federal organic labeling law expansion in retail channels. |
Research Methodology
Independent corroboration across primary interviews with plant managers at precipitated silica facilities, procurement leads at Volga fertilizer conglomerates, distribution channel partners in Central Federal District logistics hubs, and technical R&D directors at food processing laboratories underwrites the qualitative findings. Secondary validation draws from customs and trade data, Eurasian Economic Commission regulatory filings, SEC disclosures from multinational chemical conglomerates, and GOST standard documentation. Bottom-up volume estimates from individual production facilities reconcile with top-down market sizing from end-use consumption patterns.
Comparable-period anchoring to historical fertilizer output cycles and food processing capacity expansions structures the projection framework across the analysis window. Segmentation dimensions span product grade tier, end-use industry application, regional production hub concentration, and certification status. CAGRs derive from trend extrapolation of silica consumption intensity per ton of nitrogen compound output and dairy powder formulation specifications. Forecast inputs incorporate TR CU 029/2012 amendment timelines and import substitution policy trajectories.
The model holds under stable regulatory enforcement and continued Eurasian Economic Union technical harmonization; deviation in TR CU amendment severity or raw material import restriction intensity would shift capacity expansion assumptions. Forecasts reflect documented base conditions and scenario-weighted probability assessments. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Food Grade Stearic Acid Market
Food Additives and Ingredients
Africa Food Stabilizers Market
Food Additives and Ingredients
Global Edible Films and Coatings for Fruits and Vegetables Market
Food Additives and Ingredients
Soft Drink Ingredients Market
Food Additives and Ingredients
Argentina Gellan Gum Market
Food Additives and Ingredients
Italy Sodium Reduction Ingredients Market
Food Additives and Ingredients
Sucroglycerides Market
Food Additives and Ingredients
South America Brewing Enzymes Market
Food Additives and Ingredients
Gelatin Films Market
Food Additives and Ingredients
Beverage Clouding Agent Market
Food Additives and Ingredients
Scrambled Egg Mix Market
Food Additives and Ingredients
China Emulsifiers Market
Food Additives and Ingredients
Neohesperidin Market
Food Additives and Ingredients
France Adjuvants Market
Food Additives and Ingredients
Disodium Cocoamphodiacetate Market
Food Additives and Ingredients
Egg Wash Substitute Market