
 Food Fungal Enzyme Market | 2026-2036
Food Fungal Enzyme Market Size, Share, and Industry Trends Forecast 2026-2036
Food Fungal Enzyme Market Analytics
Food-grade enzyme certification tiers above FCC and JECFA thresholds is rotating procurement standards toward higher-purity fungal strains. Novonesis Group leverages its merged biosolutions platform to dominate pharmaceutical-grade enzyme supply chains. dsm-firmenich anchors European demand through its specialized fermentation complexes in the Netherlands. AB Enzymes competes on baking-specific protease portfolios across artisan and industrial channels.
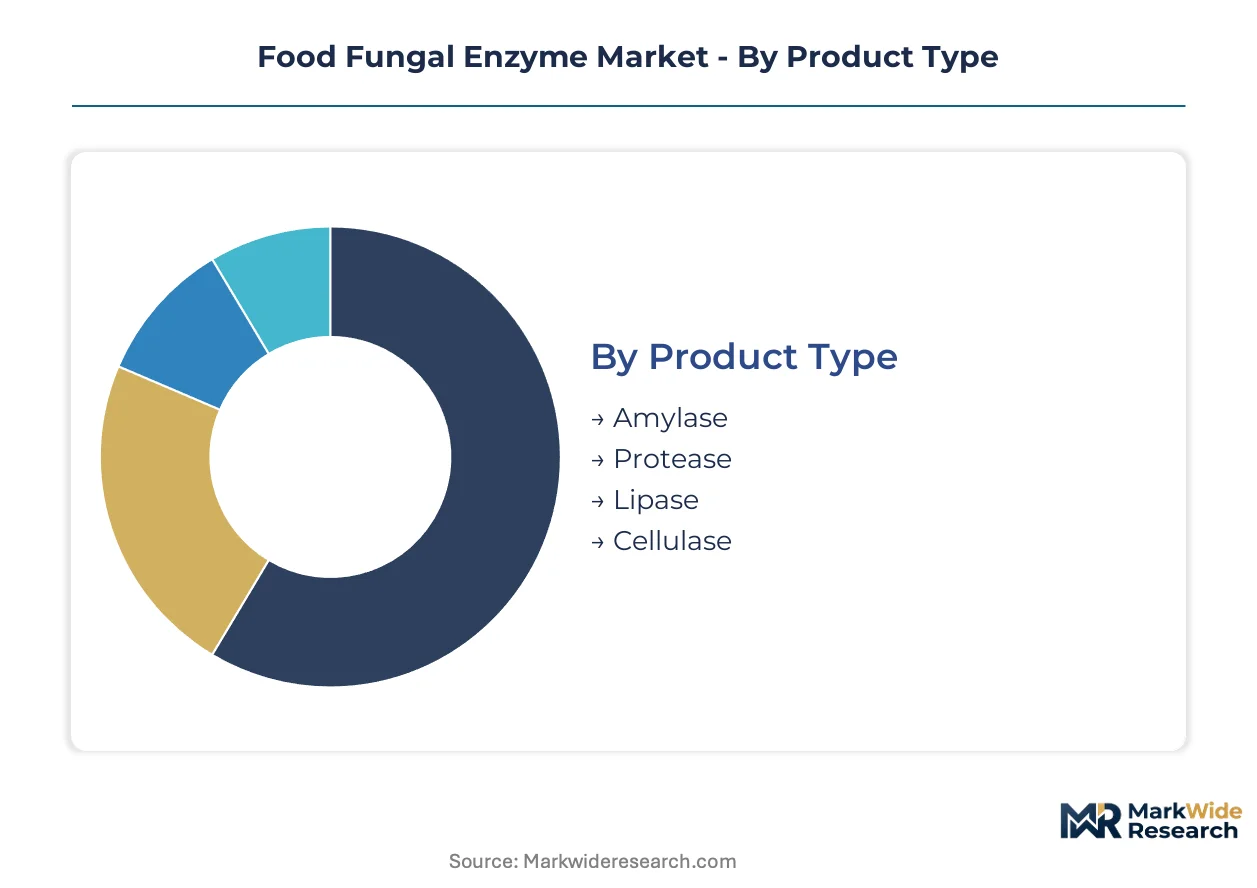
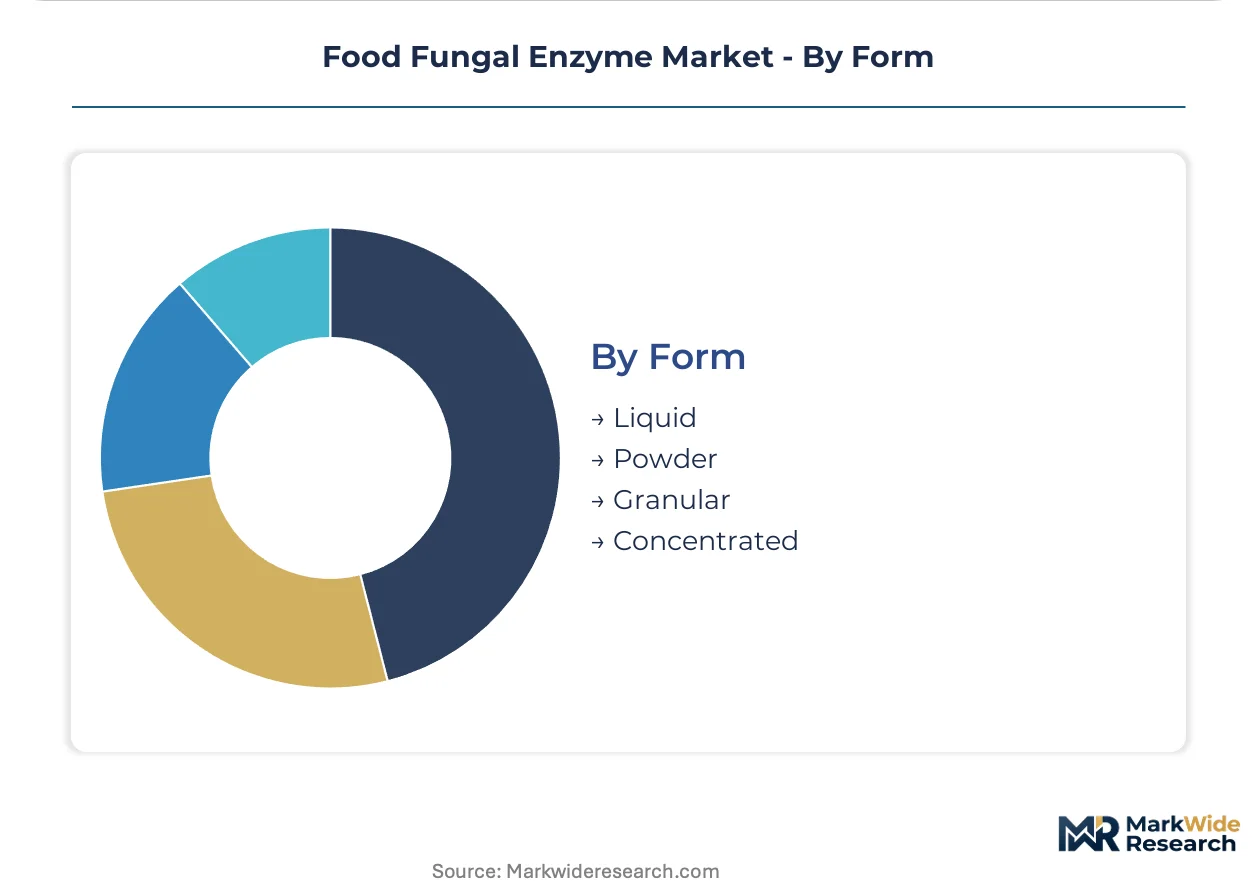
Food fungal enzymes comprise protein biocatalysts secreted by filamentous fungi such as Aspergillus oryzae and Trichoderma reesei, typically manufactured through submerged fermentation at controlled pH and temperature parameters, then deployed to catalyze starch hydrolysis, protein cleavage, or lipid modification in processed foods. Amylase and protease command the largest volume positions due to their indispensability in baking and dairy applications, while lipase exhibits the steepest growth trajectory as plant-based cheese formulations require precise fat-structured mouthfeel replication. Powder and liquid forms split the market along automation-readiness lines, with granular formats capturing premium positioning in high-throughput biscuit manufacturing where dust control and dosing precision determine operational efficiency.
EU REACH chemical registration and the F-Gas Regulation constrain solvent-based extraction methods, redirecting investment toward aqueous fermentation and downstream purification upgrades. FDA GRAS self-affirmation pathways and EFSA novel food consultations create divergent approval timelines that shape regional product launch sequencing. Stakeholders must monitor regulatory divergence between EU enzyme additive reclassifications and US FDA guidance updates on fermentation-derived ingredients to preempt compliance-driven supply disruptions.
Market Dynamics
EU Green Deal mandates and REACH chemical safety protocols are forcing accelerated reformulation of dough conditioners and processing aids toward fermentation-derived biocatalysts, restructuring procurement specifications across industrial baking and dairy processing clusters.
Growth Catalysts
- REACH solvent restrictions:ECHA registration requirements for chemical extraction methods redirect capital toward aqueous fermentation infrastructure, expanding addressable market for submerged-culture enzyme producers.
- Clean-label bakery demand:Industrial bakers in Germany and the Netherlands are eliminating potassium bromate and azodicarbonamide, creating specification pull for fungal protease and amylase alternatives.
- Plant-based cheese proliferation:Precision lipase deployment enables fat-structured mouthfeel replication in analog formulations, opening volume positions in dairy alternatives manufacturing.
Market Restraints
- Input cost volatility:Corn steep liquor and soybean meal price fluctuations squeeze fermentation media economics, compressing margin stability for bulk amylase producers.
- Supply concentration risk:Strain banking and master cell repository control concentrates among three European fermentation houses, creating single-source vulnerability for pharmaceutical-grade certification tiers.
- Regulatory friction:Divergent FDA GRAS self-affirmation timelines versus EFSA novel food consultation durations delay synchronized product launches, fragmenting commercialization sequencing.
Strategic Opportunities
- Underpenetrated precision fermentation:Continuous processing technology convergence with AI-driven bioprocess control enables real-time titer optimization, unlocking capital efficiency gains for mid-scale producers.
- Indian FSSAI enzyme additive reclassification:Pending regulatory clarity on fungal-derived processing aids creates first-mover positioning for fermentation complexes serving South Asian processed food manufacturing.
- Brewery waste valorization:Spent grain and yeast extract streams from Belgian and Czech brewing clusters offer low-cost substrate alternatives for lipase production, circularizing feedstock economics.
Industry Challenges
- Talent scarcity in downstream processing:Purification chromatography and membrane filtration expertise concentrates among retiring specialists in Dutch and Danish fermentation hubs, constraining capacity expansion timelines.
- Capex intensity for GMP compliance:Pharmaceutical-grade enzyme isolation suites require seven-figure cleanroom investments, filtering participation to consolidated biosolutions platforms with captive capital access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Food Fungal Enzyme Market |
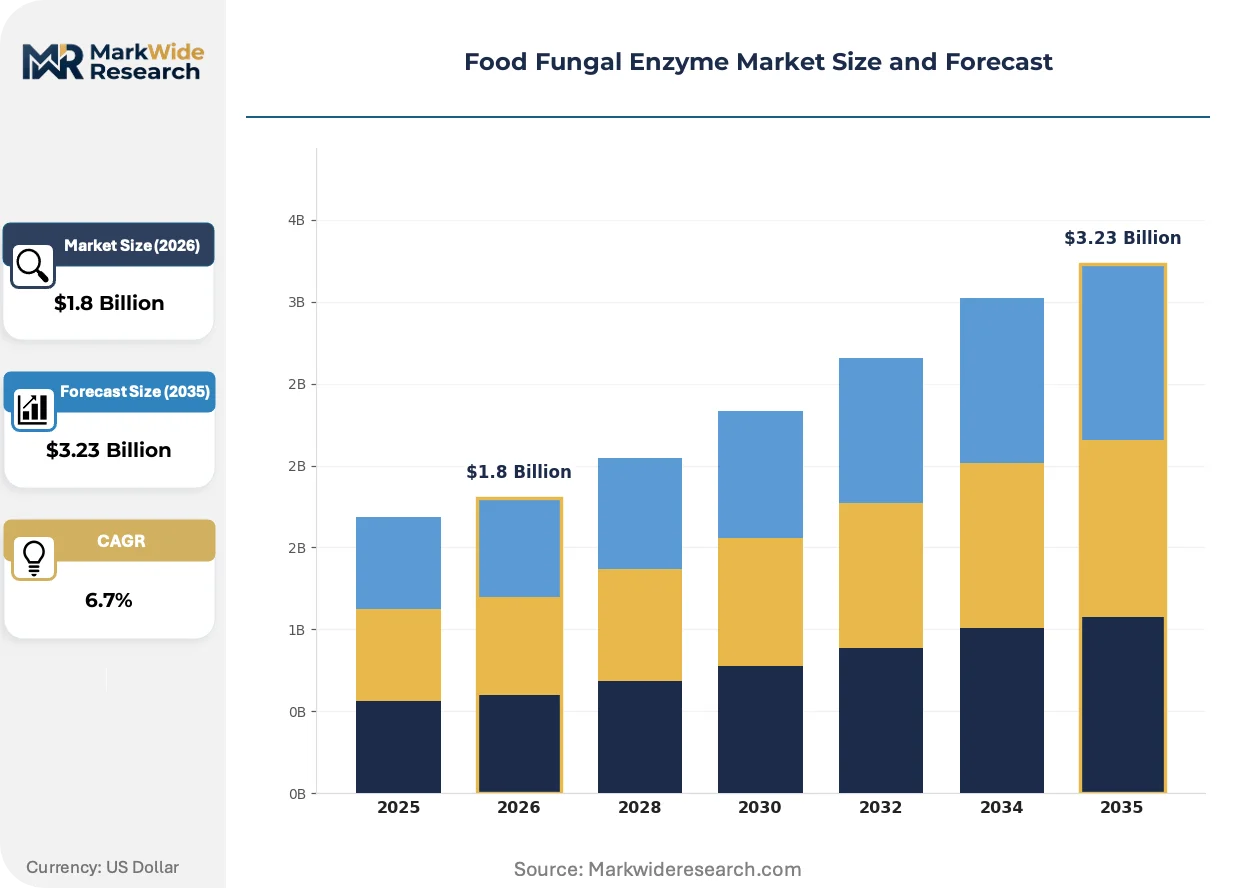
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Amylase, Protease, Lipase, Cellulase Application: Baking, Dairy, Beverages, Confectionery End User: Food Manufacturers, Restaurants, Retailers, Home Bakers Form: Liquid, Powder, Granular, Concentrated |
| Companies Covered | Novonesis Group, International Flavors & Fragrances Inc., dsm-firmenich, Associated British Foods plc, Advanced Enzyme Technologies, Amano Enzyme Inc., Chr. Hansen, BASF, AB Enzymes, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Food Fungal Enzyme Market Evolving Landscape
Bioprocess intensification and regulatory chemistry restrictions are converging to reshape manufacturing footprints, with digital control systems and alternative feedstocks emerging as decisive competitive differentiators.
Continuous fermentation with perfusion bioreactor technology is supplanting traditional fed-batch protocols in high-volume amylase production. Novozymes and DSM-Firmenich are retrofitting Dutch and German facilities with real-time biomass monitoring and automated harvest systems. This shift compresses capital intensity per kilogram of active enzyme while enabling tighter process analytical technology compliance for pharmaceutical-grade certification.
EU F-Gas Regulation phase-down schedules are eliminating hydrofluorocarbon-based cooling in downstream lyophilization operations. Fermentation houses are installing ammonia-based refrigeration and vacuum belt drying alternatives to maintain temperature-sensitive enzyme stability. Lipase and protease fractions destined for thermally unstable applications face the steepest equipment reconfiguration requirements.
Buyer specification sheets now mandate carbon intensity disclosures aligned with CSRD corporate sustainability reporting obligations. Industrial bakers in Germany are auditing scope 3 emissions from enzyme suppliers, with fermentation electricity source documentation becoming a standard procurement gate. Suppliers with grid-connected biogas or offshore wind power purchase agreements capture preferred vendor status in RFP evaluations.
Food Fungal Enzyme Market Segmentation
Segmentation in food fungal enzymes reveals how procurement specifications diverge across regulatory environments and processing scales. Manufacturers configure supply portfolios differently for industrial automation versus artisan flexibility, while export markets demand certification tiers unavailable in domestic-only product lines.
Product Type:
Amylase and protease production concentrates in German and Dutch fermentation clusters serving EU industrial baking demand, while lipase capacity expands for export-oriented plant-based dairy analog producers in North America and Asia-Pacific.
- Amylase:Alpha-amylase and glucoamylase fractions catalyze starch hydrolysis in dough conditioning and glucose syrup production. Demand clusters in Frankfurt-Hamburg industrial baking corridors where clean-label reformulation eliminates chemical oxidizers.
- Protease:Endo- and exopeptidase variants modify gluten networks and accelerate cheese ripening. Dutch dairy processors and German artisan bakeries drive specification pull for fungal-derived alternatives to animal rennet and chemical dough relaxers.
- Lipase:Precision fat-modifying biocatalysts for structured lipids in plant-based cheese.
- Cellulase:Fiber-degrading enzymes for fruit juice clarification and vegetable processing.
Amylase commands the established base. The steepest expansion runs through lipase as precision fermentation enables designer fat profiles.
Application:
Cost tier differentiation separates commodity-grade bakery enzymes from pharmaceutical-certification dairy biocatalysts requiring seven-figure cleanroom investments.
- Baking:Dough conditioning and crumb softening applications dominate volume positions. Industrial biscuit and bread manufacturers in Germany and the Netherlands specify fungal protease and amylase to replace azodicarbonamide and potassium bromate under EU additive restrictions.
- Dairy:Cheese ripening acceleration and milk clotting functions command premium pricing tiers. EFSA novel food consultation requirements and FDA GRAS self-affirmation pathways create divergent approval timelines that fragment commercialization sequencing across Atlantic markets.
- Beverages:Juice clarification and brewing adjunct processing.
- Confectionery:Invertase and specialized carbohydrases for texture modification.
Baking anchors volume demand. Dairy captures margin expansion through certification-tier premiums.
End User:
Customer type determines packaging scale and technical service intensity, with food manufacturers requiring automated dosing integration and home bakers driving single-serve retail formats.
- Food Manufacturers:Industrial-scale procurement with automated dosing systems and HACCP integration requirements. German and Dutch baking conglomerates negotiate multi-year supply agreements with fermentation houses for guaranteed amylase and protease volumes.
- Restaurants:Mid-scale commercial kitchens requiring flexible batch sizing.
- Retailers:Private-label enzyme blends for consumer-facing baking aids.
- Home Bakers:Small-format retail packaging with simplified application instructions.
Food manufacturers concentrate procurement volume. Home bakers represent the emerging direct-to-consumer channel.
Form:
Supply concentration in aqueous fermentation infrastructure favors liquid formats for high-volume industrial contracts, while powder and granular variants require additional downstream capital for spray drying and agglomeration.
- Liquid:Ready-to-dose aqueous suspensions for automated bakery and dairy processing lines. Dutch fermentation complexes optimize liquid amylase titers for direct tanker delivery to industrial baking clusters around Rotterdam and Groningen.
- Powder:Spray-dried enzyme preparations for extended shelf stability and freight efficiency.
- Granular:Dust-controlled agglomerated formats for high-throughput biscuit manufacturing where explosive atmosphere regulations constrain fine powder handling.
- Concentrated:High-activity formulations requiring dilution before application.
Liquid formats dominate industrial contracts. Granular specifications gain share in safety-regulated manufacturing environments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics favor European fermentation houses supplying amylase and protease to North American and Asian-Pacific bakery processors, while lipase capacity expansion targets plant-based dairy analog demand in the United States and China.
Germany
Industrial baking clusters around Frankfurt and Hamburg drive specification pull for fungal-derived dough conditioners as azodicarbonamide and potassium bromate face EU additive restrictions. REACH chemical safety protocols redirect procurement toward aqueous fermentation biocatalysts. The Lower Saxony-Hamburg corridor concentrates enzyme R&D facilities serving continental European biscuit and bread manufacturers.
United States
Plant-based cheese proliferation in California and the Midwest generates demand for precision lipase enabling fat-structured mouthfeel replication. FDA GRAS self-affirmation pathways accelerate product launch timelines relative to European consultation procedures. Chicago-area dairy alternative manufacturing clusters source fungal protease for analog formulations targeting retail and foodservice channels.
Netherlands
Specialized fermentation complexes in Rotterdam and Groningen optimize liquid amylase titers for direct tanker delivery to industrial baking operations. CSRD corporate sustainability reporting obligations require enzyme suppliers to document fermentation electricity sources and carbon intensity. Dutch dairy processors specify fungal-derived alternatives to animal rennet under EFSA novel food consultation frameworks.
India
Processed food manufacturing expansion in Maharashtra and Gujarat awaits FSSAI enzyme additive reclassification clarity for fungal-derived processing aids. Pending regulatory determinations create first-mover positioning opportunities for fermentation complexes serving South Asian markets. Mumbai-Pune industrial corridors concentrate biscuit and convenience food producers evaluating clean-label reformulation options.
China
Brewing and beverage processing in Shandong and Guangdong provinces generates spent grain streams suitable for circular lipase production feedstocks. SAMR food additive regulations govern import substitution strategies for domestic fermentation capacity expansion. Qingdao-area brewing clusters offer substrate valorization partnerships for enzyme manufacturers seeking cost-competitive production economics.
Food Fungal Enzyme Market Competitive Landscape
Concentration sits with consolidated biosolutions platforms controlling pharmaceutical-grade certification tiers and captive fermentation infrastructure. Mid-scale specialists compete on baking-specific protease portfolios and regional technical service proximity. Three archetypes dominate: merged pharmaceutical-food enzyme conglomerates, European fermentation houses with GMP-compliant isolation suites, and Asia-Pacific contract manufacturers serving price-sensitive bulk amylase demand. Competitive moves center on continuous processing technology licensing and strategic partnerships for brewery waste valorization feedstock agreements.
Within the merged biosolutions tier, Novonesis Group occupies a position spanning pharmaceutical-grade and food-grade enzyme supply chains. Among European fermentation specialists, dsm-firmenich anchors demand through Dutch fermentation complex operations, while AB Enzymes exemplifies the baking-focused protease portfolio archetype competing across artisan and industrial distribution channels.
| Leading Market Players |
|---|
| Novonesis Group |
| International Flavors & Fragrances Inc. |
| dsm-firmenich |
| Associated British Foods plc |
| Advanced Enzyme Technologies |
| Amano Enzyme Inc. |
| Chr. Hansen |
| BASF |
| AB Enzymes |
| Others |
Value Network & Pricing Analysis
Multi-year offtake agreements between German industrial baking conglomerates and Dutch fermentation houses lock in supply access for amylase and protease volumes while providing price visibility against corn steep liquor and soybean meal volatility. These contract structures insulate buyers from spot market fluctuations in fermentation media inputs while securing pharmaceutical-grade certification tiers for dairy applications.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake pricing across premium, standard, and economy certification tiers. Price differentiation hinges on FCC/JECFA purity grades and CSRD-aligned carbon intensity disclosures, with pharmaceutical-grade cleanroom isolation commanding substantial premiums. Pricing pressure stems from corn steep liquor cost volatility squeezing bulk amylase margins. Artisan bakeries exhibit highest price sensitivity; dairy alternative manufacturers show lowest sensitivity for precision lipase specifications.
Supply Chain Analysis
Six-to-eight week lead times for pharmaceutical-grade enzyme isolation reflect GMP-compliant cleanroom queue constraints at Dutch and German fermentation facilities. Supply concentrates in the Netherlands, Germany, and Denmark, drawing from corn steep liquor, soybean meal, and spent grain feedstocks. Single-source vulnerability concentrates in European strain banking repositories. Distribution runs through direct tanker delivery to Rotterdam-Groningen industrial baking clusters and packaged export to North American plant-based dairy manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits at a platform-economics inflection where continuous fermentation technology convergence with AI-driven bioprocess control is creating interoperability standards that favor integrated biosolutions platforms over point-product specialists.
For Market Incumbents: Fortify master cell repository control and captive strain banking capabilities against emerging precision fermentation entrants leveraging continuous processing technology. Deepen backward integration into brewery waste valorization partnerships in Belgium and Czechia to secure low-cost lipase feedstocks. Prioritize GMP cleanroom capacity additions in the Lower Saxony-Hamburg corridor to defend pharmaceutical-grade certification tier premiums. For New Entrants and Emerging Players: Differentiate on AI-driven bioprocess optimization for mid-scale amylase producers seeking capital efficiency gains. Target India's FSSAI enzyme additive reclassification window for first-mover positioning in Maharashtra-Gujarat biscuit manufacturing. Pursue technical service proximity to German artisan bakeries as the go-to-market angle, competing on application-specific protease portfolios rather than bulk volume. For Investors and Strategic Acquirers: European fermentation houses with GMP-compliant isolation suites and captive renewable electricity purchase agreements represent the priority acquisition archetype. Long-term viability hinges on CSRD carbon intensity disclosure capabilities and REACH solvent restriction compliance positioning. Watch for EFSA novel food consultation timeline convergence with FDA GRAS pathways as the signal for synchronized transatlantic product launch feasibility.| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Fermentation Retrofit | Real-time titer optimization compresses capital intensity per kilogram at Dutch facilities. |
| Brewery Waste Valorization Partnership | Spent grain streams from Belgian brewing clusters circularize lipase feedstock economics. |
| GMP Cleanroom Capacity Expansion | Seven-figure isolation suite investments filter participation to consolidated platforms. |
| FSSAI Regulatory First-Mover Positioning | Pending enzyme additive reclassification creates entry window for South Asian supply. |
| CSRD Carbon Intensity Disclosure Integration | Grid-connected biogas documentation secures preferred vendor status with German bakers. |
Research Methodology
Initial hypotheses were tested against primary input from fermentation plant managers, procurement leads at German and Dutch baking conglomerates, technical R&D directors at biosolutions platforms, and regulatory affairs specialists navigating EFSA novel food consultations, then refined through secondary validation against ECHA REACH registration databases, SEC 10-K filings from merged enzyme conglomerates, EU F-Gas Regulation implementation schedules, and customs trade data for fermentation equipment imports. Bottom-up volume modeling triangulated with top-down market sizing across certification tiers.
Variance decomposition across the projection horizon isolates drivers by product type, application, form, and regional regulatory cluster. CAGRs derive from segment-level growth rate reconciliation with macroeconomic fermentation capacity expansion assumptions. Industry-specific inputs include corn steep liquor price elasticity coefficients and pharmaceutical-grade cleanroom utilization rates at Dutch facilities.
The analysis sits within stated boundaries; outcomes outside sustained EU Green Deal enforcement or FSSAI regulatory clarity timelines would require recalibration. Forecasts assume continued REACH solvent restriction phase-down and CSRD disclosure mandate implementation. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Clean Labelled Food Additives Market
Food Additives and Ingredients
Asia-Pacific Food Preservatives Market
Food Additives and Ingredients
Amaranth (E123) Market
Food Additives and Ingredients
Canada Food Enzymes Market
Food Additives and Ingredients
Vietnam Food Additives Market
Food Additives and Ingredients
Food Stabilizer Systems Market
Food Additives and Ingredients
South Africa Food Colorants Market
Food Additives and Ingredients
Fat Replacers Salt Reducers and Replacers Market
Food Additives and Ingredients
North America Microencapsulation Market
Food Additives and Ingredients
Alpha-Linolenic Acid Market
Food Additives and Ingredients
Fish-Free Omega-3 Ingredients Market
Food Additives and Ingredients
Beta Agonist Feed Additive Market
Food Additives and Ingredients
Emulsifiers Market
Food Additives and Ingredients
Brazil Food Preservatives Market
Food Additives and Ingredients
Germany Food Acidulants Market
Food Additives and Ingredients
Canada Food Additives Market