
 South America Food Enzymes Market | 2026-2036
South America Food Enzymes Market Size, Share, and Industry Trends Forecast 2026-2036
South America Food Enzymes Market Analytics
ANVISA's updated enzyme purity standards are consolidating the cost-of-entry calculus for foreign suppliers entering Brazil. Novozymes leverages its fermentation technology leadership to sustain premium positioning across South American dairy applications. Cargill anchors regional supply security through backward integration into enzyme manufacturing inputs. Kerry Group plc differentiates via customized enzyme blends tailored to local beverage producers in Colombia and Peru.
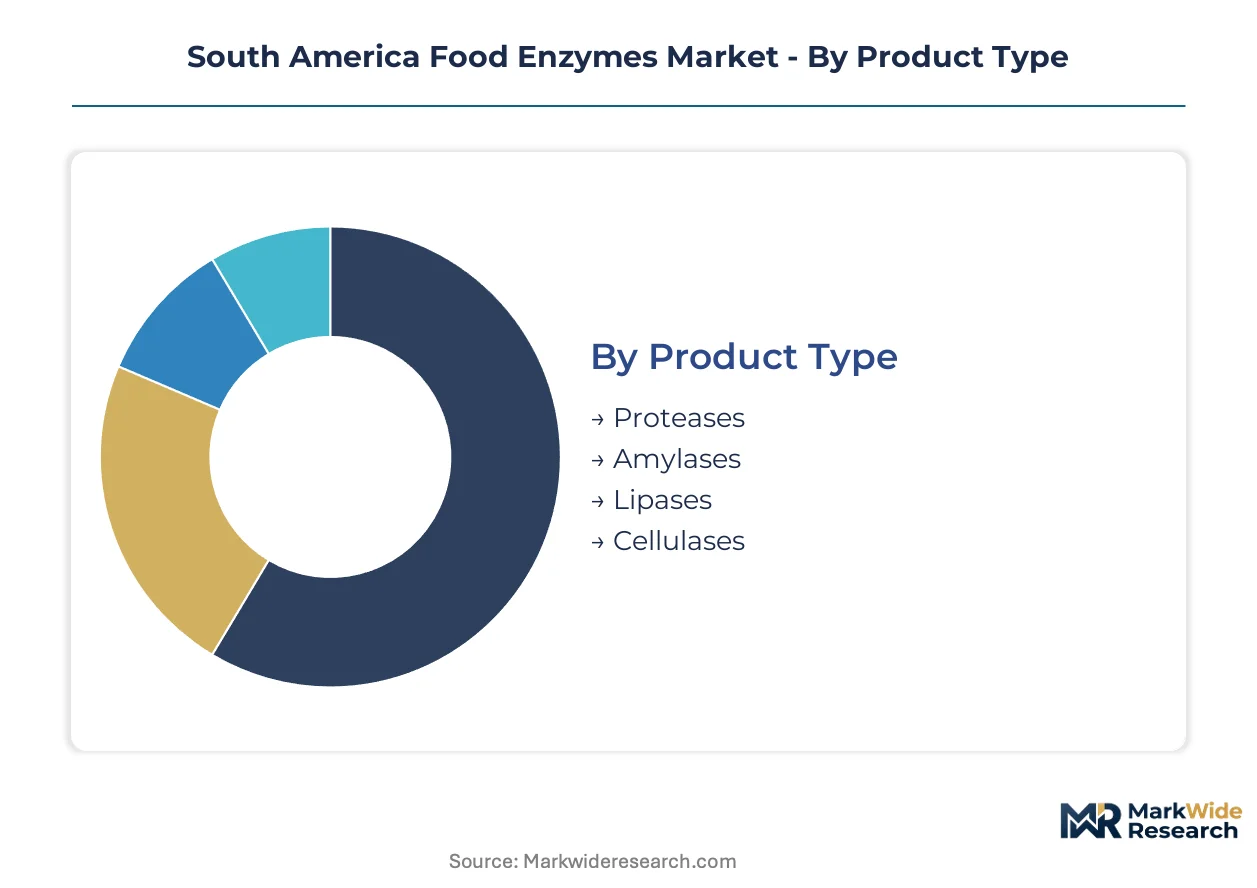
Food enzymes comprise protein-based biological catalysts—typically operating at 30–70°C and pH 4.0–8.0—that accelerate biochemical reactions in food matrices without permanent consumption. These biocatalysts enable starch hydrolysis, protein modification, lipid conversion, and cell wall degradation to improve processing yields, texture profiles, and shelf stability. Proteases command the largest product-type share due to their indispensability in meat tenderization and dairy coagulation across Argentine beef operations and Brazilian cheese production. Lipases represent the fastest-expanding category as clean-label interest intensifies among South American margarine and specialty fat manufacturers seeking to replace chemical interesterification. Amylases occupy a mature, high-volume position in the region's wheat-processing sector, where margin pools have compressed amid commoditization.
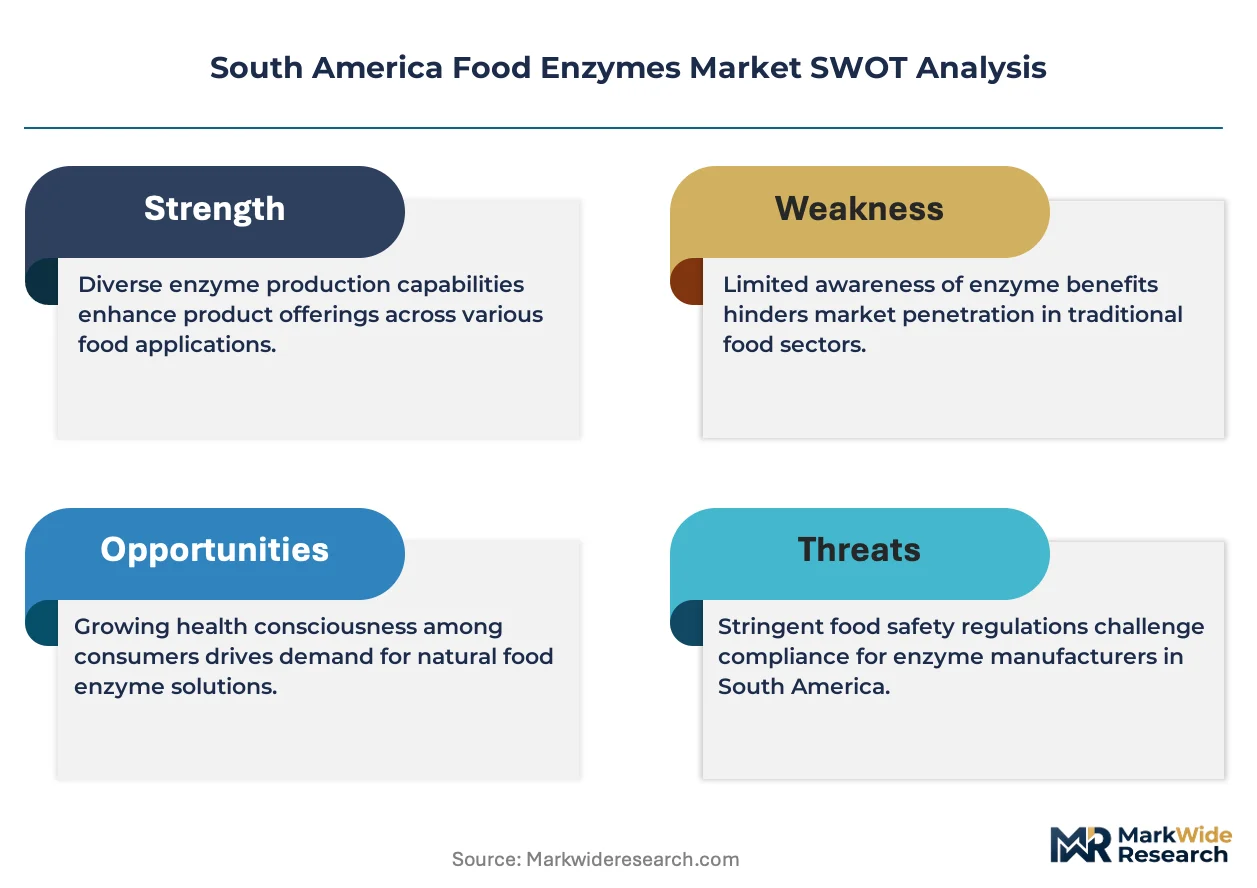
ANVISA in Brazil, the National Directorate of Food and Drug in Argentina, and INVIMA in Colombia enforce divergent enzyme labeling and safety assessment protocols that fragment compliance costs across the Andean Mercosur trade zone. REACH-equivalent substance notification requirements in Brazil and Argentina are forcing reformulation of enzyme carriers and stabilizers. Stakeholders must monitor regulatory harmonization negotiations between Mercosur and Pacific Alliance frameworks to anticipate cross-border product registration pathways.
Market Dynamics
ANVISA's tightening purity thresholds for imported enzyme preparations are restructuring competitive entry conditions across Brazil's industrial baking corridor, forcing foreign suppliers to recalibrate carrier formulations and documentation protocols.
Growth Catalysts
- Clean-label substitution:Brazilian and Argentine bakery manufacturers are accelerating enzyme adoption to displace chemical conditioners and extend shelf life without artificial additives.
- ANVISA regulatory modernization:Updated food additive frameworks are creating tiered compliance pathways that reward suppliers with advanced fermentation documentation.
- Dairy processing expansion:Protease demand is intensifying across Argentine beef operations and Brazilian cheese production as coagulation efficiency becomes a margin priority.
Market Restraints
- Carrier reformulation costs:REACH-equivalent substance notification requirements in Brazil and Argentina are forcing expensive redesign of enzyme stabilizers and diluents.
- Import concentration risk:Foreign suppliers dominate high-purity enzyme preparations, exposing Brazilian manufacturers to currency volatility and documentation delays.
- Amylase commoditization:Wheat-processing applications in São Paulo and Minas Gerais states face compressed margin pools as generic substitutes proliferate.
Strategic Opportunities
- Peru beverage enzyme blends:Customized solutions for local producers remain underdeveloped relative to Brazil and Argentina, creating white space for formulation specialists.
- Lipase clean-label positioning:Colombian and Chilean margarine manufacturers are seeking enzymatic interesterification to replace chemical processes.
- Mercosur-Pacific Alliance harmonization:Ongoing regulatory convergence negotiations could streamline cross-border product registration for compliant suppliers.
Industry Challenges
- Fermentation scale-up expertise:Brazilian biotech talent pools lag demand for industrial enzyme production at ANVISA-certified purity grades.
- Legacy equipment integration:Argentine meat processors face technical friction retrofitting protease dosing systems into existing tenderization lines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Food Enzymes Market |
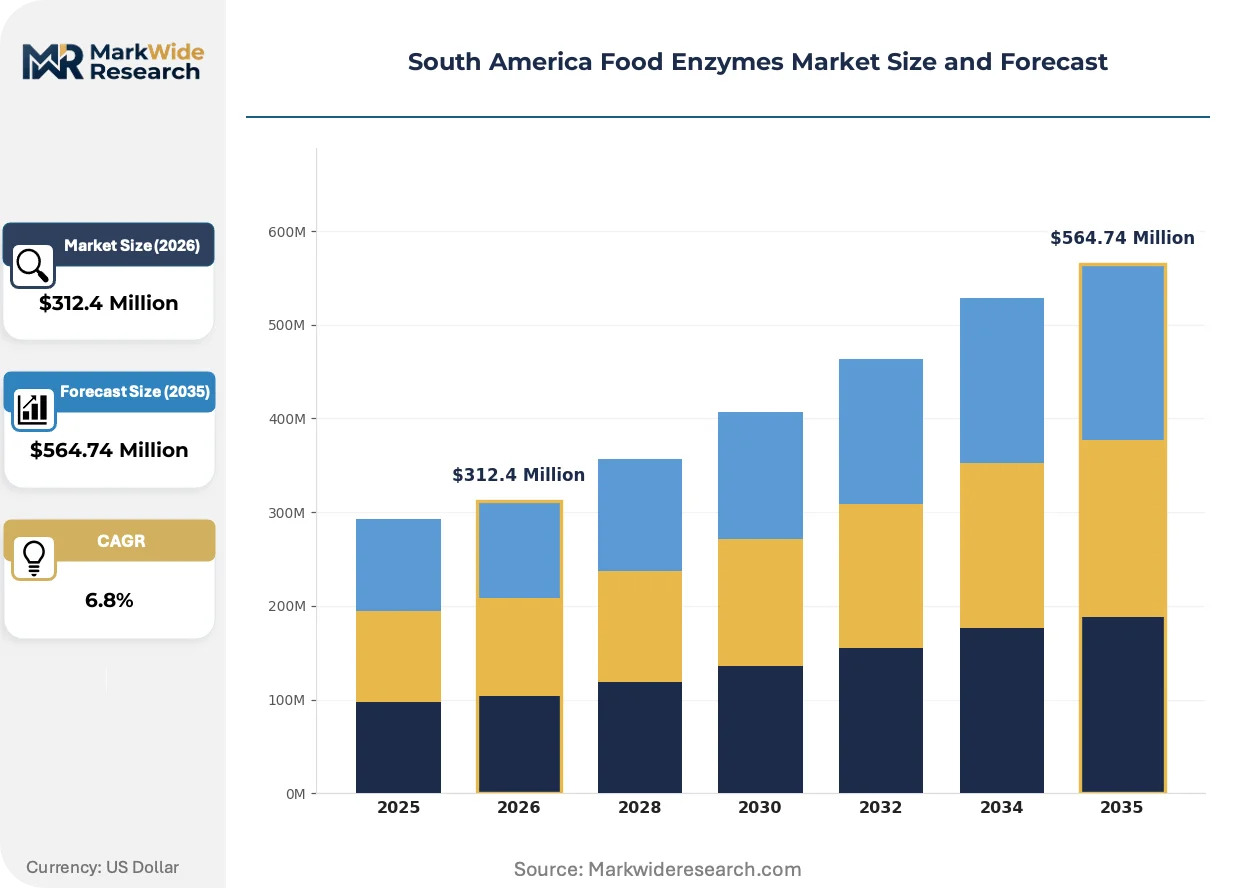
| Market Size in 2026 | $312.4 Million |
| Market Size in 2035 | $564.74 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Proteases, Amylases, Lipases, Cellulases Application: Baking, Dairy Processing, Beverage Production, Meat Processing End User: Food Manufacturers, Beverage Companies, Dairy Producers, Restaurants Distribution Channel: Online Sales, Direct Sales, Distributors, Retail Stores |
| Companies Covered | International Flavors & Fragrances, Inc., Cargill, Novozymes, Ajinomoto Group, Chr. Hansen, DSM-Firmenich, Associated British Foods plc, DuPont, Kerry Group plc, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Food Enzymes Market Evolving Landscape
Biocatalytic process intensification is reshaping South American food manufacturing, with enzyme suppliers and end-users co-developing application-specific formulations that compress processing steps and reduce thermal energy requirements.
Precision fermentation-derived enzymes are consolidating quality consistency advantages over traditional extraction methods. Brazilian dairy cooperatives are adopting these biocatalysts for standardized coagulation performance. This technology is consolidating supplier power toward firms with captive bioreactor capacity and strain optimization capabilities.
ANVISA's evolving enzyme purity standards are tightening documentation burdens for imported preparations. Industrial baking operations in São Paulo state face reformulation timelines to meet carrier disclosure requirements. Argentine food additive registrants are responding by accelerating local toxicity testing partnerships to preempt compliance gaps.
Ingredient procurement patterns among Colombian and Peruvian beverage manufacturers are shifting from spot-market enzyme purchases toward annual formulation service contracts. Technical support and application troubleshooting are displacing price-only negotiations. This behavioral change is most visible in Lima and Bogotá processing clusters where SKU proliferation demands responsive supplier partnerships.
South America Food Enzymes Market Segmentation
Enzyme procurement patterns across South America diverge sharply by product chemistry and customer scale, with capital requirements for fermentation infrastructure and formulation expertise determining supplier access tiers. Understanding these segment boundaries clarifies where margin pools concentrate and which entry pathways remain viable for new competitors.
Product Type:
Capital intensity varies dramatically across enzyme classes, with fermentation-derived proteases and lipases demanding substantially higher bioreactor investment than extraction-based cellulases.
- Proteases:These protein-hydrolyzing enzymes require submerged fermentation at ANVISA-certified purity grades, locking in significant upfront capex for temperature-controlled bioprocessing. Argentine beef tenderization operations and Brazilian cheese cooperatives in Minas Gerais anchor regional demand as meat and dairy processors prioritize coagulation consistency.
- Lipases:Ester bond-cleaving biocatalysts operate through precision fermentation with strain optimization capabilities that consolidate supplier power toward firms with captive R&D infrastructure. Colombian and Chilean margarine manufacturers are accelerating adoption to displace chemical interesterification and capture clean-label positioning.
- Amylases:Starch-degrading workhorses dominate wheat-processing volumes across São Paulo's industrial baking corridor, though commoditization has compressed supplier margins.
- Cellulases:Cell wall-degrading enzymes see concentrated use in fruit juice clarification and olive oil extraction, particularly among Peruvian and Chilean processors.
Proteases absorb the bulk of installed capacity; lipases are expanding most quickly.
Application:
Application selection maps directly to customer technical sophistication and annual enzyme spend, with dairy and meat processors commanding dedicated formulation support while beverage producers negotiate standardized blends.
- Baking:Enzyme blends for dough conditioning and shelf-life extension command the highest per-kilogram premiums, with São Paulo and Minas Gerais industrial bakeries driving specification intensity as they displace chemical conditioners.
- Dairy Processing:Milk-clotting and cheese-ripening applications concentrate in southern Brazil and Argentina's Pampas dairy belt, where cooperatives prioritize batch-to-batch consistency in protease performance.
- Beverage Production:Enzymatic clarification and filtration support in Colombia and Peru relies more heavily on distributor technical service than direct supplier relationships.
- Meat Processing:Tenderization and flavor development applications in Argentine beef operations face retrofit friction when integrating protease dosing into legacy processing lines.
Baking captures the steepest pricing premiums; beverage production offers the broadest customer acquisition runway.
End User:
Customer scale determines procurement modality, with large food manufacturers negotiating annual formulation contracts while restaurants and smaller operators purchase through distributor spot markets.
- Food Manufacturers:Industrial bakeries and packaged food producers across Brazil's southeast maintain the most sophisticated enzyme specification requirements, including carrier disclosure documentation for ANVISA compliance.
- Beverage Companies:Colombian and Peruvian juice and beer processors are shifting from spot-market purchases toward technical service agreements that include application troubleshooting.
- Dairy Producers:Argentine and Brazilian cooperatives prioritize fermentation-derived enzyme consistency over price, consolidating procurement toward suppliers with bioreactor scale.
- Restaurants:Commercial kitchen enzyme use remains nascent, concentrated in high-volume bakery and meat preparation operations in São Paulo and Buenos Aires metropolitan areas.
Food manufacturers concentrate the highest per-account revenue; beverage companies are converting fastest to service-contract relationships.
Distribution Channel:
Channel selection reflects customer technical complexity and geographic concentration, with direct sales dominating formulation-intensive accounts while distributors capture fragmented regional demand.
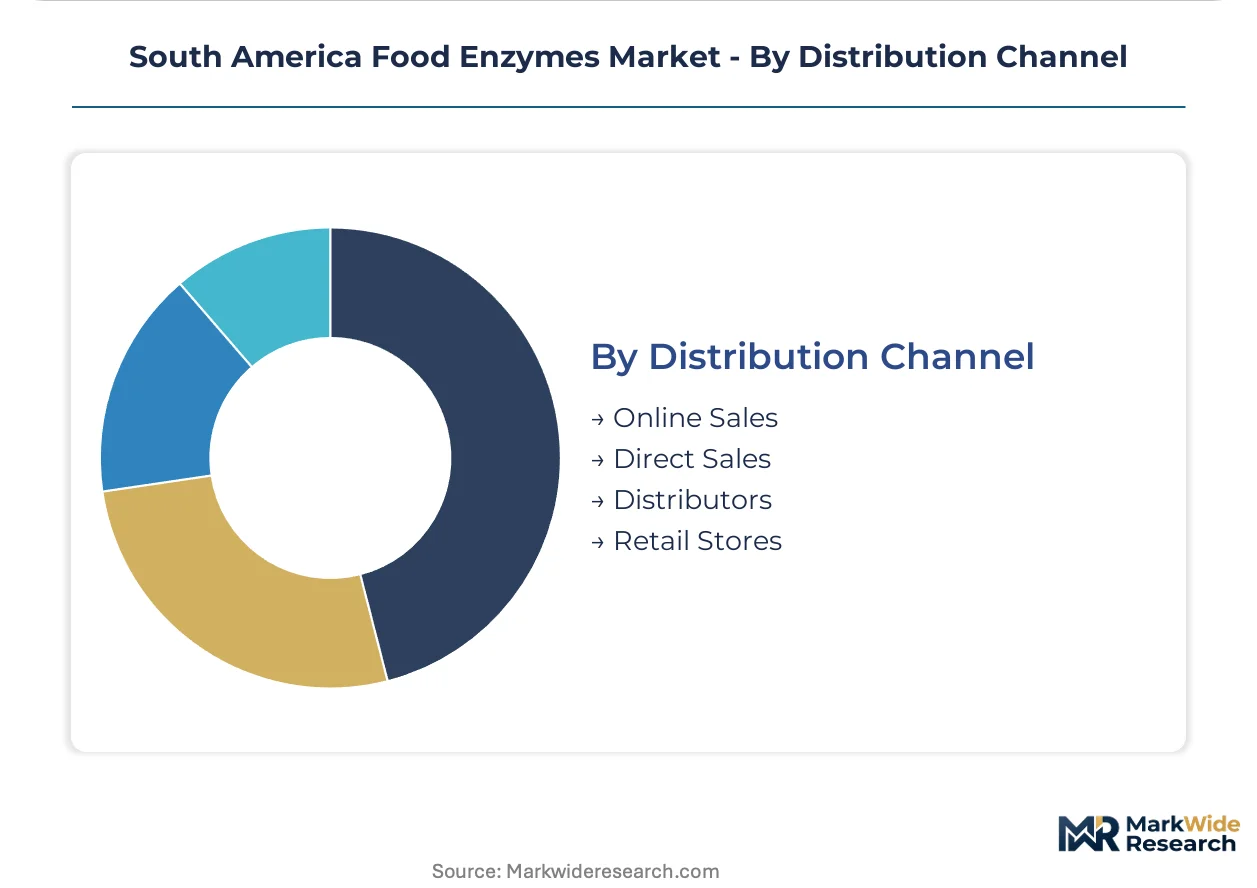
- Direct Sales:Large Brazilian dairy and baking operations require dedicated technical representatives for enzyme dosing optimization and regulatory documentation support.
- Distributors:Regional chemical and ingredient distributors capture mid-sized Argentine meat processors and Colombian beverage producers seeking local inventory and credit terms.
- Online Sales:E-commerce penetration remains limited to standardized amylase and cellulase preparations for smaller food manufacturers in secondary Brazilian cities.
- Retail Stores:Point-of-sale enzyme availability concentrates in São Paulo and Buenos Aires specialty ingredient suppliers serving artisanal bakeries and restaurants.
Direct sales anchor the highest-margin relationships; distributor networks are deepening geographic coverage fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manaus Free Trade Zone tax incentives concentrate enzyme importation and formulation activities in Brazil's northern corridor, redirecting supply chain flows away from traditional southeastern entry points.
Brazil
Industrial bakeries in São Paulo and Minas Gerais states drive protease and amylase consumption as manufacturers displace chemical conditioners. ANVISA's updated food additive frameworks mandate carrier disclosure documentation for imported preparations. São Paulo's baking corridor faces compressed reformulation timelines to meet purity thresholds.
Argentina
Beef tenderization operations across the Pampas region anchor regional protease demand for meat processing applications. The National Directorate of Food and Drug enforces divergent safety assessment protocols that fragment compliance costs with neighboring Mercosur members. Buenos Aires metropolitan processors encounter technical friction retrofitting legacy dosing systems.
Colombia
Margarine manufacturers in Bogotá processing clusters are accelerating lipase adoption to replace chemical interesterification processes. INVIMA maintains labeling requirements that differ from Brazilian ANVISA standards, complicating cross-border product registration. Beverage producers in the capital region are shifting procurement toward annual formulation service contracts.
Chile
Specialty fat producers in Santiago's industrial belt seek enzymatic solutions for clean-label positioning in export-oriented food manufacturing. The country's national food regulator enforces REACH-equivalent substance notification requirements for enzyme stabilizers. Valparaíso corridor processors concentrate demand for cellulases in fruit juice clarification applications.
Peru
Lima-based beverage manufacturers represent underdeveloped demand relative to Brazilian and Argentine markets, creating white space for customized enzyme blends. The country's health regulatory agency maintains notification pathways that lag regional harmonization efforts. Coastal processing clusters are converting from spot-market purchases toward technical support agreements.
South America Food Enzymes Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across South America's enzyme procurement tiers. The vendor base separates into fermentation-technology leaders, formulation service providers, and commodity amylase suppliers. Three strategic archetypes dominate: integrated biotech platforms with captive bioreactor capacity, application-specific blenders with regional technical service networks, and trading houses leveraging distributor relationships for geographic coverage. M&A activity concentrates on acquiring local toxicity testing capabilities to preempt ANVISA compliance gaps, while capacity expansion targets precision fermentation scale-up in southern Brazil.
Among Denmark-based biotechnology platforms, Novozymes and Chr. Hansen occupy positions exemplifying fermentation-technology leadership and strain optimization capabilities. Kerry Group plc represents the formulation-service archetype through customized blend development for Andean beverage producers. These three anchors illustrate how competitive positioning stratifies across technology ownership, application expertise, and geographic service density.
| Leading Market Players |
|---|
| International Flavors & Fragrances, Inc. |
| Cargill |
| Novozymes |
| Ajinomoto Group |
| Chr. Hansen |
| DSM-Firmenich |
| Associated British Foods plc |
| DuPont |
| Kerry Group plc |
| Others |
Value Network & Pricing Analysis
Fermentation substrate costs, particularly corn steep liquor and dextrose pricing indices, cascade through South American enzyme supply chains into three distinct procurement tiers. Brazilian industrial bakeries in São Paulo state absorb premium positioning for ANVISA-certified purity grades, while Argentine meat processors negotiate volume-based standard tiers and Peruvian beverage manufacturers access economy-grade cellulase blends through distributor spot markets.
Pricing Analysis
Short lead-time premiums of fifteen to twenty percent apply to ANVISA-documentation-ready enzyme preparations, while spot inventory of generic amylases trades at contracted discounts. Three-tier pricing structure across premium fermentation-derived, standard extraction-based, and economy generic levels reflects certification grade and bioreactor scale. Pricing pressure stems from carrier reformulation costs under REACH-equivalent notification requirements. Large Brazilian dairy cooperatives exhibit lowest price sensitivity; Peruvian juice processors remain most cost-conscious.
Supply Chain Analysis
Reverse-logistics flows for enzyme stabilizer returns and carrier refurbishment concentrate in the Manaus Free Trade Zone, creating a northern Brazilian consolidation hub. Supply draws from Denmark, the Netherlands, and domestic Brazilian fermentation facilities. Raw material dependencies include corn-derived dextrose, soy peptone, and pharmaceutical-grade salts. Single-source vulnerability persists for precision fermentation strains held by technology leaders. Distribution runs through direct technical sales for large accounts and regional chemical distributors for mid-tier processors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
South American food enzymes are transitioning from chemical extraction to precision fermentation manufacturing, with strain-optimized biocatalysts displacing traditional catalytic processes across dairy and baking applications.
For Market Incumbents: To counter emerging local fermentation capacity in southern Brazil, accelerate backward integration into captive bioreactor operations in Minas Gerais and preempt ANVISA compliance gaps through accelerated toxicity testing partnerships. Channel control via exclusive formulation service agreements with Colombian beverage clusters reinforces switching costs. For New Entrants and Emerging Players: Capture white space in Peruvian beverage enzyme blends and Chilean specialty fat interesterification applications where technical service infrastructure remains underdeveloped. The most penetrable entry point is Lima-based juice clarification, accessed through distributor technical partnerships rather than direct sales investment. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap formulation specialists with established INVIMA registration pathways in Colombia and Bogotá processing cluster relationships. Long-term viability over a five-to-ten year horizon rests on precision fermentation scale-up capabilities. Monitor Mercosur-Pacific Alliance harmonization negotiations as the critical inflection signal for cross-border product registration arbitrage.| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Scale-Up | Captive bioreactor capacity in southern Brazil consolidates supply security against import volatility. |
| ANVISA Certification Investment | Advanced fermentation documentation creates tiered compliance pathways rewarding documented purity. |
| Local Toxicity Testing Partnerships | Argentine registrants accelerate compliance to preempt carrier disclosure requirement gaps. |
| Customized Blend Development | Annual formulation contracts with Colombian beverage producers displace spot-market purchasing. |
| Regional Distributor Deepening | Mid-sized Argentine meat processors seek local inventory and credit terms through chemical distributors. |
Research Methodology
Multi-period observation of ANVISA regulatory filing volumes, enzyme import customs data, and industrial bakery capacity expansion anchored the trend analysis, supplemented by interviews with fermentation technology directors, ANVISA regulatory affairs specialists, Brazilian dairy cooperative procurement managers, and Colombian beverage processing engineers. Secondary validation drew from ANVISA food additive registries, Brazilian customs trade statistics, SEC filings of listed enzyme suppliers, and Mercosur regulatory harmonization documents. Bottom-up segment sizing triangulated against top-down industry value estimates.
Input-output matrices mapped fermentation capacity utilization, raw material cost indices, and end-use application growth rates across the projection horizon. Segmentation dimensions modeled include enzyme product chemistry, processing application, customer scale tier, and distribution channel structure. CAGRs were derived from regression analysis of historical volume trends against projected capacity additions and regulatory implementation timelines. Industry-specific forecast inputs incorporated ANVISA purity threshold phase-in schedules and wheat-processing margin compression indices.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to Mercosur-Pacific Alliance regulatory convergence timing and Brazilian real currency volatility against enzyme import pricing. Practitioners should monitor ANVISA carrier disclosure enforcement actions and precision fermentation patent filings for early signals of competitive repositioning.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Leavening Agents Market
Food Additives and Ingredients
Coconut Fatty Acids Market
Food Additives and Ingredients
Egypt Feed Additives Market
Food Additives and Ingredients
Chocolate Wax Market
Food Additives and Ingredients
Food Grade Potassium Sorbate Market
Food Additives and Ingredients
South America Feed Anti-Caking Agents Market
Food Additives and Ingredients
Lycopene Food Colors Market
Food Additives and Ingredients
Japan Food Emulsifiers Market
Food Additives and Ingredients
Phosphated Distarch Phosphate Market
Food Additives and Ingredients
South America Brewing Enzymes Market
Food Additives and Ingredients
Clean Labelled Food Additives Market
Food Additives and Ingredients
Global Natamycin Market
Food Additives and Ingredients
Natural Solubilizers Market
Food Additives and Ingredients
Africa Food Preservatives Market
Food Additives and Ingredients
Food Antimicrobial Additives Market
Food Additives and Ingredients
Argentina Food Acidulants Market