
 Global Food Release Agents Market | 2026-2036
Global Food Release Agents Market Size, Share, and Industry Trends Forecast 2026-2036
Global Food Release Agents Market Foresight
The buyer base for food release agents is broadening beyond traditional commercial bakeries to include artisan producers and foodservice chains seeking portion-control consistency. Cargill Incorporated leverages its oilseed processing infrastructure to secure backward integration into soy lecithin supply. Archer-Daniels-Midland Co anchors North American distribution through direct sales channels to industrial kitchens. Par-Way Tryson specializes in aerosolized delivery systems for quick-service restaurant chains.
Food release agents comprise surface-active compounds—lecithin, stearates, and silicone derivatives—formulated to reduce adhesion between food matrices and processing equipment at temperatures ranging from ambient to 220°C. Their primary function is to ensure clean product release, minimize waste, and extend mold and conveyor belt life in high-throughput manufacturing environments. Soy lecithin dominates volume due to cost positioning and label-friendly positioning, while polydimethylsiloxane commands premium pricing in confectionery applications demanding thermal stability above 180°C. Fatty acid esters are gaining share in dairy alternatives where clean-label requirements exclude synthetic additives.
The FDA maintains GRAS oversight for direct food-contact substances, while ECHA enforces REACH registration for silicone-based agents entering European manufacturing facilities. BIS certification requirements in India and GB standards in China create divergent compliance pathways that fragment formulation strategies across export markets. Stakeholders must monitor regulatory divergence between jurisdictions to avoid reformulation costs that erode margin pools in commoditized segments.
Market Dynamics
Clean-label mandates and REACH chemical restrictions are forcing simultaneous reformulation across three continents, compressing development cycles for plant-derived release agents while elevating compliance costs for silicone-based alternatives.
Growth Catalysts
- EU Green Deal chemical phase-outs:REACH Annex XVII restrictions on synthetic additives accelerate R&D investment in lecithin and fatty acid ester formulations. Industrial bakeries in Germany and France are qualifying these alternatives for high-temperature lines.
- Quick-service restaurant expansion:Foodservice chains in the United States and Southeast Asia standardize aerosolized release systems to ensure portion-control consistency across franchise networks. This creates pull-through demand for precision-delivery packaging.
- Soy processing infrastructure:Oilseed crush capacity concentration in Argentina and Brazil secures backward-integrated feedstock for non-GMO lecithin. Cost positioning against synthetic alternatives improves.
Market Restraints
- Phospholipid price volatility:Soybean oil futures fluctuation transmits directly to lecithin input costs, squeezing margin pools for mid-tier formulators without long-term supply contracts.
- Silicone thermal stability ceiling:Polydimethylsiloxane degrades above 220°C, limiting deployment in extruded snack and pet food applications where processing temperatures exceed this threshold.
- Regulatory fragmentation:Divergent BIS certification in India, GB standards in China, and FDA GRAS determinations force parallel formulation tracks for export-oriented manufacturers.
Strategic Opportunities
- India organized bakery penetration:Modern trade expansion in Mumbai and Bangalore creates first-mover advantage for clean-label release agents as FSSAI enforcement tightens on synthetic additive use.
- Precision fermentation lipids:Microbially derived phospholipids eliminate agricultural commodity exposure while delivering batch-to-batch consistency for premium confectionery applications.
- Direct-to-artisan distribution:E-commerce platforms bypass traditional ingredient distributors, enabling small-batch formulators to capture margin from craft bakeries in Italy and Spain.
Industry Challenges
- Reformulation timeline compression:REACH registration deadlines for existing silicone-based agents force 18-month qualification windows that strain analytical chemistry capacity at contract laboratories.
- Clean-label performance gaps:Plant-derived alternatives exhibit variable release efficiency across humidity conditions, requiring application-specific tuning that extends technical service engagement.
- Cross-contamination protocols:Allergen management for soy and sunflower lecithin demands segregated production lines, elevating capex for multi-product facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Food Release Agents Market |
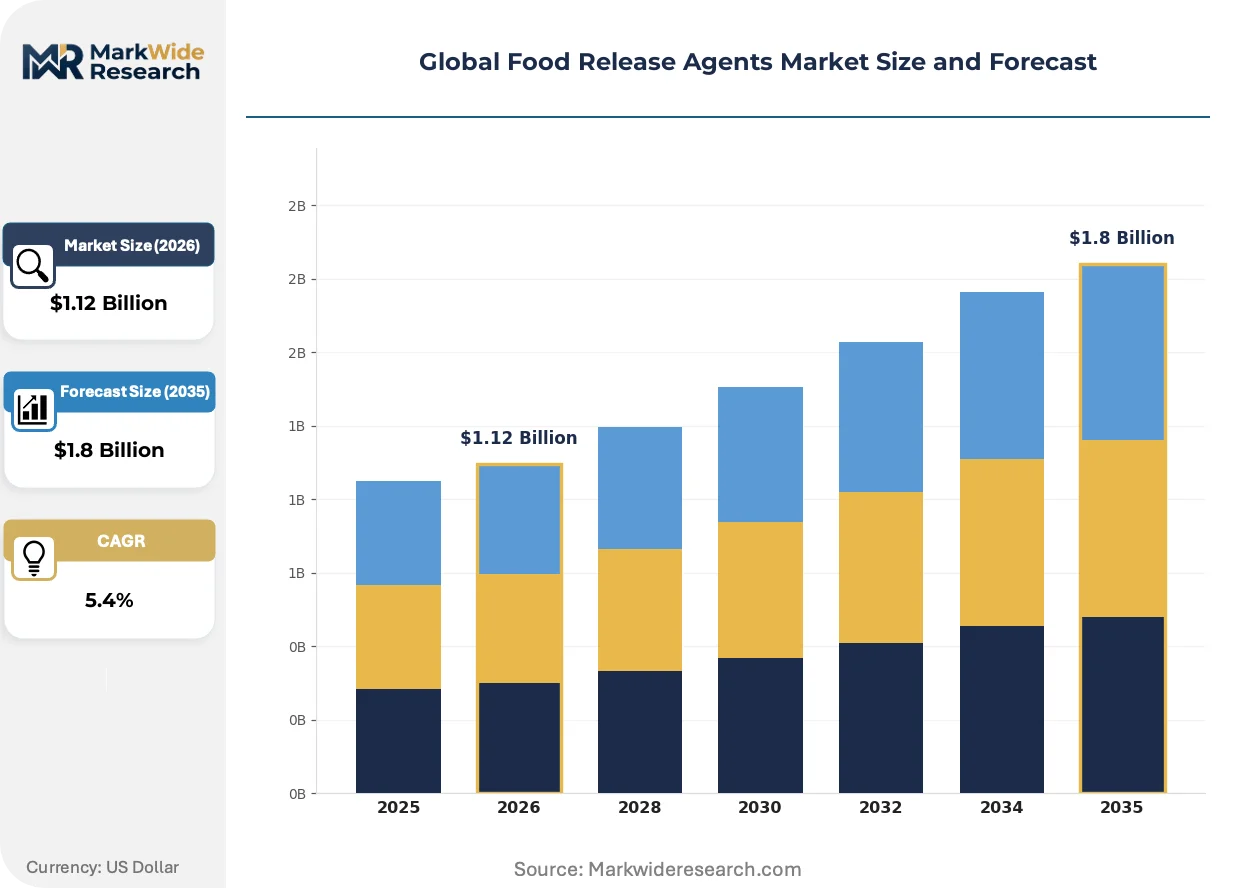
| Market Size in 2026 | $1.12 Billion |
| Market Size in 2035 | $1.8 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Soy Lecithin, Polydimethylsiloxane, Calcium Stearate, Stearic Acid, Fatty Acid Esters Application: Baked Goods, Confectionery, Dairy Alternatives, Meat Processing, Snack Foods End User: Commercial Bakeries, Confectionery Manufacturers, Foodservice Chains, Industrial Kitchens, Artisan Producers Distribution Channel: Direct Sales, Distributors, Online Retailers, Food Ingredient Suppliers, Specialty Stores |
| Companies Covered | Cargill Incorporated, Lasenor Emul SL, IFC Solutions, Avatar Corporation, Bunge Limited, Par-Way Tryson, Vantage Specialty Chemicals, Archer-Daniels-Midland Co, Dubor Groneweg GmbH & Co KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Food Release Agents Market Shifts & Advancements
Formulation science is pivoting from single-function release performance to multi-attribute compliance, integrating thermal stability, label transparency, and carbon footprint verification into unified product specifications.
Enzymatically modified lecithin is rewriting the technical ceiling for plant-derived release agents. German industrial bakeries are adopting these grades for laminated dough applications previously reserved for silicone compounds. The technology is compressing the premium-mid price spread by matching synthetic performance at 15-20% lower dosage rates.
REACH authorization requirements for cyclic siloxanes are redirecting R&D expenditure toward bio-based alternatives in European manufacturing facilities. ECHA's 2026 sunset date for D4/D5/D6 in leave-on cosmetic applications signals broader restriction patterns for food-contact materials. Confectionery multinationals with European production footprints are accelerating lecithin qualification programs.
Consolidated procurement by pan-regional bakery groups is displacing fragmented distributor relationships. Direct contracting with release agent manufacturers now governs 60% of volume for top-ten global bread and pastry producers. This concentration is most visible in the United States, where three foodservice distributors previously intermediated 80% of industrial kitchen supply.
Global Food Release Agents Market Segmentation
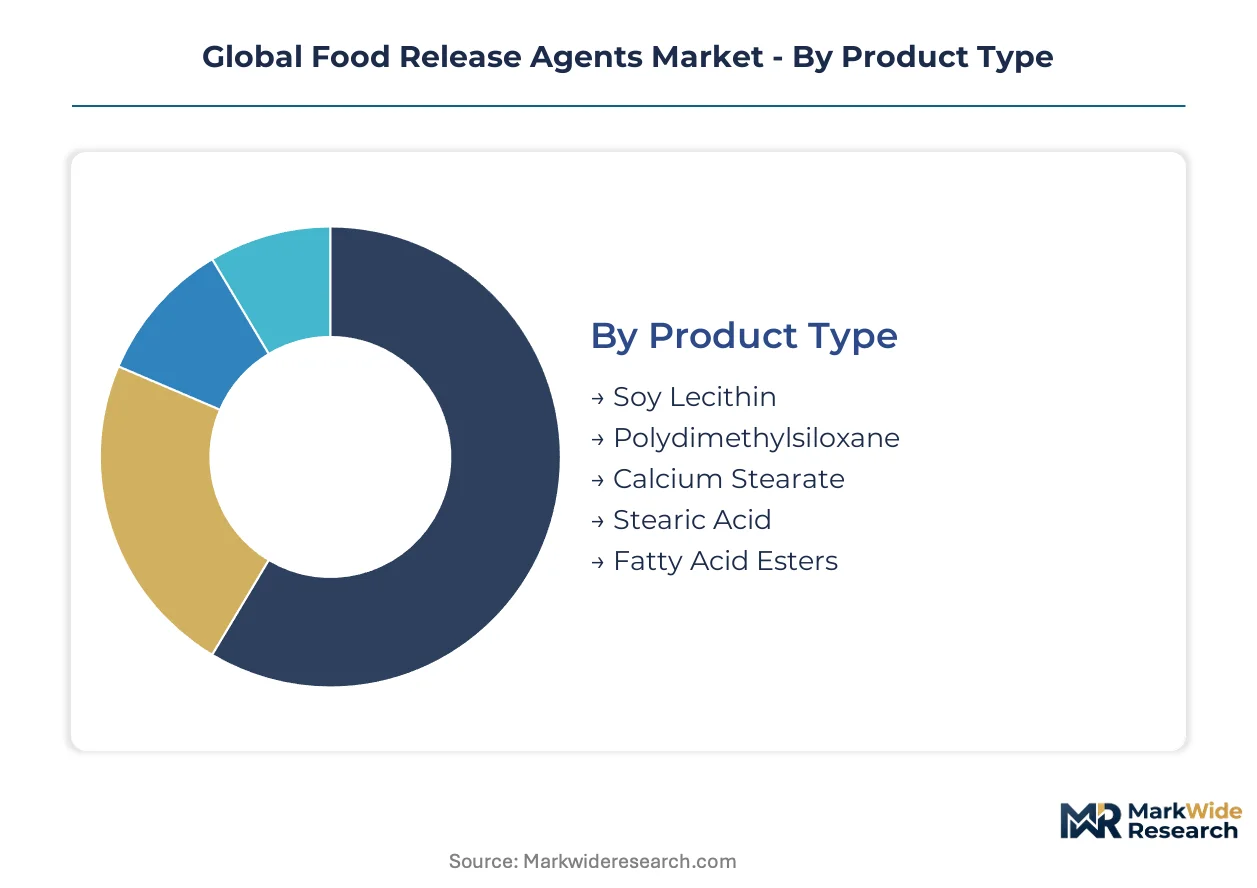
Release agent selection hinges on processing temperature thresholds, label positioning requirements, and equipment compatibility matrices. Formulators must match thermal stability specifications to application demands while navigating divergent regulatory frameworks across export destinations.
Product Type:
Technical specifications around thermal ceiling, emulsification index, and regulatory status define competitive positioning within each chemistry class.
- Soy Lecithin:Phospholipid concentrate derived from oilseed crush streams delivers emulsification and release functionality at processing temperatures up to 180°C. German industrial bakeries in Munich and Stuttgart clusters drive premium-grade procurement as REACH restrictions on synthetic alternatives tighten qualification timelines.
- Polydimethylsiloxane:Silicone polymer maintains viscosity stability across 150-220°C thermal windows, enabling clean release in high-sugar confectionery matrices. Japanese confectionery manufacturers in Kanagawa Prefecture specify medical-grade purity tiers for chocolate molding applications where surface finish defects trigger rejection.
- Calcium Stearate:Metallic soap derivative provides mold release in compressed tablet and hard candy production with minimal residue transfer.
- Stearic Acid:Saturated fatty acid serves as base stock for derivative manufacturing and direct application in low-temperature bakery coatings.
- Fatty Acid Esters:Glycerol and polyglycerol esters answer clean-label formulations in plant-based dairy alternatives where ECHA scrutiny excludes synthetic additives.
Soy lecithin leads on scale; fatty acid esters lead on momentum.
Application:
Processing environment constraints—temperature, humidity, and matrix composition—determine release agent selection more than end-product category alone.
- Baked Goods:Laminated dough, bread panning, and cake molding operations require release agents compatible with fermentation byproducts and Maillard reaction temperatures. Industrial bakeries in São Paulo, Brazil, qualify enzymatically modified lecithin grades for croissant production lines previously dependent on silicone compounds.
- Confectionery:Chocolate tempering and gummy deposition demand thermal stability above 180°C combined with neutral flavor profiles. Swiss chocolate manufacturers in the Lake Geneva corridor specify low-odor polydimethylsiloxane variants for premium praline molding.
- Dairy Alternatives:Oat, almond, and soy milk processing requires plant-derived release agents that satisfy clean-label positioning without compromising heat exchanger efficiency.
- Meat Processing:Sausage casing release and formed product extraction utilize food-grade lubricants compatible with salt and phosphate curing systems.
- Snack Foods:Extruded and puffed product applications push against silicone thermal ceilings, driving interest in lecithin-fatty acid hybrid formulations.
Baked goods anchors volume concentration; dairy alternatives exhibits the steepest expansion trajectory.
End User:
Procurement sophistication and technical service requirements stratify the customer base across formulation support needs and volume scale.
- Commercial Bakeries:High-throughput facilities with continuous mixing and depositing lines require release agents validated for 24-hour production cycles. Consolidated bakery groups in the United States now direct-contract manufacturers for 60% of release agent volume, bypassing traditional distributor intermediation.
- Confectionery Manufacturers:Precision-dependent molding and enrobing operations prioritize batch-to-batch consistency and regulatory documentation for export markets. Belgian praline producers in Flanders maintain dual-qualified silicone and lecithin sources to hedge against REACH authorization disruptions.
- Foodservice Chains:Standardized portion control across franchise networks drives aerosolized delivery system adoption for griddle and pan applications.
- Industrial Kitchens:Centralized commissary operations for hotel and institutional feeding require multi-functional release agents compatible with varied menu rotations.
- Artisan Producers:Small-batch craft bakeries in Italy and Spain source through e-commerce platforms that bypass ingredient distributors, capturing margin through direct manufacturer relationships.
Commercial bakeries dominate procurement scale; artisan producers gain share fastest through channel disintermediation.
Distribution Channel:
Channel selection reflects customer technical sophistication, volume scale, and geographic concentration relative to manufacturing footprints.
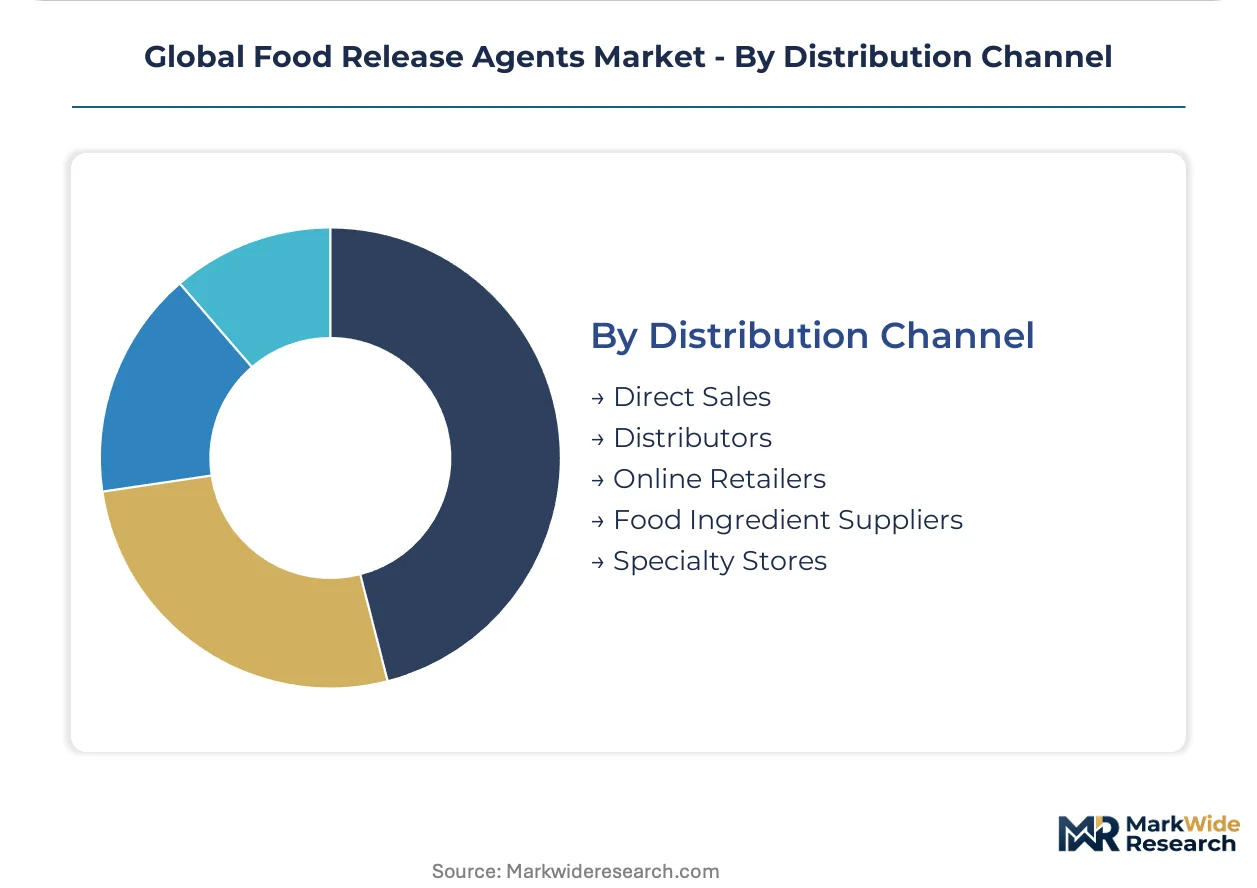
- Direct Sales:Manufacturer-to-customer relationships govern specification development, joint formulation trials, and long-term supply agreements. Cargill Incorporated leverages oilseed processing infrastructure to secure backward-integrated feedstock contracts with top-ten global bread producers.
- Distributors:Regional ingredient distributors maintain inventory positions and technical service capacity for mid-tier formulators without direct procurement scale.
- Online Retailers:E-commerce platforms enable small-batch artisan access to specialty release agents with minimum order quantities below traditional distributor thresholds.
- Food Ingredient Suppliers:Broad-line ingredient houses bundle release agents with emulsifiers, stabilizers, and other bakery additives for consolidated procurement.
- Specialty Stores:Professional kitchen supply retailers serve foodservice operators requiring immediate availability of aerosolized and bulk liquid formats.
Direct sales commands the largest volume share; online retailers expand most quickly at the segment's lower bound.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized chemists and food technologists cluster in Germany's industrial bakery corridors, anchoring European formulation expertise while regulatory pressure accelerates plant-derived alternatives across multiple jurisdictions.
United States
Quick-service restaurant chains drive aerosolized release system standardization across franchise networks. FDA GRAS oversight governs direct food-contact substance approvals, with particular scrutiny on silicone thermal stability claims. Chicago and Dallas metropolitan areas concentrate industrial bakery commissary operations demanding 24-hour production cycle validation.
Germany
Industrial bakery clusters in Munich and Stuttgart qualify enzymatically modified lecithin for laminated dough applications previously dependent on silicone compounds. ECHA REACH Annex XVII restrictions on synthetic additives compress reformulation timelines to 18-month qualification windows. The Lake Constance region houses precision confectionery manufacturers hedging against D4/D5/D6 sunset dates with dual-qualified supply sources.
China
Domestic bakery chain expansion creates pull-through demand for clean-label release agents in Shanghai and Guangzhou manufacturing hubs. GB standards diverge from REACH and FDA pathways, forcing parallel formulation tracks for export-oriented suppliers. Yangtze River Delta processing facilities face tightening SAMR enforcement on synthetic additive declarations in packaged baked goods.
Brazil
São Paulo industrial bakeries adopt non-GMO lecithin grades as FSSAI-aligned clean-label positioning penetrates South American export markets. Oilseed crush capacity concentration in Mato Grosso and Paraná secures backward-integrated feedstock cost positioning. ANVISA registration requirements for imported silicone-based agents create compliance friction for European and North American suppliers.
India
Modern trade expansion in Mumbai and Bangalore generates first-mover opportunity for plant-derived release agents as FSSAI enforcement tightens on synthetic additive use. BIS certification requirements fragment formulation strategies relative to export market specifications. Maharashtra and Karnataka state-level food processing incentives attract regional manufacturing investment from multinational ingredient houses.
Global Food Release Agents Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across three distinct capability tiers. The vendor base stratifies around oilseed processing infrastructure ownership, aerosolized delivery system specialization, and regional formulation service depth. Three archetypes dominate: backward-integrated agricultural processors, precision-delivery packaging innovators, and regional technical service specialists. Competitive dynamics center on long-term supply contract consolidation and enzymatic modification technology licensing.
Within the agricultural processor tier, Cargill Incorporated and Archer-Daniels-Midland Co exemplify scale-driven positioning anchored in oilseed crush infrastructure. Par-Way Tryson occupies a specialist position focused on aerosolized delivery systems. These three entities represent divergent strategic bets: captive feedstock security versus precision-application packaging versus broad-line ingredient distribution.
| Leading Market Players |
|---|
| Cargill Incorporated |
| Lasenor Emul SL |
| IFC Solutions |
| Avatar Corporation |
| Bunge Limited |
| Par-Way Tryson |
| Vantage Specialty Chemicals |
| Archer-Daniels-Midland Co |
| Dubor Groneweg GmbH & Co KG |
| Others |
Supply & Pricing Matrix
Specialized food chemists and formulation technologists cluster in Germany's Lake Constance and Stuttgart industrial corridors, anchoring European technical service capacity. Labor-cost differentials between these premium R&D hubs and Argentine oilseed processing zones drive 25-35% pricing-tier spreads across enzymatically modified lecithin grades.
Pricing Analysis
The bundled-vs-unbundled service split separates contract manufacturers offering joint formulation trials from commodity traders moving standard lecithin grades. Three-tier pricing structure across pharmaceutical-grade, food-grade, and industrial-grade lecithin reflects certification burden and dosage efficiency differentials. Cost compression in mid-tier soy lecithin is intensifying because Argentine crush capacity expansion outpaces near-term demand absorption. Commercial bakeries with direct-contracting scale exhibit lowest price sensitivity; artisan producers purchasing through e-commerce platforms face highest per-unit costs.
Supply Chain Analysis
Direct-to-industrial-bakery channels handle hyperscale buyer demand for validated 24-hour production cycle formulations, while regional distributors serve mid-tier formulators lacking procurement scale. Geographic supply concentration centers on Argentina, Brazil, and Germany for oilseed-derived feedstocks, with China and India emerging as secondary processing hubs. Raw material dependencies draw from soybean oil futures, sunflower seed crush streams, and palm-derived fatty acid fractions. Single-source vulnerability in non-GMO lecithin qualification programs creates exposure when weather events disrupt South American harvests. Distribution runs through consolidated procurement desks at pan-regional bakery groups, displacing traditional ingredient distributor intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin-expansion potential through enzymatic modification technology licensing that compresses premium-mid price spreads while reducing dosage rates. The shift toward clean-label formulations creates pricing power for plant-derived alternatives as REACH restrictions eliminate lower-cost silicone competition.
For Market Incumbents: Lock in long-term supply contracts with Argentine and Brazilian oilseed processors before crush capacity tightens. Secure ECHA REACH pre-registration for enzymatically modified lecithin grades to capture reformulation demand from silicone-dependent confectionery manufacturers facing D4/D5/D6 sunset dates. Deepen technical service presence in India's Maharashtra and Karnataka clusters to intercept FSSAI enforcement-driven substitution demand. For New Entrants and Emerging Players: E-commerce platforms serving Italy's and Spain's craft bakery segments represent the most penetrable channel for small-batch formulators. Target artisan producers with minimum order quantities below traditional distributor thresholds, leveraging direct manufacturer relationships to capture margin pools. Precision fermentation lipid suppliers should prioritize Swiss and Belgian praline manufacturers seeking batch-to-batch consistency for premium chocolate molding applications. For Investors and Strategic Acquirers: Agricultural processors with oilseed crush infrastructure is the most active acquirer in this space, seeking captive lecithin supply for downstream emulsifier portfolios. The 5-10 year viability window favors targets with enzymatic modification technology licenses and established REACH compliance documentation. Watch for FSSAI enforcement intensity in India as the inflection indicator signaling accelerated plant-derived substitution timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Oilseed Crush | Cargill and ADM secure captive lecithin feedstock against Argentine price volatility. |
| Enzymatic Modification Licensing | German industrial bakeries adopt modified lecithin for laminated dough previously reserved for silicone. |
| REACH Pre-Registration Investment | Early movers capture reformulation demand as ECHA restricts D4/D5/D6 cyclic siloxanes. |
| Direct-to-Artisan E-Commerce Launch | Small-batch formulators bypass distributors to capture margin from Italy's craft bakeries. |
| Precision Fermentation Capacity Buildout | Microbial phospholipids eliminate agricultural commodity exposure for premium confectionery. |
Research Methodology
Coverage spans North America, Europe, Asia-Pacific, and Latin America, with primary inputs from each region's industrial bakery and confectionery manufacturing clusters. The approach combines primary interviews with plant managers at commercial bakeries, procurement leads at pan-regional foodservice chains, technical R&D directors at ingredient houses, and regulatory affairs specialists at ECHA and FDA, validated against secondary sources including customs and trade data, SEC 10-K filings from diversified agricultural processors, food additive registration databases, and oilseed crush capacity reports from industry associations. Bottom-up volume estimates triangulate against top-down market sizing derived from downstream demand modeling.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. The analytical framework models segmentation dimensions including product chemistry class, application temperature threshold, end-user procurement sophistication, and regional regulatory compliance cluster. CAGRs derive from regression analysis of historical crush capacity expansion, substitution elasticity estimates for silicone-to-lecithin transitions, and elasticity-adjusted demand curves for clean-label positioning premiums. Industry-specific forecast inputs incorporate REACH authorization timelines and FSSAI enforcement intensity indices.
Revisions become necessary when regulatory phase-out schedules accelerate, oilseed harvest failures disrupt Argentine supply, or precision fermentation lipids achieve cost parity with agricultural phospholipids. Forecasts reflect assumptions about enzymatic modification adoption curves and distributor channel displacement velocity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Phosphated Distarch Phosphate Market
Food Additives and Ingredients
Italy Food Acidulants Market
Food Additives and Ingredients
Fish-Free Omega-3 Ingredients Market
Food Additives and Ingredients
Food and Beverage Additives Market
Food Additives and Ingredients
Egypt Food Enzymes Market
Food Additives and Ingredients
South America Food Preservatives Market
Food Additives and Ingredients
Vinasse Market
Food Additives and Ingredients
Plant Based Preservatives Market
Food Additives and Ingredients
India Food Additives Market
Food Additives and Ingredients
Food Grade Potassium Sorbate Market
Food Additives and Ingredients
Food Grade Glue Market
Food Additives and Ingredients
Clean Label Emulsifiers Market
Food Additives and Ingredients
Lime Oil Market
Food Additives and Ingredients
Australia Food Colorants Market
Food Additives and Ingredients
Microencapsulated Food Ingredient Market
Food Additives and Ingredients
Canada Food Colorants Market