
 Mexico Anti Caking Market | 2026-2036
Mexico Anti Caking Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Anti Caking Market Foresight
Food manufacturing is pivoting toward silica and calcium carbonate anti-caking agents as powdered product lines expand across snack seasonings, baking mixes, and dairy powders. BASF SE leverages its technical silica portfolio to serve multinational food brands operating in Mexico's central industrial belt. Cargill Incorporated anchors demand through its integrated food ingredient supply chain, bundling anti-caking solutions with core commodity offerings. Evonik Industries AG specializes in precipitated silica grades engineered for hygroscopic powder stability in tropical storage conditions.
Anti-caking agents are functional additives—typically inorganic minerals like silica or organic compounds like modified starch—applied at 0.5-2.0% concentration to prevent particle agglomeration in powdered and granulated products by absorbing surface moisture or creating physical barriers between crystals. The silica segment dominates volume due to its superior specific surface area and regulatory acceptance across food and pharmaceutical grades, while calcium carbonate captures margin in pharmaceutical tableting applications where USP-NF compliance commands premium positioning. Starch-based alternatives are gaining traction among clean-label food manufacturers seeking plant-derived declarations, though performance limitations in high-humidity environments constrain penetration.
COFEPRIS maintains additive approval lists under NOM-120-SSA1-1994 and subsequent amendments, requiring toxicological dossiers for new anti-caking substances that lengthen registration timelines for imported formulations. NOM-247-SSA1-2008 specifies purity thresholds for food-grade silicon dioxide and calcium salts, directly influencing supplier qualification criteria and testing protocols. SADER's agricultural input regulations extend oversight to fertilizer-grade anti-caking applications, creating dual compliance tracks for suppliers serving both food and farm sectors. Stakeholders must monitor pending updates to Mexico's food contact substance framework and align R&D investments with emerging clean-label certification schemes before regulatory windows tighten.
Market Dynamics
COFEPRIS regulatory stringency under NOM-120-SSA1-1994 amendments is compressing registration timelines for imported anti-caking formulations, forcing suppliers to localize toxicological dossier preparation and testing infrastructure within Mexico's central industrial corridor.
Growth Catalysts
- Snack seasoning expansion:Powdered spice blend manufacturers in Querétaro and Guanajuato are scaling silica-based anti-caking integration to support export-ready product lines for North American retail chains.
- NOM-247-SSA1-2008 compliance infrastructure:Domestic laboratory certification for food-grade silicon dioxide purity testing is reducing import dependency and accelerating supplier qualification cycles.
- Tropical storage adaptation:Precipitated silica grades engineered for hygroscopic stability are penetrating dairy powder and baking mix segments facing humidity challenges in Mexico's coastal distribution networks.
Market Restraints
- Calcium carbonate input volatility:Limestone feedstock price swings from Nuevo León mining operations are compressing margins for pharmaceutical tableting-grade anti-caking suppliers.
- Clean-label starch performance ceiling:Modified tapioca and rice starch alternatives fail moisture absorption benchmarks above 65% relative humidity, limiting penetration in Veracruz and Yucatán storage conditions.
- Dual-track SADER compliance:Fertilizer-grade anti-caking producers serving agricultural inputs face divergent purity thresholds from food-grade NOM standards, fragmenting quality systems.
Strategic Opportunities
- Estado de México pharmaceutical cluster:USP-NF compliant calcium carbonate for tablet compression remains underpenetrated among generic drug manufacturers expanding capacity in Toluca corridor.
- COFEPRIS pre-approval consultation pathways:Early engagement protocols for novel anti-caking substances are shortening time-to-market for suppliers investing in local regulatory affairs capabilities.
- Modified starch-crystalline cellulose hybridization:Plant-derived clean-label formulations combining mechanical barrier and moisture absorption functions are opening premium positioning in organic-certified food channels.
Industry Challenges
- Food-grade mineral toxicologist scarcity:Qualified professionals capable of preparing COFEPRIS-compliant safety dossiers are concentrated in Mexico City, creating recruitment bottlenecks for Guadalajara and Monterrey suppliers.
- Legacy packaging line retrofit costs:Automated dosing systems for 0.5-2.0% anti-caking concentration precision require capital outlays that mid-cap seasoning blenders in San Luis Potosí struggle to justify.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Anti Caking Market |
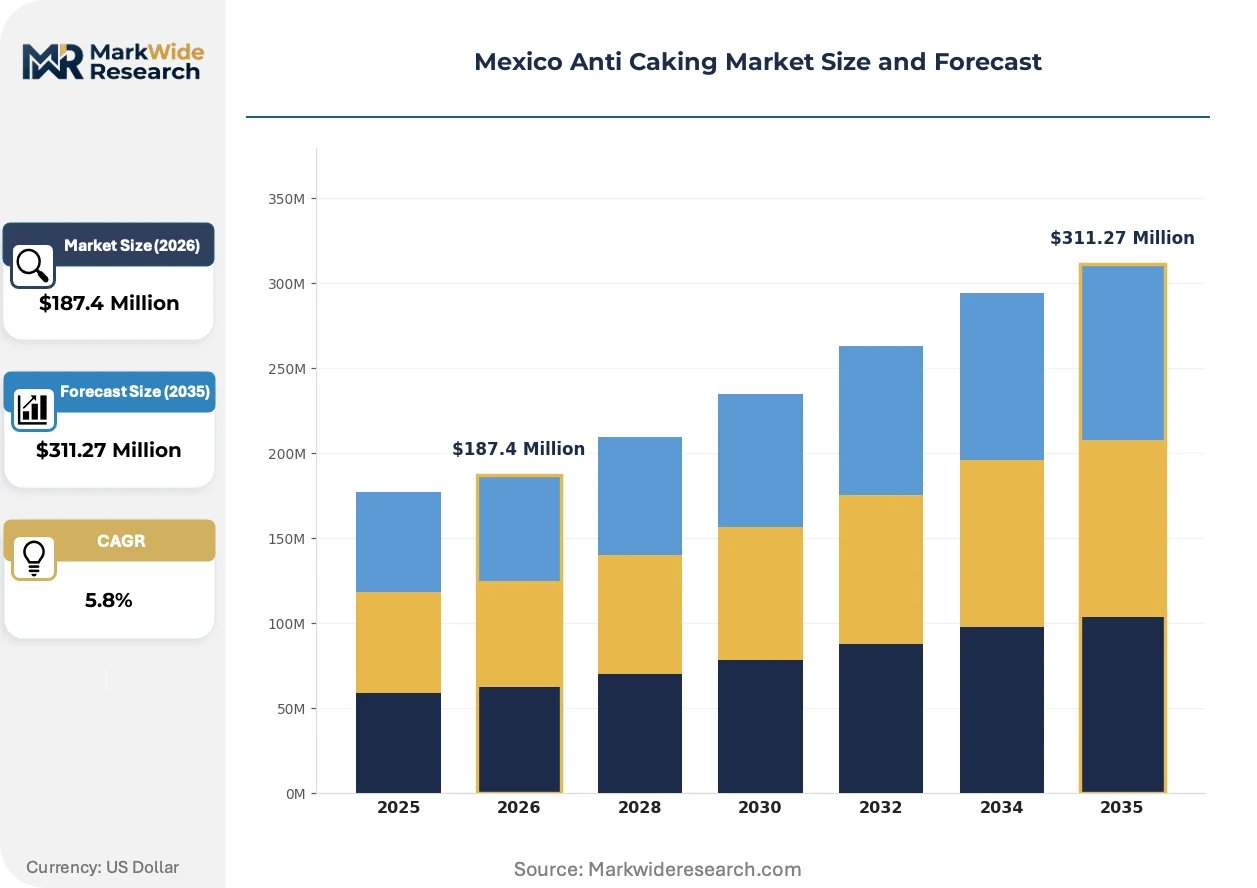
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silica, Calcium Carbonate, Starch, Magnesium Carbonate Application: Food Industry, Pharmaceuticals, Agriculture, Cosmetics End User: Food Manufacturers, Chemical Industries, Farmers, Drug Manufacturers Distribution Channel: Online Retail, Distributors, Direct Sales, Wholesalers |
| Companies Covered | BASF SE, Cargill Incorporated, Evonik Industries AG, PQ Corporation, Dr Oetker (Chemische Fabrik Budenheim KG), Agropur Ingredients, PPG Industries Inc, Solvay, Univar Solutions Inc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Anti Caking Market Shifts & Advancements
Silica surface chemistry engineering and plant-derived starch modification are converging to expand clean-label anti-caking performance envelopes, while regulatory pre-approval systems and procurement centralization reshape competitive access.
Nano-structured precipitated silica with controlled pore distribution is unifying moisture absorption and flowability functions in single-additive systems. Multinational snack manufacturers operating in Querétaro are adopting these grades at pilot scale for reduced ingredient declaration complexity. The technology is unifying previously separate anti-caking and drying agent SKUs, compressing supplier relationship overhead and simplifying inventory management for seasoning blend houses.
COFEPRIS is tightening toxicological data requirements for silicon dioxide variants under pending NOM-120 amendments, extending registration timelines for imported specialty grades. Domestic formulators with in-house analytical capabilities are capturing preferential review status. Pharmaceutical tableting applications face the steepest compliance burden, driving API manufacturers toward pre-qualified Mexican suppliers with established purity certification histories.
Centralized procurement through integrated food ingredient distributors is displacing direct supplier relationships among mid-cap seasoning and baking mix manufacturers. Guanajuato-based processors are consolidating anti-caking purchasing with starch, salt, and flavor systems under single-source agreements. This concentration is most visible in the tortilla and snack seasoning vertical, where volume commitments unlock technical service support and formulation co-development access previously reserved for multinational accounts.
Mexico Anti Caking Market Segmentation
Anti-caking agent procurement in Mexico fragments across technical specifications, regulatory pathways, and supply chain configurations that determine supplier qualification and pricing power. Understanding these segment boundaries reveals where COFEPRIS compliance costs concentrate and where formulation flexibility creates competitive openings.
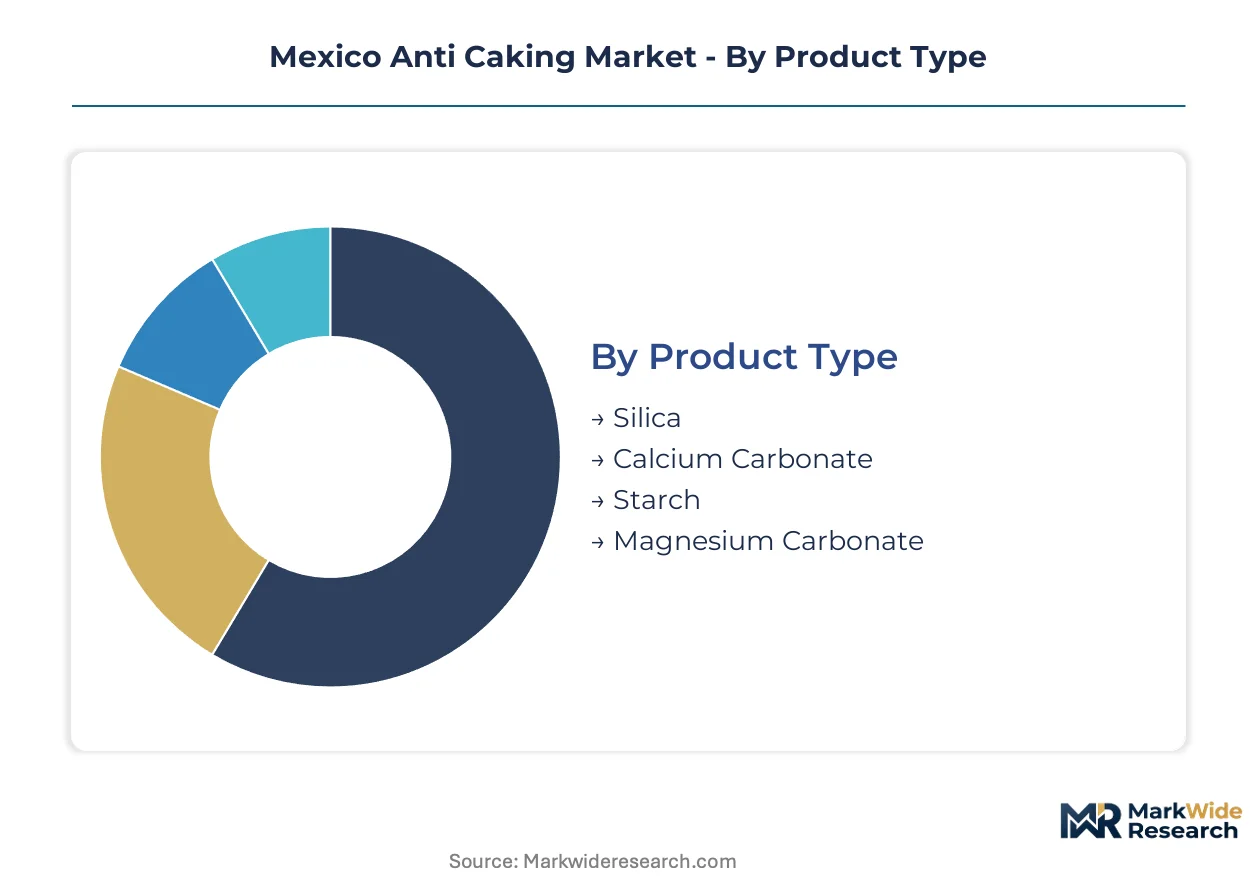
Product Type:
Silica and calcium carbonate formulations carry divergent COFEPRIS registration burdens under NOM-247-SSA1-2008 purity thresholds, while starch alternatives navigate cleaner approval trajectories with performance trade-offs.
- Silica:Precipitated and fumed silicon dioxide variants dominate food-grade applications through superior specific surface area and established toxicological dossiers. COFEPRIS maintains this segment under strictest scrutiny, requiring batch-level purity certification for imported grades. Snack seasoning manufacturers in Querétaro and Guanajuato absorb these compliance costs given silica's irreplaceable moisture absorption capacity in tropical storage conditions.
- Calcium Carbonate:Pharmaceutical tableting applications command premium positioning through USP-NF compliance, though limestone feedstock volatility from Nuevo León mining operations compresses margins. The segment splits into heavy and light precipitated grades, with the latter capturing pharmaceutical share where particle size distribution directly impacts tablet dissolution profiles.
- Starch:Modified tapioca and rice starch variants serve clean-label food channels seeking plant-derived declarations, though moisture absorption failures above 65% relative humidity constrain penetration in Veracruz coastal distribution.
- Magnesium Carbonate:Niche positioning in specialized pharmaceutical and sports nutrition applications where alkaline buffering properties complement anti-caking functions.
Silica sits at the top of the volume ranking, with starch climbing the fastest among manufacturers pursuing organic certification pathways.
Application:
End-use concentration determines regulatory jurisdiction and technical service intensity, with food and pharmaceutical channels demanding divergent purity documentation.
- Food Industry:Powdered seasonings, baking mixes, and dairy powders absorb the majority of silica-based anti-caking volume. COFEPRIS food additive approvals under NOM-120-SSA1-1994 frame compliance costs, while NOM-247-SSA1-2008 purity thresholds dictate supplier qualification protocols for silicon dioxide and calcium salts.
- Pharmaceuticals:Tablet compression and powder blend stability applications require USP-NF or equivalent pharmacopeial compliance, with API manufacturers in Toluca corridor driving demand for pre-qualified domestic suppliers.
- Agriculture:Fertilizer-grade anti-caking falls under SADER jurisdiction with divergent purity thresholds from food-grade NOM standards, fragmenting quality systems for dual-sector suppliers.
- Cosmetics:Talc replacement strategies and loose powder formulations generate modest volume with distinct INCI declaration requirements.
Food Industry maintains volume leadership, with Pharmaceuticals expanding most quickly as generic drug manufacturing capacity concentrates in Estado de México.
End User:
Customer scale and technical sophistication determine whether procurement flows through integrated distributors or direct supplier relationships.
- Food Manufacturers:Central Mexico's snack seasoning and tortilla processing clusters anchor silica demand, with multinational operators in Querétaro qualifying suppliers through centralized global protocols.
- Chemical Industries:Intermediate compound producers serving multiple downstream sectors require flexible formulation capabilities and rapid batch certification turnaround.
- Farmers:Agricultural input procurement through cooperatives and regional distributors drives fertilizer-grade anti-caking volume with price-sensitive specification tolerance.
- Drug Manufacturers:API and generic finished dose producers in Toluca corridor prioritize suppliers with established COFEPRIS pharmaceutical substance master files.
Food Manufacturers represent the largest addressable base, with Drug Manufacturers gaining share fastest through pharmaceutical cluster expansion.
Distribution Channel:
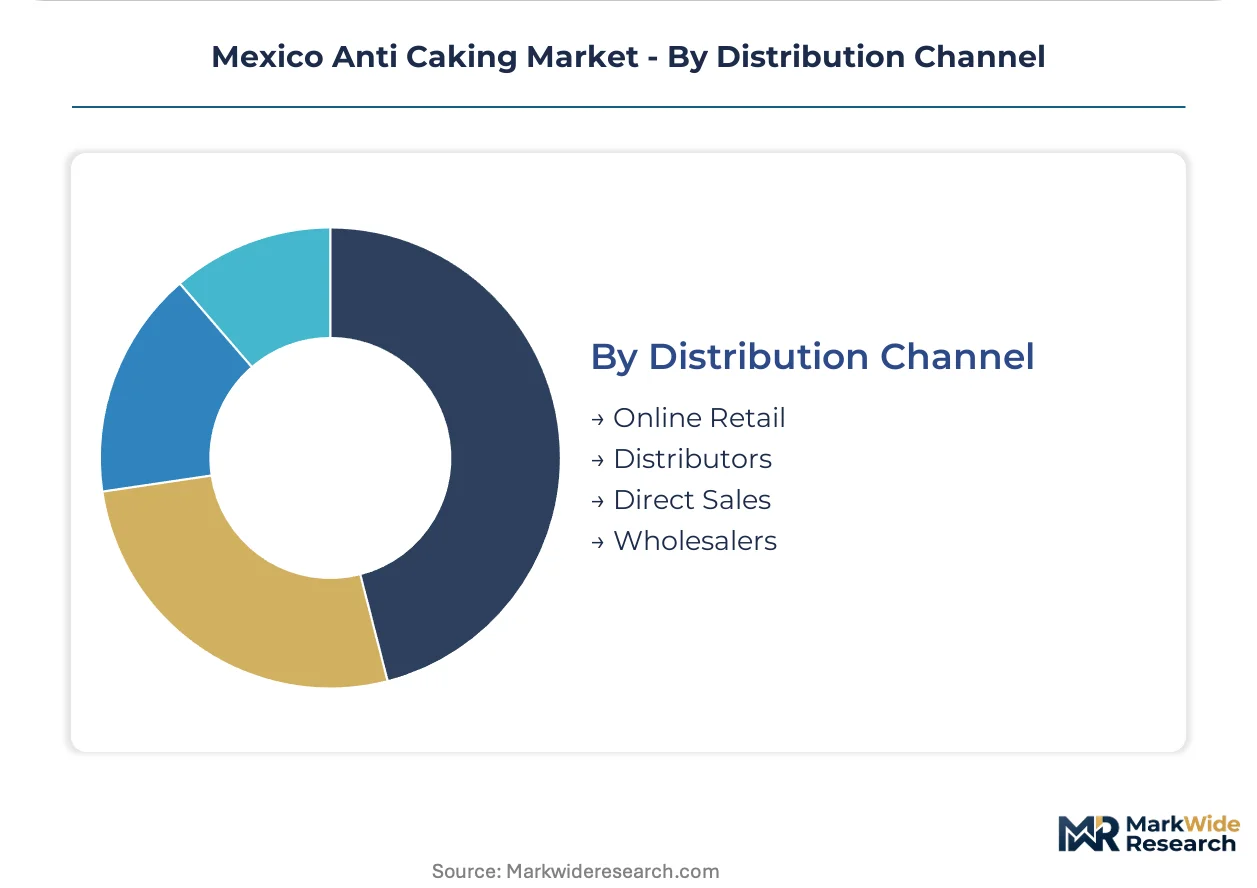
Channel selection reflects customer scale, technical service requirements, and inventory carrying cost trade-offs across Mexico's industrial geography.
- Distributors:Integrated food ingredient distributors in Guanajuato consolidate anti-caking purchasing with starch, salt, and flavor systems under single-source agreements.
- Direct Sales:Multinational food and pharmaceutical manufacturers bypass intermediaries for volume commitments unlocking technical service support and formulation co-development access.
- Online Retail:Specialty chemical marketplaces serve small-scale cosmetics formulators and research institutions with modest minimum order quantities.
- Wholesalers:Agricultural input suppliers in regional hubs bridge SADER compliance requirements for fertilizer-grade anti-caking reaching farming cooperatives.
Distributors capture the largest transaction volume, with Direct Sales expanding most quickly among centralized procurement functions of multinational operators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping supplier investment patterns as compliance cost differentials between central Mexico's COFEPRIS-certified laboratories and coastal import channels widen. Production gravity is shifting toward states with established NOM-247 testing infrastructure.
Bajío Region
Querétaro and Guanajuato snack seasoning manufacturers absorb the majority of silica-based anti-caking volume. COFEPRIS maintains regional laboratory certification under NOM-120-SSA1-1994 amendments. Multinational food brands operating in Querétaro industrial parks qualify suppliers through centralized procurement protocols.
Estado de México
Pharmaceutical tableting applications in Toluca corridor drive USP-NF compliant calcium carbonate demand. The state's generic drug manufacturing expansion prioritizes suppliers with established pharmaceutical substance master files. API producers in Cuautitlán Izcalli cluster require batch-level purity documentation.
Nuevo León
Limestone feedstock volatility from regional mining operations compresses margins for pharmaceutical-grade calcium carbonate suppliers. SADER's agricultural input regulations create dual compliance tracks for fertilizer-grade anti-caking producers. Monterrey-based chemical distributors bridge food and farm sector quality systems.
Jalisco
Guadalajara's food processing sector faces toxicologist scarcity for COFEPRIS safety dossier preparation. The state's dairy powder manufacturers test precipitated silica grades for tropical storage stability. Regional distributors consolidate anti-caking purchasing with starch and flavor systems.
Veracruz
Coastal humidity conditions above 65% relative humidity expose performance limitations in modified starch alternatives. SADER oversight extends to fertilizer-grade applications reaching farming cooperatives through regional wholesalers. Port infrastructure supports imported specialty silica grades pending domestic certification.
Mexico Anti Caking Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with multinational chemical conglomerates commanding pharmaceutical-grade certification channels while regional distributors capture mid-cap food manufacturing accounts. The vendor base concentrates around three strategic archetypes: integrated silica producers with precipitated and fumed grade portfolios, diversified food ingredient suppliers bundling anti-caking with commodity offerings, and specialized pharmaceutical excipient manufacturers. Capacity expansion and regulatory pre-qualification investments dominate competitive moves as COFEPRIS tightens registration timelines.
Among Germany-based chemical conglomerates, BASF SE and Evonik Industries AG occupy positions within the premium technical silica tier, exemplifying integrated producers with established COFEPRIS dossier histories. Cargill Incorporated anchors the diversified food ingredient archetype, representing bundled supply chain approaches that consolidate anti-caking procurement with core commodity distribution.
| Leading Market Players |
|---|
| BASF SE |
| Cargill Incorporated |
| Evonik Industries AG |
| PQ Corporation |
| Dr Oetker (Chemische Fabrik Budenheim KG) |
| Agropur Ingredients |
| PPG Industries Inc |
| Solvay |
| Univar Solutions Inc |
| Others |
Supply & Pricing Matrix
Surface chemistry engineering in precipitated silica production is compressing unit economics while concentrating supply relationships among COFEPRIS-certified domestic formulators with in-house analytical capabilities. This technical transition simultaneously elevates purity certification costs and locks out import-dependent competitors lacking localized toxicological dossier infrastructure.
Pricing Analysis
Distributor margins in Guanajuato's integrated food ingredient channels absorb the steepest compression as centralized procurement concentrates volume leverage among multinational seasoning blenders. Three-tier pricing structure across USP-NF pharmaceutical, food-grade NOM-certified, and fertilizer-grade SADER tiers separates compliance-burdened segments from commodity alternatives. Price differentiation hinges on batch-level purity documentation and COFEPRIS registration status. Margins are tightening in calcium carbonate pharmaceutical grades due to Nuevo León limestone feedstock volatility. Generic drug manufacturers in Toluca corridor exhibit highest price sensitivity; multinational snack brands in Querétaro industrial parks least.
Supply Chain Analysis
Reverse-logistics flows for rejected silica batches remain underdeveloped, forcing manufacturers to absorb disposal costs or divert off-spec material to lower-grade fertilizer applications. Supply concentrates in Germany, China, and domestic Mexican production hubs certified under NOM-247-SSA1-2008. Raw material dependencies span sodium silicate feedstock, specialized precipitating agents, and high-purity limestone. Single-source vulnerability in COFEPRIS-registered toxicologist talent constrains dossier preparation capacity. Distribution runs through integrated food ingredient distributors consolidating anti-caking with starch, salt, and flavor systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where COFEPRIS pre-approval consultation pathways for novel anti-caking substances are accelerating time-to-market advantages for prepared suppliers.
For Market Incumbents: Acquire in-house COFEPRIS toxicological dossier preparation capabilities to defend against emerging domestic formulators capturing preferential review status. Anchor backward integration into sodium silicate feedstock to buffer against specialty chemical import delays. Expand precipitated silica capacity in Querétaro corridor to lock in multinational seasoning blender volume commitments. For New Entrants and Emerging Players: Mid-cap pharmaceutical generic manufacturers in Estado de México represent the most penetrable buyer archetype currently underserved by pre-qualified domestic calcium carbonate suppliers. Establish technical service partnerships with Guadalajara dairy powder processors seeking tropical storage stability solutions. Prioritize SADER dual-track compliance infrastructure to capture fertilizer-grade anti-caking spillover from agricultural input cooperatives. For Investors and Strategic Acquirers: Valuations sit cheapest among regional distributors lacking COFEPRIS-certified laboratory partnerships but commanding sticky relationships with mid-cap food manufacturers. Long-term viability over the projection horizon rests on regulatory pre-qualification moats deepening as registration timelines extend. Target acquisition archetype: domestic formulators with established pharmaceutical substance master files and underutilized analytical capacity. Monitor pending NOM-120 amendment implementation timelines as inflection signal for import-dependent competitor displacement.| Strategic Initiative | Industry Significance |
|---|---|
| COFEPRIS Pre-Approval Consultation Investment | Shortens registration timelines for novel silica grades against import-dependent rivals. |
| Backward Integration into Sodium Silicate | Secures feedstock supply for precipitated silica production amid import volatility. |
| Pharmaceutical Substance Master File Establishment | Unlocks generic drug manufacturer procurement in Toluca corridor expansion. |
| Hybrid Starch-Cellulose R&D Partnership | Opens organic-certified food channels through plant-derived clean-label formulations. |
| Central Mexico Laboratory Certification | Captures preferential COFEPRIS review status as toxicological data requirements tighten. |
Research Methodology
Direct dialogue with COFEPRIS regulatory affairs specialists, food manufacturing procurement leads in Querétaro and Guanajuato, pharmaceutical quality directors in Estado de México, and agricultural input distributors in Veracruz grounded qualitative findings. Secondary validation drew from COFEPRIS additive approval registers, NOM-247-SSA1-2008 purity certification records, SADER agricultural input compliance filings, and customs trade data for silica and calcium carbonate imports. Bottom-up demand modeling across seasoning, dairy, baking, and pharmaceutical applications triangulated against top-down supply capacity assessments.
Segment-level value and volume trajectories across the analysis window reflect product type splits between silica, calcium carbonate, starch, and magnesium carbonate variants; application concentration in food, pharmaceutical, agricultural, and cosmetic channels; and distribution channel differentiation between integrated distributors and direct sales. CAGRs derived from regression analysis against industrial production indices, processed food output trends, and pharmaceutical manufacturing capacity expansion. Forecast inputs incorporated COFEPRIS registration pipeline velocity and NOM amendment implementation probability.
Underlying measurement precision varies by segment; silica-based food-grade applications carry tighter precision than emerging starch alternatives where performance data remains sparse. Forecasts reflect assumptions around regulatory timeline stability and limestone feedstock price continuity. Practitioners should monitor COFEPRIS NOM-120 amendment publication schedules and SADER fertilizer-grade purity threshold harmonization proposals for early revision signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Food Grade Carrageenan Market
Food Additives and Ingredients
South America Feed Anti-Caking Agents Market
Food Additives and Ingredients
Food Starch Market
Food Additives and Ingredients
South America Food Stabilizers Market
Food Additives and Ingredients
Annatto Food Colors Market
Food Additives and Ingredients
Beta Agonist Feed Additive Market
Food Additives and Ingredients
Russia Food Enzymes Market
Food Additives and Ingredients
Food Protein Ingredient Market
Food Additives and Ingredients
Asia Pacific Food Acidulants Market
Food Additives and Ingredients
United Kingdom Food Additives Market
Food Additives and Ingredients
Food Grade Release Agent Market
Food Additives and Ingredients
Global Food Texturants Market
Food Additives and Ingredients
Spain Food Additives Market
Food Additives and Ingredients
Food and Beverage Additives Market
Food Additives and Ingredients
Global Baking Powder Market
Food Additives and Ingredients
China Food Enzymes Market