
 Fat Replacers Market | 2026-2036
Fat Replacers Market Size, Share, and Industry Trends Forecast 2026-2036
Fat Replacers Market Analysis
Plant-based dairy and bakery applications is broadening as consumer preference shifts toward reduced-calorie, clean-label products. Cargill Incorporated leverages its global ingredient supply network to sustain formulation partnerships across major food manufacturers. Kerry Group PLC differentiates through taste-modulation technologies that anchor fat-reduced product lines without sensory compromise.
Fat replacers are functional ingredients engineered to mimic the physical properties of dietary fats—mouthfeel, texture, and moisture retention—while delivering substantially lower caloric density, typically through protein microparticulation, carbohydrate gelation, or lipid analogue structuring. Their primary commercial purpose centers on enabling food manufacturers to achieve nutritional-profile targets without reformulating entire production processes. Carbohydrate-based replacers occupy the largest volume position given cost parity and processing familiarity, while protein-based alternatives are gaining fastest in premium positioning where labeling transparency commands margin premiums. Fiber-based systems compete in bakery and snack channels where water-binding capacity determines shelf-stability outcomes.
FDA nutrition-labeling requirements and EFSA health-claim substantiation frameworks collectively determine which fat-replacer compositions achieve permitted status in formulated foods. The USDA dietary guidelines and Japan's Consumer Affairs Agency labeling standards further constrain permissible fat-content claims across export-bound product lines. Stakeholders must monitor evolving regulator positions on novel lipid analogues and clean-label definitions to preempt compliance-driven reformulation cycles.
Market Dynamics
Clean-label reformulation mandates from FDA and EFSA are compressing acceptable ingredient portfolios, forcing manufacturers to retire synthetic fat mimetics and validate natural alternatives through accelerated sensory testing protocols.
Growth Catalysts
- EFSA Health-Claim Substantiation:Validated satiety and metabolic-benefit frameworks enable premium positioning for protein-based replacers in European functional foods.
- Bakery Sector Water-Binding Requirements:Fiber-based systems capture formulation share as extended shelf-life specifications tighten across industrial bread production.
- Japan Consumer Affairs Agency Calorie-Display Rules:Transparent fat-content labeling drives reformulation investment in confectionery and prepared meal categories.
Market Restraints
- Oleogel Structural Instability:Lipid analogue crystallization failures during thermal cycling limit adoption in fried snack applications despite caloric advantages.
- Soy Protein Concentrate Supply Concentration:Midwestern United States crushing capacity constraints create input volatility for microparticulated protein replacers.
- REACH Registration Burden:Novel carbohydrate esters face extended ECHA evaluation timelines that delay commercial launch across EU member states.
Strategic Opportunities
- Germany Precision Fermentation Infrastructure:Cell-cultured fat precursors leverage existing biotech manufacturing clusters for next-generation lipid analogue scale-up.
- USDA BioPreferred Program:Federal procurement preference creates guaranteed offtake channel for bio-based fat replacers in institutional foodservice.
- Hybrid Protein-Carbohydrate Systems:Convergent formulation architectures address clean-label requirements while delivering superior mouthfeel in plant-based meat analogues.
Industry Challenges
- Sensory Scientist Talent Scarcity:Cross-functional expertise spanning rheology, flavor chemistry, and nutrition science commands premium compensation and extends hiring cycles.
- GRAS Self-Determination Documentation:FDA notification preparation for novel lipid analogues requires 18-24 month investment before commercial clearance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fat Replacers Market |
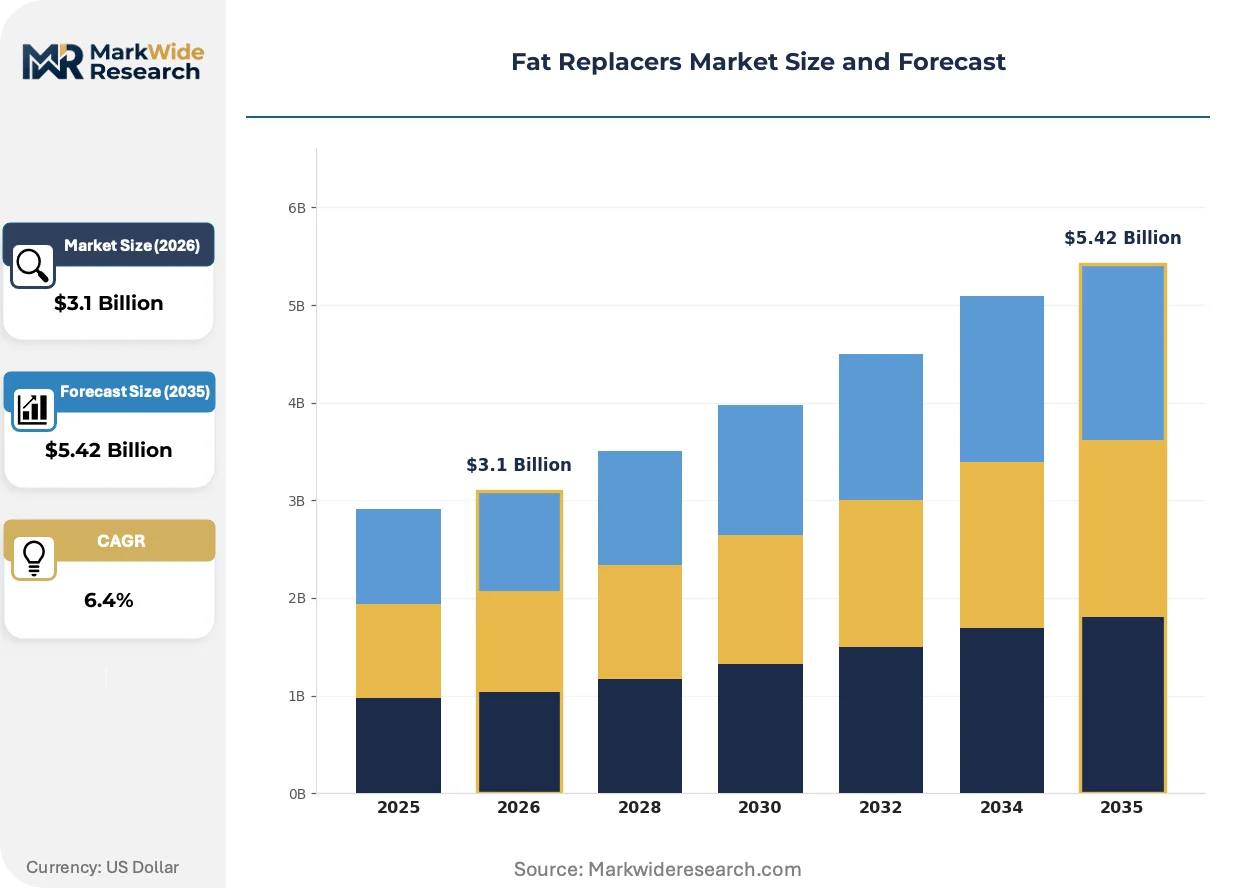
| Market Size in 2026 | $3.1 Billion |
| Market Size in 2035 | $5.42 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Protein-Based, Carbohydrate-Based, Lipid-Based, Fiber-Based Application: Dairy Products, Baked Goods, Confectionery, Sauces End User: Food Manufacturers, Restaurants, Retail Chains, Health Food Stores Form: Granular, Liquid, Powdered, Emulsified |
| Companies Covered | Cargill Incorporated, Archer Daniels Midland Company, Tate & Lyle PLC, Ingredion Incorporated, Kerry Group PLC, CP Kelco U.S. Inc., Ashland Global Holdings Inc., FMC Corporation, Koninklijke DSM N.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fat Replacers Market Emerging Trajectories
Active reformulation cycles are compressing traditional ingredient qualification timelines, with sensory validation now running parallel to regulatory submission rather than sequential. This acceleration is redrawing competitive moats around formulation expertise and rapid prototyping infrastructure.
Microencapsulated oil-in-water emulsions are unifying texture delivery and oxidative stability in reduced-fat dressings and spreads. Mid-sized dairy processors in the United States and Germany are adopting these systems at 18-month replacement cycles versus historical 5-year ingredient lock-ins. The technology is unifying what were previously separate fat-function and preservative-additive procurement decisions into single-ingredient specifications.
EFSA's 2023 updated guidance on nutrition and health claims requires randomized controlled trial data for satiety-related fat-replacer marketing. European bakery and snack manufacturers now commission clinical studies before launch, compressing product development budgets and extending time-to-market. Prepared meal and ready-to-eat segments absorb the steepest compliance costs, driving consolidation around contract research organizations with established EFSA submission track records.
Retail buyer consolidation is compressing supplier negotiation cycles and unbundling technical service from ingredient pricing. United States supermarket private-label divisions now demand dedicated application laboratories within 200 miles of their central distribution points. This geographic proximity requirement disadvantages European and Asian ingredient suppliers without North American technical infrastructure, reshaping regional competitive positioning in the contract manufacturing channel.
Fat Replacers Market Segmentation
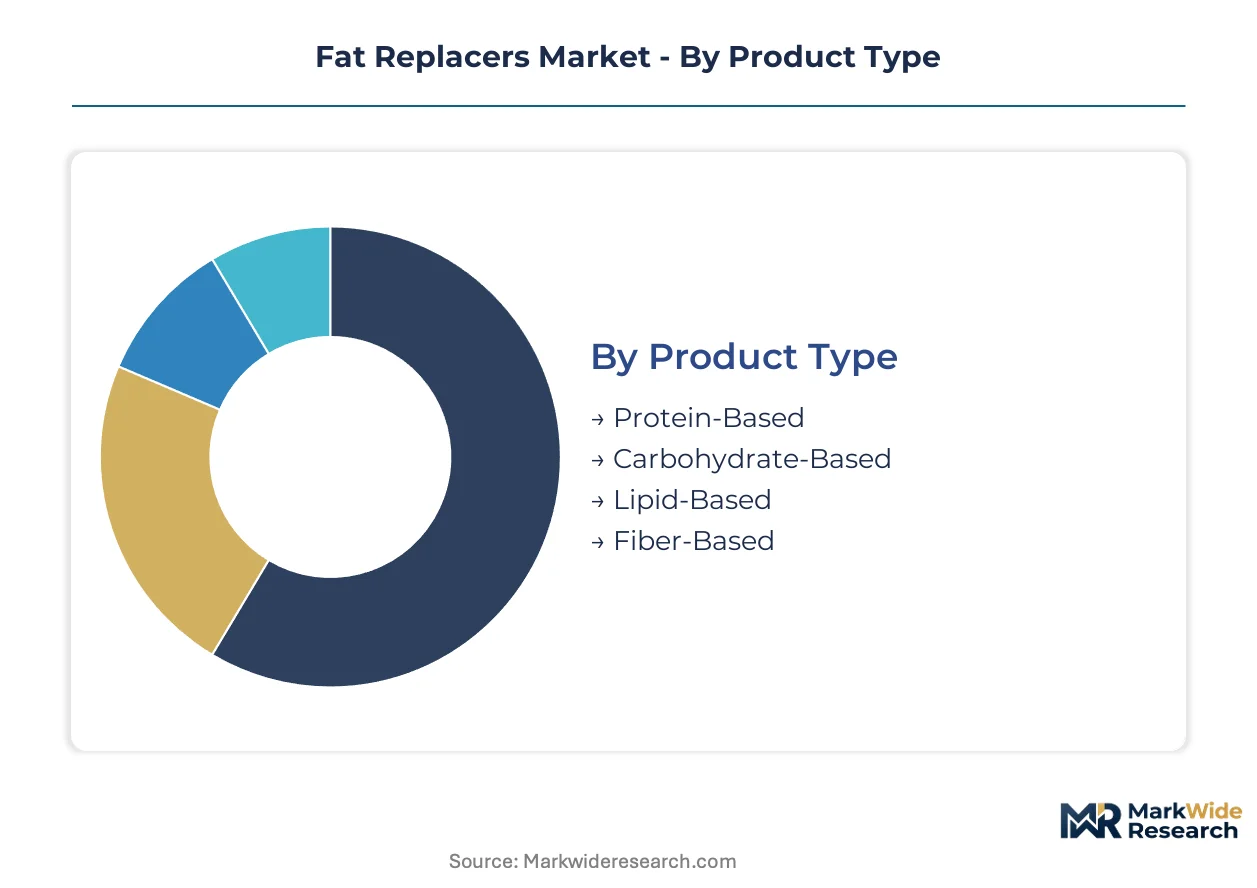
Segmentation in the fat replacers market determines procurement priorities across reformulation cycles. Manufacturers align ingredient specifications with processing infrastructure and label-positioning goals. Each dimension carries distinct margin and compliance implications.
Product Type:
Upgrade cycles in fat replacer procurement now compress from five-year lock-ins to eighteen-month qualification windows as clean-label mandates accelerate.
- Carbohydrate-Based:Starches, maltodextrins, and cellulose derivatives form hydrogels that replicate fat mouthfeel through water-binding. Industrial bakeries in Germany and the United States standardize on these systems for cost parity and processing familiarity. Shelf-stability specifications in extended-distribution bread lines reinforce procurement concentration here.
- Protein-Based:Microparticulated whey and soy proteins deliver 1-2 micron particle sizes that mimic fat globule sensory properties. Premium positioning in European functional foods leverages EFSA-validated satiety claims. Reformulation investments concentrate where label transparency commands margin premiums.
- Lipid-Based:Structured emulsions and oleogels replicate crystallization behavior of conventional fats.
- Fiber-Based:Oat hull, sugar beet, and citrus fiber systems compete on water-binding capacity in snack applications.
Volume placements concentrate in carbohydrate-based systems; the faster expansion belongs to protein-based alternatives.
Application:
Application-specific formulation requirements create divergent technical service demands from ingredient suppliers.
- Baked Goods:Reduced-fat cookies, cakes, and pastries require fat replacers that maintain aeration structure and moisture equilibrium through freeze-thaw cycles. Industrial bread production in the United States and Japan absorbs the largest formulation volumes as calorie-display rules tighten.
- Dairy Products:Ice cream, yogurt, and cheese analogues demand fat replacers with compatible melting profiles and freeze-thaw stability. German precision fermentation infrastructure supports next-generation lipid analogue development for this segment.
- Confectionery:Chocolate and coating applications impose strict tempering compatibility constraints on fat replacer selection.
- Sauces:Pourable and spoonable dressings prioritize emulsion stability over shear-thinning recovery.
Reformulation spending concentrates in baked goods; dairy applications are climbing the fastest.
End User:
Customer-type segmentation reveals procurement sophistication gaps that determine pricing realization and technical service intensity.
- Food Manufacturers:CPG companies with captive R&D facilities run parallel sensory and regulatory validation to compress launch timelines. These buyers unbundle technical service from ingredient pricing and demand dedicated application laboratories within defined geographic radii.
- Restaurants:Chain operators with centralized procurement specify fat-reduced menu items to meet calorie-disclosure obligations. Health Food Stores: Independent retailers prioritize clean-label certification over cost optimization in assortment decisions.
- Retail Chains:Private-label divisions consolidate supplier negotiations and impose geographic proximity requirements on ingredient partners.
Procurement volume concentrates among food manufacturers; health food stores are gaining share fastest.
Form:
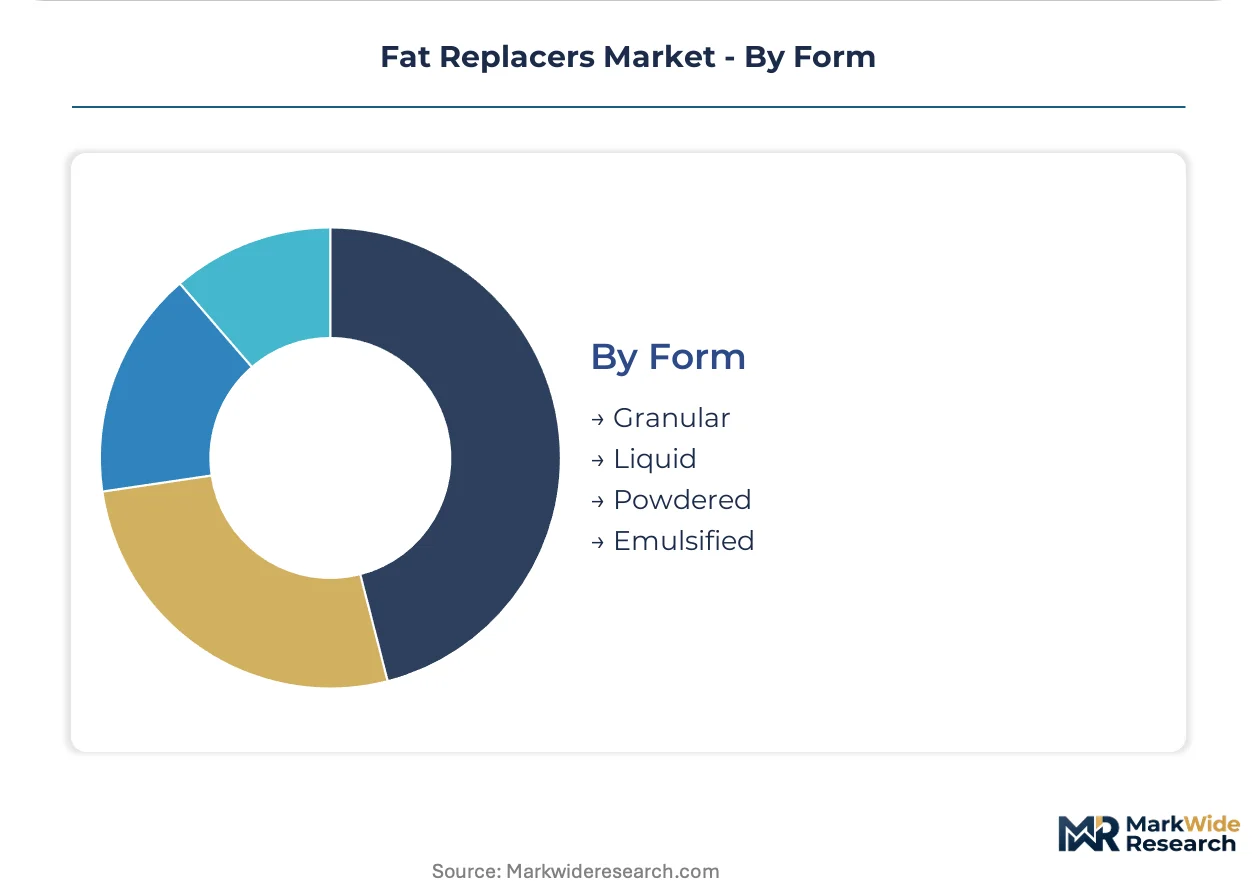
Physical form selection determines handling infrastructure requirements and dispersion uniformity in target matrices.
- Powdered:Spray-dried and agglomerated formats dominate dry-mix applications where storage stability and flowability determine handling economics. Bakery premix operations in the United States standardize on these formats for inventory efficiency.
- Liquid:Pumpable emulsions and suspensions integrate directly into continuous processing lines without rehydration steps. Prepared meal manufacturers in Japan favor liquid systems for batch consistency.
- Granular:Free-flowing particulates suit dry-blending operations with limited shear equipment.
- Emulsified:Pre-stabilized oil-in-water systems unify fat function and oxidative protection in single-ingredient specifications.
Shipment volumes concentrate in powdered formats; emulsified systems show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free Trade Zones in the United Arab Emirates and designated processing parks in Singapore concentrate multinational ingredient formulation activity. These zones offer streamlined customs protocols and co-located pilot facilities that compress qualification timelines. Reformulation investment clusters accordingly.
United States
Industrial bread manufacturers in the Midwest absorb the largest carbohydrate-based fat replacer volumes as calorie-display mandates tighten. FDA nutrition-labeling updates force synthetic mimetics into accelerated retirement cycles. Chicago and Minneapolis-St. Paul anchor technical service laboratories serving private-label retail divisions.
Germany
Precision fermentation infrastructure in Bavaria and Baden-Württemberg supports cell-cultured lipid analogue scale-up for dairy applications. EFSA health-claim substantiation frameworks determine which protein-based replacers achieve premium positioning. Munich and Stuttgart host contract research organizations with established European submission track records.
Japan
Consumer Affairs Agency calorie-display rules drive reformulation investment in confectionery and prepared meal categories. Liquid emulsion systems dominate procurement for batch-consistent processing in Osaka and Nagoya manufacturing corridors. Tokyo-based ingredient distributors coordinate just-in-time delivery to compressed production schedules.
China
Mid-scale bakery processors in the Yangtze River Delta adopt hybrid protein-carbohydrate systems for clean-label positioning. SAMR labeling standards constrain permissible fat-content claims across export-bound product lines. Shanghai and Hangzhou concentrate application development centers serving domestic and Southeast Asian markets.
India
FSSAI enforcement of packaged food labeling norms accelerates fat-reduced product line launches in Mumbai and Ahmedabad industrial zones. Health-conscious urban consumers in Delhi-NCR and Bangalore drive demand for fiber-based systems in snack applications. Domestic ingredient formulators expand technical service presence to capture reformulation budgets.
Fat Replacers Market Vendor Landscape
Branded specialists and contract manufacturers split share differently across segments. The vendor base organizes around three tiers: global ingredient conglomerates with captive supply networks, mid-scale regional formulators with application expertise, and niche technology licensors with proprietary emulsion platforms. Consolidation pressure runs highest where retail buyer consolidation compresses supplier negotiation cycles. Geographic proximity requirements and dedicated application laboratories emerge as dominant competitive moves.
Among North American agricultural processors, Cargill Incorporated and Archer Daniels Midland Company exemplify scale-driven supply network operators. European specialists Tate & Lyle PLC and Kerry Group PLC occupy positions anchored in taste-modulation and health-claim validation capabilities. Ingredion Incorporated represents the hybrid archetype bridging commodity carbohydrate supply with differentiated formulation services.
| Leading Market Players |
|---|
| Cargill Incorporated |
| Archer Daniels Midland Company |
| Tate & Lyle PLC |
| Ingredion Incorporated |
| Kerry Group PLC |
| CP Kelco U.S. Inc. |
| Ashland Global Holdings Inc. |
| FMC Corporation |
| Koninklijke DSM N.V. |
| Others |
Supply Flow & Price Mechanics
Captive crushing capacity in the Midwestern United States anchors both supply security and pricing power for soy protein concentrate, the dominant microparticulated protein input. This backward integration into oilseed processing creates cost advantages that commodity carbohydrate suppliers cannot replicate without equivalent infrastructure investments.
Pricing Analysis
Short-lead-time premiums command substantial markups in fat replacer procurement as bakery and dairy manufacturers compress qualification cycles from five-year lock-ins to eighteen-month windows. Three-tier pricing structure across premium, standard, and economy levels separates EFSA-validated protein-based systems from commodity carbohydrate hydrogels and synthetic lipid analogues. Cost compression in carbohydrate-based tiers is intensifying because Midwestern crushing capacity constraints create input volatility for protein alternatives. Private-label retail divisions demonstrate highest price sensitivity, while functional food manufacturers with captive R&D absorb premiums for validated satiety claims.
Supply Chain Analysis
Domestic-content mandates in the USDA BioPreferred Program are reshaping sourcing decisions for institutional foodservice channels, favoring North American crushing operations over imported protein isolates. Supply concentrates in the United States, Germany, and China, with the Yangtze River Delta emerging as a hybrid system formulation hub. Raw material dependencies center on soybeans, wheat starches, and citrus fiber pulp. Single-source vulnerability in Midwestern soy protein concentrate creates structural exposure to weather-driven crop failures. Distribution runs through ingredient distributors with co-located technical service laboratories in Chicago, Munich, and Shanghai.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Midwestern crushing capacity constraints prop pricing power for integrated oilseed processors, creating a supply-constrained market structure that favors incumbents with captive raw material access.
For Market Incumbents: Acquire precision fermentation infrastructure in Bavaria and Baden-Württemberg to secure cell-cultured lipid analogue scale-up capabilities. Consolidate application laboratories within 200-mile radii of major retail distribution points to defend against geographic proximity requirements. Offset margin pressure from accelerated sensory testing protocols by unbundling technical service from commodity ingredient pricing. For New Entrants and Emerging Players: Direct-to-formulator digital platforms offer lower customer acquisition costs than traditional distributor relationships for mid-scale dairy processors. Target health food store channels where clean-label certification commands margin premiums over cost optimization. Penetrate India's Mumbai and Ahmedabad industrial zones where FSSAI enforcement accelerates reformulation demand and domestic technical service presence remains underdeveloped. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to agricultural conglomerates seeking taste-modulation capabilities. Five-to-ten-year viability hinges on EFSA health-claim validation infrastructure that compresses time-to-market for European functional food launches. Monitor FDA GRAS notification timelines as inflection indicators for novel lipid analogue commercial clearance.| Strategic Initiative | Industry Significance |
|---|---|
| Application Laboratory Expansion | Geographic proximity to retail distribution points satisfies private-label procurement mandates in the United States. |
| EFSA Health-Claim Validation Investment | Randomized controlled trial data enables premium positioning for protein-based replacers in European functional foods. |
| Backward Integration into Oilseed Crushing | Captive soy protein concentrate supply insulates against Midwestern capacity constraints and input volatility. |
| Hybrid System Formulation Development | Convergent protein-carbohydrate architectures address clean-label requirements in plant-based meat analogues. |
| Precision Fermentation Capacity Buildout | German biotech manufacturing clusters support next-generation cell-cultured lipid analogue commercialization. |
Methodological Framework
Trade publications, SEC filings from ingredient conglomerates, and EFSA guidance documents formed the secondary backbone of this analysis. Primary interviews with formulation scientists at CPG companies, procurement leads at industrial bakeries, regulatory affairs specialists navigating FDA GRAS pathways, and technical service directors at regional formulators combined with bottom-up and top-down triangulation to validate volume estimates. Customs data tracking maltodextrin and protein isolate shipments, industry association reports from food ingredient federations, and patent filings covering microparticulation technologies provided additional secondary anchors.
Historical trendline analysis across installed formulation capacity, reformulation cycle frequencies, and validated health-claim counts established baseline growth patterns. The analytical framework segmented volume and value projections by product type, application, end user, and physical form across the analysis window. CAGRs derived from regression analysis of procurement intensity indices and regulatory compliance cost trajectories. Forecast inputs incorporated EFSA submission pipeline data, USDA BioPreferred program enrollment trends, and Japan Consumer Affairs Agency labeling rule implementation schedules.
Inputs from primary interviews and secondary databases were available through the study window; gaps in real-time procurement contract terms and undisclosed formulation partnerships introduce uncertainty bands around competitive share estimates. Forecasts reflect documented assumptions regarding regulatory clearance timelines and clean-label definition evolution. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Food Sources
Precision Fermentation Market
Alternative Food Sources
North America Meat Substitutes Market
Alternative Food Sources
Middle East and Africa Edible Insects Market
Alternative Food Sources
Fish Meal Alternative Market
Alternative Food Sources
Feather Meal Market
Alternative Food Sources
Vegan Sashimi Market
Alternative Food Sources
Spirulina Beverages Market
Alternative Food Sources
Vegan Eggs Market
Alternative Food Sources
Paleo Food Market
Alternative Food Sources
North America Fat Replacers Market
Alternative Food Sources
Single Cell Protein Market
Alternative Food Sources
Global Algae Protein Market
Alternative Food Sources
Global Meal Replacement Market
Alternative Food Sources
Middle East and Africa Meal Replacement Products Market
Alternative Food Sources
South America Fat Replacers Market
Alternative Food Sources
Meat Alternative Market