
 Zero Sugar Beverages Market | 2026-2036
Zero Sugar Beverages Market Size, Share, and Industry Trends Forecast 2026-2036
Zero Sugar Beverages Market Analytics
Buyer concentration across retail and convenience channels is rebalancing as mass-market grocers consolidate shelf-space negotiation power while direct-to-consumer platforms fragment purchasing patterns. PepsiCo leverages its bottling infrastructure to sustain distribution density in North American convenience networks. The Coca-Cola Company anchors zero-sugar portfolio expansion through its fountain equipment installed base. Nestlé competes in sparkling water through specialized mineral sourcing and regional spring water control.
Zero sugar beverages are non-alcoholic drinks formulated without sucrose, fructose, or other caloric sweeteners, typically employing non-nutritive alternatives such as aspartame, sucralose, steviol glycosides, or monk fruit extract to achieve sweetness while maintaining negligible caloric content below regulatory labeling thresholds. These products serve consumers managing glycemic response, weight control objectives, or dental health concerns across commercial and household consumption contexts. Sodas retain the largest revenue pool though sparkling water captures the fastest volume trajectory as health positioning shifts consumer preference away from caramel coloring and phosphoric acid associations. Energy drinks concentrate margin in functional ingredient premiums while iced tea segments navigate between brewed authenticity claims and zero-calorie formulation acceptance.
The FDA governs non-nutritive sweetener safety thresholds and GRAS determinations in the United States while the EFSA establishes acceptable daily intake benchmarks across European markets, with both frameworks directly constraining formulation latitude and label claim permissibility. China's SAMR implements GB standards for food additive usage that condition market entry for international brands. Stakeholders must monitor evolving sweetener safety reviews and front-of-package labeling mandates to anticipate reformulation costs and regional portfolio prioritization shifts.
Market Dynamics
Sugar taxation frameworks across Mexico, the United Kingdom, and South Africa are forcing manufacturers toward systematic reformulation, compressing lead times between regulatory announcement and portfolio overhaul while elevating R&D allocation toward non-nutritive sweetener alternatives.
Growth Catalysts
- Millennial Health Prioritization:Health-conscious millennials now drive category expansion across retail and digital channels, creating sustained pull for clean-label zero-sugar alternatives in household and commercial consumption contexts.
- Sugar Taxation Frameworks:Mexico's IEPS tax, the United Kingdom's Soft Drinks Industry Levy, and South Africa's Health Promotion Levy reshape formulation standards and push manufacturers toward accelerated reformulation cycles.
- Steviol Glycoside Extraction Advances:Biotechnology improvements in steviol glycoside purification are lowering unit costs and expanding supply availability for natural-positioned zero-sugar beverages.
Market Restraints
- Stevia Supply Concentration:Raw stevia leaf sourcing concentrates in Chinese agricultural regions, exposing manufacturers to climate volatility and trade friction in natural sweetener supply chains.
- Aspartame Safety Reviews:Ongoing WHO/IARC re-evaluations of aspartame carcinogenicity risk create regulatory overhang and force parallel formulation tracks pending scientific consensus.
- Functional Beverage Substitution:Electrolyte-enhanced waters and adaptogenic drinks capture wellness-oriented consumers seeking benefits beyond caloric reduction alone.
Strategic Opportunities
- India Market Underpenetration:India's FSSAI regulatory framework for non-nutritive sweeteners remains less restrictive than Western equivalents, opening white space for early-mover portfolio establishment in urban centers.
- Direct-to-Consumer Subscription Models:Digital-native beverage brands bypass traditional retail slotting fees through specialized zero-sugar curated boxes, capturing lifetime value data and reducing customer acquisition costs.
- Front-of-Package Labeling Mandates:Chile's black octagon warning labels and impending EU Nutri-Score expansions create competitive advantage for pre-positioned zero-sugar portfolios in markets adopting mandatory nutritional disclosure.
Industry Challenges
- Flavor Chemist Talent Scarcity:Formulation expertise in masking non-nutritive sweetener aftertaste remains concentrated among veteran flavor houses, constraining in-house R&D team scaling for emerging brands.
- Clean-Label Certification Timelines:Non-GMO Project verification and organic certification processes extend 12-18 months, delaying product launches and compressing innovation-to-shelf windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Zero Sugar Beverages Market |
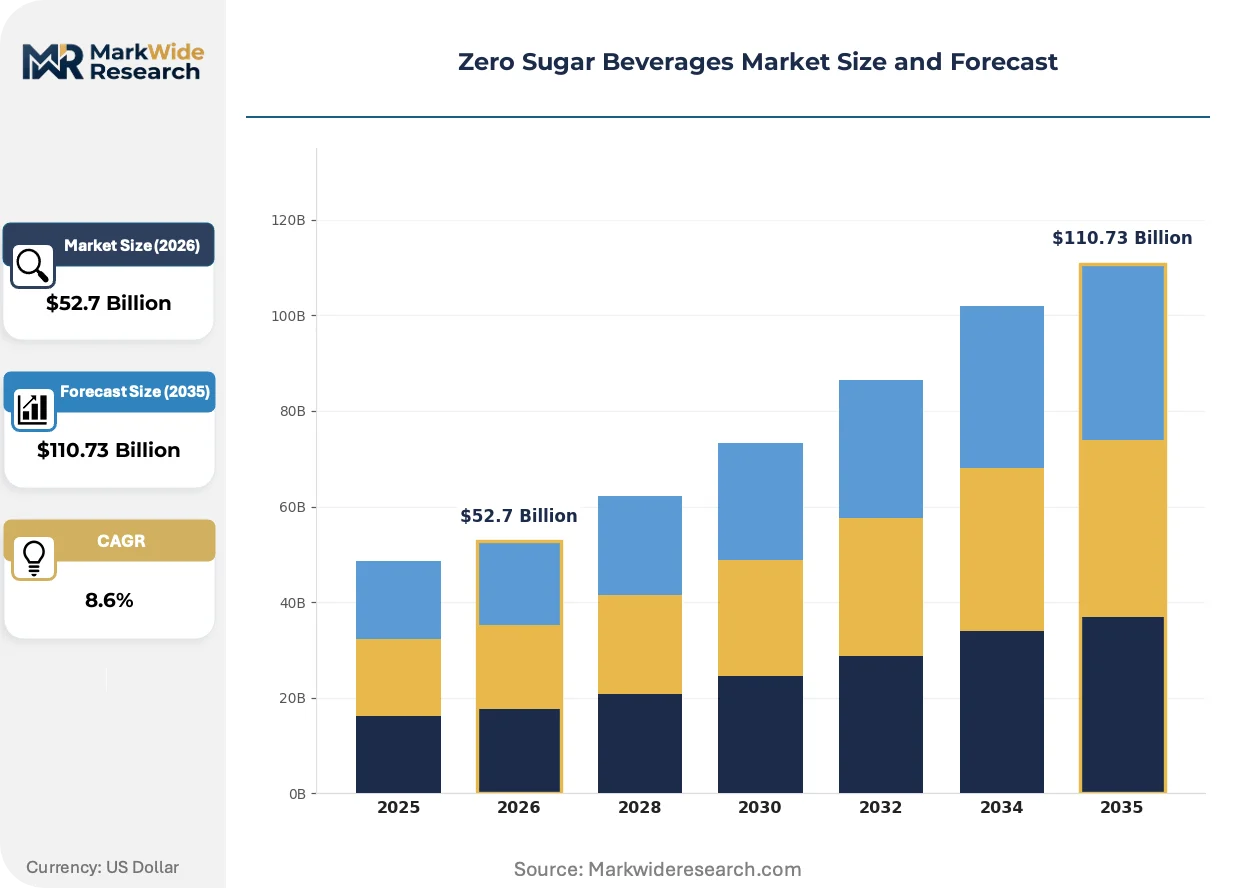
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $110.73 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sodas, Sparkling Water, Energy Drinks, Iced Tea End User: Health Conscious Consumers, Athletes, Diabetics, Millennials Size: 12 oz, 16 oz, 20 oz, 24 oz Distribution Channel: Retail Stores, Online Marketplaces, Convenience Stores, Wholesalers |
| Companies Covered | Keurig Dr Pepper, Molson Coors Beverage Company, The Coca-Cola Company, Suntory Holdings Limited, Carlsberg Group, PepsiCo, Monster Beverage Corporation, Zevia, Nestlé, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Zero Sugar Beverages Market Evolving Landscape
Biotechnology advances in rare sugar production and enzymatic conversion are compressing cost curves for next-generation sweeteners, while regulatory pressure on legacy artificial options accelerates substitution timelines across major beverage portfolios.
Enzymatically produced allulose is rewriting cost economics for caloric-reduction claims, enabling beverage manufacturers to achieve 70% sweetness equivalence with negligible glycemic impact. Mid-sized functional drink producers in the United States are adopting allulose at the fastest pace, drawn by FDA-exempt status from added sugar labeling. This technology is compressing price premiums between zero-sugar and full-sugar formulations, eroding the historical 40-60% shelf price gap that constrained mass-market penetration.
The European Union's 2023 extension of Nutri-Score mandatory adoption to commercial foodservice is tightening formulation standards across fountain and vending channels. Manufacturers serving EU institutional accounts must now reformulate to achieve B-grade or higher scores, eliminating caramel coloring and phosphoric acid from legacy cola recipes. Germany's out-of-home beverage sector is responding fastest, with major contract foodservice operators demanding A-grade portfolio options by 2026.
Health-conscious procurement in corporate workplace refreshment programs is fragmenting traditional vending contracts. Facility managers in United States tech corridors are unbundling beverage service from single-supplier agreements, instead curating multi-brand zero-sugar selections through micro-market platforms. This pattern is most visible in Austin, Seattle, and San Francisco metropolitan clusters, where employee wellness metrics directly influence catering vendor selection criteria.
Zero Sugar Beverages Market Segmentation
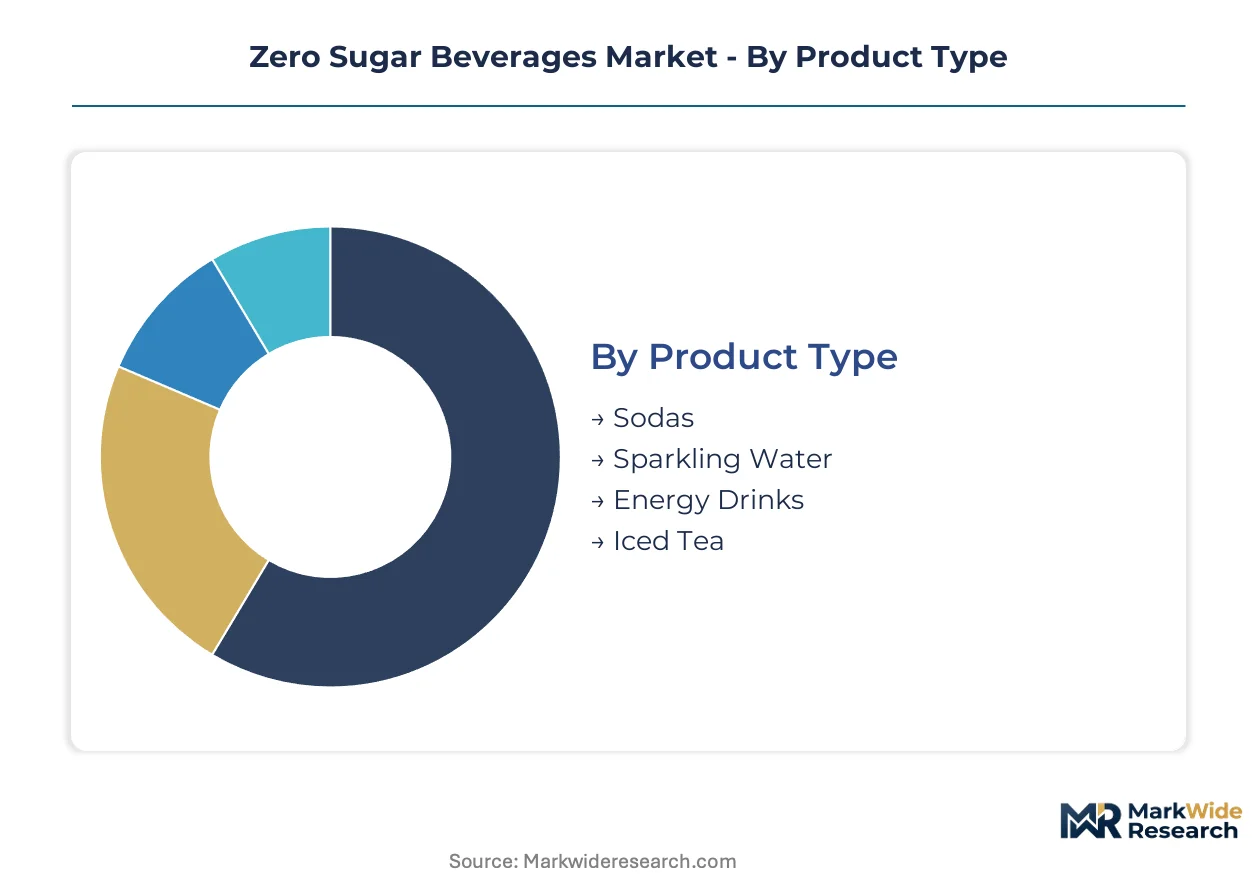
Zero sugar beverage portfolios require granular segmentation to align formulation investments with distinct consumption occasions and channel economics. Each dimension reveals divergent margin structures and regulatory exposure that reshape manufacturer resource allocation.
Product Type:
Standalone beverage categories operate as finished goods ready for immediate consumption, while embedded ingredient systems supply foodservice and private-label channels with bulk sweetener premixes.
- Sodas:Carbonated soft drinks rely on caramel coloring and phosphoric acid combinations masked by high-intensity sweetener blends. Demand clusters in the United States and Mexico where fountain equipment installed bases lock in volume commitments despite sugar taxation pressure.
- Sparkling Water:Unflavored and essenced variants achieve sweetness through trace natural flavor oils rather than non-nutritive additives, positioning outside GRAS scrutiny while capturing consumers seeking clean-label alternatives. German and United Kingdom retail channels show the steepest volume climb as Nutri-Score labeling elevates water-based options.
- Energy Drinks:Functional ingredient stacks combine caffeine, taurine, and B-vitamins with sucralose or ace-K sweetening for metabolic neutrality.
- Iced Tea:Brewed tea extracts face formulation tension between authenticity claims and zero-calorie acceptance in Southern United States markets.
Volume placements concentrate in sodas; the faster expansion belongs to sparkling water.
End User:
Cost tier stratification separates premium-positioned wellness seekers from price-sensitive medical necessity buyers, with distinct channel access and brand loyalty patterns.
- Health Conscious Consumers:Broad demographic spanning glycemic management, weight control, and dental health motivations drives household pantry stocking of multi-format portfolios. Digital subscription penetration runs highest among this cohort in Austin, Seattle, and San Francisco metropolitan clusters.
- Millennials:Cohort-specific preference for transparent sourcing and environmental claims shapes willingness-to-pay thresholds for certified sustainable packaging and regenerative agriculture ingredients. China's tier-one cities and Germany's urban centers show parallel demand density.
- Athletes:Performance-oriented consumption occasions prioritize electrolyte balance and rapid hydration alongside caloric neutrality.
- Diabetics:Medical necessity purchasing concentrates in pharmacy-adjacent retail and healthcare institutional channels with reimbursement sensitivity.
Health conscious consumers anchor current volume; millennials are climbing the fastest as wellness procurement enters corporate refreshment programs.
Size:
Application context dictates format selection, with on-the-go portability competing against household economy and foodservice fountain scale.
- 12 oz:Standard single-serve can format optimized for vending machine compatibility and cold vault placement in convenience networks. United States interstate highway corridors and Mexico's OXXO store footprint sustain this format's dominance.
- 16 oz:Expanded can and bottle formats capture foodservice fountain alternatives and quick-service restaurant combo meal attachments. South Africa's sugar-tax tier thresholds create price discontinuities that push volume toward this mid-tier option.
- 20 oz:Resealable bottle format targets extended consumption occasions and workplace desk retention.
- 24 oz:Economy multi-serve packaging reduces per-ounce cost for household pantry stocking in warehouse club channels.
12 oz placements concentrate in immediate consumption; 16 oz is expanding most quickly as taxation thresholds reshape optimal purchase sizing.
Distribution Channel:
Supply concentration varies dramatically, with consolidated retail buyers extracting slotting concessions while fragmented digital platforms enable direct brand-consumer relationships.
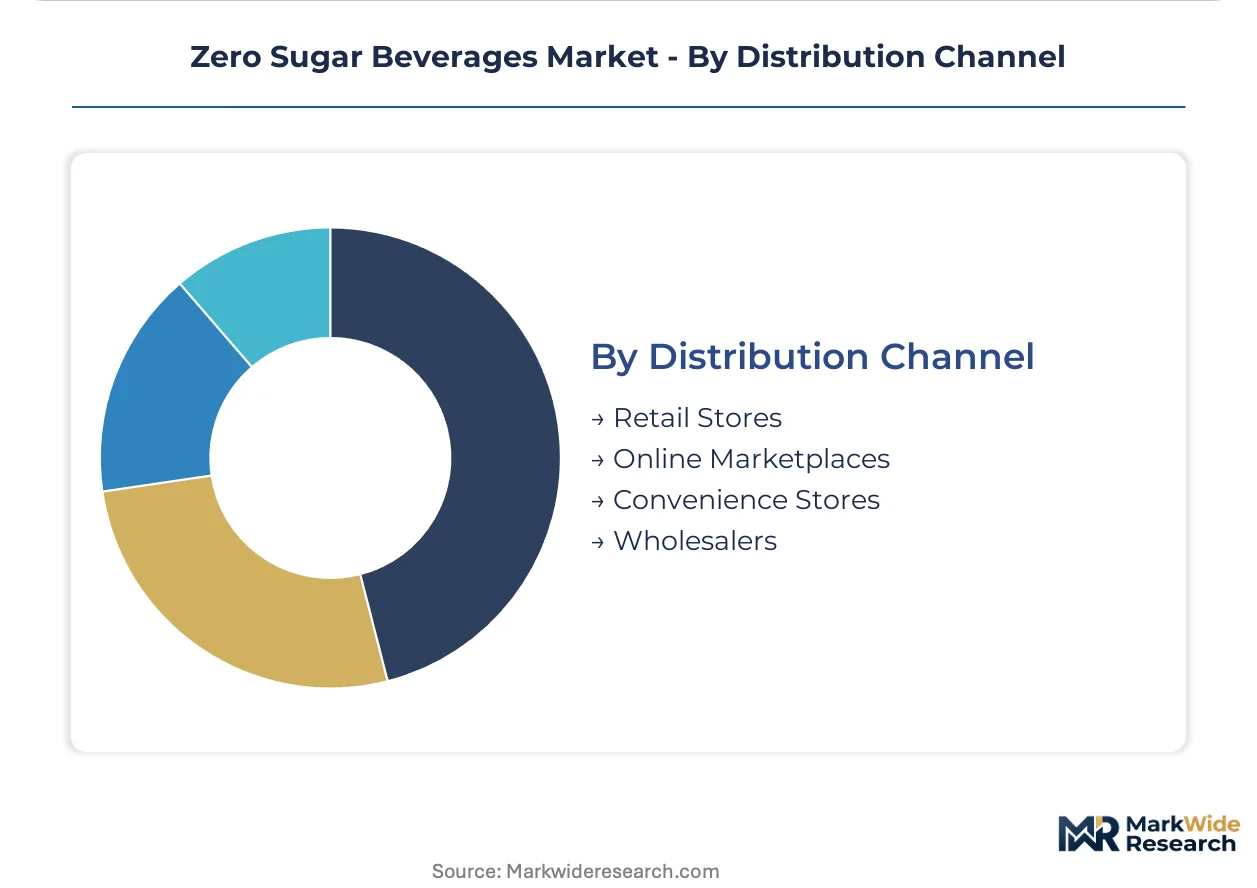
- Retail Stores:Mass-market grocers and supermarket chains command planogram negotiation power that determines shelf space allocation between zero-sugar and full-sugar SKUs. Walmart and Kroger's United States footprint exemplifies this channel's gatekeeper function.
- Online Marketplaces:Amazon and Tmall platforms enable subscription-based replenishment and curated variety packs that bypass traditional retail slotting fee structures. China's digital commerce penetration for beverages exceeds Western benchmarks.
- Convenience Stores:Impulse-driven cold vault placement depends on bottler distribution density and cooler equipment placement contracts.
- Wholesalers:Institutional and foodservice volume flows through specialized beverage distributors with fountain equipment maintenance capabilities.
Retail stores anchor volume concentration; online marketplaces are gaining share fastest as subscription models capture lifetime value data.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for zero sugar beverages concentrates in markets combining large consumer bases with active sugar taxation regimes. Regulatory pressure on caloric sweeteners varies sharply across geographies, forcing manufacturers to maintain parallel formulation portfolios.
United States
Millennial wellness procurement and corporate refreshment program fragmentation drive category expansion. The FDA governs non-nutritive sweetener GRAS determinations and added sugar labeling thresholds. Austin, Seattle, and San Francisco metropolitan clusters exhibit the highest digital subscription penetration for curated zero-sugar selections.
China
Urban tier-one consumers and expanding middle-class health awareness create sustained pull for clean-label alternatives. SAMR implements GB standards for food additive usage that condition market entry for international brands. Shanghai and Beijing retail channels show accelerating sparkling water adoption as Nutri-Score-equivalent disclosure norms emerge.
Germany
Nutri-Score labeling mandates and out-of-home beverage sector procurement standards tighten formulation requirements. EFSA establishes acceptable daily intake benchmarks for non-nutritive sweeteners across European markets. Contract foodservice operators in Berlin and Munich metropolitan areas demand A-grade portfolio options by 2026.
Mexico
Sugar taxation through IEPS compresses full-sugar beverage economics and accelerates reformulation cycles. Fountain equipment installed bases lock in volume commitments despite regulatory pressure. Mexico City and Guadalajara urban centers concentrate demand for mid-tier 16 oz formats that navigate tax tier thresholds.
United Kingdom
The Soft Drinks Industry Levy reshapes manufacturer portfolio allocation toward zero-sugar variants. Front-of-package labeling expansions create competitive advantage for pre-positioned clean-label offerings. London and Manchester retail networks show steepest volume climb for sparkling water as caramel coloring associations weaken.
Zero Sugar Beverages Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue direct-to-consumer subscription models and functional ingredient specialization. The market exhibits consolidated bottling infrastructure alongside fragmented digital-native brand proliferation. Three archetypes dominate: multinational beverage conglomerates with fountain equipment lock-in, regional mineral water specialists with spring source control, and venture-backed direct-to-consumer brands leveraging curated box economics. Competitive moves center on portfolio reformulation acceleration and micro-market platform partnerships.
Among multinational beverage conglomerates, The Coca-Cola Company, PepsiCo, and Nestlé occupy positions spanning fountain infrastructure, bottling density, and regional spring water control. The Coca-Cola Company exemplifies equipment-installed-base anchoring through fountain network relationships. PepsiCo represents distribution density maintenance in North American convenience networks. Nestlé sits within the mineral sourcing specialist tier through regional spring water portfolio management.
| Leading Market Players |
|---|
| Keurig Dr Pepper |
| Molson Coors Beverage Company |
| The Coca-Cola Company |
| Suntory Holdings Limited |
| Carlsberg Group |
| PepsiCo |
| Monster Beverage Corporation |
| Zevia |
| Nestlé |
| Others |
Value Network & Pricing Analysis
EU Nutri-Score expansion gates qualified supply for premium-tier zero-sugar portfolios while compressing margin structures for legacy formulations that fail B-grade thresholds. Manufacturers achieving A-grade certification capture pricing power in German and French retail channels where procurement committees enforce mandatory disclosure standards.
Pricing Analysis
Volume concentrates in mass-market 12 oz cans through convenience networks while margin pools in functional energy drink premiums and direct-to-consumer subscriptions. Three-tier pricing structure across premium, standard, and economy levels separates certified clean-label SKUs from conventional zero-sugar variants and private-label alternatives. Price differentiation hinges on organic certification status and regenerative agriculture ingredient sourcing. Cost compression in the standard tier is intensifying because stevia supply concentration in Chinese agricultural regions exposes formulations to climate volatility and trade friction.
Supply Chain Analysis
Direct-to-retail distribution handles hyperscale grocer demand through bottler infrastructure while specialized beverage distributors manage fountain equipment maintenance for foodservice accounts. Raw stevia leaf sourcing concentrates in Chinese provinces, with allulose enzymatic production scaling fastest among United States mid-sized functional drink producers. Supply chain risk centers on single-source vulnerability for natural sweetener extraction where biotechnology purification capacity remains geographically concentrated. Distribution runs through consolidated retail buyers extracting slotting concessions alongside fragmented digital platforms enabling subscription-based brand relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Zero-sugar beverage formulation is transitioning from artificial sweetener legacy systems toward rare sugar and enzymatic alternatives, with allulose production economics displacing historical 40-60% shelf price premiums.
For Market Incumbents: Deepen backward integration into steviol glycoside purification capacity to offset Chinese agricultural concentration risk. Anchor fountain equipment relationships through A-grade Nutri-Score portfolio pre-positioning before EU commercial foodservice mandates tighten. Incumbent bottling density in North American convenience networks remains defensible against digital-native entrants only if paired with rapid reformulation cycles pending WHO aspartame safety reviews. For New Entrants and Emerging Players: Micro-market platform operators represent the most penetrable channel partner type for bypassing traditional retail slotting fee structures. Target corporate workplace refreshment programs in Austin, Seattle, and San Francisco metropolitan clusters where wellness procurement metrics influence vendor selection. India's FSSAI regulatory framework offers white-space establishment in urban tier-one cities with less restrictive non-nutritive sweetener standards than Western equivalents. For Investors and Strategic Acquirers: Stevia biotechnology purification facility announcements are the leading indicator that natural-positioned supply constraints are easing and premium-tier margin compression will follow. Long-term viability favors portfolios with enzymatic allulose production capabilities and direct-to-consumer data infrastructure over legacy artificial sweetener dependencies. Acquisition target archetype: venture-backed brands with curated subscription economics and micro-market platform partnerships in high-density urban corridors.| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Allulose Scale-Up | Compresses cost curves for caloric-reduction claims while maintaining FDA-exempt added sugar labeling status. |
| Direct-to-Consumer Subscription Launch | Captures lifetime value data and reduces customer acquisition costs through curated zero-sugar variety boxes. |
| Micro-Market Platform Partnership | Penetrates corporate workplace refreshment procurement unbundling from traditional single-supplier vending contracts. |
| EU Nutri-Score A-Grade Certification | Secures competitive positioning ahead of mandatory commercial foodservice adoption in German institutional channels. |
| Stevia Biotechnology Backward Integration | Reduces exposure to Chinese agricultural climate volatility and trade friction in natural sweetener supply chains. |
Research Methodology
Multi-period observation of sugar taxation implementation timelines and reformulation cycle velocities anchored the trend analysis, supplemented by interviews with beverage R&D directors, retail category buyers, flavor house formulation chemists, and foodservice procurement managers. Secondary validation drew from FDA GRAS determination filings, EFSA acceptable daily intake benchmarks, SAMR GB standard publications, Nielsen retail audit data, and customs records for stevia leaf import flows. Bottom-up SKU-level volume modeling and top-down macroeconomic demand drivers were triangulated to constrain forecast variance.
Segment-weighting across product type, end-user motivation, format size, and distribution channel dimensions shaped the analytical framework across the analysis window. CAGRs were derived from category growth rate differentials applied to base-year revenue pools, with sparkling water volume trajectories and energy drink margin premiums serving as industry-specific forecast inputs. Regional regulatory phase-in schedules and front-of-package labeling mandate calendars conditioned geographic growth assumptions.
Caveats apply where WHO aspartame safety review outcomes or EU Nutri-Score expansion timelines could materially shift the outlook for artificial sweetener formulation economics and premium-tier pricing power. Forecasts reflect assumptions about biotechnology cost compression rates and sugar taxation framework adoption patterns that warrant periodic stress-testing of base assumptions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Non-Alcoholic Beverages
Non-Alcoholic Spirits Market
Non-Alcoholic Beverages
Fermented Non Dairy Non Alcoholic Beverages Market
Non-Alcoholic Beverages
Carbonated Ready-To-Drink Tea Market
Non-Alcoholic Beverages
Bubble Tea Market
Non-Alcoholic Beverages
Probiotic Soda Market
Non-Alcoholic Beverages
Hydrogen Water Machine Market
Non-Alcoholic Beverages
Naturally Cultured Beverages Market
Non-Alcoholic Beverages
North America Bottled Water Market
Non-Alcoholic Beverages
Europe Energy Drink Market
Non-Alcoholic Beverages
Gulf Cooperation Council (GCC) Bottled Water Market
Non-Alcoholic Beverages
Japan Soy Beverages Market
Non-Alcoholic Beverages
Water Vending Machine Market
Non-Alcoholic Beverages
Europe Sports and Energy Drinks Market
Non-Alcoholic Beverages
Sugar Free Carbonated Drinks Market
Non-Alcoholic Beverages
Low- and No-Calorie Soda Market
Non-Alcoholic Beverages
China Non-Alcoholic Beverages Market