
 Ammonium Chloride Food Grade Market | 2026-2036
Ammonium Chloride Food Grade Market Size, Share, and Industry Trends Forecast 2026-2036
Ammonium Chloride Food Grade Market Outlook
Sodium chloride alternatives in yeast-raised dough systems is realigning ammonium chloride economics for food processors seeking cleaner-label leavening aids. BASF leverages its technical-grade purification infrastructure to sustain food-certification throughput across European bakery supply chains. Tata Chemicals anchors South Asian distribution through integrated salt-to-specialty chemical operations. Hebei Chengxin Salt Chemical Group dominates captive ammonia sourcing, controlling cost volatility that competitors navigate through spot-market exposure.
Ammonium chloride food grade is a purified inorganic salt with minimum assay typically exceeding 99.5 percent and strict limits on heavy metals, arsenic, and lead, produced via direct neutralization of ammonia with hydrochloric acid followed by crystallization and drying; it functions primarily as a yeast nutrient, dough conditioner, and acidity regulator in commercial food production. Powder and granule formats lead volume due to dosing precision in automated bakery lines, while crystal grades command premium positioning among artisan confectionery manufacturers. The nutrient supplement application grows fastest as fortified flour mandates expand, though flavoring agent usage remains mature with thin margin pools.
The FDA's Food Additive Regulations and EFSA's purity specifications under EU food law shape product standards, with China's SAMR GB standards increasingly governing export-access terms for Asian suppliers. REACH registration requirements in Europe and evolving FSSAI additive codes in India are tightening analytical certification burdens, filtering smaller producers from cross-border trade. Stakeholders must monitor regulatory divergence between CODEX-aligned and national-standard markets when allocating capital toward purification upgrades or geographic expansion.
Market Dynamics
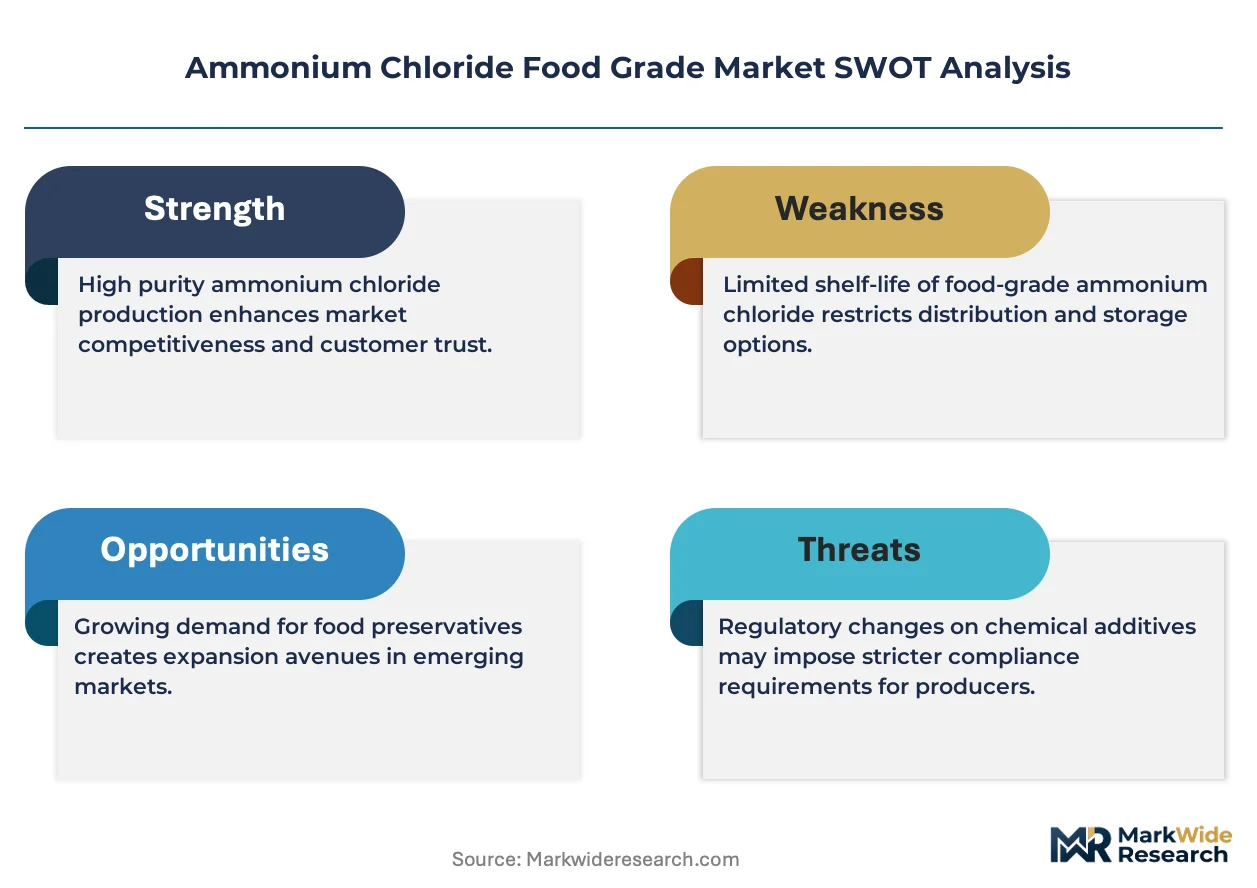
The Ammonium Chloride Food Grade Market is undergoing structural recalibration as EU REACH and F-Gas Regulation compliance costs filter down to purity specifications, compressing margins for non-integrated processors while rewarding captive ammonia producers.
Growth Catalysts
- Fortified flour mandates:Government nutrition programs across South Asia and Sub-Saharan Africa are embedding ammonium chloride into mandatory enrichment protocols, expanding addressable volume in milling operations.
- REACH registration:The EU's chemical safety framework is filtering sub-scale suppliers from cross-border trade, concentrating demand among certified producers with analytical documentation capabilities.
- Yeast-raised dough automation:Commercial bakeries deploying continuous-mix systems require precision-dosed leavening aids, favoring granule-format ammonium chloride over traditional sodium chloride blends.
Market Restraints
- Captive ammonia concentration:Chinese state-owned salt-chemical complexes control upstream synthesis, exposing spot-market-dependent processors to feedstock volatility.
- Heavy metal testing thresholds:EFSA and FDA specifications for arsenic and lead are tightening faster than purification technology diffusion, stranding legacy crystallization assets.
- Potassium bicarbonate substitution:Clean-label bakery formulators are reformulating around sodium-free alternatives, constraining ammonium chloride's expansion in premium positioning tiers.
Strategic Opportunities
- India FSSAI additive codes:Evolving domestic standards for acidity regulators create first-mover advantage for suppliers establishing analytical certification partnerships with Indian flour millers.
- Nutrient supplement convergence:Ammonium chloride is unifying with vitamin premix systems in automated fortification lines, opening formulation service revenue streams beyond commodity sales.
- SAMR GB export alignment:Chinese suppliers adapting to national food safety standards gain preferential access to Belt and Road markets with harmonized purity benchmarks.
Industry Challenges
- Analytical chemist scarcity:Heavy metals testing and batch certification require specialized laboratory talent that regional processors struggle to recruit outside Shanghai and Rotterdam clusters.
- Crystallization retrofit capex:Food-grade purity upgrades demand stainless-stallation of corrosion-resistant evaporator systems, stretching balance sheets for mid-cap salt processors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ammonium Chloride Food Grade Market |
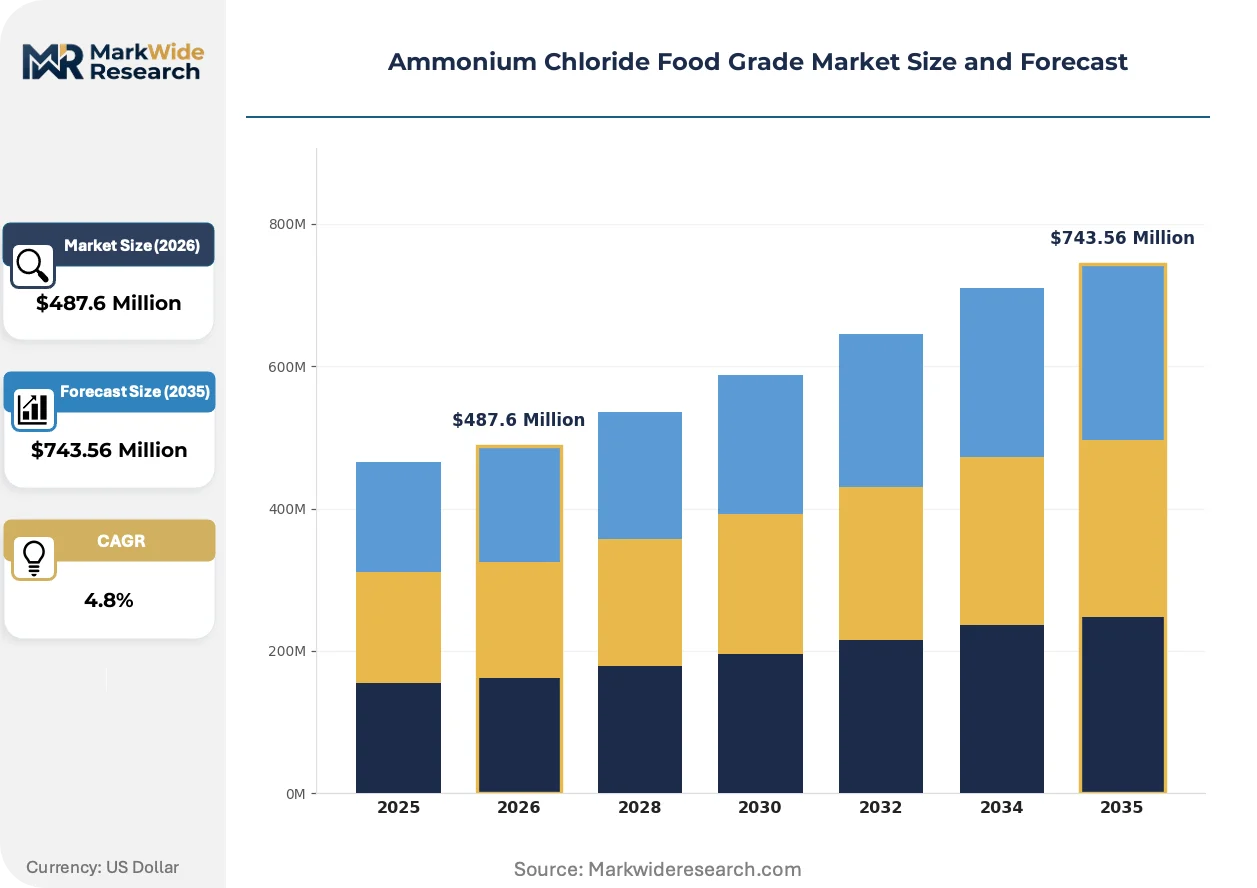
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $743.56 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Granules, Crystals, Solution Application: Food Additive, Nutrient Supplement, Flavoring Agent, Preservative End User: Bakeries, Confectioneries, Dairy Products, Beverage Industry Packaging Type: Bags, Bulk Containers, Drums, Pails |
| Companies Covered | BASF, Tata Chemicals, Tosoh Corporation, Hebei Chengxin Salt Chemical Group, North American Salt Company, Compass Minerals, Tianjin Hesheng Chemical Co., Ltd., Jiangsu Juanjia Chemical Co., Ltd., Hefei TNJ Chemical Industry Co., Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ammonium Chloride Food Grade Market Strategic Shifts
Process intensification and regulatory digitization are compressing batch-to-batch variability while traceability requirements reshape supplier qualification protocols across bakery and nutrient supplement channels.
Membrane filtration is unifying crystallization and heavy metals removal into single-unit operations, eliminating multi-stage washing sequences. European specialty chemical producers are retrofitting existing technical-grade lines with nanofiltration skids to serve food-certification throughput without greenfield investment. This convergence is compressing capital requirements for purity upgrades and enabling faster regulatory approval cycles.
The EU's F-Gas Regulation is mandating refrigerant phase-downs that indirectly elevate ammonia market pricing, cascading into ammonium chloride feedstock costs. Industrial gas producers are reallocating ammonia capacity toward cooling applications, tightening merchant availability for chemical neutralization. Food-grade processors in Germany and the Netherlands are responding with backward integration into on-site ammonia synthesis.
Direct miller-procurement contracts are displacing layered distribution networks in bulk leavening aid purchasing. Large bakery conglomerates in Brazil and Turkey are establishing specification-lock agreements with certified producers, bypassing regional chemical traders. This concentration is most visible in automated industrial baking clusters where dosing-system integration requires technical partnership depth.
Ammonium Chloride Food Grade Market Segmentation
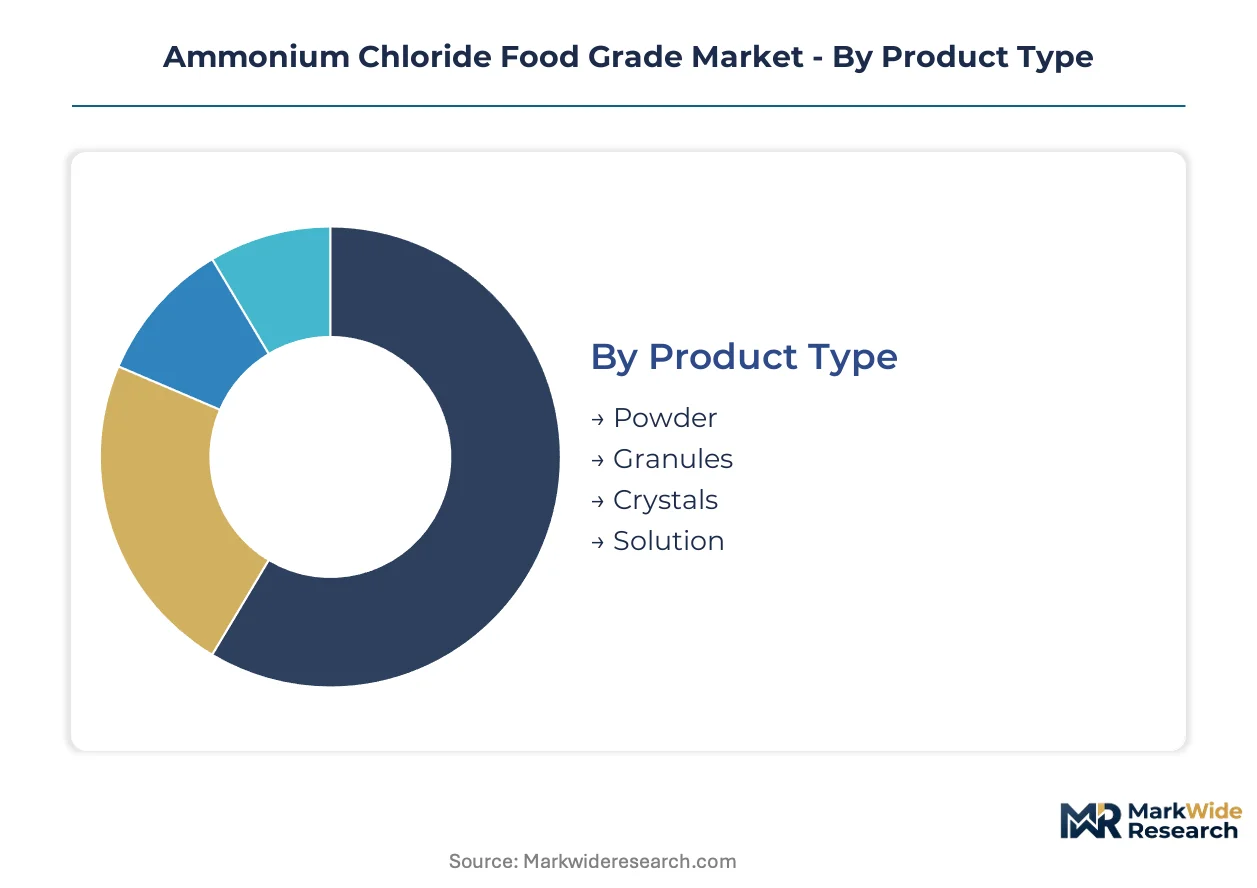
Segmentation in the Ammonium Chloride Food Grade Market reveals how form factor, application intensity, and customer scale reshape procurement economics. Purification grade and dosing precision requirements split demand across automated industrial bakeries and artisan confectionery workshops.
Product Type:
Volume leadership clusters in formats optimized for continuous-process integration, while premium positioning attaches to grades demanding visual clarity or dissolution control.
- Powder:Finely milled particles below 150 microns enable homogeneous distribution in dry flour premixes. Demand concentrates in industrial milling operations across China and India where automated dosing systems require flowable, non-caking material. Powder formats absorb the majority of nutrient supplement volume as fortified flour mandates expand.
- Granules:Spherical agglomerates between 0.5-2.0 millimeters deliver calibrated dissolution rates in continuous-mix dough systems. European commercial bakeries in Germany and the Netherlands specify granule grades for precision leavening control, with REACH-registered suppliers capturing specification-locked contracts.
- Crystals:Large, visually distinct crystalline structures command artisan confectionery preference for surface decoration and controlled acidity release.
- Solution:Pre-dissolved aqueous formats serve beverage acidification and liquid nutrient fortification where dry blending is impractical.
Mature deployment sits with Powder in commodity flour fortification. Newer deployment is concentrated in Granules as continuous-process bakeries retrofit dosing infrastructure.
Application:
Margin architecture separates established functional categories from emerging regulatory-driven segments where certification burdens filter supplier participation.
- Food Additive:Acidity regulation and dough conditioning in yeast-raised systems represents the foundational use case. Bakeries in Brazil and Turkey specify food-grade ammonium chloride for pH control in commercial bread production, with direct miller-procurement contracts displacing trader intermediaries.
- Nutrient Supplement:Government-mandated flour enrichment programs across South Asia and Sub-Saharan Africa embed ammonium chloride as a nitrogen source in vitamin-mineral premixes. SAMR GB standards alignment enables Chinese suppliers to access Belt and Road procurement frameworks.
- Flavoring Agent:Salty-umami enhancement in Scandinavian licorice and select confectionery applications maintains steady but thin-margin volume.
- Preservative:Limited adoption in shelf-stable bakery products where water activity reduction complements pH management.
Established volume anchors to Food Additive functionality. Steepest expansion trajectory belongs to Nutrient Supplement as mandatory fortification spreads to additional national programs.
End User:
Customer scale and process automation intensity determine specification stringency, splitting the market between commodity chemical traders and technical partnership suppliers.
- Bakeries:Industrial-scale bread and pastry manufacturers deploy ammonium chloride in automated continuous-mix lines requiring granule-format precision dosing. Large conglomerates in Brazil establish multi-year supply agreements with certified producers, bypassing regional distribution layers.
- Confectioneries:Artisan and industrial candy producers utilize crystal grades for controlled acidity release in pectin gels and licorice formulations. European specialty confectioners pay premiums for heavy-metals-certified material meeting EFSA specifications.
- Dairy Products:Limited application in processed cheese and dairy-based beverages where pH adjustment supports protein stability.
- Beverage Industry:Solution-format ammonium chloride serves acidification in sports drinks and functional beverages where dry salt incorporation is incompatible with liquid processing.
Procurement consolidation is most advanced in Bakeries. Technical partnership requirements are expanding fastest in Confectioneries as heavy-metals testing thresholds tighten.
Packaging Type:
Logistics economics and contamination risk segment the market between bulk flow for integrated processors and protective containment for smaller-scale users.
- Bags:Multi-layer laminated sacks with moisture barriers dominate mid-volume bakery and confectionery procurement. Indian flour millers favor 25-kilogram bags for manual handling compatibility in facilities lacking pneumatic conveying.
- Bulk Containers:Flexible intermediate bulk containers and silo deliveries serve large-scale industrial bakeries in Germany and the Netherlands with integrated dosing systems. Bulk formats eliminate packaging waste and reduce per-kilogram logistics costs for high-throughput users.
- Drums:Steel and fiber drums with sealed closures protect solution-format material from contamination during transport and storage.
- Pails:Smaller rigid containers serve laboratory-scale users and artisan producers requiring frequent batch access with minimal atmospheric exposure.
Cost-optimized procurement clusters in Bulk Containers for integrated processors. Specification-sensitive buyers in artisan tiers retain Pails and Drums for contamination control.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bonded logistics zones in coastal China concentrate upstream salt-chemical synthesis, while REACH-registered European clusters and FSSAI-aligned South Asian milling corridors reshape downstream procurement geography.
China
Hebei province anchors captive ammonia production for food-grade neutralization, with Tianjin and Jiangsu chemical parks housing crystallization and drying infrastructure. SAMR GB standards alignment enables Belt and Road export access for fortified flour programs. Shandong and Hebei processors dominate powder-format supply for automated dosing systems.
Germany
Commercial bakeries in North Rhine-Westphalia and Bavaria specify granule-format ammonium chloride for continuous-mix lines, locking multi-year contracts with REACH-registered suppliers. EFSA purity specifications and ECHA registration requirements filter sub-scale traders from cross-border participation. BASF leverages Ludwigshafen technical-grade infrastructure to sustain food-certification throughput.
India
Government-mandated wheat flour enrichment programs in Maharashtra and Gujarat embed ammonium chloride into vitamin-mineral premixes, expanding addressable volume in milling operations. FSSAI additive code evolution creates certification partnership opportunities with domestic flour millers. Tata Chemicals anchors distribution through integrated salt-to-specialty operations in Mithapur.
Brazil
Large bakery conglomerates in São Paulo and Minas Gerais establish direct-procurement agreements with certified producers, bypassing regional chemical traders. ANVISA food additive regulations shape import documentation requirements for acidity regulators. Industrial baking clusters in the Southeast retrofit dosing infrastructure to accommodate precision-leavening specifications.
United States
FDA Food Additive Regulations govern ammonium chloride deployment in yeast-raised dough systems across industrial bakeries in Illinois and California. Compass Minerals and North American Salt Company serve mid-continent milling corridors through integrated evaporated salt operations. Heavy metals testing protocols under EPA-aligned state standards elevate analytical certification burdens for import suppliers.
Ammonium Chloride Food Grade Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated salt-chemical complexes commanding upstream synthesis and regional distributors retaining artisan-tier access. The vendor base concentrates around three strategic archetypes: captive-ammonia state-owned enterprises, diversified chemical conglomerates with food-certification infrastructure, and mid-cap salt processors retrofitting technical-grade lines. M&A activity targets REACH-registered analytical capabilities, while capacity expansion focuses on membrane filtration retrofits that compress batch-to-batch variability without greenfield crystallization investment.
Among diversified chemical conglomerates, BASF and Tata Chemicals exemplify archetypes leveraging technical-grade purification infrastructure to sustain food-certification throughput across European and South Asian supply chains respectively. Hebei Chengxin Salt Chemical Group occupies a position within the captive-ammonia tier, representing upstream integration models that control feedstock volatility through state-owned salt-chemical complex governance. These three entities anchor distinct competitive vectors: European regulatory compliance, South Asian distribution integration, and Chinese upstream synthesis control.
| Leading Market Players |
|---|
| BASF |
| Tata Chemicals |
| Tosoh Corporation |
| Hebei Chengxin Salt Chemical Group |
| North American Salt Company |
| Compass Minerals |
| Tianjin Hesheng Chemical Co., Ltd. |
| Jiangsu Juanjia Chemical Co., Ltd. |
| Hefei TNJ Chemical Industry Co., Ltd. |
| Others |
Value Chain & Pricing Dynamics
Membrane filtration retrofits are compressing capital requirements for food-grade purity upgrades while simultaneously concentrating supply among processors with technical-grade infrastructure already in place. This production-method transition rewards BASF and Tata Chemicals with existing purification assets while stranding mid-cap salt processors facing stainless-stallation capex burdens for corrosion-resistant evaporator systems.
Pricing Analysis
Volume leadership in powder-format nutrient supplements trades at thin margins serving fortified flour mandates, while crystal grades for artisan confectionery command premiums based on EFSA heavy-metals certification and visual clarity specifications. Three-tier pricing structure separates REACH-registered European suppliers from SAMR GB-aligned Chinese exporters and uncertified spot-market traders. Cost compression in standard grades intensifies as Chinese state-owned complexes leverage captive ammonia sourcing. Industrial bakeries in Germany and the Netherlands exhibit lowest price sensitivity due to specification-locked multi-year contracts, whereas Indian flour millers dependent on manual-handling 25-kilogram bags remain most exposed to logistics-driven volatility.
Supply Chain Analysis
India's FSSAI evolving additive codes and Brazil's ANVISA import documentation requirements are redirecting procurement toward domestic-content-compliant suppliers with established analytical certification partnerships. Upstream synthesis concentrates in China through Hebei Chengxin Salt Chemical Group and Shandong processors, while downstream formulation draws from German commercial bakeries and Indian milling corridors in Maharashtra and Gujarat. Raw material dependencies center on merchant ammonia availability, hydrochloric acid supply contracts, and stainless-steel evaporator components. Single-source vulnerability runs through Chinese state-owned ammonia complexes where industrial gas producers reallocate capacity toward F-Gas Regulation-driven cooling applications. Distribution runs through direct miller-procurement contracts displacing regional chemical traders in Brazil and Turkey.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Membrane filtration is replacing legacy multi-stage crystallization sequences, compressing batch-to-batch variability and enabling faster regulatory approval cycles without greenfield investment. This technology transition favors processors with existing technical-grade infrastructure over mid-cap salt specialists facing retrofit capex constraints.
For Market Incumbents: Extend REACH-registered analytical capabilities into Indian FSSAI certification partnerships before domestic standards fully crystallize, locking specification-locked contracts with Maharashtra and Gujarat flour millers. Deepen backward integration into on-site ammonia synthesis to offset merchant feedstock volatility from F-Gas Regulation-driven refrigerant phase-downs. Prioritize membrane filtration retrofits over greenfield crystallization assets to defend margin position against Chinese state-owned competitors with captive synthesis.
For New Entrants and Emerging Players: Enter via nutrient supplement convergence opportunities in automated fortification lines serving South Asian and Sub-Saharan African government enrichment programs, where formulation service revenue streams exceed commodity margin pools. Target artisan confectionery segments in Scandinavia and European specialty producers paying premiums for heavy-metals-certified crystal grades. Establish analytical chemist partnerships with Shanghai or Rotterdam laboratory clusters to bypass talent scarcity constraining regional processors.
For Investors and Strategic Acquirers: Re-rating potential sits with diversified chemical conglomerates possessing food-certification infrastructure given membrane filtration convergence enabling technical-grade line retrofits. Long-term viability over the next decade hinges on regulatory digitization capabilities and traceability protocol integration across bakery and nutrient supplement channels. Target acquisition archetype: mid-cap salt processors with stainless-stallation assets and SAMR GB export alignment for Belt and Road market access. Watch for inflection in Indian FSSAI additive code finalization triggering procurement consolidation toward certified suppliers.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ammonia Synthesis | German and Dutch processors control feedstock costs against F-Gas Regulation-driven merchant tightness. |
| Membrane Filtration Retrofit | European specialty chemical producers compress capital requirements for REACH food-certification throughput. |
| FSSAI Certification Partnership | First-mover suppliers lock specification-locked contracts with Maharashtra and Gujarat flour millers. |
| Direct Miller-Procurement Contracts | Brazilian bakery conglomerates bypass regional traders for precision-dosing technical partnership depth. |
| SAMR GB Export Alignment | Chinese suppliers gain preferential Belt and Road access for fortified flour procurement frameworks. |
Study Parameters
Independent corroboration across primary interviews with bakery procurement directors, chemical plant managers, and regulatory affairs specialists, combined with secondary validation through EFSA additive specifications, SAMR GB standards documentation, and customs trade flow data, underwrites the qualitative findings. Bottom-up triangulation across powder, granule, crystal, and solution format demand and top-down reconciliation against end-use consumption in bakeries, confectioneries, and nutrient supplement applications anchor the quantitative envelope.
Comparable-period anchoring to historical fortified flour mandate rollouts and REACH registration phase-in patterns shaped the projection horizon. The analytical framework models segmentation across product type, application intensity, customer automation scale, and regional regulatory cluster throughout the forecast period. CAGRs derive from volume trajectory analysis against purity upgrade investment cycles and substitution elasticity estimates for potassium bicarbonate in clean-label formulations.
Forecast precision tightens around the base case; tail outcomes carry wider variance under F-Gas Regulation acceleration or Indian FSSAI code evolution timing. The analytical envelope reflects assumptions regarding membrane filtration diffusion rates, merchant ammonia availability, and heavy-metals testing threshold tightening trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Additives and Ingredients
Germany Food Colorants Market
Food Additives and Ingredients
Italy Food Additives Market
Food Additives and Ingredients
South America Brewing Enzymes Market
Food Additives and Ingredients
Argentina Gellan Gum Market
Food Additives and Ingredients
Argentina Food Colorants Market
Food Additives and Ingredients
Microencapsulation Market
Food Additives and Ingredients
Europe Leavening Agents Market
Food Additives and Ingredients
Japan Food Acidulants Market
Food Additives and Ingredients
Coconut Fatty Acids Market
Food Additives and Ingredients
North America Fermented Ingredient Market
Food Additives and Ingredients
United Kingdom Food Acidulants Market
Food Additives and Ingredients
Mexico Food Acidulants Market
Food Additives and Ingredients
Australia Food Additives Market
Food Additives and Ingredients
South America Food Additives Market
Food Additives and Ingredients
Australia Food Enzymes Market
Food Additives and Ingredients
Activated Cake Emulsifier Market