
 Modified Maize Starch Market | 2026-2036
Modified Maize Starch Market Size, Share, and Industry Trends Forecast 2026-2036
Modified Maize Starch Market Analytics
Technical service layers around formulation support and application-specific customization is expanding what processors sell beyond commodity starch. Ingredion Incorporated leverages its global application labs to anchor premium positioning in specialty food systems. Cargill Incorporated sustains backward integration into North American corn belts, securing supply continuity for industrial buyers. Tate & Lyle PLC differentiates through clean-label ingredient portfolios that command tighter customer relationships.
Modified maize starch refers to corn starch that has undergone physical, enzymatic, or chemical alteration to achieve specific functional properties such as improved freeze-thaw stability, enhanced shear resistance, or controlled viscosity under thermal processing. Manufacturers produce these variants through cross-linking, oxidation, or pregelatinization to serve as thickeners, stabilizers, and binders across food, pharmaceutical, and industrial applications. Cross-linked starch dominates volume due to its superior acid and heat stability in retorted sauces and dressings. Pregelatinized starch captures growth momentum in instant food systems where cold-water dispersibility eliminates cooking steps. Acetylated starch holds concentrated margin pools in frozen dessert applications where manufacturers pay premiums for extended shelf-life performance.
FDA food additive regulations under CFR 172 govern chemical modification limits and labeling requirements for starches sold into U.S. food channels. REACH compliance in Europe mandates disclosure of acetylation and oxidation chemistries, raising reformulation costs for exporters. India's FSSAI standards for modified starches in processed foods are tightening purity specifications, redirecting import sourcing toward certified suppliers. Stakeholders must monitor how diverging regional purity standards reshape qualification timelines and regional manufacturing footprints.
Market Dynamics
Clean-label mandates from the EU Green Deal are compressing formulation windows for modified maize starch, forcing processors to eliminate synthetic additives while preserving functional performance in retorted and frozen food systems.
Growth Catalysts
- EU Green Deal sustainability standards:The tightening carbon-intensity requirements for agricultural processing inputs are redirecting procurement toward certified low-carbon starch variants in European food manufacturing.
- India PLI scheme for domestic value chains:Production-linked incentives for maize processing infrastructure are accelerating capacity buildout and import substitution in the country's modified starch sector.
- Pregelatinized starch cold-water dispersibility:This enzymatic modification technology is eliminating cooking steps in instant food systems, capturing demand from ready-meal manufacturers seeking process simplification.
Market Restraints
- North American corn supply concentration:Drought vulnerability across the US Corn Belt creates input cost volatility and supply continuity risks for cross-linked starch production.
- REACH disclosure mandates for acetylation chemistries:ECHA compliance requirements raise reformulation costs for exporters serving European pharmaceutical and food channels.
- Native starch functional improvements:Advances in unmodified starch processing are narrowing the performance gap in low-stress applications, threatening displacement in economy-tier thickeners.
Strategic Opportunities
- India's underpenetrated frozen dessert sector:Acetylated starch applications for extended shelf-life performance remain nascent in the country's emerging ice cream and confectionery markets.
- Technical service layer monetization:Application-specific formulation support and customization capabilities enable processors to capture value beyond commodity starch pricing.
- FSSAI purity specification tightening:India's strengthening standards for modified starches in processed foods are redirecting import sourcing toward certified suppliers, creating qualification advantages for compliant domestic producers.
Industry Challenges
- Food technologist specialization gap:Shortage of professionals trained in enzymatic modification protocols and freeze-thaw stability testing is extending product development timelines for customized starch solutions.
- Dual certification burden:Simultaneous FDA CFR 172 compliance and REACH registration requirements are compressing margin structures for exporters serving transatlantic markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Modified Maize Starch Market |
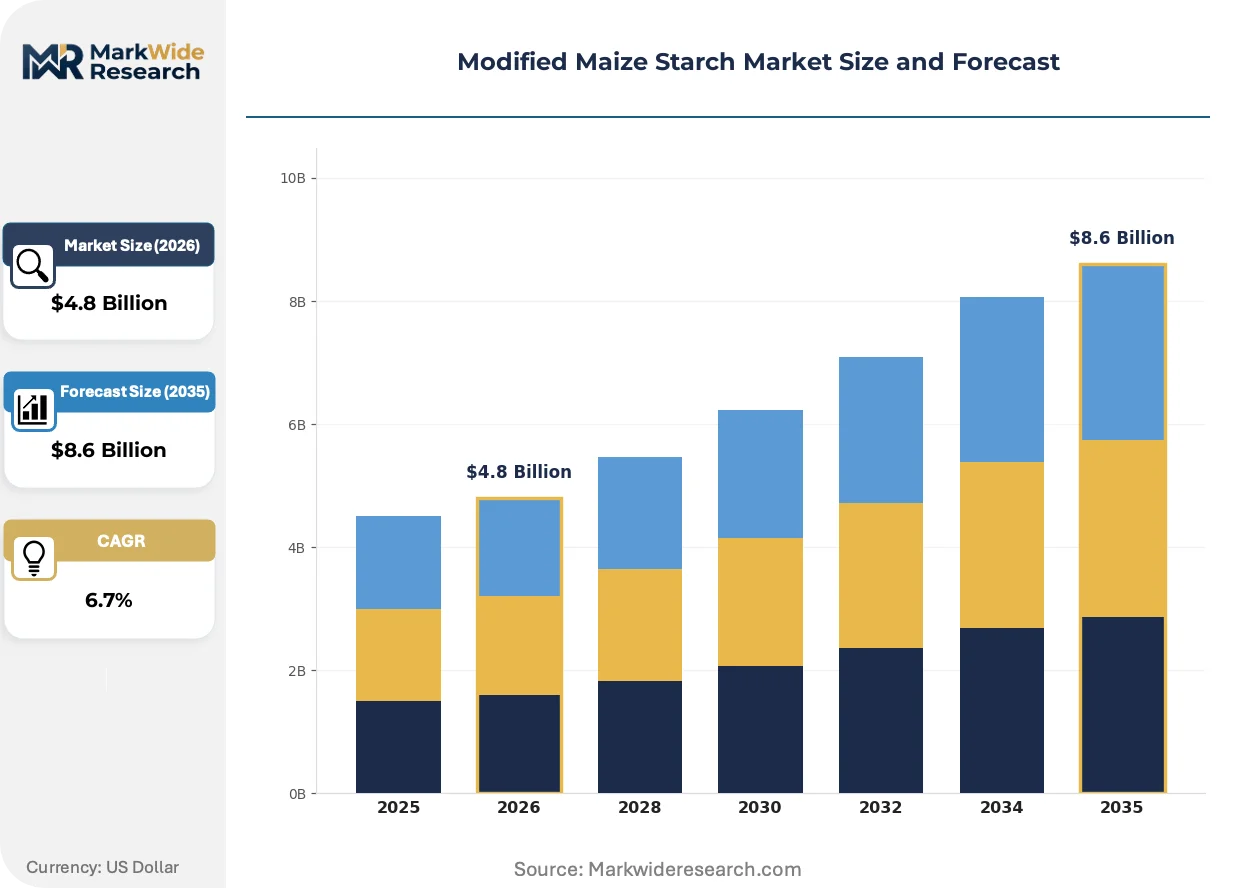
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cross-linked Starch, Pregelatinized Starch, Oxidized Starch, Acetylated Starch End Use Industry: Food & Beverage, Pharmaceuticals, Paper & Packaging, Personal Care Form: Powder, Granules, Pellets, Aqueous Application: Thickening Agent, Stabilizer, Emulsifier, Binders |
| Companies Covered | Ingredion Incorporated, Cargill Incorporated, Archer Daniels Midland Company, Tate & Lyle PLC, Roquette Frères, Agrana Beteiligungs-AG, Grain Processing Corporation, Avebe U.A., Emsland-Stärke GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Modified Maize Starch Market Evolving Landscape
Enzymatic modification platforms are displacing traditional chemical processes across premium starch tiers, while regulatory divergence between FDA and ECHA frameworks is fragmenting qualification pathways for global suppliers.
Clean-label enzymatic modification is expanding into high-value food systems where processors seek to eliminate E-number additives without sacrificing acid stability or shear resistance. Premium sauce and dressing manufacturers in Western Europe are adopting these variants at accelerated pace, compressing the addressable market for chemically cross-linked alternatives in clean-label product lines.
REACH disclosure requirements for oxidation and acetylation chemistries are mandating supply chain transparency that many Asian exporters cannot yet provide. European food and pharmaceutical manufacturers are responding by shortening approved supplier lists and demanding third-party certification of modification processes, raising barriers for uncertified market entrants.
Direct technical collaboration between starch processors and food manufacturers is displacing traditional distributor-led procurement in formulated product development. Large ready-meal and sauce producers in Germany and France are embedding supplier technologists within their innovation teams, compressing development cycles and locking in volume commitments through co-development contracts rather than spot purchasing.
Modified Maize Starch Market Segmentation
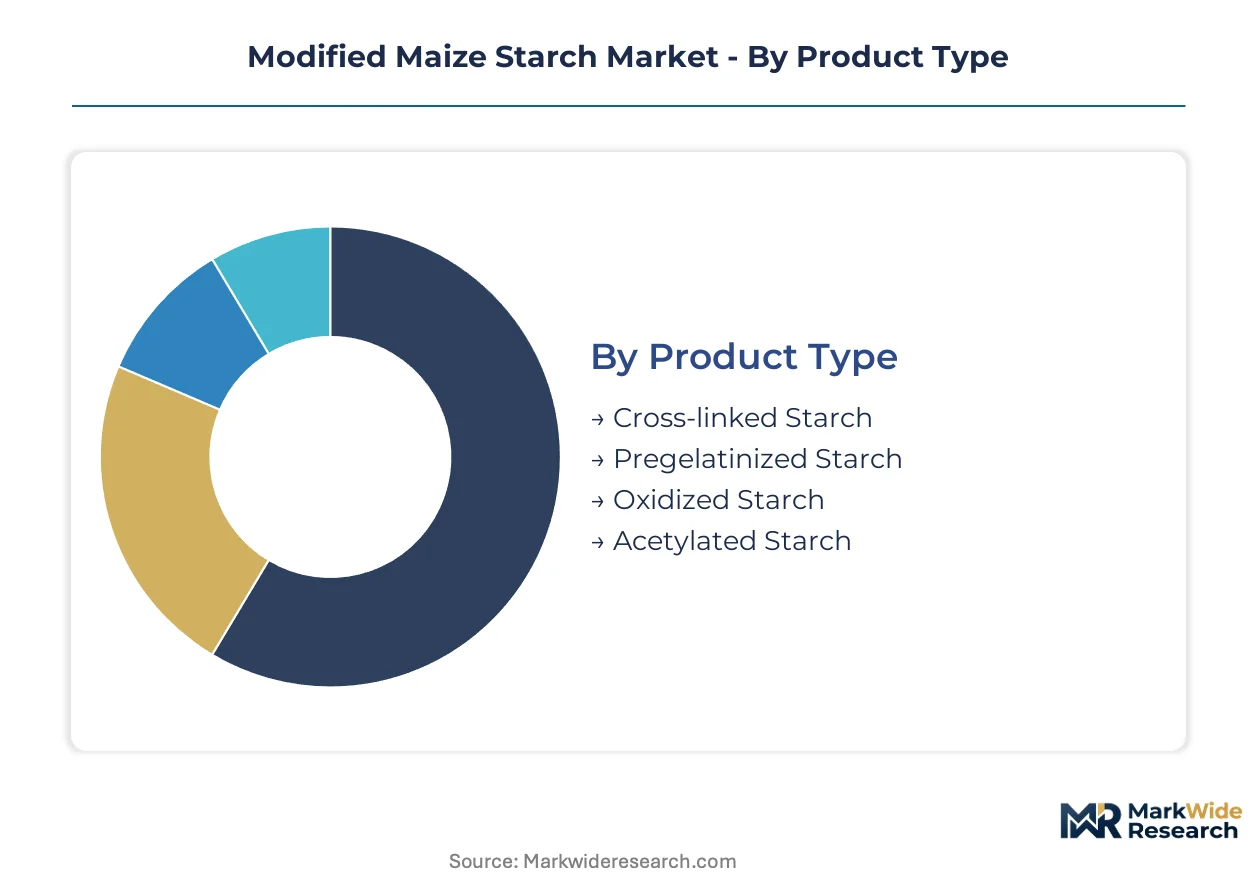
Modified maize starch processors compete across four distinct segmentation axes where technical specifications, regulatory compliance burdens, and application performance requirements reshape procurement priorities. Buyers select grades based on modification chemistry, end-use validation protocols, physical handling properties, and functional role in formulated systems.
Product Type:
Cost tier determines procurement volume and margin capture across modification chemistries.
- Cross-linked Starch:Phosphorylation or adipic acid cross-linking creates acid-stable, heat-resistant starch networks. Demand concentrates in retorted sauces and dressings where US and European manufacturers prioritize process tolerance over clean-label positioning.
- Pregelatinized Starch:Enzymatic or thermal pregelatinization eliminates gelatinization temperature requirements, enabling cold-water dispersibility. Ready-meal manufacturers in Germany and France are adopting these variants fastest as they eliminate cooking steps in instant food systems.
- Oxidized Starch:Hypochlorite oxidation reduces viscosity and improves film-forming properties for paper coating applications.
- Acetylated Starch:Esterification with acetic anhydride extends freeze-thaw stability for frozen desserts; REACH disclosure mandates compress margins for European pharmaceutical channels.
Volume sits with cross-linked variants; growth tilts toward pregelatinized grades.
End Use Industry:
Application maturity and certification stringency segment buyers by validation burden.
- Food & Beverage:Clean-label mandates from the EU Green Deal are compressing formulation windows, forcing processors to eliminate synthetic additives while preserving functional performance in retorted and frozen systems.
- Pharmaceuticals:Excipient-grade starches require USP-NF or Ph.Eur. compliance for tablet binders and disintegrants; dual FDA-EMA qualification timelines extend supplier onboarding to 18-24 months.
- Paper & Packaging:Surface sizing and coating applications prioritize oxidized starch for film-forming and adhesive properties.
- Personal Care:Cosmetic-grade specifications for powder absorbency and skin-feel drive acetylated starch demand in emulsion systems.
Food and beverage commands absolute volume; pharmaceuticals deliver steepest expansion trajectory.
Form:
Physical state dictates handling infrastructure and dissolution kinetics in customer plants.
- Powder:Standard milled starch with bulk density of 0.4-0.6 g/cm³ dominates high-volume food manufacturing where pneumatic conveying systems are installed.
- Granules:Agglomerated particles improve flowability and reduce dusting; pharmaceutical tableting operations in India specify this form for direct compression compatibility.
- Pellets:Extruded spherical particles enable controlled release in specialty pharmaceutical and agricultural applications.
- Aqueous:Pre-dispersed slurries eliminate hydration steps for paper mill wet-end addition and textile sizing operations.
Powder maintains installed base dominance; aqueous dispersions gain share fastest in continuous-process paper mills.
Application:
Functional role in formulated systems determines technical service intensity and pricing power.
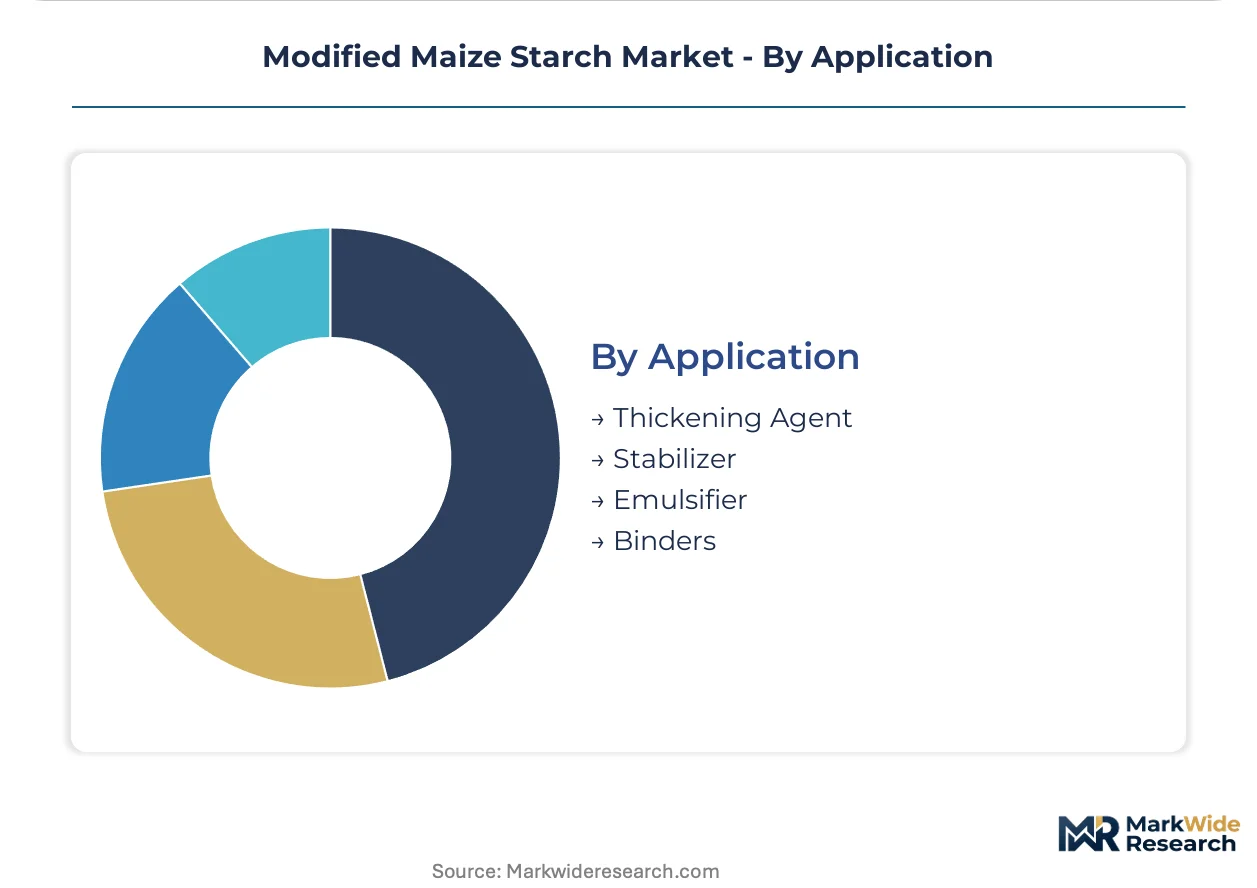
- Thickening Agent:Viscosity development under shear and temperature defines performance in sauces, soups, and gravies; cross-linked variants resist breakdown in acidic tomato-based systems.
- Stabilizer:Freeze-thaw stability and emulsion integrity preservation concentrate demand in frozen desserts and dairy alternatives where acetylated starch commands premium positioning.
- Emulsifier:Surface-active modified starches stabilize oil-in-water emulsions in salad dressings and beverages.
- Binders:Adhesive and cohesive properties drive use in pharmaceutical tablets, construction materials, and corrugated board manufacturing.
Thickening captures foundational volume; stabilizer applications expand most quickly as clean-label frozen dessert formulations proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chicago anchors North American modified maize starch activity through its proximity to the US Corn Belt and concentration of food processing headquarters. The global market distributes across four major producing regions with distinct regulatory and demand profiles.
United States
Midwest corn processing clusters in Iowa and Illinois supply cross-linked starch to retorted sauce manufacturers. FDA CFR 172 governs chemical modification limits for food-grade exports. Decatur, Illinois hosts integrated processing facilities where backward integration into corn supply secures volume commitments for industrial buyers.
Germany
Ready-meal manufacturers in Hamburg and Cologne drive pregelatinized starch adoption for cold-water dispersibility. REACH disclosure mandates for acetylation chemistries compress margins for pharmaceutical channel suppliers. The Ruhr industrial corridor concentrates paper coating applications using oxidized starch variants.
India
Frozen dessert formulators in Maharashtra and Gujarat represent underpenetrated demand for acetylated starch shelf-life extension. FSSAI purity specification tightening redirects import sourcing toward certified domestic producers. The PLI scheme accelerates maize processing capacity buildout in Madhya Pradesh corn belts.
China
Instant noodle and soup manufacturers in Shandong Province absorb pregelatinized starch volumes for process simplification. GB standards for food additive starch modifications diverge from Western frameworks, fragmenting qualification pathways. Yangtze River Delta food tech clusters embed supplier technologists within innovation teams.
Brazil
São Paulo-based meat processors utilize cross-linked starch for marinade stability in export-oriented operations. ANVISA pharmaceutical excipient standards extend supplier onboarding timelines for tablet binder applications. Campinas hosts technical service centers supporting South American formulation customization demand.
Modified Maize Starch Market Competitive Landscape
Capital-heavy producers compete with asset-light technical service specialists across tiered market positions. The structure concentrates among integrated agribusiness conglomerates and regional starch processors with captive corn supply. Three archetypes dominate: North American integrated giants with Corn Belt origination, European clean-label specialists with enzymatic modification platforms, and Asian domestic champions leveraging policy support. Competitive moves center on technical service layer monetization and dual-certification capacity expansion for transatlantic qualification.
Among North American integrated processors, Ingredion Incorporated and Cargill Incorporated occupy positions defined by global application lab networks and backward integration into corn supply chains. Tate & Lyle PLC exemplifies the European clean-label specialist archetype with positioning around regulatory-compliant ingredient portfolios. These three entities anchor the premium tier where formulation support capabilities command value beyond commodity starch pricing.
| Leading Market Players |
|---|
| Ingredion Incorporated |
| Cargill Incorporated |
| Archer Daniels Midland Company |
| Tate & Lyle PLC |
| Roquette Frères |
| Agrana Beteiligungs-AG |
| Grain Processing Corporation |
| Avebe U.A. |
| Emsland-Stärke GmbH |
| Others |
Value Network & Pricing Analysis
Corn procurement costs in Iowa and Illinois processing clusters cascade through three distinct pricing tiers downstream, with cross-linked starch commanding premium positioning in retorted sauce applications while pregelatinized variants capture value through cold-water dispersibility in ready-meal systems. REACH disclosure mandates for acetylation chemistries in European pharmaceutical channels compress margins for exporters, redirecting price differentiation toward certification-grade validation rather than commodity volume scale.
Pricing Analysis
Yield-based pricing anchors value capture in frozen dessert applications where acetylated starch extends shelf-life performance, separating premium grades from standard cross-linked variants through freeze-thaw stability certification. Price differentiation hinges on dual FDA-EMA qualification status and technical service bundling for formulation support. Cost compression in economy-tier thickeners is intensifying because native starch functional improvements narrow the performance gap in low-stress applications. Ready-meal manufacturers in Germany exhibit lowest price sensitivity due to co-development contract structures, while Indian frozen dessert formulators remain most price-sensitive given nascent market development.
Supply Chain Analysis
Maize supply rests on US Corn Belt origination, Indian Madhya Pradesh cultivation, and Brazilian São Paulo state processing clusters for South American coverage. Modified starch production draws from corn feedstock, enzymatic modification reagents, and acetic anhydride for esterification chemistries. Single-source vulnerability concentrates in US Midwest drought exposure, creating input cost volatility for cross-linked starch manufacturers. Distribution runs through integrated processor direct sales for large food manufacturers, supplemented by regional distributors serving mid-tier pharmaceutical and paper coating accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Modified maize starch operates as a cost-of-compliance market where REACH disclosure mandates for acetylation and oxidation chemistries erect barrier-to-entry moats favoring dual-certified incumbents with established European pharmaceutical supplier status.
For Market Incumbents: Deepen technical service layer monetization by embedding application technologists within German and French ready-meal innovation teams, compressing development cycles and locking volume commitments through co-development contracts rather than spot purchasing. Expand backward integration into Madhya Pradesh corn belts under India's PLI scheme to secure supply continuity for Asian pharmaceutical channel growth. Native starch functional improvements threaten displacement in economy-tier thickeners, requiring defensive certification investment to maintain premium positioning. For New Entrants and Emerging Players: Launch via technical partnership models with Maharashtra and Gujarat frozen dessert formulators, targeting acetylated starch shelf-life extension applications where penetration remains nascent and price sensitivity is offset by performance premiums. India's FSSAI purity specification tightening redirects import sourcing toward certified domestic producers, creating qualification advantages for compliant local manufacturing. Prioritize enzymatic modification platforms to capture clean-label demand from EU Green Deal mandates without bearing legacy chemical process compliance burdens. For Investors and Strategic Acquirers: FSSAI certification timeline acceleration for domestic Indian producers is the leading indicator that policy-supported capacity buildout will consolidate regional supply structures within a decade-long horizon. Acquisition target archetype: mid-scale enzymatic modification specialists with existing European clean-label customer relationships and underutilized Madhya Pradesh corn processing infrastructure. Watch for ECHA disclosure requirement expansion beyond acetylation to additional modification chemistries as the signal for further regulatory-driven supplier list contraction.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Corn Supply | Iowa and Madhya Pradesh origination secures volume commitments for industrial buyers. |
| Dual Certification Capacity Expansion | Simultaneous FDA CFR 172 and REACH registration compresses transatlantic supplier timelines. |
| Technical Service Center Establishment | Application labs in Hamburg and São Paulo anchor premium positioning through formulation support. |
| Enzymatic Modification Platform Investment | Clean-label enzymatic processes displace chemical cross-linking in EU Green Deal-compliant systems. |
| Long-term Co-development Contracts | Embedded supplier technologists lock volume commitments from German ready-meal manufacturers. |
Research Methodology
Independent corroboration across plant managers at Iowa and Illinois processing facilities, procurement leads at German sauce manufacturers, and regulatory affairs directors at European pharmaceutical excipient suppliers underwrites the qualitative findings in this study. Primary interviews with starch application technologists, FSSAI compliance officers, and paper mill wet-end engineers combined with secondary validation from customs and trade data, SEC 10-K filings of integrated agribusiness conglomerates, and ECHA registration disclosures. Bottom-up capacity assessments across Madhya Pradesh and US Corn Belt processing clusters triangulate against top-down demand modeling from food and beverage formulation trends.
Rate-of-change decomposition across the projection horizon segments volume and value by modification chemistry, end-use industry validation burden, physical form handling requirements, and functional role in formulated systems. CAGRs derive from regression analysis against corn feedstock price indices, enzymatic modification technology adoption curves, and regulatory qualification timeline compression in Indian and European markets. Forecast inputs incorporate PLI scheme capacity buildout schedules and EU Green Deal carbon-intensity benchmarking for agricultural processing inputs.
The model assumes a particular technology adoption path; alternative pathways for enzymatic modification platform displacement of chemical processes would alter the outlook for premium tier margin structures. Forecasts reflect assumptions regarding FSSAI enforcement consistency, ECHA disclosure scope stability, and Corn Belt climate patterns. A small set of named triggers—drought severity indices, REACH annex expansion announcements, and PLI scheme disbursement acceleration—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Malted Wheat Flour Market
Ingredients
Heart Health Ingredients Market
Ingredients
Edible Peanut Oil and Soybean Oil Market
Ingredients
Licorice Root Market
Ingredients
Industrial Starch Market
Ingredients
Cooking Coconut Milk Market
Ingredients
North America Fats and Oils Market
Ingredients
Edible Fiber Market
Ingredients
Europe Feed Yeast Market
Ingredients
North America Collagen Ingredients Market
Ingredients
Acetylated Starch Market
Ingredients
Edible Animal Fat Market
Ingredients
Meat Starter Culture Market
Ingredients
North America Vegetable Oils Market
Ingredients
Oat Fiber Market
Ingredients
US Plant-Based Oils Market