
 Exterior Doors Market | 2026-2036
Exterior Doors Market Size, Share, and Industry Trends Forecast 2026-2036
Exterior Doors Market Intelligence
Impact-rated and hurricane-resistant door systems are redrawing the competitive landscape for coastal and high-wind zone construction. JELD-WEN leverages its extensive distribution network to serve both large-scale builders and the fragmented remodeling channel. Masonite International differentiates through material innovation, particularly in its high-performance composite and fiberglass door lines. Meanwhile, Therma-Tru positions its brand strength to command a premium in the North American fiberglass entry door segment.
Exterior doors are engineered building components designed to provide access, security, and environmental separation for a structure's envelope. Their construction often involves multi-layer cores for thermal insulation, measured by U-factor, and weatherstripping to prevent air and water infiltration. Fiberglass and composite materials are gaining share from traditional wood and steel, driven by their durability and low maintenance. The residential homes application remains the largest segment, while commercial building projects demand specialized fire-rated and security-enhanced doors.
Product specifications are heavily influenced by building codes and energy efficiency programs like the US Environmental Protection Agency's ENERGY STAR. In Europe, CE marking and adherence to ISO 9001 quality management standards are critical for market access and demonstrating compliance. Manufacturers must now decide whether to invest in smart-home technology integration or focus purely on enhancing material performance and security features.
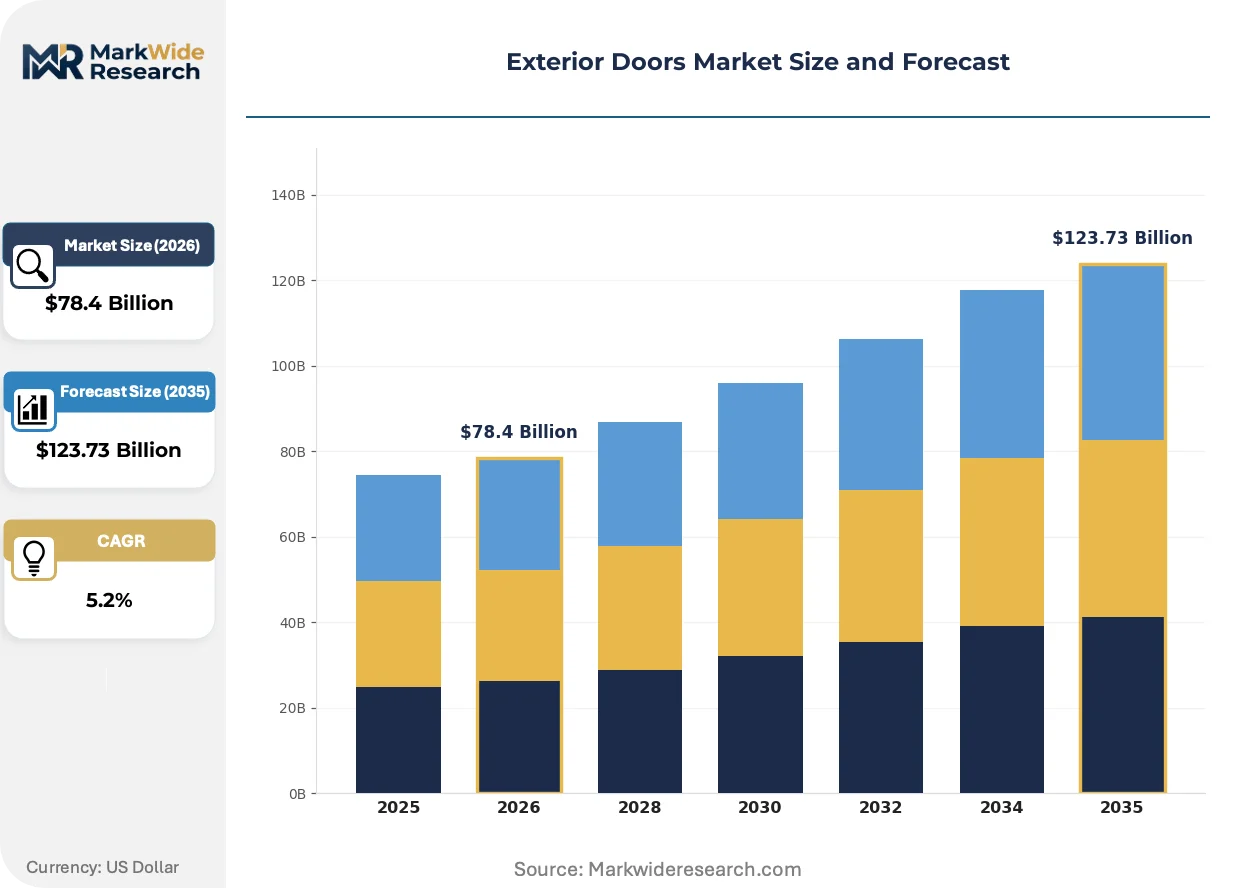
Market Dynamics
The central structural force shaping the exterior doors market is the convergence of stringent energy efficiency regulations and material science advancements. Mandates like the EU's building performance directives and US ENERGY STAR criteria are pushing fiberglass and composites into the mainstream.
Growth Catalysts
- Energy Efficiency Mandates:Stricter building codes in developed economies, including performance directives in the European Union, compel the use of doors with superior thermal insulation (low U-factors), particularly in the large residential renovation segment.
- New Housing Construction:A high volume of new residential projects in countries like the United States and India creates baseline demand for all types of exterior doors, from basic steel to high-performance fiberglass systems.
- Material Substitution:Fiberglass and composite materials continue to gain market share from wood and steel, driven by homeowner demand for enhanced durability, lower maintenance requirements, and superior resistance to weathering and insects.
Market Restraints
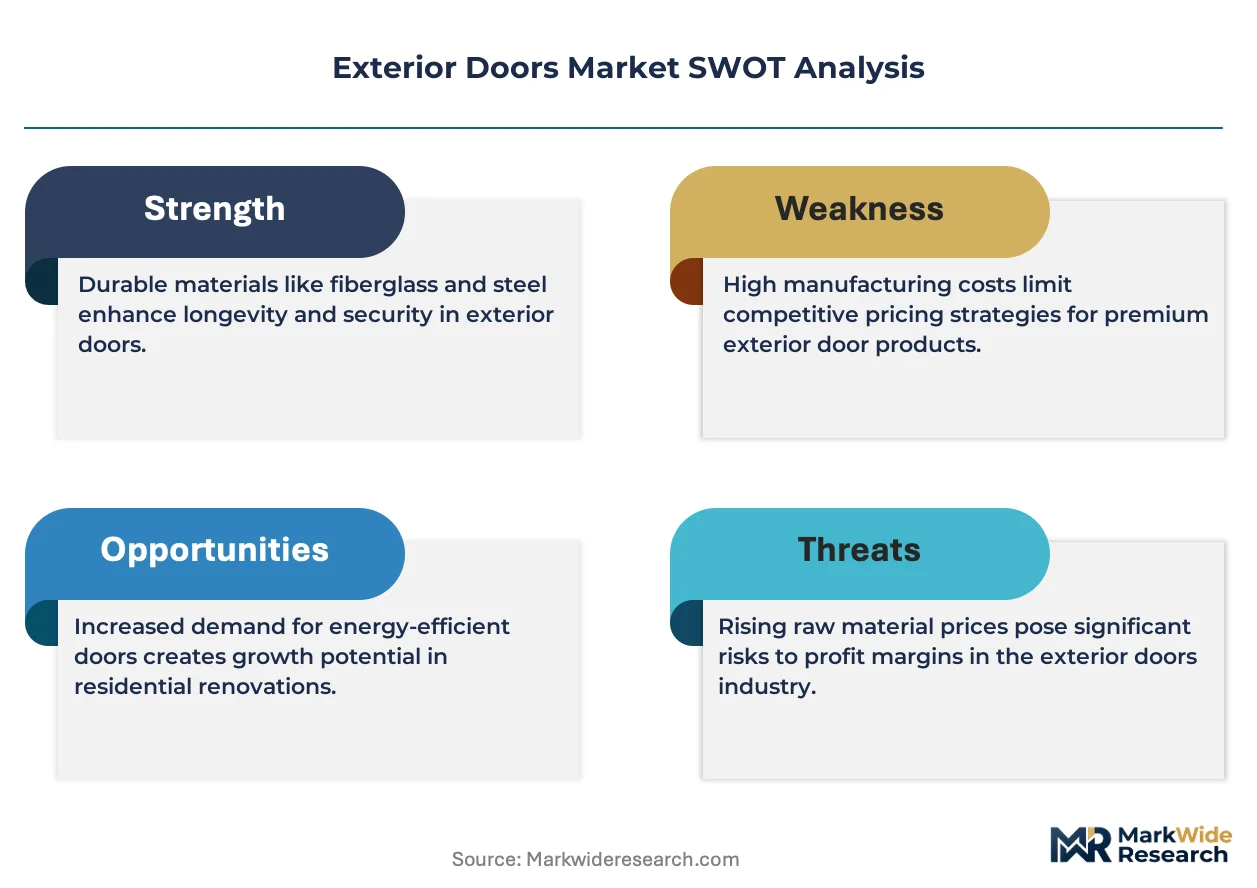
- Raw Material Price Volatility:The cost of resins, fiberglass, and other chemical inputs for composite doors is subject to fluctuations in global commodity markets, creating margin pressure for manufacturers.
- Competition from Traditional Materials:In price-sensitive market segments and certain developing regions, lower-cost traditional wood and standard-gauge steel doors remain a significant competitive substitute, limiting penetration for premium materials.
- Installation Complexity:High-performance, pre-hung door systems require precise installation to ensure energy efficiency and weather-sealing capabilities, creating a dependency on skilled labor which can be a bottleneck.
Strategic Opportunities
- Smart Home Integration:Incorporating smart locks, embedded sensors, and video doorbell technology directly into door systems offers a significant value-add opportunity, targeting the premium residential and security-conscious commercial segments.
- Climate-Resilient Products:Developing and marketing impact-rated and hurricane-resistant door systems for coastal regions and high-wind zones provides a path for product differentiation and access to a high-value, specialized construction market.
- Renovation Incentives:Government programs promoting energy-efficient retrofits, such as tax credits available through the US Inflation Reduction Act (IRA), create direct financial incentives for homeowners to upgrade to higher-performance exterior doors.
Industry Challenges
- Navigating Global Certifications:Manufacturers face complexity and cost in securing and maintaining compliance across divergent regional standards, such as the US ENERGY STAR program, European CE marking, and various ISO quality standards.
- Supply Chain Adaptation:Shifting production from traditional woodworking and metal fabrication to composite material molding and smart component integration requires significant capital investment and reconfiguration of existing supply chains and factory layouts.
- Skilled Labor Scarcity:A shortage of trained installers capable of correctly fitting and sealing advanced, engineered door systems can lead to performance issues and reputational risk, undermining the value proposition of energy-efficient products.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Exterior Doors Market |
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $123.73 Billion |
| CAGR (2026 – 2036) | 5.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Wood, Steel, Fiberglass, Aluminum, Composite Door Style: Panel, Flush, French, Sliding, Folding Application: Residential Homes, Commercial Buildings, Educational Institutions, Government Facilities, Hospitality Venues Installation Type: Pre-hung, Slab, Pocket, Double Door, Revolving |
| Companies Covered | Andersen Windows & Doors, Marvin Windows and Doors, Masonite International, ASSA ABLOY, Hörmann, JELD-WEN, Therma-Tru, Ply Gem, Pella Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Exterior Doors Market Strategic Shifts & Innovations
The market's evolution is defined by the transformation of the exterior door from a simple barrier to an engineered system integral to a building's performance, security, and energy management. This shift is driven by material science, regulatory pressures, and changing consumer expectations for resilience.
Advanced multi-layer core systems using polyurethane foam and other insulating materials provide exceptional thermal performance, measured by U-factor. Residential builders and homeowners undertaking renovations are the primary adopters of this technology. This material evolution is supplanting solid wood and hollow steel doors, which offer inferior insulation and are becoming non-compliant with stricter energy codes in many regions.
European Union building performance directives represent a powerful regulatory driver, establishing progressively stricter minimum requirements for the energy efficiency of building components. This directly forces manufacturers to innovate in thermal break technology and weatherstripping to reduce heat loss through the building envelope. The residential renovation segment in EU member states is most affected, as upgrades must now meet these higher standards.
A distinct behavioral shift is the prioritization of climate resilience in purchasing decisions, especially for properties in vulnerable geographic areas. This disrupts traditional buying criteria, elevating performance certifications like hurricane-impact ratings to a primary consideration alongside aesthetics and cost. This trend is most visible in coastal construction in the United States and is influencing product development for export-oriented manufacturers globally.
Exterior Doors Market Segmentation
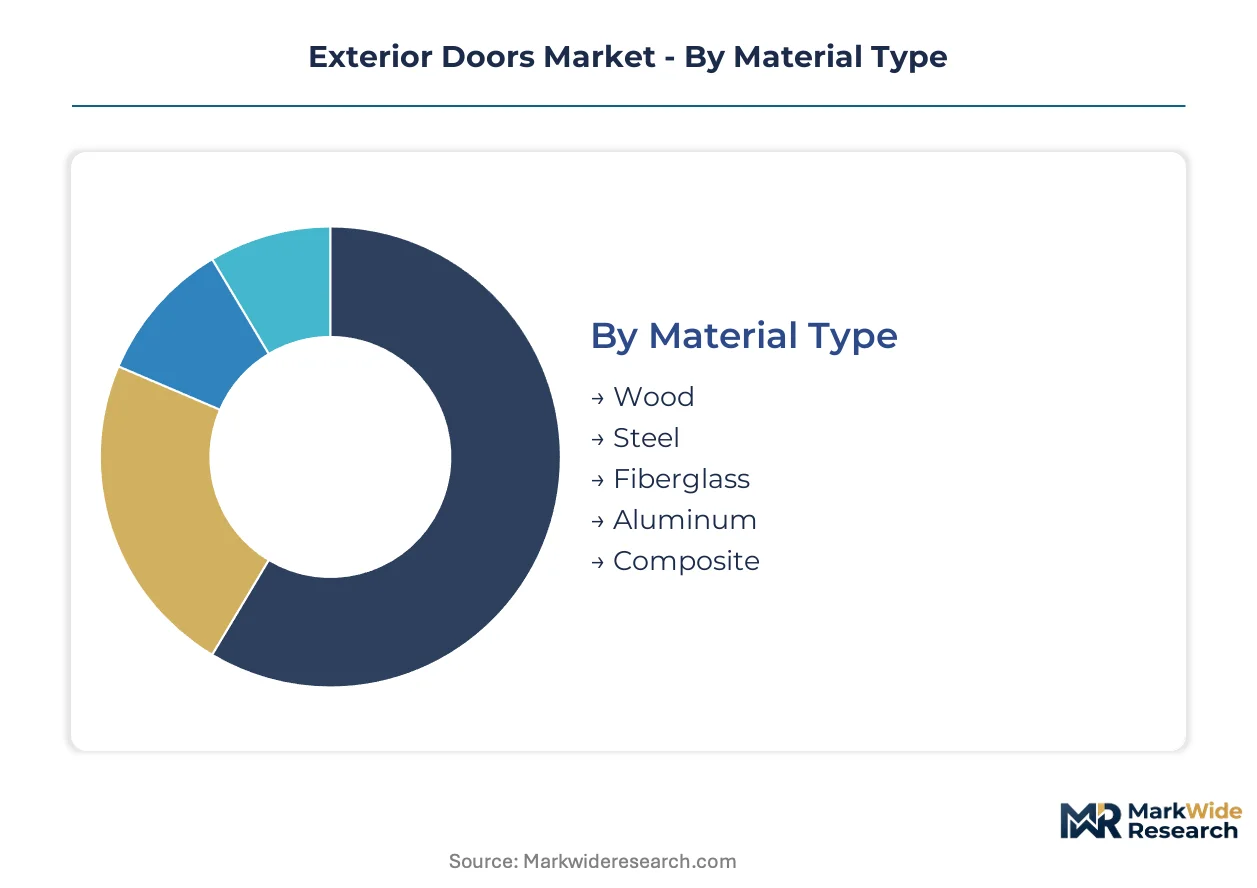
Understanding the exterior doors market through its core segments reveals distinct demand drivers and competitive dynamics. Regulatory pressures and material science advancements influence product specifications across various categories. This granular breakdown aids in identifying high-growth niches and potential areas for strategic investment within the industry.
Material Type:
The material type segmentation highlights intense substitution pressure as advanced composites challenge traditional options across various building projects.
- Fiberglass:These doors feature multi-layer construction, often with polyurethane foam cores, providing superior thermal insulation and weather resistance. Demand concentrates in residential renovation projects, driven by energy efficiency mandates like EU directives and US ENERGY STAR criteria.
- Composite:High-performance composite doors integrate diverse resins and reinforcing fibers, offering exceptional impact resistance and durability. Demand is particularly strong in coastal construction and high-wind zones, influenced by stringent US building codes for climate resilience.
- Wood:Traditional wood doors provide classic aesthetics and natural insulation, primarily serving premium residential and historical renovation segments.
- Steel:Steel doors offer cost-effectiveness and robust security, making them a common choice for entry-level residential and light commercial applications.
- Aluminum:Lightweight aluminum doors are favored for commercial applications and modern designs due to their corrosion resistance and sleek profiles.
Steel retains significant volume leadership; fiberglass holds the steepest expansion curve.
Door Style:
Door style segmentation reflects varied aesthetic and functional requirements across diverse architectural applications.
- Panel:Panel doors feature raised or recessed sections, providing traditional aesthetics for residential and classic commercial buildings.
- Sliding:Sliding doors offer a space-saving solution and expansive views, popular for modern residential patio access and commercial storefronts.
- Flush:Flush doors present a minimalist, flat surface, commonly used in commercial interior applications and contemporary residential designs.
- French:French doors comprise multiple glass panes, enhancing natural light and elegant appeal in residential and hospitality settings.
- Folding:Folding doors create wide, seamless openings, frequently specified for hospitality venues and high-end residential spaces.
Panel doors remain a residential staple, while sliding and folding styles gain traction in contemporary designs.
Application:
Application segmentation reveals the dominant volume contributions from residential projects alongside specialized commercial needs.
- Residential Homes:This segment represents the largest application area, driven by new housing construction in the United States and India, alongside extensive renovation activity.
- Commercial Buildings:Commercial projects demand specialized exterior doors with enhanced security features, fire ratings, and durability for heavy traffic environments.
- Educational Institutions:Doors for educational facilities prioritize durability, security, and adherence to specific safety and accessibility codes.
- Government Facilities:Government buildings require high-security doors, often with blast resistance and adherence to stringent national certifications.
- Hospitality Venues:Hospitality applications emphasize aesthetic appeal, acoustic performance, and advanced access control systems for guest rooms and public areas.
Residential homes consistently drive the largest demand, with commercial applications requiring stringent performance specifications.
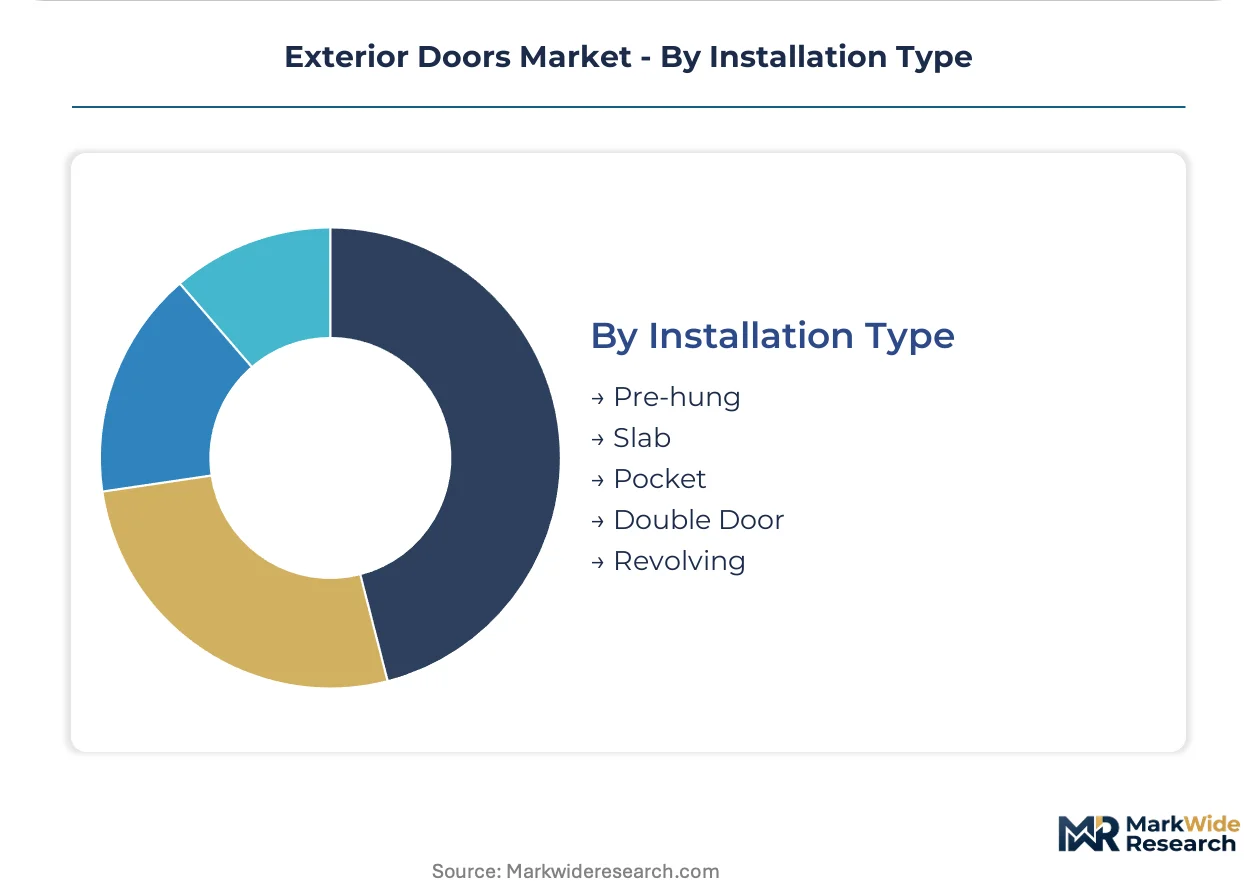
Installation Type:
Installation type segmentation differentiates between established methods and specialized solutions for unique architectural demands.
- Pre-hung:Pre-hung systems include the door slab, frame, and hardware pre-assembled, simplifying installation and ensuring optimal energy efficiency in residential projects.
- Slab:Slab doors consist solely of the door panel, offering cost-effective replacement options for existing frames or custom installations in renovation projects.
- Pocket:Pocket doors slide into a wall cavity, providing a space-saving solution typically used for interior applications in compact residential designs.
- Double Door:Double door systems create grand entrances, commonly specified for both high-end residential properties and commercial main entryways.
- Revolving:Revolving doors manage high pedestrian traffic flow while minimizing energy loss, primarily installed in commercial buildings and institutional facilities.
Pre-hung systems simplify installation, while specialized types like revolving doors address specific commercial requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global exterior doors market exhibits varied regional dynamics, with certain countries acting as net exporters of finished products and others as primary importers. This balance influences local manufacturing investment and supply chain configurations. Demand often concentrates in regions with robust construction activity and stringent energy efficiency mandates.
United States
New housing construction and extensive residential renovation projects drive substantial demand for exterior doors. The US ENERGY STAR criteria and tax credits available through the US Inflation Reduction Act (IRA) compel manufacturers to offer higher-performance products. Florida's coastal construction market consistently drives demand for impact-rated and hurricane-resistant door systems.
Germany
Energy-efficient retrofits and residential renovations significantly contribute to door demand in Germany. EU building performance directives and CE marking requirements mandate superior thermal insulation for all building components. Bavaria's construction sector actively prioritizes high U-factor performance for new and upgraded buildings.
India
Rapid urbanization and a high volume of new housing developments create baseline demand for exterior doors across India. BIS standards for building materials influence product specifications and quality benchmarks. Major metropolitan areas like Delhi-NCR experience sustained volume demand for entry-level and mid-range door solutions.
China
Extensive residential and commercial building projects, alongside ongoing urban development, drive significant demand for exterior doors in China. GB standards for construction materials guide product compliance and manufacturing processes. The Yangtze River Delta region sees substantial manufacturing and consumption of diverse door types.
Canada
Residential new builds and renovation activity contribute to consistent demand for exterior doors, particularly those designed for cold climate insulation. National building codes emphasize thermal performance for exterior envelopes, influencing product design. Ontario's housing market demonstrates consistent demand for energy-efficient door systems.
Exterior Doors Market Key Industry Players
Listed leaders compete with private specialists across distribution reach and material innovation within the exterior doors market. The market exhibits a tiered structure, with large, diversified manufacturers alongside niche providers focused on specific material types or applications. Major players frequently engage in strategic partnerships to expand their product portfolios and prioritize capacity expansion to meet growing demand in key residential segments.
Scale-driven manufacturers like JELD-WEN and Masonite International exemplify diversified approaches to market penetration. JELD-WEN, Inc. leverages its extensive distribution network across various channels. Masonite International focuses on material innovation, particularly in composite and fiberglass lines. Therma-Tru Corporation represents a premium brand strategy, commanding higher price points in the North American fiberglass entry door segment. These entities anchor distinct competitive archetypes within the global exterior doors market.
| Leading Market Players |
|---|
| Andersen Windows & Doors |
| Marvin Windows and Doors |
| Masonite International |
| ASSA ABLOY |
| Hörmann |
| JELD-WEN |
| Therma-Tru |
| Ply Gem |
| Pella Corporation |
| Others |
Cost & Logistics Intelligence
EU building performance directives gate both supply qualification and price differentiation across the exterior doors market. These regulations enforce material specifications and thermal performance, directly impacting manufacturing costs and market access for premium products.
Pricing Analysis
Industrial OEM buyers anchor transactional pricing for standard steel and wood doors in high-volume new construction projects. Price differentiation stems from performance certifications like US ENERGY STAR ratings and specialized features such as hurricane-impact resistance. Pricing pressure intensifies for basic material categories due to raw material price volatility and competition from lower-cost substitutes. Residential renovation projects, particularly for high-performance fiberglass doors, exhibit lower price sensitivity due to homeowner focus on long-term energy savings and durability.
Supply Chain Analysis
Specialized resin and fiberglass production capacity underwrites the supply chain for high-performance exterior doors. Supply concentrates in regions with advanced manufacturing capabilities, including parts of North America and Europe, alongside China for basic components. The market depends on raw materials like resins, fiberglass, and steel, making it susceptible to global commodity price fluctuations. Distribution runs through both direct channels to large-scale builders and fragmented networks serving the remodeling and custom-build segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The exterior doors market offers a fragmentation opportunity as evolving regulatory demands and climate resilience priorities create distinct, underserved niches.
For Market Incumbents:
Consolidate market share by strategically acquiring smaller, specialized manufacturers focused on smart home integration or advanced material sciences. Invest in R&D for next-generation composite materials to counter the threat of material substitution and meet increasingly stringent energy efficiency mandates. Leverage extensive distribution networks to push high-performance product lines into the growing residential renovation segment, reinforcing brand loyalty against emerging entrants.
For New Entrants and Emerging Players:
A service-layer gap exists in the precise installation and post-sales support for complex, high-performance door systems. Target the premium residential and coastal construction segments with specialized climate-resilient products and certified installation services. A direct-to-consumer model combined with expert installation partnerships can differentiate offerings, particularly for smart-enabled door systems that require specialized setup and integration expertise.
For Investors and Strategic Acquirers:
Capital-intensity ratios are inflecting upwards across the high-performance composites and smart door systems sub-segments, indicating long-term growth potential. Target specialized material innovators or software companies integrating smart home technology directly into door hardware. The signal to watch is the adoption rate of integrated smart locks and embedded sensors in new housing starts, indicating a shift towards value-added, connected building components.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Advanced Composite R&D | Develop next-generation materials offering superior thermal insulation and impact resistance for regulatory compliance. |
| Expand Smart Home Integration | Incorporate embedded sensors and video doorbell technology to capture premium residential market share. |
| Acquire Specialized Installation Firms | Ensure precise fitting and optimal performance of engineered door systems, mitigating skilled labor scarcity risks. |
| Strengthen Coastal Market Presence | Develop and market impact-rated door systems for high-wind zones, accessing a high-value construction segment. |
| Optimize Supply Chain for Resins | Mitigate raw material price volatility by securing long-term contracts for critical resins and fiberglass inputs. |
Research Approach
Two parallel data streams informed the analysis: extensive primary interviews and rigorous secondary research. We engaged with architects, builders, material suppliers, and distribution channel partners to gather qualitative insights into market dynamics. This primary intelligence was triangulated with secondary data from building codes, energy efficiency program reports, company financial statements, and construction industry statistics.
The analytical framework modeled market volume and value across the projection horizon, segmenting by material type, application, installation type, and key geographies. Compound annual growth rates were derived from historical data trends and projected shifts in regulatory environments and consumer preferences. Housing starts data and residential renovation expenditure served as critical industry-specific forecast inputs for market demand projections.
Underlying assumptions cover stable economic growth and consistent regulatory enforcement, with deviation risk concentrated in raw material price shifts and unexpected changes to building codes. Revision becomes warranted when global commodity prices or major regional construction activity indicators cross predefined thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
China Cement Market
Building Materials
Calcium Aluminate Cement Market
Building Materials
Roofing and Tile Underlayment Market
Building Materials
Foam Bricks Market
Building Materials
Global Magnesia Chrome Brick Market
Building Materials
Middle East and Africa Concrete Admixtures Market
Building Materials
Latin America Facade Market
Building Materials
Fiber Cement Market
Building Materials
Europe Concrete Admixtures Market
Building Materials
Granite Market
Building Materials
Construction Repair Composites Market
Building Materials
Construction Materials Market
Building Materials
Light Gauge Steel Framing Market
Building Materials
Africa Green Cement Market
Building Materials
India Cement Market
Building Materials
Solar Control Window Film Market