
 North America Building Thermal Insulation Market | 2026-2036
North America Building Thermal Insulation Market Size, Share, and Industry Trends Forecast 2026-2036
North America Building Thermal Insulation Market Intelligence
Multi-source procurement among large-scale contractors is hardening as a standard practice across the North America Building Thermal Insulation Market. Owens Corning leverages its integrated fiberglass manufacturing network to sustain material availability across volatile resin markets. Johns Manville Corporation anchors its position through deep specialization in commercial roofing and mechanical insulation systems. ROCKWOOL Insulation A/S differentiates via fire-resistant mineral wool formulations that command specification in high-rise and institutional envelopes.
North America Building Thermal Insulation encompasses engineered materials designed to reduce conductive heat flow through building envelopes, typically measured by thermal resistance values ranging from R-13 to R-60 depending on climate zone and assembly type. These materials function to minimize energy transfer between conditioned interior spaces and external environments, directly reducing HVAC load and operational carbon emissions. Fiberglass retains the largest installed base across residential walls and attics, though spray foam commands premium pricing in commercial applications where air sealing and moisture control integrate with thermal performance. Mineral wool occupies a defensible niche in fire-rated assemblies and industrial process piping where temperature extremes exceed polymer stability thresholds.
The EPA Energy Star certification program and IECC model code cycles shape product specifications and contractor compliance obligations across U.S. jurisdictions, while Canada's National Building Code and provincial energy step codes drive parallel demand in that market. The U.S. Department of Energy building standards program and state-level stretch codes in California, New York, and Massachusetts create fragmented but escalating performance floors that manufacturers must map. Stakeholders should monitor code adoption timelines and utility incentive program designs to anticipate regional demand inflections before competitors lock in specification relationships.
Market Dynamics
Commercial retrofit mandates across the United States are compressing specification cycles as aging office stock faces simultaneous pressure from IECC code cycles, EPA Energy Star thresholds, and utility incentive program redesigns.
Growth Catalysts
- IECC Model Code Adoption:Multiple U.S. states are implementing 2021 and 2024 code cycles that mandate higher R-value assemblies in both new construction and renovation projects, pulling forward replacement demand.
- Cooling-Dominated Climates:The southeastern United States generates outsized demand for spray-applied and advanced foam systems where humidity management integrates with thermal performance requirements.
- Utility Rebate Program Expansion:State-level energy efficiency programs in California, New York, and Massachusetts are deepening contractor engagement through performance-based incentive structures.
Market Restraints
- Petrochemical Feedstock Volatility:Spray foam and extruded polystyrene manufacturers face margin compression from benzene and methanol price swings that resist pass-through in competitive bid environments.
- Regional Production Concentration:Fiberglass batt manufacturing clusters in the Ohio River Valley create geographic supply vulnerability to winter logistics disruptions and rail bottlenecks.
- Fire-Rating Substitution Limits:Polymer-based insulations face specification ceilings in high-rise envelopes where mineral wool retains mandatory status under NFPA 285 assembly testing protocols.
Strategic Opportunities
- Canadian Energy Step Code Alignment:British Columbia and Ontario provincial codes are accelerating toward net-zero-ready standards, opening premium system demand ahead of U.S. adoption curves.
- Deep Energy Retrofit Bundling:HVAC replacement and envelope upgrade convergence creates specification pull for integrated air-sealing and insulation packages in commercial office renovation.
- Cross-Laminated Timber Hybrid Assemblies:Mass timber construction growth in Pacific Northwest and Northeast markets favors breathable insulation systems that manage moisture in solid-wood envelopes.
Industry Challenges
- Certified Installer Scarcity:Spray foam application requires EPA Section 608 refrigerant handling credentials plus manufacturer-specific training, constraining crew expansion in high-demand markets.
- Code Cycle Fragmentation:Contractors operating across multiple states face compliance mapping complexity as jurisdictions adopt staggered IECC editions with varying amendment packages.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Building Thermal Insulation Market |
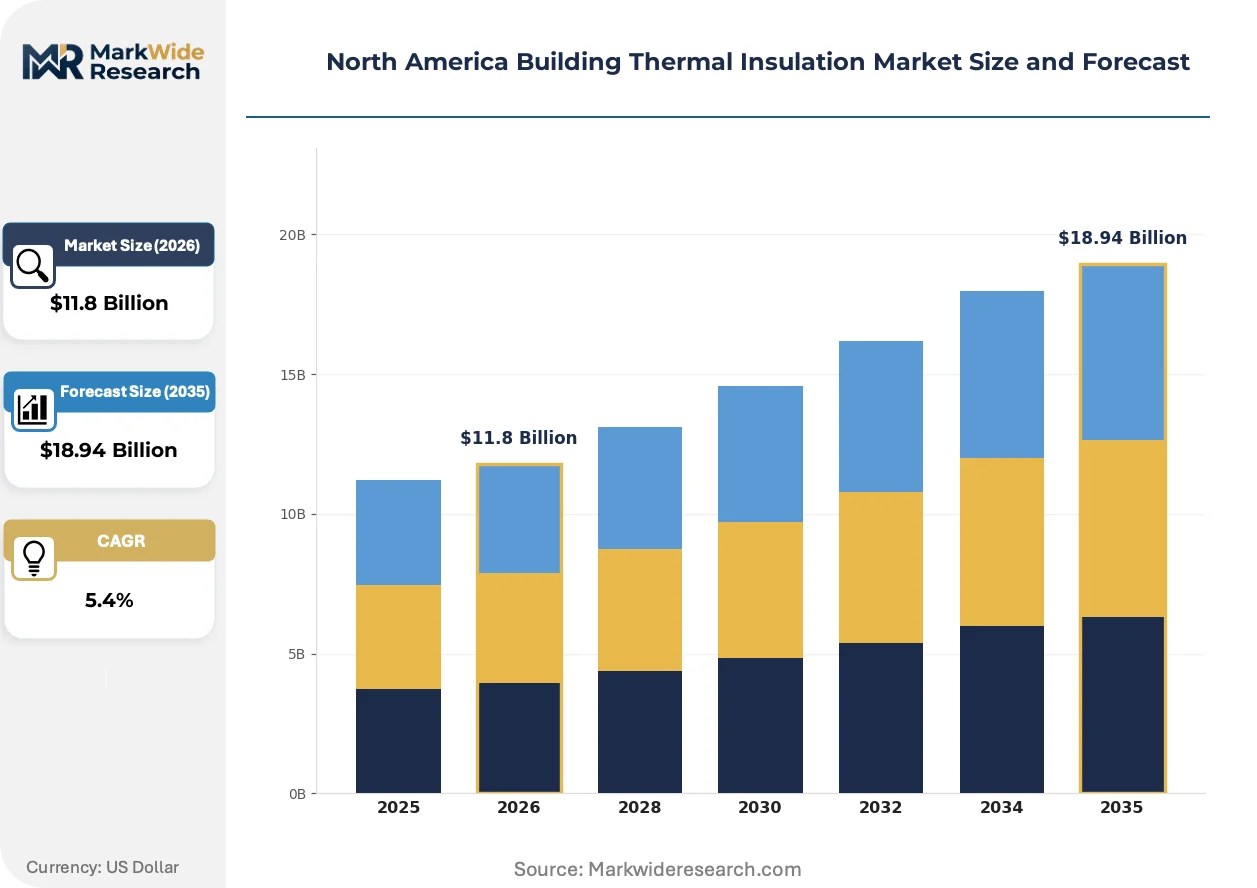
| Market Size in 2026 | $11.8 Billion |
| Market Size in 2035 | $18.94 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fiberglass, Foam Board, Spray Foam, Mineral Wool End User: Residential, Commercial, Industrial, Institutional Installation Method: Batt, Blown-in, Rigid, Spray Application: Walls, Roofs, Floors, Crawl Spaces |
| Companies Covered | Saint-Gobain, Johns Manville Corporation, Owens Corning, Knauf Insulation, ROCKWOOL Insulation A/S, Kingspan Group, Dow Inc., CertainTeed Corporation, GAF Materials Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Building Thermal Insulation Market Strategic Shifts & Innovations
Bio-based and recycled-content formulations are gaining specification traction as embodied carbon accounting penetrates procurement criteria across institutional and corporate real estate portfolios.
Aerogel blanket systems are expanding into curtain wall spandrel applications where extreme thermal resistance must fit within constrained cavity depths. High-performance commercial facade contractors in Chicago and Toronto are specifying silica aerogel composites for cold-climate high-rises. This technology is expanding into markets previously dominated by vacuum insulated panels by offering comparable R-value per inch without field-handling fragility.
The EPA Energy Star Multifamily New Construction program and evolving ASHRAE Standard 90.1 appendices are tightening whole-building thermal performance modeling requirements. Design teams must now document envelope assembly R-values through third-party verification rather than default tables. Commercial developers in Massachusetts and Washington state are responding by pre-specifying continuous insulation systems that exceed code minimums to buffer against future cycle escalation.
Large-scale general contractors are consolidating insulation procurement through national account structures that bypass traditional distribution layers. This channel compression concentrates volume with manufacturers offering direct-to-site logistics and certified installation networks. The phenomenon is most visible in Sun Belt metropolitan areas where multifamily ground-up construction remains at elevated levels.
North America Building Thermal Insulation Market Segmentation
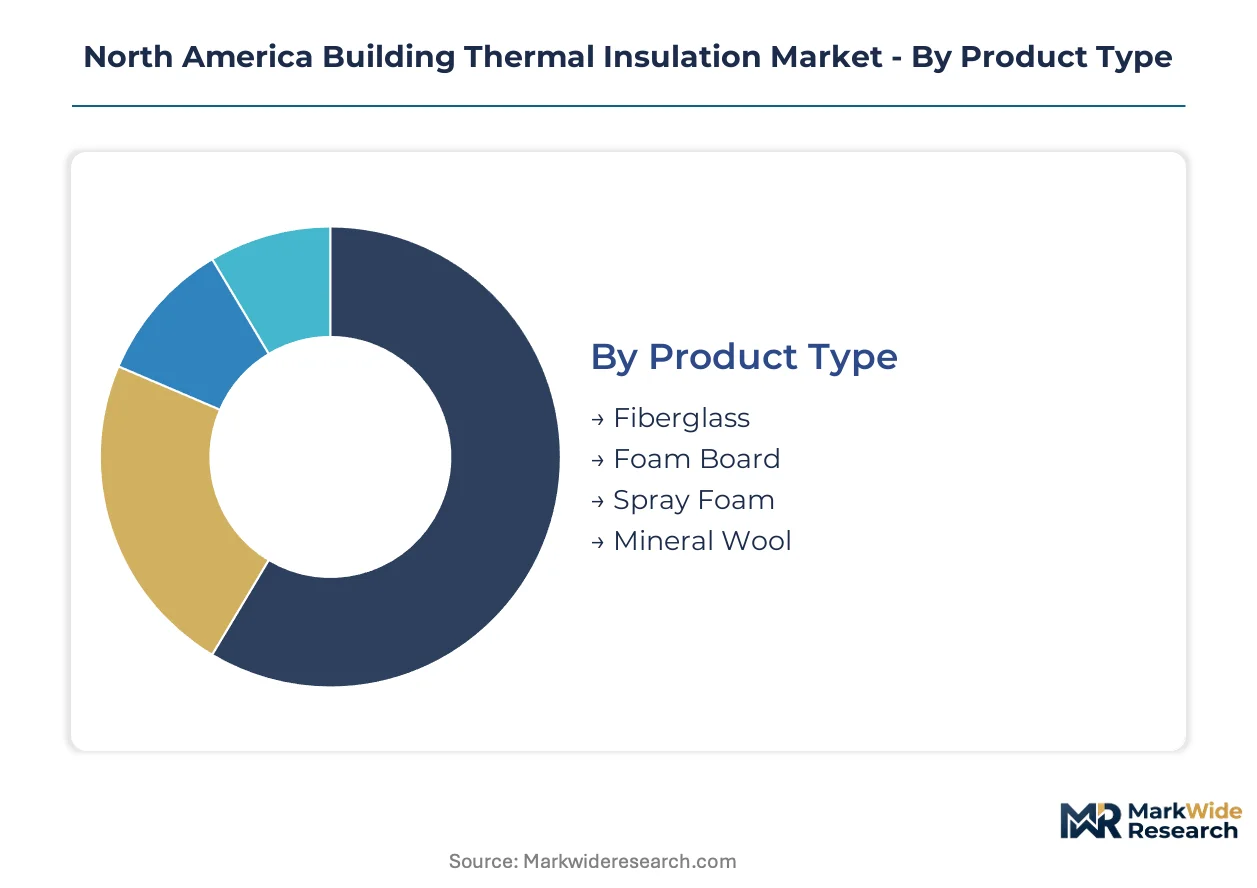
Segmentation in the North America Building Thermal Insulation Market reveals how specification requirements diverge across climate zones, assembly types, and regulatory environments. Contractors and architects navigate these categories to match thermal performance, fire ratings, and installation constraints to project-specific demands.
Product Type:
Standardization dominates fiberglass and foam board manufacturing, while spray foam and mineral wool require greater customization to project specifications and code requirements.
- Fiberglass:Composed of fine glass fibers bound with phenolic resin, this material delivers R-values between R-13 and R-49 depending on density and thickness. Demand concentrates in residential wall cavities and attic spaces across the Midwest and Plains states where cost sensitivity and batt installation familiarity drive specification. IECC code minimums in these regions rarely exceed fiberglass performance thresholds.
- Spray Foam:Two-component polyurethane systems expand on application to create monolithic air barriers with R-values reaching R-6.5 per inch for closed-cell formulations. Commercial retrofit contractors in Florida and Texas specify this material where humidity control and air sealing integrate with cooling load reduction in high-performance envelopes.
- Foam Board:Extruded polystyrene and polyisocyanurate panels provide continuous insulation in commercial facades and below-grade assemblies.
- Mineral Wool:Stone or slag wool fibers deliver fire resistance up to 2,150°F, commanding specification in NFPA 285-tested high-rise curtain walls.
Most installed capacity flows through Fiberglass. Expansion is steepest in Spray Foam.
End User:
Cost tiers separate residential retrofit from institutional new construction, with commercial and industrial occupying intermediate positions on specification complexity and performance premiums.
- Residential:Single-family and multifamily builders drive volume through batt and blown-in systems in walls, attics, and crawl spaces. Demand clusters in Sun Belt metropolitan areas where new construction permits remain elevated and utility rebate programs in California and Massachusetts subsidize deep energy retrofits.
- Commercial:Office, retail, and hospitality renovation projects specify continuous insulation and air-sealing packages to meet ASHRAE Standard 90.1 appendix compliance. Aging office stock in Chicago and New York faces simultaneous pressure from EPA Energy Star certification requirements and local energy benchmarking ordinances.
- Industrial:Process piping, tanks, and equipment insulation in refineries and manufacturing facilities require temperature stability beyond polymer limits.
- Institutional:Schools, hospitals, and government buildings prioritize fire-rated assemblies and embodied carbon accounting in procurement criteria.
Residential commands the greatest material volume. Commercial retrofits are climbing the fastest as code cycles tighten.
Installation Method:
Volume scale and crew skill requirements create distinct margin profiles across methods, from commodity batt labor to certified spray foam application.
- Batt:Pre-cut fiberglass or mineral wool sections friction-fit between studs and joists, requiring minimal specialized equipment. Production homebuilders in the southeastern United States favor this method for speed and predictable labor costing on repetitive floor plans.
- Blown-in:Loose-fill cellulose or fiberglass pneumatically deposited in attic floors and closed wall cavities achieves higher coverage density than batt. Weatherization contractors in Pennsylvania and Ohio leverage utility program funding to deploy this method in low-income housing stock.
- Rigid:Foam board mechanically fastened or adhered to substrates provides continuous insulation without thermal bridging.
- Spray:On-site chemical reaction requires EPA Section 608 certified applicators and respiratory protection protocols.
Batt installation handles the greatest square footage. Spray application is gaining share fastest in high-performance commercial envelopes.
Application:
Assembly location determines moisture management strategy, fire exposure, and accessibility constraints that filter product selection.
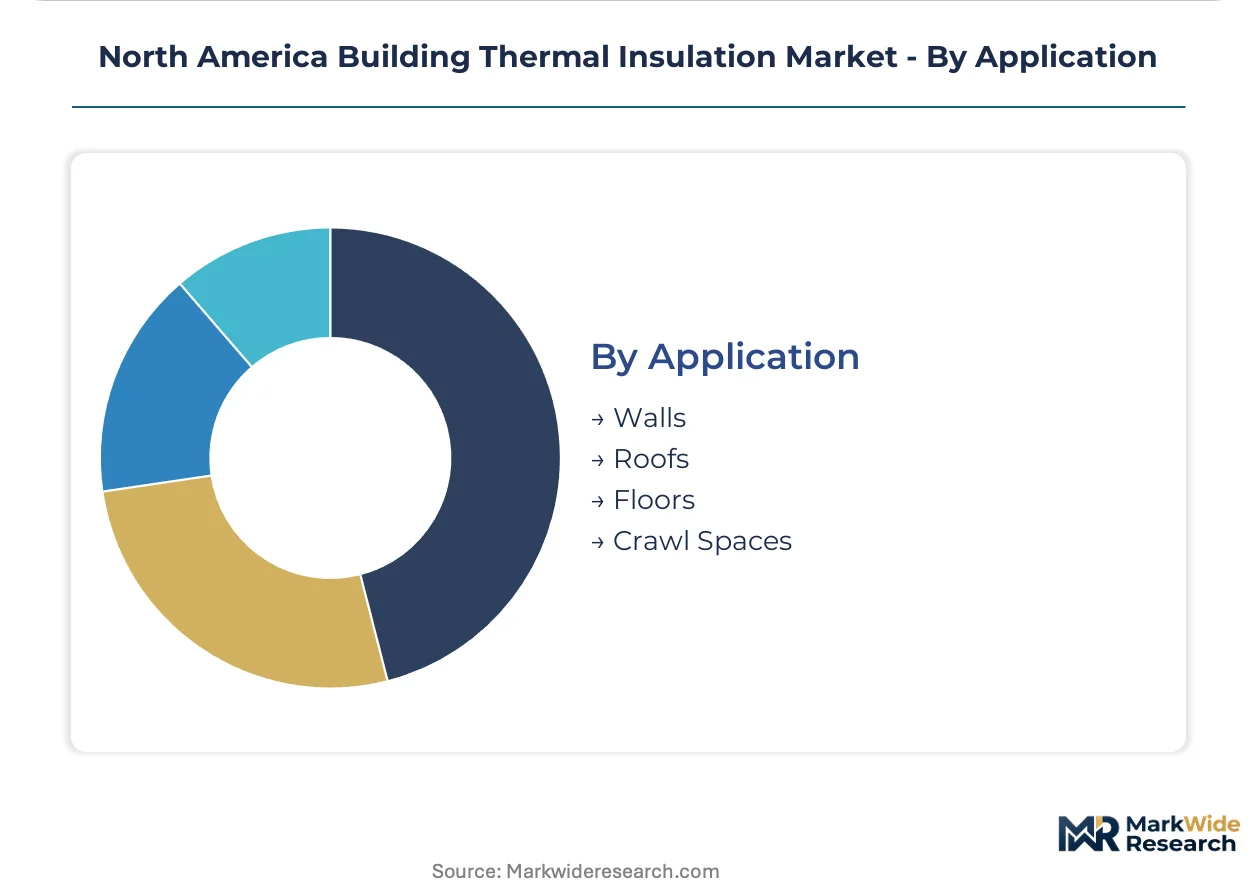
- Walls:Above-grade framed assemblies accommodate batt, spray foam, or rigid board depending on cavity depth and continuous insulation requirements. Deep energy retrofits in Massachusetts and Washington state increasingly specify exterior rigid board with rainscreen cladding to exceed current IECC minimums.
- Roofs:Flat commercial assemblies and residential attics present distinct challenges of compressive strength, dimensional stability, and ventilation integration. SPF contractors in Texas and Arizona dominate this segment where cooling load reduction justifies premium material costs.
- Floors:Above unconditioned crawl spaces or garages, insulation must resist gravity loading and pest intrusion.
- Crawl Spaces:Below-grade perimeter walls and rim joists require moisture-tolerant materials and vapor barrier integration.
Wall assemblies absorb the largest material volumes. Roof applications are expanding most quickly in commercial retrofit markets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory divergence between Canadian provincial energy step codes and U.S. state-level IECC adoption timelines is creating arbitrage opportunities for manufacturers with cross-border production flexibility. Compliance cost gaps favor investment in jurisdictions with slower code escalation cycles.
United States
The southeastern United States generates concentrated demand for spray-applied foam systems where cooling-dominated climates and humidity management requirements dominate specification. EPA Energy Star certification thresholds and accelerating IECC code cycles in California, New York, and Massachusetts are tightening minimum R-value requirements for both new construction and renovation. The Chicago metropolitan area anchors commercial retrofit activity as aging office stock faces simultaneous pressure from local energy benchmarking ordinances and ASHRAE Standard 90.1 compliance deadlines.
Canada
British Columbia and Ontario provincial energy step codes are accelerating toward net-zero-ready standards, opening premium system demand ahead of U.S. adoption curves. The National Building Code and provincial amendments drive parallel demand for higher-performance assemblies in institutional and multifamily construction. Toronto and Vancouver metropolitan areas concentrate specification activity for continuous insulation and air-sealing packages in mid-rise residential and commercial envelope projects.
Mexico
Industrial manufacturing expansion along the northern border states is pulling insulation demand for process piping and facility envelopes serving export-oriented production. CONUEE energy efficiency programs and evolving building codes in Mexico City and Monterrey are gradually tightening thermal performance requirements for commercial construction. The Bajío Region automotive cluster generates specialized demand for high-temperature industrial insulation systems exceeding polymer stability thresholds.
North America Building Thermal Insulation Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue bio-based formulations and recycled-content specializations that command specification in institutional procurement. The market structure reflects moderate consolidation with three to five integrated manufacturers controlling volume production of fiberglass and foam board categories. Strategic archetypes include integrated resin-to-finished-goods operators, mineral wool specialists leveraging fire-rating differentiation, and regional spray foam applicator networks. Dominant competitive moves center on national account direct procurement relationships and certified installer network expansion.
Within the integrated manufacturing tier, Owens Corning and Johns Manville Corporation exemplify scale-driven positions anchored in fiberglass production networks. ROCKWOOL Insulation A/S occupies the fire-resistant mineral wool specialization, commanding specification in high-rise and institutional envelopes where NFPA 285 assembly testing protocols mandate non-combustible materials. These three entities represent distinct strategic positions: resin-integrated fiberglass supply, commercial roofing and mechanical insulation depth, and fire-rated formulation expertise.
| Leading Market Players |
|---|
| Saint-Gobain |
| Johns Manville Corporation |
| Owens Corning |
| Knauf Insulation |
| ROCKWOOL Insulation A/S |
| Kingspan Group |
| Dow Inc. |
| CertainTeed Corporation |
| GAF Materials Corporation |
| Others |
Cost & Logistics Intelligence
Benzene and methanol price indices cascade through spray foam and extruded polystyrene supply chains, compressing margins for polymer-based insulation manufacturers while fiberglass producers anchored in captive resin networks maintain pricing power across volatile petrochemical cycles.
Pricing Analysis
Input-cost pass-through from benzene and methanol volatility fragments pricing power across polymer insulation tiers. Three-tier pricing structure across premium, standard, and economy levels separates certified spray foam applicators from commodity batt distributors from regional mineral wool suppliers. Pricing pressure stems from petrochemical feedstock swings that resist full pass-through in competitive bid environments for commercial retrofit projects. Residential retrofit contractors exhibit highest price sensitivity, while institutional developers prioritize fire-rating certification over unit economics.
Supply Chain Analysis
EPA Section 608 certification and manufacturer-specific applicator training gate access to spray foam installation networks, concentrating qualified crew capacity in Sun Belt metropolitan markets. Raw material sourcing draws from Ohio River Valley fiberglass manufacturing clusters, Gulf Coast petrochemical corridors, and Ontario mineral wool production facilities. Single-source vulnerability concentrates in rail-dependent resin deliveries to Midwest batt plants during winter logistics disruptions. Distribution runs through national account structures that bypass traditional wholesale layers for large-scale general contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The North America Building Thermal Insulation Market functions as a stable compounder where successive IECC code cycles create replacement demand pull with limited cyclical volatility.
For Market Incumbents: To counter margin compression from petrochemical volatility, secure backward integration into phenolic resin production or captive benzene sourcing through Gulf Coast pipeline networks. Expand certified installer academies in Florida and Texas to lock out emerging spray foam competitors before crew scarcity eases. For New Entrants and Emerging Players: E-commerce specification platforms targeting residential retrofit contractors in Pennsylvania and Ohio offer lowest barrier-to-entry routes for bio-based insulation formulations. Prioritize loose-fill cellulose segments where utility program funding subsidizes weatherization deployment and brand loyalty remains undeveloped. For Investors and Strategic Acquirers: Asymmetric upside sits with regional spray foam applicator networks possessing EPA certification density in cooling-dominated climate zones. Five-to-ten year viability hinges on code adoption velocity rather than construction cycle timing. Monitor British Columbia energy step code implementation as early indicator of premium system demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Certified Installer Network Expansion | EPA Section 608 credentialing programs in Texas and Florida lock in specification relationships before crew capacity saturates. |
| Backward Integration into Resin Supply | Captive phenolic production shields Owens Corning and Johns Manville from benzene price volatility in fiberglass manufacturing. |
| Cross-Border Production Flexibility | Ontario and British Columbia facilities capture Canadian energy step code premiums ahead of U.S. IECC adoption curves. |
| Bio-Based Formulation Development | Recycled-content and plant-based binders command specification in institutional procurement with embodied carbon accounting requirements. |
| National Account Direct Procurement | Bypassing distribution layers concentrates volume with manufacturers offering site-direct logistics for Sun Belt multifamily construction. |
Research Approach
Multiple input streams — primary interviews with commercial contractors and building envelope specifiers, secondary validation through IECC adoption tracking and utility program databases, and trade flow analysis — were reconciled to construct market estimates. Conversations with spray foam applicators, fiberglass distribution managers, and institutional procurement officers informed capacity and pricing intelligence. Secondary sources included U.S. Department of Energy building standards documentation, Canadian National Building Code amendments, and EPA Energy Star certification records. Bottom-up project pipeline analysis and top-down construction spending triangulation anchored volume forecasts.
Historical construction permit trajectories were cross-referenced against panel input from regional contractor associations to model segment growth across the projection horizon. Segmentation dimensions included product type, installation method, end-use sector, and climate zone regulatory cluster. CAGRs were derived from code adoption timelines and replacement cycle analysis rather than extrapolated trend fitting. Key inputs encompassed IECC amendment tracking, utility rebate program redesign schedules, and petrochemical feedstock correlation models.
Regulatory delay, petrochemical price spike persistence, and certified installer training bottlenecks are the dominant revision risks to modeled demand. Forecasts reflect documented assumptions regarding code adoption velocity and construction labor availability. A model refresh is warranted upon material change in IECC 2024 cycle adoption rates across southeastern states.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
HVAC Systems
Air Pressure Booster System Market
HVAC Systems
Global Commercial Insulation Market
HVAC Systems
US Commercial HVAC Rooftop Units Market
HVAC Systems
Marine HVAC Market
HVAC Systems
Industrial Exhaust Fan Market
HVAC Systems
Residential Hydronic Underfloor Heating Market
HVAC Systems
North America and GCC HVAC Insulation Market
HVAC Systems
Global Building Thermal Insulation Market
HVAC Systems
Hospital HVAC Systems Market
HVAC Systems
Malaysia Building Thermal Insulation Material Market
HVAC Systems
Industrial Hood Ventilation Market
HVAC Systems
Tunnel and Metro Ventilation Fans Market
HVAC Systems
Ductless HVAC System Market
HVAC Systems
Europe District Cooling Pipeline Network Market
HVAC Systems
Spray Booth Ventilation System Market
HVAC Systems
Global Building Thermal Insulation Material Market