
 Middle East and Africa Concrete Admixtures Market | 2026-2036
Middle East and Africa Concrete Admixtures Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East and Africa Concrete Admixtures Market Foresight
Multi-source procurement among ready-mix suppliers is consolidating around fewer technical-grade admixture partners with regional blending capabilities. Sika leverages its integrated supply chain across Gulf markets to secure bulk contracts for mega-project concrete supply. Fosroc International anchors its position through localized manufacturing in Saudi Arabia and South Africa, reducing import dependency for water-reducing formulations. BASF SE competes on R&D intensity, sustaining patent coverage in polycarboxylate ether superplasticizers tailored for hot-climate placement conditions.
Concrete admixtures encompass chemical and mineral additives dosed at less than five percent by weight of cementitious content to modify fresh or hardened concrete properties, including slump retention, air entrainment, and chloride ingress resistance. Their primary industrial purpose centers on enabling pumpable, durable concrete in aggressive environments while reducing water-cement ratios below 0.40 for specified compressive strengths. Superplasticizers command the largest product-type value pool due to their essential role in self-consolidating and high-strength concrete formulations across Gulf skyscraper projects. Infrastructure Development represents the fastest-growing application segment, driven by rail networks, desalination plants, and renewable energy foundations spanning Morocco to Oman. Ready-Mix Concrete dominates delivery mode volumes as batch-plant centralization replaces site-mixed practices in urban corridors.
Saudi Standards, Metrology and Quality Organization (SASO) and South African Bureau of Standards (SABS) enforce cement-admixture compatibility testing and environmental release thresholds that shape product registration timelines and reformulation costs for imported chemistries. The UAE's Ministry of Climate Change and Environment applies green building rating alignment to public project specifications, filtering admixture selection toward formulations with verified embodied carbon reductions. Stakeholders must monitor how evolving national building codes across Kenya, Egypt, and Nigeria adopt performance-based concrete standards that privilege certified admixture suppliers over commodity traders.
Market Dynamics
Mega-infrastructure procurement across the Gulf Cooperation Council is consolidating specification power around fewer technical-grade admixture suppliers with regional blending capabilities, compressing margins for commodity traders while rewarding integrated formulators.
Growth Catalysts
- Dubai's High-Rise Pipeline:Sustained skyscraper construction in the United Arab Emirates requires specialized superplasticizers for vertical concrete pumping above 300 meters, creating dedicated demand for slump-retention chemistries.
- SASO Compatibility Mandates:Saudi Arabia's national standards body now enforces cement-admixture compatibility testing that filters uncertified imports and privileges pre-registered technical suppliers.
- Desalination Infrastructure:Coastal concrete specifications for chlorides resistance are accelerating procurement of corrosion-inhibiting admixtures across Oman, Qatar, and Kuwait.
Market Restraints
- Naphthalene Feedstock Volatility:Conventional superplasticizer production depends on petrochemical derivatives whose price swings compress formulation margins for regional blenders.
- Import Dependency in East Africa:Kenya and Ethiopia lack domestic polycarboxylate ether production, exposing contractors to currency-driven cost spikes and extended lead times.
- SABS Reformulation Costs:South Africa's environmental release thresholds force imported chemistry re-registration cycles that delay market entry by 18-24 months.
Strategic Opportunities
- Nigeria's Performance Standards:Evolving national building codes in Lagos and Abuja are pivoting toward performance-based concrete specifications that favor certified admixture suppliers over commodity traders.
- Green Building Rating Alignment:The UAE Ministry of Climate Change and Environment applies embodied carbon verification to public project specifications, creating preference for low-carbon admixture formulations.
- Rail Network Foundations:Morocco-to-Oman rail corridors require mass concrete placements with extended workability windows, opening demand for retarding superplasticizer blends.
Industry Challenges
- Hot-Climate Placement Expertise:Gulf contractors face severe slump loss in 45°C ambient conditions, requiring specialized dosing protocols that strain site-level technical capacity.
- Batch-Plant Centralization:Ready-mix concrete consolidation across urban corridors demands real-time admixture inventory management systems that legacy producers struggle to deploy.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East and Africa Concrete Admixtures Market |
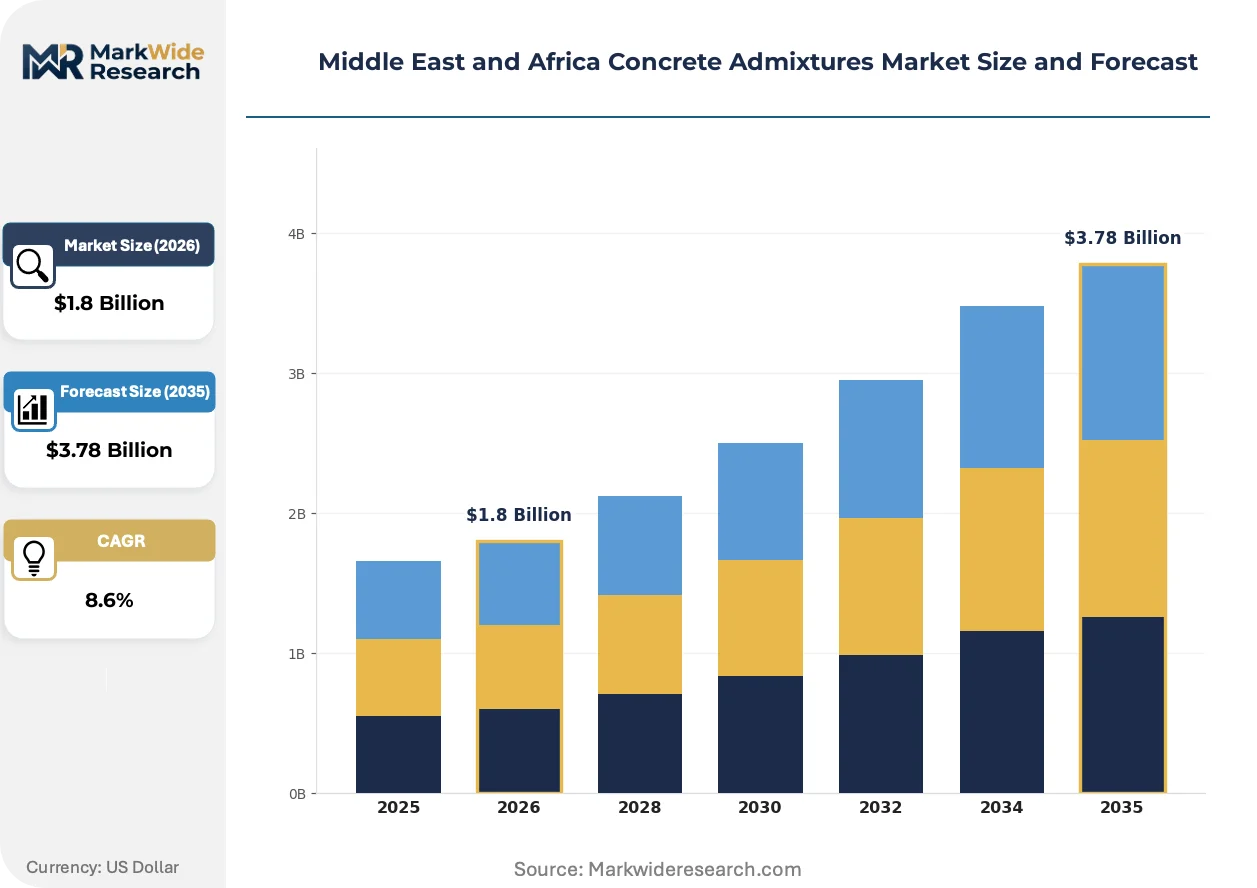
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.78 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Superplasticizers, Fly Ash, Water Reducing Admixtures, Air-Entraining Agents Application: Residential Construction, Commercial Construction, Infrastructure Development, Precast Concrete End User: Contractors, Builders, Architects, Engineers Delivery Mode: Ready-Mix Concrete, Site-Mixed Concrete, Packaged Admixtures, Bulk Admixtures |
| Companies Covered | Sika, Fosroc International, Ha-Be Middle East, Saint Gobain, Mapei, BASF SE, GCP Applied Technologies, RPM International Inc., CHRYSO Group, Others |
| Regions Covered | Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East and Africa Concrete Admixtures Market Shifts & Advancements
Formulation chemistry and procurement architecture are undergoing parallel transformation as climate-adapted admixtures displace conventional options and buyer concentration reshapes supplier relationships.
Polycarboxylate ether superplasticizers with tailored side-chain architectures are decentralizing the technical advantage of incumbent suppliers by enabling regional blenders to match high-performance specifications previously captive to multinational patent portfolios. Saudi and Emirati ready-mix leaders are adopting these chemistries for self-consolidating concrete in complex formwork. The technology is decentralizing specification authority from global R&D centers to localized technical service teams.
SASO and SABS are tightening environmental release thresholds for admixture chemistries, forcing reformulation of imported naphthalene and melamine-based products. Industrial consequence includes extended product registration timelines and accelerated phase-out of legacy formulations. Water-reducing admixtures face the steepest compliance burden, with suppliers pivoting toward bio-based raw material feedstocks to maintain market access.
Buyer concentration among Gulf mega-project contractors is compressing supplier negotiation cycles and unbundling technical service from material supply. EPC firms in the United Arab Emirates and Qatar now procure admixtures through centralized framework agreements that specify performance metrics rather than brand chemistry. This pattern is most visible in Dubai's sustained high-rise pipeline, where single-source technical partnerships are displacing multi-supplier spot purchasing.
Middle East and Africa Concrete Admixtures Market Segmentation
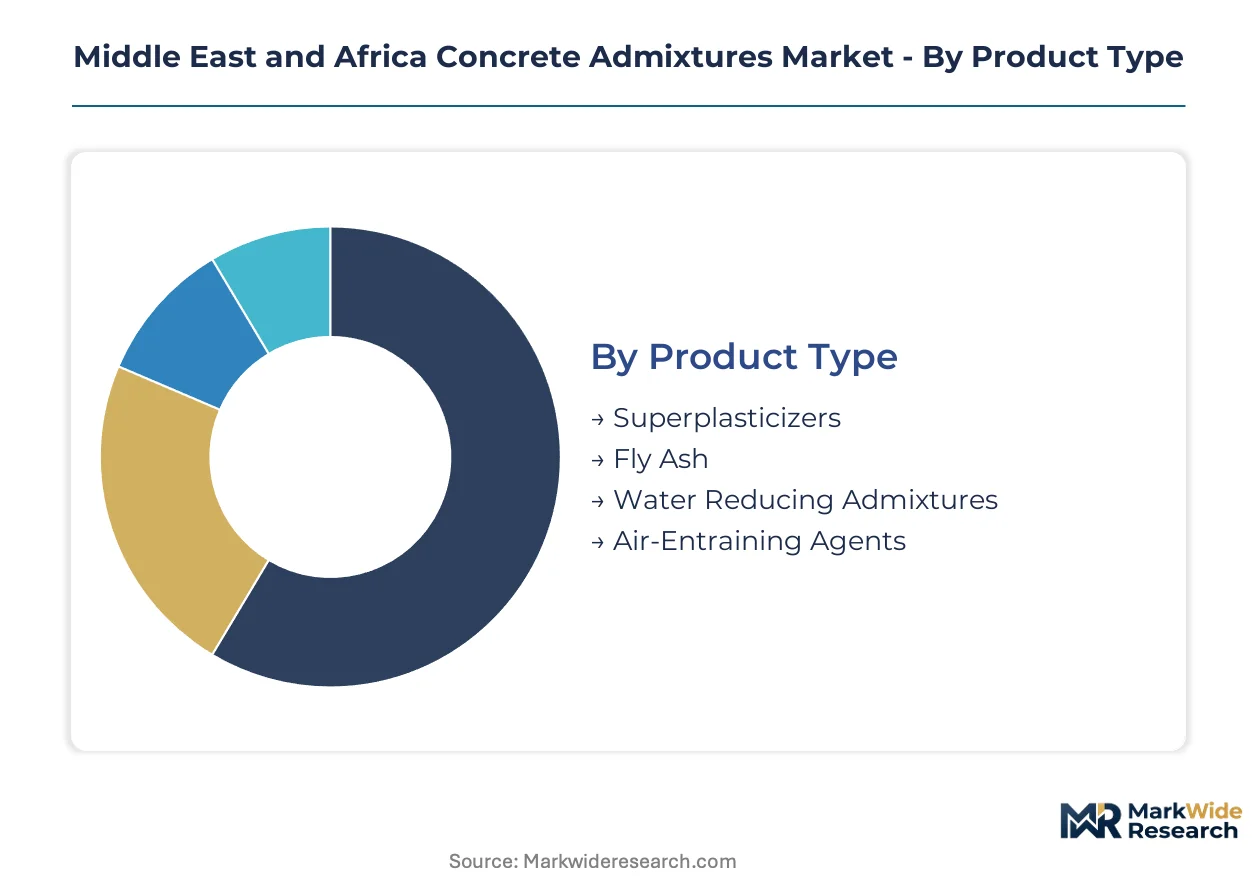
Segmentation in concrete admixtures reveals how technical specifications, project scale, and procurement methods reshape supplier relationships across Middle East and Africa construction corridors. Understanding these divisions exposes where formulation margins concentrate and where standardization pressures erode differentiation.
Product Type:
Customization intensity varies sharply across this category, with patented molecular architectures commanding premium positioning against commodity mineral extenders.
- Superplasticizers:Polycarboxylate ether and naphthalene-based chemistries enable water-cement ratios below 0.40 for high-strength concrete. Demand clusters in Dubai's vertical construction above 300 meters, where slump retention under pump pressure determines specification authority.
- Water Reducing Admixtures:Lignosulfonate and melamine formulations reduce mixing water by 5-12 percent without sacrificing workability. Procurement concentrates among Saudi ready-mix batch plants seeking SASO-compatible certifications for mega-project supply.
- Fly Ash:Pulverized fuel ash from coal combustion replaces 15-35 percent of cementitious content, lowering embodied carbon in South African green building projects.
- Air-Entraining Agents:Vinsol resin and synthetic surfactant formulations stabilize microscopic air bubbles for freeze-thaw durability in Morocco's Atlas Mountain infrastructure.
Most installed capacity flows through Water Reducing Admixtures. Expansion is steepest in Superplasticizers.
Application:
Project scale and specification complexity create divergent margin profiles, with billion-dollar infrastructure tenders rewarding integrated technical service while residential volume prizes logistics efficiency.
- Infrastructure Development:Rail networks, desalination plants, and renewable energy foundations demand mass concrete with extended workability windows. Oman-to-Morocco rail corridors require retarding superplasticizer blends for continuous pours exceeding 500 cubic meters.
- Commercial Construction:High-rise offices and retail complexes in Abu Dhabi and Lagos specify self-consolidating concrete for complex formwork geometries. Performance-based contracts now dominate procurement, filtering out uncertified commodity suppliers.
- Residential Construction:Mid-rise housing across Nairobi and Cairo employs standard water-reducing formulations with minimal technical support. Price sensitivity here compresses margins for regional blenders competing on delivery reliability.
- Precast Concrete:Factory-cast structural elements in Saudi Arabia's NEOM project require accelerated curing admixtures for production cycle efficiency.
Infrastructure Development absorbs the largest volume share. Commercial Construction is climbing the fastest as performance specifications tighten.
End User:
Technical decision-making authority fragments across project phases, with early-stage designers specifying performance criteria that contractors later source through consolidated procurement frameworks.
- Contractors:Gulf mega-project EPC firms now procure admixtures through centralized framework agreements specifying slump retention and compressive strength metrics rather than brand chemistry. Dubai's sustained high-rise pipeline exemplifies this shift toward single-source technical partnerships.
- Builders:Mid-scale residential developers across Kenya and Ethiopia rely on spot purchasing from distributors, exposing projects to currency-driven cost volatility and inconsistent quality.
- Architects:Green building rating alignment in the UAE drives specification of low-carbon admixture formulations with verified embodied carbon reductions.
- Engineers:Structural designers in South Africa enforce SABS-compliant compatibility testing between cement and admixture chemistries, extending registration timelines for imported products.
Contractors control the dominant procurement volume. Architects are gaining specification influence fastest through sustainability mandates.
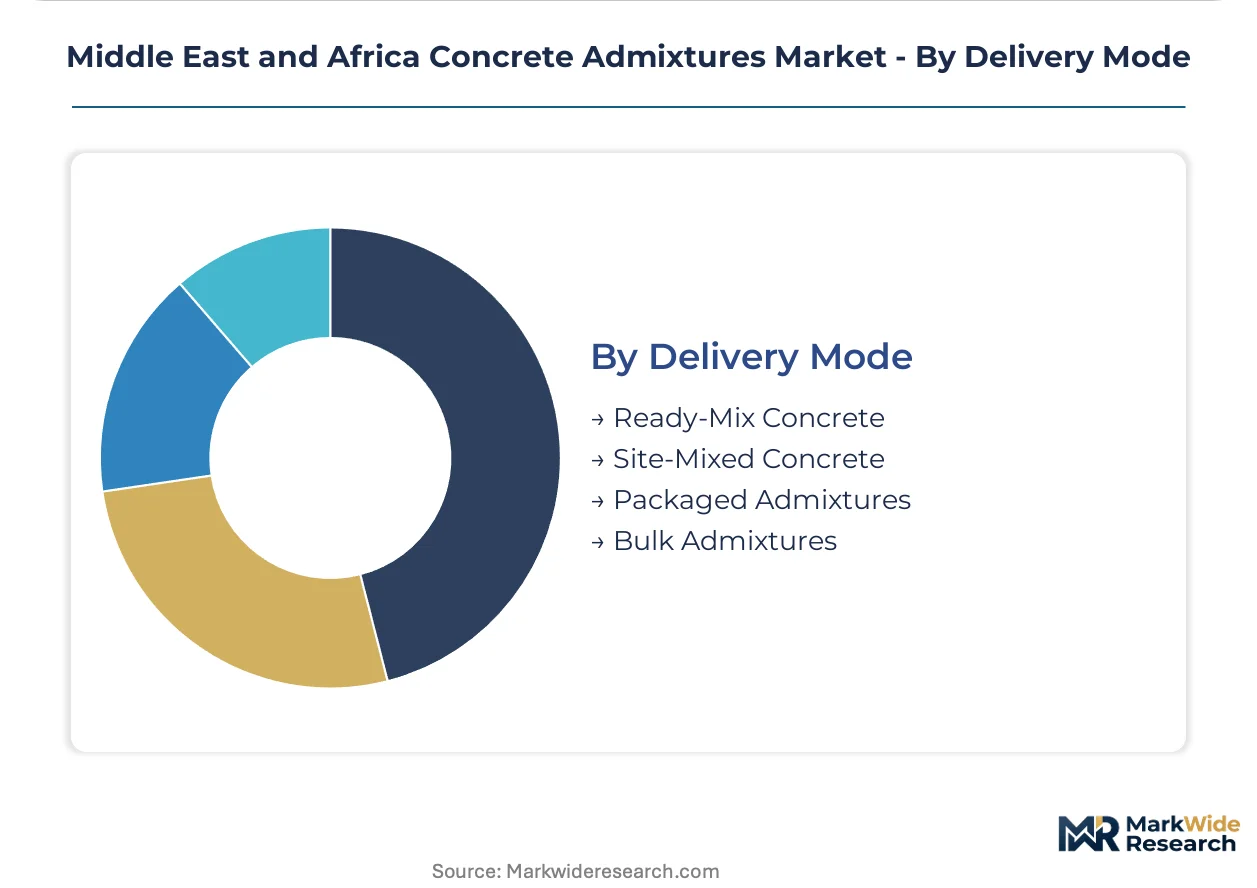
Delivery Mode:
Supply chain configuration separates centralized batch-plant economies from site-level flexibility, with urban density determining which model achieves cost parity.
- Ready-Mix Concrete:Batch-plant centralization across Gulf urban corridors demands real-time admixture inventory management systems. Sika and Fosroc secure bulk supply contracts through integrated technical service networks spanning Saudi Arabia and the UAE.
- Site-Mixed Concrete:Remote infrastructure projects in Oman and rural Nigeria retain on-site batching for logistics flexibility, though quality consistency suffers without automated dosing equipment.
- Bulk Admixtures:Tanker-delivered liquid formulations serve high-volume continuous pours, reducing packaging waste and per-liter logistics costs.
- Packaged Admixtures:20-liter containers and dry powder sachets address small-scale repairs and rural construction beyond ready-mix distribution networks.
Ready-Mix Concrete channels the majority of admixture volume. Bulk Admixtures are expanding most quickly as mega-project concentration accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping production footprints as formulators relocate blending capacity toward jurisdictions with streamlined environmental release protocols. Cost-of-compliance gaps between Gulf standardization frameworks and Sub-Saharan import regimes are accelerating regional manufacturing investment.
United Arab Emirates
Dubai's sustained vertical construction pipeline above 300 meters generates dedicated demand for slump-retention superplasticizers under high-pressure pumping conditions. The Ministry of Climate Change and Environment enforces green building rating alignment on public project specifications, filtering admixture selection toward verified low-carbon formulations. Abu Dhabi's batch-plant corridors concentrate procurement through centralized framework agreements that specify performance metrics over brand chemistry.
Saudi Arabia
NEOM and Red Sea Project mega-developments require mass concrete placements with extended workability windows for continuous desert pours. SASO mandates cement-admixture compatibility testing that extends registration timelines for imported chemistries while privileging pre-registered technical suppliers. The Eastern Province industrial cluster anchors localized polycarboxylate ether production, reducing import dependency for water-reducing formulations.
South Africa
Green building code tightening in Johannesburg and Cape Town pushes formulators toward bio-based raw material feedstocks for embodied carbon reduction. SABS enforces environmental release thresholds that force 18-24 month re-registration cycles on imported naphthalene and melamine-based products. The Gauteng urban corridor concentrates ready-mix batch-plant centralization, demanding real-time admixture inventory management systems.
Nigeria
Lagos and Abuja infrastructure expansion is pivoting toward performance-based concrete specifications that favor certified admixture suppliers over commodity traders. The country's national standards body is adopting compatibility testing frameworks modeled on Gulf precedents, extending product registration requirements. Port Harcourt's coastal concrete specifications for chlorides resistance accelerate procurement of corrosion-inhibiting formulations.
Egypt
New administrative capital construction and Suez Canal economic zone development require specialized superplasticizers for high-temperature placement conditions. The country's central building authority is evolving national concrete standards toward performance-based specifications that privilege technical-grade suppliers. Cairo-Alexandria urban corridor batch-plant consolidation is displacing site-mixed practices, centralizing admixture procurement decisions.
Middle East and Africa Concrete Admixtures Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue regional blending partnerships to bypass extended import registration timelines. Market structure concentrates specification authority around integrated formulators with localized manufacturing footprints, compressing margins for commodity traders without technical service capabilities. Three archetypes dominate: multinational chemical conglomerates with patent-protected molecular architectures, regional blenders with SASO/SABS pre-registration advantages, and construction-material specialists backward-integrating into admixture supply. Competitive moves center on capacity localization in Saudi Arabia and South Africa, plus strategic partnerships with Gulf mega-project EPC firms for bulk supply contracts.
Among Swiss-anchored chemical specialists, Sika represents the integrated-formulator archetype with Gulf supply chain integration. Fosroc International exemplifies the regional-manufacturing model through localized production in Saudi Arabia and South Africa. BASF SE occupies a position emphasizing R&D intensity and patent coverage in climate-adapted superplasticizer chemistries.
| Leading Market Players |
|---|
| Sika |
| Fosroc International |
| Ha-Be Middle East |
| Saint Gobain |
| Mapei |
| BASF SE |
| GCP Applied Technologies |
| RPM International Inc. |
| CHRYSO Group |
| Others |
Supply & Pricing Matrix
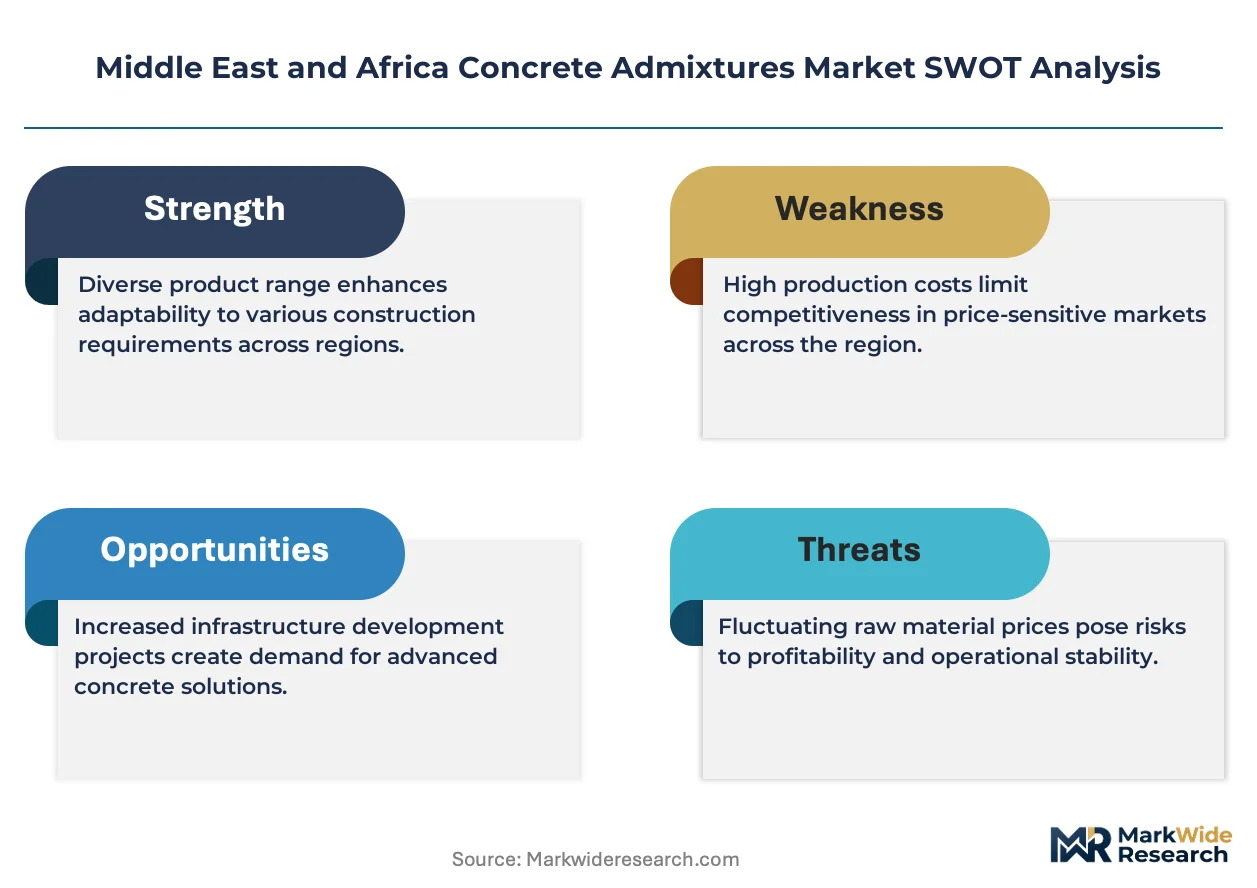
Naphthalene and polycarboxylate ether feedstock costs cascade through three distinct pricing tiers for Gulf mega-project contractors, South African ready-mix batch plants, and East African spot buyers. Petrochemical derivative volatility compresses margins for regional blenders without backward integration into raw material supply.
Pricing Analysis
Input-cost pass-through from naphthalene and melamine derivatives shapes a contract-based long-term offtake model for Saudi and Emirati mega-projects, while spot purchasing dominates East African procurement. Price differentiation hinges on SASO/SABS certification tier and volume scale, with certified technical-grade formulations commanding premiums over commodity imports. Pricing pressure stems from currency-driven cost spikes in Kenya and Ethiopia, where polycarboxylate ether import dependency exposes contractors to exchange volatility. Gulf EPC firms show least price sensitivity due to centralized framework agreements, while Nairobi and Cairo residential developers remain most exposed to margin compression.
Supply Chain Analysis
SASO domestic-content mandates and SABS environmental release thresholds are reshaping sourcing toward Saudi Arabia, South Africa, and the United Arab Emirates as preferred blending jurisdictions. Raw material supply draws from petrochemical feedstocks, bio-based alternatives, and imported polycarboxylate ether monomers. Single-source vulnerability concentrates in East Africa's absence of domestic superplasticizer production. Distribution runs through integrated technical service networks for ready-mix batch plants, with packaged admixtures reaching remote site-mixed operations beyond bulk tanker range.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in concrete admixtures rests on the shift from commodity spot purchasing to performance-based framework agreements, amplified by localized production reducing import dependency costs.
For Market Incumbents: Hedge against naphthalene feedstock volatility through backward integration into bio-based raw material feedstocks or captive supply of polycarboxylate ether monomers. Anchor capacity expansion in Saudi Arabia's Eastern Province industrial cluster to exploit SASO pre-registration advantages against emerging regional blenders. Certification investment in SABS-compliant environmental release protocols defends position against delayed import re-registration cycles. For New Entrants and Emerging Players: Enter via Nigeria's pivot toward performance-based concrete specifications in Lagos and Abuja infrastructure corridors, where certified supplier scarcity creates white-space opportunity. Target Kenya and Ethiopia's import-dependent polycarboxylate ether gap through technical partnerships with Gulf manufacturers seeking East African distribution. A go-to-market angle centered on automated dosing equipment and real-time inventory management addresses batch-plant centralization demand. For Investors and Strategic Acquirers: Consolidation pressure builds where SASO and SABS compliance burdens extend product registration timelines beyond 18 months, stranding capital for uncertified traders. Long-term viability favors regional blenders with pre-registered technical portfolios and integrated Gulf supply chain footprints. Acquisition target archetype: mid-scale formulators with localized Saudi or South African manufacturing and existing mega-project EPC relationships. The signal to watch is accelerating framework agreement concentration among Dubai and Riyadh contractors.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Localized polycarboxylate ether production in Saudi Arabia's Eastern Province reduces import dependency for water-reducing formulations. |
| Backward Integration | Captive supply of bio-based raw material feedstocks hedges against naphthalene petrochemical derivative volatility. |
| Long-term Supply Agreement | Centralized framework agreements with UAE and Qatar EPC firms lock in bulk volumes for mega-project concrete supply. |
| Green Manufacturing Transition | Low-carbon admixture formulations align with UAE Ministry of Climate Change green building rating requirements. |
| Joint Venture | Technical partnerships between Gulf multinationals and East African distributors bridge Kenya and Ethiopia's polycarboxylate ether production gap. |
Research Methodology
Bottom-up ready-mix and infrastructure project modeling reconciled against top-down admixture production and trade flow tracking forms the analytical core of this study. Primary interviews with Gulf EPC procurement directors, Saudi batch-plant technical managers, South African green building specifiers, and Nigerian regulatory affairs leads combined with secondary validation from SASO certification databases, SABS environmental release filings, customs and trade data, and chemical industry association reports. Triangulation across these sources anchors volume and value estimates.
Input-output matrices mapping naphthalene and polycarboxylate ether feedstock availability through regional blending capacity to end-use consumption by project type drive the forecast framework. Segmentation dimensions span product type chemistry, application scale from residential to mega-infrastructure, delivery mode concentration, and country-level regulatory cluster. CAGRs derive from projected cement consumption intensity, green building code adoption curves, and infrastructure investment pipelines across the analysis window. Industry-specific inputs include slump-retention performance requirements for Dubai vertical construction and chloride resistance specifications for coastal desalination infrastructure.
Inputs from primary stakeholder interviews and published regulatory filings were available through the study window; gaps in real-time contractor procurement data and unreported spot pricing in East African markets introduce uncertainty bands around volume estimates. Forecasts reflect assumptions regarding SASO and SABS enforcement continuity, petrochemical feedstock cost trajectories, and Gulf mega-project execution schedules. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Precast Concrete Retaining Walls Market
Building Materials
Brick Adhesive Market
Building Materials
Europe Concrete Admixtures Market
Building Materials
Dry Mix Mortar Market
Building Materials
Global Fiber Cement Siding Market
Building Materials
Self-Healing Construction Materials Market
Building Materials
Fiber Reinforced Concrete Market
Building Materials
Fire Resistant Mortar Market
Building Materials
Aluminum Door and Window Market
Building Materials
Bolt (Fastener) Market
Building Materials
United States White Cement Market
Building Materials
Cement Tiles Market
Building Materials
Spain Architectural Coatings Market
Building Materials
US Facade Market
Building Materials
Composite Rebar Market
Building Materials
Mass Timber Construction Market