
 Africa Green Cement Market | 2026-2036
Africa Green Cement Market Size, Share, and Industry Trends Forecast 2026-2036
Africa Green Cement Market Intelligence
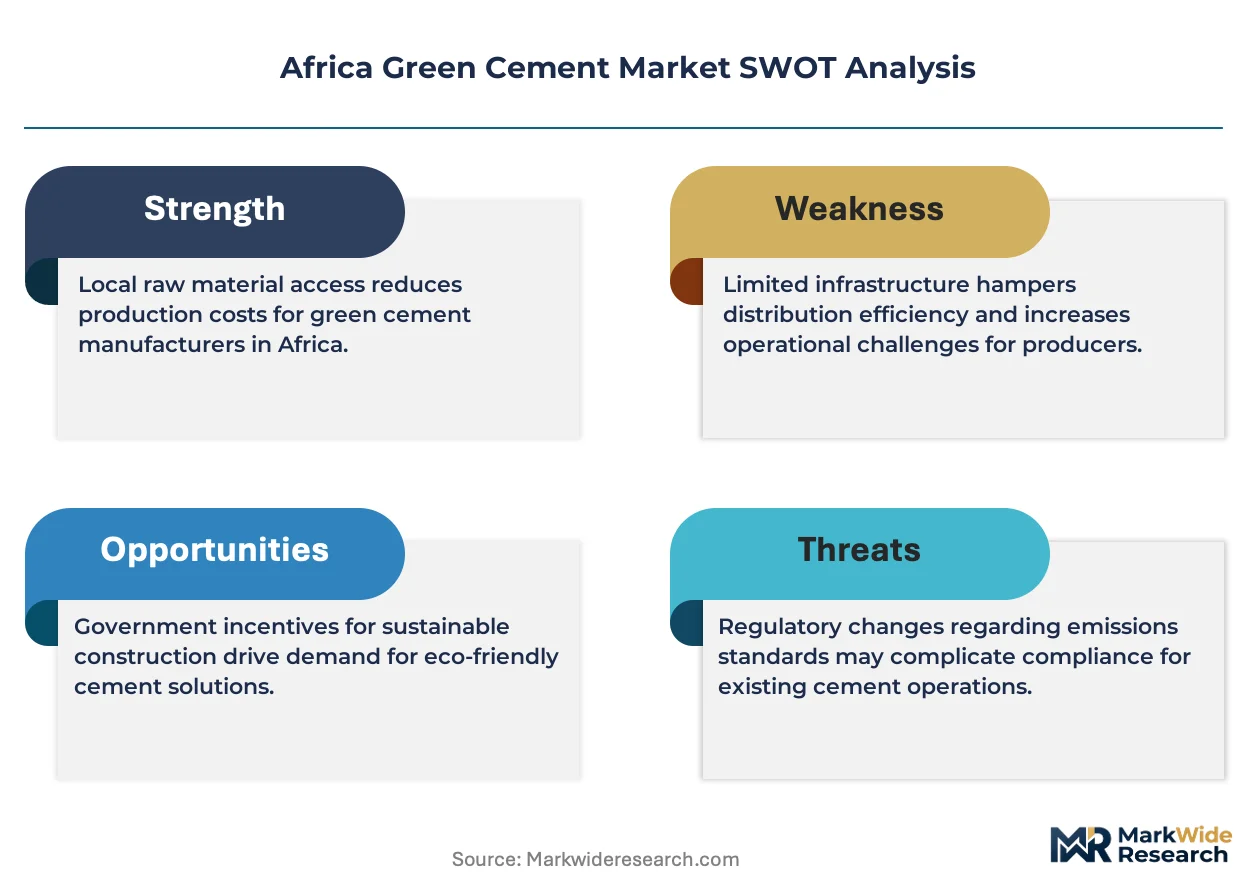
The capital-intensity divergence between integrated multinationals and regional producers is collapsing as carbon-capture retrofits and alternative fuel infrastructure become table stakes for large-scale contracts. Holcim leverages its global decarbonization playbook to anchor premium blended cement supply across North and West African markets. PPC Ltd. sustains vertical integration into limestone reserves and fly-ash sourcing networks that shield margin structures from energy price volatility. Sephaku Cement specializes in dry-process technology leadership, positioning its product line for government tenders with strict emissions thresholds.
Green cement denotes hydraulic binding materials manufactured with reduced clinker content, incorporating supplementary cementitious materials such as fly ash, slag, or calcined clays, and produced via energy-efficient kilns or carbon-capture systems to achieve lower embodied carbon than conventional Ordinary Portland Cement. The primary commercial purpose is to meet structural performance requirements in concrete construction while complying with tightening environmental benchmarks. Blended Cement and Fly Ash Cement currently occupy the deepest margin pools as procurement officers in government projects prioritize cost-competitive low-carbon specifications. Carbon Capture technology leads investment visibility among technology segments, though Energy-efficient Manufacturing dominates installed capacity due to faster payback periods on kiln retrofits.
South Africa's Department of Forestry, Fisheries and the Environment enforces carbon budgeting mechanisms that directly elevate the cost of high-clinker production, while Nigeria's Federal Ministry of Environment coordinates with the Standards Organisation of Nigeria to embed emissions thresholds in public infrastructure contracts. Kenya's National Environment Management Authority is tightening environmental impact assessments for cement plant expansions, channeling investment toward alternative fuel use and waste-heat recovery systems. Stakeholders must monitor how rapidly national regulators harmonize local standards with ISO 14064 carbon accounting protocols to avoid fragmentation in cross-border project financing.
Market Dynamics
Carbon intensity benchmarks enforced by South Africa's Department of Forestry, Fisheries and the Environment are compressing clinker ratios across domestic production, forcing integrated producers to reconfigure kiln operations around alternative fuel streams and calcined clay blends.
Growth Catalysts
- Public Infrastructure Procurement:Federal housing programs in Nigeria are embedding emissions thresholds into concrete specifications for government contractors, channeling volume toward blended cement formulations.
- Kenya's NEMA Directives:The National Environment Management Authority is tightening environmental impact assessments for cement plant expansions, accelerating investment in waste-heat recovery systems.
- Calcined Clay Activation:LC3 (Limestone Calcined Clay Cement) technology is gaining regulatory approval across multiple African jurisdictions as a drop-in clinker substitute with lower embodied carbon.
Market Restraints
- Fly Ash Supply Concentration:Dependence on coal-fired power generation in South Africa and Zimbabwe creates geographic concentration risk for SCM sourcing as utilities decommission aging plants.
- Alternative Fuel Infrastructure Costs:Waste-derived fuel preprocessing and storage systems require capital deployment that regional producers cannot access at commercial lending rates.
- Clinker Import Dependence:Coastal markets in West Africa rely on seaborne clinker from Turkey and Vietnam, exposing margin structures to freight rate volatility and currency fluctuation.
Strategic Opportunities
- East African Infrastructure Corridor:Kenya, Tanzania, and Ethiopia are accelerating dam, road, and rail construction with blended cement mandates in tender documents.
- Carbon Credit Monetization:South Africa's carbon tax framework allows verified emission reductions to generate tradeable offsets, creating a revenue stream for low-carbon producers.
- Waste Co-processing Partnerships:Municipal solid waste and agricultural residue supply agreements with cement plants are unlocking feedstock diversification in Nigeria and Ghana.
Industry Challenges
- Technical Skills Gap:Kiln operation and alternative fuel handling require specialized engineering expertise that training institutions in Zambia and Tanzania have not scaled to meet.
- Certification Timeline Compression:ISO 14064 carbon accounting protocol verification cycles of 12-18 months delay contract eligibility for new market entrants.
- Legacy Asset Stranding:Wet-process kilns in older Egyptian and Moroccan facilities face prohibitive retrofit economics under tightening emissions standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa Green Cement Market |
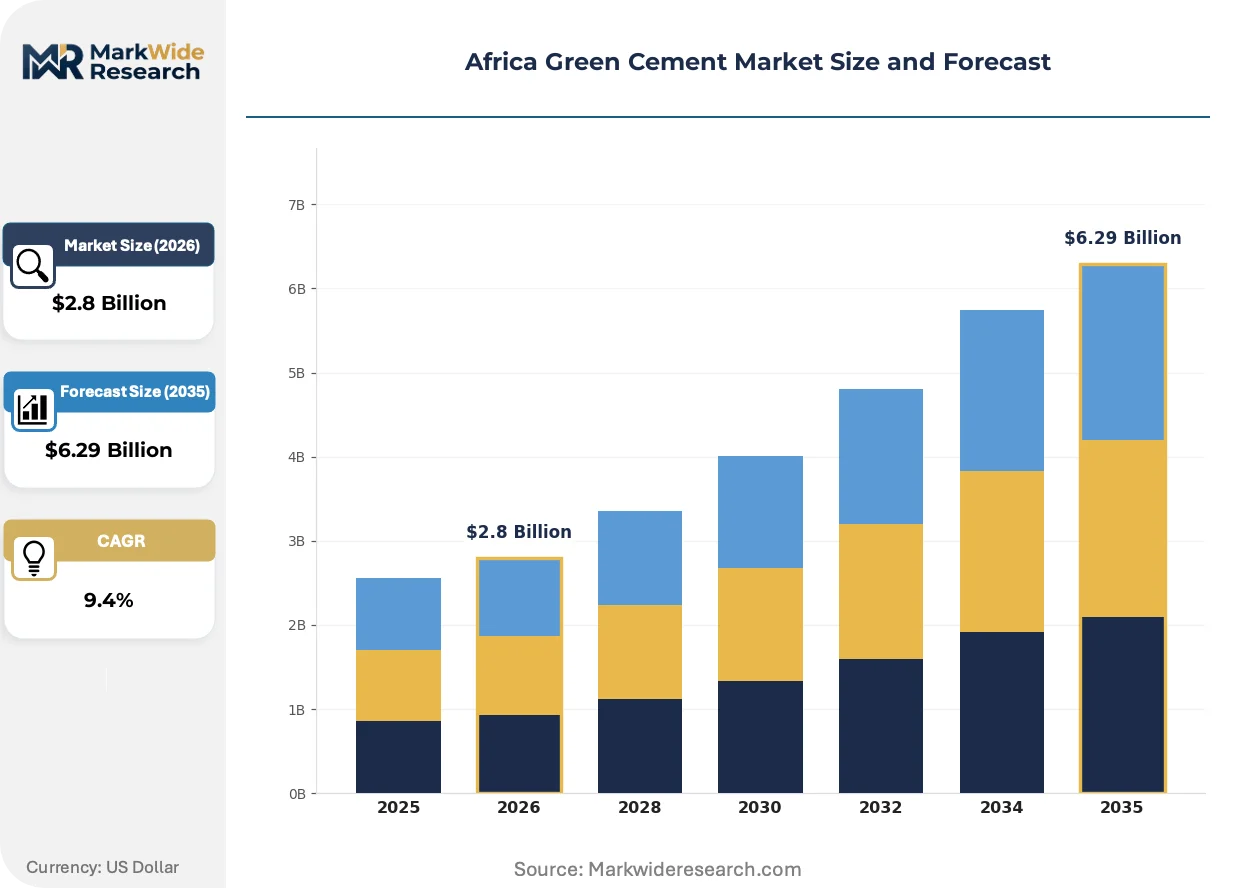
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $6.29 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ordinary Portland Cement, Blended Cement, Fly Ash Cement, Recycled Aggregate Cement Application: Residential Construction, Commercial Construction, Infrastructure Development, Precast Concrete Products Technology: Carbon Capture, Energy-efficient Manufacturing, Alternative Fuel Use, Dry Process Technology End User: Construction Companies, Government Projects, Private Developers, Manufacturing Firms |
| Companies Covered | Holcim, Heidelberg Materials, PPC Ltd., Afrisam, Dangote Cement, East African Portland Cement PLC, CEMEX, Lafarge Africa, Sephaku Cement, Others |
| Regions Covered | Africa: South Africa, Nigeria, Egypt, Kenya, Morocco, Ethiopia, Ghana, Algeria, Rest of Africa |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa Green Cement Market Strategic Shifts & Innovations
Technology convergence between carbon capture systems and alternative fuel co-processing is redefining capital allocation priorities for integrated producers across the continent.
Calcined clay activation is supplanting conventional fly ash as the dominant supplementary cementitious material in government tender specifications. Kenyan and Ethiopian procurement officers now prioritize LC3-compliant bids for hydropower and transport infrastructure. This shift is compressing demand for imported coal combustion residuals while elevating domestic kaolin and bentonite extraction.
South Africa's carbon budgeting mechanisms now mandate sectoral emission ceilings that directly elevate production costs for high-clinker Ordinary Portland Cement. Domestic producers are responding by accelerating kiln retrofits and securing long-term biomass supply contracts. The policy pressure is most acute in the commercial ready-mix segment, where contractors face margin compression from both input costs and client sustainability requirements.
Aggregated procurement platforms are consolidating demand from multiple government agencies into single-tender frameworks with standardized low-carbon specifications. Nigeria's Federal Ministry of Environment coordinates these consolidated purchases, displacing fragmented municipal contracting. This concentration is visible most prominently in Lagos and Abuja metropolitan housing developments, where Dangote Cement and regional competitors now compete on verified carbon intensity scores rather than unit pricing alone.
Africa Green Cement Market Segmentation
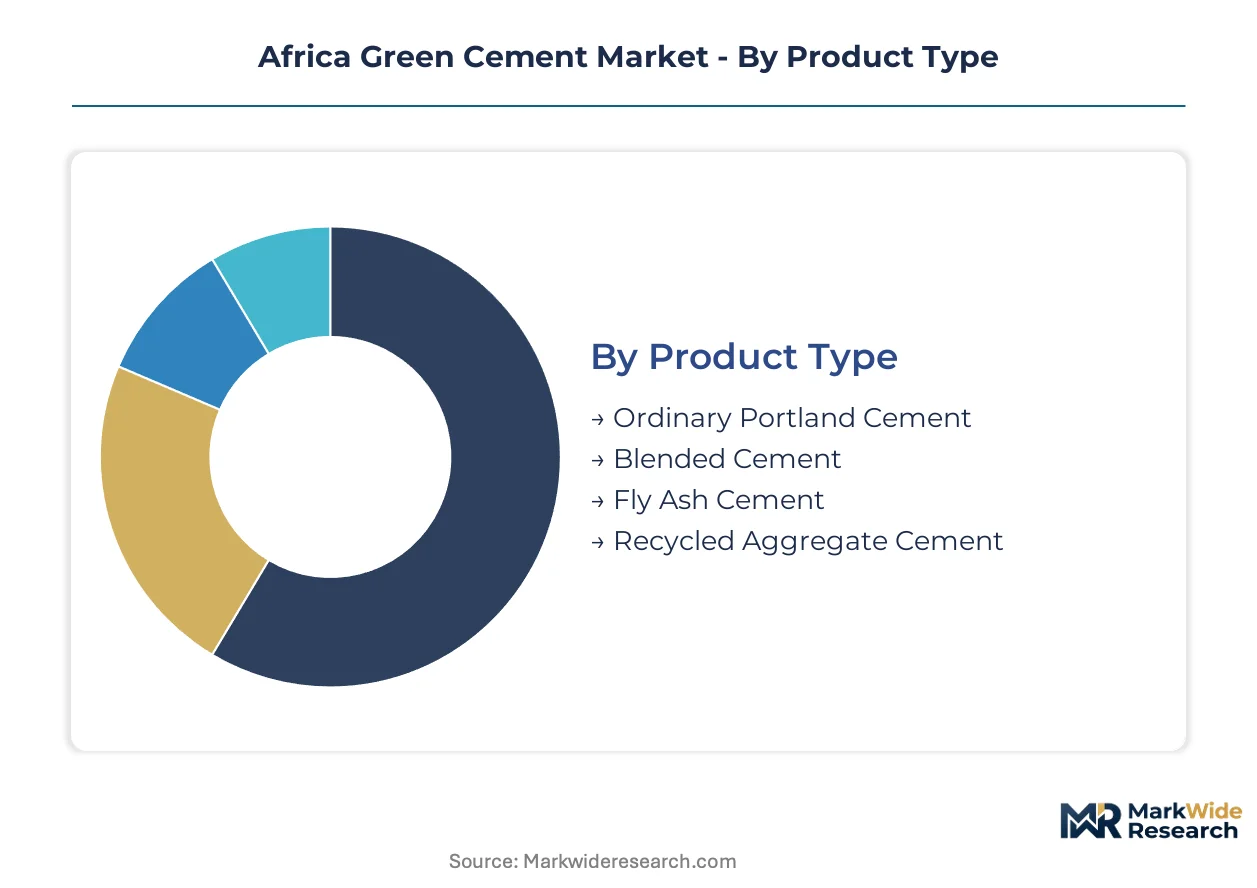
Segmentation reveals how procurement mandates and technology maturity split the Africa Green Cement Market into distinct competitive arenas. Product formulations, application requirements, and manufacturing technologies each face divergent substitution pressures from conventional cement and alternative building materials.
Product Type:
Blended Cement faces the strongest substitution threat as calcined clay and geopolymers gain regulatory approval across East and West African jurisdictions.
- Blended Cement:Formulations combining Portland clinker with supplementary cementitious materials such as fly ash, slag, or calcined clays achieve embodied carbon reductions. Nigerian federal housing programs and Kenyan hydropower tenders now embed blended cement specifications as mandatory bid criteria.
- Fly Ash Cement:Coal combustion residuals replace 15-35% of clinker content, delivering cost-competitive strength performance. South African procurement officers prioritize this formulation for commercial ready-mix contracts, though utility decommissioning threatens feedstock security.
- Ordinary Portland Cement:Conventional high-clinker formulation now carries carbon tax penalties under South Africa's environmental budgeting mechanisms.
- Recycled Aggregate Cement:Construction and demolition waste substitutes virgin limestone in select non-structural applications.
Blended Cement retains volume leadership; Fly Ash Cement holds the steepest expansion curve.
Application:
Cost tier stratification separates premium-specification infrastructure from price-sensitive residential builds.
- Infrastructure Development:Dams, rail corridors, and port facilities demand LC3-compliant formulations with verified carbon intensity scores. Ethiopian and Tanzanian government tender documents now exclude high-clinker bids from eligibility pools.
- Residential Construction:Mass housing programs in Lagos and Abuja metropolitan zones drive procurement volume toward cost-optimized blended formulations with 20-30% clinker reduction.
- Commercial Construction:Office and retail developments in Johannesburg and Cape Town face client sustainability requirements that elevate low-carbon specifications.
- Precast Concrete Products:Standardized manufacturing enables consistent quality control for emissions-verified structural elements.
Infrastructure Development commands the highest specification premiums; Residential Construction generates the deepest procurement volume.
Technology:
Supply concentration around kiln retrofit capabilities favors integrated producers with captive capital access.
- Energy-efficient Manufacturing:Waste-heat recovery systems and optimized kiln thermodynamics dominate installed capacity across Egyptian and Moroccan facilities due to faster payback periods.
- Alternative Fuel Use:Municipal solid waste and agricultural residue co-processing reduces fossil fuel dependence. Nigerian cement plants secure long-term supply agreements with waste management authorities in Lagos and Kano.
- Carbon Capture:Post-combustion absorption and oxyfuel systems attract investment visibility despite capital intensity constraints.
- Dry Process Technology:Sephaku Cement anchors its competitive positioning on this kiln configuration for government tenders with strict emissions thresholds.
Energy-efficient Manufacturing dominates current capacity; Alternative Fuel Use is climbing the fastest.
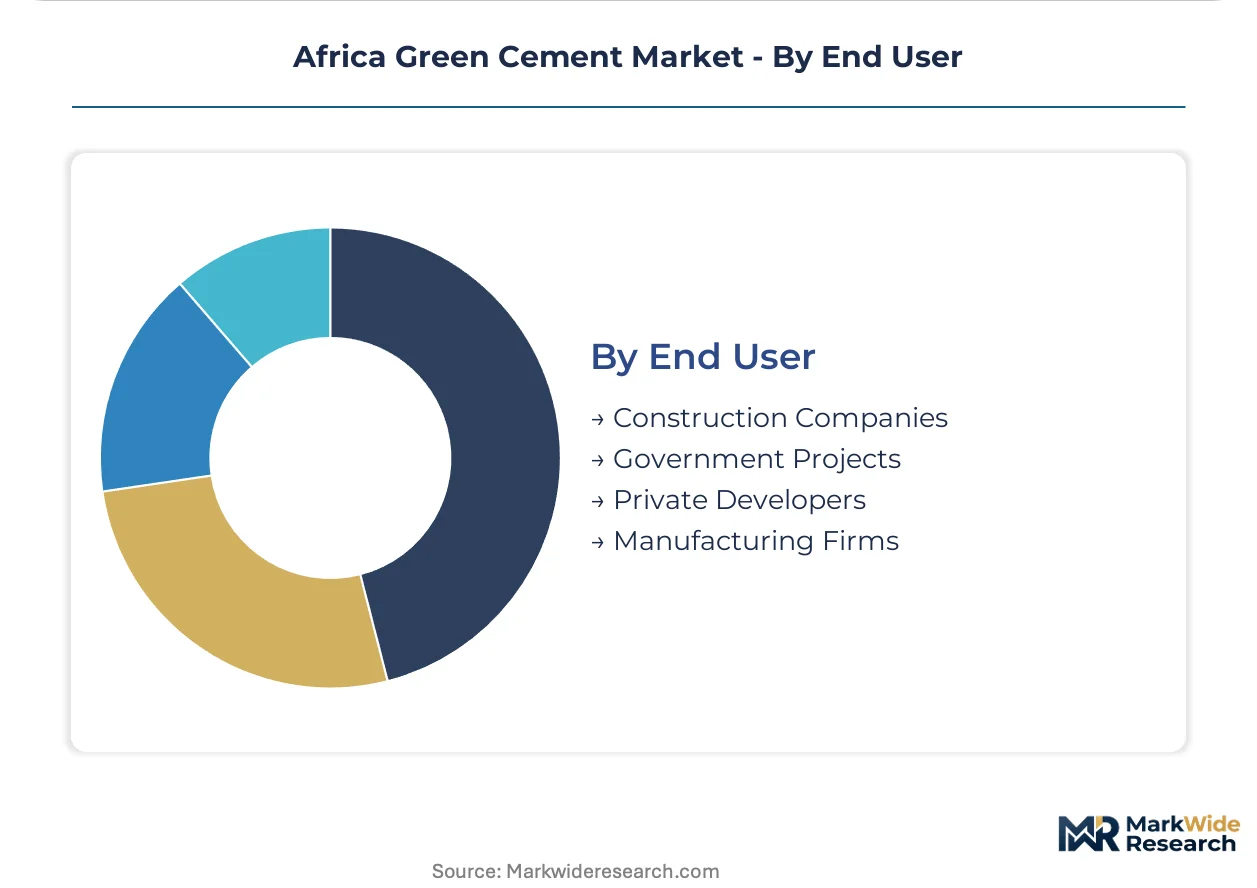
End User:
Customer type determines specification stringency and contract duration structures.
- Government Projects:Aggregated procurement platforms in Nigeria and Kenya consolidate demand from multiple agencies into single-tender frameworks with standardized low-carbon requirements. Verification cycles of 12-18 months for ISO 14064 carbon accounting protocols delay contract eligibility for new entrants.
- Construction Companies:Commercial ready-mix contractors face margin compression from both input cost volatility and client sustainability mandates in South Africa's major metropolitan markets.
- Private Developers:Lagos and Abuja metropolitan housing developments increasingly compete on verified carbon intensity scores rather than unit pricing alone.
- Manufacturing Firms:Industrial facility construction generates steady demand for precast concrete products with consistent quality specifications.
Government Projects anchor procurement volume; Construction Companies are expanding specifications fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across African markets. South Africa prioritizes carbon-compliant formulations for commercial construction, while Nigeria and Kenya drive volume through federal housing programs and infrastructure corridors that mandate blended cement specifications.
South Africa
Johannesburg and Cape Town metropolitan developments anchor demand for low-carbon ready-mix concrete. The Department of Forestry, Fisheries and the Environment enforces carbon budgeting mechanisms that elevate production costs for high-clinker formulations. Durban-Gqeberha industrial corridors concentrate alternative fuel preprocessing infrastructure for waste-derived kiln feeds.
Nigeria
Federal housing programs in Lagos and Abuja generate procurement volume for cost-optimized blended cement with 20-30% clinker reduction. The Federal Ministry of Environment coordinates with the Standards Organisation of Nigeria to embed emissions thresholds in public infrastructure contracts. Dangote Cement's captive limestone reserves and waste-to-energy partnerships reshape supply specifications in the Niger Delta production cluster.
Kenya
Hydropower and transport infrastructure tenders in Nairobi and Mombasa now exclude high-clinker bids from eligibility pools. The National Environment Management Authority tightens environmental impact assessments for cement plant expansions. The Athi River industrial zone concentrates dry-process kiln capacity serving government contractors with strict emissions thresholds.
Ethiopia
Dam and rail construction programs in Addis Ababa and the Oromia region accelerate procurement of LC3-compliant formulations. The Ethiopian Environmental Protection Authority channels investment toward calcined clay activation technology. The Dire Dawa-Djibouti corridor anchors blended cement distribution for cross-border infrastructure financing.
Egypt
Legacy wet-process kilns in Cairo-Alexandria industrial zones face prohibitive retrofit economics under tightening emissions standards. The Egyptian Environmental Affairs Agency accelerates permitting for waste-heat recovery systems in new capacity additions. Suez Canal Economic Zone projects test carbon-capture integration for export-oriented production.
Africa Green Cement Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier in the Africa Green Cement Market. Multinational producers with global decarbonization playbooks anchor premium supply across North and West African markets, while regional champions sustain vertical integration into limestone reserves and supplementary cementitious material sourcing networks. Three archetypes dominate: integrated multinationals deploying carbon-capture retrofits, regional producers with captive raw material access, and dry-process technology specialists targeting government tenders. Competitive moves concentrate on strategic partnerships for alternative fuel supply and portfolio diversification into calcined clay blends.
Within the integrated multinational tier, Holcim and Heidelberg Materials occupy positions exemplifying global decarbonization infrastructure deployment across African markets. Among regional champions, PPC Ltd. and Dangote Cement represent archetypes of backward integration into captive limestone and energy feedstock control. Sephaku Cement anchors the technology-specialist vector with dry-process kiln positioning for emissions-intensive tender environments.
| Leading Market Players |
|---|
| Holcim |
| Heidelberg Materials |
| PPC Ltd. |
| Afrisam |
| Dangote Cement |
| East African Portland Cement PLC |
| CEMEX |
| Lafarge Africa |
| Sephaku Cement |
| Others |
Cost & Logistics Intelligence
ISO 14064 carbon accounting protocol verification gates both supplier qualification and price differentiation in African green cement procurement, compressing contract eligibility timelines while elevating premiums for verified low-carbon formulations in government tenders.
Pricing Analysis
Long-term offtake agreements dominate procurement for integrated producers serving Nigerian federal housing and Kenyan hydropower corridors, while spot purchasing persists in South African commercial ready-mix where contractors face volatile input costs. Three-tier pricing structure across premium LC3-compliant, standard blended, and economy high-clinker formulations tracks certification grade and clinker reduction percentage. Pricing pressure stems from freight rate volatility on seaborne clinker imports to West African coastal markets. Government project officers show lowest price sensitivity due to mandated emissions thresholds, while informal residential builders in peri-urban zones resist premiums above conventional cement.
Supply Chain Analysis
Strategic stockpiling of calcined clay and fly ash characterizes procurement strategies among Nigerian and South African integrated producers, buffering against feedstock disruption from utility decommissioning and seasonal agricultural residue availability. Geographic supply concentration centers on Nigeria, South Africa, and Egypt for clinker production, with Vietnam and Turkey anchoring import flows to West African terminals. Raw material dependencies encompass limestone reserves, coal combustion residuals, and kaolin deposits for LC3 activation. Single-source vulnerability concentrates in fly ash procurement as South African power utilities retire aging coal plants. Distribution runs through bulk terminal networks at Lagos, Durban, and Mombasa serving government contractors and commercial ready-mix operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored in regulatory entrenchment: carbon intensity benchmarks and ISO 14064 verification requirements create switching costs that lock in qualified suppliers across multi-year infrastructure procurement cycles.
For Market Incumbents: Secure long-term biomass and calcined clay supply agreements before agricultural residue competition intensifies from emerging LC3 specialists. Defend market position by accelerating waste-heat recovery retrofits in Egyptian and Moroccan legacy assets threatened by tightening emissions standards. Prioritize certification investment to compress ISO 14064 verification timelines below the 12-month threshold for new tender eligibility. For New Entrants and Emerging Players: Anchor in Ethiopian dam construction and Tanzanian rail corridors where LC3-compliant specifications exclude high-clinker incumbents from bid pools. Target municipal solid waste co-processing partnerships in Lagos and Kano where Dangote Cement's alternative fuel infrastructure remains underdeveloped. Pursue go-to-market positioning as verified low-carbon specialists for aggregated procurement platforms consolidating Nigerian federal housing demand. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with stranded wet-process kiln assets in North Africa requiring capital-intensive retrofit. Long-term viability favors producers with captive limestone reserves and established alternative fuel preprocessing infrastructure. Watch for inflection when South Africa's carbon tax framework expands sectoral coverage beyond current commercial ready-mix thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| Calcined Clay Supply Integration | Backward integration into Kenyan kaolin deposits secures LC3 feedstock for Ethiopian hydropower tenders. |
| Waste-to-Energy Partnership | Municipal solid waste agreements with Lagos authorities reduce fossil fuel exposure in Niger Delta production. |
| Carbon Capture Retrofit | Post-combustion absorption installation qualifies Suez Canal Economic Zone output for EU import protocols. |
| ISO 14064 Fast-Track Certification | Compressed verification timelines unlock eligibility for Nigerian consolidated procurement platforms. |
| Dry-Process Kiln Conversion | Sephaku Cement's technology leadership positions capture South African government tenders with strict emissions ceilings. |
Research Approach
Initial hypotheses were tested against primary input from cement plant operations directors, government procurement officers at Nigeria's Federal Ministry of Environment, commercial ready-mix contractors in Johannesburg, and alternative fuel supply coordinators at Lagos waste management authorities, then refined through secondary validation against customs trade data, SEC filings from listed producers, Standards Organisation of Nigeria technical specifications, and South African Department of Forestry, Fisheries and the Environment regulatory notices. Bottom-up volume estimates from kiln capacity and clinker factor assumptions were triangulated against top-down procurement flow analysis from aggregated tender platforms.
Variance decomposition across the projection horizon isolates volume sensitivity to infrastructure spending commitments, carbon tax rate assumptions, and clinker import cost trajectories. Segmentation dimensions modeled encompass product formulation tier, application specification intensity, kiln technology configuration, and end-user procurement consolidation level. CAGRs were derived from regression against historical cement consumption elasticities and forward infrastructure pipeline assessments. Industry-specific forecast inputs include LC3 regulatory approval timelines and alternative fuel preprocessing capacity buildout schedules.
Decision-makers should treat outputs as directional under base assumptions of sustained carbon budgeting enforcement and stable clinker trade flows; material deviation in either factor would warrant model refresh. Revision becomes warranted when South African carbon tax coverage expansion or Nigerian federal housing program suspension crosses implementation thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Fiber Reinforced Polymer Composites (FRP) Market
Building Materials
Rapid Strength Concrete Market
Building Materials
Global Corrugated Steel Sheets Market
Building Materials
Cement Tiles Market
Building Materials
North America Dry-Mix Mortar Market
Building Materials
China Aluminum Door and Window Market
Building Materials
Global Pozzolan Market
Building Materials
Construction Materials Market
Building Materials
Commonwealth of Independent States (CIS) Building and Construction Sheets Market
Building Materials
Germany Architectural Coatings Market
Building Materials
Precast Concrete Retaining Walls Market
Building Materials
Construction Stone Market
Building Materials
Global Glass Fiber Reinforced Concrete Market
Building Materials
ASEAN Dry Mix Mortar Market
Building Materials
United States Architectural Coatings Market
Building Materials
Fiber Reinforced Polymer (FRP) Rebars Market