
 Solar Control Window Film Market | 2026-2036
Solar Control Window Film Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Control Window Film Market Analysis
Buyer concentration among large commercial real estate portfolios and national automotive fleet operators is repositioning procurement toward volume-contract suppliers with specification-grade certification. Eastman Chemical Company leverages its polyester supply chain and sputtering expertise to serve this consolidated channel. Saint-Gobain anchors European specification work through its building-science relationships and performance-guarantee programs. Johnson Window Films competes in the North American aftermarket through installer-network density and regional distribution control.
Solar control window film comprises multi-layer polymer laminates, typically polyethylene terephthalate substrates with metalized, dyed, or ceramic infrared-rejecting coatings, applied via adhesive bonding to glazing surfaces to reduce solar heat gain while preserving visible light transmission. Ceramic film segments command premium positioning due to non-conductive, signal-friendly properties suited to connected-vehicle and smart-building applications. Metallized film sustains volume leadership in commercial retrofits where thermal performance per dollar dominates selection criteria. Marine application represents a specialized growth pocket driven by superyacht refit cycles and salt-corrosion-resistant coating requirements.
The US Department of Energy's building energy codes and the EPA's Energy Star program shape product performance thresholds and rebate eligibility for residential and commercial installations. The EU F-Gas Regulation and REACH compliance frameworks restrict certain adhesive chemistries and drive reformulation toward lower-global-warming-potential alternatives. Stakeholders must monitor evolving state-level stretch codes in California, New York, and Massachusetts alongside emerging green building certification updates that redefine acceptable solar heat gain coefficients for retrofit eligibility.
Market Dynamics
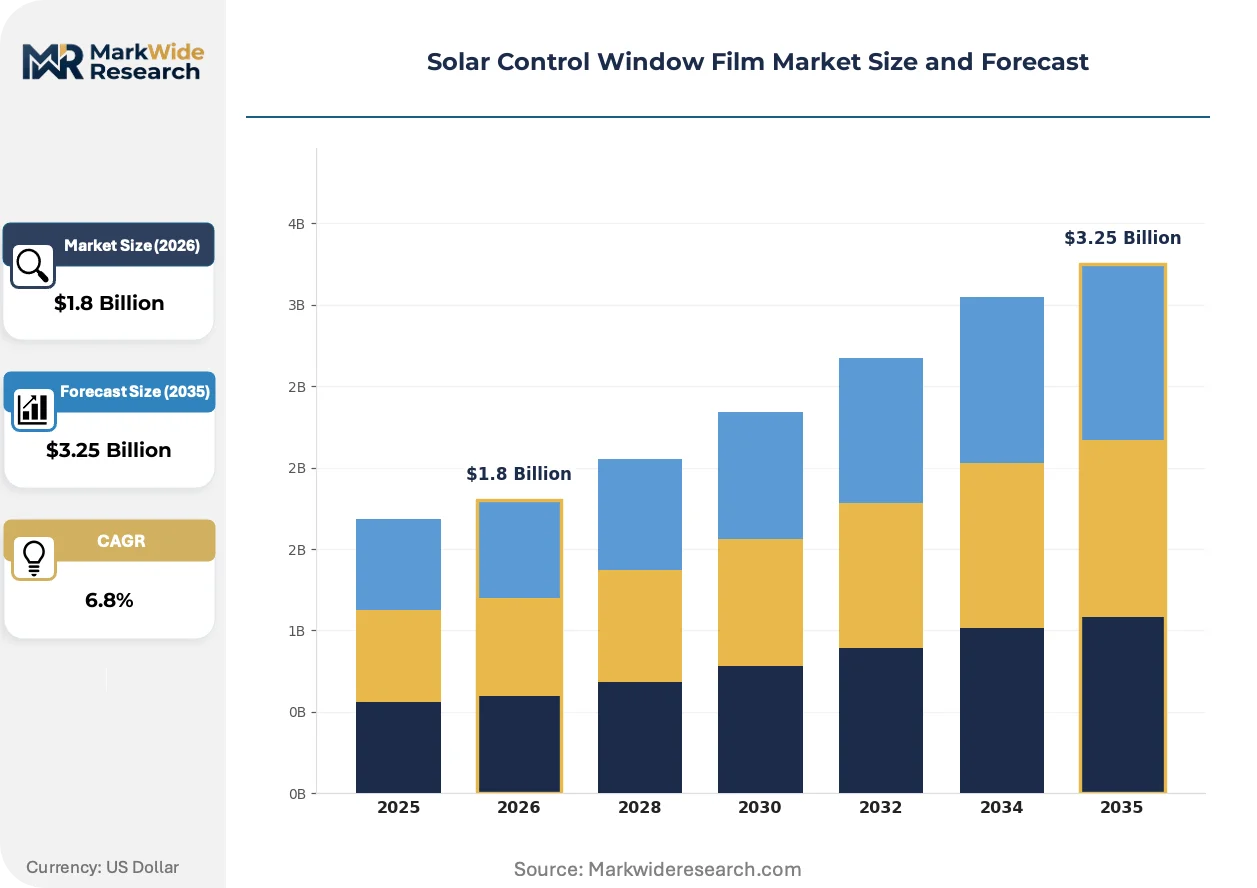
Utility rebate programs and green building certification incentives are consolidating procurement authority among large commercial real estate portfolios, forcing film suppliers to restructure around volume-contract specifications and performance-guarantee frameworks rather than discrete project sales.
Growth Catalysts
- California Title 24 energy codes:Mandatory solar heat gain coefficient thresholds for commercial retrofits are specifying ceramic and metallized films as compliance pathways, accelerating replacement cycles across aging building stock.
- Automotive fleet electrification:Connected-vehicle architectures demand signal-friendly ceramic films for cabin thermal management without disrupting 5G, GPS, or keyless entry systems.
- Superyacht refit clusters:Salt-corrosion-resistant coating specifications in Mediterranean and Caribbean shipyards are creating specialized demand for marine-grade solar control laminates.
Market Restraints
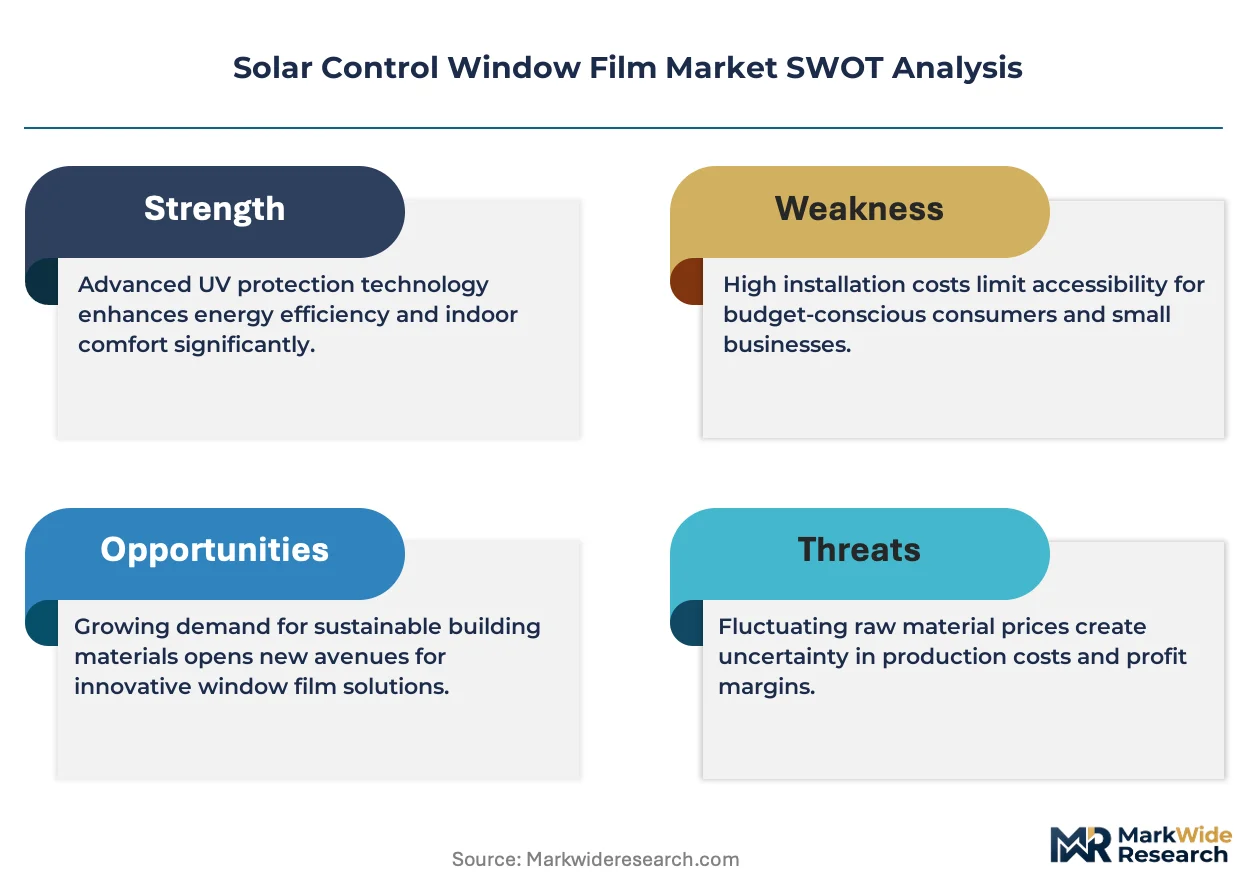
- Polyester substrate concentration:Sputtering-grade PET supply chains cluster among Asian chemical producers, exposing film manufacturers to input volatility and logistics bottlenecks.
- EU REACH adhesive restrictions:Reformulation requirements for lower-global-warming-potential chemistries are extending R&D timelines and raising compliance costs for European market entry.
- Low-E glazing substitution:Vacuum-insulated and electrochromic smart glass technologies are capturing new construction specifications where solar control film cannot integrate.
Strategic Opportunities
- India BIS energy efficiency standards:Emerging mandatory building codes in commercial hubs like Mumbai and Bangalore are creating first-mover advantages for specification-grade film suppliers.
- Utility-managed efficiency programs:Demand-response aggregators are bundling window film installation into grid-stabilization contracts, opening direct-to-utility sales channels bypassing traditional distributor networks.
- Photovoltaic-integrated film convergence:Building-integrated photovoltaics manufacturers are partnering with film producers to develop semi-transparent power-generating glazing laminates for curtainwall retrofits.
Industry Challenges
- Certified installer scarcity:Specification-grade ceramic film application demands squeegee technique and contamination control training that outpaces vocational pipeline output in secondary metropolitan markets.
- Green building certification timeline compression:LEED and BREEAM version updates are shortening acceptable solar heat gain coefficient windows, forcing rapid product requalification and documentation resubmission cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Control Window Film Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.25 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Dyed Film, Metallized Film, Ceramic Film, Clear Film Application: Residential, Commercial, Automotive, Marine Installation Type: DIY, Professional, Temporary, Permanent End User: Homeowners, Business Owners, Fleet Operators, Contractors |
| Companies Covered | 3M, Saint-Gobain, Eastman Chemical Company, Avery Dennison Corporation, Garware Hi-Tech Films, Madico Inc., Johnson Window Films, LINTEC Corporation, Solar Screen International SA, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Control Window Film Market Emerging Trajectories
Film manufacturers are reconfiguring product architectures around signal transparency, thermal selectivity, and embedded intelligence rather than commodity solar rejection, compressing traditional metallized film margins while opening premium positioning for functionalized ceramics.
Nanoparticle-doped ceramic infrared-rejecting coatings are decentralizing specification authority away from generalist glazing contractors toward specialized building-envelope consultants and automotive thermal engineers who control performance criteria. These consultants specify ceramic films for connected-vehicle fleets and smart-building facades where electromagnetic interference tolerance is non-negotiable. The shift is compressing metallized film share in segments where thermal performance per dollar once dominated selection.
REACH and the EU F-Gas Regulation are restricting solvent-based adhesive chemistries and fluorinated compounds used in conventional film lamination, compelling reformulation toward waterborne and bio-based alternatives. European film producers are accelerating compliance investments to maintain specification eligibility for public building retrofits. German and French regulatory enforcement is most stringent, creating competitive separation between compliant and non-compliant supplier portfolios.
Buyer concentration among national fleet operators and institutional real estate investment trusts is compressing sales cycles and unbundling after-sales service from product supply. Large buyers now contract directly with film manufacturers for multi-site rollouts, relegating regional distributors to logistics execution. The United States exhibits this pattern most acutely, where REIT procurement desks centralize specification across hundreds of properties simultaneously.
Solar Control Window Film Market Segmentation
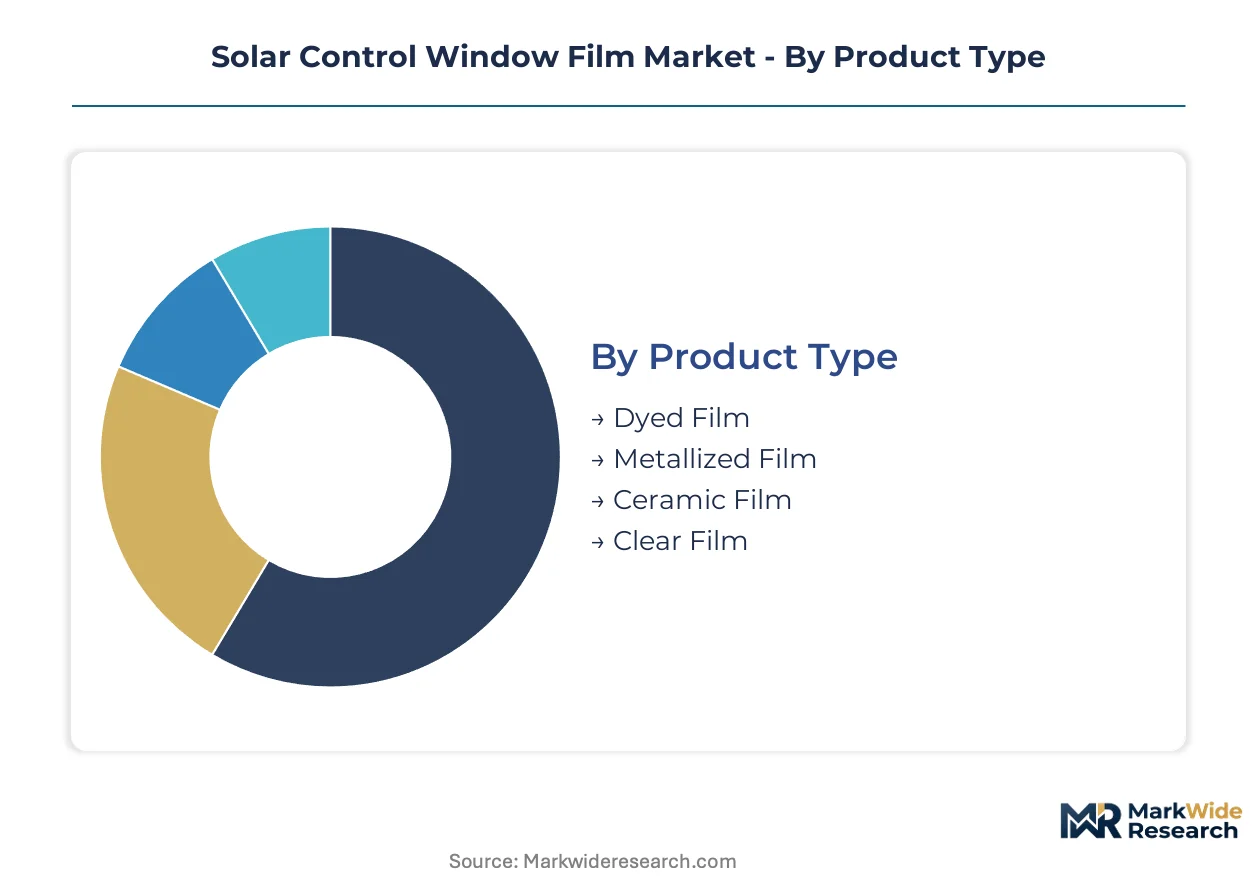
Solar control window film segmentation reflects divergent technical requirements across glazing integration depths. Product architecture determines whether films function as surface-applied retrofits or specification-grade building envelope components.
Product Type:
Integration depth separates commodity surface treatments from embedded performance systems in glazing specifications.
- Metallized Film:Multi-layer laminates with vapor-deposited aluminum or silver coatings deliver high infrared rejection through reflective interference. Demand clusters in United States commercial retrofits where California Title 24 compliance drives specification at volume price points. Thermal performance per dollar sustains its position in aging building stock upgrades.
- Ceramic Film:Sputtered metal oxide nanoparticle coatings achieve selective solar transmission without metallic conductivity. Connected-vehicle architectures in Germany and fleet electrification programs specify ceramic for 5G and GPS signal transparency. Premium positioning reflects non-negotiable electromagnetic compatibility requirements.
- Dyed Film:Absorptive colorant-loaded PET substrates provide entry-level glare reduction for residential aftermarket applications.
- Clear Film:Spectrally selective coatings reject infrared while maximizing visible transmission for heritage building retrofits.
Volume placements concentrate in metallized film; the faster expansion belongs to ceramic film.
Application:
Cost tier stratification separates high-volume standardized installations from specialized performance environments.
- Commercial:Large-format curtainwall and storefront glazing in institutional real estate portfolios drive specification-grade procurement. REIT-managed properties in New York and Massachusetts leverage utility rebate programs for multi-site rollouts. Energy code compliance timelines compress replacement cycles across Class A office stock.
- Automotive:OEM and aftermarket cabin thermal management demands ceramic compatibility with connected-vehicle electronics. Fleet operators in China prioritize signal-friendly films for electric vehicle thermal load reduction. Electrification mandates accelerate specification authority shift toward automotive thermal engineers.
- Residential:Homeowner-driven retrofit demand concentrates in sun-belt climates with utility incentive alignment.
- Marine:Superyacht refit clusters in Mediterranean and Caribbean shipyards specify salt-corrosion-resistant coating systems.
Commercial applications absorb the largest volume share; automotive is climbing the fastest as fleet specifications tighten.
Installation Type:
Customer type determines whether procurement flows through retail channels or direct manufacturer contracting.
- Professional:Certified applicator networks execute specification-grade ceramic installations with contamination control protocols. Scarcity of trained installers in secondary United States metropolitan markets extends project timelines. Performance guarantees require documented squeegee technique and environmental controls.
- DIY:Pre-cut kit formats serve residential aftermarket through big-box retail and e-commerce channels.
- Permanent:Adhesive-bonded systems dominate commercial and automotive OEM specifications.
- Temporary:Static-cling and removable formats address rental property restrictions and seasonal applications.
Permanent installations command the greatest volume; professional application channels are gaining share fastest as specification complexity rises.
End User:
Supply concentration shapes procurement authority distribution across fragmented versus consolidated buyer bases.
- Fleet Operators:National automotive and commercial vehicle fleets centralize specification across thousands of units simultaneously. Direct manufacturer contracts displace distributor networks for volume pricing and uniform performance documentation. United States-based operators lead consolidation trends.
- Business Owners:Commercial real estate investment trusts bundle window film into capital improvement programs across property portfolios.
- Contractors:Glazing and building envelope specialists control specification authority for high-performance ceramic installations.
- Homeowners:Price-sensitive retail purchasers respond to utility rebate availability and seasonal promotion cycles.
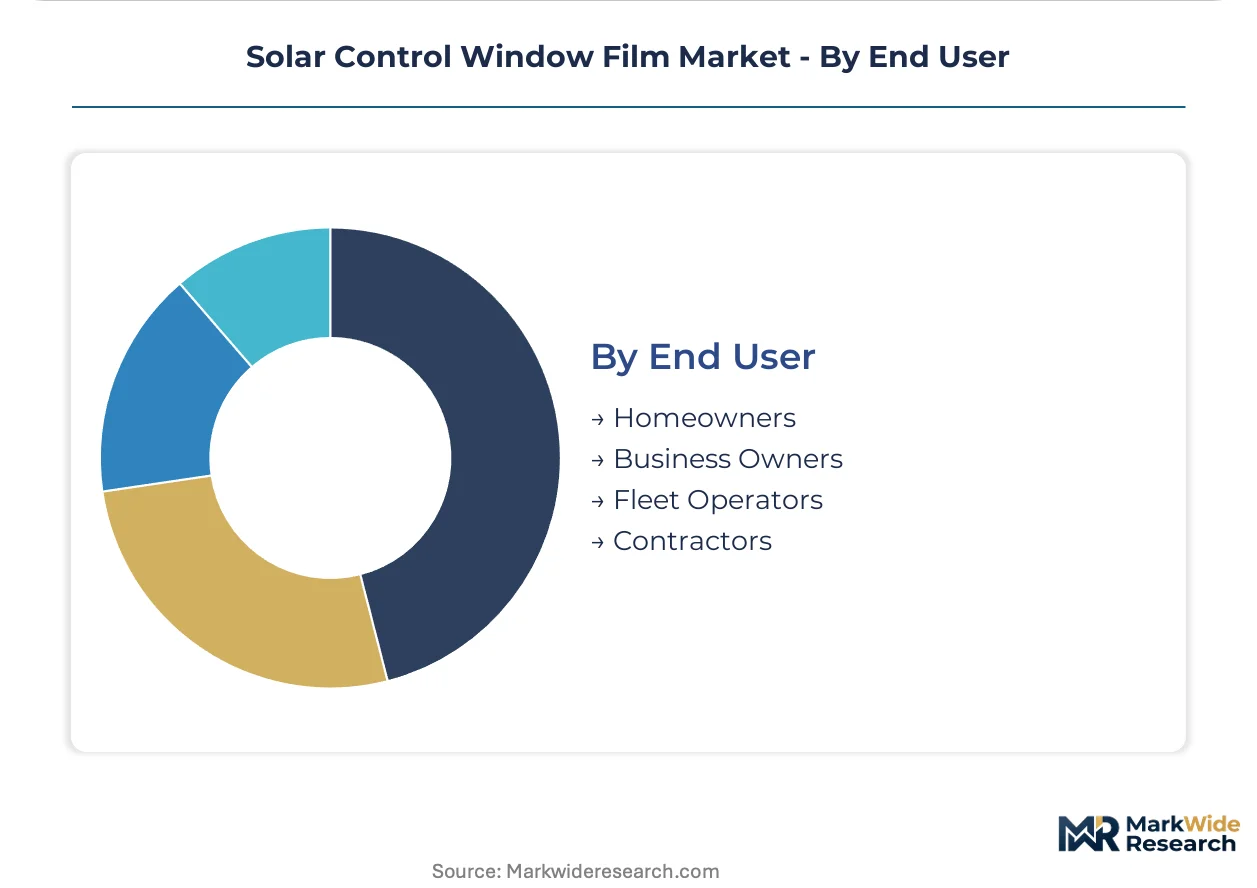
Business owners represent the largest volume segment; fleet operators are expanding most quickly as procurement centralizes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Polyester substrate production concentrates in Asian chemical manufacturing corridors, with film fabrication clustering near coastal glazing markets and automotive assembly zones. Sputtering-grade PET supply chains feed regional conversion facilities across three continents.
United States
Commercial real estate investment trusts in New York and Massachusetts drive multi-site retrofit procurement through utility-managed efficiency programs. California's Title 24 energy codes mandate solar heat gain coefficient thresholds for commercial buildings, specifying ceramic and metallized films as compliance pathways. Los Angeles and San Francisco building stock replacement cycles accelerate as aging curtainwall systems face energy code deadlines.
Germany
Connected-vehicle fleet operators specify ceramic films for 5G and GPS signal transparency in electrified cabin architectures. The EU F-Gas Regulation and REACH compliance frameworks restrict solvent-based adhesive chemistries, compelling reformulation toward waterborne alternatives. Stuttgart's automotive engineering cluster and Frankfurt's commercial property markets anchor specification-grade demand for electromagnetic-compatible glazing solutions.
China
Electric vehicle thermal management programs prioritize signal-friendly ceramic films to reduce HVAC loads without disrupting connected-vehicle electronics. Utility rebate programs in commercial hubs align with national dual carbon goals for building efficiency retrofits. Shanghai and Shenzhen manufacturing corridors host sputtering-grade PET production and film conversion capacity serving domestic and export markets.
India
Bureau of Indian Standards energy efficiency standards for commercial buildings in Mumbai and Bangalore create first-mover specification opportunities for certified film suppliers. Green building certification adoption accelerates in IT park developments across Hyderabad and Chennai. Salt-corrosion-resistant marine-grade specifications serve superyacht refit demand from Mediterranean and Caribbean shipyards sourcing through Indian distributors.
Japan
METI building energy codes and JIS standards shape performance thresholds for high-rise commercial retrofits in Tokyo and Osaka. Automotive OEM thermal engineering specifications favor ceramic films for connected-vehicle compatibility in domestic and export vehicle programs. Nagoya's automotive supplier corridor and Yokohama's port facilities concentrate film distribution for marine and commercial glazing applications.
Solar Control Window Film Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue photovoltaic-integrated glazing and smart-building envelope convergence. The vendor base stratifies across three tiers: multinational chemical conglomerates with captive polyester supply chains, regional specialists with certified installer network density, and niche marine-grade formulators with salt-corrosion-resistant coating expertise. Dominant competitive moves include direct contracting with national fleet operators and REIT procurement desks, alongside vertical integration into sputtering-grade substrate production to secure input cost stability.
Within the multinational chemical tier, Eastman Chemical Company and Saint-Gobain occupy positions anchored by polyester supply chain control and European specification relationships respectively. Johnson Window Films exemplifies the regional specialist archetype through North American installer-network density. Japanese and Korean industrial conglomerates represented by LINTEC Corporation sit within the precision-coating technology tier, serving automotive OEM specifications with electromagnetic-compatible ceramic formulations.
| Leading Market Players |
|---|
| 3M |
| Saint-Gobain |
| Eastman Chemical Company |
| Avery Dennison Corporation |
| Garware Hi-Tech Films |
| Madico Inc. |
| Johnson Window Films |
| LINTEC Corporation |
| Solar Screen International SA |
| Others |
Supply Flow & Price Mechanics
Commercial real estate investment trust procurement desks concentrate multi-site volume contracting, compressing transaction margins while elevating specification-grade ceramic films to premium price tiers through performance-guarantee frameworks. This buyer consolidation rewards suppliers with captive sputtering-grade PET substrate production and certified installer networks, while marginalizing regional distributors to logistics-only roles.
Pricing Analysis
Volume placements in metallized film segments operate on thin transactional margins, while ceramic film commands premium positioning through electromagnetic compatibility certification and signal-transparency guarantees. Price differentiation separates specification-grade ceramic installations with documented squeegee technique and contamination control from commodity metallized retrofits competing on thermal performance per dollar. Cost compression in metallized tiers intensifies as polyester substrate volatility and Asian chemical producer concentration squeeze input costs. Fleet operators and institutional buyers exhibit lowest price sensitivity, prioritizing uniform performance documentation across thousand-unit rollouts, while residential DIY purchasers respond acutely to utility rebate thresholds and seasonal promotion cycles.
Supply Chain Analysis
Reverse-logistics flows for specification-grade film remain minimal given permanent adhesive bonding, though marine-grade salt-corrosion-resistant coating systems in Mediterranean and Caribbean refit clusters generate specialized return-for-recertification channels. Sputtering-grade PET substrate production concentrates in China, South Korea, and Japan, with film fabrication clustering near coastal glazing markets and automotive assembly zones. Raw material dependencies center on vapor-deposition-grade aluminum and silver feedstocks, metal oxide nanoparticle precursors, and REACH-compliant waterborne adhesive chemistries. Single-source vulnerability in Asian chemical producer corridors exposes film manufacturers to logistics bottlenecks and tariff exposure. Distribution runs through direct manufacturer contracting with national fleet operators and REIT procurement desks, relegating traditional distributor networks to secondary metropolitan markets and residential retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The solar control window film sector occupies a technology-transition phase where nanoparticle-doped ceramic infrared-rejecting coatings displace legacy metallized laminates in connected-vehicle and smart-building specifications. This substitution compresses commodity film margins while opening premium positioning for electromagnetic-compatible formulations.
For Market Incumbents: To counter low-E glazing substitution in new construction specifications, Eastman Chemical Company and Saint-Gobain should deepen backward integration into sputtering-grade PET substrate production to secure input cost stability against Asian chemical producer volatility. Ceramic film producers must accelerate REACH-compliant waterborne adhesive reformulation to maintain European public building retrofit eligibility as German and French enforcement tightens. Specification-grade certification investment represents the critical defensive lever, as green building certification timeline compression forces rapid product requalification cycles. For New Entrants and Emerging Players: Capture first-mover positioning in India's Bureau of Indian Standards energy efficiency standards for commercial buildings in Mumbai and Bangalore, where mandatory codes create specification-grade demand without entrenched incumbent relationships. Marine-grade salt-corrosion-resistant coating systems for superyacht refit clusters offer specialized white-space with premium margin structures detached from commodity pricing pressure. Direct-to-utility sales channels through demand-response aggregator partnerships bypass traditional distributor density requirements and accelerate market entry. For Investors and Strategic Acquirers: Distressed-cycle entries favor regional specialists with certified installer network density in secondary United States metropolitan markets, where scarcity of trained applicators extends project timelines and creates acquisition value. Long-term viability across a five-to-ten-year window hinges on photovoltaic-integrated film convergence partnerships with building-integrated photovoltaics manufacturers for semi-transparent power-generating glazing laminates. Practitioners should monitor California Title 24 stretch code updates and EU F-Gas Regulation enforcement intensity as inflection indicators for specification authority shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sputtering-Grade PET Production | Captive substrate supply insulates margin compression from Asian chemical producer concentration. |
| REACH-Compliant Waterborne Adhesive Reformulation | Maintains European public building retrofit eligibility under tightening German and French enforcement. |
| Certified Installer Network Expansion | Addresses scarcity in secondary United States metropolitan markets that extends project timelines. |
| Photovoltaic-Integrated Film Partnership | Positions for semi-transparent power-generating glazing convergence in curtainwall retrofits. |
| Direct-to-Utility Sales Channel Development | Bypasses traditional distributor networks through demand-response aggregator grid-stabilization contracts. |
Methodological Framework
Trade association filings, customs and trade data, and SEC regulatory disclosures formed the secondary backbone, cross-referenced against primary interviews with building envelope consultants, automotive thermal engineers, REIT procurement managers, and certified film applicators. Bottom-up installation volume estimates from utility rebate program administrators triangulated against top-down polyester substrate production data from Asian chemical manufacturing corridors. Primary fieldwork captured specification authority shifts from generalist glazing contractors toward specialized consultants controlling ceramic film performance criteria.
Historical trendline analysis of commercial retrofit cycles, automotive fleet electrification mandates, and superyacht refit clusters informed the projection framework across the analysis window. Segmentation dimensions modeled include product architecture tier, application environment, installation type, and end-user procurement concentration. CAGRs derived from regression analysis of energy code compliance timelines, utility incentive program budgets, and connected-vehicle electronics penetration curves. Industry-specific forecast inputs encompassed California Title 24 adoption velocity and EU F-Gas Regulation reformulation cost pass-through assumptions.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to low-E glazing substitution rates in new construction and photovoltaic-integrated film technology maturation. Projections reflect assumptions regarding regulatory enforcement consistency, substrate supply chain stability, and certified installer vocational pipeline expansion. Practitioners should monitor California stretch code pre-enforcement drafts, EU REACH adhesive restriction implementation timelines, and utility demand-response program budget allocations for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Blind Bolts Market
Building Materials
Aluminum Door and Window Market
Building Materials
India Dry Mix Mortar Market
Building Materials
North America Cement Market
Building Materials
Malaysia Architectural Coatings Market
Building Materials
India Construction Ornamental Stone Market
Building Materials
Global Fiber Cement Siding Market
Building Materials
Stone Coated Steel Roofing Market
Building Materials
Middle-East and Africa Buildings and Construction Sheets Market
Building Materials
Low-E Construction Glass Market
Building Materials
US Cement Tiles Market
Building Materials
US Contract Glazing Market
Building Materials
LAMEA Engineered Stone Market
Building Materials
India Cement Market
Building Materials
Natural Stone Market
Building Materials
Europe Concrete Admixtures Market