
 Italy Oriented Strand Board Market | 2026-2036
Italy Oriented Strand Board Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Oriented Strand Board Market Insights
Residential contractors is bifurcating from traditional plywood buyers as cost-sensitive housing developers prioritize engineered wood panels for multi-story frames. Kronospan leverages its integrated resin and strand supply chain to maintain pricing leverage across the Po Valley. Egger Group anchors its Italian position through dedicated OSB capacity serving furniture manufacturers in Friuli-Venezia Giulia.
Oriented Strand Board consists of layered wood strands bonded with waterproof phenol-formaldehyde or MDI resin under heat and pressure, yielding panels with directional strength properties calibrated to 6-25 mm thickness ranges for load-bearing applications. Structural Board dominates volume flows into Italian residential construction, while Specialty Board commands premium positioning in moisture-resistant and fire-retardant formulations for commercial facades. Furniture Grade segments compete with medium-density fiberboard in cabinetry applications where surface aesthetics determine specification.
Italy's national building regulator enforces Eurocode 5 compliance for timber structures, while regional energy agencies under the National Recovery and Resilience Plan mandate thermal performance thresholds that favor thicker OSB insulation layers. BIS certification requirements for imported panels create procedural friction for non-EU suppliers entering the peninsula. Stakeholders must track how the EU Deforestation Regulation reshapes strand sourcing economics for Italian mills dependent on Baltic and Alpine timber flows.
Market Dynamics
Italy's Oriented Strand Board market is being fundamentally restructured by the Superbonus 110% energy retrofit program, which mandates structural panel upgrades and is concentrating demand among certified contractors capable of navigating complex compliance workflows.
Growth Catalysts
- Superbonus 110% retrofit mandates:Italy's national recovery framework requires thermal performance upgrades in residential envelopes, directly expanding specification for load-bearing OSB sheathing in wall and roof assemblies.
- Multi-story timber construction:Housing developers across Lombardy and Veneto are specifying engineered wood panels for mid-rise frames, displacing traditional masonry and concrete in cost-sensitive projects.
- Cross-laminated timber integration:CLT fabricators in South Tyrol are procuring OSB as complementary structural layers, creating integrated supply relationships with strand board mills.
Market Restraints
- Phenol-formaldehyde resin cost volatility:Petrochemical feedstock fluctuations compress margins for mills without captive chemical production or long-term supply contracts.
- Baltic timber sourcing concentration:Italian mills depend on Estonian and Latvian softwood strands, exposing production schedules to shipping disruptions and EU Deforestation Regulation verification delays.
- Medium-density fiberboard substitution:Furniture manufacturers in Friuli-Venezia Giulia specify MDF for cabinetry applications where surface smoothness outweighs structural performance requirements.
Strategic Opportunities
- Fire-retardant Specialty Board formulations:Commercial facade contractors in Milan and Turin face stringent fire safety codes, creating premium positioning for treated OSB in high-rise cladding systems.
- Emilia-Romagna industrial corridor expansion:Logistics and light manufacturing construction in Bologna and Modena is generating demand for fast-erection panelized building systems.
- EU Deforestation Regulation compliance services:Mills offering verified chain-of-custody documentation capture specification preference from public procurement frameworks requiring sustainable sourcing.
Industry Challenges
- Eurocode 5 structural engineering certification:Contractors face extended timelines securing compliance documentation for timber-framed multi-story buildings, compressing project delivery windows.
- Alpine timber supply reconfiguration:Mills must rebuild strand sourcing relationships as Austrian and Slovenian suppliers adapt to new EU-wide due diligence requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Oriented Strand Board Market |
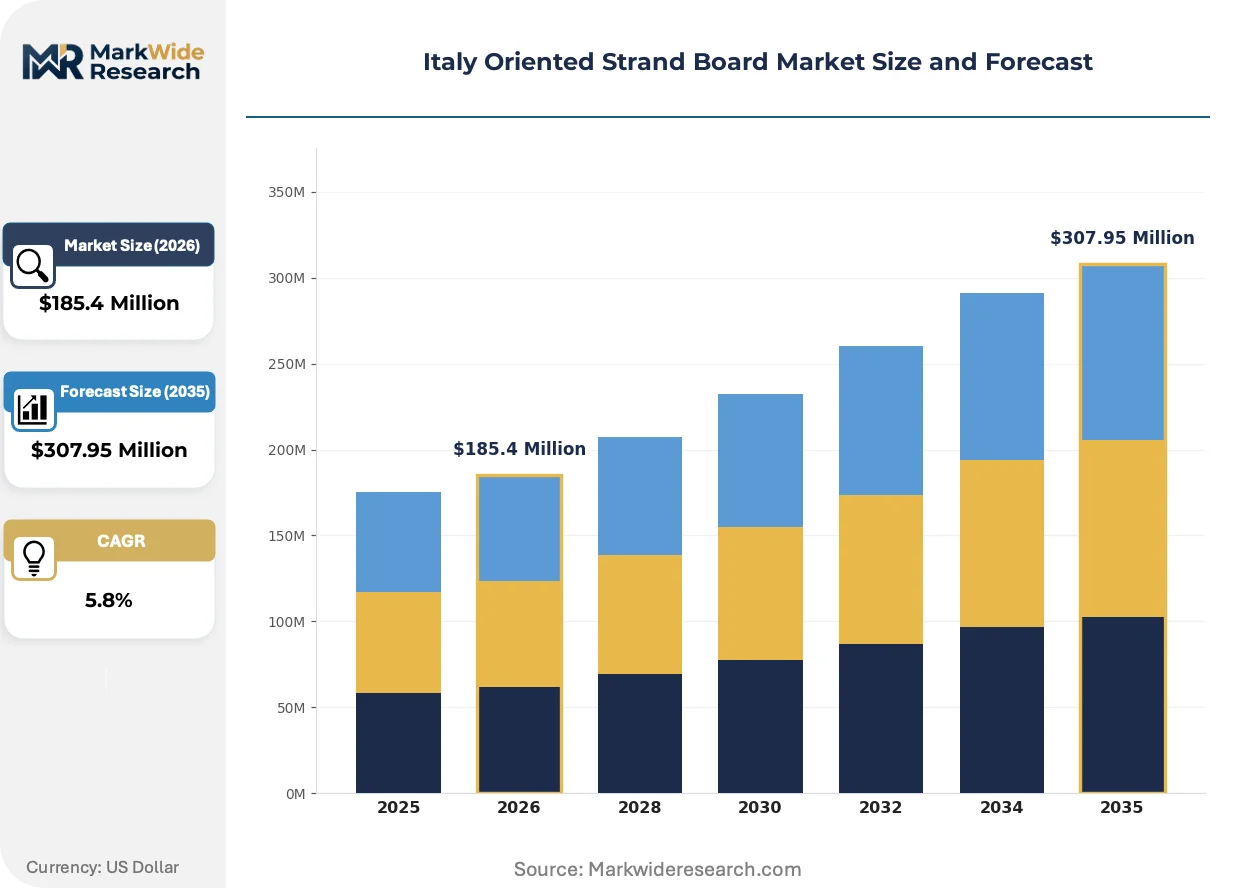
| Market Size in 2026 | $185.4 Million |
| Market Size in 2035 | $307.95 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Structural Board, Insulation Board, Furniture Grade, Specialty Board Application: Construction, Furniture Production, Packaging, Floor Covering End User: Contractors, Manufacturers, Retailers, Exporters Thickness: Thin, Medium, Thick, Extra Thick |
| Companies Covered | Egger Group, SWISS KRONO Group, Kronospan, Sonae Arauco, West Fraser, SMARTPLY Europe (Coillte), FINSA, Pfleiderer Group, UPM-Kymmene Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Oriented Strand Board Market Trends and Innovations
Moisture-resistant resin formulations and digital fabrication workflows are reshaping how Italian contractors specify and install structural panels across residential and commercial verticals.
MDI resin systems are bifurcating from traditional phenol-formaldehyde binders in applications demanding superior moisture resistance. Northern Italian contractors working on energy retrofit projects specify MDI-bonded panels for roof decks and foundation walls. This chemistry shift is compressing the addressable market for conventional resin formulations while expanding premium-grade OSB volumes.
Italy's National Recovery and Resilience Plan enforcement through regional energy agencies is mandating thermal bridge elimination in building envelopes. Construction firms must document panel R-values and installation continuity to secure tax credit eligibility. Residential contractors in Lombardy are responding by procuring thicker OSB insulation layers calibrated to specific U-value targets.
Direct mill-to-contractor procurement platforms are consolidating specification influence among large housing developers. Digital tendering systems in Veneto and Emilia-Romagna bypass traditional distribution intermediaries for volume projects. This channel compression is most visible in social housing developments where public procurement frameworks favor transparent, auditable supply chains.
Italy Oriented Strand Board Market Segmentation
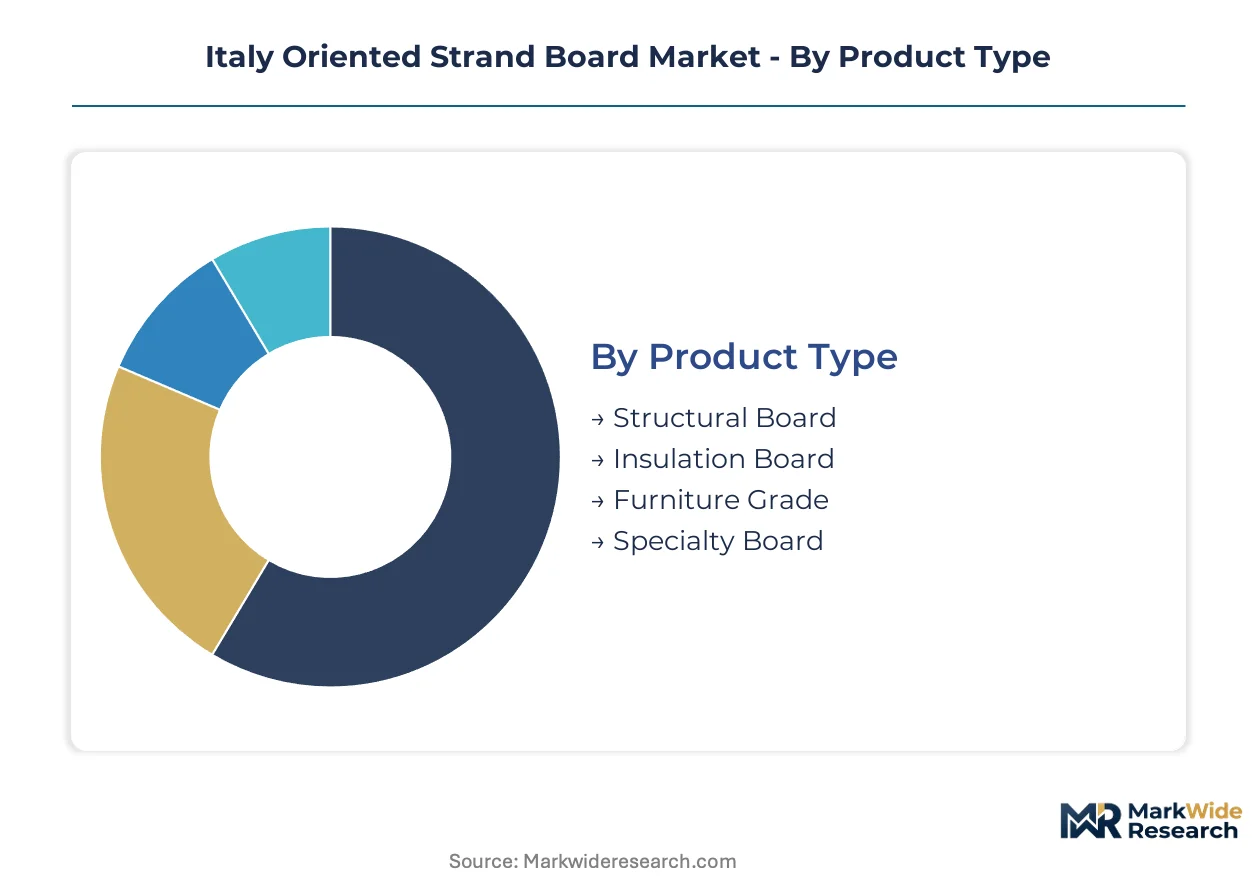
OSB segmentation in Italy reflects divergent margin economics across load-bearing structural applications versus commodity furniture grades. Specification requirements under Superbonus 110% retrofit mandates and Eurocode 5 compliance create tiered pricing power that reshapes competitive positioning by product category.
Product Type:
Margin pools concentrate in formulations commanding technical premiums for fire resistance and moisture protection, while commodity structural grades compete on scale and logistics efficiency.
- Structural Board:Load-bearing panels bonded with phenol-formaldehyde or MDI resin, calibrated to 9-18 mm thickness for wall sheathing and roof decking. Demand concentrates among residential contractors executing Superbonus 110% retrofits across Lombardy and Veneto, where thermal bridge elimination mandates thicker panel specifications. Pricing leverage depends on Eurocode 5 certification documentation and mill proximity to northern industrial corridors.
- Specialty Board:Fire-retardant and moisture-resistant formulations incorporating treated resins and enhanced strand orientation. Commercial facade contractors in Milan and Turin specify these panels for high-rise cladding systems facing stringent fire safety codes. Premium positioning reflects extended testing protocols and BIS certification requirements for treated structural panels.
- Insulation Board:Low-density panels engineered for thermal performance in envelope assemblies. Regional energy agencies under the National Recovery and Resilience Plan mandate specific R-value documentation.
- Furniture Grade:Surface-calibrated panels competing with medium-density fiberboard in cabinetry applications. Friuli-Venezia Giulia manufacturers prioritize surface smoothness over structural performance.
Structural Board holds installed capacity. Specialty Board is rotating up the share rankings.
Application:
Construction applications dominate volume flows, yet furniture production and packaging segments exhibit divergent procurement patterns shaped by specification intensity and customer scale.
- Construction:Wall sheathing, roof decking, and subflooring in timber-framed residential and commercial buildings. Multi-story housing developers across the Po Valley specify engineered wood panels for mid-rise frames, displacing traditional masonry in cost-sensitive projects. Direct mill-to-contractor procurement platforms are consolidating specification influence among large developers executing social housing developments.
- Furniture Production:Cabinetry substrates and interior fittings where surface aesthetics determine specification. Friuli-Venezia Giulia manufacturers source OSB for structural components while specifying MDF for visible surfaces.
- Packaging:Industrial crating and export dunnage applications prioritizing cost over performance. Logistics operators in Emilia-Romagna procure standard-grade panels for pallet and crate fabrication.
- Floor Covering:Underlayment and subfloor systems in renovation projects. Flooring contractors specify moisture-resistant grades for concrete slab applications.
Construction absorbs the dominant production share. Floor Covering is gaining specification traction in retrofit-intensive regions.
End User:
Contractor procurement behavior diverges sharply from manufacturer purchasing, with certification capability and tax credit navigation determining market access.
- Contractors:Certified building firms executing Superbonus 110% retrofits and new timber-framed construction. These end users require comprehensive Eurocode 5 documentation and chain-of-custody verification for public procurement eligibility. Lombardy and Veneto contractors are consolidating procurement through digital tendering platforms that bypass traditional distribution intermediaries.
- Manufacturers:Furniture producers and CLT fabricators procuring OSB as complementary structural layers. South Tyrol CLT operations integrate strand board as secondary structural elements in mass timber assemblies.
- Retailers:Building material distributors serving small-scale renovation contractors and DIY segments. Inventory carrying costs and specification support requirements constrain margin realization.
- Exporters:Trading operations shipping Italian-produced panels to Mediterranean and North African markets. BIS certification requirements for non-EU destinations create procedural friction.
Contractors command priority allocation. Manufacturers are deepening integration with mill technical services.
Thickness:
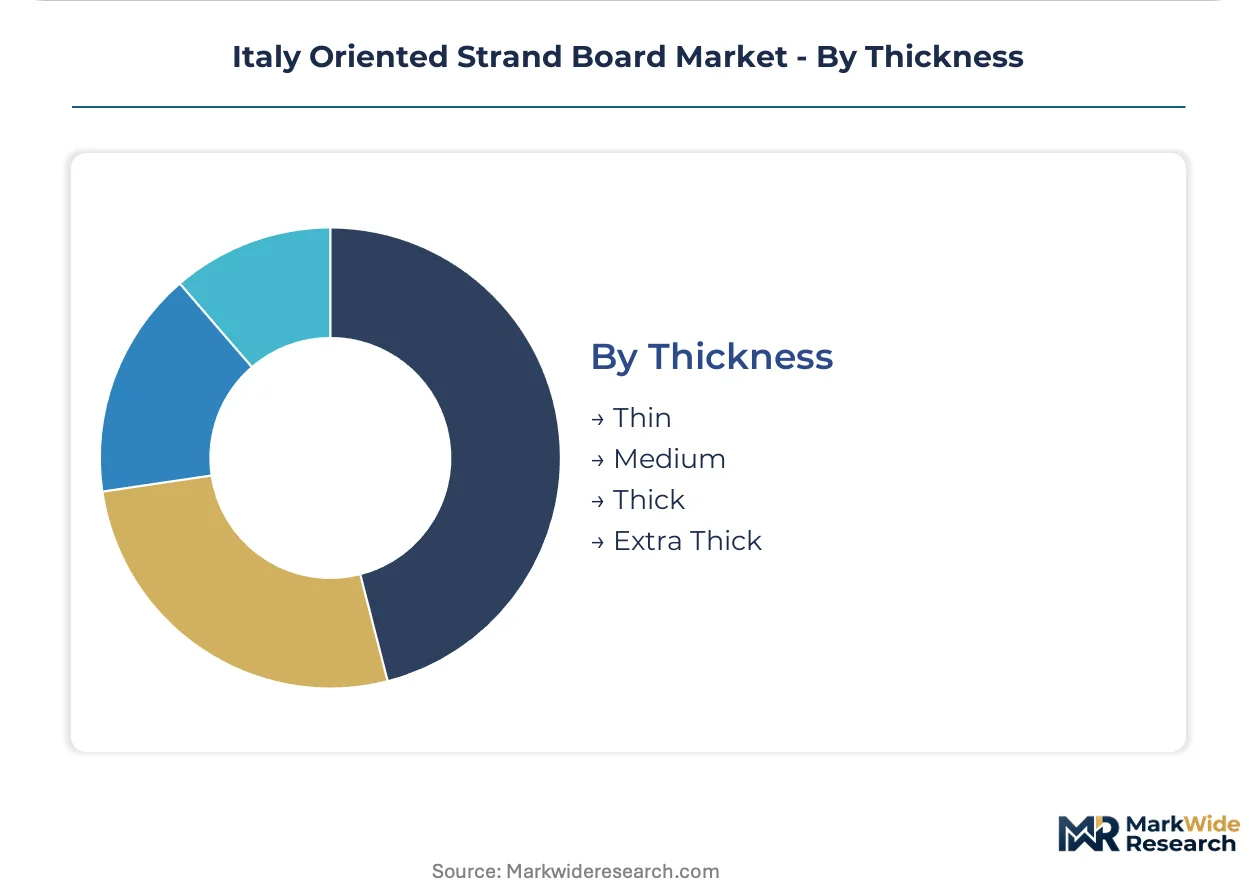
Thermal performance mandates under regional energy agency enforcement are shifting volume toward thicker calibrations that deliver specified U-values.
- Thick:Panels exceeding 18 mm specified for load-bearing wall assemblies and roof structures requiring enhanced thermal performance. National Recovery and Resilience Plan enforcement through regional energy agencies mandates thermal bridge elimination, driving specification for thicker insulation layers calibrated to specific U-value targets.
- Medium:12-18 mm range serving standard wall sheathing and subflooring applications. Cost-optimized housing developments in Emilia-Romagna specify this calibration for panelized building systems.
- Thin:6-9 mm panels for furniture backing, packaging, and non-structural applications. Price-sensitive segments compete with plywood and particleboard alternatives.
- Extra Thick:Panels exceeding 25 mm for specialized acoustic and fire-rated assemblies. Limited production runs serve premium commercial retrofit projects.
Thick calibrations anchor current production planning. Extra Thick is climbing the specification ladder in fire-rated commercial verticals.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Estonian and Latvian softwood exporters supply strand feedstock to Italian mills clustered along the Po Valley industrial corridor, with Baltic shipping routes determining production scheduling across northern fabrication centers.
Lombardy
Milan-based contractors executing Superbonus 110% retrofits specify thick-calibration OSB for thermal bridge elimination in multi-story residential envelopes. Regional energy agencies under the National Recovery and Resilience Plan mandate U-value documentation for tax credit eligibility. Construction clusters in Monza and Bergamo concentrate procurement through digital tendering platforms that bypass traditional distribution channels.
Veneto
Housing developers across the Veneto plain specify engineered wood panels for mid-rise timber frames displacing masonry construction in cost-sensitive projects. Eurocode 5 compliance requirements enforced by Italy's national building regulator extend engineering certification timelines for multi-story assemblies. Verona and Vicenza host contractor consolidation zones where certified firms navigate complex public procurement workflows.
Emilia-Romagna
Logistics and light manufacturing construction in Bologna and Modena generates demand for fast-erection panelized building systems. The Superbonus framework mandates structural panel upgrades in commercial retrofit applications. Industrial corridors between Parma and Ravenna concentrate mill-to-contractor direct procurement relationships for volume social housing developments.
Friuli-Venezia Giulia
Furniture manufacturers in Udine and Pordenone source OSB for structural cabinetry components while specifying medium-density fiberboard for visible surfaces. Surface aesthetics determine specification trade-offs in this export-oriented manufacturing cluster. Regional mills serve integrated supply relationships with South Tyrol cross-laminated timber fabricators requiring complementary structural layers.
Piedmont
Turin-based commercial facade contractors face stringent fire safety codes driving premium positioning for fire-retardant Specialty Board in high-rise cladding systems. BIS certification requirements for treated structural panels create procedural friction in specification workflows. The Alpine proximity exposes mills to Austrian and Slovenian timber supply reconfiguration under EU Deforestation Regulation due diligence requirements.
Italy Oriented Strand Board Market Competitive Landscape
Listed leaders compete with private specialists across resin chemistry and strand sourcing dimensions, producing a tiered structure where scale-driven pan-European operators coexist with regional mill specialists. Three archetypes dominate: integrated chemical-resin producers leveraging captive supply chains, Baltic-timber-dependent fabricators exposed to shipping volatility, and specialty-formulation developers capturing premium positioning in fire-rated and moisture-resistant grades. Competitive moves concentrate on backward integration into resin production and chain-of-custody certification services for EU Deforestation Regulation compliance.
Within the integrated-resin tier, Kronospan and SWISS KRONO Group occupy positions exemplifying upstream control over phenol-formaldehyde and MDI chemistry supply. Egger Group anchors the specialty-formulation vector through dedicated Italian capacity. Sonae Arauco represents the Iberian-Atlantic sourcing archetype with distinct timber flow configurations.
| Leading Market Players |
|---|
| Egger Group |
| SWISS KRONO Group |
| Kronospan |
| Sonae Arauco |
| West Fraser |
| SMARTPLY Europe (Coillte) |
| FINSA |
| Pfleiderer Group |
| UPM-Kymmene Corporation |
| Others |
Pricing and Supply Chain Analysis
Mill-scale economies along the Po Valley industrial corridor concentrate pricing power among integrated resin producers while compressing margin floors for strand-dependent fabricators exposed to Baltic timber volatility. Kronospan's captive phenol-formaldehyde supply chain anchors price floors that smaller mills cannot match without long-term petrochemical contracts or MDI chemistry partnerships.
Pricing Analysis
Prior-generation phenol-formaldehyde bonded panels trade at commodity spot levels while current-generation MDI resin systems command 15-25% premiums for moisture-resistant specifications, and next-generation fire-retardant formulations with enhanced strand orientation capture the highest tier. Three-tier pricing structure across premium fire-rated Specialty Board, standard Structural Board, and economy Furniture Grade segments reflects certification intensity and thermal performance documentation. Cost compression in standard grades intensifies because housing developers in Emilia-Romagna consolidate procurement through digital tendering platforms that bypass distribution markups. Small-scale retailers serving DIY renovation segments exhibit highest price sensitivity, while certified Superbonus contractors prioritize specification compliance over unit cost.
Supply Chain Analysis
Strategic stockpile preferences dominate among Italian mills buffering against Baltic shipping disruptions, while just-in-time resin delivery from integrated chemical producers minimizes working capital drag. Supply concentrates in Estonian and Latvian softwood strand exports, Austrian and Slovenian Alpine timber flows, and German petrochemical resin production. Raw material dependencies center on phenol-formaldehyde and MDI binders, waterproofing additives, and fire-retardant treatment chemicals. Single-source vulnerability in Baltic strand sourcing exposes production schedules to EU Deforestation Regulation verification delays and shipping chokepoints through North Sea ports. Distribution runs through direct mill-to-contractor platforms for volume housing developments and traditional building material distributors for fragmented renovation segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among certified contractors capable of navigating Superbonus 110% compliance workflows, fragmenting access for smaller mills lacking documentation capabilities. Digital procurement platforms in Lombardy and Veneto accelerate this consolidation by favoring suppliers with integrated chain-of-custody systems.
For Market Incumbents: Fortify backward integration into resin production or secure captive MDI supply contracts to defend margin compression from petrochemical feedstock volatility. Expand fire-retardant Specialty Board capacity in Piedmont to capture premium positioning from Turin commercial facade contractors facing stringent fire safety codes. Eurocode 5 certification documentation capabilities represent the critical lever for maintaining specification influence among consolidated buyer pools. For New Entrants and Emerging Players: Lead with EU Deforestation Regulation compliance services as a differentiated entry wedge, offering verified chain-of-custody documentation that incumbent mills lack capacity to scale rapidly. Target Emilia-Romagna logistics construction segments where panelized building system demand outpaces established supplier relationships. Partner with regional energy agencies to embed thermal performance documentation directly into procurement workflows, bypassing traditional specification battles. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among mills with long-term offtake agreements to CLT fabricators in South Tyrol and certified contractor networks in Lombardy, insulating cash flow from spot market volatility. Five-to-ten year viability favors integrated operators with captive resin production and diversified timber sourcing beyond Baltic concentration. Acquisition targets should demonstrate established BIS certification pathways and documented Superbonus project completion track records. The signal to watch is enforcement intensity of EU Deforestation Regulation due diligence requirements, which will strand non-compliant inventory and accelerate consolidation toward verified supply chains.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Production | Captive phenol-formaldehyde supply insulates margins from petrochemical volatility affecting Baltic-dependent competitors. |
| Fire-Retardant Specialty Board Capacity Expansion | Turin and Milan commercial facade contractors face escalating fire safety codes that premium formulations address. |
| EU Deforestation Regulation Compliance Services | Verified chain-of-custody documentation captures specification preference from public procurement frameworks mandating sustainable sourcing. |
| Direct Mill-to-Contractor Digital Platforms | Bypassing distribution intermediaries consolidates influence among large housing developers executing social housing developments. |
| CLT Fabricator Long-Term Supply Agreements | South Tyrol mass timber operations require complementary OSB structural layers with documented thermal performance. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with plant managers at Po Valley mills, procurement leads at Lombardy housing developers, distribution channel partners in Emilia-Romagna, and technical R&D directors at resin suppliers; alongside secondary validation through customs and trade data, SEC filings of listed wood panel producers, Eurostat construction statistics, and BIS certification registries. Bottom-up volume estimates from mill capacity utilization and top-down demand calibration from regional building permit data were triangulated to cross-validate market sizing.
Across the projection horizon, the analytical framework modeled volume and value trajectories by product type, application vertical, end-user archetype, and thickness calibration, with regional energy agency enforcement intensity as an additional dimension. CAGRs were derived from regression analysis of historical construction output correlated with Superbonus uptake rates and timber-framed building permit growth. Forecast inputs incorporated strand board substitution rates against plywood and medium-density fiberboard, as well as CLT integration trends in South Tyrol mass timber construction.
The analysis sits within stated boundaries; outcomes outside sustained Superbonus program extension or stable Baltic timber trade flows would require recalibration. Forecasts reflect documented assumptions regarding regional energy agency enforcement timelines and Eurocode 5 certification adoption curves. Revision becomes warranted when EU Deforestation Regulation verification delays exceed current clearance thresholds or when MDI resin supply constraints disrupt specialty formulation production.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Travertine Tiles Market
Building & Construction Materials
Russia Cross Laminated Timber Market
Building & Construction Materials
Building Insulation Market
Building & Construction Materials
Girdle Plates Market
Building & Construction Materials
US Commercial Windows Market
Building & Construction Materials
South Africa Wall Putty Market
Building & Construction Materials
Russia Ceramic Tiles Market
Building & Construction Materials
Ceramic Wall Tiles Market
Building & Construction Materials
Roofing Tiles Market
Building & Construction Materials
Piping Systems Market
Building & Construction Materials
US Steel Merchant and Rebar Market
Building & Construction Materials
North America Ceramic Tiles Market
Building & Construction Materials
Oriented Strand Board (OSB) Market
Building & Construction Materials
Roofing Underlay Market
Building & Construction Materials
Sliding Bearing Market
Building & Construction Materials
North America Gypsum Board Market