
 China Cement Market | 2026-2036
China Cement Market Size, Share, and Industry Trends Forecast 2026-2036
China Cement Market Insights
Clinker-to-cement ratio reduction is reconfiguring margin pools across the China cement value chain. Anhui Conch Cement leverages captive limestone reserves to sustain cost leadership across eastern provinces. China National Building Material anchors national supply through its consolidated platform of regional subsidiaries. Huaxin Cement specializes in low-carbon product lines to differentiate amid tightening environmental compliance.
Cement is a hydraulic binder produced by grinding clinker with gypsum and supplementary cementitious materials to achieve specified compressive strength grades, primarily serving to bind aggregate in concrete for load-bearing structures. Ordinary Portland Cement dominates volume but faces margin compression as Blended Cement captures structural growth from infrastructure specifications favoring lower embodied carbon. Infrastructure applications for roads and bridges concentrate demand, while Residential Construction segments mature with slower permit issuance in tier-one cities.
MEE carbon intensity benchmarks, GB standards for building materials, and provincial dual carbon implementation timelines collectively reshape kiln upgrade cycles and market access conditions across Chinese cement manufacturing. SAMR market concentration reviews influence merger pathways among mid-scale producers. Stakeholders must monitor clinker substitution rates and carbon trading scheme participation as determinants of competitive cost position.
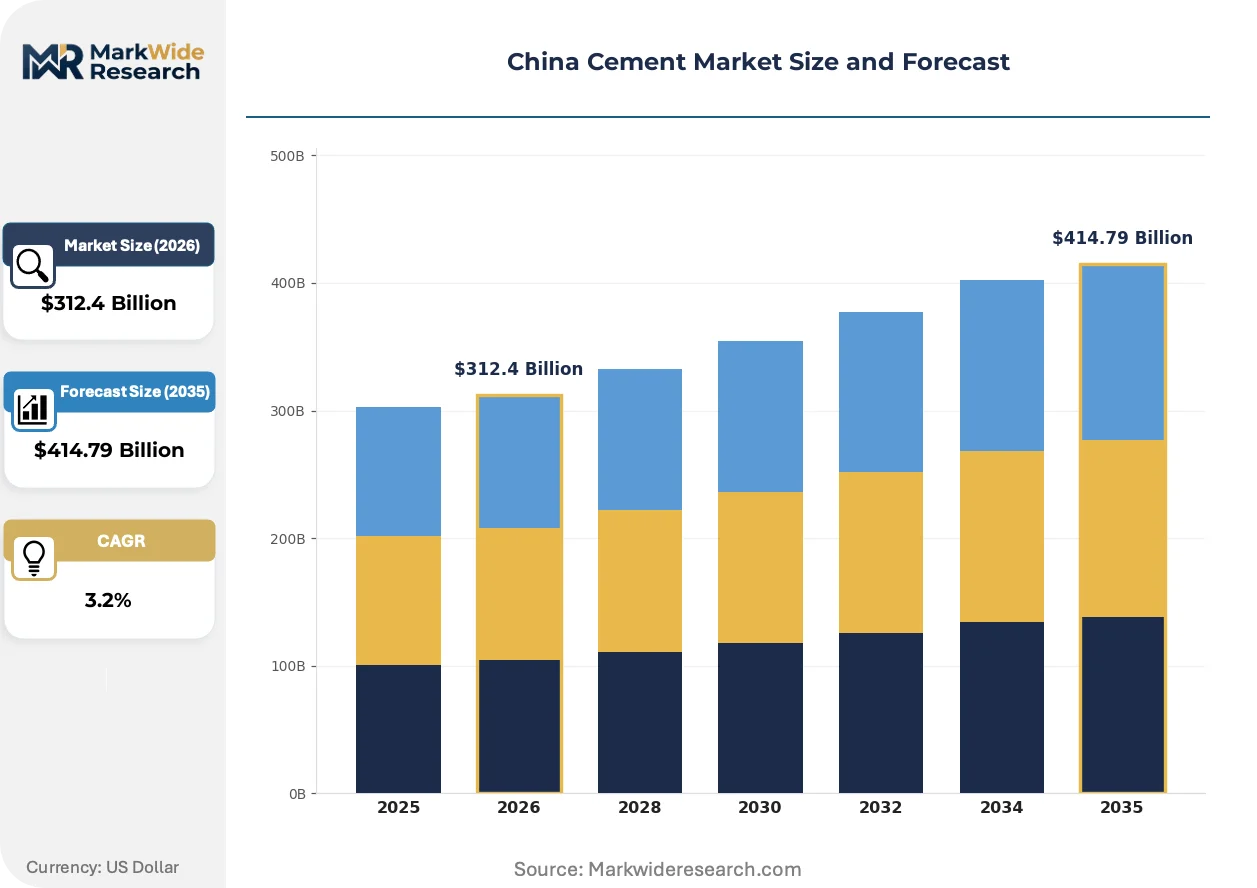
Market Dynamics
MEE dual carbon enforcement is compressing kiln upgrade cycles across eastern provinces while clinker substitution mandates restructure raw material procurement economics for integrated producers.
Growth Catalysts
- Belt and Road infrastructure anchor:Megaproject corridors spanning Central Asia and Southeast Asia sustain bulk cement offtake from coastal manufacturing clusters. Yangtze River Delta urban consolidation drives continuous demand for high-grade concrete inputs.
- GB standard elevation:Revised building material specifications mandate lower embodied carbon in public works, accelerating blended cement formulation adoption across state-backed contractors.
- Carbon trading scheme maturation:National ETS expansion into building materials sectors creates compliance-driven demand for low-clinker product lines among emissions-intensive producers.
Market Restraints
- Limestone reserve concentration:Captive quarry access concentrates in Anhui and Jiangsu provinces, locking out smaller producers from cost-competitive clinker sourcing.
- Alternative binder substitution:Geopolymer and alkali-activated materials capture niche specification share in high-durability infrastructure segments.
- SAMR concentration thresholds:Merger review stringency blocks mid-scale consolidation pathways that could rationalize excess kiln capacity in northern provinces.
Strategic Opportunities
- Western province kiln replacement:Sichuan and Shaanxi manufacturing bases lag coastal emission standards, creating first-mover advantage for low-carbon technology licensors.
- Industrial waste co-processing:Municipal sludge and hazardous waste thermal substitution opens revenue streams from waste management fees alongside fuel cost reduction.
- CCUS integration at coastal plants:Carbon capture retrofit readiness positions Jiangsu and Zhejiang facilities for future hydrogen or synthetic fuel kiln conversions.
Industry Challenges
- Process engineer scarcity:Deep expertise in alternative fuel combustion and raw meal chemistry sits concentrated among retiring technical staff at legacy state-owned enterprises.
- Legacy DCS migration complexity:Kiln control system upgrades to enable real-time emission optimization require parallel operational retraining and extended commissioning timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Cement Market |
| Market Size in 2026 | $312.4 Billion |
| Market Size in 2035 | $414.79 Billion |
| CAGR (2026 – 2036) | 3.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ordinary Portland Cement, Blended Cement, Rapid Hardening Cement, Sulfate Resistant Cement End User: Residential Construction, Commercial Construction, Infrastructure, Industrial Construction Distribution Channel: Direct Sales, Retail, Online, Wholesalers Application: Roads, Bridges, Buildings, Dams |
| Companies Covered | China National Building Material, Anhui Conch Cement, China Resources Cement, West China Cement, Huaxin Cement, Jidong Cement, Taiheiyo Cement China, Shanshui Cement, Sinoma Cement, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Cement Market Trends and Innovations
Digital kiln optimization and alternative fuel substitution are converging to compress emission intensity benchmarks while product formulation shifts toward supplementary cementitious material integration.
Oxyfuel combustion technology captures CO2 in concentrated streams for subsequent utilization or storage, rendering obsolete conventional post-combustion capture retrofits at integrated cement plants. State-grid industrial customers in Jiangsu province pilot full-scale demonstrations. The technology is rendering obsolete carbon-intensive amine scrubbing installations that dominated early decarbonization roadmaps.
MEE provincial dual carbon implementation timelines harden clinker-to-cement ratio ceilings through 2025-2027 milestone enforcement. GB 175 standard revisions embed these benchmarks into product certification requirements. Blended cement specialists in the Yangtze Delta accelerate slag and fly ash sourcing partnerships to secure compliant supply chains.
Direct procurement from manufacturer-owned distribution terminals displaces traditional multi-layer trader networks for bulk infrastructure contracts. State-owned construction groups consolidate supplier panels around emission-verified producers. This consolidation concentrates most visibly in Guangdong and Zhejiang public works tendering.
China Cement Market Segmentation
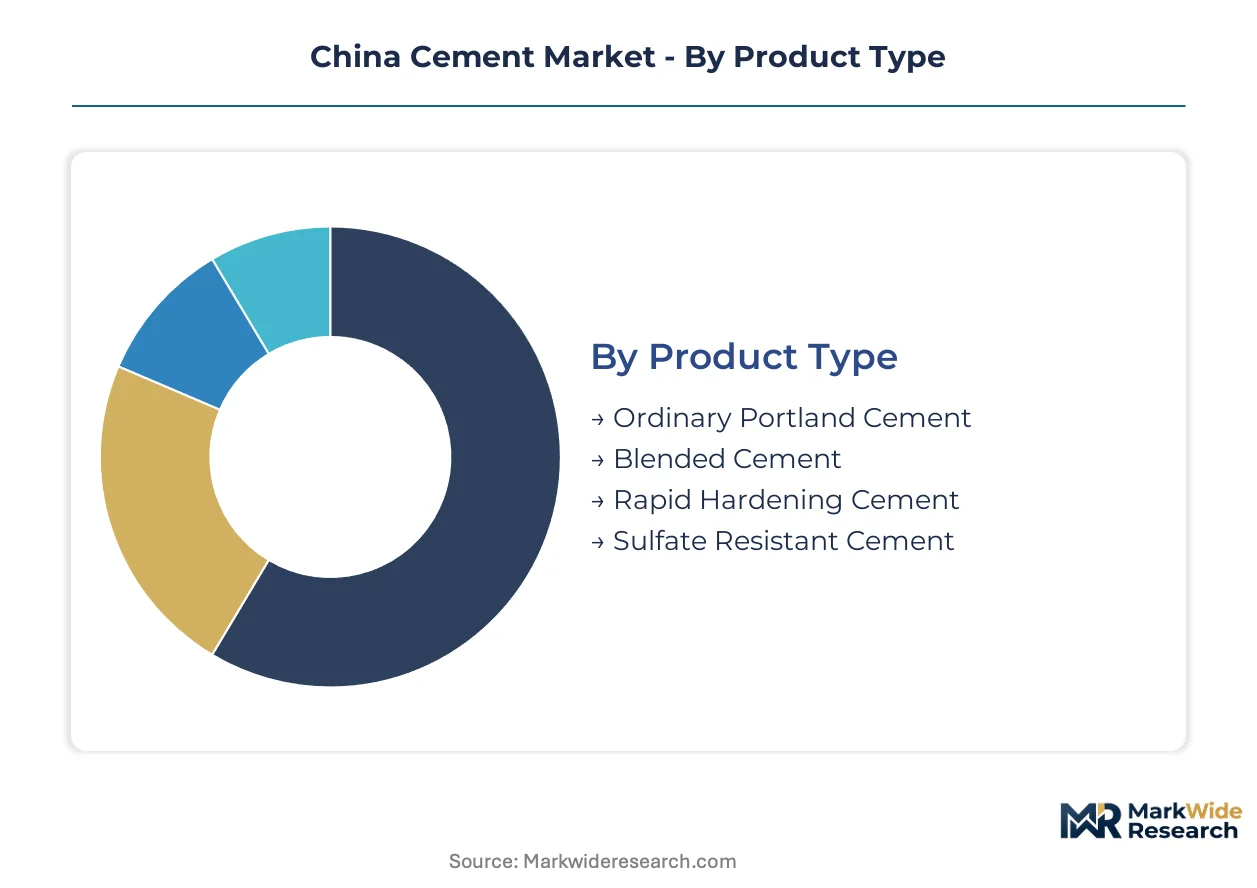
Cement segmentation in China tracks divergent technical specifications across infrastructure grades, procurement channel consolidation among state contractors, and carbon-intensity differentiation under tightening MEE enforcement. Each dimension carries distinct margin implications as dual carbon deadlines approach.
Product Type:
Construction specifications span load-bearing requirements, chemical exposure resistance, and embodied carbon limits that reshape formulation economics.
- Ordinary Portland Cement:High-clinker content delivers standardized compressive strength for general-purpose concrete. Yangtze River Delta infrastructure contractors specify this grade for conventional roadbed and foundation work despite margin pressure from carbon trading compliance costs.
- Blended Cement:Supplementary cementitious materials—slag, fly ash, limestone powder—replace clinker fractions to meet GB 175 carbon intensity ceilings. Public works tenders in Jiangsu and Zhejiang provinces now mandate blended formulations for state-backed megaprojects.
- Rapid Hardening Cement:Calcium aluminate clinker enables early strength development for emergency repair contracts and winter construction windows.
- Sulfate Resistant Cement:Low tricalcium aluminate content withstands aggressive groundwater exposure in coastal and chemical plant foundations.
The dominant share belongs to Ordinary Portland Cement, while Blended Cement is closing the gap fastest.
End User:
Customer archetypes separate volume-scale state procurement from fragmented private development with diverging specification stringency.
- Infrastructure:Belt and Road corridor construction, high-speed rail, and interprovincial highway networks concentrate bulk offtake through centralized state contractor panels. MEE emission verification requirements now gate supplier eligibility for these tenders.
- Residential Construction:Tier-one city permit slowdowns compress volume demand while tier-three and tier-four urbanization sustains moderate offtake for mid-rise concrete frame construction.
- Commercial Construction:Office and retail development tracks provincial GDP growth with delayed project completions in Guangdong and Fujian dampening near-term cement call-offs.
- Industrial Construction:Manufacturing facility foundations and heavy equipment pads require specialized sulfate-resistant and low-heat hydration formulations.
Infrastructure commands the largest volume position, though Residential Construction once held comparable share before regulatory tightening.
Distribution Channel:
Channel structure reflects the tension between bulk logistics efficiency for megaprojects and credit-extended trader networks serving fragmented demand.
- Direct Sales:Manufacturer-owned distribution terminals deliver bulk pneumatic tanker shipments to state construction group batching plants. Anhui Conch Cement and China National Building Material have expanded terminal coverage along Yangtze River barge routes to capture this channel.
- Wholesalers:Regional distributors extend trade credit to smaller contractors and retail builders in county-level markets, absorbing working capital requirements that integrated producers avoid.
- Retail:Bagged cement sales through construction material yards serve renovation and rural housing demand with higher per-ton margins offset by logistics fragmentation.
- Online:Digital procurement platforms aggregate small-lot orders for independent contractors, though bulk cement's logistics economics limit penetration.
Direct Sales generates the highest revenue concentration, with Wholesalers retaining critical reach into underpenetrated county markets.
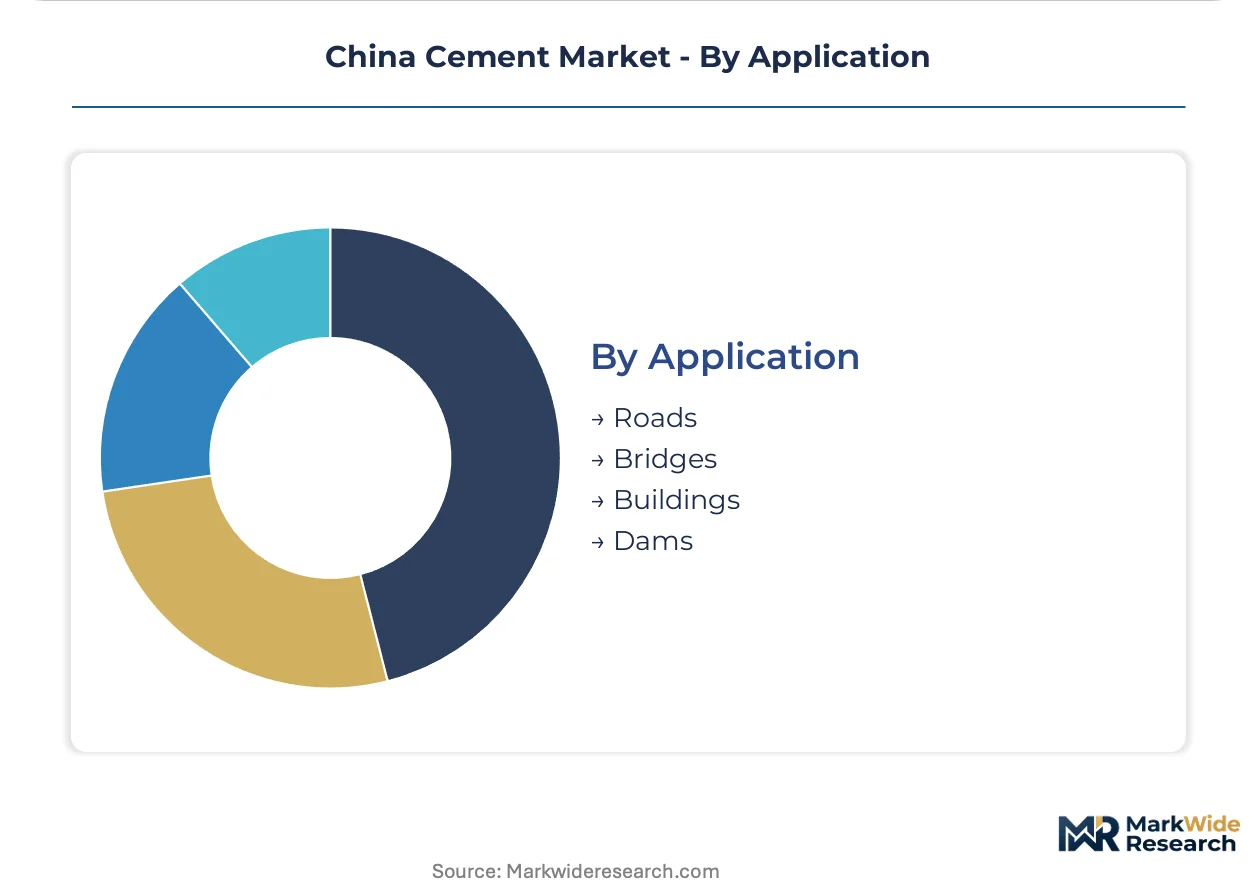
Application:
Structural use cases impose distinct performance specifications that filter back to clinker chemistry and grinding fineness requirements.
- Buildings:Vertical construction demands consistent workability and pumpability in ready-mix concrete for high-rise frame elements. GB standard revisions for building energy efficiency indirectly tighten cement quality tolerances.
- Roads:Pavement and subbase applications prioritize volume throughput and flexural strength development with less stringent chemical purity requirements than structural concrete.
- Bridges:Prestressed and post-tensioned concrete for long-span structures requires low-heat hydration cements to prevent thermal cracking during mass pours.
- Dams:Roller-compacted concrete specifications favor pozzolanic blends with extended setting characteristics for continuous placement operations.
Buildings absorbs the greatest tonnage, yet Infrastructure's road and bridge segments drive premium-grade demand expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across Chinese provinces. Infrastructure contractors in coastal clusters absorb premium-grade cement costs without volume reduction, while county-level residential builders in interior provinces shift rapidly to lower-specification alternatives when delivered prices rise.
Yangtze River Delta
Shanghai-Nanjing-Hangzhou infrastructure corridors sustain premium blended cement offtake for high-speed rail and interprovincial highway networks. MEE Jiangsu provincial dual carbon enforcement mandates clinker-to-cement ratio ceilings of 0.65 by 2026. Suzhou and Nantong manufacturing bases anchor low-carbon technology deployment through oxyfuel combustion pilot programs.
Pearl River Delta
Guangdong-Hong Kong-Macao Greater Bay Area construction drives demand for sulfate-resistant formulations in coastal foundation work. GB 175 standard revisions embed carbon intensity benchmarks into public works tender specifications. Shenzhen and Dongguan batching plants consolidate supplier panels around emission-verified producers with direct terminal access.
Beijing-Tianjin-Hebei
Capital region air quality targets compress kiln operating hours during winter heating seasons, constraining effective supply capacity. Hebei provincial environmental regulators enforce stricter NOx emission limits than national baselines. Tangshan clinker production clusters face accelerated retrofit requirements under 2025 dual carbon milestone enforcement.
Sichuan-Chongqing
Western province urbanization sustains volume demand for ordinary Portland cement in mid-rise residential construction. Chongqing municipal carbon trading scheme participation creates compliance cost differentiation among local producers. Chengdu manufacturing bases lag coastal emission standards, opening technology licensing opportunities for low-carbon kiln retrofits.
Shandong Peninsula
Jinan-Qingdao industrial construction drives specialized demand for rapid hardening cement in manufacturing facility foundations. Shandong provincial energy intensity targets accelerate alternative fuel substitution in legacy kiln operations. Weihai and Yantai coastal plants position for future CCUS integration through carbon capture retrofit readiness programs.
China Cement Market Competitive Landscape
Capability concentration sits with integrated producers commanding captive limestone reserves; scale advantage sits with consolidated platforms spanning multiple provincial markets. The market structure tiers between national champions with direct sales terminal networks and mid-scale producers dependent on wholesale distributor relationships. Two strategic archetypes dominate: vertically integrated resource owners and low-carbon formulation specialists. Competitive moves center on kiln technology licensing partnerships and industrial waste co-processing joint ventures that secure alternative fuel supply chains.
Within the national champion tier, China National Building Material occupies a position exemplifying consolidated platform scale across regional subsidiaries. Anhui Conch Cement anchors cost leadership through captive quarry access in eastern provinces. Huaxin Cement represents the low-carbon differentiation archetype, with product positioning structured around tightening MEE compliance requirements.
| Leading Market Players |
|---|
| China National Building Material |
| Anhui Conch Cement |
| China Resources Cement |
| West China Cement |
| Huaxin Cement |
| Jidong Cement |
| Taiheiyo Cement China |
| Shanshui Cement |
| Sinoma Cement |
| Others |
Pricing and Supply Chain Analysis
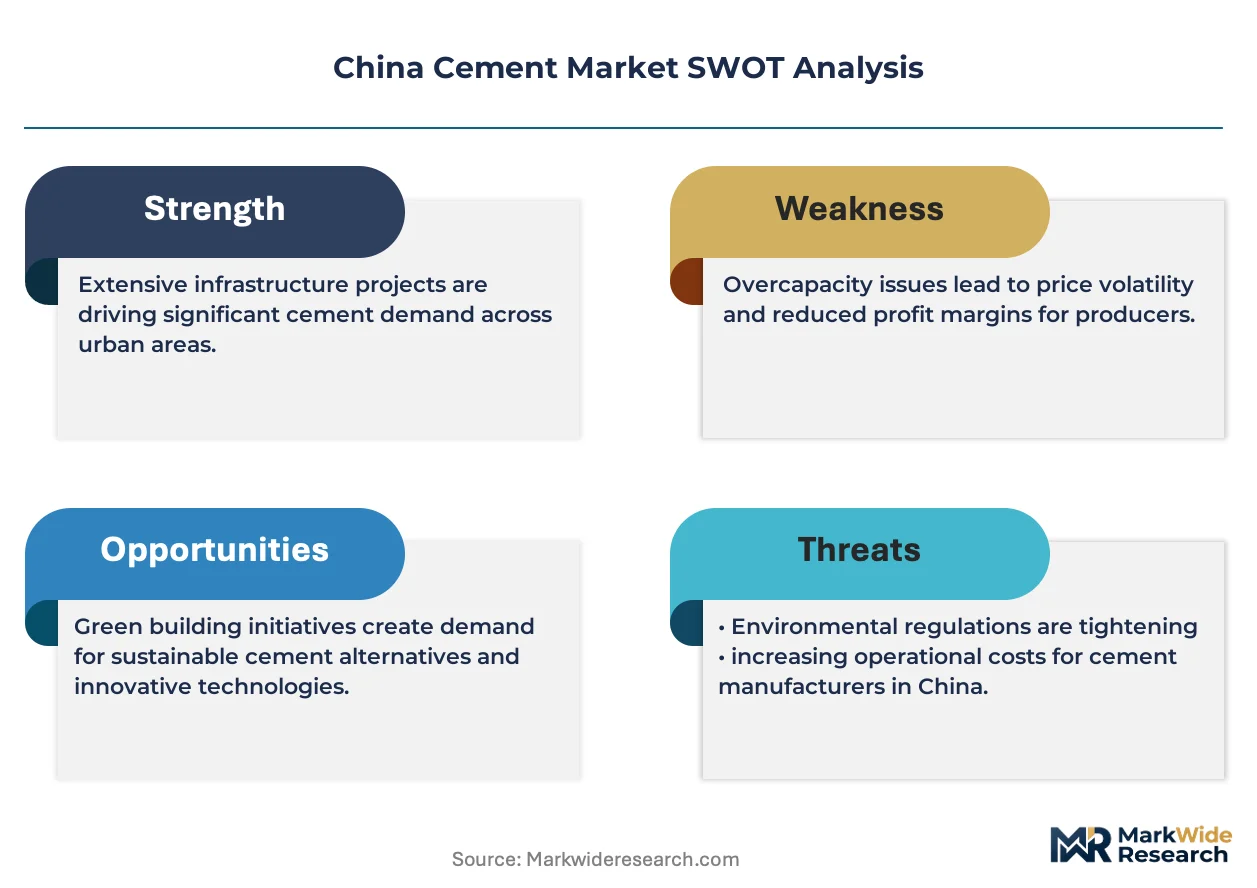
Overcapacity in northern Hebei kiln clusters compresses utilization rates below coastal benchmarks, forcing producers to absorb carbon compliance costs into thin margins while coastal operators capture pricing power through terminal network density.
Pricing Analysis
Long-term offtake contracts dominate bulk infrastructure procurement, with state construction groups locking in twelve-month supply agreements at fixed clinker-equivalent rates. Price differentiation separates emission-verified blended cement from standard-grade OPC, with MEE compliance certification commanding delivery premiums in Jiangsu tenders. Pricing pressure stems from carbon trading scheme participation costs that erode margins for high-clinker producers. County-level residential builders in Sichuan exhibit acute price sensitivity, shifting to lower-specification alternatives when delivered costs rise above threshold levels.
Supply Chain Analysis
Limestone feedstock draws from captive quarries concentrated in Anhui, Jiangsu, and Shandong provinces, with integrated producers commanding cost advantages through backward control over high-calcium reserves. Raw material procurement hinges on slag and fly ash sourcing partnerships for SCM blending, plus petcoke and coal alternatives for kiln fuel flexibility. Single-source vulnerability sits with Yangtze River barge corridors that handle bulk clinker movements from manufacturing bases to coastal terminals. Distribution runs through manufacturer-owned pneumatic tanker networks serving state batching plants, supplemented by credit-extended wholesaler relationships penetrating county-level markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market demands substitution defense against geopolymer and alkali-activated binders capturing specification share in high-durability infrastructure segments.
For Market Incumbents: Harden emission-verified product positioning through oxyfuel combustion licensing partnerships that lock in MEE compliance ahead of 2025-2027 milestone enforcement. Deepen captive limestone reserve control in western provinces where quarry access remains fragmented, insulating cost structures against carbon trading volatility.
For New Entrants and Emerging Players: Western province kiln replacement in Sichuan and Shaanxi manufacturing bases offers penetrable white space where emission standards lag coastal benchmarks. Municipal sludge co-processing joint ventures with waste management authorities open revenue streams alongside fuel cost reduction, bypassing capital-intensive clinker production entirely.
For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because SAMR concentration thresholds block organic growth pathways for mid-scale producers, positioning emission-compliant regional platforms as acquisition targets. Monitor clinker-to-cement ratio enforcement timelines as the inflection signal for margin compression severity across high-carbon incumbents.
| Strategic Initiative | Industry Significance |
|---|---|
| Oxyfuel Combustion Licensing | Positions Jiangsu and Zhejiang facilities for hydrogen kiln conversions under MEE dual carbon enforcement. |
| Industrial Waste Co-processing | Secures municipal sludge supply chains that reduce petcoke dependency while generating waste management fee revenue. |
| Captive Limestone Expansion | Anchors cost leadership in eastern provinces where high-calcium quarry access concentrates among integrated producers. |
| Blended Cement Formulation Partnerships | Locks in slag and fly ash sourcing for GB 175 compliance ahead of clinker ratio ceiling enforcement. |
| Direct Terminal Network Buildout | Displaces multi-layer trader networks for state contractor bulk procurement along Yangtze River barge routes. |
Research Methodology
Operator-level perspectives from kiln operations managers, state construction group procurement directors, provincial environmental regulators, and industrial waste co-processing specialists anchored the qualitative base for this analysis. Primary fieldwork combined with secondary validation through MEE enforcement circulars, GB standards documentation, SAMR merger review filings, and provincial dual carbon implementation timelines. Customs data on clinker trade flows, carbon trading scheme transaction records, and infrastructure tender specifications provided quantitative cross-checks. Bottom-up capacity modeling and top-down demand triangulation converged on segment-level outputs.
Scenario-bracketing framed the analytical approach, with volume and value outputs tested across emission enforcement stringency variants and alternative fuel substitution pace assumptions. Segmentation dimensions spanned product type, end user archetype, distribution channel structure, and regional production cluster. CAGRs derived from capacity utilization trajectories, kiln upgrade cycle timing, and infrastructure investment correlations. Clinker-to-cement ratio compliance pathways and carbon trading scheme participation rates served as industry-specific forecast inputs.
Practitioners should monitor MEE provincial milestone enforcement delays, SAMR concentration threshold adjustments, and geopolymer specification penetration for early signals requiring forecast revision. Cross-checking against infrastructure investment databases and provincial environmental disclosure filings is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Dutch Brick Market
Building Materials
India Construction Ornamental Stone Market
Building Materials
Roofing and Insulation Market
Building Materials
Commonwealth of Independent States (CIS) Building and Construction Sheets Market
Building Materials
Polymer-Modified Cementitious Mortar Market
Building Materials
Poland Architectural Coatings Market
Building Materials
Iron and Steel Slag Market
Building Materials
Stone Adhesive Market
Building Materials
Latin America Facade Market
Building Materials
US Facade Market
Building Materials
Canada Architectural Coatings Market
Building Materials
Global Lightweight Aggregate Concrete Market
Building Materials
East Africa Cement Market
Building Materials
Solar Control Window Film Market
Building Materials
Europe Cement Market
Building Materials
North America Engineered Stone Market