
 Europe Concrete Admixtures Market | 2026-2036
Europe Concrete Admixtures Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Concrete Admixtures Market Foresight
Commercial infrastructure developers is bifurcating from residential builders as the dominant buyer archetype for high-performance admixture formulations. Sika AG leverages its Swiss R&D footprint to dominate specialty superplasticizer supply for tunneling and bridge projects across the Alpine arc. MAPEI S.p.A. anchors Southern European demand through vertically integrated manufacturing in Italy and Spain, while BASF SE competes on polymer chemistry depth for self-compacting concrete applications.
Concrete admixtures are chemical formulations—typically lignosulfonates, polycarboxylate ethers, or naphthalene-based polymers—dosed at 0.5–5.0% by weight of cement to modify rheology, set time, or durability performance in fresh and hardened concrete. Their primary industrial purpose is enabling specified mechanical properties and placement characteristics under constrained site conditions or aggressive exposure classes. Superplasticizers command the deepest margin pools due to polymer complexity and specification stickiness in infrastructure tenders, while accelerating admixtures face commoditization pressure from regional blenders. The ready-mix delivery mode concentrates volume but packaged products capture higher per-kilogram returns from repair and renovation contractors.
The European Chemicals Agency's REACH framework governs substance registration and hazard communication for admixture raw materials, while the Construction Products Regulation mandates CE marking for declared performance in structural applications. Germany's KBA and France's ANSM do not regulate this sector directly, but national building codes transposed from Eurocode 2 enforce durability class requirements that drive admixture selection. Stakeholders must monitor how the EU's forthcoming revision to the Construction Products Regulation incorporates embodied carbon thresholds, as this will determine which polymer platforms retain specification access.
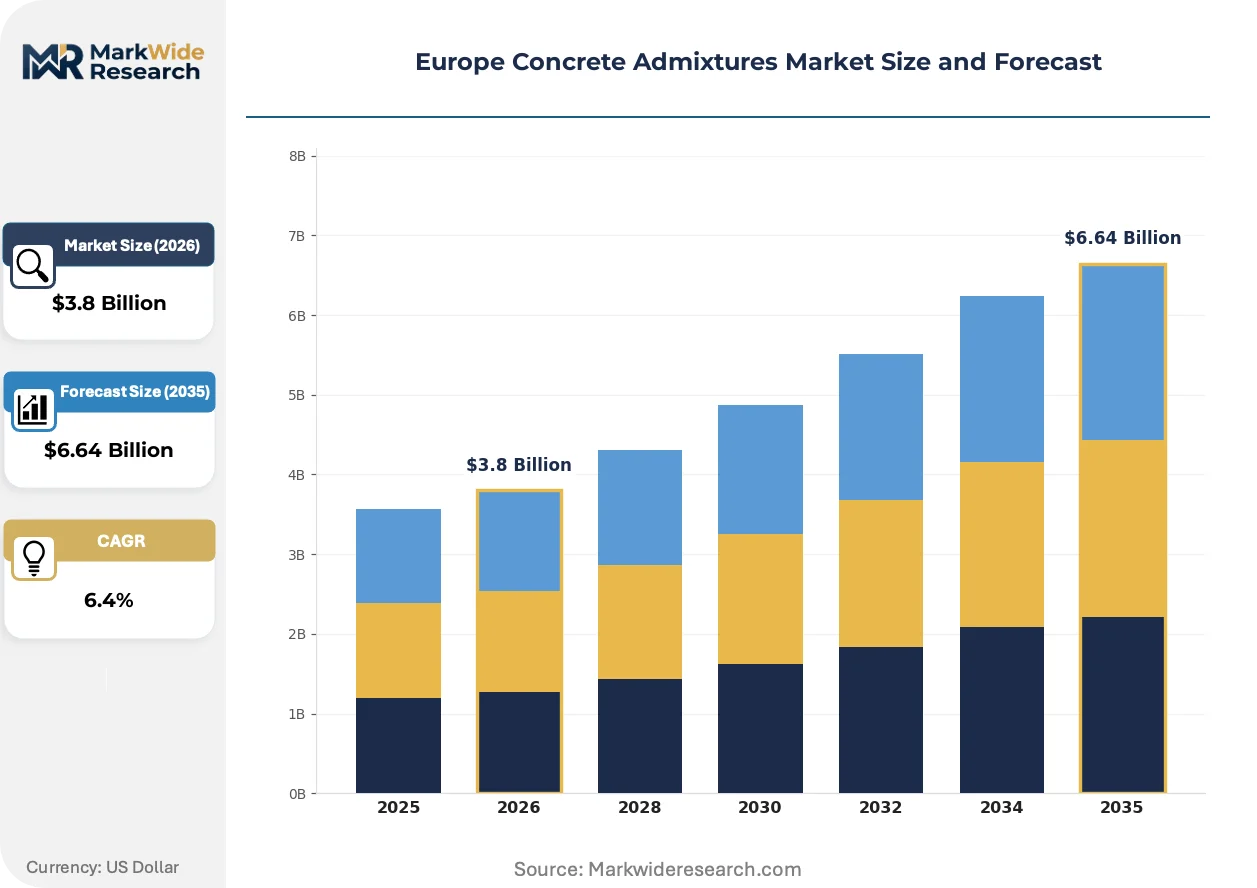
Market Dynamics
The EU Green Deal's embodied carbon benchmarks are compressing specification windows for conventional polymer platforms while elevating bio-based and low-carbon admixture chemistries in infrastructure tenders across the Rhine-Ruhr corridor.
Growth Catalysts
- CE marking under CPR:Mandatory declared performance for structural applications drives specification-grade admixture adoption in German and French public works.
- Tunneling activity in the Alpine arc:High-performance superplasticizer demand concentrates around Switzerland's Gotthard Base Tunnel extensions and Austrian Brenner Base Tunnel segments.
- Urban densification corridors:Self-compacting concrete specifications for vertical construction spread through Bavaria's Munich-Regensburg axis.
Market Restraints
- Naphthalene feedstock volatility:Crude oil derivative pricing swings compress margin stability for conventional superplasticizer producers.
- REACH registration costs:Small and mid-size blenders face substance dossier burdens that favor scaled chemical majors with existing ECHA portfolios.
- Substitute material encroachment:Supplementary cementitious materials including calcined clays and fly ash reduce admixture dosing requirements in low-carbon concrete mixes.
Strategic Opportunities
- Poland's infrastructure catch-up:EU cohesion fund absorption for road and rail projects creates specification-grade admixture demand outside established Western European saturation zones.
- CSRD-aligned carbon accounting:Corporate sustainability reporting mandates position low-embodied-carbon admixture platforms as differentiated procurement options.
- Digital dosing systems:IoT-enabled admixture metering at ready-mix plants enables performance-based service contracts displacing commodity volume sales.
Industry Challenges
- Polymer chemist scarcity:Formulation expertise gaps in polycarboxylate ether synthesis constrain R&D velocity for mid-tier producers.
- CE marking timeline compression:Factory production control audits and notified body assessments delay new product market entry by 12-18 months.
- Legacy batching equipment incompatibility:Older ready-mix plant infrastructure requires capital retrofitting to handle next-generation viscosity-modifying admixtures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Concrete Admixtures Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plasticizers, Superplasticizers, Retarding Admixtures, Accelerating Admixtures Application: Residential Construction, Commercial Infrastructure, Industrial Projects, Roads and Bridges End User: Contractors, Builders, Construction Firms, Precast Manufacturers Delivery Mode: Ready-Mix, On-Site Mixing, Bulk Delivery, Packaged Products |
| Companies Covered | Sika AG, MAPEI S.p.A, Fosroc, Inc., BASF SE, Saint-Gobain, CEMEX S.A.B de C.V., RPM International Inc., Chryso SAS, Ha-Be Concrete Chemicals GmbH, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Concrete Admixtures Market Shifts & Advancements
Formulation chemistry is pivoting toward bio-derived raw material streams as polymer science converges with carbon accounting requirements in European infrastructure procurement.
Polycarboxylate ether superplasticizers with tailored side-chain architectures are bifurcating specification access between premium infrastructure tenders demanding extended slump retention and commodity residential applications tolerating shorter workability windows. Alpine tunneling contractors specify high-range water reducers with 4-6 hour slump retention for continuous pour operations. This technical stratification is bifurcating supplier tiers into specification-locked specialty producers versus volume-commodity blenders.
REACH substance restriction proposals under ECHA's SVHC roadmap are tightening hazard classifications for certain naphthalene derivatives and lignosulfonate process streams. Admixture formulators face reformulation costs or raw material substitution to retain CE marking eligibility. Southern European producers with captive lignin supply from pulp and paper integration face disproportionate exposure to these reclassification proceedings.
Buyer concentration among pan-European ready-mix majors is consolidating procurement decisions into centralized technical committees. Regional blending operations lose specification influence as Heidelberg Materials and Holcim centralize admixture approval lists. Poland and Romania exhibit the most visible procurement consolidation effects as Western European majors acquire local concrete networks.
Europe Concrete Admixtures Market Segmentation
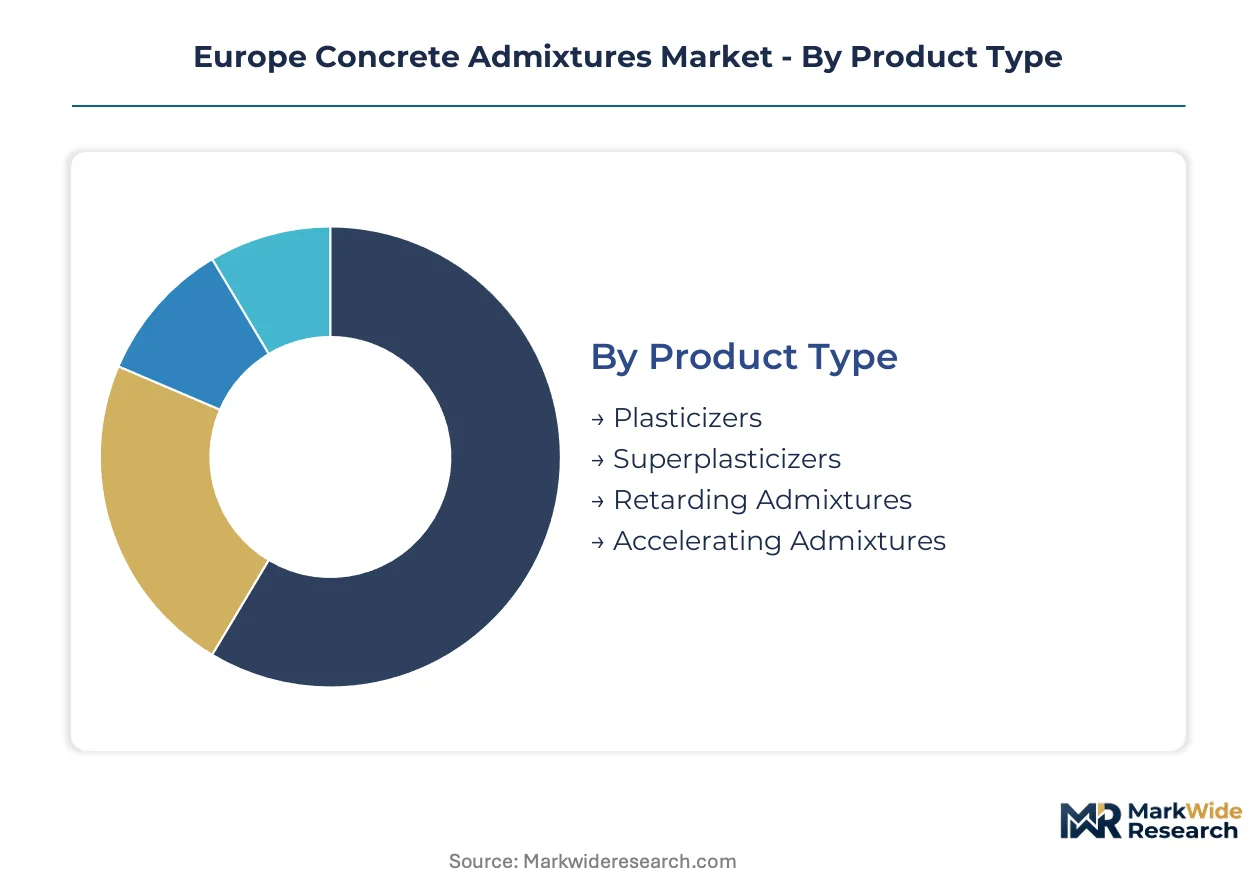
Concrete admixture suppliers configure product portfolios around specification intensity and logistics economics. Segment boundaries are blurring as infrastructure tenders demand multi-functional formulations combining rheology control with carbon performance.
Product Type:
Margin pools concentrate in polymer-intensive formulations where specification stickiness protects pricing power from commodity erosion.
- Plasticizers:Lignosulfonate and sulfonated naphthalene formulations reduce water demand by 5-12% in standard-grade concrete. Demand concentrates in Poland's residential construction recovery where cost-sensitive builders prioritize dosing economy over extended workability.
- Superplasticizers:Polycarboxylate ether platforms with tailored side-chain architectures enable 25-40% water reduction for self-compacting and high-strength specifications. Alpine tunneling contractors across Switzerland and Austria specify these for 4-6 hour slump retention in continuous pour operations, locking in premium procurement terms.
- Retarding Admixtures:Hydroxycarboxylic acid and sugar-based formulations delay set time for large-volume pours in hot-weather concreting across Southern Europe.
- Accelerating Admixtures:Calcium chloride and non-chloride rapid-set formulations face margin compression from regional blenders in Germany's repair and renovation segment.
The dominant share belongs to Superplasticizers, while Accelerating Admixtures is closing the gap fastest through cold-weather infrastructure schedules.
Application:
Application segments diverge sharply on specification complexity and carbon accounting stringency.
- Residential Construction:Standard-grade plasticizers dominate volume in multi-family housing across Bavaria and Baden-Württemberg, where builders prioritize placement speed over extended workability windows.
- Commercial Infrastructure:Self-compacting concrete specifications with polycarboxylate superplasticizers concentrate in Munich's vertical densification corridor and Frankfurt's high-rise cluster. CE marking requirements under the Construction Products Regulation drive specification-grade procurement decisions.
- Industrial Projects:Chemical-resistant and high-durability admixture blends serve manufacturing facility foundations in Belgium's Antwerp-Rotterdam port axis.
- Roads and Bridges:Freeze-thaw resistant formulations with air-entraining agents address exposure class requirements in Nordic climate zones.
Commercial Infrastructure commands the value concentration, yet Residential Construction is expanding most quickly through Poland's EU cohesion fund absorption.
End User:
End-user categories stratify by technical capability and procurement centralization.
- Contractors:Pan-European infrastructure specialists specify high-performance superplasticizers for public works tenders with embodied carbon benchmarks.
- Builders:Regional residential developers drive plasticizer volume through standardized mix designs with limited formulation variation.
- Construction Firms:Mid-tier generalists balance cost and performance across mixed project portfolios in France's regional cities.
- Precast Manufacturers:Automated batching operations demand consistent admixture performance for repetitive production cycles in Italy's precast hub around Bergamo.
Contractors retain the dominant procurement influence, while Precast Manufacturers are gaining specification voice through factory production control integration.
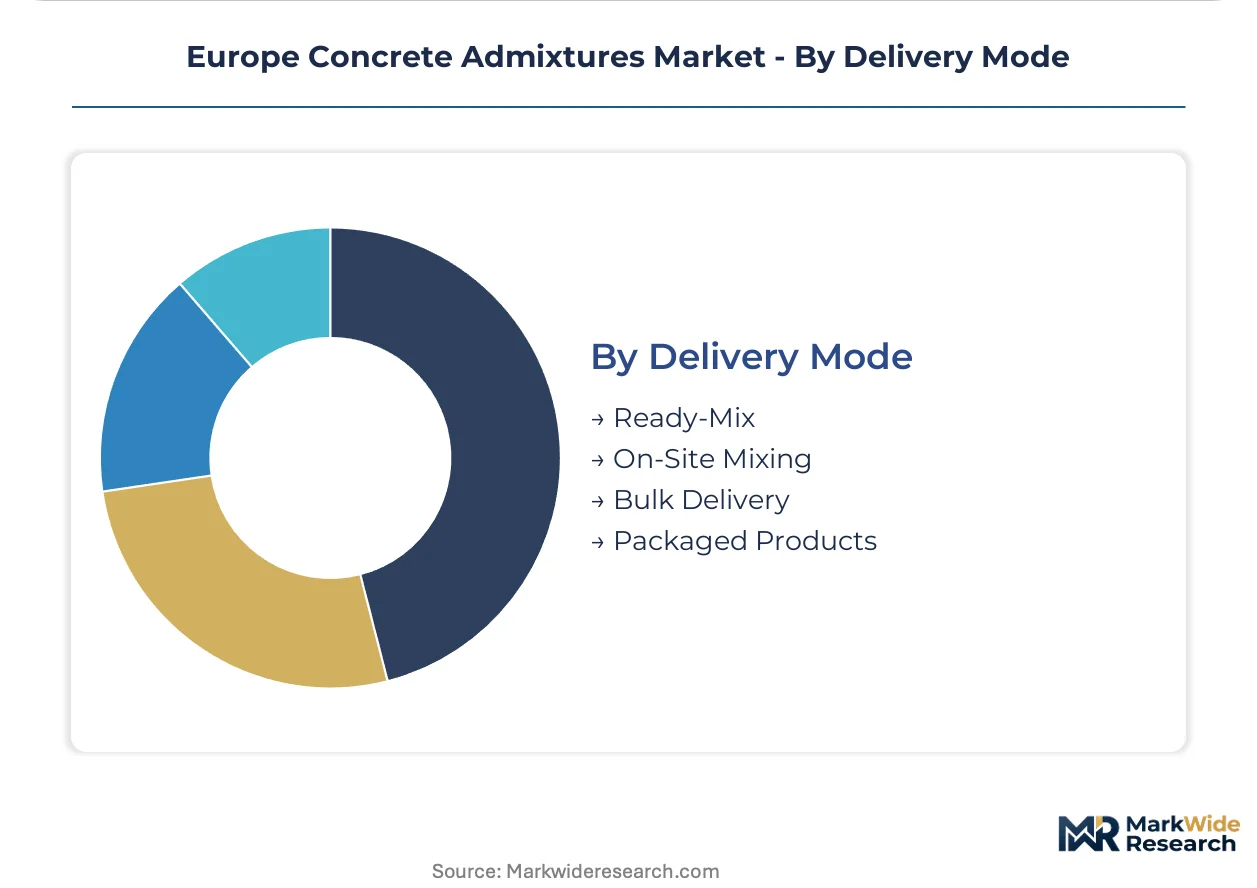
Delivery Mode:
Delivery economics separate volume-scale operations from value-capture opportunities.
- Ready-Mix:Centralized batching plants across Germany's Rhine-Ruhr corridor consume bulk superplasticizer deliveries with automated dosing systems.
- On-Site Mixing:Remote infrastructure projects in Austria's Alpine valleys require mobile admixture storage and manual dosing protocols.
- Bulk Delivery:Tanker shipments serve high-volume precast and ready-mix operations with dedicated storage infrastructure.
- Packaged Products:5-25 liter containers capture premium per-kilogram returns from repair contractors and small-batch renovators in urban renovation zones.
Ready-Mix dominates volume throughput, though Packaged Products is climbing the fastest through repair and renovation market fragmentation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Brenner Base Tunnel anchors Austria's strategic position, underwriting Alpine corridor connectivity while driving specification-grade admixture procurement for continuous pour operations across challenging geology.
Germany
Urban densification along the Munich-Regensburg axis and Rhine-Ruhr corridor sustains polycarboxylate superplasticizer demand for self-compacting concrete in high-rise and tunneling applications. CE marking under the Construction Products Regulation enforces declared performance standards for structural admixtures in federal infrastructure tenders. Bavaria's precast manufacturing cluster around Nuremberg integrates automated dosing systems for repetitive production cycles.
Switzerland
Gotthard Base Tunnel extensions and Alpine transit projects concentrate high-range water reducer procurement for extended slump retention in continuous concrete placement. Swissmedic and federal building codes enforce durability class requirements that favor specification-grade formulations over commodity alternatives. Zurich's technical universities collaborate with admixture developers on low-carbon polymer platforms.
Italy
Bergamo's precast manufacturing hub and Milan's vertical construction corridor drive demand for retarding and superplasticizer formulations in automated batching operations. ECHA's REACH framework governs substance registration for lignosulfonate process streams prevalent in Southern European production. MAPEI's vertically integrated manufacturing in Milan and Spain anchors regional supply security.
Poland
EU cohesion fund absorption for road and rail infrastructure creates specification-grade admixture demand outside Western European saturation zones. National transpositions of Eurocode 2 enforce durability requirements that displace ungraded blending operations in public works tenders. Warsaw and Kraków construction corridors concentrate ready-mix plant modernization for automated dosing compatibility.
France
Grand Paris Express tunneling and Lyon-Turin rail link segments sustain high-performance superplasticizer procurement for extended workability in mass concrete pours. ANSM and national building codes transposed from EU directives regulate structural admixture performance declarations. Île-de-France's ready-mix consolidation under Heidelberg Materials and Holcim centralizes procurement decisions into technical committees.
Europe Concrete Admixtures Market Competitive Landscape
Listed leaders compete with private specialists across polymer chemistry depth and specification access, producing a tiered structure where scale-driven majors anchor infrastructure tenders while regional blenders capture commoditized residential volume. Strategic archetypes separate into specification-locked specialty producers, vertically integrated construction material conglomerates, and regional blending operations serving cost-sensitive builders. Competitive moves concentrate on backward integration into raw material supply and geographic expansion through distributor networks in underpenetrated Eastern European markets.
Within the specialty chemical tier, Sika AG and BASF SE exemplify listed leaders with deep polymer science capabilities, while MAPEI S.p.A. represents private specialists with vertically integrated manufacturing footprints. These three anchors occupy positions across the premium specification spectrum, with Swiss and German origins reflecting historical concentration of construction chemical R&D in Alpine and Rhine-Ruhr industrial corridors.
| Leading Market Players |
|---|
| Sika AG |
| MAPEI S.p.A |
| Fosroc, Inc. |
| BASF SE |
| Saint-Gobain |
| CEMEX S.A.B de C.V. |
| RPM International Inc. |
| Chryso SAS |
| Ha-Be Concrete Chemicals GmbH |
| Others |
Supply & Pricing Matrix
Long-term offtake agreements between polycarboxylate ether producers and pan-European ready-mix majors lock in both feedstock access and price visibility across the Rhine-Ruhr corridor, insulating specification-grade suppliers from naphthalene derivative volatility while compressing margin flexibility for spot-market blenders.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates Alpine tunneling specifications from Bavarian residential volume. Premium tiers command price premiums for CE-marked polycarboxylate formulations with extended slump retention, while economy segments face cost compression from regional blenders in Poland's cohesion-funded infrastructure. Price differentiation hinges on certification grade and volume scale, with pan-European ready-mix majors extracting steep discounts through centralized procurement committees.
Supply Chain Analysis
BASF's Ludwigshafen polymer complex anchors European polycarboxylate ether supply, creating single-source vulnerability for mid-tier blenders lacking backward integration into ethylene oxide feedstock. Raw material dependencies center on crude oil derivatives, lignosulfonate process streams from Southern European pulp integration, and specialty amines for retarding formulations. Tariff exposure on Chinese naphthalene sulfonate imports compounds margin pressure. Distribution runs through bulk tanker networks serving automated ready-mix plants alongside packaged product channels for renovation contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe Concrete Admixtures Market tracks infrastructure investment cycles, with EU cohesion fund absorption in Eastern Europe and Alpine tunneling extensions providing cyclical uplift through the projection horizon.
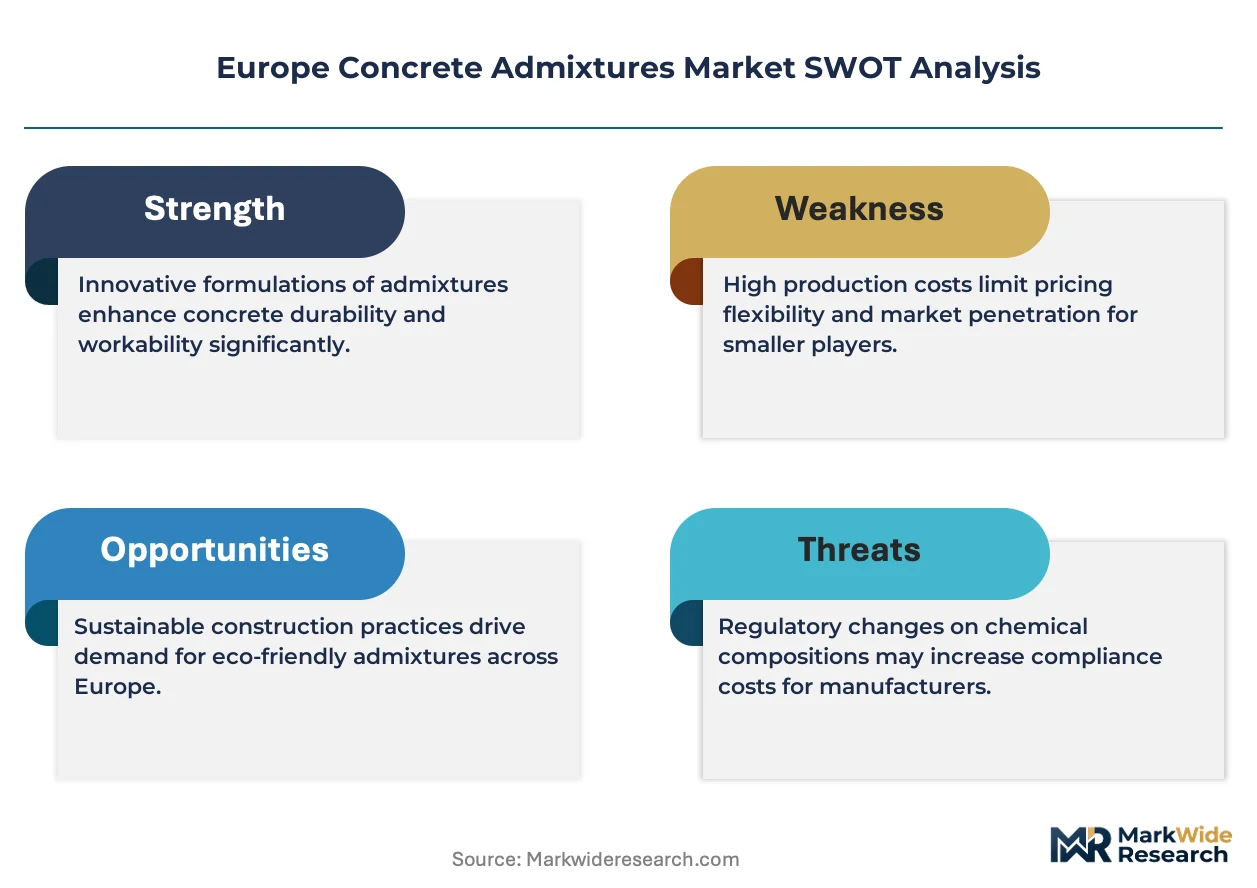
For Market Incumbents: Compound specification stickiness in Alpine infrastructure by deepening captive supply of bio-derived polymer platforms ahead of REACH SVHC reclassifications. Prioritize R&D investment in low-carbon admixture chemistries to defend margin position against supplementary cementitious material substitution in federal tenders. Extend automated dosing system partnerships to lock out regional blenders from CE-marked procurement lists.
For New Entrants and Emerging Players: Lead with digital dosing system integration as a service-based wedge into Poland's modernizing ready-mix sector, where legacy equipment incompatibility creates white-space for IoT-enabled performance contracts. Target Romania's consolidating concrete networks through distributor partnerships rather than direct specification battles with Sika and BASF. Emphasize carbon accounting transparency to differentiate against incumbent commodity volume plays.
For Investors and Strategic Acquirers: Regional blending operations with captive lignin supply and established distributor relationships in underpenetrated Eastern European markets represent the most defensible acquisition profile. Long-term viability rests on formulation chemistry depth rather than volume scale, given REACH registration cost barriers. Watch ECHA's SVHC roadmap progression as the signal for which polymer platforms retain specification access.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Ethylene Oxide | Captive feedstock supply insulates BASF and Sika from naphthalene derivative price volatility. |
| CE Marking Investment | Factory production control audits enable access to German federal infrastructure tenders under CPR. |
| Digital Dosing System Partnerships | IoT-enabled metering at Heidelberg Materials plants displaces commodity volume sales with performance contracts. |
| Bio-Derived Platform Development | Low-carbon polymer chemistry aligns procurement specifications with EU Green Deal embodied carbon benchmarks. |
| Eastern European Distributor Expansion | Local blending capacity in Poland and Romania captures EU cohesion fund infrastructure absorption outside Western saturation zones. |
Research Methodology
Cross-validation between primary interviews with admixture formulators, ready-mix plant managers, and infrastructure procurement officers anchors the qualitative findings against secondary validation from ECHA substance registrations, Cefic chemical industry reports, and Eurocode 2 national transposition documents. Bottom-up volume estimates from plant-level capacity assessments triangulate with top-down construction spend projections across the analysis window.
Sensitivity analysis around naphthalene feedstock price scenarios and REACH registration timeline assumptions shapes the forecast framework. Segmentation dimensions include product type tier, application exposure class, delivery mode logistics economics, and regional regulatory cluster. CAGRs derive from modeled construction output correlations and admixture intensity factors by specification grade.
The analysis sits within stated boundaries; outcomes outside sustained EU infrastructure spending levels or accelerated REACH substance restrictions would require recalibration. Practitioners should keep alternative scenarios live as ECHA's SVHC roadmap and Construction Products Regulation revision timelines evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Industrial Concrete Flooring Market
Building Materials
Commonwealth of Independent States (CIS) Building and Construction Sheets Market
Building Materials
Asia-Pacific Kinetic Tiles Market
Building Materials
Concrete Reinforcing Fiber Market
Building Materials
US Cement Tiles Market
Building Materials
Concrete Admixtures Market
Building Materials
Door Frame Metal Market
Building Materials
North America Architectural Coatings Market
Building Materials
Asia-Pacific Cement Market
Building Materials
Fly Ash Bricks Market
Building Materials
Asia-Pacific Building and Construction Sheets Market
Building Materials
United Kingdom White Cement Market
Building Materials
Qatar Cement Market
Building Materials
India Concealed Cistern Market
Building Materials
United States White Cement Market
Building Materials
Acoustic Damping Tiles Market