
 Light Gauge Steel Framing Market | 2026-2036
Light Gauge Steel Framing Market Size, Share, and Industry Trends Forecast 2026-2036
Light Gauge Steel Framing Market Intelligence
The EU Green Deal is recalibrating material specifications across European construction supply chains, compelling steel framing suppliers to document lifecycle emissions and circularity credentials. Nucor Building Systems leverages its electric arc furnace network to produce lower-carbon steel sections for North American projects. ArcelorMittal S.A. anchors European supply through integrated mills offering Environmental Product Declarations compliant with CSRD disclosure rules. Tata BlueScope Steel Limited dominates Oceania and Southeast Asian distribution with coated steel products engineered for humid climates.
Light gauge steel framing comprises cold-formed steel sections manufactured from galvanized sheet steel typically 0.5 to 2.5 millimeters thick, shaped through roll-forming or press-braking into C-studs, U-tracks, and proprietary profile shapes designed to carry structural and non-structural loads in wall, floor, and roof assemblies. Studs and track categories occupy the highest volume share in residential and commercial applications where repetitive framing geometries favor standardized section libraries. Joist segments are gaining traction in mid-rise construction as engineers specify deeper profile depths to achieve longer clear spans without intermediate supports.
FEMA and the International Code Council in the United States enforce seismic and wind-load standards that dictate steel gauge minimums and connection detailing, directly influencing product design and regional stocking patterns. China's GB standards and Ministry of Housing and Urban-Rural Development directives govern prefabricated steel construction quality, creating compliance barriers for imported framing systems. India's BIS certification requirements for structural steel products are tightening, affecting market entry timelines for foreign suppliers. Stakeholders must monitor evolving embodied carbon regulations and building code harmonization across target jurisdictions to align certification investments with demand trajectories.
Market Dynamics
Prefabricated modular construction is compressing project timelines and reshaping procurement patterns across residential and commercial verticals, forcing steel framing suppliers to reconfigure production workflows around just-in-sequence delivery models rather than traditional batch manufacturing.
Growth Catalysts
- EU Green Deal embodied carbon mandates:The EU Green Deal's tightening thresholds for construction materials are compelling developers to specify recycled-content steel framing systems with documented Environmental Product Declarations.
- Seismic code upgrades in California:FEMA and ICC seismic provisions are mandating higher-gauge steel sections and enhanced connection detailing in multi-story residential construction across high-risk zones.
- Prefabrication clusters in China's tier-one cities:Shenzhen and Shanghai construction authorities are fast-tracking approvals for modular steel-frame buildings, accelerating demand for standardized cold-formed sections.
Market Restraints
- Zinc-coated sheet steel price volatility:Galvanized coil input costs fluctuate with energy-intensive smelting economics, compressing margin predictability for roll-forming operations.
- Regional mill concentration:Domestic electric arc furnace capacity constraints in the United States create supply bottlenecks during construction seasonality peaks.
- Dimensional tolerance limitations:Cold-forming processes impose strict gauge-to-depth ratios that restrict profile optimization for long-span floor assemblies.
Strategic Opportunities
- India's affordable housing vertical:PMAY-Urban subsidies and BIS certification streamlining are opening volume pathways for imported light-gauge systems in multi-story residential projects.
- Building-integrated photovoltaics convergence:Steel framing manufacturers partnering with BIPV module suppliers can capture rooftop energy retrofit demand through pre-wired structural assemblies.
- Direct-to-contractor digital platforms:E-procurement channels are bypassing traditional distributor markups in Australia's residential renovation segment, enabling margin capture for mill-direct suppliers.
Industry Challenges
- Certification timeline compression:India's BIS structural steel product approvals now require extended third-party testing cycles, delaying market entry for new foreign suppliers by 8-14 months.
- Legacy BIM integration friction:Cold-formed steel proprietary profile libraries lack standardization across Revit and Tekla platforms, forcing fabricators to maintain duplicate digital assets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Light Gauge Steel Framing Market |
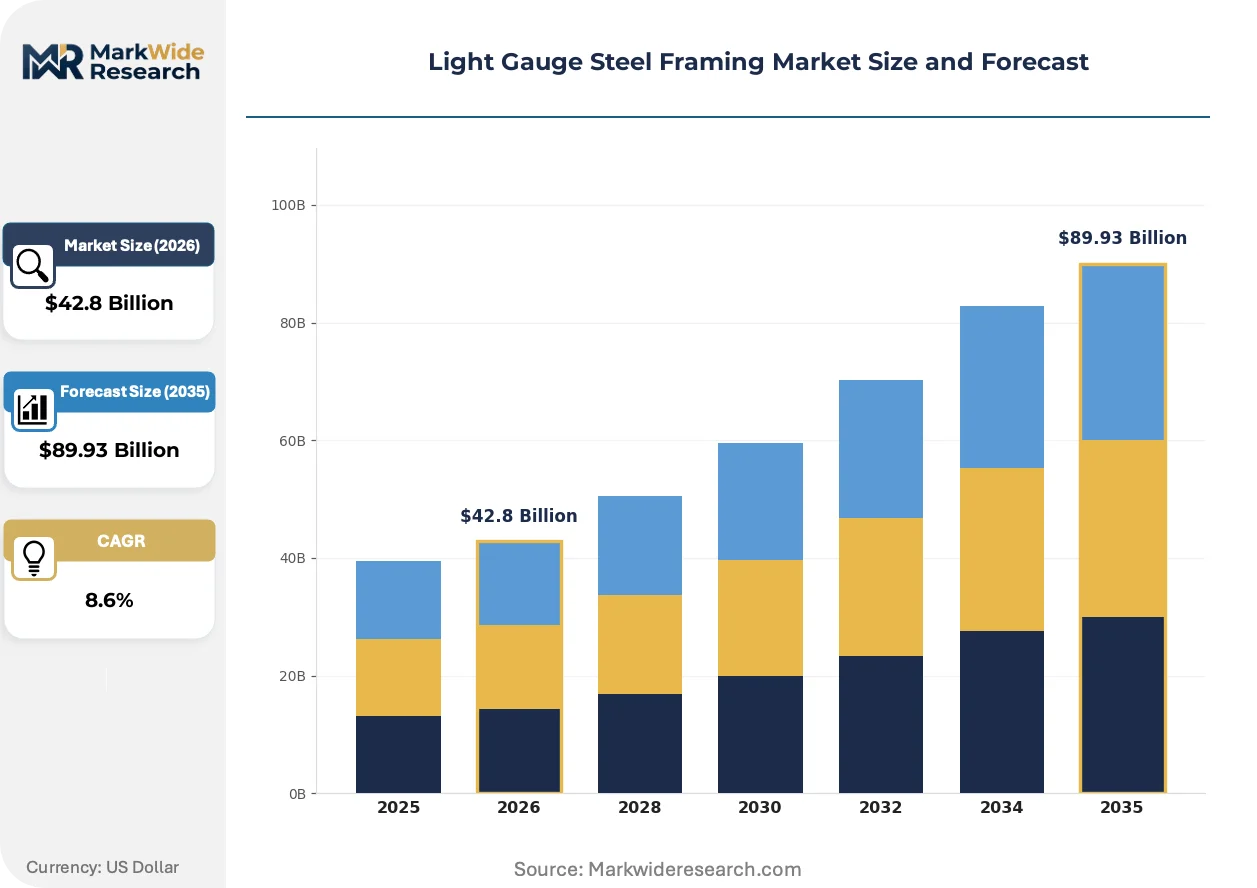
| Market Size in 2026 | $42.8 Billion |
| Market Size in 2035 | $89.93 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Studs, Track, Bracing, Joists Application: Residential Construction, Commercial Buildings, Industrial Structures, Infrastructure Projects End User: Contractors, Architects, Builders, Engineers Delivery Model: Direct Sales, Online Distribution, Retail Outlets, Wholesale |
| Companies Covered | Hadley Industries Ltd., Nucor Building Systems, ArcelorMittal S.A., CEMCO, Precision Walls Inc., ClarkDietrich Building Systems, Jinggong Steel, Tata BlueScope Steel Limited, FRAMECAD Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Light Gauge Steel Framing Market Strategic Shifts & Innovations
Digital fabrication workflows and material traceability systems are converging to transform how steel framing is specified, manufactured, and assembled on job sites. Three developments are compressing traditional supply chain structures.
Building information modeling is integrating with automated roll-forming equipment to enable parametric profile generation from structural engineering files. Mid-rise developers in Texas and Florida are adopting this workflow to eliminate manual takeoff errors and reduce field cutting waste. The technology is integrating design-to-fabrication data flows, collapsing the traditional 4-6 week detailing-to-delivery cycle into sub-10-day turnarounds for repetitive framing geometries.
REACH chemical disclosure requirements and the EU Construction Products Regulation are mandating digitized material passports for steel products sold in European member states. Manufacturers must now tag each production batch with smelter origin, recycled content percentage, and coating chemistry. German and Dutch housing associations are prioritizing suppliers with compliant digital documentation, creating procurement preference hierarchies that exclude non-compliant imports.
Design-build contracting consolidation is compressing specification authority into fewer decision-makers per project. Large multifamily developers in Atlanta and Phoenix are consolidating framing procurement under single-source agreements with pre-qualified fabricators, displacing the traditional fragmented bidding process. This concentration is most visible in the 4-12 story residential segment, where repeat-builder relationships now lock in 2-3 year supply commitments with volume pricing mechanisms.
Light Gauge Steel Framing Market Segmentation
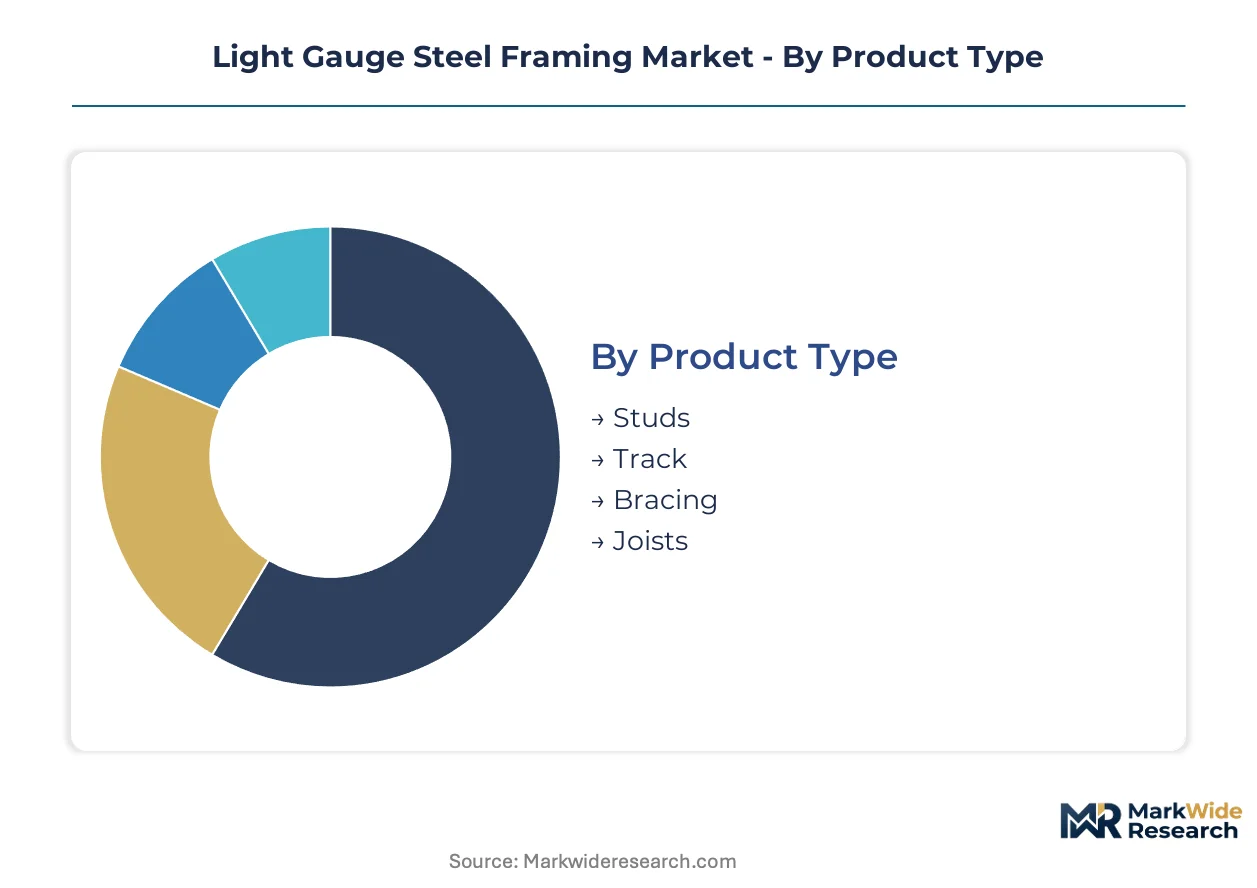
Segmentation in light gauge steel framing reveals how procurement authority, fabrication technology, and project delivery methods concentrate value across distinct supply chain tiers. Understanding these splits helps suppliers align inventory investments with where specification decisions actually occur.
Product Type:
Roll-forming capacity concentrates disproportionately in studs and track production, creating margin pressure in commoditized sections while specialized profiles retain pricing power.
- Studs:Cold-formed C-sections manufactured from galvanized coil in 0.5-1.6mm gauges serve as vertical load-bearing elements in wall assemblies. Demand concentrates in United States residential construction where FEMA seismic codes mandate minimum 18-gauge thickness in high-risk zones, compressing supply during California building season peaks.
- Track:U-shaped channels provide top and bottom plates for stud wall systems, with repetitive geometries favoring high-volume continuous roll-forming operations. Procurement in China's tier-one cities is accelerating as Shenzhen and Shanghai modular construction clusters standardize on 50mm and 64mm base widths for prefabricated panel factories.
- Bracing:Diagonal strap and flat-strap tension members stabilize lateral loads in shear wall assemblies, typically fabricated from wider coil widths with punched connection patterns.
- Joists:Deeper profile sections enable longer clear spans in floor assemblies, with engineers specifying proprietary web-stiffened geometries for mid-rise residential projects in Texas and Florida.
Today's leader: Studs. Tomorrow's challenger: Joists.
Application:
Project scale and code complexity fragment demand across construction verticals, with residential volume competing against commercial margin premiums.
- Residential Construction:Single-family and multifamily housing absorbs standardized framing packages through repetitive unit designs. Fire-resistant steel substitution for lumber is accelerating across United States sunbelt markets where insurance premiums on wood-frame construction are climbing fastest.
- Commercial Buildings:Office, retail, and hospitality projects specify engineered framing systems with documented seismic performance. EU Green Deal embodied carbon thresholds are filtering procurement toward mills with Environmental Product Declarations in German and Dutch commercial developments.
- Industrial Structures:Warehousing and manufacturing facilities prioritize long-span capabilities and rapid enclosure, favoring deeper joist profiles and pre-engineered metal building integration.
- Infrastructure Projects:Transportation and utility applications require corrosion-resistant coatings and specialized connection hardware for exposed or buried service conditions.
Residential commands current volume. Commercial delivers margin expansion.
End User:
Specification authority is consolidating under fewer decision-makers per project as design-build contracting displaces fragmented bidding.
- Contractors:General and specialty contractors control procurement timing and inventory staging, with large multifamily developers in Atlanta and Phoenix locking in multi-year supply agreements with pre-qualified fabricators.
- Architects:Design professionals influence material selection through BIM-integrated specification libraries, though legacy friction between Revit and Tekla platforms complicates cold-formed steel profile standardization.
- Builders:Production homebuilders leverage direct mill relationships to bypass distributor markups, particularly in Australia's renovation segment where e-procurement channels are compressing traditional supply tiers.
- Engineers:Structural engineers dictate gauge minimums and connection detailing through seismic and wind-load calculations, directly shaping regional stocking patterns for roll-forming operations.
Contractors hold procurement leverage. Engineers retain technical gatekeeping.
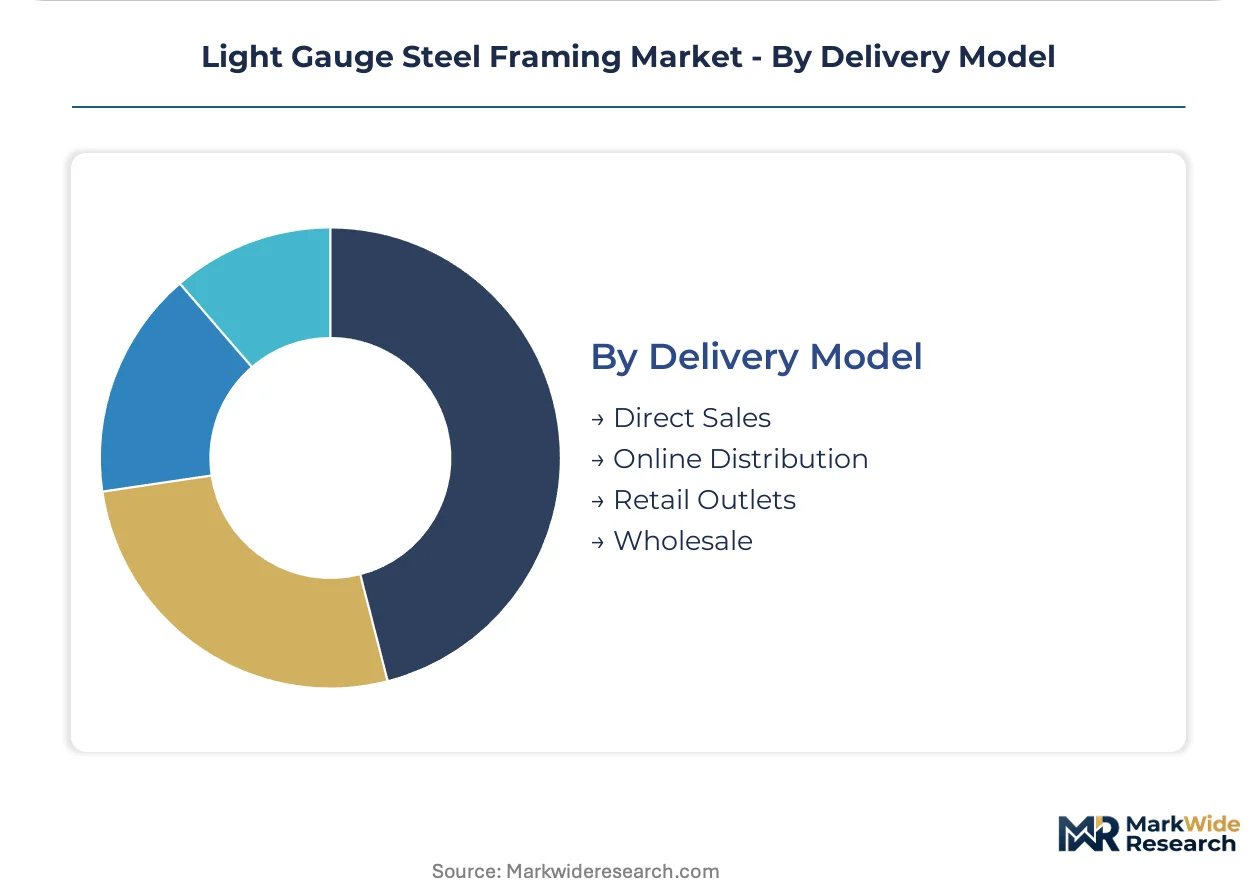
Delivery Model:
Channel structure determines margin capture, with digital intermediaries disrupting traditional distributor economics in fragmented renovation markets.
- Direct Sales:Mill-direct relationships lock in volume commitments and just-in-sequence delivery for large developers, collapsing the traditional 4-6 week detailing-to-delivery cycle through parametric fabrication workflows.
- Online Distribution:Digital platforms are bypassing traditional markups in Australia's residential renovation segment, enabling margin capture for suppliers with standardized product data and rapid quoting capabilities.
- Retail Outlets:Big-box and specialty building material retailers serve small contractors and repair markets with cut-to-length services and immediate availability.
- Wholesale:Regional distributors maintain buffer inventory for construction seasonality, though electric arc furnace capacity constraints in the United States create periodic supply bottlenecks during peak demand windows.
Direct sales dominate project volume. Online channels are expanding fastest in renovation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Light gauge steel framing originated in post-war North American construction as a fire-resistant alternative to timber, then scaled through Japanese manufacturing precision and Chinese prefabrication clusters. Demand geography now tracks seismic code stringency, embodied carbon regulation, and modular construction adoption.
United States
California's seismic retrofit mandates and Florida's wind-load codes drive specification of higher-gauge sections in multi-story residential. FEMA and ICC provisions enforce connection detailing standards that shape regional mill stocking patterns. Atlanta and Phoenix developers consolidate procurement under single-source fabricator agreements for 4-12 story projects.
China
Shenzhen and Shanghai construction authorities fast-track approvals for modular steel-frame buildings, accelerating demand for standardized cold-formed sections. GB standards and Ministry of Housing directives govern prefabricated quality, creating compliance barriers for imported systems. Yangtze River Delta panel factories standardize on 50mm and 64mm track base widths.
Germany
REACH chemical disclosure and EU Construction Products Regulation mandate digitized material passports with smelter origin and recycled content data. Dutch and German housing associations prioritize suppliers with compliant Environmental Product Declarations. Ruhr Valley integrated mills anchor European supply through CSRD-aligned disclosure frameworks.
India
PMAY-Urban subsidies for affordable housing open volume pathways for imported systems in multi-story residential projects. BIS certification requirements for structural steel products now require extended third-party testing cycles. Maharashtra and Gujarat construction corridors absorb standardized framing packages through repetitive unit designs.
Australia
E-procurement channels bypass traditional distributor markups in residential renovation, enabling margin capture for mill-direct suppliers. Queensland and New South Wales humid climates drive specification of coated steel products with enhanced corrosion resistance. Sydney and Melbourne developers leverage direct fabricator relationships for just-in-sequence delivery.
Light Gauge Steel Framing Market Key Industry Players
Premium-margin players sit above commodity-margin players across certification depth and digital integration capabilities. The vendor base separates into integrated steel producers with captive coil supply, specialized roll-forming fabricators with regional distribution networks, and technology licensors enabling parametric design-to-fabrication workflows. Dominant competitive moves include backward integration into electric arc furnace capacity and strategic partnerships with BIM platform providers to collapse detailing-to-delivery cycles.
Among integrated steel producers, ArcelorMittal S.A. and Nucor Building Systems exemplify the premium-tier archetype through Environmental Product Declaration compliance and low-carbon production positioning. Tata BlueScope Steel Limited occupies a specialized position serving humid-climate markets with coated product formulations. FRAMECAD Ltd. represents the technology-licensor vector, enabling digital fabrication workflows without direct manufacturing exposure.
| Leading Market Players |
|---|
| Hadley Industries Ltd. |
| Nucor Building Systems |
| ArcelorMittal S.A. |
| CEMCO |
| Precision Walls Inc. |
| ClarkDietrich Building Systems |
| Jinggong Steel |
| Tata BlueScope Steel Limited |
| FRAMECAD Ltd. |
| Others |
Cost & Logistics Intelligence
Certification-grade bifurcation between EPD-documented low-carbon steel and commodity galvanized coil creates divergent margin structures across procurement tiers, with EU Green Deal compliance costs embedding premium pricing in German and Dutch supply chains while spot-market volatility compresses margins in undifferentiated North American roll-forming operations.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the market by embodied carbon documentation and seismic performance ratings. Price differentiation hinges on Environmental Product Declaration availability and FEMA seismic code compliance tier, with California and Florida buyers absorbing gauge-thickness premiums for multi-story residential applications. Cost compression in economy-grade coil feedstock is intensifying because zinc-coated sheet steel prices fluctuate with energy-intensive smelting economics. Small contractors and renovation specialists exhibit highest price sensitivity, while design-build consolidators in Atlanta and Phoenix lock in volume pricing through multi-year fabricator agreements.
Supply Chain Analysis
Skilled roll-forming technician shortages in the United States Rust Belt and Yangtze River Delta constrain capacity expansion timelines for precision cold-forming operations. Geographic supply concentration centers on China, the United States, and Germany, with integrated mills in each region controlling captive electric arc furnace output. Raw material dependencies rest on galvanized coil from integrated steel producers, zinc ingot for coating chemistry, and specialized roll-forming tooling from Japanese and German equipment suppliers. Single-source vulnerability around electric arc furnace capacity in the United States creates seasonal bottlenecks during construction peaks. Distribution runs through mill-direct relationships for large developers, regional wholesalers for buffer inventory, and emerging digital platforms in Australia's renovation segment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Light gauge steel framing functions as a stable compounder anchored by regulatory ratcheting on embodied carbon and seismic performance that perpetually upgrades specification minimums across major construction markets.
For Market Incumbents: To counter margin erosion from zinc-coated coil price volatility, deepen backward integration into electric arc furnace capacity near high-demand construction corridors, and fortify specification authority by embedding proprietary profile libraries directly into Revit and Tekla BIM platforms to collapse competitor access to design-phase influence. For New Entrants and Emerging Players: Launch via e-procurement channels targeting Australia's fragmented residential renovation segment, where distributor markups remain vulnerable to mill-direct digital disruption. India's PMAY-Urban affordable housing vertical offers the most penetrable volume pathway, particularly in Maharashtra and Gujarat construction corridors where BIS certification streamlining is accelerating. Prioritize just-in-sequence delivery capabilities to match Shenzhen and Shanghai modular panel factory procurement rhythms. For Investors and Strategic Acquirers: Asymmetric upside sits with technology-licensor archetypes enabling parametric design-to-fabrication workflows without direct manufacturing exposure, particularly those with established BIM platform partnerships. Long-term viability favors assets with defensible positions in low-carbon steel production and digital material passport compliance. Watch for inflection when EU member states mandate digitized batch-level traceability as a procurement gate for housing association contracts.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into EAF Capacity | Captive coil supply insulates margin from zinc price volatility and construction seasonality peaks. |
| BIM Platform Partnership | Direct Revit and Tekla integration locks specification authority before competitive bidding begins. |
| EPD Certification Investment | EU Green Deal compliance creates procurement preference hierarchies excluding non-documented imports. |
| Just-in-Sequence Delivery Capability | Shenzhen and Shanghai modular factories prioritize suppliers matching compressed panel assembly timelines. |
| Digital Material Passport Deployment | REACH and EU Construction Products Regulation mandate batch-level traceability for market access. |
Research Approach
Multiple input streams — executive interviews with roll-forming operations managers, procurement leads at design-build consolidators, structural engineering specification directors, and BIM platform integration specialists — were reconciled against customs data for galvanized coil trade flows, FEMA and ICC code documentation, EU EPD registry filings, and SEC disclosures from integrated steel producers. Bottom-up project pipeline analysis across residential, commercial, and industrial verticals was cross-validated with top-down construction spending forecasts from national statistical agencies.
Historical capacity utilization patterns and panel manufacturer order backlogs were cross-referenced against expert panel assessments of prefabrication adoption trajectories across the analysis window. Segmentation modeling incorporated product type, application vertical, end-user procurement authority, and delivery channel structure, with CAGRs derived from regression analysis of construction output correlations and steel framing penetration rates. Industry-specific inputs included electric arc furnace operating rates, modular construction permit velocity in China's tier-one cities, and BIS certification timeline compression effects on import market entry.
Several conditions sit outside the modeled scope, including abrupt tariff restructuring on steel coil trade, unanticipated relaxation of seismic code stringency in high-risk zones, and breakthrough displacement of cold-formed steel by mass timber in mid-rise residential applications. Forecasts reflect assumptions regarding regulatory ratcheting continuity and construction labor availability. Material deviation in zinc price volatility extremes, electric arc furnace capacity expansion delays, or modular construction policy reversals in China warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Indonesia Dry Mix Mortar Market
Building Materials
Europe Acrylic Resin Dispersion Based Primers in Construction Market
Building Materials
South Africa White Cement Market
Building Materials
Global White Cement Market
Building Materials
North America Cement Market
Building Materials
Concrete and Cement Market
Building Materials
Concrete Blocks and Bricks Market
Building Materials
Qatar Facade Market
Building Materials
Ductile Iron Pipe Market
Building Materials
Precast Concrete Retaining Walls Market
Building Materials
Cement Board Market
Building Materials
Composite Decking and Railing Market
Building Materials
GRC Cladding Market
Building Materials
US Commercial Paving Slabs Market
Building Materials
Geocells Market
Building Materials
Building and Construction Plastics Market