
 Roofing and Tile Underlayment Market | 2026-2036
Roofing and Tile Underlayment Market Size, Share, and Industry Trends Forecast 2026-2036
Roofing and Tile Underlayment Market Analysis
Southeast Asia is reconfiguring regional supply dynamics as Vietnam and Indonesia expand fiberglass mat production for underlayment substrates. Owens Corning leverages its integrated fiberglass supply chain to dominate North American synthetic underlayment output. GAF Materials Corporation anchors residential distribution through contractor-exclusive channel programs. Johns Manville sustains technical leadership in high-temperature modified bitumen formulations for commercial membranes.
Roofing and tile underlayment comprises water-resistant or waterproof barrier materials installed beneath primary roof coverings to prevent moisture infiltration and manage condensation, typically manufactured through saturated felt processing, polymer extrusion, or nonwoven synthetic mat formation with specified permeance ratings between 5 and 20 perms. Synthetic underlayment manufactured from polyethylene and polypropylene dominates value creation due to superior UV stability and walkability during installation compared to traditional organic felt. Residential application generates the largest volume base, though commercial membrane specifications command premium pricing through longer warranty terms and stricter fire-resistance certifications. Fiberglass-reinforced asphalt shingles retain mature market share in North American re-roofing cycles while metal sheet retrofits accelerate fastest in regions adopting stringent wind-uplift codes.
FEMA building codes in hurricane-prone US counties mandate enhanced underlayment fastening patterns and self-adhered ice dam protection layers, directly elevating material specifications above baseline ASTM D226 requirements. The EPA's Energy Star roof reflectance program and evolving IECC thermal envelope standards are shifting specification authority from contractors toward architects and building envelope consultants. Stakeholders must monitor how municipal electrification mandates and heat-island ordinances in cities like Phoenix and Miami reshape cool-roof assembly requirements and underlayment compatibility with reflective surface materials.
Market Dynamics
Synthetic underlayment displacement of organic felt concentrates competitive advantage among integrated polymer producers with captive resin supply, compressing margins for non-integrated converters while elevating specification authority toward building envelope consultants.
Growth Catalysts
- FEMA hurricane-resistant fastening mandates:Enhanced underlayment attachment patterns in US coastal counties drive specification upgrades above baseline ASTM D226 requirements, forcing re-roofing contractors toward higher-performance barrier systems.
- Sun Belt suburban housing expansion:Residential construction velocity across Florida, Texas, and Arizona concentrates demand for UV-stable synthetic substrates that withstand prolonged exposure during extended build schedules.
- Polyethylene extrusion advances:Improved polymer processing yields lighter-weight rolls with superior walkability, reducing installer fatigue and accelerating job-site throughput for residential roofing crews.
Market Restraints
- Petrochemical feedstock volatility:Polypropylene and polyethylene resin prices fluctuate with crude oil benchmarks, squeezing converter margins when polymer costs spike without corresponding roofing contract escalation clauses.
- Fiberglass mat supply concentration:Southeast Asian substrate production clusters in Vietnam and Indonesia create vulnerability to regional port congestion and energy rationing that disrupts North American synthetic underlayment output.
- Modified bitumen temperature limitations:Traditional asphalt-based membranes degrade under sustained thermal cycling above 80°C, restricting application on high-slope metal roof assemblies in desert climates.
Strategic Opportunities
- Self-adhered ice dam protection layers:FEMA-mandated self-sealing membranes in northern US counties create specification pull for peel-and-stick modified bitumen products with superior low-temperature flexibility.
- Cool-roof assembly compatibility:IECC thermal envelope standards and municipal heat-island ordinances in Phoenix and Miami drive demand for underlayment formulations compatible with highly reflective surface materials.
- Contractor-exclusive channel programs:Direct-to-installer distribution models bypass traditional two-step distribution, capturing specification authority and warranty registration data for aftermarket service revenue.
Industry Challenges
- Building envelope consultant skill scarcity:Specification authority migration from contractors toward technical consultants strains the talent pool for hygrothermal modeling and permeance-rated assembly design.
- Multi-certification compliance timelines:Simultaneous pursuit of ASTM D226, ASTM D6757, and ICC-ES AC188 approvals extends product launch cycles by 12-18 months for new synthetic formulations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Roofing and Tile Underlayment Market |
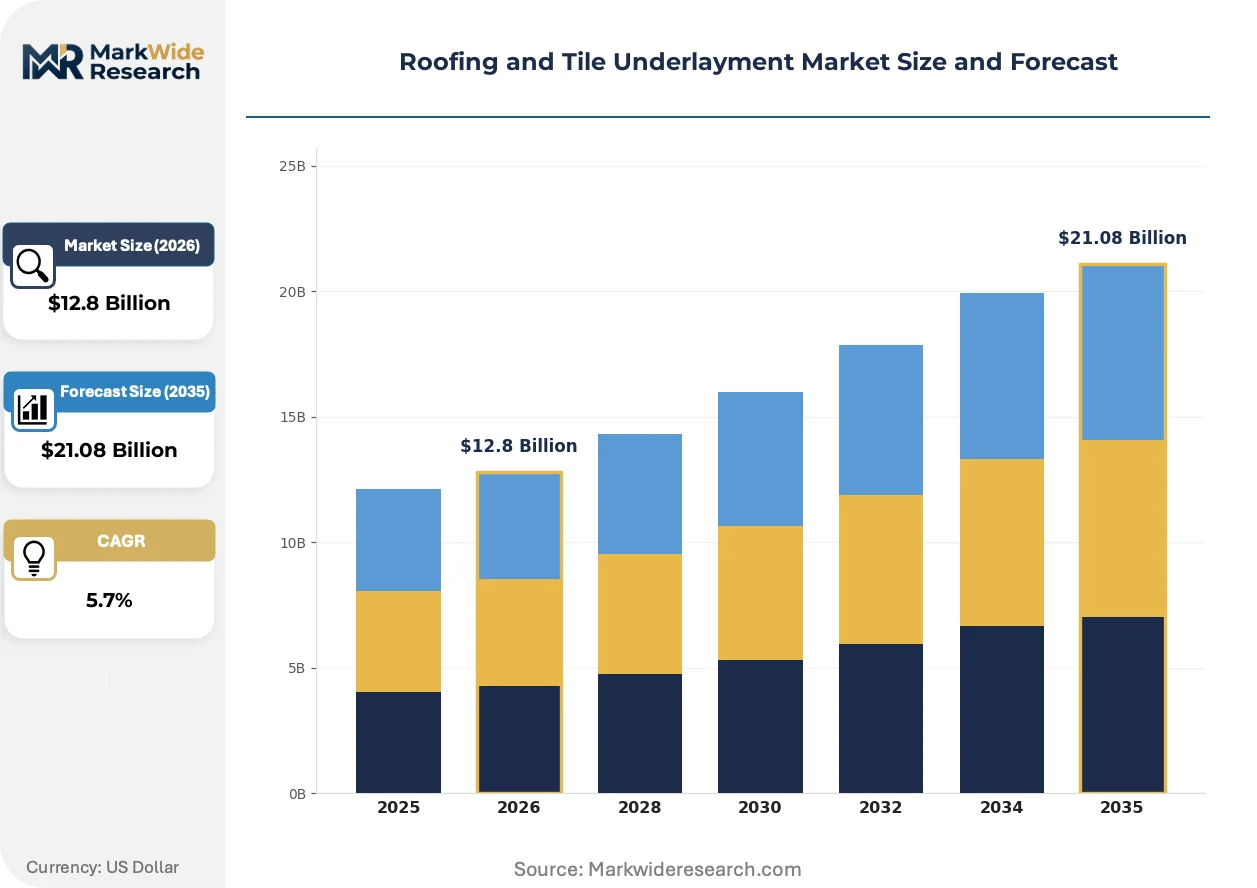
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $21.08 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
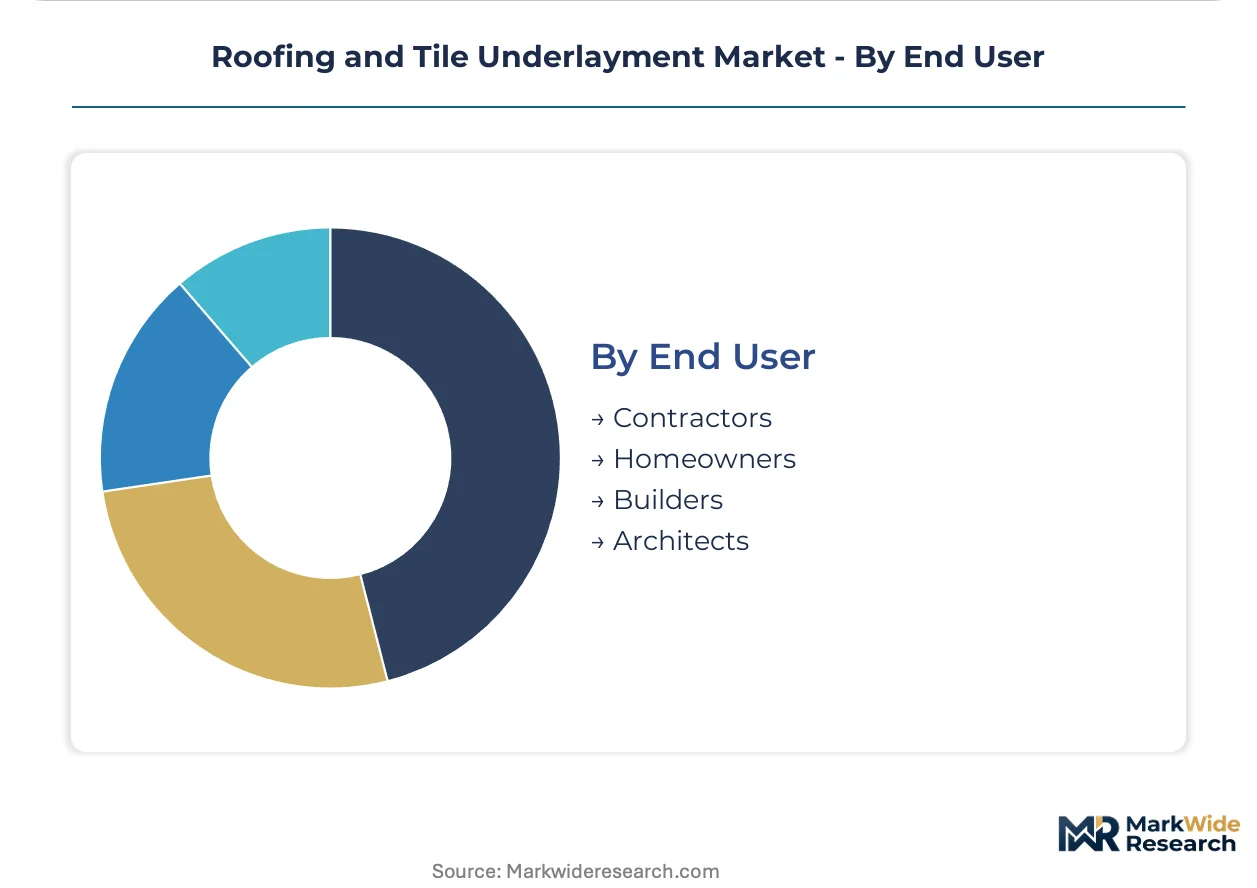
| Segmentation | Product Type: Asphalt Shingles, Metal Sheets, Membrane, Synthetic Underlayment Application: Residential, Commercial, Industrial, Agricultural Material: Fiberglass, Organic Felt, Rubber, Polyethylene End User: Contractors, Homeowners, Builders, Architects |
| Companies Covered | Johns Manville, IKO Industries, GAF Materials Corporation, Continental Materials, GCP Applied Technologies, Owens Corning, Carlisle SynTec, FT Synthetics, CertainTeed, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Roofing and Tile Underlayment Market Emerging Trajectories
Material science convergence with regulatory pressure is compressing traditional product lifecycles while elevating performance thresholds across residential and commercial roofing assemblies.
Multilayer coextruded polyethylene membranes with integrated slip-resistant surfaces are rendering obsolete single-ply spunbonded polypropylene in steep-slope residential applications. Production homebuilders in Texas and Florida specify these advanced substrates for their superior traction during installation and extended UV exposure tolerance. The technology is compressing price premiums for walkable synthetic underlayment to parity with traditional felt in high-volume procurement.
EPA stormwater management regulations and evolving IECC thermal envelope standards are transferring specification authority from roofing contractors toward architects and building envelope consultants. Municipal electrification mandates in Sun Belt cities accelerate cool-roof assembly requirements that demand underlayment compatibility with reflective metal and tile surfaces. Commercial membrane specifications now prioritize fire-resistance certifications and longer warranty terms over initial material cost.
Direct procurement from manufacturer to installer is displacing traditional two-step distribution in residential re-roofing segments. Contractor-exclusive loyalty programs capture specification authority and warranty registration data while reducing distributor markup. This channel compression is most visible in Florida and Arizona metropolitan markets where large roofing contractors consolidate purchasing power across multi-crew operations.
Roofing and Tile Underlayment Market Segmentation
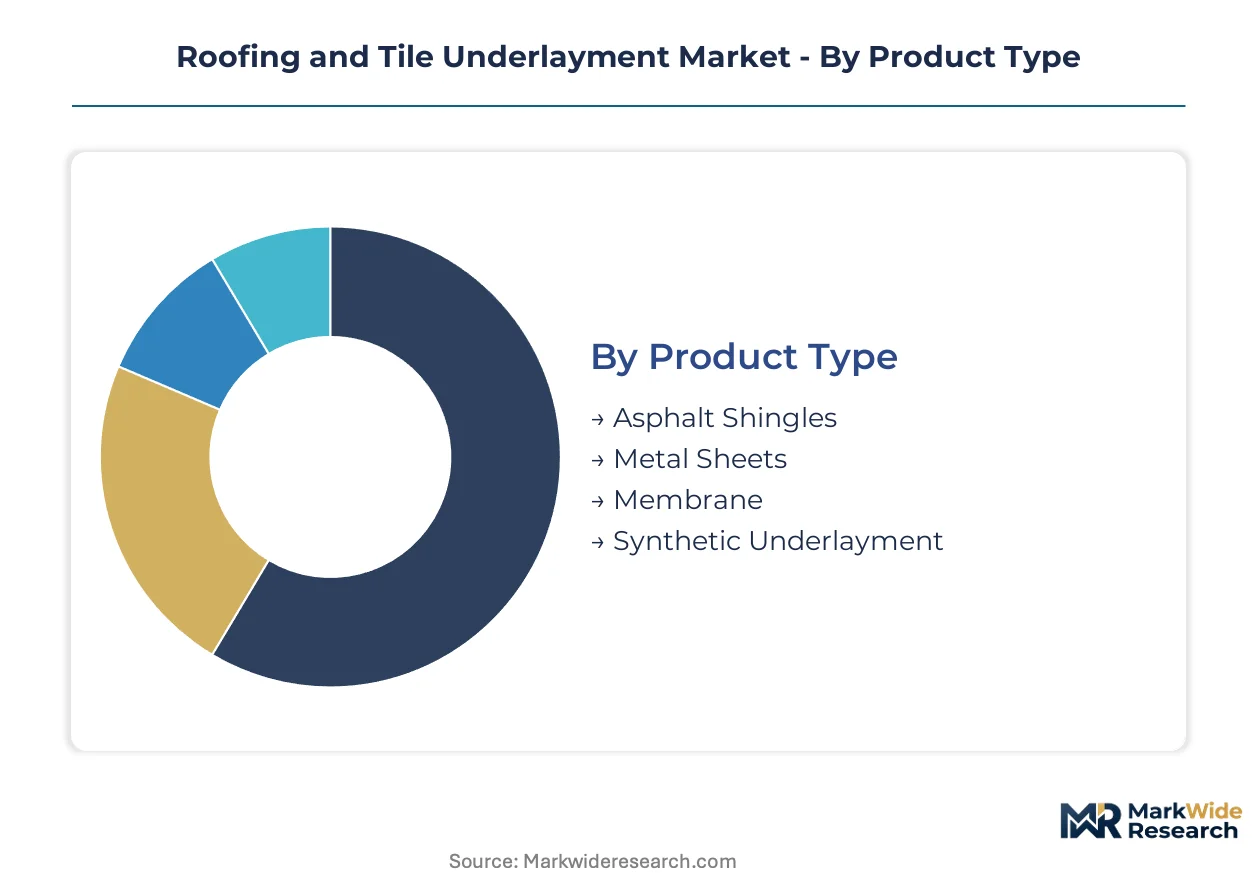
Segmentation in roofing and tile underlayment reveals how specification authority migrates across stakeholder groups and how material performance requirements diverge between steep-slope residential assemblies and low-slope commercial membranes. Understanding these divides enables targeted positioning against distinct procurement behaviors and code compliance pathways.
Product Type:
Product selection spans from commodity asphalt systems to engineered synthetic barriers, with performance premiums concentrating in hurricane-prone and high-UV exposure zones.
- Synthetic Underlayment:Multilayer polyethylene and polypropylene formulations deliver UV stability up to 180 days and superior walkability during installation. Demand clusters in Florida, Texas, and Arizona suburban developments where extended construction schedules expose substrates to prolonged sun exposure. FEMA coastal fastening mandates accelerate displacement of traditional felt in re-roofing cycles.
- Asphalt Shingles:Fiberglass-reinforced mats dominate North American residential re-roofing with mature supply chains and established contractor familiarity. Volume concentrates in Midwest and Northeast replacement markets where moderate climates reduce premium synthetic specifications.
- Metal Sheets:Standing seam and corrugated profiles require specialized underlayment with high-temperature resistance for thermal cycling in desert climates.
- Membrane:Modified bitumen and TPO systems anchor commercial low-slope specifications with fire-resistance certifications and extended warranty terms.
Established volume favors asphalt shingles; emerging adoption favors synthetic underlayment.
Application:
Application segmentation tracks how building codes and insurance requirements reshape material specifications across occupancy types and climate zones.
- Residential:Steep-slope assemblies generate the largest unit volume, with procurement shifting from distributor channels toward direct manufacturer-to-contractor programs. Sun Belt housing expansion concentrates demand for UV-stable synthetic substrates that withstand installation delays and thermal cycling.
- Commercial:Low-slope membrane specifications command premium pricing through 20-30 year warranty terms, fire-resistance certifications, and strict ASTM D6757 compliance. Building envelope consultants increasingly control specification authority for large-format retail and warehouse projects.
- Industrial:Heavy-duty modified bitumen systems address chemical resistance and mechanical protection requirements in manufacturing facilities.
- Agricultural:Cost-driven specifications favor traditional felt in barn and outbuilding applications with shorter service life expectations.
Residential channels deliver volume scale; commercial specifications capture margin premiums.
Material:
Material chemistry determines permeance ratings, thermal stability, and compatibility with primary roof coverings across climate extremes.
- Polyethylene:Coextruded multilayer films with integrated slip-resistant surfaces are displacing spunbonded polypropylene in steep-slope residential applications. Advances in polymer processing yield lighter-weight rolls that reduce installer fatigue and accelerate job-site throughput.
- Fiberglass:Reinforcing mats anchor asphalt shingle durability and synthetic underlayment tear resistance, with Southeast Asian production clusters in Vietnam and Indonesia supplying North American converters.
- Organic Felt:Saturated cellulose substrates retain cost-sensitive market share in agricultural and temporary protection applications.
- Rubber:EPDM and butyl formulations serve specialized self-adhered ice dam protection layers in northern US counties with FEMA-mandated low-temperature flexibility.
Fiberglass substrates anchor supply security; polyethylene formulations gain specification share.
End User:
Procurement authority is fragmenting across stakeholder groups as building codes and energy standards elevate technical complexity.
- Contractors:Installation crews prioritize walkability, roll weight, and fastening efficiency, driving preference for synthetic substrates with slip-resistant surfaces. Large multi-crew operations in Phoenix and Miami consolidate purchasing power through manufacturer-direct loyalty programs.
- Architects:Building envelope consultants specify permeance-rated assemblies and hygrothermal modeling for commercial projects, displacing traditional contractor-driven selection. EPA Energy Star and IECC thermal envelope standards elevate their authority over cool-roof compatibility requirements.
- Builders:Production homebuilders in Texas and Florida specify advanced polyethylene membranes for volume procurement at parity pricing with traditional felt.
- Homeowners:End-user influence concentrates in insurance-mandated re-roofing scenarios following storm damage claims.
Contractor channels dominate current volume; architect and consultant specifications are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. Sun Belt states in the United States favor UV-stable synthetic substrates for extended construction schedules, while European specifications prioritize fire-resistance certifications under stricter building codes. Southeast Asian production clusters supply fiberglass mat substrates to converters worldwide.
United States
Residential construction velocity across Florida, Texas, and Arizona concentrates demand for synthetic underlayment with 180-day UV exposure tolerance. FEMA mandates enhanced fastening patterns in hurricane-prone coastal counties, elevating specifications above baseline ASTM D226 requirements. Houston and Phoenix metropolitan markets host large roofing contractors consolidating purchasing power through manufacturer-direct loyalty programs.
Germany
Commercial membrane specifications command premium pricing through extended warranty terms and strict fire-resistance certifications under EU construction product regulations. The country's national building regulator enforces thermal envelope standards that elevate building envelope consultant authority over material selection. Industrial clusters in North Rhine-Westphalia anchor modified bitumen formulation expertise for low-slope commercial applications.
China
Rapid urbanization drives membrane demand for large-format retail and warehouse construction across Yangtze River Delta and Pearl River Delta megacity clusters. The Ministry of Ecology and Environment enforces dual carbon goals that reshape cool-roof assembly requirements in major municipalities. Zhejiang and Jiangsu provinces concentrate fiberglass mat production capacity serving domestic and export markets.
Vietnam
Expanding fiberglass mat production for underlayment substrates reconfigures regional supply dynamics for North American converters. Port congestion and energy rationing create vulnerability in substrate supply chains dependent on Southeast Asian manufacturing clusters. Industrial zones near Ho Chi Minh City anchor expanding export-oriented substrate fabrication capacity.
Indonesia
Fiberglass mat manufacturing expansion supports synthetic underlayment output for roofing markets in Australia and North America. The country's national industrial regulator oversees export-oriented manufacturing zones with preferential trade access to key destination markets. Batam and Bintan industrial estates concentrate substrate production serving integrated polymer converters.
Roofing and Tile Underlayment Market Vendor Landscape
Capability concentration sits with integrated polymer producers possessing captive resin supply; scale advantage sits with established roofing materials conglomerates with distribution infrastructure. The market structure favors backward-integrated specialists over non-integrated converters facing margin compression from feedstock volatility. Three archetypes dominate: integrated polymer producers, established roofing materials conglomerates, and regional substrate specialists. Capacity expansion and direct-to-installer channel compression represent the dominant competitive moves reshaping market access.
Among integrated building materials conglomerates, Owens Corning and GAF Materials Corporation exemplify scale-driven positioning through captive supply chain control and distribution infrastructure. Johns Manville occupies a position representing technical leadership in high-temperature modified bitumen formulations. These three companies anchor the competitive landscape as reference points for strategic archetype analysis without ascribing specific market share figures or financial performance metrics.
| Leading Market Players |
|---|
| Johns Manville |
| IKO Industries |
| GAF Materials Corporation |
| Continental Materials |
| GCP Applied Technologies |
| Owens Corning |
| Carlisle SynTec |
| FT Synthetics |
| CertainTeed |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Vietnamese fiberglass mat production is compressing substrate pricing while forcing North American converters toward longer-term offtake contracts to secure volume commitments. This utilization dynamic simultaneously erodes spot-market supplier power and rewards integrated polymer producers with captive resin supply.
Pricing Analysis
Long-term offtake contracts dominate procurement between large roofing contractors and integrated manufacturers, insulating buyers from polyethylene resin volatility while locking in volume commitments. Price differentiation separates premium synthetic underlayment with 180-day UV ratings from standard-grade felt and economy agricultural membranes. Cost compression in standard-grade synthetics is intensifying because Vietnamese fiberglass substrate exports are flooding spot markets. Production homebuilders in Texas and Florida exhibit lowest price sensitivity due to volume procurement power, while independent re-roofing contractors in the Midwest remain most price-sensitive.
Supply Chain Analysis
Polyethylene and polypropylene resin supply draws from Gulf Coast petrochemical clusters in the United States, with Southeast Asian fiberglass mat production concentrated in Vietnam and Indonesia. Raw material dependencies center on crude oil derivatives for polymer feedstock, silica sand for fiberglass production, and asphalt binders for modified bitumen membranes. Single-source vulnerability in Southeast Asian substrate supply creates exposure to regional port congestion and energy rationing. Distribution runs through contractor-exclusive direct channels in Sun Belt metropolitan markets, bypassing traditional two-step wholesale distribution.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Warranty registration data and aftermarket service revenue are expanding faster than underlying membrane hardware sales, converting transactional roofing material purchases into recurring-revenue relationships. This service-attach dynamic favors players who capture specification authority early in the building envelope design process.
For Market Incumbents: Build captive resin supply moats through backward integration into Gulf Coast petrochemical infrastructure or long-term polymer offtake agreements. Incumbents must defend against non-integrated converters facing margin compression by accelerating direct-to-installer channel programs in Phoenix and Miami metropolitan markets. Certification investment in FEMA-compliant fastening systems represents a critical lever for specification authority in hurricane-prone counties.
For New Entrants and Emerging Players: Agricultural underpenetration in Midwest barn and outbuilding applications offers white-space entry with lower certification barriers and faster procurement cycles. New entrants should target commercial membrane specifications in northern US counties where FEMA-mandated self-adhered ice dam protection layers command premium pricing. A go-to-market angle anchored in building envelope consultant education programs bypasses entrenched contractor relationships.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among integrated polymer producers with contractor-exclusive loyalty programs and warranty registration databases. Long-term viability over the next decade hinges on positioning within cool-roof assembly supply chains compatible with municipal electrification mandates. The acquisition target archetype comprises regional substrate specialists with Southeast Asian manufacturing footprints. The signal to watch is municipal heat-island ordinance adoption velocity in Sun Belt cities as an inflection indicator for reflective surface material demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Feedstock | Gulf Coast resin supply control insulates margins from crude oil benchmark volatility. |
| Contractor-Exclusive Channel Programs | Direct distribution in Florida and Miami captures specification authority and warranty data. |
| FEMA Compliance Certification Investment | Hurricane-resistant fastening approvals unlock coastal county re-roofing specifications. |
| Southeast Asian Substrate Capacity Expansion | Vietnamese fiberglass mat production reconfigures regional supply dynamics for North American converters. |
| Building Envelope Consultant Education Programs | Technical training shifts specification authority from contractors toward architects and consultants. |
Methodological Framework
Cross-validation between primary interviews with roofing contractors, building envelope consultants, and production homebuilder procurement directors anchors the qualitative findings against secondary data from ASTM standards documentation, FEMA building code filings, and EPA Energy Star program specifications. The analysis draws from customs records tracking fiberglass mat imports, SEC filings of integrated building materials conglomerates, and regional housing permit databases. Bottom-up triangulation across installer-level procurement patterns and top-down validation against residential construction expenditure data ensure methodological rigor.
Calibration against historical housing start volatility and petrochemical price cycles shapes the projection framework across the analysis window. Segmentation dimensions include product chemistry, application type, material substrate, and end-user procurement authority. CAGRs derive from elasticity-adjusted demand modeling incorporating Sun Belt migration patterns and evolving IECC thermal envelope standards. Industry-specific forecast inputs center on FEMA code adoption timelines and municipal electrification mandate propagation.
Practitioners should monitor resin price spikes without corresponding roofing contract escalation clauses and Southeast Asian energy rationing events for early signals requiring forecast revision. Cross-checking against regional housing permit data from the US Census Bureau is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Fly Ash Bricks Market
Building Materials
Global Lightweight Aggregate Concrete Market
Building Materials
Italy Cement Market
Building Materials
North America Dry-Mix Mortar Market
Building Materials
Cement Tiles Market
Building Materials
Poland Architectural Coatings Market
Building Materials
Europe Concealed Cistern Market
Building Materials
US Commercial Paving Slabs Market
Building Materials
Foam Bricks Market
Building Materials
Pozzolana Cement Market
Building Materials
Exterior Doors Market
Building Materials
Fiber Reinforced Concrete Market
Building Materials
Composite Decking and Railing Market
Building Materials
Light Gauge Steel Framing Market
Building Materials
United States Architectural Coatings Market
Building Materials
Construction Stone Market