
 Woodworking Power Tools Market | 2026-2036
Woodworking Power Tools Market Size, Share, and Industry Trends Forecast 2026-2036
Woodworking Power Tools Market Insights
Buyer concentration among professional contractors and large-scale furniture manufacturers is expanding as mid-sized woodworking shops consolidate procurement volumes. Stanley Black & Decker leverages its brand portfolio to dominate the North American retail channel for cordless platforms. Robert Bosch GmbH sustains engineering intensity in brushless motor systems for precision routing applications. Makita Corporation anchors its position in the Asia-Pacific professional segment through battery platform standardization across its LXT ecosystem.
Woodworking power tools encompass electrically or pneumatically driven equipment designed to cut, shape, finish, or join wood and wood-composite materials, typically operating at rotational speeds between 3,000 and 25,000 RPM depending on the application. These tools serve furniture fabrication, structural carpentry, and architectural millwork by reducing manual labor time and improving dimensional repeatability. Saws generate the largest revenue pool within product type categories due to their essential role in dimensioning raw lumber across all end-use tiers. Cordless technology commands the fastest expansion trajectory within technology segments as lithium-ion cell energy density improvements extend runtime for previously cord-dependent applications like table saws and thickness planers. The professionals end-user category concentrates margin pools because specification requirements for continuous-duty cycles justify premium pricing over hobbyist-grade alternatives.
The Occupational Safety and Health Administration enforces noise exposure limits and guarding requirements that compel manufacturers to redesign blade enclosures and dust collection interfaces on stationary equipment. CE marking under the EU Machinery Directive mandates risk assessments and conformity procedures that filter lower-capability suppliers from European distribution channels. China's Standardization Administration maintains GB standards for power tool electromagnetic compatibility that shape export design requirements for manufacturers targeting domestic production. Stakeholders must monitor how evolving battery transportation regulations and recycling mandates influence cordless platform economics and regional sourcing strategies.
Market Dynamics
Brushless motor integration with high-density lithium-ion battery packs is compressing corded equipment's installed base across professional job sites, forcing manufacturers to reconfigure product architectures and service revenue models around platform ecosystems rather than individual tool sales.
Growth Catalysts
- OSHA Noise Exposure Limits:Stricter enforcement of permissible exposure levels is accelerating demand for low-decibel brushless motors and enclosed blade systems in stationary equipment categories.
- Residential Construction Electrification:Single-family and multi-family builders are standardizing cordless platforms to eliminate trip hazards and reduce generator dependency on wood-framed job sites.
- Battery Chemistry Advances:Silicon-anode and solid-state cell developments are extending runtime for high-draw applications previously restricted to corded power supplies.
Market Restraints
- Lithium Supply Concentration:Processing capacity for battery-grade lithium hydroxide concentrates in Chile and Australia creates input cost volatility for cordless platform manufacturers.
- CE Marking Compliance Burden:EU Machinery Directive conformity assessments impose documentation and testing costs that filter smaller suppliers from European distribution channels.
- Pneumatic Tool Substitution:Compressed-air systems retain cost advantages in high-volume fixed-facility operations, limiting cordless penetration in industrial millwork.
Strategic Opportunities
- India PLI Scheme for Manufacturing:Production-linked incentives for advanced cell and power tool assembly are attracting capacity investments targeting domestic and export markets.
- Refurbishment and Battery Recycling Services:Extended producer responsibility mandates in Germany and France are creating aftermarket revenue streams around cell replacement and tool redeployment.
- IoT-Enabled Fleet Management:Tool-tracking and usage-analytics platforms are integrating with contractor enterprise resource planning systems to reduce loss rates and optimize utilization.
Industry Challenges
- Brushless Motor Technician Scarcity:Repair networks lack trained personnel for electronic speed control diagnostics and field coil replacement, extending equipment downtime.
- Cross-Platform Battery Incompatibility:Proprietary cell form factors and communication protocols fragment fleet standardization efforts for multi-brand contractors.
- GB Standard Electromagnetic Testing:China's conformity assessment timelines for power tool electromagnetic compatibility certification delay product launches by four to six months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Woodworking Power Tools Market |
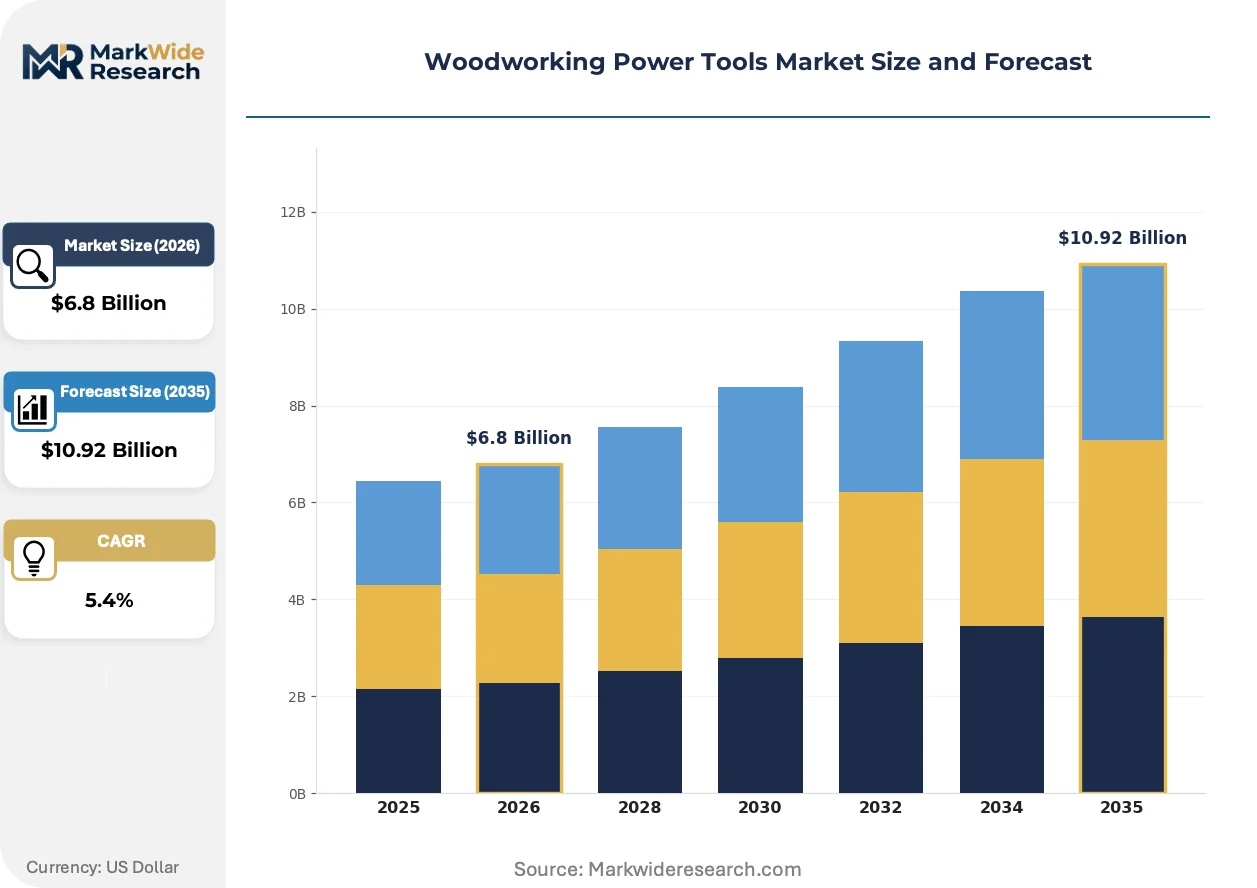
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.92 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Drills, Saws, Sanders, Routers End User: Professionals, Hobbyists, Contractors, Manufacturers Technology: Corded, Cordless, Pneumatic, Hydraulic Application: Furniture Making, Cabinetry, Flooring, DIY Projects |
| Companies Covered | Stanley Black & Decker, Inc., Robert Bosch GmbH, Makita Corporation, Techtronic Industries Co. Ltd., Atlas Copco AB, Snap-on Incorporated, Hilti AG, Festool GmbH, Ingersoll Rand, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Woodworking Power Tools Market Trends and Innovations
Equipment architectures are converging around connected, battery-native platforms that embed diagnostics and usage tracking directly into tool electronics. This shift is compressing replacement cycles for corded legacy equipment while opening service-based revenue models.
Brushless DC motor systems are integrating permanent magnet rotor designs with sensorless control algorithms to deliver higher torque density in compact form factors. Cabinet shops and architectural millwork contractors are adopting these systems for precision routing and joinery applications where variable speed control improves surface finish quality. The technology is integrating electronic feedback loops that adjust power delivery based on load conditions, reducing thermal stress and extending service intervals.
REACH restrictions on cobalt and nickel compounds in battery electrodes are forcing cell manufacturers to reformulate cathode chemistries toward lithium iron phosphate and manganese-rich alternatives. This regulatory pressure is reshaping supply agreements for power tool OEMs dependent on cylindrical cell supplies. Professional-grade cordless platforms face the steepest reformulation timelines, as high-discharge applications previously relied on nickel-cobalt-aluminum oxide chemistries for energy density.
Equipment-as-a-service contracting is displacing capital purchase models among mid-sized woodworking operations facing balance sheet constraints. Rental and lease channels are capturing share from independent distributors in North American metropolitan construction markets. Germany's Mittelstand furniture manufacturers exhibit the strongest service-contract penetration, driven by tax-advantaged operating expense treatment and bundled maintenance provisions.
Woodworking Power Tools Market Segmentation
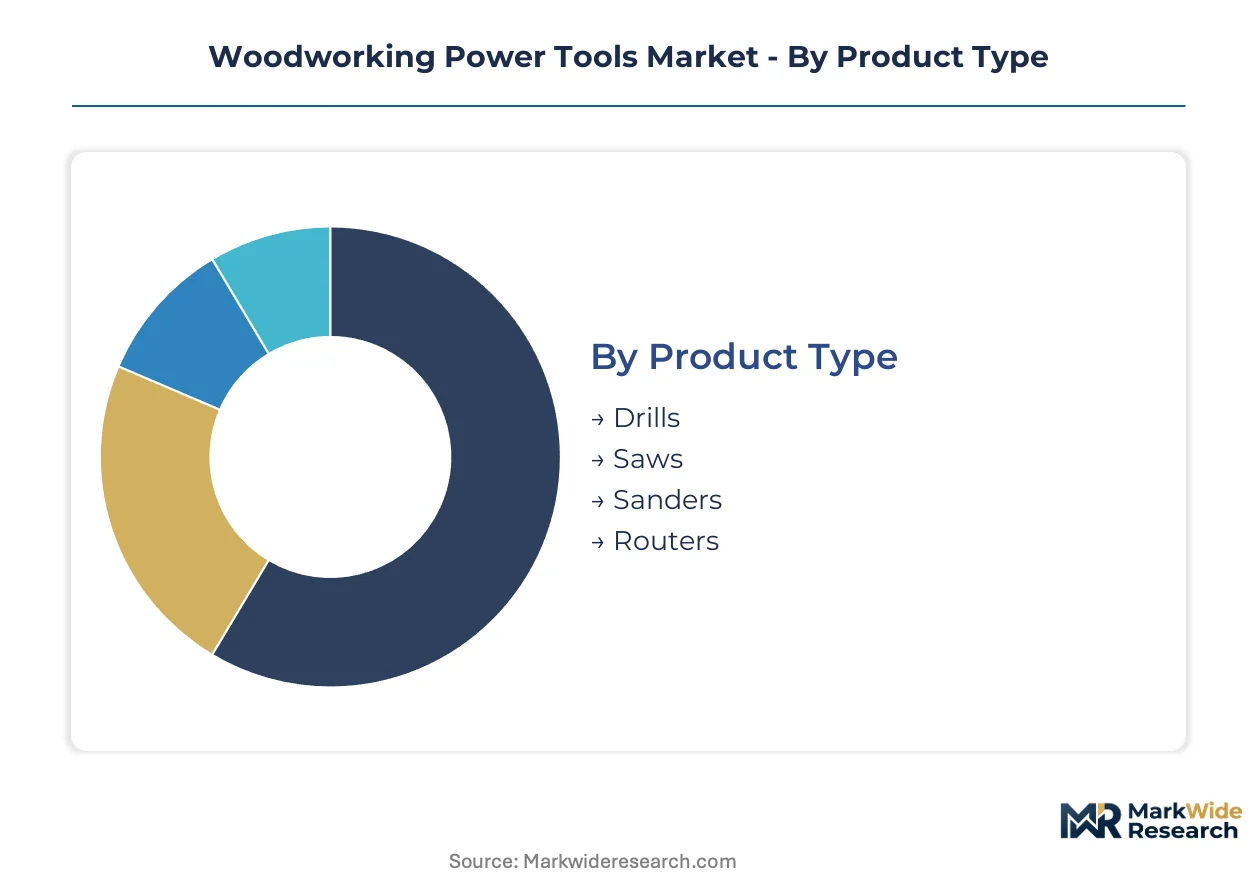
Segmentation in woodworking power tools separates volume-driven commodity sales from premium platform ecosystems. Understanding these divides clarifies where battery standardization commands loyalty versus where pneumatic systems retain cost advantages.
Product Type:
Volume concentrates in high-frequency dimensioning equipment while premium margins accrue to precision finishing tools.
- Saws:Circular, miter, and table saw configurations generate the largest revenue pool through essential lumber dimensioning across residential construction and furniture fabrication. Demand clusters with professional contractors in Germany, Japan, and the United States where OSHA and CE marking compliance for blade guarding and dust collection drives specification upgrades.
- Routers:Variable-speed plunge and fixed-base systems deliver precision edge profiling and joinery for architectural millwork. Brushless motor integration from Bosch and Makita is reshaping this segment as cabinet shops prioritize surface finish quality and thermal management.
- Drills:Compact driver-drill combinations serve fastener installation across all user tiers.
- Sanders:Orbital and belt configurations address surface preparation before finishing operations.
Today's leader: Saws. Tomorrow's challenger: Routers.
End User:
Margin pools concentrate with specification-heavy professional buyers rather than price-sensitive occasional users.
- Professionals:Continuous-duty cycle requirements justify premium pricing for brushless motor systems and standardized battery platforms. This tier concentrates procurement volumes among consolidated mid-sized woodworking shops and specialized architectural millwork contractors.
- Contractors:Residential construction firms standardize cordless platforms across job sites to eliminate trip hazards and reduce generator dependency. Single-family and multi-family builders in North American metropolitan markets drive fleet-level purchasing.
- Manufacturers:Large-scale furniture producers consolidate procurement through enterprise resource planning integration.
- Hobbyists:Entry-level corded equipment dominates occasional-use residential applications.
Professionals extract maximum platform value. Contractors are expanding fleet standardization fastest.
Technology:
Power delivery architecture determines runtime, portability, and maintenance economics across job site and fixed-facility deployment.
- Cordless:Lithium-ion cell energy density improvements extend runtime for previously cord-dependent applications like table saws and thickness planers. Silicon-anode and solid-state developments are compressing corded equipment's installed base across professional job sites.
- Corded:Continuous power supply retains cost advantages in high-volume fixed-facility operations where pneumatic substitution also competes.
- Pneumatic:Compressed-air systems maintain share in industrial millwork through lower capital cost and simpler maintenance.
- Hydraulic:Specialized high-torque applications in heavy timber framing and engineered wood processing.
Cordless commands the steepest expansion trajectory. Pneumatic defends industrial strongholds.
Application:
End-use differentiation separates precision-driven commercial fabrication from tolerance-flexible residential projects.
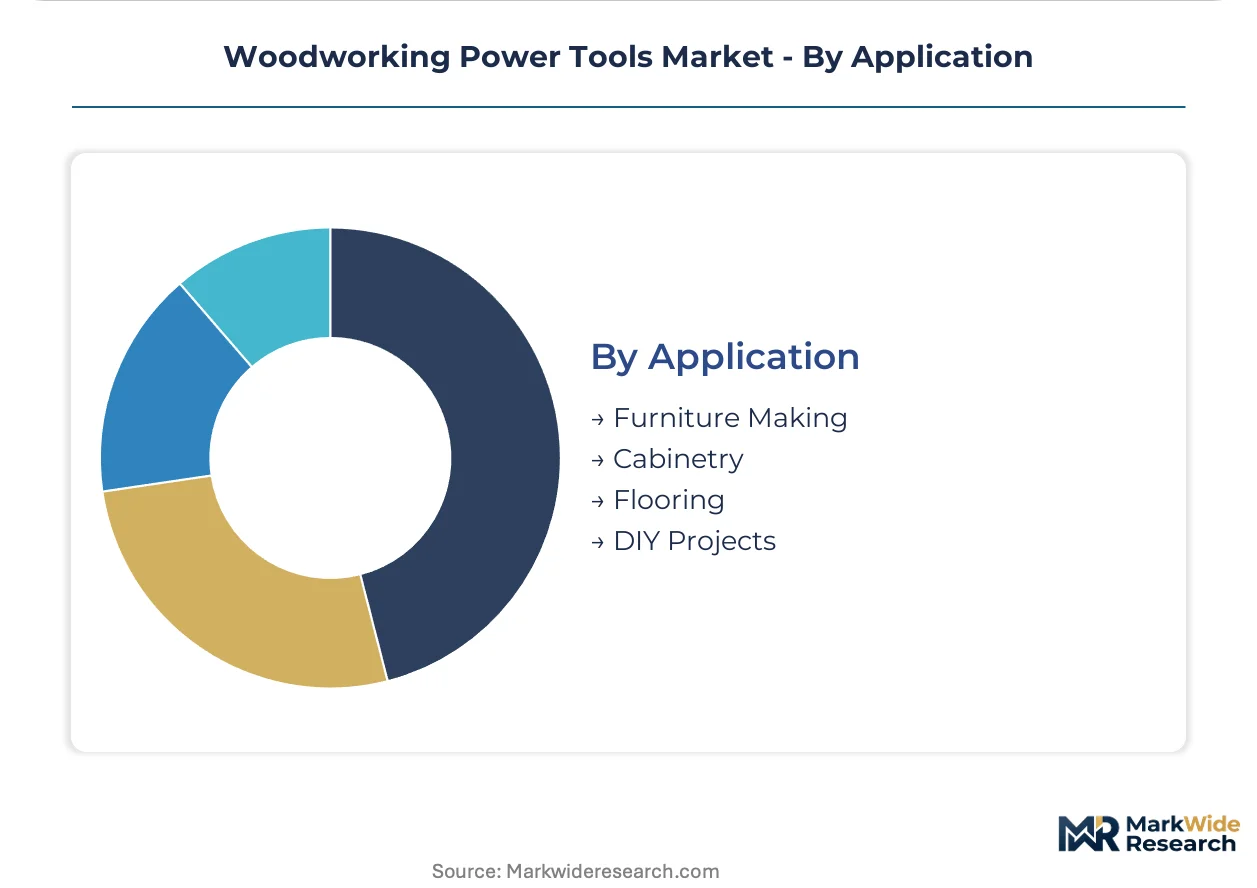
- Furniture Making:Dimensional repeatability requirements drive specification for electronic feedback systems and variable speed control. Germany's Mittelstand manufacturers exhibit strong equipment-as-a-service contract penetration through tax-advantaged operating expense treatment.
- Cabinetry:Architectural millwork contractors adopt brushless DC systems for precision routing where load-condition power adjustment improves surface finish quality.
- Flooring:High-frequency cutting and fastening operations favor cordless platform standardization.
- DIY Projects:Occasional-use tolerance requirements accommodate entry-level corded and budget cordless alternatives.
Furniture making anchors premium specification. Cabinetry is gaining connected-platform adoption fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates precision equipment specification while the United States drives cordless platform standardization across residential construction. Japan anchors professional-grade battery platform development. Regulatory divergence across these markets fragments certification requirements and shapes regional sourcing strategies.
Germany
Architectural millwork contractors and Mittelstand furniture manufacturers sustain demand for brushless routing systems with electronic feedback control. CE marking under the EU Machinery Directive mandates comprehensive risk assessments for blade guarding and dust collection interfaces. The Stuttgart and Black Forest industrial clusters concentrate precision tooling fabrication where equipment-as-a-service contracts penetrate deepest through tax-advantaged operating expense structures.
United States
Single-family and multi-family residential builders are eliminating corded equipment from wood-framed job sites to reduce trip hazards and generator dependency. OSHA enforces permissible noise exposure limits that accelerate adoption of low-decibel brushless motors and enclosed blade systems. Metropolitan construction markets in Texas, Florida, and the Pacific Northwest drive fleet-level cordless platform procurement through consolidated contractor purchasing.
Japan
Professional contractors demand standardized battery ecosystems across high-discharge applications including table saws and thickness planers. METI oversees industrial standards coordination while JIS certification requirements filter lower-capability imports from domestic distribution. The Nagoya and Osaka manufacturing belts concentrate precision motor and electronic speed control production for export-oriented power tool assembly.
China
Domestic furniture fabrication and construction activity absorb growing volumes of cordless equipment despite pneumatic retention in high-volume fixed facilities. The Standardization Administration maintains GB standards for electromagnetic compatibility that extend certification timelines for foreign-designed products. Yangtze River Delta manufacturing zones concentrate lithium-ion cell assembly and power tool final production targeting both domestic consumption and export markets.
India
Mid-sized woodworking shops and emerging residential construction firms are expanding power tool procurement as labor costs rise and dimensional repeatability requirements tighten. The PLI scheme for advanced cell and power tool assembly attracts capacity investments from multinational and domestic manufacturers. Gujarat and Maharashtra industrial corridors concentrate new assembly operations targeting domestic replacement of imported professional-grade equipment.
Woodworking Power Tools Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across distinct technology and distribution vectors. Market structure concentrates around three tiers: multinational platform ecosystem operators, regional professional-grade specialists, and cost-optimized volume manufacturers serving hobbyist segments. Strategic archetypes include battery-native platform architects, pneumatic system defenders in industrial millwork, and connected-tool service integrators. Competitive moves center on M&A to secure motor control intellectual property and geographic expansion to capture India PLI scheme incentives.
Among diversified conglomerates with tool divisions, Stanley Black & Decker, Inc. occupies a position exemplifying retail channel dominance through brand portfolio breadth. Robert Bosch GmbH and Makita Corporation represent engineering-intensive archetypes focused on brushless motor systems and battery platform standardization respectively. These three entities anchor distinct competitive vectors: retail distribution scale, precision routing technology, and professional ecosystem loyalty across the Asia-Pacific contractor segment.
| Leading Market Players |
|---|
| Stanley Black & Decker, Inc. |
| Robert Bosch GmbH |
| Makita Corporation |
| Techtronic Industries Co. Ltd. |
| Atlas Copco AB |
| Snap-on Incorporated |
| Hilti AG |
| Festool GmbH |
| Ingersoll Rand |
| Others |
Pricing and Supply Chain Analysis
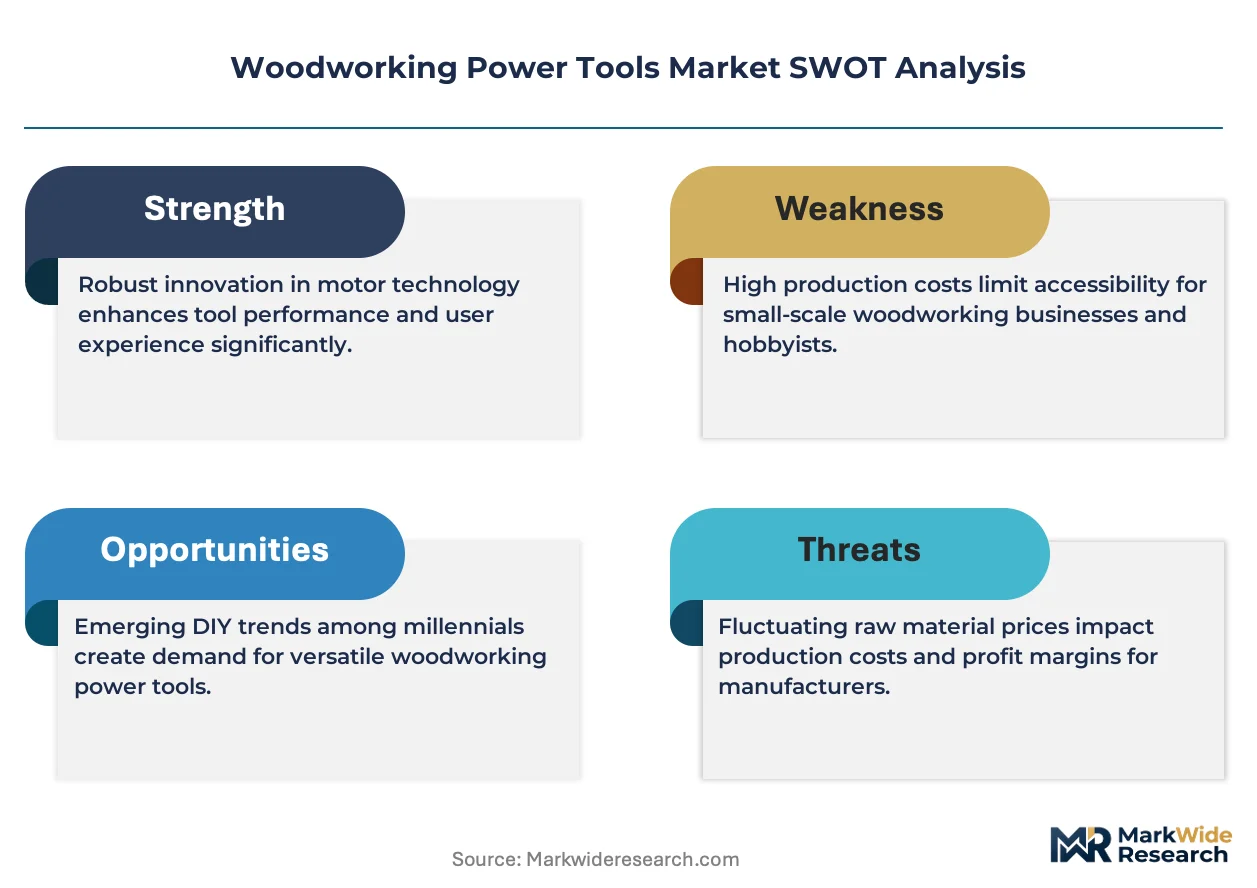
Captive lithium hydroxide processing in Chile and Australia anchors both cordless platform economics and manufacturer pricing power. This upstream concentration forces OEMs to absorb cell chemistry cost volatility or push price adjustments through professional-grade tiers where specification loyalty runs deepest.
Pricing Analysis
Capacity additions in China's Yangtze River Delta manufacturing zones are reshaping price floors for entry-level cordless equipment. Three-tier pricing structure across premium, standard, and economy levels separates brushless motor systems with electronic feedback from basic brushed alternatives and hobbyist-grade imports. Price differentiation hinges on CE marking compliance depth and battery platform standardization breadth. Cost compression in economy tiers is intensifying because GB standard electromagnetic testing extends certification timelines for foreign-designed products. Hobbyist segments exhibit highest price sensitivity; professional contractors purchasing through fleet standardization programs demonstrate lowest sensitivity due to operating expense treatment and bundled maintenance provisions.
Supply Chain Analysis
Single-source vulnerability sits with Australian and Chilean lithium hydroxide processing capacity for battery-grade cell inputs. Component sourcing draws from China for lithium-ion cell assembly, Japan for precision motor and electronic speed control production, and Germany for brushless rotor fabrication. Raw material dependencies span cobalt and nickel compounds facing REACH restriction pressures, silicon-anode developments, and permanent magnet rare earths. Tariff exposure on cylindrical cell imports fragments regional sourcing strategies for multinational OEMs. Distribution runs through consolidated retail channels in North America, specialized industrial distributors in Germany, and direct contractor fleet sales in Japan.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Woodworking power tools function as a regulatory compounder where OSHA noise exposure limit enforcement and EU Machinery Directive blade guarding mandates continuously refresh equipment replacement cycles.
For Market Incumbents: Deepen battery platform ecosystem lock-in through cross-tool compatibility guarantees and trade-in programs for legacy corded equipment. Expand captive lithium supply agreements with Australian and Chilean processors to buffer cell chemistry cost volatility. Prioritize brushless motor technician certification networks to reduce field service downtime that threatens contractor loyalty. For New Entrants and Emerging Players: Industrial distributors serving Germany's Mittelstand furniture manufacturers represent the most penetrable channel partner type for equipment-as-a-service contracting models. Target India's PLI scheme incentive zones in Gujarat and Maharashtra for assembly capacity that qualifies for domestic procurement preferences. White-space exists in IoT-enabled fleet management integration with contractor ERP systems. For Investors and Strategic Acquirers: Roll-up economics work for regional professional-grade specialists because CE marking compliance burdens filter smaller suppliers from European distribution channels. Five-to-ten year viability favors brushless motor control IP holders and standardized battery platform operators over pneumatic system defenders in industrial millwork. Monitor solid-state cell development timelines as inflection indicator for cordless penetration into previously cord-dependent applications.| Strategic Initiative | Industry Significance |
|---|---|
| Battery Platform Standardization | Makita's LXT ecosystem locks professional contractors through cross-tool runtime guarantees and charger interoperability. |
| Backward Integration into Cell Supply | Captive lithium hydroxide offtake from Chilean processors buffers Stanley Black & Decker against spot price volatility in cordless platform economics. |
| Equipment-as-a-Service Contracting | Germany's tax-advantaged operating expense treatment drives Mittelstand furniture manufacturers toward bundled maintenance provisions. |
| Brushless Motor IP Acquisition | Bosch's precision routing technology commands premium positioning in architectural millwork where surface finish quality justifies specification upgrades. |
| India PLI Scheme Manufacturing Footprint | Advanced cell and power tool assembly incentives attract capacity targeting domestic replacement of imported professional-grade equipment. |
Research Methodology
Multiple input streams — primary interviews with power tool OEM product managers, contractor fleet procurement officers, and lithium cell supply specialists; secondary validation through OSHA enforcement databases, EU Machinery Directive conformity assessments, and customs trade records — were reconciled through bottom-up and top-down triangulation. Primary fieldwork captured specification requirements from residential construction firms in Texas and Florida, architectural millwork contractors in Stuttgart, and furniture manufacturers in Nagoya. Secondary sources included SEC 10-K filings from listed tool manufacturers, METI industrial standards coordination documents, and BIS certification timelines for electromagnetic compatibility testing.
Historical shipment data cross-referenced against panel input from distribution channel partners anchored the analytical framework across the analysis window. Segmentation dimensions modeled encompassed product type, end-user tier, power delivery technology, and application intensity. CAGRs were derived from curve-fitting procedures applied to verified installation base data and replacement cycle assumptions. Industry-specific forecast inputs incorporated battery chemistry energy density improvement curves and regulatory enforcement intensity indices for noise exposure and dust collection mandates.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to solid-state cell commercialization timelines, lithium supply concentration disruptions, and REACH restriction expansion to additional electrode compounds. Forecasts reflect documented assumptions regarding professional contractor fleet standardization rates and residential construction electrification adoption curves. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tools
Woodpecker Tools Market
Tools
3D Milling Machines Market
Tools
US Hitter Based Hand Tools Market
Tools
Coil Thread Insert Market
Tools
Cordless Trim Routers Market
Tools
Wire Cutters Market
Tools
Quick Release Pins Market
Tools
Boring Tools Market
Tools
Europe Machine Tools Market
Tools
Fastening Power Tools Market
Tools
Gear Hobbing Cutter Market
Tools
Industrial Plate Bending Machines Market
Tools
Leather Embossing Machine Market
Tools
Garden Digging Tools Market
Tools
Gouging Torch Market
Tools
Woodcarving Tool Market