
 Latin America Facade Market | 2026-2036
Latin America Facade Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Facade Market Foresight
Commercial high-rise development is pivoting toward performance-driven envelope solutions as Latin American cities densify vertically. Tecnoglass Inc anchors its position through vertically integrated glass manufacturing in Colombia, supplying insulated units across the Andean region. Mallol Arquitectos differentiates through specialized high-rise facade engineering in Panama and Costa Rica. Ventanar competes aggressively in Mexico's residential tower segment with pre-fabricated panel systems that reduce on-site labor.
A facade constitutes the weather-resistant outer envelope of a building, typically comprising curtain walls, cladding panels, or window wall assemblies engineered to manage thermal transmittance below 2.0 W/m²K while resisting wind loads exceeding 150 km/h. Its primary function balances structural protection with daylight optimization and HVAC load reduction. Glass dominates value capture in premium commercial towers, while composite materials represent the fastest-growing category as Brazilian developers pursue lighter structural loads. Stick-built installation retains volume leadership across mid-rise residential projects, though unitized systems command superior margins in accelerated construction schedules.
Brazil's ABNT thermal performance standards and Mexico's CONUEE energy efficiency codes jointly mandate solar heat gain coefficient thresholds that filter out conventional single-pane specifications. Colombia's green building council certification program and Peru's seismic-resistant construction regulations further segment market access by compliance capability. Stakeholders must monitor evolving municipal facade fire safety ordinances in Santiago and Buenos Aires, where aluminum composite panel restrictions are tightening following international incidents.
Market Dynamics
Unitized curtain wall systems are compressing construction schedules across Latin America's commercial high-rise pipeline, forcing material suppliers and installers to synchronize delivery precision with accelerated vertical build rates.
Growth Catalysts
- CONUEE Energy Efficiency Codes:Mexico's thermal performance mandates for non-residential buildings are filtering out single-pane specifications and redirecting procurement toward low-emissivity insulated glass units.
- Automotive Manufacturing Clusters:Climate-responsive envelope demand from Guanajuato's assembly plants and Tamaulipas electronics facilities is pulling advanced facade solutions into industrial construction.
- Green Building Incentives:Colombia's certification program for sustainable construction is accelerating aluminum composite panel specification across Bogotá and Medellín commercial towers.
Market Restraints
- Aluminum Price Volatility:Raw material swings for extruded aluminum profiles are compressing margin predictability for system fabricators serving mid-rise residential developers.
- Seismic Engineering Complexity:Peru's strict structural movement requirements for high-rise envelopes are extending design validation cycles and limiting supplier qualification.
- Fire Safety Ordinance Divergence:Santiago and Buenos Aires municipal restrictions on aluminum composite panel core materials are fragmenting product standardization across the Southern Cone.
Strategic Opportunities
- Pre-fabricated Panel Systems:Mexico's residential tower segment offers white space for factory-assembled window wall units that reduce on-site labor dependency.
- Photovoltaic Integration:Building-integrated solar facade technology convergence is creating new specification channels for curtain wall contractors serving São Paulo's net-zero commercial commitments.
- Andean Region Climate Adaptation:Bogotá's altitude-driven thermal performance requirements are opening specialized demand for high-performance glazing systems.
Industry Challenges
- Facade Engineering Talent Scarcity:Specialized computational fluid dynamics and thermal bridging analysis capabilities are concentrated among a limited pool of consultants in Panama and Costa Rica.
- Multi-jurisdictional Certification:ABNT compliance for Brazil, CONUEE for Mexico, and Colombia's green building council create overlapping documentation burdens for regional suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Facade Market |
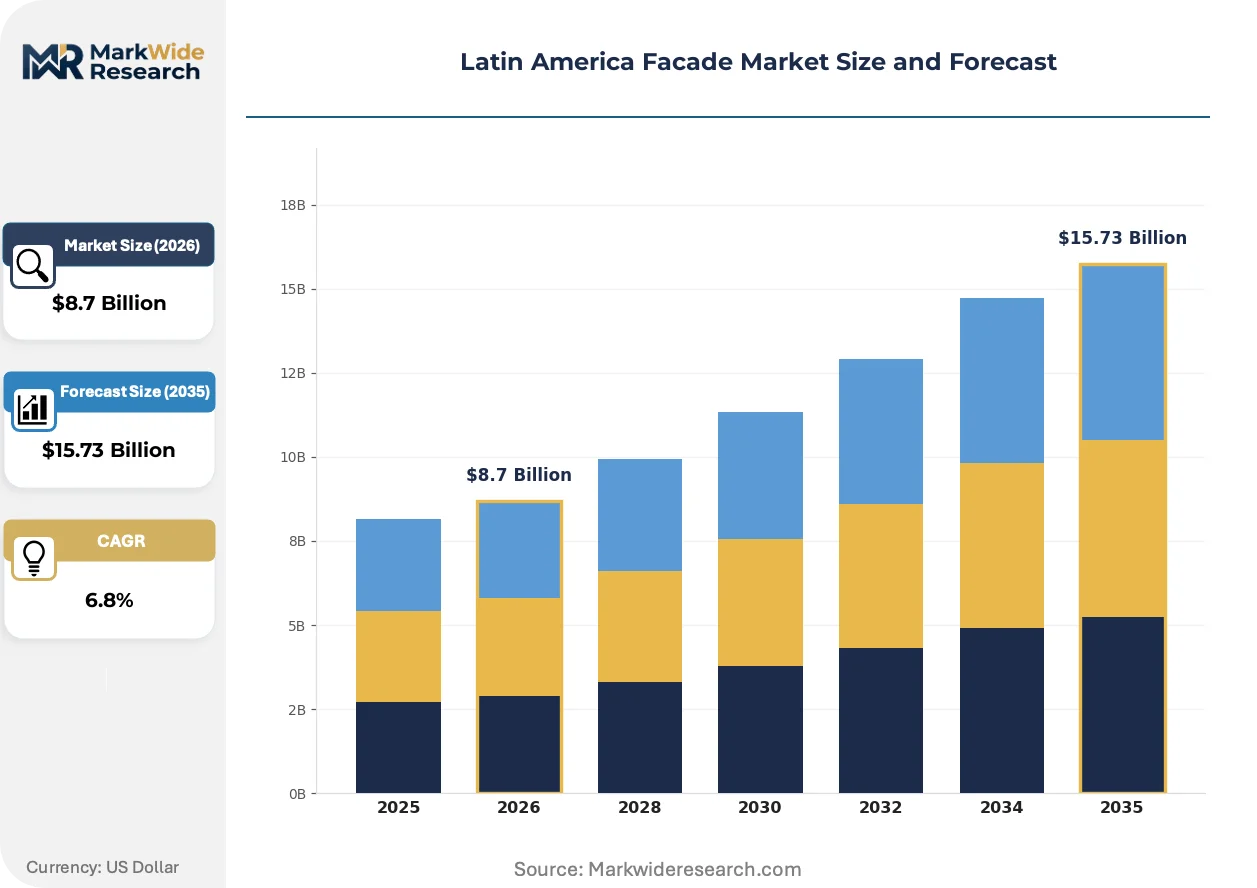
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Glass, Metal, Wood, Composite Installation Method: Unitized, Stick-built, Panelized, Pre-fabricated Building Type: Commercial, Residential, Industrial, Institutional Design Style: Modern, Traditional, Sustainable, Minimalist |
| Companies Covered | Estudio Marshall & Associates, Au-Mex, Tecnoglass Inc, PFEIFER Structures, Dante Tisi, Roofway, Mallol Arquitectos, ULMA, Ventanar, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Facade Market Shifts & Advancements
Digital fabrication and climate-responsive material science are compressing the gap between architectural intent and envelope performance across Latin America's vertical construction surge.
Electrochromic glazing is absorbing daylight management responsibilities previously handled by external shading systems. São Paulo's premium commercial developers are specifying switchable glass for floor-to-floor solar control without mechanical louvers. This technology is absorbing specification share from static low-emissivity units in towers targeting LEED Platinum equivalence.
Brazil's ABNT thermal performance standards and updated solar heat gain coefficient thresholds are mandating triple-pane configurations for high-rise commercial envelopes. The industrial consequence is disqualification of conventional single-pane suppliers from new construction eligibility. Developers in Rio de Janeiro and Brasília are responding by pre-qualifying only fabricators with in-house insulated glass production.
Design-build procurement consolidation is compressing the traditional architect-bid-build sequence for facade packages. Mexican industrial developers are awarding turnkey envelope contracts directly to vertically integrated system suppliers, bypassing fragmented subcontractor tiers. This pattern is most visible in Querétaro's aerospace manufacturing facilities where schedule certainty outweighs first-cost optimization.
Latin America Facade Market Segmentation
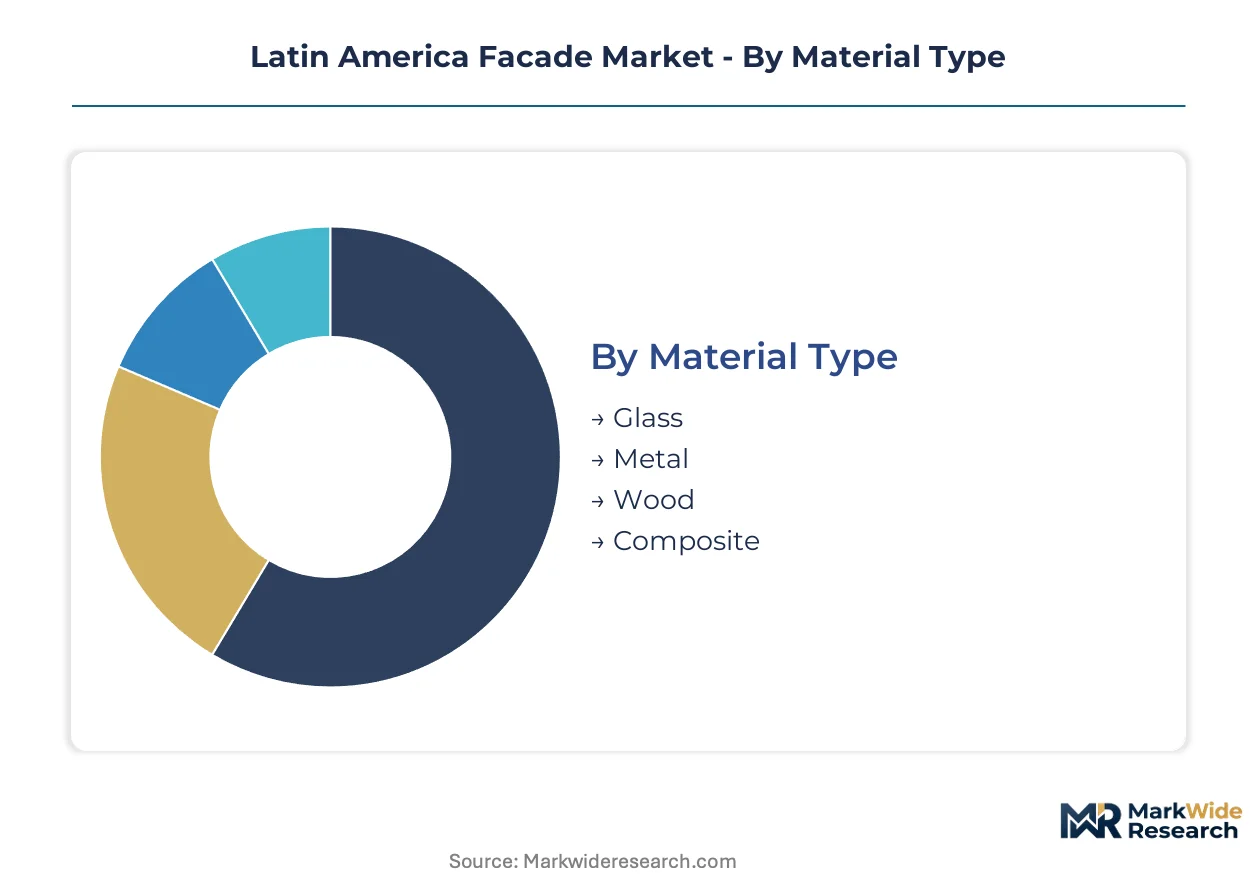
Facade specification across Latin America fragments along material performance, installation logistics, and building typology. Each segmentation axis reveals distinct procurement channels and margin structures that suppliers must navigate simultaneously.
Material Type:
Glass commands concentrated value capture in São Paulo and Mexico City high-rises, while metal and composite suppliers fight for share in mid-rise residential and industrial applications.
- Glass:Low-emissivity and triple-pane configurations dominate premium commercial towers. Brazil's ABNT thermal standards disqualify single-pane suppliers from new construction eligibility, concentrating procurement among fabricators with captive insulated glass production.
- Metal:Extruded aluminum profiles face margin compression from raw material price swings. Demand concentrates in mid-rise residential developers across Mexico's industrial corridor seeking lighter structural loads than glass alternatives permit.
- Wood:Limited to boutique institutional and heritage restoration projects in Colombia and Costa Rica. Moisture resistance treatments add cost layers that restrict specification outside climate-controlled interiors.
- Composite:Aluminum composite panels gain traction from Colombia's green building incentives. Fire safety ordinance divergence between Santiago and Buenos Aires fragments product standardization across the Southern Cone.
Today's leader: Glass. Tomorrow's challenger: Composite.
Installation Method:
Schedule acceleration in Latin America's vertical construction surge is reweighting procurement criteria toward factory precision and reduced on-site labor dependency.
- Unitized:Pre-assembled floor-to-floor modules compress construction timelines for commercial high-rises. São Paulo developers specify these systems where accelerated vertical build rates synchronize material delivery with crane schedules.
- Stick-built:Retains volume leadership across mid-rise residential projects through lower first-cost positioning. Field assembly tolerances widen in seismic zones, extending quality validation cycles.
- Panelized:Factory-assembled wall units reduce weather dependency for Bogotá's altitude-driven construction schedules. Logistics complexity limits penetration outside Andean region clusters.
- Pre-fabricated:Window wall systems target Mexico's residential tower segment with labor substitution value. Ventanar competes aggressively here with reduced on-site crew requirements.
Unitized systems capture premium margins; pre-fabricated panels are climbing the fastest as labor costs rise.
Building Type:
End-use differentiation separates climate-responsive envelope requirements from cosmetic cladding decisions across Latin America's construction pipeline.
- Commercial:High-rise towers in São Paulo and Mexico City mandate thermal transmittance below 2.0 W/m²K. Electrochromic glazing absorbs specification share from static low-emissivity units in LEED-targeting developments.
- Residential:Mid-rise towers across Mexico's industrial corridor prioritize cost-efficient window wall assemblies. Pre-fabricated panel systems reduce on-site labor dependency for accelerated delivery schedules.
- Industrial:Automotive and electronics manufacturing facilities in Guanajuato and Tamaulipas demand climate-responsive envelopes. HVAC load reduction drives insulated glass specification despite higher first costs.
- Institutional:Schools and healthcare facilities in Colombia and Peru face seismic engineering complexity. Extended design validation cycles limit supplier qualification to established regional fabricators.
Commercial towers anchor current revenue; industrial facilities represent the steepest expansion trajectory.
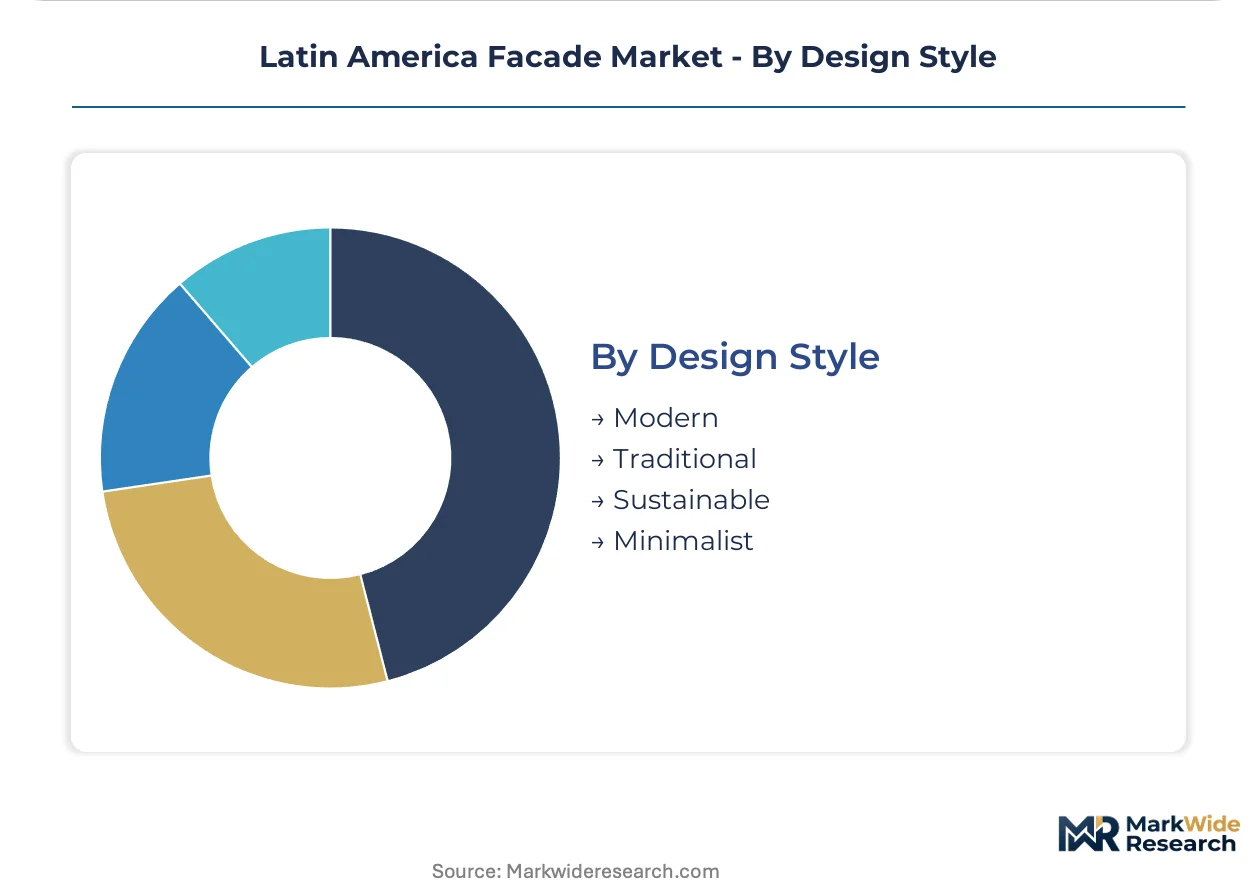
Design Style:
Architectural intent across Latin America is compressing into performance-driven minimalism, with sustainability mandates overtaking aesthetic differentiation in specification decisions.
- Modern:Floor-to-floor glass curtain walls dominate São Paulo's premium commercial pipeline. Clean sightlines demand unitized systems with concealed fastening and thermal break engineering.
- Traditional:Limited to heritage-sensitive districts in Mexico City and Cartagena. Local material sourcing requirements extend procurement timelines beyond standard commercial schedules.
- Sustainable:Colombia's green building council certification program accelerates aluminum composite panel specification. Photovoltaic integration creates new channels for curtain wall contractors serving net-zero commitments.
- Minimalist:Reduced visual mass drives demand for slim-profile framing systems. Thermal bridging analysis capabilities concentrate among limited consultant pools in Panama and Costa Rica.
Modern styling holds present dominance; sustainable design is gaining share fastest as certification mandates spread.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Guanajuato's automotive manufacturing corridor anchors facade demand across Mexico's industrial belt. Climate-responsive envelope specifications from assembly plants and electronics facilities are pulling advanced glazing systems into non-residential construction at accelerated rates.
Brazil
São Paulo's commercial high-rise pipeline drives specification of unitized curtain wall systems with thermal transmittance below 2.0 W/m²K. ABNT thermal performance standards mandate triple-pane configurations that disqualify conventional single-pane suppliers from new construction eligibility. Developers in Rio de Janeiro and Brasília pre-qualify only fabricators with captive insulated glass production.
Mexico
Querétaro's aerospace manufacturing facilities and Tamaulipas electronics plants demand climate-responsive envelopes for HVAC load reduction. CONUEE energy efficiency codes filter out single-pane specifications and redirect procurement toward low-emissivity insulated glass units. Design-build procurement consolidation compresses traditional architect-bid-build sequences for facade packages across the Bajío Region.
Colombia
Bogotá's altitude-driven thermal performance requirements open specialized demand for high-performance glazing systems. The national green building council certification program accelerates aluminum composite panel specification across commercial towers. Tecnoglass Inc anchors supply through vertically integrated glass manufacturing serving the Andean region.
Chile
Santiago's municipal fire safety ordinances tighten restrictions on aluminum composite panel core materials following international incidents. Seismic engineering complexity extends design validation cycles for high-rise envelopes. Premium commercial developers specify electrochromic glazing for floor-to-floor solar control without mechanical louvers.
Peru
Lima's institutional construction sector faces strict structural movement requirements for high-rise envelopes. Extended design validation cycles limit supplier qualification to established regional fabricators. Seismic-resistant construction regulations segment market access by compliance capability across healthcare and education facilities.
Latin America Facade Market Competitive Landscape
Capacity expansion dominates the current landscape as fabricators respond to compressed construction schedules across Latin America's vertical build surge. The vendor base stratifies into three tiers: multinational system suppliers with captive glass production, regional specialists in unitized engineering, and residential-focused panel fabricators. Vertically integrated players capture premium margins in accelerated commercial towers. Strategic partnerships between aluminum extruders and glazing contractors are displacing fragmented subcontractor tiers. Geographic expansion into adjacent Andean markets represents the second dominant competitive move.
Within the vertically integrated tier, Tecnoglass Inc exemplifies captive production advantages through its Colombian manufacturing base. Among regional engineering specialists, Mallol Arquitectos occupies a position in high-rise facade design across Panama and Costa Rica. Ventanar represents the residential-focused archetype competing aggressively in Mexico's tower segment with labor-reducing panel systems. These three anchors illustrate how competitive positioning fragments across material control, engineering specialization, and installation methodology rather than converging on uniform scale advantages.
| Leading Market Players |
|---|
| Estudio Marshall & Associates |
| Au-Mex |
| Tecnoglass Inc |
| PFEIFER Structures |
| Dante Tisi |
| Roofway |
| Mallol Arquitectos |
| ULMA |
| Ventanar |
| Others |
Supply & Pricing Matrix
Certification-grade divergence between ABNT-compliant thermal performance systems and conventional single-pane specifications splits Latin America's facade market into premium and commodity procurement channels with fundamentally different margin structures and supplier qualification requirements. This bifurcation concentrates pricing power among vertically integrated fabricators with captive insulated glass production while compressing returns for stick-built installers serving mid-rise residential developers.
Pricing Analysis
Aluminum extrusion cost pass-through dominates margin volatility for system fabricators serving Mexico's industrial corridor. Three-tier pricing structure across premium, standard, and economy levels separates unitized curtain wall contractors from panelized residential specialists and stick-built volume players. Pricing pressure stems from raw material swings for extruded aluminum profiles. Mid-rise residential developers exhibit highest price sensitivity; São Paulo premium commercial towers prioritize schedule certainty over first-cost optimization.
Supply Chain Analysis
Float glass supply rests on Brazilian and Colombian domestic production capacity, with specialty low-emissivity coatings drawing from imported raw materials. Extruded aluminum profiles hinge on Chilean and Mexican smelter output, while sealant and thermal break components feed from Argentine chemical processors. Single-source vulnerability concentrates in electrochromic glazing substrates. Distribution runs through vertically integrated system suppliers bypassing fragmented subcontractor tiers in accelerated commercial towers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Latin America's facade market compounds steadily as urban densification across São Paulo and Mexico City sustains replacement demand and thermal code upgrades force continuous specification advancement.
For Market Incumbents: Deploy captive glass production capacity to defend margin position against aluminum price volatility and emerging panelized competitors. Expand engineering consultancy capabilities in seismic-resistant design to capture Peru and Chile institutional construction. Deepen backward integration into aluminum extrusion to offset raw material swing exposure. For New Entrants and Emerging Players: Colombia's green building council certification program opens a window for aluminum composite panel specialists to penetrate Bogotá commercial towers. Target Mexico's residential tower segment with pre-fabricated window wall systems that reduce on-site labor dependency. Pursue design-build procurement relationships with Bajío Region industrial developers seeking turnkey envelope solutions. For Investors and Strategic Acquirers: Consolidation pressure builds where facade engineering talent scarcity concentrates computational fluid dynamics capabilities among limited Panama and Costa Rica consultancies. Long-term viability favors vertically integrated fabricators with captive insulated glass production and multi-jurisdictional certification documentation. Watch electrochromic glazing adoption rates in LEED-targeting developments as inflection indicator for premium specification shift.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Aluminum Extrusion | Mitigates raw material price volatility for Brazilian system fabricators serving ABNT-mandated projects. |
| Seismic Engineering Certification Investment | Unlocks Peru and Chile institutional construction where strict structural movement requirements limit supplier qualification. |
| Pre-fabricated Panel System Launch | Captures Mexico residential tower demand with labor-reducing window wall assemblies from Ventanar-competing entrants. |
| Photovoltaic Facade Integration Partnership | Creates specification channels for São Paulo net-zero commercial commitments through building-integrated solar technology. |
| Andean Region Geographic Expansion | Addresses Bogotá altitude-driven thermal performance requirements with specialized high-performance glazing distribution. |
Research Methodology
Coverage spans Brazil, Mexico, Colombia, Chile, and Peru, with primary inputs from each market combining interviews with facade system fabricators, commercial tower developers, industrial facility procurement managers, and seismic engineering consultants with secondary validation. Secondary sources include ABNT thermal performance filings, CONUEE energy efficiency code documentation, Colombia Green Building Council certification databases, and customs trade data on aluminum extrusion imports. Bottom-up project pipeline analysis triangulates against top-down construction expenditure estimates.
Rate-of-change decomposition separates volume growth from specification upgrade value capture across the analysis window. Segmentation dimensions modeled include material type, installation method, building typology, and thermal performance tier. CAGRs derive from regression against construction permit data and energy code implementation schedules. Industry-specific inputs incorporate ABNT triple-pane mandate compliance timelines and CONUEE solar heat gain coefficient threshold enforcement patterns.
Forecast precision tightens around the base case; tail outcomes carry wider variance under aluminum price volatility extremes and municipal fire safety ordinance divergence. Forecasts reflect documented assumptions on code implementation schedules and construction financing availability. A small set of triggers warrants ongoing watch: electrochromic glazing cost curves, seismic code revisions in Peru, and Southern Cone aluminum composite panel restrictions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Drywall Joint Tape Market
Building Materials
Global Magnesia Chrome Brick Market
Building Materials
Middle-East and Africa Buildings and Construction Sheets Market
Building Materials
Sprayed Concrete Market
Building Materials
US Facade Market
Building Materials
US Contract Glazing Market
Building Materials
Asia-Pacific Facade Market
Building Materials
North America Construction Aggregates Market
Building Materials
Fire Resistant Mortar Market
Building Materials
Composite Rebar Market
Building Materials
Asia-Pacific Dry-Mix Mortar Market
Building Materials
Cribbing Blocks Market
Building Materials
Natural Stone Market
Building Materials
GCC Concealed Cistern Market
Building Materials
Singapore Architectural Coatings Market
Building Materials
Ireland Cement Market