
 Fiberglass Doors Market | 2026-2036
Fiberglass Doors Market Size, Share, and Industry Trends Forecast 2026-2036
Fiberglass Doors Market Foresight
China's manufacturing corridor is narrowing the cost gap with North American producers of fiberglass door skins and frame assemblies. Therma-Tru Doors leverages its Ohio-based pultrusion capacity to sustain domestic supply chain advantages. Masonite competes through broad distribution coverage across big-box retail and pro-dealer channels. Jeld-Wen Holding, Inc anchors its position with vertically integrated composite pressing operations in the southeastern United States.
Fiberglass doors are engineered entry systems comprising glass-reinforced polymer skins bonded to insulated foam cores, typically achieving R-values between R-5 and R-10 depending on thickness and core chemistry. These assemblies resist moisture infiltration, thermal bowing, and insect degradation better than traditional wood or steel alternatives, making them standard for residential and light commercial exterior openings. Entry doors command the largest volume share due to universal replacement cycles and code-mandated performance minimums, while energy-efficient insulation configurations capture expanding margin pools as utility rebates tighten eligibility thresholds. Patio doors represent the fastest-growing product type as open-concept residential design extends glass wall demand into mid-market housing segments.
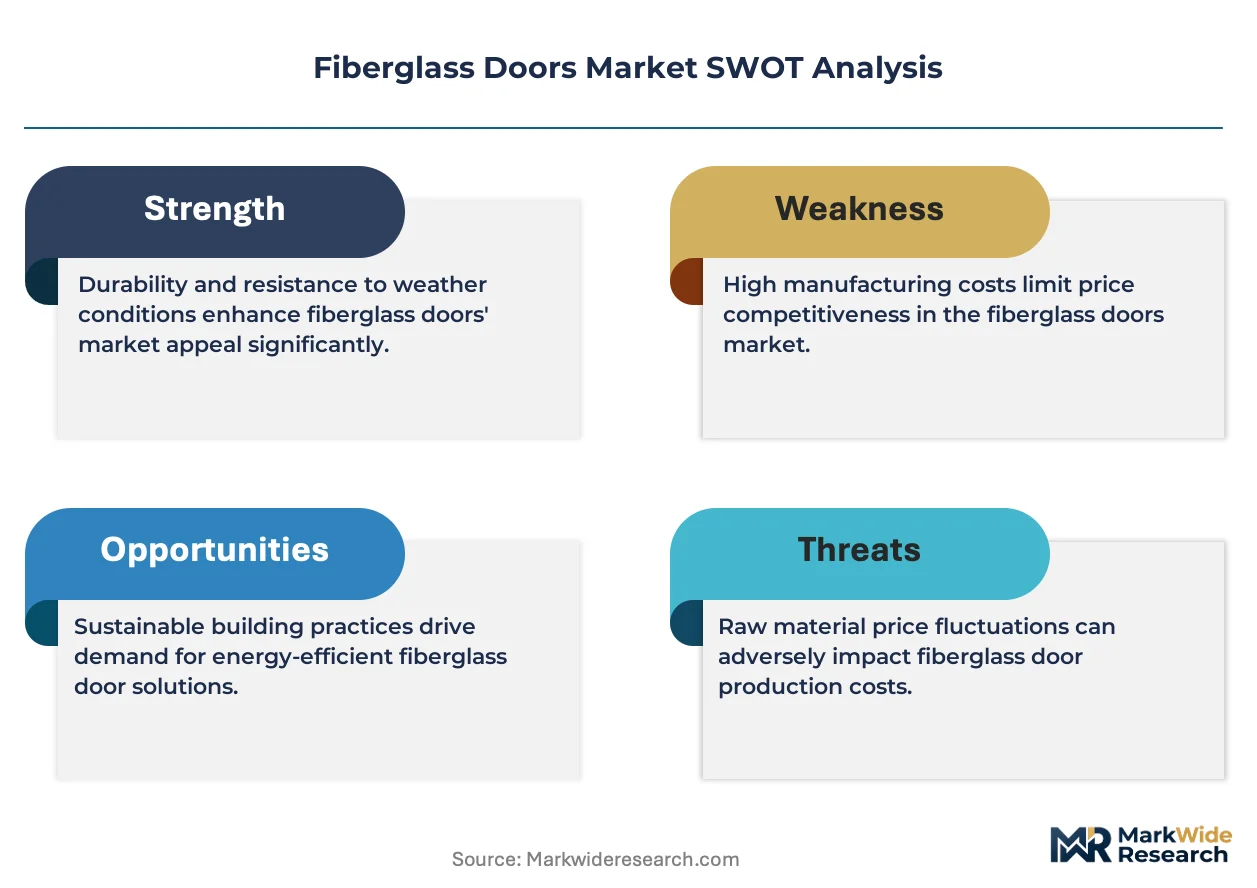
EPA Energy Star certification and DOE building envelope standards shape product development priorities, forcing manufacturers to validate thermal performance through third-party NFRC ratings before qualifying for utility incentive programs. The International Residential Code adoption across U.S. municipalities further standardizes air leakage maximums that fiberglass systems routinely satisfy. Stakeholders must monitor state-level stretch codes in California and New York, where net-ready building mandates will soon require doors to integrate with whole-home energy management systems rather than meeting static R-value thresholds alone.
Market Dynamics
EPA Energy Star certification thresholds and DOE building envelope code revisions are compressing product development cycles, forcing manufacturers to validate thermal performance through third-party NFRC ratings before qualifying for utility incentive programs.
Growth Catalysts
- Net-Ready Building Mandates:California and New York stretch codes now require doors to integrate with whole-home energy management systems rather than meeting static R-value thresholds alone.
- Pultrusion Process Advancements:Automated fiber placement and resin injection systems are reducing skin-to-core delamination defects while accelerating production throughput for entry system manufacturers.
- Sun Belt Construction:Residential development across Florida, Texas, and Arizona is generating sustained volume for thermally stable entry systems that resist humidity-induced warping.
Market Restraints
- Petrochemical Input Volatility:Styrene and unsaturated polyester resin prices fluctuate with crude oil benchmarks, compressing margin predictability for composite skin producers.
- Chinese Manufacturing Concentration:Door skin and frame assembly production clusters in Guangdong and Zhejiang provinces create supply chain vulnerability for North American distributors dependent on imported components.
- Steel Door Substitution:Cold-rolled steel entry systems retain cost advantage in multi-family housing segments where thermal performance requirements remain less stringent.
Strategic Opportunities
- Smart Home Integration:Embedded sensor arrays and wireless connectivity modules are enabling doors to communicate with HVAC and security systems, opening premium pricing tiers.
- IRA Tax Credits:The Inflation Reduction Act's residential efficiency rebates are expanding eligible product categories to include high-performance entry systems with verified air leakage ratings.
- Patio Door Expansion:Open-concept residential design is extending glass wall demand into mid-market housing segments previously served by sliding vinyl alternatives.
Industry Challenges
- NFRC Certification Timelines:Third-party thermal performance validation requires 12-18 month testing cycles, delaying product launches and freezing SKU rationalization decisions.
- Composite Pressing Capex:Vertically integrated frame production demands continuous lamination presses exceeding $4 million per line, constraining mid-tier manufacturer expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fiberglass Doors Market |
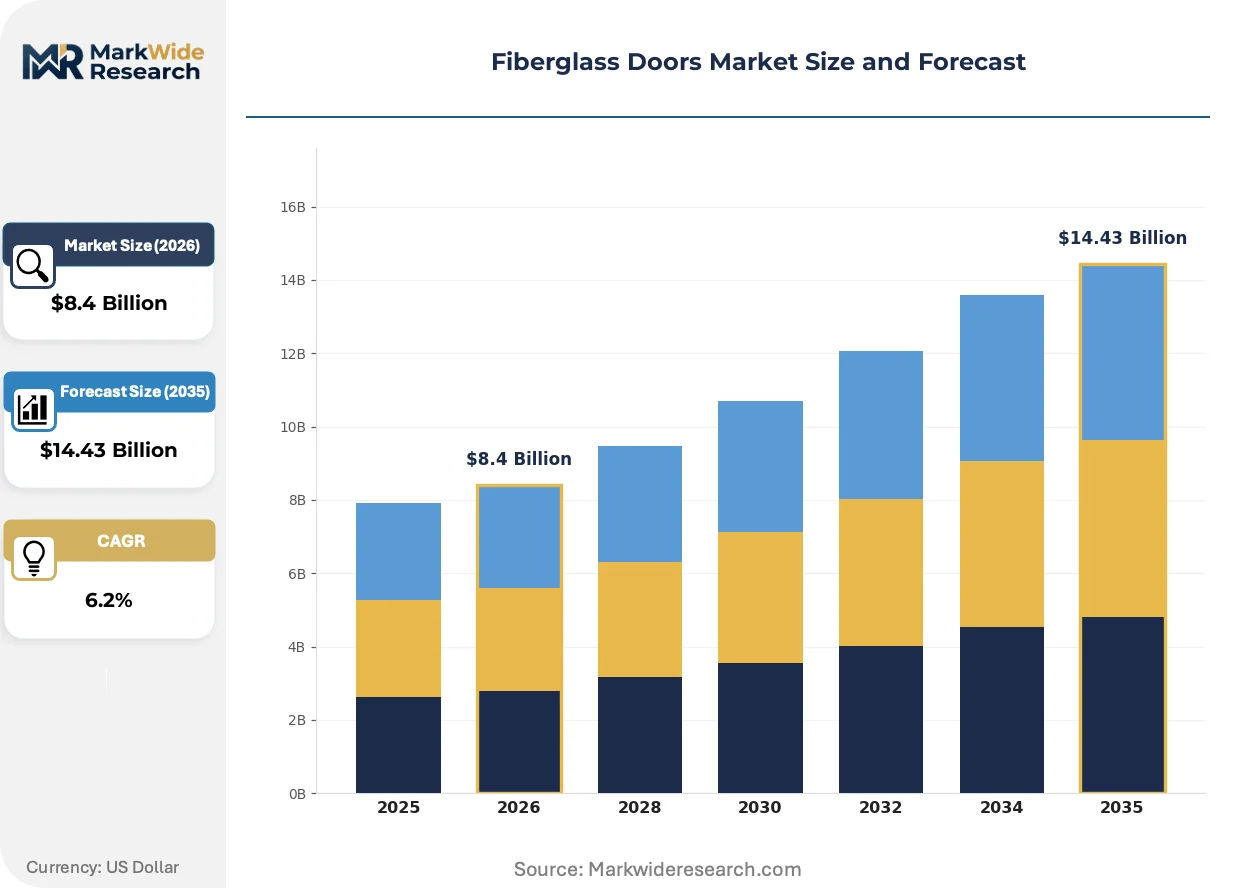
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $14.43 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Entry Doors, Patio Doors, French Doors, Sliding Doors Insulation Type: High-Performance, Thermal Break, Energy Efficient, Soundproof Design Style: Traditional, Modern, Rustic, Craftsman Installation Type: New Construction, Replacement, Retrofit, Custom |
| Companies Covered | Therma-Tru Doors, Jeld-Wen Holding, Inc, Masonite, Pella Corporation, Plastpro, Assa Abloy AB, Bayer Built Inc., ProVia, ETO Doors Corp., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fiberglass Doors Market Shifts & Advancements
Digital fabrication and regulatory tightening are converging to reshape how fiberglass entry systems are engineered, certified, and procured across residential and light commercial construction channels.
Embedded sensor networks is digitizing door assemblies into active building envelope components. High-volume residential developers in Texas and Florida are specifying pre-wired frames with humidity and intrusion detection as standard features on premium subdivisions. This capability expansion is digitizing the traditional entry system from a passive barrier into a data node that feeds whole-home energy management platforms.
The DOE's pending building envelope standard revisions will mandate blower-door-verified air leakage maximums for all residential new construction. Manufacturers must redesign jamb-to-frame interfaces and weatherstripping compression systems to achieve sub-0.3 cfm/sf ratings. Entry door assemblies with existing NFRC certifications face retrofit pressure, while patio door systems encounter particular difficulty meeting the proposed thresholds due to sliding panel geometry.
Pro-dealer channel consolidation is compressing distributor relationships into fewer, larger networks with national purchasing agreements. Independent lumberyards in the Midwest and Southeast are losing specification influence to consolidated pro-dealer banners with centralized composite door procurement. This concentration is most visible in the replacement market, where national renovation platforms now direct homeowner traffic toward certified installer networks rather than traditional retail showrooms.
Fiberglass Doors Market Segmentation
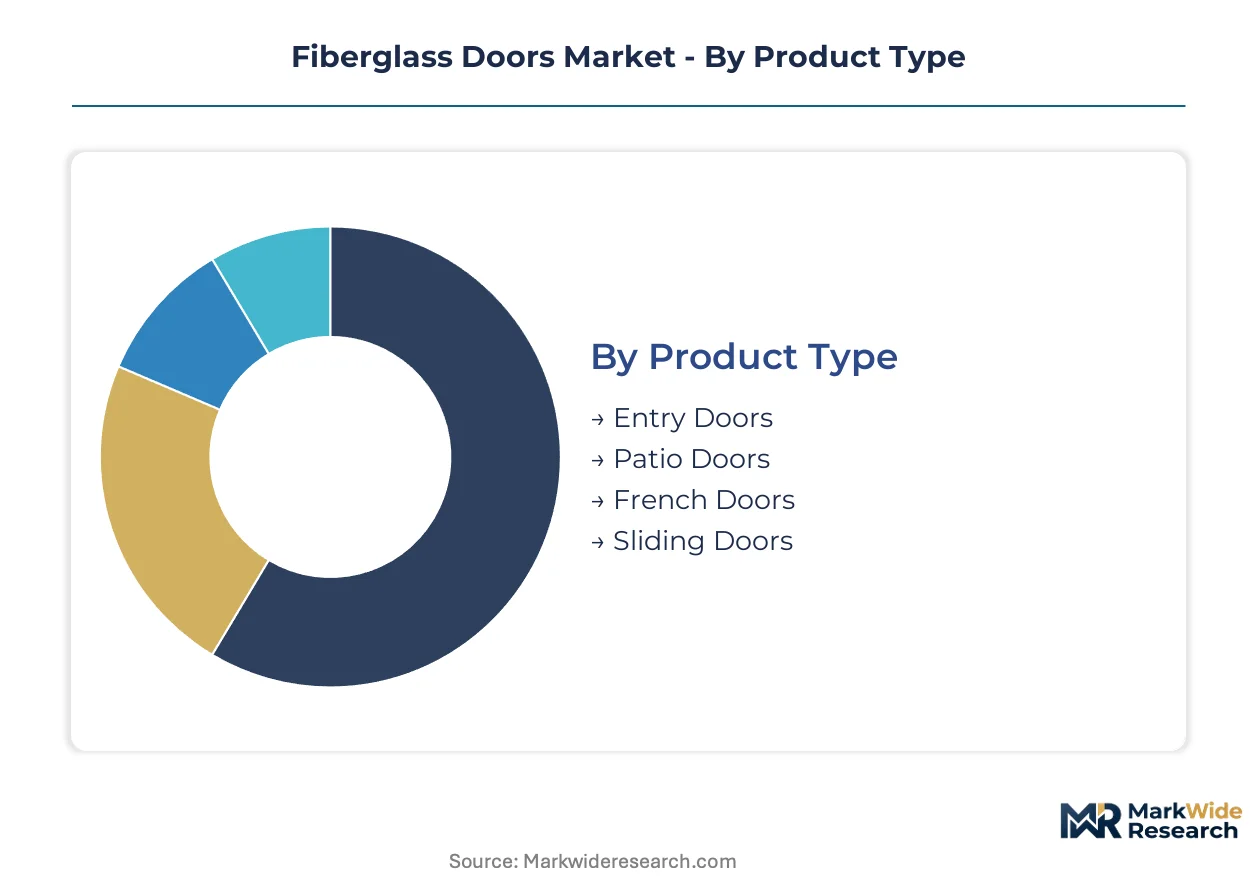
Fiberglass door manufacturers engineer product portfolios around distinct performance tiers and installation contexts. Segment boundaries determine warranty structures, distribution channel selection, and the intensity of technical support required post-installation.
Product Type:
After-sales service intensity varies sharply across product types, with entry systems demanding rapid response capabilities for security failures while patio installations require specialized glazing contractors.
- Entry Doors:Reinforced polymer skins bonded to polyurethane foam cores create assemblies rated for forced-entry resistance and thermal performance. Demand concentrates in Sun Belt states where replacement cycles accelerate due to UV exposure and humidity-induced frame degradation. These systems require certified installer networks for warranty validation.
- Patio Doors:Multi-panel sliding or hinged configurations with expanded glass ratios challenge thermal performance targets. Residential developers in Florida and Texas specify these for open-concept floor plans, though sliding panel geometry complicates air leakage certification under pending DOE envelope standards. Field service complexity exceeds entry door equivalents due to roller mechanism maintenance.
- French Doors:Hinged paired panels with traditional sightlines serve formal living spaces. Demand clusters in Northeastern renovation markets where historic district guidelines restrict material substitutions.
- Sliding Doors:Single-track configurations maximize opening width for backyard access. Multi-family housing in Arizona and California drives volume where space constraints eliminate swing alternatives.
Entry doors hold the largest share; momentum sits with patio doors.
Insulation Type:
Cost tier stratification separates specification-grade systems from code-minimum alternatives, with rebate eligibility thresholds creating sharp price-performance discontinuities.
- High-Performance:Multi-chamber cores with aerogel or vacuum-insulated panels achieve R-values exceeding R-10. Net-ready building mandates in California and New York stretch codes now require these configurations for whole-home energy management integration. Premium pricing depends on NFRC certification maintenance.
- Thermal Break:Polyamide strips interrupt conductive pathways between interior and exterior frame surfaces. Cold-climate residential construction in Minnesota and Wisconsin specifies these for condensation resistance, though petrochemical input volatility compresses margin stability.
- Energy Efficient:Standard polyurethane cores meeting EPA Energy Star thresholds without specialized engineering. Utility rebate programs in Texas and Florida expand eligible product categories under IRA residential efficiency provisions.
- Soundproof:Denser core chemistries and laminated glass packages target urban infill projects near transportation corridors. Multi-family developers in Chicago and Seattle specify these for lease rate premiums.
Energy efficient configurations dominate volume; high-performance systems are climbing the fastest.
Design Style:
Customer type segmentation distinguishes production homebuilders seeking standardized SKUs from custom residential architects specifying unique panel profiles.
- Traditional:Raised panel profiles with decorative glass inserts replicate historic wood door aesthetics. Replacement markets in the Northeast and Midwest sustain demand where homeowners associations enforce architectural consistency.
- Modern:Flush surfaces with minimal hardware and expansive lites align with contemporary residential architecture. Speculative builders in Austin and Denver specify these for millennial buyer segments.
- Rustic:Distressed textures and iron grille patterns serve mountain and lakefront vacation properties. Colorado and Montana regional dealers maintain specialized inventory for this segment.
- Craftsman:Shaker-inspired lines with tapered stiles reference early 20th-century design movements. Pacific Northwest markets show concentration due to regional architectural heritage preservation.
Traditional styling commands the largest share; modern designs are gaining share fastest.
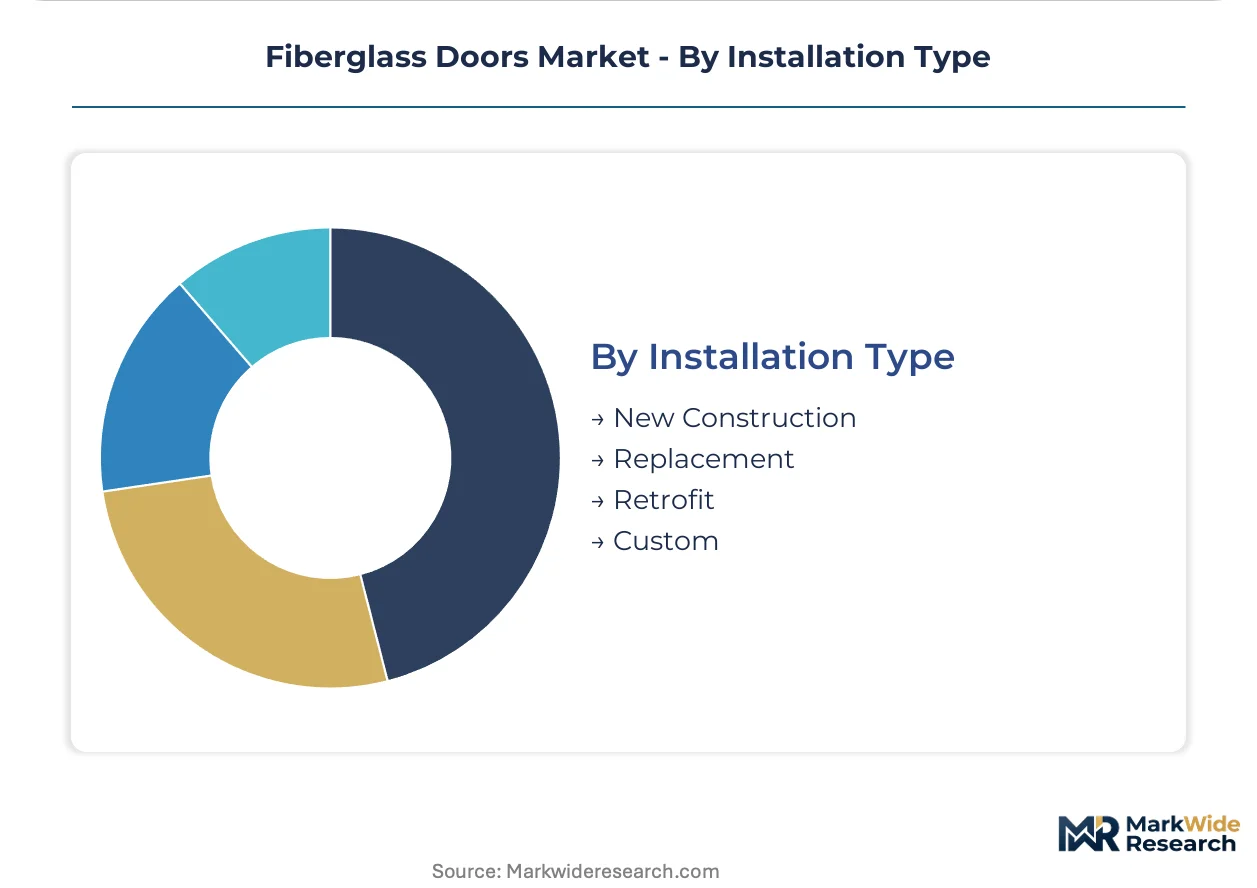
Installation Type:
Application context determines lead time requirements, with new construction demanding just-in-time delivery coordination and replacement installations requiring rapid turnaround on measured openings.
- New Construction:Production homebuilders specify standardized rough openings with bulk purchasing agreements. Sun Belt volume concentrates with national builders in Phoenix, Houston, and Atlanta metropolitan areas.
- Replacement:Aging entry system failures drive emergency procurement decisions. Independent remodeling contractors in the Midwest rely on pro-dealer networks with same-day availability for common jamb widths.
- Retrofit:Historic structure modifications require custom jamb extensions and casing profiles. Preservation specialists in Boston and Philadelphia maintain relationships with regional millwork shops.
- Custom:Non-standard dimensions and specialized glazing specifications serve architect-designed residences. Lead times extend 8-12 weeks due to NFRC recertification requirements for modified assemblies.
Replacement installations hold the largest share; custom work shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Long Beach anchors North American fiberglass door distribution, handling resin feedstocks and finished assemblies from Asian manufacturing corridors while serving as the primary entry point for Sun Belt construction materials.
United States
Replacement cycles for aging entryways in the Midwest and new construction across Florida, Texas, and Arizona drive sustained volume. EPA Energy Star certification requirements and DOE building envelope code revisions compress product development timelines for domestic manufacturers. Pultrusion operations in Ohio and composite pressing facilities across the Southeast concentrate domestic supply chain capacity.
China
Guangdong and Zhejiang provinces host concentrated manufacturing clusters producing door skins and frame assemblies for export markets. MIIT industrial standards and dual carbon goals shape factory upgrading requirements for energy-intensive composite production. Shenzhen and Ningbo ports facilitate containerized shipments to North American distributors.
Germany
Cold-climate thermal performance specifications from the federal building code drive demand for high-R-value entry systems in residential renovation markets. REACH chemical compliance requirements restrict certain resin formulations used in glass-reinforced polymer skins. Industrial clusters in North Rhine-Westphalia and Bavaria maintain specialized fabrication capacity for premium architectural segments.
Canada
Energy efficiency rebate programs at the provincial level expand eligible product categories for high-performance entry systems. Health Canada and PMRA regulations govern chemical emissions from foam core insulations used in door assemblies. Manufacturing concentration in Ontario serves cross-border supply chains into the US Northeast and Midwest replacement markets.
India
Rapid urbanization in Maharashtra and Gujarat generates construction volume for thermally stable entry systems in high-humidity coastal zones. BIS certification requirements for building materials create compliance barriers for imported composite products. The PLI scheme for construction materials incentivizes domestic manufacturing capacity for polymer-based building envelope components.
Fiberglass Doors Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying glass-reinforced polymer skins, insulated cores, and hardware assemblies. The vendor base organizes around three strategic archetypes: vertically integrated manufacturers with captive pultrusion capacity, distribution-focused assemblers sourcing components from global supply chains, and specialty fabricators serving custom architectural specifications. Competitive positioning sharpens through M&A consolidation of pro-dealer networks and geographic expansion into Sun Belt construction corridors.
Among North American platform integrators, Therma-Tru Doors, Jeld-Wen Holding, Inc, and Masonite exemplify distinct strategic positions. Therma-Tru occupies a position anchored by Ohio-based pultrusion capacity. Jeld-Wen represents vertically integrated composite pressing operations concentrated in the southeastern United States. Masonite exemplifies distribution breadth across big-box retail and pro-dealer channels. These three entities collectively illustrate how supply chain configuration, manufacturing geography, and channel access define competitive differentiation in residential entry systems.
| Leading Market Players |
|---|
| Therma-Tru Doors |
| Jeld-Wen Holding, Inc |
| Masonite |
| Pella Corporation |
| Plastpro |
| Assa Abloy AB |
| Bayer Built Inc. |
| ProVia |
| ETO Doors Corp. |
| Others |
Supply & Pricing Matrix
Petrochemical input volatility determines both pricing tier spreads and supply chain shape in fiberglass door manufacturing. Styrene and unsaturated polyester resin price swings compress margin predictability for composite skin producers while forcing distributors to maintain dual-sourcing strategies across domestic pultrusion operations and Asian component imports.
Pricing Analysis
Volume-discount tiering structures separate national builder programs from independent pro-dealer procurement. Three-tier pricing stratification across premium, standard, and economy levels reflects NFRC certification grade and thermal performance tier. Cost compression in economy segments is intensifying because steel door substitution retains advantage in multi-family housing. Production homebuilders exhibit highest price sensitivity; custom residential architects demonstrate lowest.
Supply Chain Analysis
Export-control regime limitations on advanced composite manufacturing equipment constrain capacity expansion outside established corridors. Production gravity centers on China, the United States, and Germany. Door skin fabrication draws from glass fiber rovings, polyurethane foam cores, and thermoset resin formulations. Single-source vulnerability concentrates in Guangdong and Zhejiang province clusters. Distribution runs through consolidated pro-dealer networks with national purchasing agreements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story anchored by regulatory entrenchment. NFRC certification timelines and DOE code compliance create switching costs that protect established positions.
For Market Incumbents: Build certification moats by accelerating NFRC pre-validation investments ahead of pending DOE envelope standard revisions. Secure captive pultrusion capacity in Ohio and southeastern states to offset Chinese component dependency. Masonite and Jeld-Wen demonstrate channel control through pro-dealer consolidation.
For New Entrants and Emerging Players: Build out smart home integration capabilities as a white-space target, embedding sensor arrays and wireless connectivity modules that incumbents have underdeveloped. Focus on patio door segments where sliding panel geometry complicates air leakage certification and creates specification gaps. Pursue direct relationships with Sun Belt production homebuilders bypassing traditional distributor layers.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors vertically integrated manufacturers with captive composite pressing operations. Long-term viability hinges on regulatory compliance infrastructure rather than commodity cost position. Acquisition targets should display established NFRC certification pipelines and Sun Belt distribution density. Monitor IRA tax credit implementation velocity as inflection indicator for premium segment demand.
| Strategic Initiative | Industry Significance |
|---|---|
| NFRC Certification Pre-Investment | Accelerates product launch timelines ahead of DOE envelope code revisions. |
| Captive Pultrusion Capacity Addition | Reduces dependency on Chinese door skin imports amid tariff exposure. |
| Smart Home Integration Development | Opens premium pricing tiers through HVAC and security system connectivity. |
| Pro-Dealer Network Consolidation | Concentrates specification influence in replacement market channels. |
| Sun Belt Manufacturing Footprint | Positions supply adjacent to Florida, Texas, and Arizona construction volume. |
Research Methodology
Initial hypotheses were tested against primary input from residential builders, pro-dealer procurement managers, composite manufacturing engineers, and regulatory compliance officers and refined through secondary validation. Sources included EPA Energy Star certification databases, DOE building code adoption records, NFRC product directories, and customs trade data for resin feedstocks and finished assemblies. Bottom-up volume estimates triangulated with top-down construction spending allocations across the analysis window.
Demand-supply-balance framing anchored the analytical approach throughout the projection horizon. Segmentation dimensions modeled encompassed product type, insulation performance tier, design style, and installation context alongside regional construction permit velocity. CAGRs derived from historical replacement cycle analysis and new construction absorption rates. Forecast inputs incorporated utility rebate program expansion under IRA provisions and state-level stretch code adoption timelines.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese manufacturers with subsidized capacity expansion would shift outcomes. Material shifts in petrochemical input pricing or DOE envelope standard implementation schedules would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building & Construction Materials
Window Film Market
Building & Construction Materials
Insulating Glass Window Market
Building & Construction Materials
Drainage System Market
Building & Construction Materials
Insulated Metal Panels Market
Building & Construction Materials
Liquid Applied Roofing Market
Building & Construction Materials
Electrically Dimmable Exterior Window Systems for Premium Cabins Market
Building & Construction Materials
Soil Stabilization Market
Building & Construction Materials
Concrete Waterproofing with Crystalline Technology Market
Building & Construction Materials
Urethane Concrete Sealer Market
Building & Construction Materials
US Steel Merchant and Rebar Market
Building & Construction Materials
Europe Building Materials Market
Building & Construction Materials
Roof Cladding Market
Building & Construction Materials
Glass Curtain Wall Market
Building & Construction Materials
North America Gutter Guards Market
Building & Construction Materials
Drinking Water Pipe Repair Market
Building & Construction Materials
External Wall Insulation Board Market