
 India Cement Market | 2026-2036
India Cement Market Size, Share, and Industry Trends Forecast 2026-2036
India Cement Market Insights
Blended fuel systems and waste heat recovery is rewriting clinker-to-cement ratios across Indian kiln operations. UltraTech Cement Limited leverages its integrated limestone reserves to sustain among the lowest per-ton energy costs in the sector. Shree Cement Limited anchors its competitiveness through extreme manufacturing scale in Rajasthan and eastern markets. Ambuja Cements Limited differentiates via logistics innovation, using coastal movement to navigate inland freight bottlenecks.
Cement is a hydraulic binder produced by calcining limestone, clay, and corrective materials at approximately 1450°C to form clinker, then intergrinding with gypsum and supplementary cementitious materials to achieve specified compressive strength grades per IS 269 and IS 455. Its primary purpose is to bind aggregates into concrete for load-bearing structures, roads, and masonry applications across construction value chains. Portland cement occupies the dominant volume position but faces margin compression from rising petcoke and coal input costs. Blended cement captures structural growth as BIS mandates and green building codes elevate fly ash and slag inclusion rates. Infrastructure development represents the fastest-expanding application segment, driven by dedicated freight corridors, expressway buildouts, and urban metro expansion.
The Bureau of Indian Standards governs product certification through compulsory ISI marking, while the Central Pollution Control Board enforces emission caps on particulate matter and SOx from kiln stacks. The Cement Sustainability Initiative guidelines and state-level mining lease conditions together shape capital allocation toward cleaner pyroprocessing and alternative raw material sourcing. Stakeholders must monitor evolving clinker substitution mandates and carbon border adjustment preparations that could restructure export competitiveness and domestic procurement priorities.
Market Dynamics
Stricter clinker factor mandates from BIS are compressing traditional Portland cement margins while accelerating blended formulation adoption across kiln operations. This regulatory pressure is restructuring capital allocation toward alternative raw material sourcing and waste heat recovery systems.
Growth Catalysts
- Affordable Housing Mission:Central and state-sponsored housing programs are accelerating cement offtake from residential contractors across Maharashtra and Gujarat.
- Blended Cement Mandates:BIS clinker factor norms are pushing producers toward fly ash and slag inclusion, expanding addressable raw material supply.
- Freight Corridor Densification:Dedicated infrastructure corridors across western and southern states are concentrating bulk demand in logistics-advantaged clusters.
Market Restraints
- Petcoke and Coal Volatility:Thermal fuel input costs swing with import parity pricing, compressing per-ton margins for non-integrated producers.
- Limestone Lease Concentration:Captive mining rights cluster with integrated majors, raising entry barriers for new kiln capacity.
- Clinker Transport Economics:High freight costs per ton-kilometer penalize grinding-only operations distant from coastal clinker sources.
Strategic Opportunities
- Eastern Market Underpenetration:Rajasthan-based producers can extend distribution reach into Bihar and Odisha where per-capita consumption lags western averages.
- Coastal Logistics Arbitrage:Sea-borne clinker movement from Gujarat to Kerala and Tamil Nadu bypasses inland rail bottlenecks.
- Carbon Border Preparation:Early adoption of low-clinker blends positions exporters for EU CBAM compliance ahead of full implementation.
Industry Challenges
- Pyroprocessing Talent Scarcity:Experienced kiln operators and process engineers command premium compensation, constraining brownfield expansion timelines.
- Waste Heat Recovery Capex:WHR system installation requires substantial upfront capital with payback periods sensitive to power tariff volatility.
- BIS Certification Cycles:New blended formulation approvals face extended testing protocols, delaying product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Cement Market |
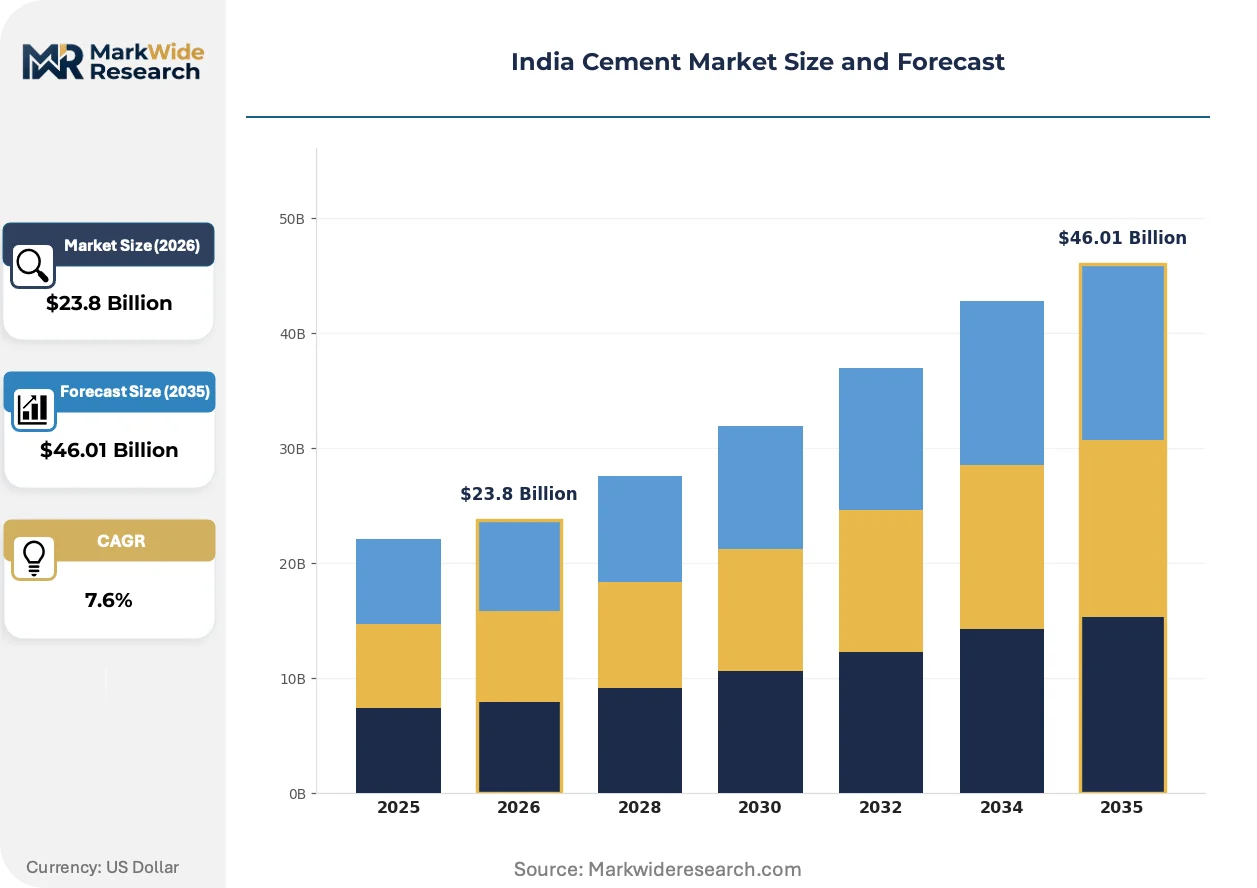
| Market Size in 2026 | $23.8 Billion |
| Market Size in 2035 | $46.01 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Portland Cement, Blended Cement, White Cement, Rapid Hardening Cement Application: Residential Construction, Infrastructure Development, Commercial Structures, Road Projects End User: Contractors, Builders, Government Projects, DIY Consumers Distribution Channel: Direct Sales, Retail Outlets, Online Sales, Wholesale Distributors |
| Companies Covered | UltraTech Cement Limited, ACC Limited, Ambuja Cements Limited, Shree Cement Limited, Dalmia Bharat Limited, JK Cement Limited, Ramco Cements Limited, Heidelberg Cement India Limited, India Cements Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Cement Market Trends and Innovations
Digital kiln control systems and alternative fuel injection are compressing energy intensity benchmarks while enabling higher substitution rates in clinker production. These shifts are redrawing competitive advantage around fuel sourcing flexibility rather than scale alone.
Calcined clay activation through flash calcination is collapsing the performance gap between blended cements and traditional Portland grades. Major infrastructure contractors in Gujarat and Maharashtra are specifying LC3-type formulations for bridge and highway projects. This technology is collapsing the premium pricing power historically attached to OPC 53-grade cement in structural applications.
BIS amendments to IS 455 and IS 269 are tightening compressive strength testing protocols and expanding permissible supplementary cementitious material inclusion rates. The Central Pollution Control Board is simultaneously enforcing stricter particulate emission caps on kiln stack operations. Blended cement producers with integrated fly ash sourcing are adapting faster than standalone grinding units dependent on merchant SCM supply.
State-level public works departments are consolidating annual cement procurement into multi-year framework agreements with pre-qualified suppliers. Bulk buyers in Tamil Nadu and Karnataka are bypassing traditional dealer networks for direct mill dispatch arrangements. This concentration is most visible in metro rail and expressway projects where single-source contracts now dominate material planning.
India Cement Market Segmentation
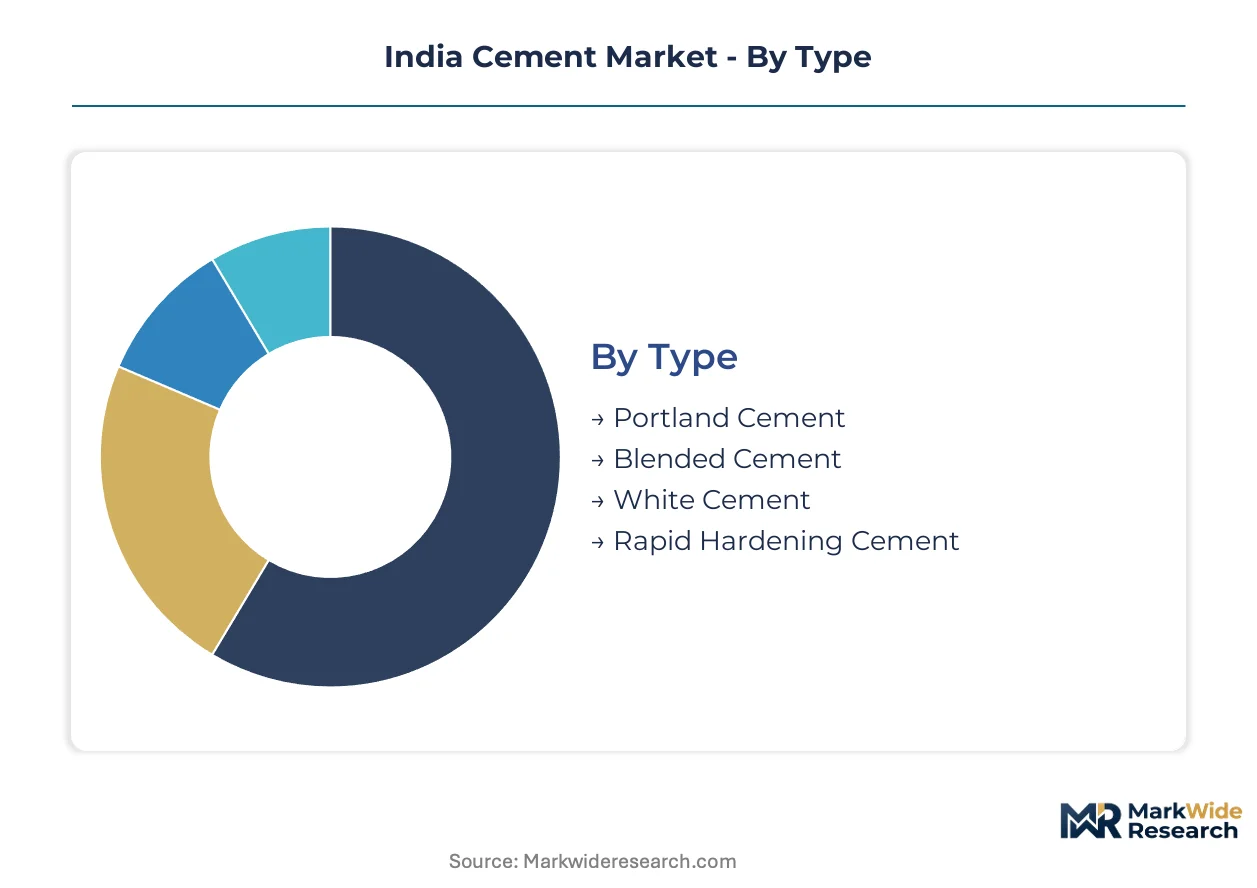
Segmentation in the India cement market exposes how regulatory mandates, fuel economics, and logistics infrastructure differentially reward specific product formulations and customer relationships. Understanding these fault lines clarifies where capital deployment and procurement strategy generate sustainable margin.
Type:
Cost tier differentiation separates commodity-grade binders from specialized formulations commanding specification premiums in structural applications.
- Portland Cement:Manufactured through calcination of limestone and clay at 1450°C to form clinker, then interground with gypsum to achieve compressive strengths per IS 269. Demand concentrates in legacy infrastructure projects across Maharashtra and Gujarat where contractors specify OPC 53-grade for bridge piers and high-rise columns, though BIS clinker factor mandates are compressing its margin advantage.
- Blended Cement:Incorporates fly ash, slag, or calcined clay as supplementary cementitious materials to reduce clinker content below 65 percent. Adoption accelerates in affordable housing programs across western states where BIS norms and green building codes elevate inclusion rates, expanding addressable raw material supply for integrated producers with captive SCM sourcing.
- White Cement:Derived from iron-free raw materials with specialized kiln firing and grinding protocols. Decorative façade applications in commercial developments drive offtake.
- Rapid Hardening Cement:Formulated through finer grinding and adjusted C3S content for accelerated early strength gain. Highway repair contracts and precast manufacturing specify this grade.
Portland cement commands the established base. The steepest expansion runs through blended cement.
Application:
Volume concentration tracks infrastructure corridor densification and housing program deployment across state-level procurement calendars.
- Residential Construction:Single-family housing and multi-story apartment blocks consume bulk cement volumes through frame structures, masonry, and plastering applications. Affordable housing missions in Maharashtra and Gujarat are accelerating offtake from regional contractors, with BIS blended cement mandates reshaping material specifications in government-subsidized projects.
- Infrastructure Development:Dedicated freight corridors, expressway buildouts, and urban metro expansion drive specification-grade demand. Metro rail projects in Tamil Nadu and Karnataka are consolidating procurement into multi-year framework agreements with pre-qualified suppliers, bypassing traditional dealer networks for direct mill dispatch.
- Commercial Structures:Office complexes, retail centers, and industrial facilities require high-performance concrete formulations. Premium specifications in Gujarat commercial developments favor white cement and specialized blends.
- Road Projects:National highway widening and rural road connectivity programs generate continuous bulk demand. Cement concrete pavement specifications in western corridor projects are elevating blended cement inclusion rates.
Infrastructure development captures the steepest volume trajectory. Residential construction maintains the deepest installed base.
End User:
Customer type determines pricing power, with institutional procurement concentrating volume and fragmenting margin across intermediated channels.
- Contractors:Project-based construction firms executing residential and commercial developments. Western India contractors are consolidating annual procurement through direct mill arrangements to bypass dealer markups.
- Builders:Real estate developers with multi-project portfolios and specification influence. Large builders in Maharashtra negotiate bulk supply agreements with logistics-advantaged producers.
- Government Projects:State public works departments and central infrastructure agencies. Tamil Nadu and Karnataka PWDs are consolidating cement procurement into framework agreements with pre-qualified suppliers.
- DIY Consumers:Individual homeowners and small-scale renovators purchasing through retail channels. Price sensitivity and brand recognition drive purchase decisions in this fragmented segment.
Government projects anchor volume concentration. Builder direct procurement is expanding most quickly.
Distribution Channel:
Supply chain configuration determines freight economics and working capital intensity, with coastal logistics arbitrage reshaping traditional rail-dependent flows.
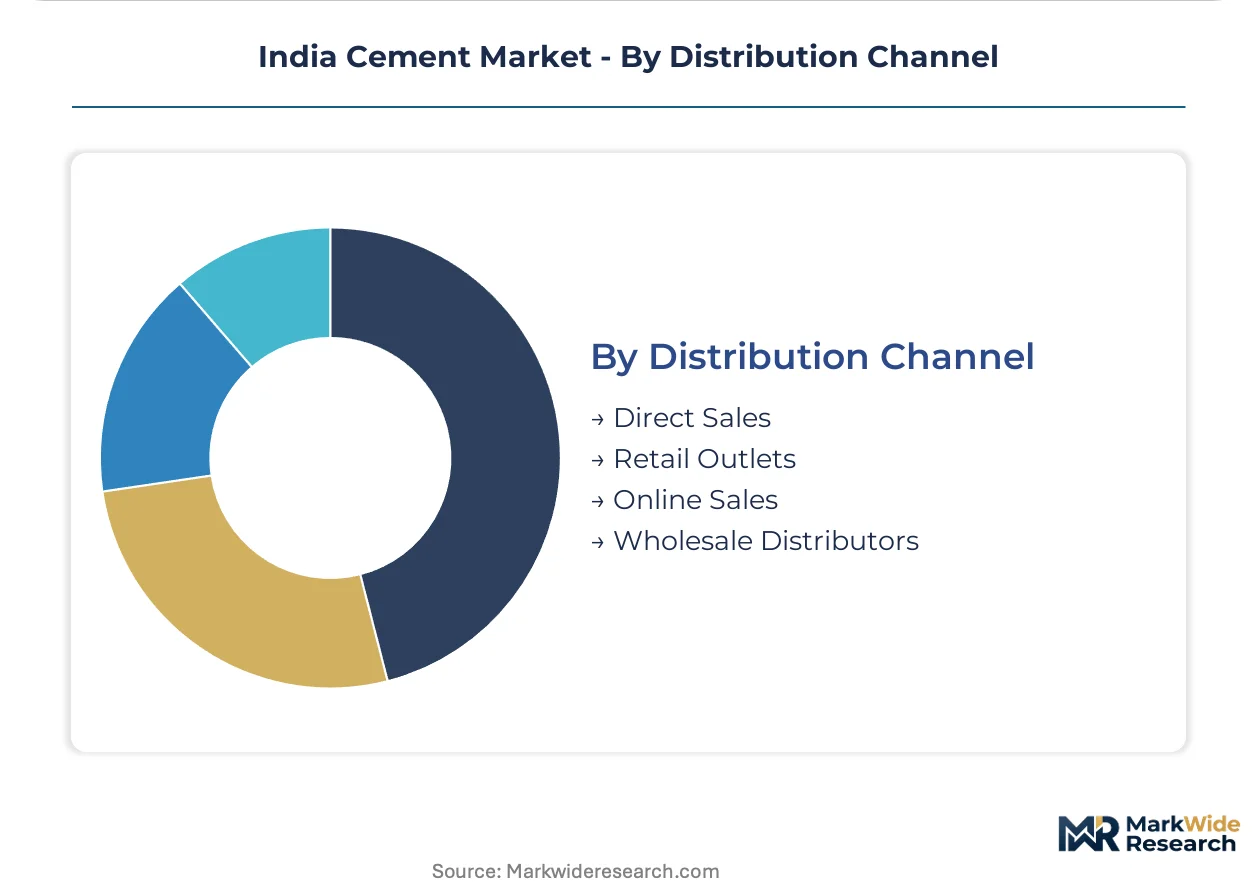
- Direct Sales:Mill-to-project bulk dispatch bypassing intermediaries. Metro rail and expressway contractors in Tamil Nadu and Karnataka are driving adoption of direct dispatch arrangements.
- Retail Outlets:Dealer networks serving fragmented residential and small commercial demand. Western states maintain dense retail penetration supporting contractor spot purchasing.
- Online Sales:Digital platforms aggregating small-order fulfillment. Urban DIY consumers and small contractors in tier-1 cities are testing this channel.
- Wholesale Distributors:Regional stockists managing inventory and credit for secondary markets. Eastern market penetration relies on distributor networks extending reach from Rajasthan production bases.
Direct sales capture the fastest-growing volume share. Retail outlets maintain the broadest geographic coverage.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Gujarat-based clinker producers ship bulk cement via coastal routes to Kerala and Tamil Nadu, bypassing congested inland rail corridors and capturing freight arbitrage against Rajasthan-origin supply.
Maharashtra
Mumbai-Pune expressway expansion and affordable housing missions in Thane and Nagpur are accelerating specification-grade cement offtake. BIS clinker factor mandates are compressing traditional Portland margins while elevating fly ash blend adoption. The Mumbai Metropolitan Region concentrates demand from metro rail contractors consolidating procurement through direct mill arrangements.
Gujarat
Dedicated freight corridors and port-led manufacturing clusters in Kutch and Saurashtra are densifying bulk demand. Central Pollution Control Board emission caps are pushing kiln operations toward waste heat recovery and alternative fuel injection. Mundra and Hazira ports enable sea-borne clinker movement to southern markets, restructuring traditional supply flows.
Karnataka
Bengaluru metro expansion and state highway widening programs are driving framework agreement procurement through pre-qualified supplier pools. State public works departments are consolidating annual cement purchases into multi-year contracts. The Bengaluru-Tumkur industrial corridor anchors grinding unit placement for logistics-advantaged distribution.
Tamil Nadu
Chennai metro rail and port modernization projects are concentrating specification-grade demand among integrated producers with coastal access. BIS blended cement mandates are accelerating slag and fly ash inclusion in government-subsidized housing. The Cuddalore-Nagapattinam belt hosts clinker import terminals serving grinding-only operations.
Rajasthan
Captive limestone reserves and extreme manufacturing scale in Chittorgarh and Jodhpur districts sustain among the lowest per-ton energy costs in the sector. Shree Cement Limited anchors production gravity here, extending distribution reach into underpenetrated Bihar and Odisha markets. Rail freight economics to eastern states remain the binding constraint on volume expansion.
India Cement Market Competitive Landscape
Channel-controlling players compete with product-specialist players across procurement consolidation trends and specification-grade positioning. The vendor base clusters around three tiers: integrated majors with captive limestone reserves, coastal logistics specialists leveraging sea-borne clinker movement, and regional grinding units dependent on merchant supply. Dominant competitive moves include brownfield kiln expansion in limestone-rich districts and direct sales force deployment to bypass dealer networks on bulk infrastructure contracts.
Within the integrated-major tier, UltraTech Cement Limited and Ambuja Cements Limited exemplify divergent logistics strategies—UltraTech leveraging inland limestone integration while Ambuja anchors coastal arbitrage. Shree Cement Limited occupies a position as the scale-driven specialist concentrated in Rajasthan and eastern markets. These three entities represent the structural archetypes shaping procurement consolidation and clinker substitution economics across Indian kiln operations.
| Leading Market Players |
|---|
| UltraTech Cement Limited |
| ACC Limited |
| Ambuja Cements Limited |
| Shree Cement Limited |
| Dalmia Bharat Limited |
| JK Cement Limited |
| Ramco Cements Limited |
| Heidelberg Cement India Limited |
| India Cements Limited |
| Others |
Pricing and Supply Chain Analysis
Chittorgarh and Jodhpur limestone clusters in Rajasthan concentrate captive mining rights among integrated majors, translating upstream resource control into pricing power over non-integrated grinding units dependent on merchant clinker supply. BIS clinker factor mandates are compressing traditional Portland cement premiums while elevating fly ash blend competitiveness, restructuring margin distribution across kiln operations.
Pricing Analysis
OPC 53-grade cement commands legacy specification premiums in bridge and high-rise applications, while LC3-type calcined clay formulations are collapsing the performance gap and eroding traditional grade-based pricing hierarchies. Three-tier pricing structure across premium specification, standard blended, and economy bulk grades differentiates by compressive strength certification and volume scale. Cost compression in standard blended tiers is intensifying because integrated producers with captive fly ash sourcing exploit BIS mandate compliance as a margin weapon. Government project contractors exhibit lowest price sensitivity due to framework agreement security, while DIY retail consumers drive hardest bargaining through dealer network fragmentation.
Supply Chain Analysis
Tariff exposure between petcoke-importing Indian kilns and volatile international fuel markets dominates supply chain risk calculus, amplifying margin volatility for non-integrated producers without captive thermal power. Manufacturing concentrates in Rajasthan, Gujarat, and Tamil Nadu, drawing from limestone reserves, coastal clinker terminals, and slag proximity to steel plants. Raw material dependencies rest on imported petcoke, domestic fly ash from thermal power stations, and merchant gypsum from Rajasthan and Gujarat mining leases. Single-source vulnerability concentrates in coastal clinker movement where Mundra and Hazira ports anchor sea-borne supply to Kerala and Tamil Nadu grinding units. Distribution runs through direct mill dispatch for bulk infrastructure contracts, retail dealer networks for fragmented residential demand, and wholesale stockists extending eastern market reach from Rajasthan production bases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Government project procurement consolidation into multi-year framework agreements is shifting buyer power toward institutional actors with volume concentration and specification influence, fragmenting margin across traditional dealer-intermediated channels.
For Market Incumbents: Entrench limestone reserve control through lease renewal investments in Chittorgarh and Jodhpur districts, while accelerating waste heat recovery deployment to defend energy cost position against petcoke volatility. Cement Sustainability Initiative compliance and BIS blended certification investment create regulatory moats against emerging grinding-only competitors lacking integrated pyroprocessing capability. Channel control through direct sales force deployment to Tamil Nadu and Karnataka metro rail contractors bypasses dealer markups and locks in specification-grade volume. For New Entrants and Emerging Players: Establish a beachhead in eastern market underpenetration zones—Bihar and Odisha—where per-capita consumption lags western averages and distributor-dependent supply chains create entry pathways for regional grinding units with merchant clinker sourcing. Coastal logistics arbitrage from Gujarat clinker terminals to Kerala and Tamil Nadu offers white-space positioning against rail-dependent Rajasthan majors. Go-to-market angle centers on government-subsidized affordable housing programs where BIS blended cement mandates favor agile formulation specialists over legacy Portland-dependent incumbents. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified conglomerates with non-core cement assets lacking captive limestone integration or coastal logistics positioning, particularly grinding-only operations in eastern states with merchant supply vulnerability. Long-term viability across the analysis window hinges on clinker substitution technology adoption and carbon border adjustment preparation for potential EU export exposure. Watch for BIS certification cycle acceleration and Central Pollution Control Board emission enforcement tightening as inflection signals for capital allocation toward cleaner pyroprocessing assets.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Limestone Mining | Captive reserve control in Rajasthan and Gujarat defends per-ton energy cost position against merchant supply volatility. |
| Waste Heat Recovery System Installation | BIS emission mandates and Central Pollution Control Board enforcement accelerate payback attractiveness for kiln stack retrofits. |
| Coastal Clinker Terminal Development | Sea-borne movement from Mundra and Hazira bypasses inland rail bottlenecks to Kerala and Tamil Nadu demand clusters. |
| LC3 Calcined Clay Formulation Scale-Up | Flash calcination technology collapses OPC 53-grade premium power in Gujarat and Maharashtra infrastructure specifications. |
| Direct Sales Force Deployment | Mill-to-project dispatch for Tamil Nadu and Karnataka metro rail contracts bypasses dealer networks and locks framework agreements. |
Research Methodology
Desk research of BIS certification records, Central Pollution Control Board emission filings, and state mining lease databases preceded structured interviews with kiln operations managers, clinker procurement leads at grinding units, public works department contract officers, and logistics coordinators at coastal terminals. Secondary validation drew from customs petcoke import data, Indian Bureau of Mines limestone production statistics, and infrastructure project tender disclosures. Bottom-up capacity modeling and top-down consumption estimation triangulated volume and value outputs.
Assumptions held fixed include BIS clinker factor mandate enforcement intensity, Central Pollution Control Board emission cap trajectories, and affordable housing program deployment calendars across Maharashtra and Gujarat. Variables included petcoke import parity pricing volatility, limestone lease renewal success rates, and slag availability from steel plant capacity cycles. Segmentation dimensions modeled encompassed product type, application, end user, and distribution channel, with regional production hub economics as an industry-specific overlay. CAGRs derived from trend extrapolation against infrastructure corridor densification and housing mission acceleration.
Sensitivities concentrate around petcoke tariff exposure, BIS blended cement approval cycle length, and eastern state rail freight economics revision. Forecasts reflect these assumption sets and risk factor weightings. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Zinc Polycarboxylate Cement Market
Building Materials
United States Architectural Coatings Market
Building Materials
North America Spray Polyurethane Foam for Building and Construction Market
Building Materials
Mexico Architectural Coatings Market
Building Materials
Saudi Arabia GRC Cladding Market
Building Materials
Pre-Fabricated Glass Block Market
Building Materials
Asia-Pacific Shotcrete Market
Building Materials
Concrete and Cement Market
Building Materials
North America Dry-Mix Mortar Market
Building Materials
Middle-East and Africa Buildings and Construction Sheets Market
Building Materials
Industrial Concrete Flooring Market
Building Materials
Cribbing Blocks Market
Building Materials
Global Corrugated Steel Sheets Market
Building Materials
West Africa Cement Market
Building Materials
Timber Frames Market
Building Materials
Door Frame Metal Market