
 Construction Materials Market | 2026-2036
Construction Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Construction Materials Market Analytics
Aftermarket service revenue in cement logistics is narrowing as producers bring fleet management in-house. Holcim leverages captive distribution networks across European markets to protect margin pools. UltraTech Cement anchors its South Asian position through backward integration into limestone mining. CRH competes in North American aggregates through disciplined quarry-to-project routing.
Construction materials encompass engineered substances—Portland cement clinker containing tricalcium silicate, graded aggregates per ASTM C33, and reinforced precast elements—fabricated for structural load-bearing, envelope performance, or finish applications in built environments. Cement commands the largest value pool among product types due to irreplaceable binding chemistry in concrete formulation, while green building technology attracts the fastest specification growth as project owners pursue LEED and BREEAM certification. Infrastructure projects consume the highest aggregate tonnage among applications, though residential buildings generate superior price realization per unit in premium urban markets.
EPA emission standards for Portland cement kilns, REACH registration requirements for construction chemicals in Europe, and India's BIS certification for structural steel collectively elevate compliance costs while accelerating substitution toward lower-carbon binders and recycled aggregates. Stakeholders must monitor regulatory tightening on embodied carbon disclosure as procurement specifications increasingly mandate Environmental Product Declarations before contract award.
Market Dynamics
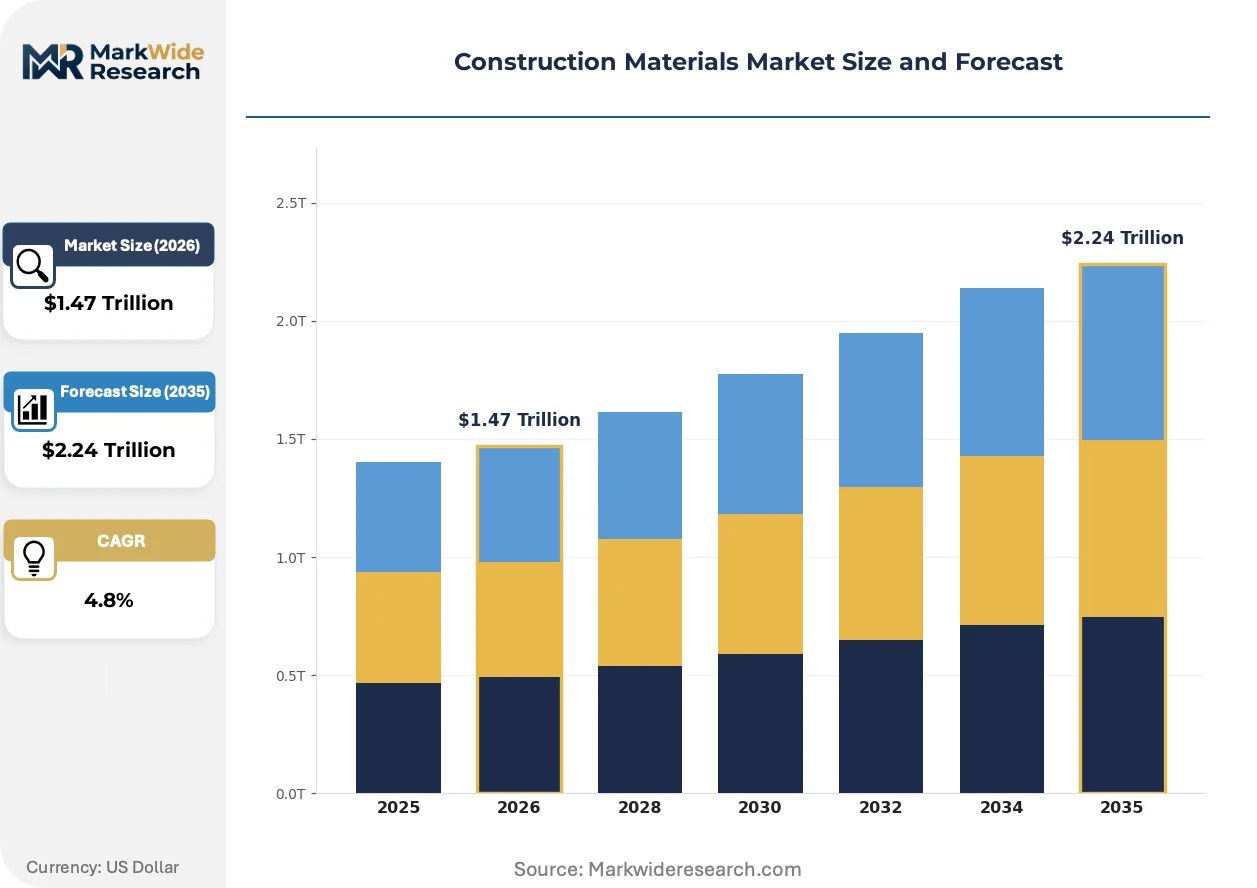
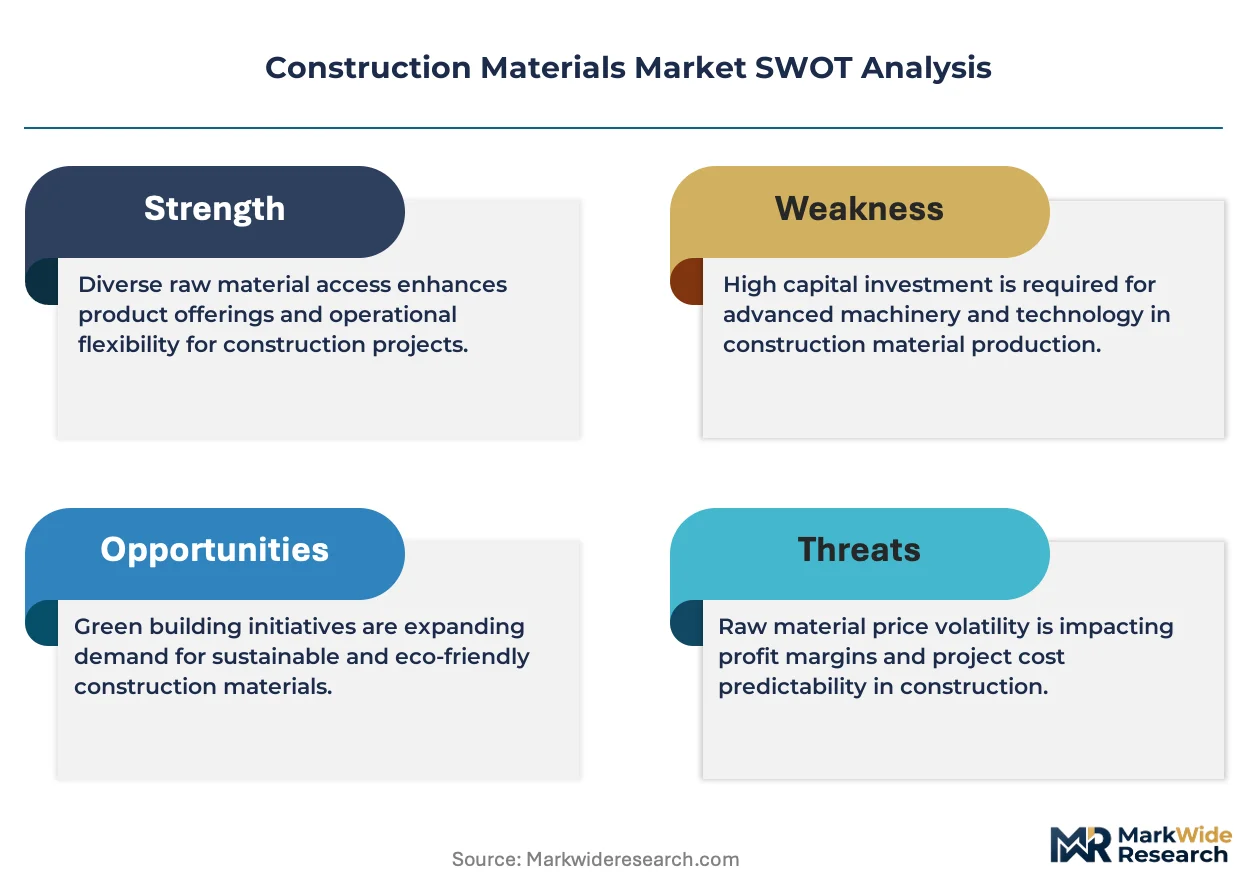
Decarbonization mandates are compressing margins across cement manufacturing while simultaneously creating premium pricing power for low-carbon binders that meet emerging procurement specifications. The structural tension between legacy kiln economics and embodied carbon disclosure requirements now governs capacity investment decisions.
Growth Catalysts
- India's BIS Certification Tightening:Stricter cement quality testing protocols are accelerating consolidation among quality-compliant producers and phasing out substandard regional suppliers across South Asian markets.
- Urban Corridor Density:Vietnam's Ho Chi Minh City to Binh Duong development axis is concentrating precast concrete demand into contiguous logistics zones that reward localized batching plant networks.
- Green Building Certification Mandates:LEED and BREEAM specifications for structural materials are pulling specification share toward Environmental Product Declaration-compliant products in premium commercial segments.
Market Restraints
- Clinker Input Cost Volatility:Energy-intensive calcination processes expose margins to natural gas and petcoke price swings that kiln operators cannot pass through in fixed-price infrastructure contracts.
- Limestone Reserve Concentration:High-purity carbonate deposits cluster in specific geologic formations, forcing long-haul raw material sourcing for coastal grinding facilities lacking captive quarry access.
- Recycled Aggregate Substitution Ceiling:Contamination variability and grading inconsistency limit post-consumer crushed concrete to non-structural fill applications, constraining circular economy penetration.
Strategic Opportunities
- EU Carbon Border Adjustment Mechanism:CBAM phase-in for cement imports creates first-mover advantage for European producers with verified low-clinker formulations and renewable energy sourcing.
- Modular Construction Integration:Offsite manufacturing of volumetric building modules is opening specification channels for factory-cured precast elements with guaranteed dimensional tolerance.
- Digital Twin Specification Tools:Building information modeling platforms are embedding material performance databases that favor suppliers with granular Environmental Product Declaration transparency.
Industry Challenges
- Embodied Carbon Accounting Skill Gap:Shortage of lifecycle assessment practitioners capable of generating ISO-compliant Environmental Product Declarations is bottlenecking supplier certification pipelines.
- Kiln Retrofit Capex Burden:Carbon capture readiness and alternative fuel handling systems require eight-figure capital commitments that strain balance sheets at mid-tier production facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Construction Materials Market |
| Market Size in 2026 | $1.47 Trillion |
| Market Size in 2035 | $2.24 Trillion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cement, Aggregates, Bricks, Concrete Application: Residential Buildings, Commercial Spaces, Infrastructure Projects, Industrial Facilities Material: Steel, Wood, Glass, Plastic Technology: Precast, Modular, 3D Printing, Green Building |
| Companies Covered | Holcim, UltraTech Cement, CRH, Eagle Materials, Owens Corning, Vulcan Materials, CEMEX, James Hardie Industries, Martin Marietta Materials, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Construction Materials Market Evolving Landscape
Material science breakthroughs are converging with digital specification platforms to restructure how structural performance is validated and procured. The traditional hierarchy of cement-based systems is fragmenting as hybrid chemistries and alternative binders claim code-compliant status.
Calcined clay and limestone filler systems are hybridizing Portland cement formulations to reduce clinker factors while maintaining early strength development. Infrastructure contractors in Northern Europe are specifying these blended cements for exposure class XC3 applications where sulfate resistance requirements permit. The technology is hybridizing competitive positioning between pure Portland suppliers and specialty binder producers, compressing the premium historically commanded by low-alkali cements.
REACH registration requirements for construction chemicals are forcing reformulation of admixture portfolios across European supply chains. Superplasticizer manufacturers must submit extended toxicity dossiers for polycarboxylate ether chemistries, extending product development timelines by 18-24 months. Ready-mix concrete producers in Germany and France are responding by qualifying alternative rheology modifiers from suppliers with completed substance registrations.
Specification authority is migrating from general contractors to project owners with net-zero commitments, who now mandate Environmental Product Declarations before contract award. This procurement pattern is displacing traditional lowest-bid awarding in commercial high-rise segments across London, Singapore, and Toronto. Asset managers with Science Based Targets initiative commitments are driving the fastest adoption curves, embedding carbon intensity thresholds directly into tender documents.
Construction Materials Market Segmentation
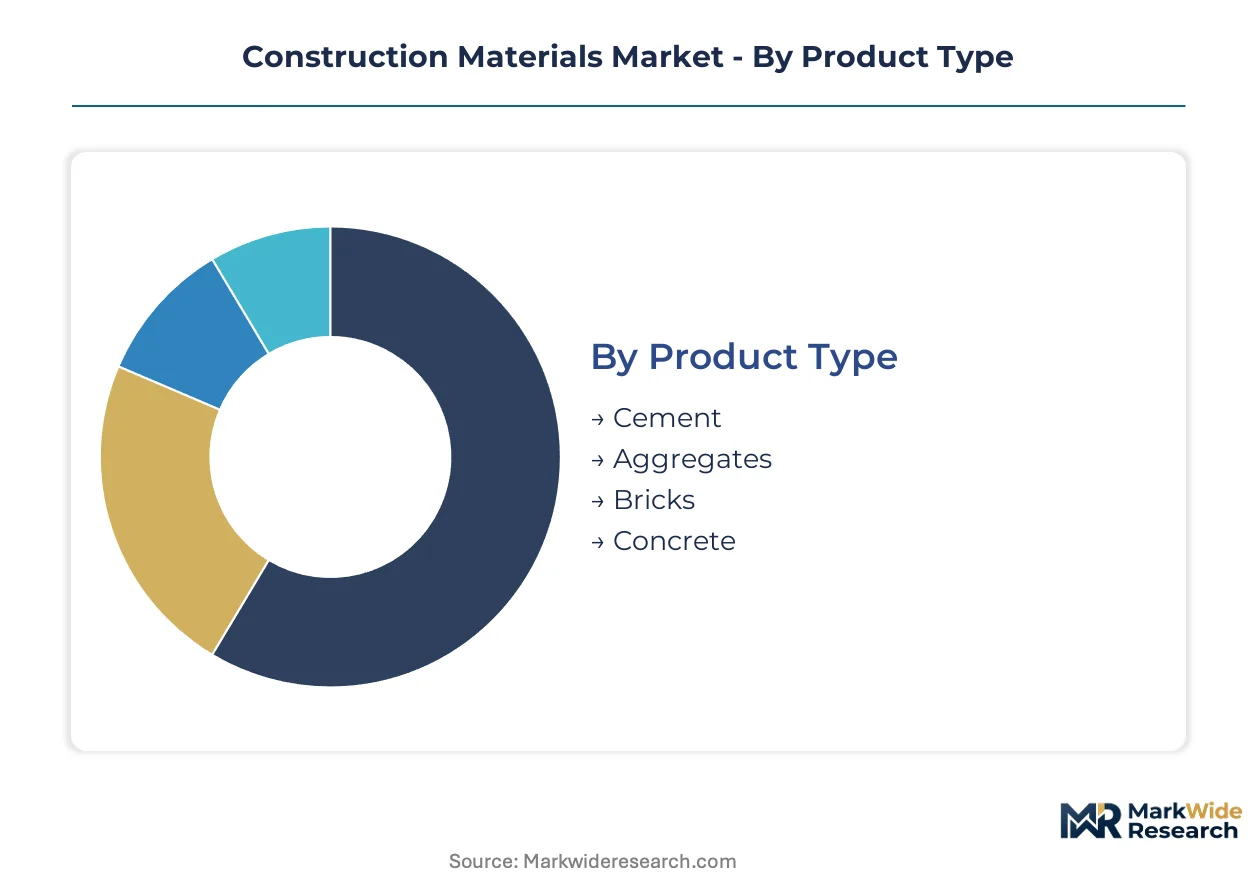
Construction materials procurement operates through distinct technical and commercial lenses. Product chemistry determines structural performance limits while application context dictates logistics economics and specification authority.
Product Type:
Material chemistry spans binding agents through structural elements with sharply divergent production economics and transport constraints.
- Cement:Portland cement clinker containing tricalcium silicate serves as the irreplaceable binder in concrete formulation. Demand concentrates in Vietnam's urban corridor from Ho Chi Minh City to Binh Duong province where precast concrete systems anchor residential high-rise construction. India's BIS tightened quality testing protocols are accelerating consolidation among quality-compliant producers.
- Aggregates:Graded materials per ASTM C33 specification provide compressive strength and dimensional stability in composite systems. Infrastructure projects consume the highest aggregate tonnage among all applications, though limestone reserve concentration forces long-haul sourcing for coastal grinding facilities lacking captive quarry access.
- Bricks:Fired clay masonry units deliver thermal mass and fire resistance in envelope applications. Regional kiln operations in South Asia supply fragmented residential markets with limited standardization.
- Concrete:Composite systems combining cement paste with graded aggregates and admixtures for structural load-bearing. Ready-mix producers in Germany and France are qualifying alternative rheology modifiers as REACH registration requirements extend product development timelines.
Established volume favors cement; emerging adoption favors precast-integrated concrete systems.
Application:
End-use context determines specification stringency, contract structure, and margin realization per unit.
- Residential Buildings:Single-family and multi-family structures generate superior price realization per unit in premium urban markets. Southeast Asian developers are expanding procurement of precast concrete systems as urban corridor density rewards localized batching plant networks.
- Commercial Spaces:Office, retail, and hospitality structures face elevated embodied carbon disclosure requirements. Asset managers with Science Based Targets initiative commitments are embedding carbon intensity thresholds directly into tender documents across London, Singapore, and Toronto.
- Infrastructure Projects:Roads, bridges, and utilities consume the highest aggregate tonnage among applications. Fixed-price contracts expose margins to clinker input cost volatility that kiln operators cannot pass through.
- Industrial Facilities:Manufacturing plants and logistics centers demand specialized flooring and containment systems. Specification authority migrates toward project owners with net-zero procurement mandates.
Residential commands margin premium; infrastructure anchors volume scale.
Material:
Structural and finish substances compete on strength-to-weight, durability, and code compliance dimensions.
- Steel:Reinforcing bars and structural sections deliver tensile capacity in composite systems. India's BIS certification for structural steel elevates compliance costs while accelerating substitution toward lower-carbon binders.
- Wood:Engineered lumber and mass timber products claim carbon sequestration advantages in mid-rise construction. Northern European contractors are specifying hybrid systems where fire codes permit.
- Glass:Glazing systems provide envelope performance with thermal and acoustic control properties. LEED and BREEAM certification mandates pull specification share toward high-performance assemblies.
- Plastic:Polymer-based membranes, insulation, and piping deliver chemical resistance and thermal performance. REACH registration requirements for construction chemicals force reformulation across European supply chains.
Steel dominates structural codes; wood gains share fastest in sustainability-driven segments.
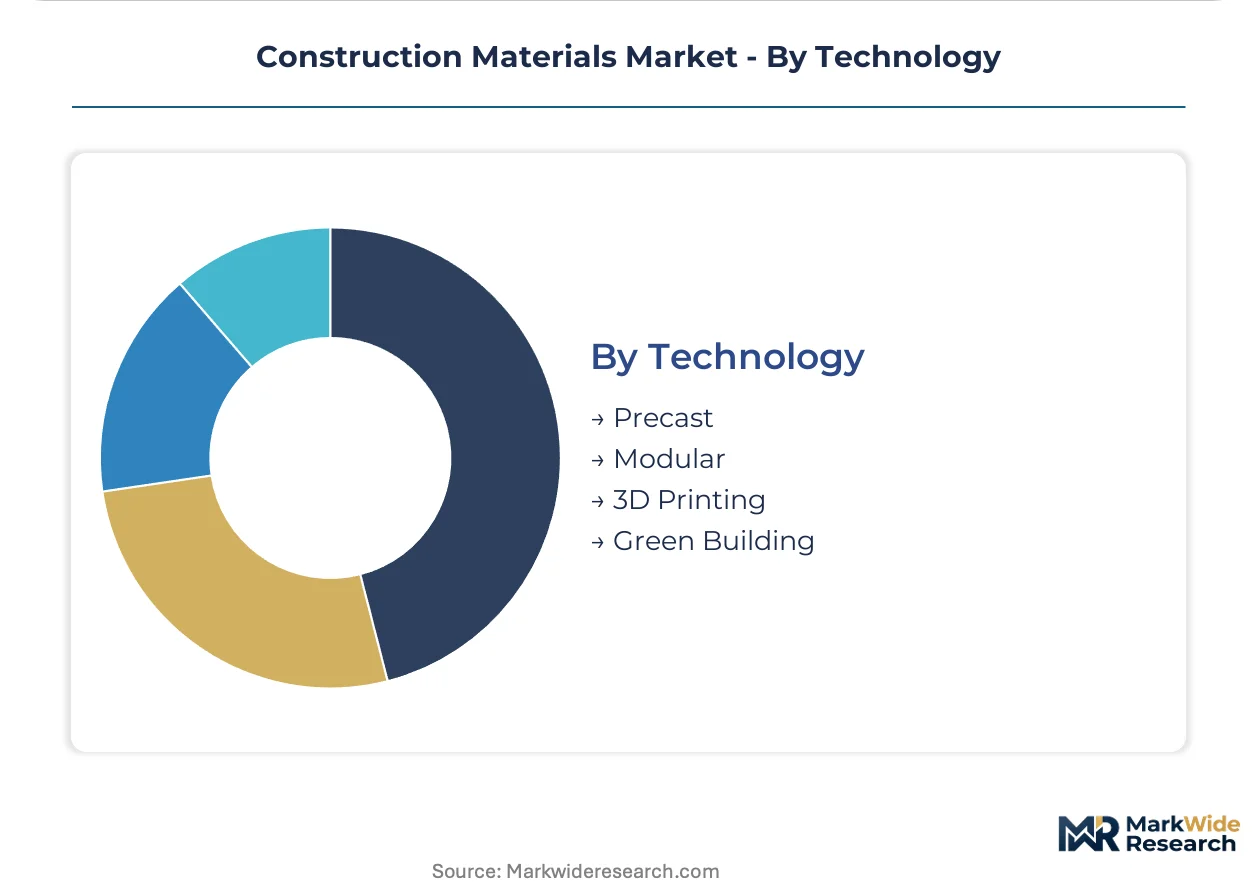
Technology:
Fabrication methods determine dimensional tolerance, curing control, and supply chain configuration.
- Precast:Factory-cured concrete elements manufactured under controlled conditions with guaranteed dimensional tolerance. Vietnam's Ho Chi Minh City to Binh Duong development axis concentrates demand into contiguous logistics zones.
- Modular:Volumetric building modules assembled offsite for rapid installation. Offsite manufacturing opens specification channels for factory-cured elements with embedded quality assurance.
- 3D Printing:Additive manufacturing of cementitious layers for complex geometries and material optimization. Building information modeling platforms embed performance databases that favor suppliers with granular Environmental Product Declaration transparency.
- Green Building:Systems and materials certified for reduced embodied carbon and operational energy. EPA emission standards for Portland cement kilns and EU Carbon Border Adjustment Mechanism phase-in create first-mover advantage for low-clinker formulations.
Precast anchors current capacity investment; green building certification drives specification migration fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity in construction materials procurement varies sharply by geography. Infrastructure buyers in emerging economies exhibit acute sensitivity to cement and aggregate costs, while commercial developers in mature markets absorb premiums for certified low-carbon products.
United States
Infrastructure contractors drive aggregate consumption through federal highway programs. EPA emission standards for Portland cement kilns elevate compliance burdens for domestic producers. Texas and Florida anchor ready-mix concrete demand through metropolitan expansion corridors.
China
Urban renewal and high-speed rail networks sustain massive cement offtake despite property sector headwinds. MIIT dual carbon goals accelerate kiln efficiency retrofits and alternative fuel adoption. The Yangtze River Delta concentrates precast concrete capacity serving Shanghai's commercial high-rise pipeline.
India
Affordable housing initiatives and smart city projects expand cement consumption across tier-2 urban centers. BIS tightened quality testing protocols phase out substandard regional suppliers. The Delhi-Mumbai Industrial Corridor concentrates integrated cement-aggregate operations with captive limestone access.
Germany
Commercial construction specifications prioritize Environmental Product Declaration-compliant materials for LEED and BREEAM certification. REACH registration requirements for construction chemicals extend admixture development timelines. The Rhine-Ruhr region hosts calcined clay blending facilities serving Northern European infrastructure contractors.
Vietnam
Residential high-rise developers expand procurement of precast concrete systems for speed-to-market advantages. Urban planning regulations concentrate construction activity along the Ho Chi Minh City to Binh Duong development axis. This corridor rewards localized batching plant networks with contiguous logistics zones.
Construction Materials Market Competitive Landscape
Capability concentration sits with integrated producers commanding captive raw material reserves; scale advantage sits with diversified building materials conglomerates spanning multiple product categories. The market structure tiers into three archetypes: multinational cement-aggregate integrators, regional specialists with quarry-to-project routing discipline, and building envelope material suppliers with specification-driven pricing power. Dominant competitive moves include backward integration into limestone mining and strategic positioning for EU Carbon Border Adjustment Mechanism compliance.
Among Switzerland-based building materials conglomerates, Holcim exemplifies the integrated multinational archetype with European distribution network control. Irish-domiciled CRH occupies a position representing quarry-to-project routing specialization across North American aggregates. UltraTech Cement anchors the South Asian integrated producer tier through upstream limestone reserve ownership. These three entities collectively illustrate the capability-scale spectrum governing procurement relationships.
| Leading Market Players |
|---|
| Holcim |
| UltraTech Cement |
| CRH |
| Eagle Materials |
| Owens Corning |
| Vulcan Materials |
| CEMEX |
| James Hardie Industries |
| Martin Marietta Materials |
| Others |
Value Network & Pricing Analysis
The Ho Chi Minh City to Binh Duong freight corridor concentrates cement logistics costs into contiguous zones where localized batching plants command pricing power over distant competitors. This corridor economics compresses delivered prices for integrated producers with captive quarry access while forcing coastal grinding facilities to absorb limestone haulage premiums or cede share.
Pricing Analysis
Aftermarket service revenue in cement logistics is narrowing as producers bring fleet management in-house and capture lifetime value through captive distribution. Pricing stratifies across Environmental Product Declaration-certified premium tiers, standard-grade bulk contracts, and economy spot purchases for non-structural fill. Cost compression in standard-grade bulk intensifies because fixed-price infrastructure contracts prevent clinker input cost pass-through. Infrastructure contractors exhibit acute price sensitivity, while commercial developers with Science Based Targets initiative commitments absorb certified-product premiums.
Supply Chain Analysis
Integrated multinational producers hold capacity concentration through captive limestone reserves in Vietnam, India, and Germany. Cement manufacturing draws from high-purity carbonate deposits, alternative fuels including refuse-derived fuel and biomass, and specialized grinding aids subject to REACH registration. Single-source vulnerability concentrates in limestone reserve access for coastal facilities lacking backward integration into mining. Distribution runs through project-direct bulk delivery for infrastructure, ready-mix plant networks for residential, and precast factory integration for modular construction.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market operates as a defensive-moat story anchored in regulatory entrenchment: BIS certification tightening and EPA kiln standards create compliance barriers that quality-compliant incumbents leverage to phase out substandard regional suppliers.
For Market Incumbents: Build captive limestone reserve moats through quarry acquisitions in Vietnam's urban corridor and India's Delhi-Mumbai Industrial Corridor. Accelerate calcined clay blending capacity to defend against low-clinker substitute technologies. Channel control through in-house fleet management protects margin pools from third-party logistics erosion.
For New Entrants and Emerging Players: Establish a beachhead in modular construction precast segments where factory-cured elements bypass established ready-mix distribution. Target green building certification-driven commercial segments in Germany and Singapore where Environmental Product Declaration transparency creates specification entry points. Partner with building information modeling platforms to embed product performance databases directly into digital twin specification tools.
For Investors and Strategic Acquirers: Regional specialists with quarry-to-project routing discipline represent the priority acquisition archetype, particularly in North American aggregates and Southeast Asian precast networks. Monitor EU Carbon Border Adjustment Mechanism implementation timelines as inflection indicators for low-clinker formulation valuations.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Limestone Mining | Captive reserve access in Vietnam and India eliminates raw material cost volatility for coastal grinding facilities. |
| Calcined Clay Blending Capacity Expansion | Rhine-Ruhr facilities serve Northern European infrastructure contractors specifying reduced-clinker exposure class XC3 applications. |
| Environmental Product Declaration Certification Investment | LEED and BREEAM procurement mandates in London, Singapore, and Toronto require ISO-compliant lifecycle assessment documentation. |
| Captive Distribution Network Control | Holcim's European fleet management protects margin pools from aftermarket service revenue erosion. |
| Digital Twin Platform Partnership | Building information modeling databases favor suppliers with granular embodied carbon transparency for specification embedding. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with cement plant managers, ready-mix procurement leads at infrastructure contractors, precast factory operations heads, and building information modeling specification engineers. Secondary validation drew from BIS certification records, EPA emission compliance filings, REACH registration databases, and trade flow customs data. Bottom-up volume modeling across product types and applications triangulated with top-down macro construction spending indicators.
Calibration against historical capacity utilization rates and project pipeline visibility anchored projections across the analysis window. Segmentation dimensions modeled include product chemistry tiers, application context, material substitution patterns, and fabrication technology adoption curves. CAGRs were derived from elasticity-adjusted demand curves incorporating clinker factor reduction trajectories and green building certification penetration rates.
Stress conditions across natural gas and petcoke price bands, limestone reserve depletion timelines, and EU Carbon Border Adjustment Mechanism phase-in schedules were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding infrastructure contract structures and commercial procurement mandate evolution. Quarterly review of kiln retrofit capex commitments and Environmental Product Declaration certification pipeline throughput is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
East Africa White Cement Market
Building Materials
Fiber Reinforced Concrete Market
Building Materials
Light Gauge Steel Framing Market
Building Materials
Asia-Pacific Shotcrete Market
Building Materials
Canada Architectural Coatings Market
Building Materials
India Dry Mix Mortar Market
Building Materials
Europe Acrylic Resin Dispersion Based Primers in Construction Market
Building Materials
Africa Green Cement Market
Building Materials
GRC Cladding Market
Building Materials
Italy Architectural Coatings Market
Building Materials
France Architectural Coatings Market
Building Materials
Global Corrugated Steel Sheets Market
Building Materials
Asia-Pacific Aluminum Door and Window Market
Building Materials
Block Paving Market
Building Materials
Concrete Market
Building Materials
Composite Decking and Railing Market