
 Calcium Aluminate Cement Market | 2026-2036
Calcium Aluminate Cement Market Size, Share, and Industry Trends Forecast 2026-2036
Calcium Aluminate Cement Market Analysis
European specialty cement producers are repositioning capacity toward high-purity alumina streams to serve heat-intensive industries. Kerneos leverages its integrated bauxite-to-cement chain across France and the Netherlands to sustain refractory-grade output. Imerys Aluminates anchors Mediterranean supply through its Greek and Italian operations, while Çimsa competes on scale from its Turkish base.
Calcium aluminate cement is a hydraulic binder produced by fusing or sintering limestone with bauxite, yielding aluminous clinker with Al₂O₃ content typically ranging from 40% to 80%; it develops rapid strength and retains performance at temperatures exceeding 1,400°C, making it essential for refractory linings, industrial flooring, and emergency repair mortars. High alumina formulations command the dominant margin pool due to their irreplaceability in steel ladles and cement kilns, while rapid hardening grades are gaining traction in repair applications where downtime carries steep operational costs. Low cement castables are displacing conventional refractories in petrochemical installations, though standard grades still occupy volume leadership in general construction.
REACH compliance in Europe and EPA emissions guidelines in the United States constrain clinker chemistry and kiln fuel choices, pushing manufacturers toward lower-carbon calcination pathways. The EU Green Deal's carbon border adjustments will reshape import competitiveness for Turkish and Chinese suppliers. Stakeholders must monitor evolving refractory specifications from ASTM and EN standards bodies as decarbonization targets redefine acceptable thermal performance thresholds.
Market Dynamics
EU Green Deal carbon border adjustments are restructuring import competitiveness for Turkish and Chinese suppliers while forcing European producers toward lower-carbon calcination pathways. This regulatory pressure intersects with refractory specification evolution from ASTM and EN standards bodies, creating simultaneous compliance and reformulation demands across the value chain.
Growth Catalysts
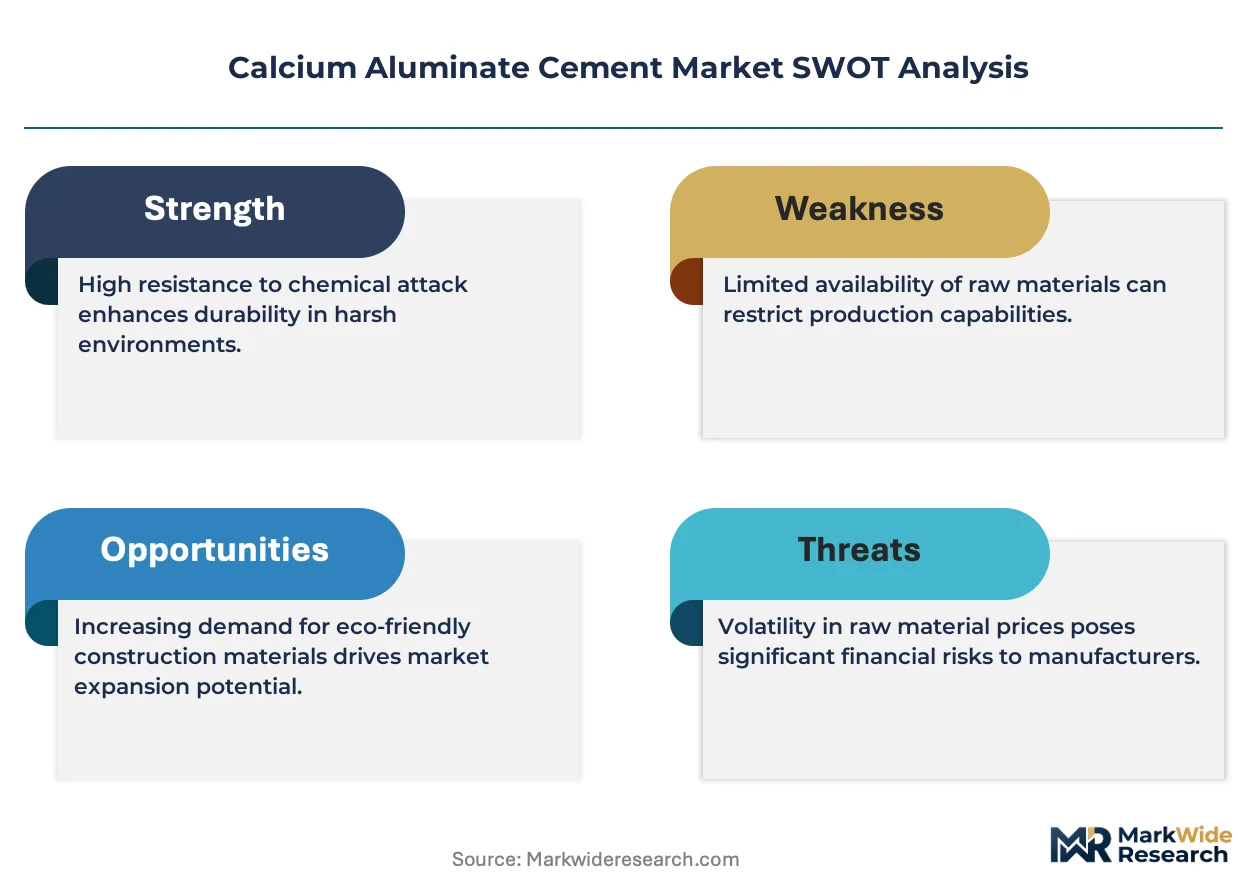
- EU Green Deal carbon border adjustments:These mechanisms penalize high-emission imports, creating protected demand pockets for compliant European producers. German steelmakers are accelerating refractory refresh cycles to lock in domestic supply.
- Steel ladle relining intensity:European steel producers face compressed maintenance windows due to capacity utilization pressures. Rapid-hardening calcium aluminate grades reduce downtime costs in emergency repair scenarios.
- Petrochemical expansion in Poland:New cracker installations and refinery upgrades across Central Europe are driving specification-grade refractory demand. Polish contractors specify low-cement castables for lining integrity.
Market Restraints
- Bauxite supply concentration:High-purity bauxite feedstock concentrates in Guinean and Australian mining jurisdictions. European producers face input cost volatility from freight rate fluctuations and export licensing delays.
- REACH registration burdens:ECHA compliance requirements for novel clinker chemistries extend product development timelines. Smaller formulation houses lack toxicology study budgets to register alternative compositions.
- Sintered alumina substitution:Advanced ceramic monoliths capture select high-temperature applications above 1,600°C. Steelmakers in cost-sensitive segments trial hybrid lining systems to reduce cement dependency.
Strategic Opportunities
- Decarbonized calcination technologies:Hydrogen-fired and electric kiln retrofits align with EU Innovation Fund eligibility. French producers piloting oxy-fuel combustion capture process emissions for CCUS integration.
- Repair mortar specification in German infrastructure:Autobahn tunnel refurbishment and railway platform upgrades create specification-grade demand. Rapid-setting formulations command premium positioning in time-critical civil applications.
- Digital refractory monitoring convergence:IoT sensor integration with predictive maintenance platforms enables performance-based supply contracts. Dutch industrial service providers bundle material supply with thermal lining analytics.
Industry Challenges
- Refractory engineering talent scarcity:Specialized formulators with high-temperature materials expertise are aging out of European workforces. Technical universities in France and Germany report declining enrollment in ceramic engineering tracks.
- EN 14647 certification timelines:New product qualification requires extended furnace testing and third-party validation. Accelerated strength development claims face skeptical scrutiny from notified bodies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Calcium Aluminate Cement Market |
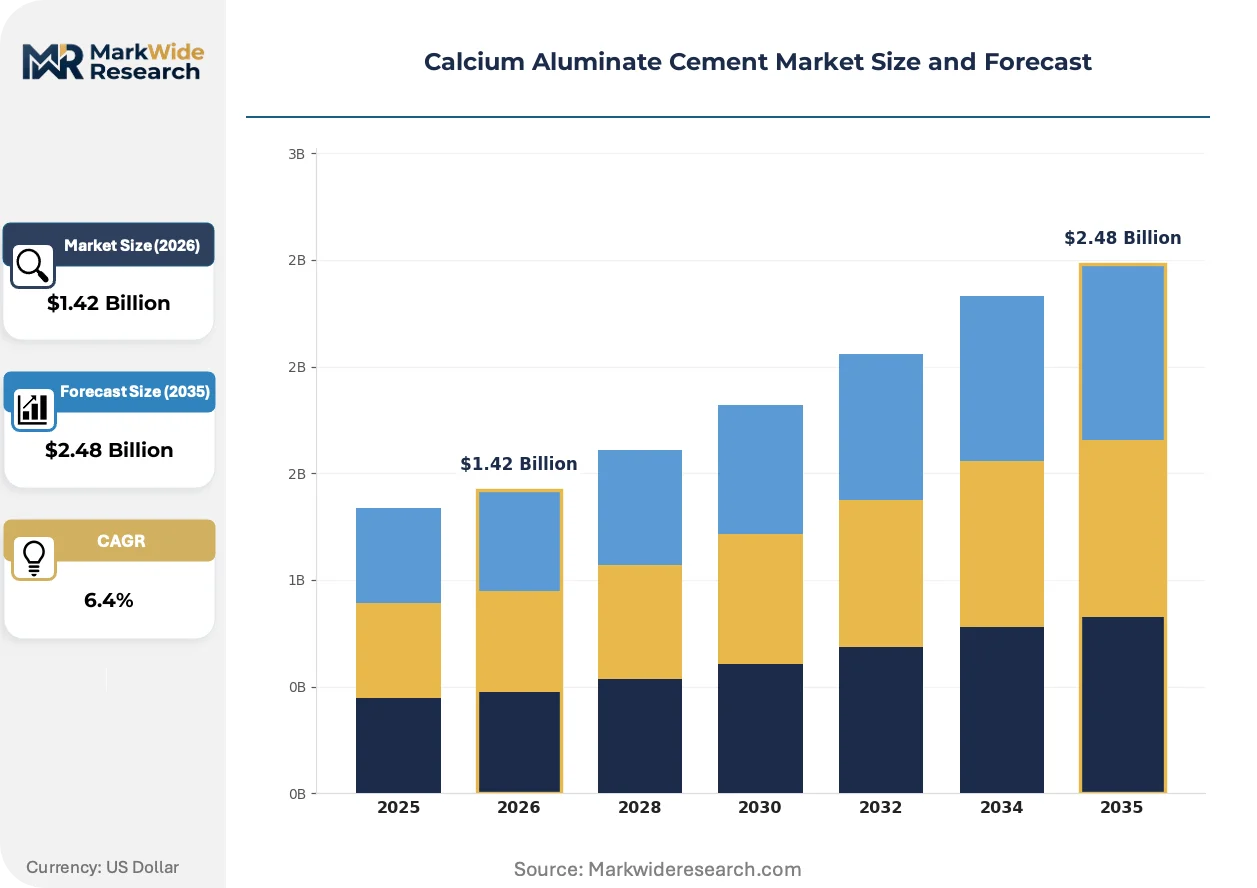
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.48 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Low Cement, High Alumina, Rapid Hardening, Standard Application: Construction, Industrial Flooring, Refractory, Repair End User: Cement Manufacturers, Construction Companies, Retailers, Contractors Packaging Type: Bags, Bulk, Drums, Pallets |
| Companies Covered | Çimsa, Cementos Molins, Imerys Aluminates, Gorka Cement, Denka Company, Almatis, Calucem Group, Caltra Nederland, Kerneos, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Calcium Aluminate Cement Market Emerging Trajectories
Formulation science and process decarbonization are converging to redefine competitive positioning in calcium aluminate cement. Producers are racing to align product portfolios with tightening thermal performance thresholds and emerging procurement specifications.
Low-cement and ultra-low-cement castables are overtaking conventional high-cement refractory concretes in petrochemical and steel applications. These advanced formulations reduce calcium aluminate binder content below 5% while maintaining green strength and fired performance. Shell and BP refineries in Rotterdam and Antwerp specify ultra-low-cement systems for cracking unit linings, compressing traditional castable margins and forcing reformulation investments across European supply bases.
REACH authorization requirements for chromium-bearing raw materials are restricting spinel-forming additives in high-alumina cements. ECHA's sunset date enforcement has triggered substitution programs for magnesia-chrome and alumina-chrome spinets previously standard in steel ladle working linings. German refractory contractors are qualifying magnesium aluminate spinel alternatives, accepting modest thermal shock trade-offs to maintain compliance.
Performance-based procurement is displacing volume-contract purchasing in major European steel and cement kiln operations. ArcelorMittal and Heidelberg Materials now contract for lining life guarantees rather than tonnage deliveries, transferring technical risk to refractory service providers. This model concentrates in German and Benelux industrial clusters where integrated service capabilities justify outcome-based pricing structures.
Calcium Aluminate Cement Market Segmentation
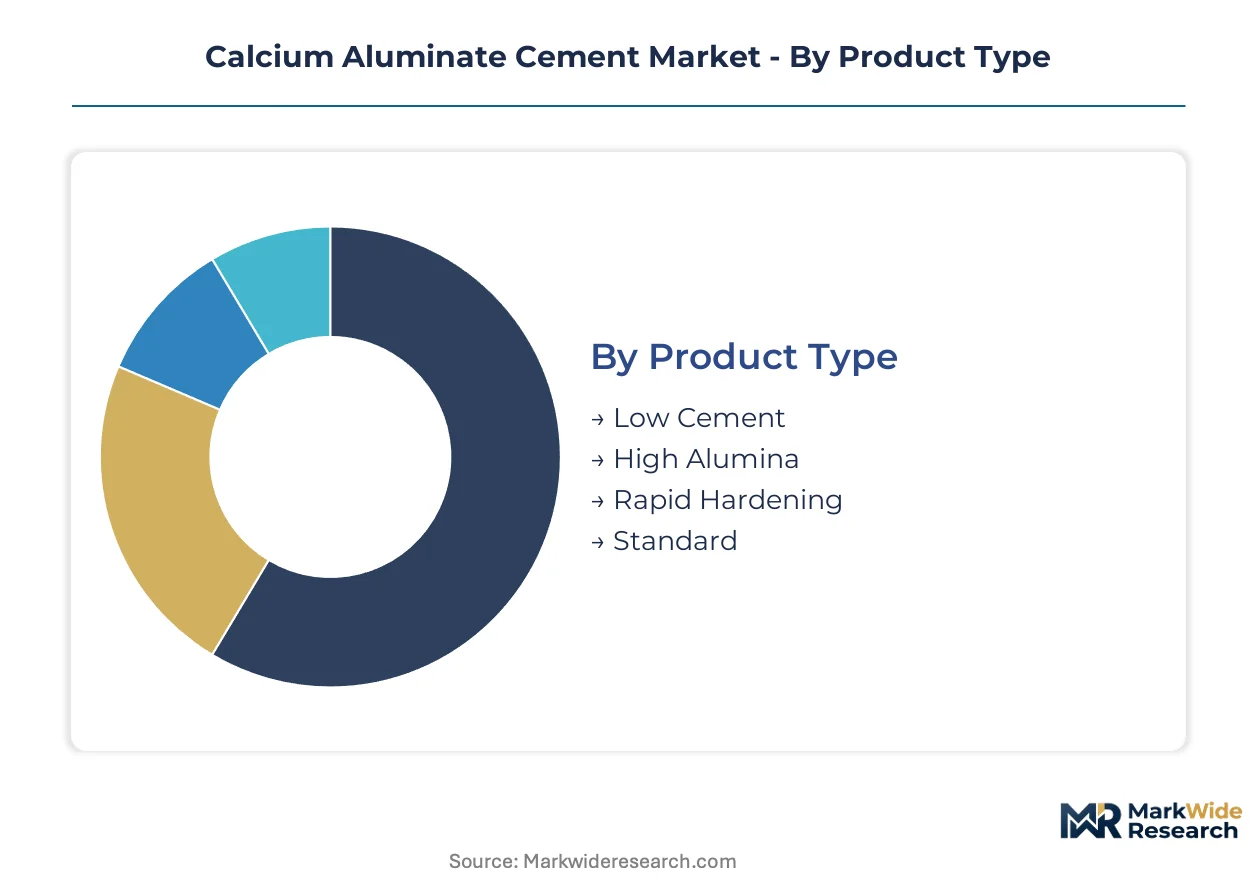
Calcium aluminate cement segments diverge sharply by thermal performance requirements and procurement sophistication. Specification-grade formulations command premium positioning in steel and petrochemical applications, while commodity grades serve volume construction markets.
Product Type:
Customization intensity runs highest in refractory-grade formulations where Al₂O₃ content and mineralogy determine service temperature limits, while standard construction grades compete on availability and logistics reliability.
- High Alumina:Formulations with Al₂O₃ content exceeding 70% deliver irreplaceable performance in steel ladle working linings and cement kiln burning zones. German steelmakers specify these grades for maintenance windows compressed by capacity utilization pressures. Leading the category by volume: Standard. Growing fastest: Low Cement.
- Low Cement:Binder content below 5% enables ultra-low porosity and superior slag resistance in petrochemical cracking units. Rotterdam and Antwerp refineries specify these systems for lining integrity under thermal cycling stress.
- Rapid Hardening:Early strength development within hours suits emergency repair scenarios where operational downtime carries steep costs. Autobahn tunnel contractors in Germany pay premiums for guaranteed return-to-service timelines.
- Standard:General-purpose formulations serve non-critical construction applications with conventional strength and temperature requirements.
Margin concentration follows the alumina gradient, with high-purity grades capturing disproportionate value despite smaller tonnages.
Application:
End-use thermal severity creates distinct specification tiers, from ambient-cure construction mortars to refractory linings exceeding 1,400°C service conditions.
- Refractory:Lining systems for steel ladles, cement kilns, and petrochemical reactors demand precise chemistry control and batch certification. Polish refinery expansions are driving specification-grade procurement for new cracker installations.
- Repair:Emergency mortar applications prioritize rapid strength gain and bond integrity to existing substrates. French railway platform refurbishment contracts specify guaranteed set-time performance.
- Construction:Structural applications leverage calcium aluminate's sulfate resistance and rapid curing for specialized concrete elements.
- Industrial Flooring:Chemical-resistant toppings for process plants exploit the binder's corrosion resistance and abrasion tolerance.
Refractory applications dominate value capture. Repair segments are expanding most quickly as infrastructure age accelerates maintenance intensity.
End User:
Procurement sophistication varies from integrated manufacturers with captive formulation capabilities to fragmented contractor networks bidding on civil projects.
- Cement Manufacturers:Kiln operators source directly for refractory maintenance, often contracting for lining life guarantees rather than tonnage deliveries. Heidelberg Materials exemplifies performance-based procurement consolidation.
- Construction Companies:Large civil contractors specify calcium aluminate for time-critical infrastructure repairs, particularly in German tunnel and railway applications.
- Contractors:Specialized refractory applicators maintain inventory for emergency response, bridging specification complexity and end-user technical requirements.
- Retailers:Distributor channels serve small-scale repair and DIY markets with bagged product formats.
Cement manufacturers concentrate procurement volume. Contractors represent the most fragmented and price-sensitive demand tier.
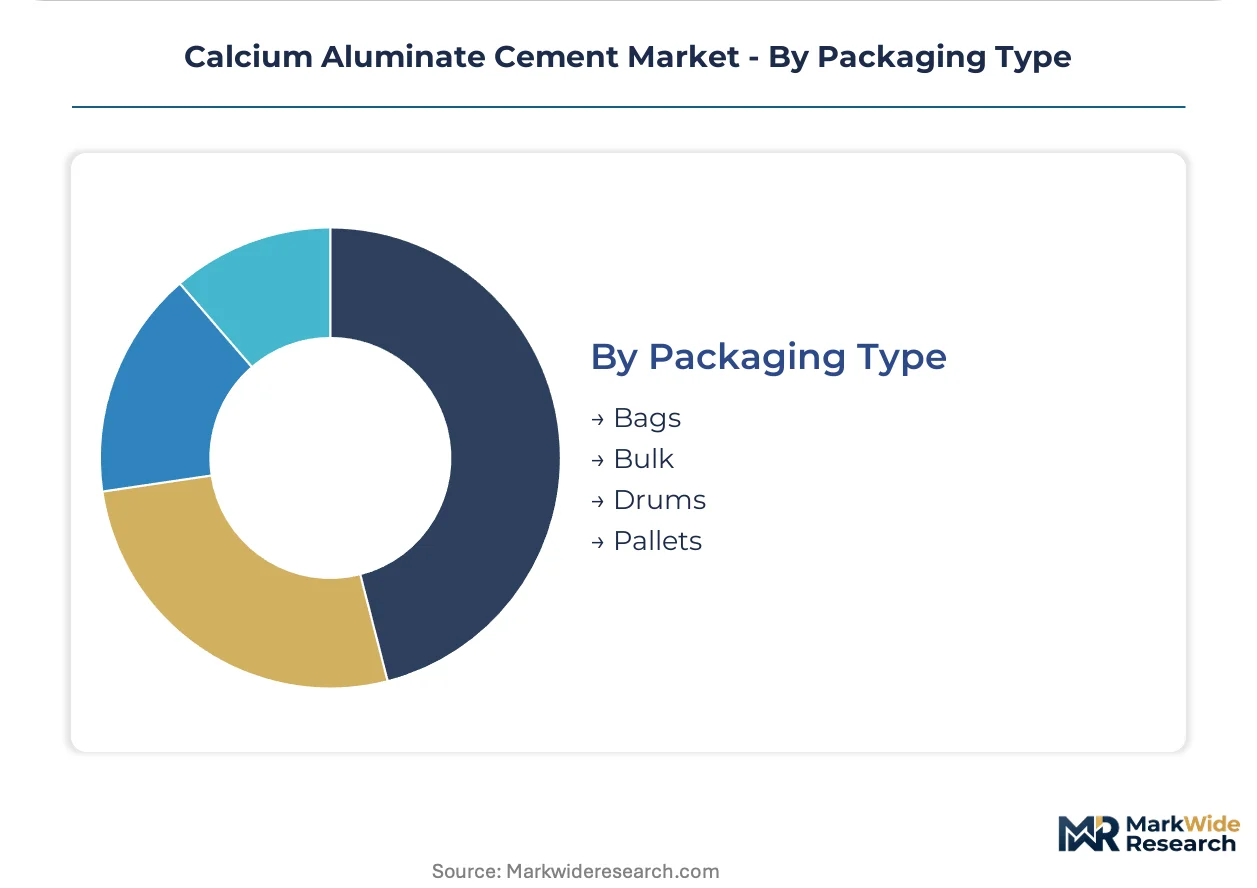
Packaging Type:
Logistics configuration aligns with end-user scale and site constraints, from bulk pneumatic delivery for continuous industrial consumption to palletized bags for intermittent repair work.
- Bulk:Pneumatic tanker delivery serves high-volume refractory plants and continuous kiln operations with dedicated silo infrastructure. ArcelorMittal facilities in Benelux receive bulk shipments for integrated ladle relining services.
- Bags:25-50kg multi-ply sacks dominate contractor and construction site procurement, enabling manual handling and variable batch sizing.
- Pallets:Unitized loads optimize warehouse efficiency for distributor stocking and large project mobilization.
- Drums:Specialty formulations requiring moisture protection or precise additive metering utilize steel or fiber drum containment.
Bulk packaging leads industrial consumption. Bags retain dominance across construction and repair segments where site access limits pneumatic infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Guinean and Australian bauxite deposits anchor feedstock supply for calcium aluminate cement production across major consuming markets. Refractory demand clusters near steel and petrochemical installations in Germany, Poland, France, Turkey, and Japan. Regulatory pressure from EU carbon border adjustments and REACH compliance is reshaping regional competitiveness.
Germany
Steel ladle relining intensity drives specification-grade cement consumption as maintenance windows compress under capacity utilization pressures. EU Green Deal carbon border adjustments protect domestic producers from high-emission Turkish and Chinese imports. The Ruhr industrial cluster hosts integrated refractory service providers bundling material supply with predictive maintenance analytics.
Poland
Petrochemical expansion across Central Europe creates demand for low-cement castables in new cracker installations and refinery upgrades. ECHA compliance requirements extend product development timelines for novel clinker chemistries. Contractors in the Pomeranian refining corridor specify ultra-low-cement systems for lining integrity under thermal cycling stress.
France
Rapid-setting formulations command premium positioning in time-critical civil applications including Autobahn tunnel refurbishment and railway platform upgrades. French producers pilot hydrogen-fired and oxy-fuel combustion kiln retrofits eligible for EU Innovation Fund support. The Lille-Roubaix manufacturing belt concentrates decarbonized calcination technology development.
Turkey
Scale-driven production from integrated bauxite-to-cement operations competes on volume across Mediterranean and Middle Eastern markets. Carbon border adjustment exposure threatens import competitiveness into EU markets. The Izmir industrial zone anchors export-oriented capacity serving refractory markets in North Africa and the Gulf states.
Japan
Advanced ceramic monoliths capture select high-temperature applications above 1,600°C, pressuring cement dependency in cost-sensitive steel segments. METI industrial decarbonization programs incentivize lower-carbon refractory procurement. The Chubu-Nagoya manufacturing corridor concentrates technical ceramics R&D displacing conventional binder systems.
Calcium Aluminate Cement Market Vendor Landscape
Established producers occupy the standard tier; emerging entrants pursue decarbonized calcination technologies and digital refractory monitoring convergence. The vendor base stratifies across integrated bauxite-to-cement operators, specialized formulation houses, and industrial service providers bundling materials with predictive analytics. Three archetypes dominate: scale-driven commodity suppliers, specification-grade purity specialists, and integrated service platforms. Competitive moves concentrate on capacity repositioning toward high-purity alumina streams and strategic partnerships for CCUS integration.
Among European integrated producers, Kerneos and Imerys Aluminates exemplify the specification-grade tier, anchoring refractory-grade output across French, Dutch, Greek, and Italian operations. Çimsa represents the scale-driven archetype, competing on volume from its Turkish production base. These three companies illustrate the geographic and strategic segmentation defining competitive positioning: EU-based purity specialists shielded by carbon border adjustments versus scale-oriented exporters exposed to compliance-driven market access constraints.
| Leading Market Players |
|---|
| Çimsa |
| Cementos Molins |
| Imerys Aluminates |
| Gorka Cement |
| Denka Company |
| Almatis |
| Calucem Group |
| Caltra Nederland |
| Kerneos |
| Others |
Supply Flow & Price Mechanics
Specialized refractory formulators in the Ruhr industrial cluster command wage premiums that compress margins for specification-grade production while widening spreads between premium high-alumina formulations and commodity rapid-hardening grades. Labor-cost differentials between German technical centers and Turkish scale operations translate directly into pricing-tier stratification across European procurement channels.
Pricing Analysis
Warranty-bundled supply contracts incorporating lining-life guarantees separate premium refractory service providers from unbundled material-only transactions. Pricing stratifies across premium, standard, and economy tiers based on Al₂O₃ purity certification and after-sales technical support intensity. Cost compression in standard construction grades intensifies as Turkish exporters absorb carbon border adjustment exposure to maintain EU market access. Cement manufacturers with performance-based procurement contracts exhibit lowest price sensitivity; fragmented civil contractors bidding on repair projects demonstrate highest elasticity.
Supply Chain Analysis
Direct-to-refractory-plant channels handle high-volume continuous consumption from integrated steel and cement kiln operators, while distributor networks serve intermittent repair contractors. Bauxite feedstock concentrates in Guinean and Australian mining jurisdictions, with European calcination capacity clustering in France, Germany, and Turkey. Supply chain risk centers on single-source vulnerability for high-purity bauxite grades subject to export licensing delays. Distribution runs through bulk pneumatic delivery for industrial consumers and palletized bag formats for construction site mobilization.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
High-purity alumina calcination capacity constraints in Europe prop pricing power for compliant domestic producers. Bauxite supply concentration and REACH registration barriers limit rapid capacity expansion, sustaining margin premiums for specification-grade output.
For Market Incumbents: Lock in captive bauxite supply through long-term offtake agreements with Guinean and Australian miners to defend against input cost volatility. Accelerate hydrogen-fired kiln retrofits eligible for EU Innovation Fund support, creating compliance moats against Turkish scale competitors exposed to carbon border adjustments. Deepen backward integration into bauxite beneficiation to secure spinel-grade feedstock for chromium-free formulations. For New Entrants and Emerging Players: EU Green Deal carbon border adjustments in Europe open a window for decarbonized calcination specialists to capture protected demand from German steelmakers accelerating refractory refresh cycles. Target repair mortar specification in German infrastructure refurbishment, where rapid-setting formulations command premium positioning and incumbent capacity is constrained. Pursue digital refractory monitoring convergence as a bundled service differentiator, integrating IoT sensor platforms with material supply contracts. For Investors and Strategic Acquirers: Re-rating potential sits with integrated bauxite-to-cement operators possessing EU-based high-purity capacity given carbon border adjustment protection and specification-grade margin expansion. Long-term viability favors producers with demonstrated CCUS integration pathways and hydrogen combustion pilots. Monitor ECHA authorization timelines for novel clinker chemistries as an inflection indicator for competitive repositioning opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Bauxite Supply | Secures high-purity feedstock from Guinean and Australian jurisdictions against export licensing volatility. |
| Hydrogen-Fired Kiln Retrofit | Aligns French and German production with EU Innovation Fund eligibility and carbon border compliance. |
| Long-Term Supply Agreement | Binds ArcelorMittal and Heidelberg Materials through performance-based lining-life guarantee contracts. |
| Digital Refractory Monitoring Platform | Enables Dutch industrial service providers to bundle predictive analytics with material tonnage deliveries. |
| Joint Venture for CCUS Integration | Captures process emissions from oxy-fuel combustion for carbon utilization in adjacent chemical production. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs for this calcium aluminate cement analysis. Primary interviews with refractory plant managers, procurement leads at German steelmakers, technical R&D directors at specialty cement producers, and distribution channel partners in Benelux markets combined with bottom-up and top-down triangulation. Secondary validation drew from ECHA REACH registration databases, EU emissions trading scheme disclosures, SEC filings from listed building materials groups, and Cefic sector reports.
Granularity-level modeling addressed product type, application severity, end-user procurement sophistication, and regional production hub economics across the analysis window. CAGRs were derived from segment-level volume trajectories and value-per-ton dynamics, with refractory-grade purity premiums and carbon border adjustment pass-through assumptions explicitly incorporated. Forecast inputs included steel ladle relining cycle compression rates, petrochemical cracker installation pipelines in Poland, and infrastructure refurbishment intensity across German civil engineering markets.
The model assumes a particular technology adoption path for hydrogen-fired and electric calcination; alternative pathways for oxy-fuel combustion with CCUS integration would alter the outlook for decarbonized production economics. Forecasts reflect assumptions regarding REACH authorization timelines, bauxite export licensing stability, and EU carbon border adjustment enforcement stringency. Periodic stress-testing of base assumptions is recommended given regulatory evolution and feedstock supply concentration risks.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Building Materials
Bolt (Fastener) Market
Building Materials
Poland Architectural Coatings Market
Building Materials
China Aluminum Door and Window Market
Building Materials
Mexico Architectural Coatings Market
Building Materials
GRC Cladding Market
Building Materials
Europe Cement Market
Building Materials
Block Paving Market
Building Materials
Middle-East and Africa Buildings and Construction Sheets Market
Building Materials
Global Glass Fiber Reinforced Concrete Market
Building Materials
Cement Market
Building Materials
United States Architectural Coatings Market
Building Materials
Asia-Pacific White Cement Market
Building Materials
Global White Cement Market
Building Materials
Concrete Market
Building Materials
Asia-Pacific Dry-Mix Mortar Market
Building Materials
Global Fiber Cement Siding Market