
 Three Way Ball Valve Market | 2026-2036
Three Way Ball Valve Market Size, Share, and Industry Trends Forecast 2026-2036
Three Way Ball Valve Market Insights
Preventive maintenance contracts and software-enabled diagnostics are repositioning how valve vendors capture lifetime value from industrial buyers. Emerson Electric Co. leverages its digital valve portfolio to embed predictive analytics into service agreements. Flowserve Corporation sustains aftermarket revenue through dedicated repair centers in high-density petrochemical zones. Swagelok Company anchors its position with specialized fabrication services for custom three-way configurations.
A three-way ball valve employs a bored spherical closure element rotated through 90 degrees to divert, mix, or shut off flow among three ports, typically manufactured with PTFE or metal-seated designs rated for pressures exceeding 1,000 psi in process-critical duties. Stainless steel constructions dominate chemical processing and oil and gas applications where corrosion resistance determines replacement cycles, while electric actuation segments are gaining fastest in water management utilities pursuing remote monitoring integration. Flanged connection types occupy the mature installed base in North American refineries, though threaded variants command premium positioning in pharmaceutical skids and laboratory distribution systems.
EPA emissions enforcement under the Clean Air Act shapes material specifications and fugitive emission testing protocols for valve procurement in US petrochemical facilities, while EU REACH compliance restricts certain coating chemistries used in cast body production. ASTM International and API 6D certification requirements govern product acceptance in upstream oil and gas applications, creating qualification barriers for unproven suppliers. Stakeholders must weigh the capital cost of smart actuator integration against the operational savings from reduced unplanned shutdowns as process industries tighten reliability targets.
Market Dynamics
Preventive maintenance contracts and software-enabled diagnostics are repositioning how valve vendors capture lifetime value from industrial buyers, compressing replacement cycles and embedding suppliers deeper into plant operations.
Growth Catalysts
- EU F-Gas Regulation:Chemical processing plants in Germany are expanding valve replacement schedules to comply with stringent fluorinated gas emission controls, accelerating demand for low-leakage sealing technologies.
- Electric actuation:Water management utilities are integrating remote monitoring capabilities, driving fastest adoption of smart actuator configurations in municipal distribution networks.
- Texas Gulf Coast petrochemical corridor:Concentrated capacity expansions in ethylene and derivative production are creating sustained procurement volume for process-critical valve assemblies.
Market Restraints
- Stainless steel price volatility:Nickel and chromium input cost swings compress margin predictability for corrosion-resistant construction grades essential to chemical processing.
- API 6D certification barriers:Upstream oil and gas qualification requirements create structural exclusion for unproven suppliers attempting market entry.
- Metal-seated cost premium:High-pressure PTFE alternatives dominate budget-constrained applications, limiting metal-seated penetration despite superior cycle life.
Strategic Opportunities
- Pharmaceutical skids:Threaded three-way configurations command premium positioning in laboratory distribution systems where cleanability and compact footprint outweigh flanged alternatives.
- EPA Clean Air Act enforcement:Fugitive emission testing protocols are reshaping material specifications, creating specification windows for low-emission packing designs in US petrochemical facilities.
- Predictive analytics convergence:Integration of valve diagnostics with distributed control systems enables outcome-based service contracts that extend vendor relationships beyond hardware supply.
Industry Challenges
- Smart actuator integration complexity:Retrofitting legacy process trains with digital positioners requires specialized commissioning expertise scarce in maintenance departments.
- REACH compliance timeline:EU restrictions on coating chemistries used in cast body production force reformulation investments with uncertain qualification schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Three Way Ball Valve Market |
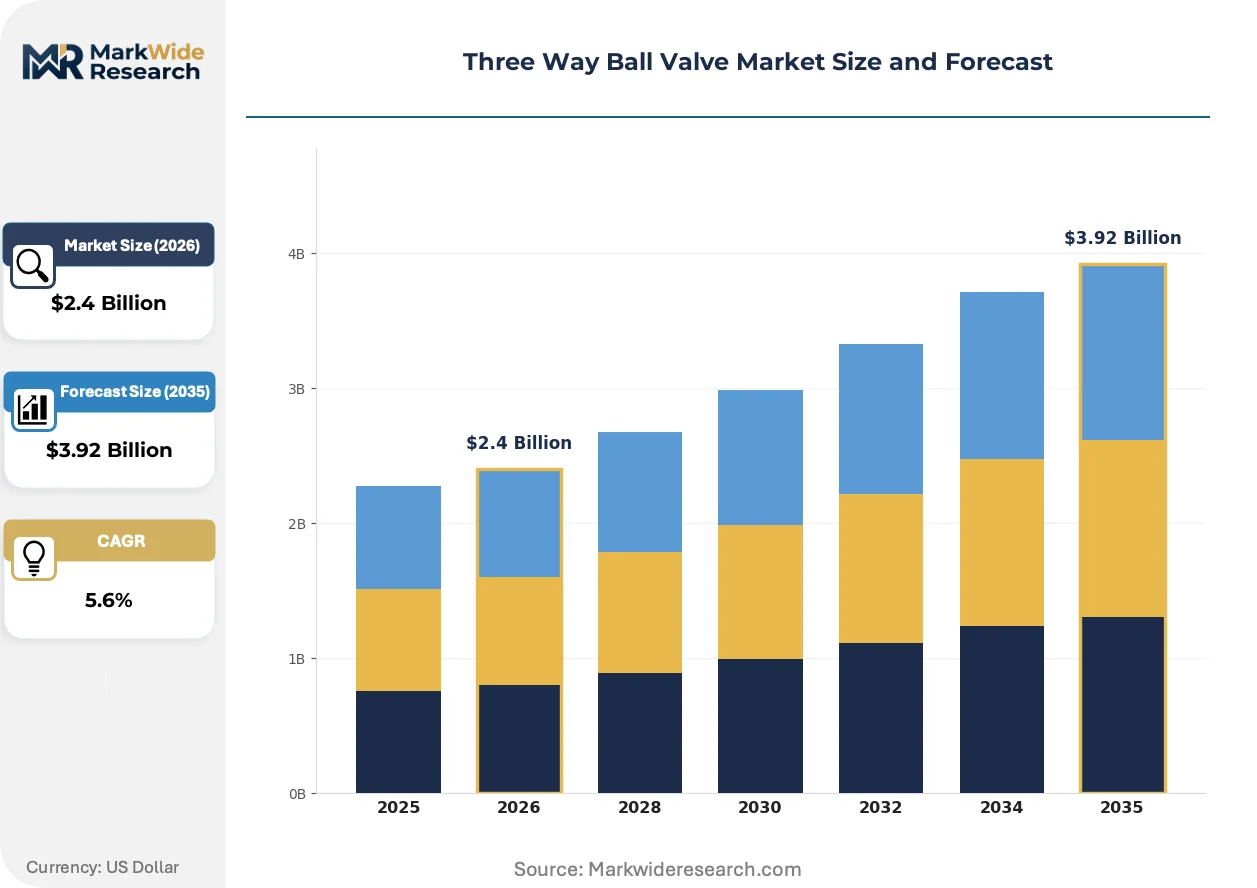
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $3.92 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Manual, Electric, Pneumatic, Solenoid End User: Oil & Gas, Water Management, HVAC, Chemical Processing Material: Stainless Steel, Brass, PVC, Carbon Steel Connection Type: Flanged, Threaded, Welded, Socket Weld |
| Companies Covered | Emerson Electric Co., Flowserve Corporation, Swagelok Company, OMAL, PetrolValves, Walworth, Pentair Valves and Controls, JC Valves, Zellinger, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Three Way Ball Valve Market Trends and Innovations
Digital valve architectures are embedding predictive capabilities directly into process infrastructure, shifting competitive advantage from manufacturing scale to software-enabled service continuity.
Wireless valve monitoring is decentralizing maintenance decision-making across distributed chemical facilities. Plant operators in the Texas Gulf Coast corridor are deploying battery-powered position transmitters to eliminate signal wiring costs in retrofit applications. This topology is decentralizing the traditional centralized maintenance dispatch model, enabling localized response teams to preempt failures before control room alerts trigger.
EPA emissions enforcement under the Clean Air Act is tightening fugitive emission testing protocols for valve procurement in US petrochemical facilities. Material specifications now mandate low-leakage packing designs certified to Method 21 screening thresholds. Stainless steel constructions with live-loaded stem seals are gaining preference in Texas and Louisiana refineries responding to inspection frequency increases.
Aftermarket service unbundling is fragmenting traditional vendor-customer relationships in North American process industries. End-users are separating repair center contracts from original equipment supply, selecting third-party specialists for turnaround maintenance. This pattern concentrates in high-density petrochemical zones where dedicated valve service infrastructure supports competitive bidding for maintenance scopes.
Three Way Ball Valve Market Segmentation
Three-way ball valve procurement decisions split sharply between installed base replacement and new specification. Material selection and actuation type determine lifecycle cost calculations that dominate capital project approvals.
Product Type:
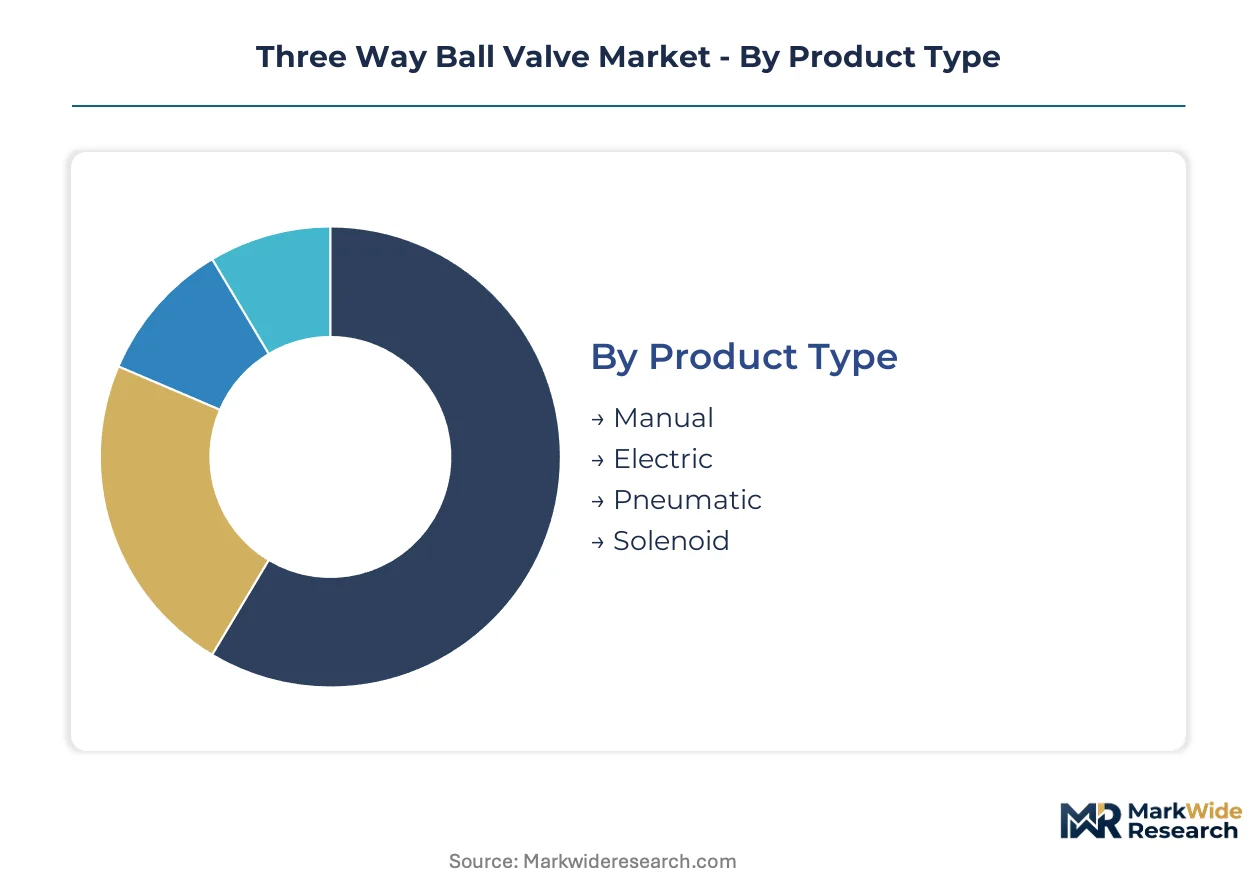
Volume concentration favors legacy manual configurations, while premium capture shifts toward integrated smart actuation systems.
- Manual:Hand-wheel or lever-operated designs dominate existing petrochemical infrastructure where simple diversion functions suffice. Demand concentrates in Texas Gulf Coast turnaround cycles as operators prioritize capital preservation over automation upgrades.
- Electric:Motor-driven actuators with 4-20mA position feedback enable remote monitoring integration demanded by water management utilities. Municipal distribution networks in Germany are specifying these for pressure zone isolation under EU F-Gas compliance timelines.
- Pneumatic:Air-powered actuation serves explosion-risk environments in oil and gas processing where electrical classification limits motor deployment.
- Solenoid:Direct-acting electromagnetic operators fit compact pharmaceutical skids requiring rapid cycling and precise positioning.
Mature deployment sits with Manual. Newer deployment is concentrated in Electric.
End User:
Application requirements range from fugitive emission containment to potable water purity, reshaping specification priorities across verticals.
- Oil & Gas:Upstream gathering systems and downstream refining impose API 6D certification and high-pressure ratings. Louisiana and Texas facilities are replacing legacy valves under intensified EPA Clean Air Act inspection protocols.
- Water Management:Municipal treatment and distribution networks prioritize electric actuation for SCADA integration. German utilities are accelerating procurement to meet EU F-Gas Regulation phase-down schedules for fluorinated gases.
- HVAC:Commercial building systems specify lower-pressure brass or bronze constructions for chilled water and heating loops.
- Chemical Processing:Aggressive media handling demands corrosion-resistant materials with live-loaded stem seals. REACH compliance is forcing coating reformulations for cast body production in European plants.
Replacement intensity clusters in Oil & Gas. Specification innovation is advancing fastest in Chemical Processing.
Material:
Cost tiers separate commodity installations from process-critical duties where failure consequences justify metallurgical premiums.
- Stainless Steel:Austenitic and duplex grades deliver corrosion resistance in acid service and chloride environments. German chemical plants are expanding replacement schedules as EU F-Gas Regulation tightens leakage tolerance.
- Brass:Copper-zinc alloys serve low-pressure HVAC and plumbing applications where dezincification resistance determines alloy selection.
- PVC:Thermoplastic constructions handle corrosive fluids in water treatment and semiconductor chemical delivery systems.
- Carbon Steel:Standard grades with protective coatings occupy budget-constrained oil and gas gathering lines where internal corrosion is manageable.
Standard-grade volume concentrates in Carbon Steel. Premium specification is climbing fastest in Stainless Steel.
Connection Type:
Installation topology and maintenance accessibility dictate joint geometry selection across new build and retrofit contexts.
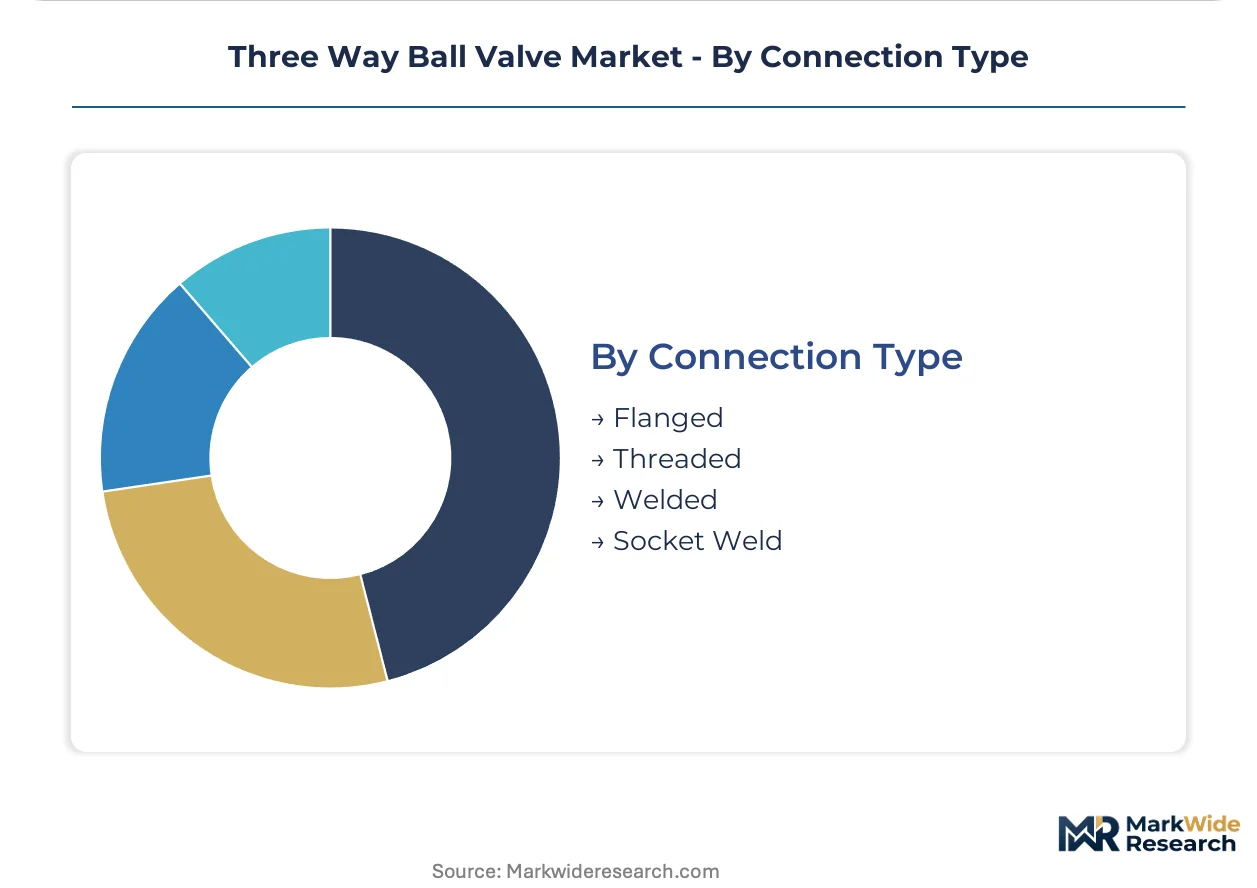
- Flanged:ASME B16.5 standardized face-to-face dimensions enable rapid replacement in North American refinery piping. Texas Gulf Coast ethylene expansions are sustaining procurement volume for raised-face and ring-type joint configurations.
- Threaded:NPT and BSP tapered connections serve compact pharmaceutical skids and laboratory distribution where cleanability and space constraints outweigh flanged alternatives.
- Welded:Butt-weld end preparations eliminate leak paths in high-integrity hydrogen and cryogenic service.
- Socket Weld:Fillet-welded joints fit smaller bore piping in chemical plants where vibration resistance matters.
Installed base dominance rests with Flanged. Growth momentum is strongest in Threaded.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing capacity concentrates in Germany and the United States while consumption spreads across chemical processing clusters and municipal water networks. Production sites in Baden-Württemberg and Texas serve export demand, yet local procurement dominates in maintenance-intensive petrochemical corridors.
United States
EPA Clean Air Act enforcement is accelerating valve replacement cycles in Gulf Coast refineries. The Texas ethylene corridor sustains concentrated demand for flanged stainless steel configurations in process-critical duties. Louisiana facilities are upgrading live-loaded stem seals under intensified fugitive emission inspection protocols.
Germany
EU F-Gas Regulation phase-down schedules are expanding replacement programs at BASF and Bayer sites in Ludwigshafen and Leverkusen. ECHA REACH compliance is forcing coating reformulations for cast body production. Bavarian chemical parks are specifying electric actuation for SCADA-integrated pressure zone isolation.
China
MIIT industrial upgrading guidelines are driving smart actuator adoption in Yangtze River Delta chemical zones. NMPA-equivalent process safety standards are tightening sealing specifications for pharmaceutical manufacturing. Shandong petrochemical complexes are importing European valve diagnostics for predictive maintenance integration.
India
BIS certification requirements for pressure equipment are creating qualification barriers for unproven suppliers entering Mumbai-Pune chemical clusters. PLI scheme incentives for specialty chemicals are expanding process plant construction in Gujarat. Reliance Industries' Jamnagar complex sustains premium procurement for high-cycle metal-seated designs.
Saudi Arabia
SABIC expansion projects in Jubail Industrial City are sustaining demand for API 6D-certified valve assemblies in high-pressure hydrocarbon service. The country's national standards body is aligning with ASTM International test protocols for fugitive emissions. NEOM development corridors are specifying electric actuation for water management infrastructure.
Three Way Ball Valve Market Competitive Landscape
Capital-heavy foundry operators compete with asset-light design houses across the three-way ball valve supply base. The market structure fragments into three tiers: integrated multinational valve divisions, regional fabrication specialists, and component-focused niche suppliers. Strategic archetypes include predictive analytics integrators, aftermarket service unbundlers, and custom configuration fabricators. Dominant competitive moves encompass M&A for digital capability acquisition and geographic expansion into high-density petrochemical zones.
Within the integrated multinational tier, Emerson Electric Co. and Flowserve Corporation exemplify predictive analytics convergence through digital valve portfolios and dedicated repair center networks. Swagelok Company anchors the specialized fabrication archetype with custom three-way configuration capabilities. These three entities represent contrasting pathways for embedding lifetime value capture into industrial buyer relationships.
| Leading Market Players |
|---|
| Emerson Electric Co. |
| Flowserve Corporation |
| Swagelok Company |
| OMAL |
| PetrolValves |
| Walworth |
| Pentair Valves and Controls |
| JC Valves |
| Zellinger |
| Others |
Pricing and Supply Chain Analysis
Private-equity-rolled-up valve specialists in Germany and the United States are consolidating foundry capacity and tightening pricing discipline through centralized procurement of nickel and chromium feedstock, while family-owned mid-caps in Italy defend margin position via captive forging operations and long-term service contracts with BASF and Bayer sites.
Pricing Analysis
Margin tightening in standard carbon steel configurations reflects nickel price volatility and compressed tender competition from Chinese exporters. Three-tier pricing structure across API 6D-certified premium, ASTM-standard mid-grade, and uncertified economy levels separates replacement cycles in Texas refineries from budget-constrained gathering lines. Cost-down pressure on electric actuation packages accelerates as water utilities consolidate procurement through municipal purchasing cooperatives. Chemical processing buyers exhibit lowest price sensitivity due to fugitive emission compliance penalties, while HVAC contractors drive hardest bargaining on brass commodity valves.
Supply Chain Analysis
Freight cost differentials between Baden-Württemberg precision foundries and Texas Gulf Coast distribution hubs are reshaping sourcing patterns for European valve OEMs serving Louisiana petrochemical expansions. Manufacturing gravity centers on Germany, the United States, and China, with Shandong casting operations feeding mid-grade carbon steel demand across Asia-Pacific project markets. Raw material supply draws from Indonesian nickel laterite, South African chromium, and domestic stainless scrap recovery networks. Single-source vulnerability concentrates in PTFE seal supply from specialized fluoropolymer compounders. Distribution runs through authorized distributor networks stocking ASME B16.5 flanged configurations for turnaround maintenance in high-density petrochemical corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Three-way ball valve manufacturing is consolidating around predictive analytics capability and API 6D certification assets, with REACH compliance timelines and smart actuator integration complexity forcing sub-scale fabricators toward exit or acquisition.
For Market Incumbents: Acquire digital valve diagnostics platforms and wireless position transmitter technology to embed outcome-based service contracts. Expand dedicated repair center footprint in Texas and Louisiana to capture aftermarket unbundling trends. Defend against specialized fabrication entrants by locking BASF and SABIC into multi-year preventive maintenance agreements with guaranteed uptime clauses. For New Entrants and Emerging Players: Enter via pharmaceutical skid fabricators in Bavaria and North Carolina seeking threaded three-way configurations with rapid-cycle solenoid actuation. Target municipal water utilities in Germany accelerating electric actuation procurement under EU F-Gas phase-down schedules. Pursue white-label supply agreements with established distributors lacking custom fabrication capability. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-cap specialists with captive stainless steel forging capacity and live-loaded stem seal IP in the US Midwest and German Ruhr region. Long-term viability hinges on software-enabled service revenue exceeding hardware margins. Watch for inflection when EPA inspection frequency increases trigger replacement wave timing in Gulf Coast refineries.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nickel Alloy Forging | Captive supply of duplex stainless grades insulates margin from LME volatility in chemical processing contracts. |
| Predictive Maintenance Platform Launch | Emerson-style digital valve portfolios capture lifetime value through SCADA-integrated diagnostics in water utilities. |
| API 6D Certification Investment | Qualification barrier creates structural exclusion protecting incumbents in SABIC and Aramco upstream procurement. |
| Pharmaceutical Skid Partnership | Threaded custom configurations command premium positioning in Roche and Novartis laboratory distribution systems. |
| EU REACH Compliance Reformulation | Coating chemistry pivot preserves access to BASF and Bayer replacement schedules under tightened emission protocols. |
Research Methodology
Multi-period observation of valve replacement cycles, nickel price volatility, and regulatory enforcement intensity anchored the trend analysis, supplemented by interviews with maintenance directors at Texas Gulf Coast refineries, procurement leads at German chemical parks, aftermarket service heads at distributor networks, and plant engineers at water management utilities. Secondary validation drew from EPA enforcement databases, ECHA REACH substance restrictions, API certification registries, and customs trade flows for stainless steel valve classifications. Bottom-up segmentation modeling triangulated against top-down petrochemical capacity expansion tracking.
Input-output matrices mapped actuation type, material grade, connection geometry, and end-use vertical against regional regulatory clusters to generate volume and value projections across the analysis window. CAGRs derived from fitted growth curves applied to replacement cycle acceleration under EU F-Gas and EPA Clean Air Act compliance timelines. Industry-specific forecast inputs incorporated MIIT smart manufacturing guidelines for Chinese chemical zones and PLI scheme incentives for Indian specialty chemical construction.
Forecast precision tightens around the base case; tail outcomes carry wider variance under nickel supply disruption scenarios or abrupt REACH coating ban enforcement. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Battery Pack Cooling Valve Actuator Systems Market
Valves
Valve Remote Control System Market
Valves
Subsea Control System Market
Valves
Choke Valves Market
Valves
Global Valves in Chemical Market
Valves
Global Solenoid Valves Market
Valves
Mobile Hydraulic Valves Market
Valves
Emergency Venting System Market
Valves
Pneumatic Slide Gates Market
Valves
Pigging Valves Market
Valves
Global Pipeline Safety Market
Valves
Top Drive Systems Market
Valves
Air Heated Vaporizer Market
Valves
Vaneometer Market
Valves
Europe Valves Market
Valves
Flow Computer Market