
 Naval Actuators and Valves Market | 2026-2036
Naval Actuators and Valves Market Size, Share, and Industry Trends Forecast 2026-2036
Naval Actuators and Valves Market Foresight
Consolidation among Western naval procurement agencies is recalibrating supplier relationships across the maritime defense supply base. MOOG Inc. leverages its precision motion control heritage to anchor long-term actuator contracts with submarine programs. Honeywell International Inc. sustains competitive positioning through integrated valve and sensor architectures that reduce platform weight. Curtiss-Wright Corporation dominates the nuclear-grade valve segment with manufacturing scale that meets stringent military specifications.
Naval actuators and valves encompass electromechanical and fluid-power devices engineered to modulate flow, pressure, and mechanical positioning within marine propulsion, ballast, and weapons systems, typically operating at pressure ratings exceeding 10,000 psi in submerged environments. Electric actuation technology is displacing legacy hydraulic systems across new-build frigates and destroyers, driven by reduced maintenance intervals and improved shock resistance. The propulsion systems application captures the largest share of valve demand due to the complexity of main engine cooling and fuel injection circuits. Control systems integration represents the fastest-expanding segment as shipbuilders demand unified digital architectures linking sensors, actuators, and bridge command networks.
The U.S. Navy's Naval Sea Systems Command enforces MIL-STD-167 and MIL-S-901 shock standards that dictate actuator housing metallurgy and valve seal materials for combatant vessels. The EU's F-Gas Regulation and REACH framework restrict certain hydraulic fluid chemistries, pushing European shipyards toward pneumatic and electric alternatives. Stakeholders must monitor evolving cybersecurity mandates for shipboard control systems, as naval forces increasingly classify valve and actuator networks as critical digital infrastructure requiring hardened communication protocols.
Market Dynamics
Electric actuation architectures are compressing maintenance cycles and reshaping supplier qualifications across NATO submarine and surface combatant programs. The shift from hydraulic to electromechanical systems concentrates procurement authority around integrated platform primes capable of certifying unified control networks.
Growth Catalysts
- IMO emissions mandates:Tighter sulfur and carbon intensity standards for marine propulsion systems accelerate electric actuator deployment in European and North American naval shipyards.
- Fleet modernization cycles:Aging Cold War-era submarines and destroyers in the United States, United Kingdom, and France drive replacement demand for high-pressure valve assemblies.
- Integrated digital architectures:Shipbuilders specify unified sensor-actuator-command networks that reduce cabling weight and improve shock resilience in combatant vessels.
Market Restraints
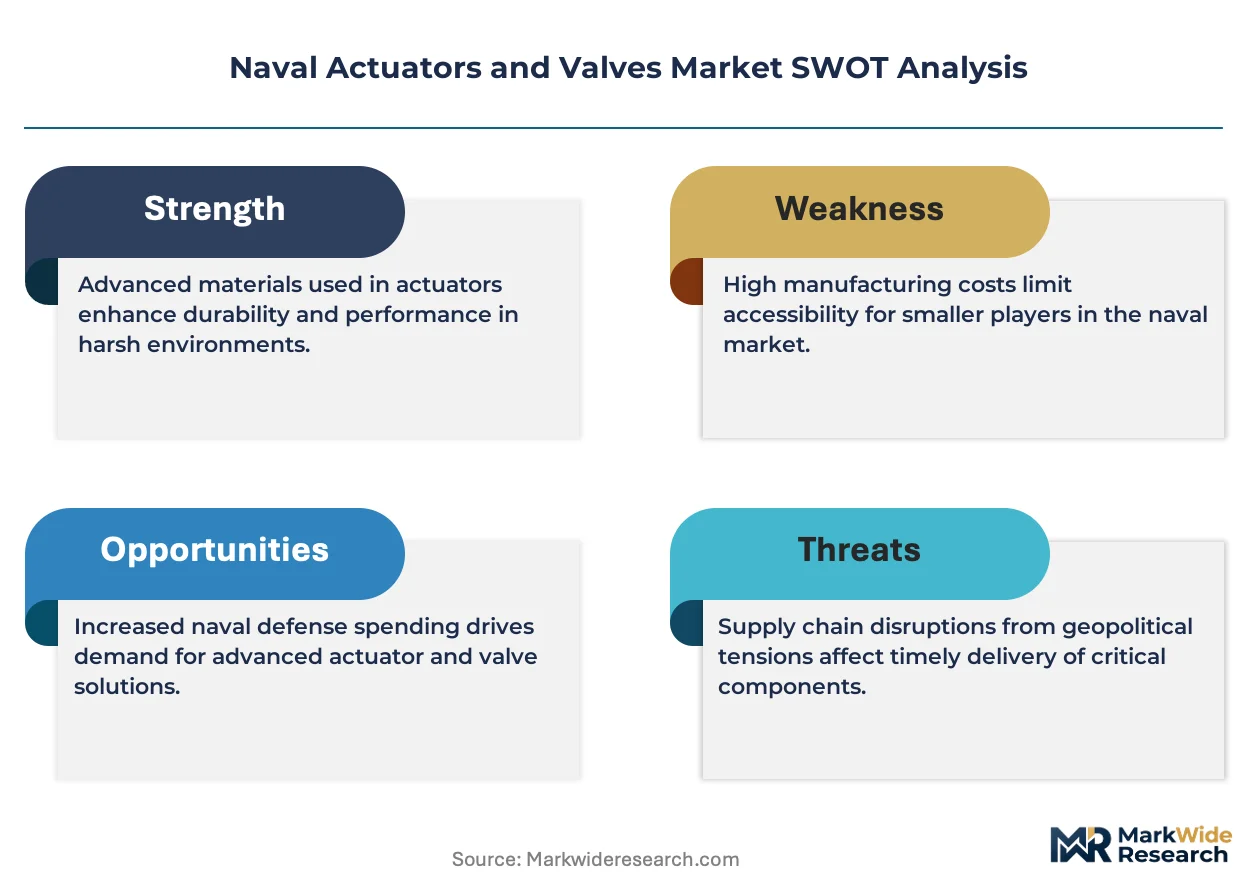
- Specialized alloy supply concentration:Nickel-based superalloys for valve housings and actuator casings face sourcing constraints from limited qualified foundries in Germany and Japan.
- REACH chemical restrictions:The EU's framework on hydraulic fluid formulations forces shipyards to abandon proven synthetic chemistries before electric alternatives achieve full qualification.
- Electromechanical torque limitations:High-thrust submarine ballast system applications remain beyond the capacity of fielded electric actuators, preserving hydraulic lock-in for critical functions.
Strategic Opportunities
- Australian nuclear submarine program:The AUKUS security pact generates long-term demand for nuclear-grade valves and precision actuators with US-UK qualification heritage.
- Digital twin integration:Convergence of physics-based modeling and real-time sensor telemetry enables predictive maintenance contracts that capture aftermarket value from platform operators.
- Polish naval expansion:Warsaw's accelerated frigate and submarine procurement creates entry points for suppliers with NATO interoperability certification.
Industry Challenges
- Cybersecurity hardening requirements:Naval Sea Systems Command and equivalent NATO authorities now classify valve and actuator networks as critical digital infrastructure, mandating encrypted communication protocols that extend development timelines.
- Multi-decade platform support obligations:Suppliers must maintain technical documentation and spare production capacity for thirty-year service lives, compressing margin structures on initial contracts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Naval Actuators and Valves Market |
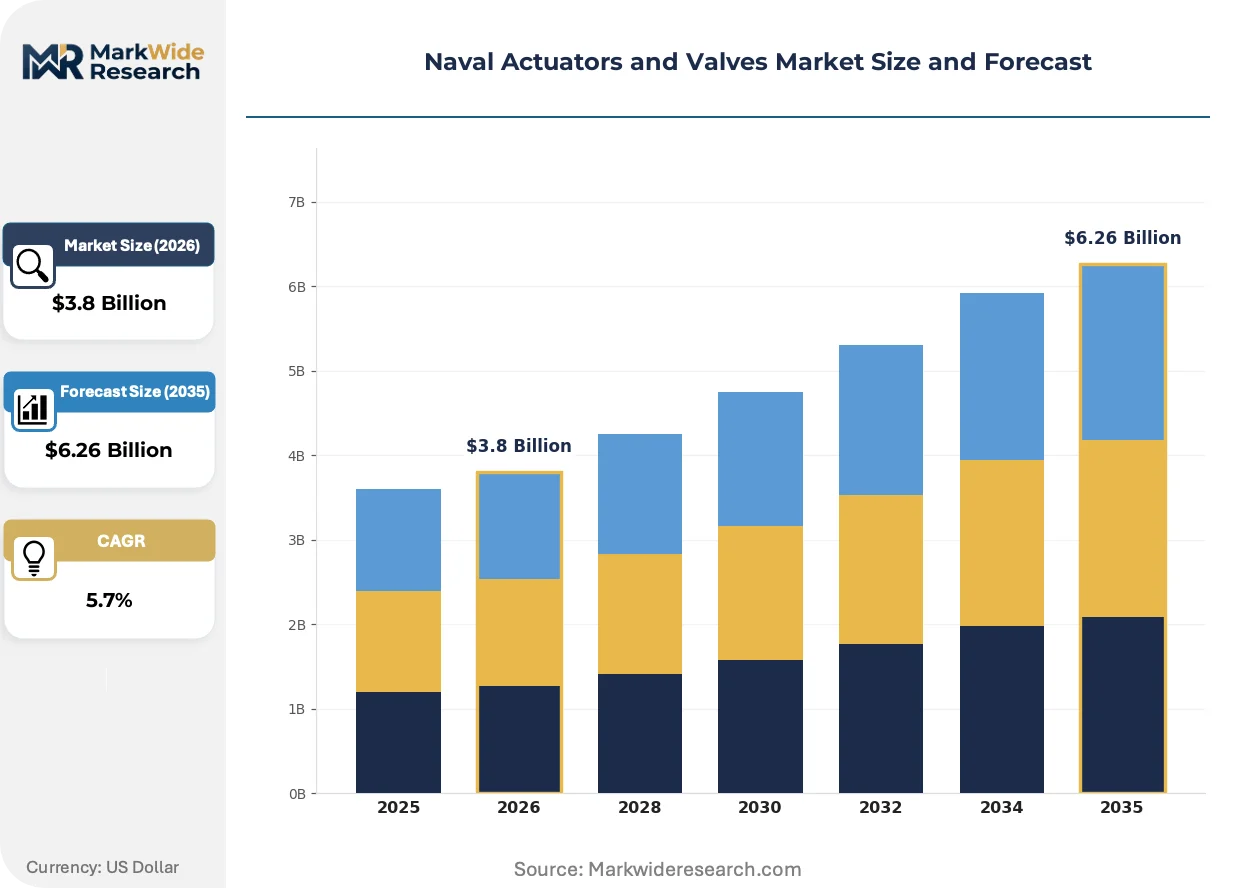
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.26 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Actuators, Valves, Sensors, Control Systems Application: Propulsion Systems, Steering Mechanisms, Ballast Systems, Cargo Handling Technology: Pneumatic, Hydraulic, Electric, Mechanical End User: Shipbuilders, Naval Forces, Offshore Operators, Marine Contractors |
| Companies Covered | MOOG Inc., Honeywell International Inc., Rotork plc, Emerson Electric Co., Curtiss-Wright Corporation, Parker Hannifin Corporation, Rolls-Royce Holdings plc, Thales Group, Flowserve Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Naval Actuators and Valves Market Shifts & Advancements
Platform digitization is collapsing the traditional separation between mechanical actuation and electronic control, forcing valve suppliers to develop embedded computing competencies. This convergence redefines competitive boundaries across the maritime defense supply base.
Modular electric actuator designs with standardized mechanical interfaces and field-replaceable electronics are modularizing procurement patterns for surface combatant programs. French and Italian shipyards specify these configurations for Horizon-class frigate derivatives. The approach compresses spare parts logistics and enables platform upgrades without hull penetration, reducing lifecycle ownership costs.
The EU F-Gas Regulation and REACH framework restrictions on perfluorinated hydraulic fluids are compelling European naval architects to eliminate traditional power transmission chemistries. German and Spanish shipyards now mandate electric or pneumatic alternatives in new-build specifications. This regulatory pressure accelerates supplier investment in high-torque electromechanical architectures previously considered immature for marine applications.
Life-cycle availability contracting is displacing transactional component procurement in major NATO shipbuilding programs. Platform primes in the United Kingdom and Netherlands now specify guaranteed operational readiness metrics rather than unit pricing for valve and actuator systems. This shift transfers technical risk to suppliers while capturing long-term service revenue for integrated solution providers.
Naval Actuators and Valves Market Segmentation
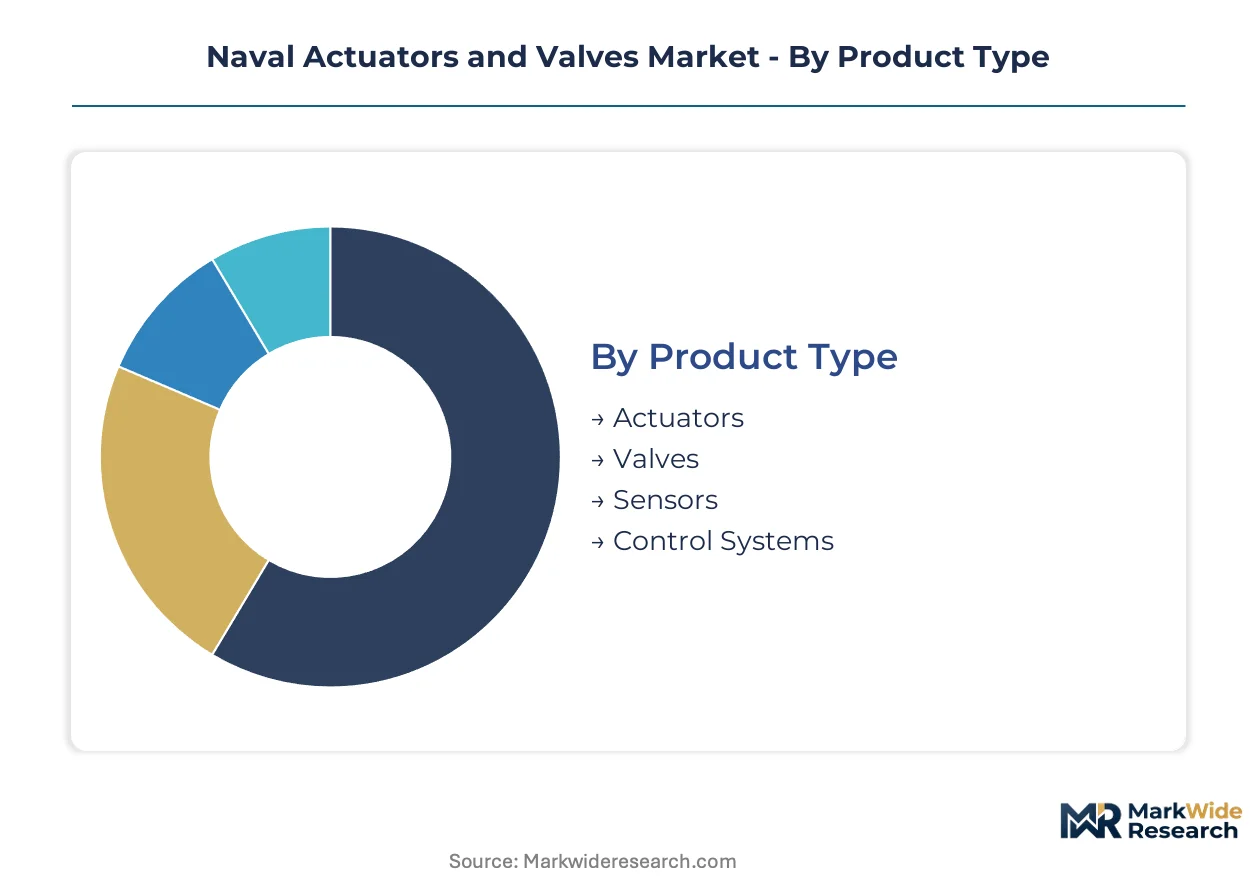
Segmentation of the naval actuators and valves market reveals how procurement patterns diverge across platform types and operational requirements. Shipbuilders prioritize integrated electromechanical architectures that reduce through-life maintenance burdens. Defense procurement agencies segment suppliers by shock certification heritage and nuclear-grade manufacturing credentials.
Product Type:
Replacement cycles for Cold War-era platforms are driving differentiated demand across component categories, with modernization budgets favoring integrated subsystems over discrete part procurement.
- Actuators:Electromechanical and electrohydraulic devices convert electrical signals into mechanical force for valve positioning, rudder control, and weapons platform alignment. United States submarine programs concentrate demand around precision motion control units certified to MIL-S-901 shock standards, with electric architectures displacing legacy hydraulic systems in surface combatant new-builds.
- Valves:High-pressure flow control devices regulate propulsion, ballast, and fire suppression circuits, typically constructed from nickel-based superalloys for corrosion resistance in submerged environments. United Kingdom and French naval shipyards prioritize nuclear-grade gate and globe valve assemblies for ballistic missile submarine replacement programs.
- Sensors:Pressure, temperature, and position transducers provide feedback loops for closed-loop control architectures.
- Control Systems:Distributed electronic modules coordinate actuator and valve networks through unified digital buses.
Valves sit at the top of the volume ranking, with control systems climbing the fastest.
Application:
Cost tier differentiation separates mission-critical propulsion applications from auxiliary systems, with nuclear submarine programs commanding premium pricing for certified components.
- Propulsion Systems:Main engine cooling, fuel injection, and exhaust management circuits demand the highest pressure ratings and material specifications. United States and United Kingdom submarine programs drive concentrated procurement of valves rated beyond 10,000 psi, with integrated sensor-actuator packages replacing legacy distributed architectures.
- Ballast Systems:High-thrust actuators control seawater intake and discharge for submarine depth management and surface vessel stability. Hydraulic systems retain dominance in submarine applications where electric torque limitations persist, though pneumatic alternatives are gaining traction in European surface combatant specifications.
- Steering Mechanisms:Rudder and fin stabilization actuators require precise positional accuracy under variable load conditions.
- Cargo Handling:Winch and crane actuators support replenishment and logistics operations with lower shock certification requirements.
Propulsion systems command the highest unit values, while ballast systems exhibit the steepest technology transition trajectory.
Technology:
Application maturity determines technology selection, with established hydraulic architectures defending position in high-thrust submarine functions while electric systems capture surface combatant new-builds.
- Electric:Brushless DC and servo motor architectures eliminate hydraulic fluid maintenance and improve shock resilience through solid-state construction. German and Spanish shipyards mandate electric actuation for Horizon-class frigate derivatives under EU F-Gas Regulation compliance timelines.
- Hydraulic:Fluid-power systems deliver unmatched force density for submarine ballast and weapons elevator applications. REACH chemical restrictions on synthetic hydraulic fluids are compressing qualified supplier lists in European procurement.
- Pneumatic:Compressed air systems serve low-torque auxiliary functions with reduced environmental compliance burden.
- Mechanical:Direct-linkage actuation persists in backup and emergency systems requiring fail-safe operation independent of shipboard power.
Electric technology is gaining share fastest in surface combatant programs, with hydraulic retention strongest in submarine applications.
End User:
Customer type shapes procurement authority concentration, with integrated platform primes consolidating component specification power away from discrete subsystem vendors.
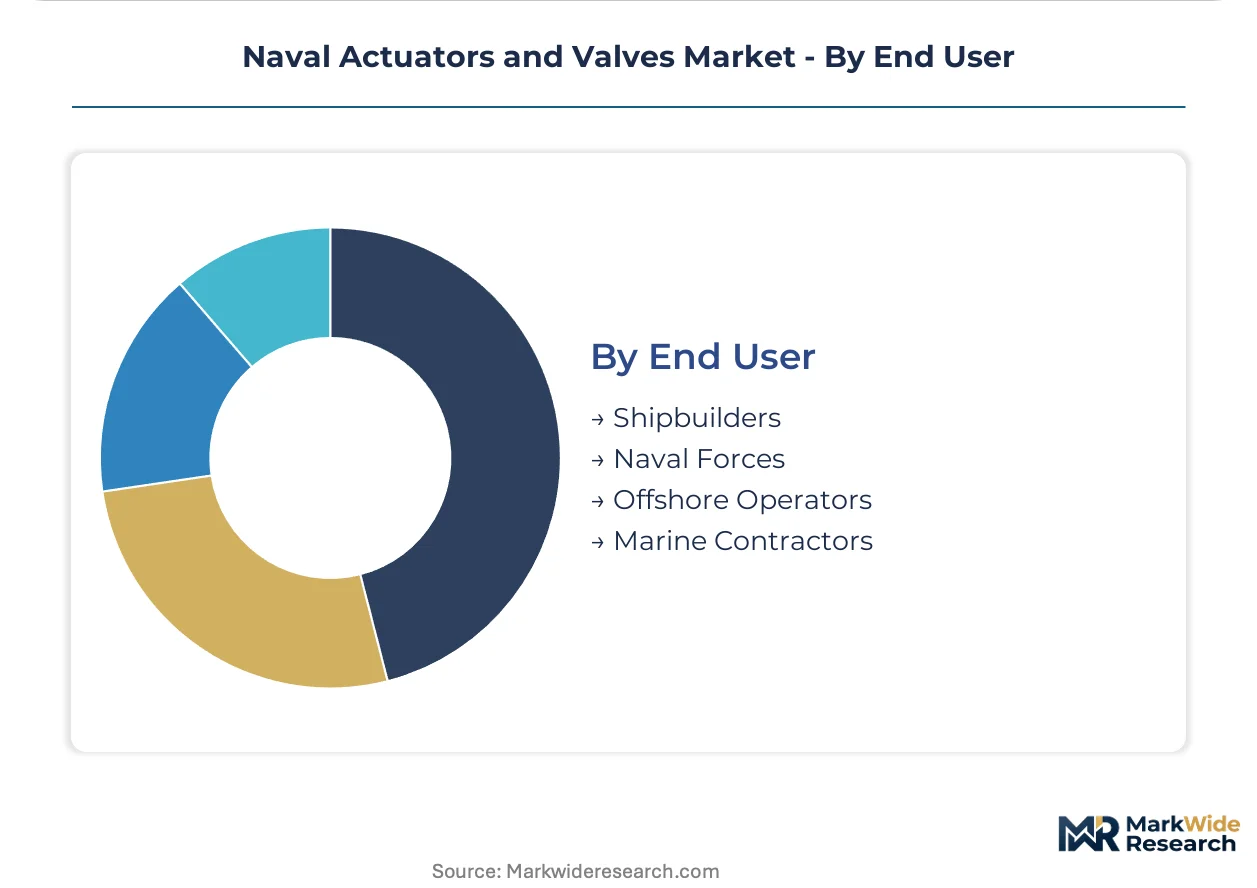
- Naval Forces:United States Navy, Royal Navy, and Marine Nationale procurement agencies specify performance-based availability contracts rather than unit pricing, transferring technical risk to suppliers. AUKUS nuclear submarine program coordination is harmonizing qualification requirements across United States, United Kingdom, and Australian procurement.
- Shipbuilders:Platform primes including BAE Systems, Naval Group, and Huntington Ingalls Industries specify unified digital architectures that collapse traditional boundaries between mechanical and electronic suppliers.
- Offshore Operators:Commercial vessel and oil platform operators demand lower-specification components with reduced certification overhead.
- Marine Contractors:Maintenance and upgrade providers capture aftermarket revenue through spare part logistics and field service networks.
Naval forces dominate procurement value, with shipbuilders consolidating specification authority most aggressively.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France concentrates submarine-grade valve procurement for ballistic missile programs, while Australia generates fresh demand through nuclear submarine acquisition under the AUKUS security framework.
United States
The Naval Sea Systems Command drives actuator modernization for Columbia-class submarines and Constellation-class frigates. MIL-STD-167 and MIL-S-901 shock standards dictate metallurgy and seal specifications for combatant vessels. Huntington Ingalls Industries in Newport News and Electric Boat in Groton anchor nuclear submarine construction with integrated valve architectures.
United Kingdom
The Dreadnought submarine replacement program sustains demand for nuclear-grade gate valves and precision motion control systems. Ministry of Defence procurement emphasizes through-life availability contracts over discrete component pricing. BAE Systems in Barrow-in-Furness consolidates specification authority for integrated sensor-actuator networks.
Germany
Thyssenkrupp Marine Systems specifies electric actuation for Type 212CD submarines and F126 frigates under EU F-Gas Regulation compliance timelines. REACH restrictions on synthetic hydraulic fluids compress qualified supplier lists for naval shipyards. The Kiel industrial cluster hosts specialized foundries supplying nickel-based superalloy valve housings.
France
Naval Group dominates procurement for SNLE 3G ballistic missile submarines and intermediate-size frigates through state-backed fleet modernization. ANSM and CNIL cybersecurity mandates increasingly classify valve networks as critical digital infrastructure. The Toulon naval base region concentrates maintenance and upgrade activity for Mediterranean fleet operations.
Australia
The AUKUS nuclear submarine program generates long-term demand for US-UK qualified valves and precision actuators with nuclear heritage certification. Defence procurement harmonization with NATO standards accelerates supplier qualification timelines. Osborne in South Australia and Henderson in Western Australia emerge as submarine construction and sustainment hubs.
Naval Actuators and Valves Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across NATO naval procurement programs. The supplier base concentrates around three tiers: integrated platform primes with specification authority, subsystem specialists with shock certification heritage, and component fabricators with nuclear-grade manufacturing credentials. Dominant competitive moves include backward integration into precision casting and strategic partnerships for digital twin integration.
Among precision motion control specialists, MOOG Inc. and Curtiss-Wright Corporation occupy positions within the shock-certified actuator tier. Honeywell International Inc. exemplifies the diversified conglomerate archetype competing through integrated valve-sensor architectures. These three companies represent contrasting strategic postures: focused electromechanical heritage versus broad aerospace-defence diversification.
| Leading Market Players |
|---|
| MOOG Inc. |
| Honeywell International Inc. |
| Rotork plc |
| Emerson Electric Co. |
| Curtiss-Wright Corporation |
| Parker Hannifin Corporation |
| Rolls-Royce Holdings plc |
| Thales Group |
| Flowserve Corporation |
| Others |
Supply & Pricing Matrix
Sovereign-backed defense primes and family-owned precision foundries in Germany and Japan anchor supply-side discipline, translating concentrated nickel-alloy sourcing into rigid price floors for nuclear-grade valve assemblies. This ownership pattern insulates tier-one suppliers from spot-market volatility while compressing margin headroom for mid-tier actuator vendors serving surface combatant programs.
Pricing Analysis
Capacity additions in South Korea and Poland are reshaping price floors for standard-grade electric actuators used in non-nuclear surface vessels. Three-tier pricing structure across MIL-S-901 certified, NATO-interoperable, and commercial-marine tiers separates United States submarine programs from European frigate new-builds and offshore support vessels. Cost compression in the commercial-marine tier intensifies because South Korean shipyards exploit scale economies and lower labor costs. Platform primes exhibit the least price sensitivity due to through-life availability contracting, while marine contractors face acute margin pressure on spare parts procurement.
Supply Chain Analysis
Specialized welder and precision machinist shortages in Kiel, Toulon, and Groton constrain throughput at certified foundries producing nickel-based superalloy valve housings. Supply concentrates in Germany, Japan, and the United States for submarine-grade components, with Italy and Spain capturing surface combatant electric actuator assembly. Raw material dependencies center on nickel superalloys, rare-earth magnets for brushless DC motors, and high-performance seal elastomers. Single-source vulnerability persists for ANSM-certified nuclear valve forgings from a limited qualified supplier base. Distribution runs through platform prime procurement offices rather than open distribution channels, with Huntington Ingalls Industries and Naval Group consolidating specification authority.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between United States and Australian procurement, where identical AUKUS-qualified components command premium pricing in Australian dollars against fixed United States Navy contract ceilings, exploiting defense procurement harmonization lags.
For Market Incumbents: Lock in long-term nickel-alloy supply agreements with Kiel and Pittsburgh foundries before REACH restrictions further compress qualified supplier lists. Anchor specification authority through embedded digital twin competencies that platform primes cannot easily replicate. Electric actuator displacement of hydraulic systems in submarine ballast applications represents the critical substitution threat requiring pre-emptive torque-density R&D investment. For New Entrants and Emerging Players: EU F-Gas Regulation in Germany and Spain opens a window for pneumatic actuator specialists to capture frigate auxiliary system contracts abandoned by hydraulic fluid-dependent incumbents. Polish naval expansion under NATO interoperability standards offers the most penetrable geographic entry point for mid-tier suppliers without nuclear heritage. Target shipbuilder-direct procurement relationships rather than naval agency channels to bypass entrenched prime-vendor lock-in. For Investors and Strategic Acquirers: Valuations sit cheapest among precision casting specialists with dormant nuclear-grade certifications and underutilized shock-test facilities. Five-to-ten-year viability hinges on AUKUS program execution rather than cyclical defense budget fluctuations. Acquisition target archetype: German or Japanese mid-caps with nickel-superalloy foundry assets and latent MIL-S-901 certification capacity. Monitor Australian Defence Department qualification timeline acceleration as the inflection signal for entry valuation repricing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Nickel-Superalloy Foundry Capacity | Captures margin from Kiel and Pittsburgh suppliers while securing REACH-compliant material traceability for European naval programs. |
| Digital Twin Platform Development | Enables predictive maintenance contracts with United States Naval Sea Systems Command and Royal Navy through-life availability frameworks. |
| AUKUS Qualification Harmonization Investment | Accelerates supplier approval for Australian nuclear submarine construction at Osborne and Henderson facilities. |
| Electric Actuator Torque Density R&D | Addresses electromechanical limitations in submarine ballast systems currently preserving hydraulic lock-in for critical functions. |
| Cybersecurity Protocol Hardening | Satisfies ANSM and Naval Sea Systems Command mandates classifying valve networks as critical digital infrastructure. |
Research Methodology
Direct dialogue with submarine platform engineers, naval procurement officers at Naval Sea Systems Command and Ministry of Defence, precision foundry operations managers, and electric actuator R&D directors grounded qualitative assessments in operational reality. Secondary validation drew from MIL-STD-167 and MIL-S-901 specification documents, EU F-Gas Regulation compliance filings, AUKUS program coordination announcements, and SEC 10-K disclosures from diversified defense conglomerates. Bottom-up component demand modeling triangulated against top-down naval shipbuilding budget allocations.
Top-down budget-flow analysis traced United States Navy, Royal Navy, and Marine Nationale procurement authority through platform primes to subsystem tiers, while bottom-up bill-of-materials estimation quantified actuator and valve content per vessel class across the projection horizon. Segmentation dimensions encompassed product type, application criticality tier, propulsion architecture, and end-user procurement authority concentration. CAGRs derived from vessel delivery schedules and modernization cycle phasing, with electric-hydraulic technology substitution curves calibrated to REACH and F-Gas Regulation compliance timelines.
Revisions become necessary when AUKUS program coordination delays, nickel-alloy supply disruptions from German or Japanese foundry constraints, or cybersecurity mandate scope expansions materialize beyond baseline assumptions. Material deviation in submarine construction schedules or regulatory enforcement intensity warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Servo Valves Market
Valves
Mooring Inspection Market
Valves
Global Valves in Oil and Gas Industry Market
Valves
Europe Vacuum Insulated Pipe Market
Valves
Europe Electro Hydraulic Servo Valve Market
Valves
Sandblast Valves Market
Valves
North America Butterfly Valve Market
Valves
One-Way Valve Market
Valves
Steam Trap Valve Market
Valves
Industrial Valves and Actuators Market
Valves
Pipeline and Process Services Market
Valves
Air Jet Ejectors Market
Valves
Mechanical Shaft Seal Market
Valves
Global Level Gauge Market
Valves
Asia-Pacific Industrial Valves Market
Valves
Rising Stem Ball Valve Market