
 Netherlands LNG Bunkering Market | 2026-2036
Netherlands LNG Bunkering Market Size, Share, and Industry Trends Forecast 2026-2036
Netherlands LNG Bunkering Market Foresight
Bio-LNG is pivoting from niche pilot volumes toward mainstream bunker economics as shipowners face EU Emissions Trading System compliance costs. Royal Dutch Shell leverages its integrated gas-to-liquids supply chain to secure long-term offtake agreements at Rotterdam. Titan LNG anchors its position through dedicated small-scale liquefaction and bunkering vessel operations across Dutch and Belgian ports. Gasunie competes by controlling onshore LNG import terminal access that feeds marine distribution networks.
Netherlands LNG bunkering denotes the commercial supply of liquefied natural gas as marine fuel to vessels operating in Dutch territorial waters and exclusive economic zones, with product delivered at temperatures below minus 162 degrees Celsius to maintain cryogenic liquid state. The practice displaces residual fuel oil in deep-sea shipping, container feeders, and offshore support vessels seeking compliance with sulfur emission control areas. Ship-to-ship transfer operations capture the dominant share of volume as this mode minimizes port stay time for large container carriers and tankers. Port-based bunkering sustains steady demand from short-sea shipping and inland waterway operators with predictable route patterns. Bio-LNG within fuel type segmentation commands expanding interest from operators targeting well-to-wake carbon intensity reductions under FuelEU Maritime standards.
The Dutch Human Environment and Transport Inspectorate enforces bunker delivery note compliance and fuel quality verification under EU MRV and IMO DCS frameworks. The European Maritime Safety Agency coordinates port state control inspections that validate LNG bunkering safety protocols and cryogenic handling equipment certification. The Netherlands Enterprise Agency administers subsidy schemes for shore power and alternative fuel infrastructure that lower capital barriers for terminal investments. Stakeholders must monitor how FuelEU Maritime tightening affects bio-LNG certificate pricing and whether Rotterdam's hydrogen import ambitions divert infrastructure capital from LNG expansion.
Market Dynamics
The Netherlands LNG bunkering market pivots on FuelEU Maritime's tightening carbon intensity benchmarks, which force shipowners to abandon residual fuel oil and lock in long-term bio-LNG offtake contracts at Rotterdam and Amsterdam terminals.
Growth Catalysts
- FuelEU Maritime:The EU regulation mandates progressive greenhouse gas intensity reductions for marine fuels, compelling container lines and tanker operators to source LNG bunkers at Dutch ports.
- Rotterdam-Antwerp corridor concentration:Dense clustering of liquefaction terminals, storage facilities, and bunkering vessels creates network economies that lower delivered fuel costs for vessel operators.
- Ship-to-ship transfer protocols:Cryogenic cargo-handling standards refined through EMSA coordination minimize port stay times for ultra-large container carriers, accelerating adoption.
Market Restraints
- Bio-LNG certificate scarcity:Limited production of biomethane meeting ISCC-EU sustainability criteria constrains supply of compliant fuel for vessels targeting well-to-wake emissions reductions.
- Liquefaction capacity concentration:Small-scale liquefaction infrastructure remains concentrated at Rotterdam and Amsterdam, leaving Zeeland and northern port clusters dependent on trucked supply.
- Hydrogen import competition:Gasunie's planned hydrogen terminal investments at Rotterdam divert infrastructure capital and regulatory attention from LNG expansion timelines.
Strategic Opportunities
- Zeeland port cluster:Vlissingen and Terneuzen terminals remain underdeveloped for LNG bunkering, offering first-mover positioning for dedicated small-scale liquefaction investments.
- Inland waterway expansion:Rhine-Maas-Scheldt delta push boats and river cruise vessels represent untapped demand segments for truck-to-barge bunkering services.
- Shore power subsidy schemes:Netherlands Enterprise Agency funding for alternative fuel infrastructure lowers capital barriers for terminal operators adding simultaneous LNG bunkering and electrification capabilities.
Industry Challenges
- Cryogenic engineer scarcity:Specialized technicians certified for minus 162 degree Celsius cargo handling command premium wages, constraining operational scaling at new terminal sites.
- Bunker delivery note compliance:Dutch Human Environment and Transport Inspectorate enforcement of EU MRV documentation requirements creates administrative friction for multi-fuel vessel operators.
- IMO DCS integration complexity:Shipowners face technical hurdles aligning onboard fuel consumption monitoring with port-side LNG mass flow metering for seamless regulatory reporting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Netherlands LNG Bunkering Market |
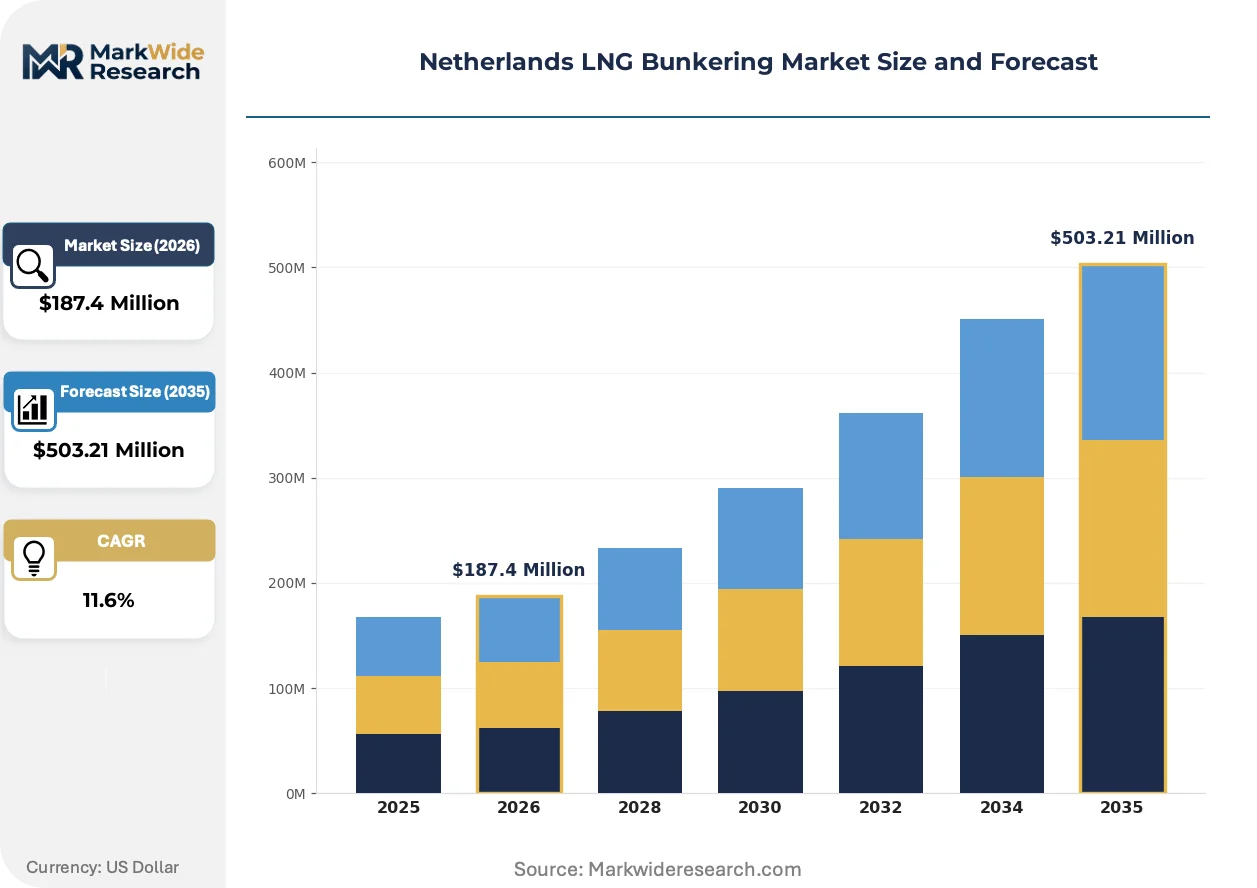
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $503.21 Million |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Fuel Type: Low Sulfur LNG, Synthetic LNG, Bio-LNG, Others Operation Mode: Ship-to-Ship, Port-Based, Terminal Operations, Others End User: Shipping Companies, Freight Forwarders, Offshore Operators, Others Service Model: Fuel Supply, Consultancy, Maintenance, Others |
| Companies Covered | Royal Dutch Shell, TotalEnergies, Titan LNG, Gasunie, Port of Rotterdam, Engie, Houpu Clean Energy, Spliethoff Group, Broadview Energy Solutions, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Netherlands LNG Bunkering Market Shifts & Advancements
Bio-LNG certification systems and digital fuel tracking platforms are compressing transaction frictions and enabling granular carbon accounting for vessel operators navigating EU compliance frameworks.
Dual-fuel engine retrofits are rewriting vessel economics across the Dutch fleet. Wärtsilä and MAN Energy Solutions propulsion systems enable container lines to switch between LNG and conventional fuel without dry-docking. Deep-sea operators at Rotterdam now specify bio-LNG blends in charter party agreements. This technology is rewriting the cost structure of compliance, allowing shipowners to arbitrage between fuel types as certificate prices fluctuate.
FuelEU Maritime's phase-in schedule tightens carbon intensity thresholds every five years through 2050. The regulation forces fuel suppliers to document well-to-wake emissions through certified mass-balance systems. Container shipping lines calling Rotterdam now require proof of sustainability certification before contracting bunkers, shifting procurement criteria from price-per-tonne to verified carbon intensity scores.
Long-term offtake contracting is displacing spot market purchases among Dutch port users. Container lines lock in multi-year bio-LNG supply agreements directly with terminal operators, bypassing traditional marine fuel traders. This pattern concentrates procurement power with integrated energy majors controlling liquefaction assets. The shift is most visible among Asia-Europe trade lane operators bunkering at Rotterdam for round-voyage fuel security.
Netherlands LNG Bunkering Market Segmentation
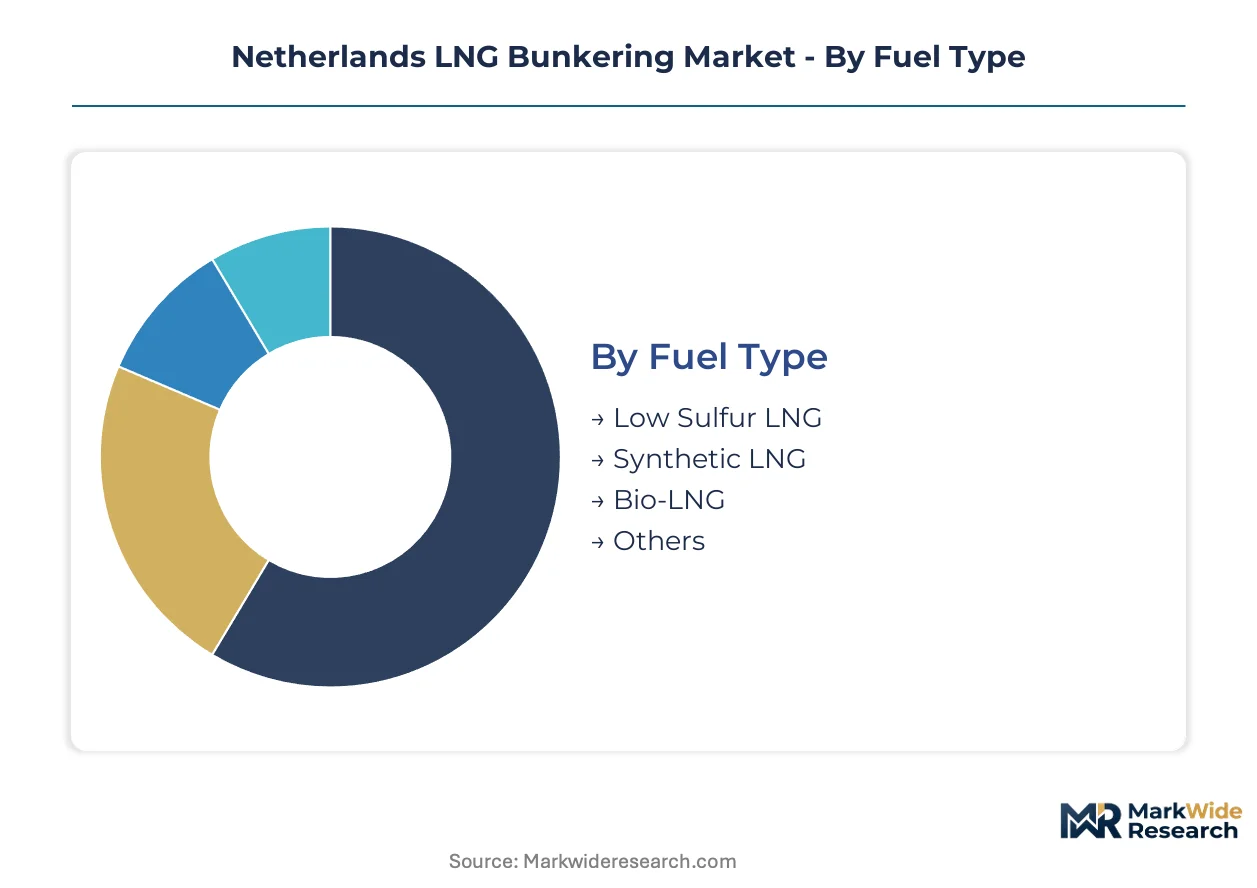
Segmentation in the Netherlands LNG bunkering market reveals how fuel types, operational modes, and service models align with distinct compliance pressures and infrastructure investments. Each category maps to specific vessel operator requirements under FuelEU Maritime and the EU Emissions Trading System.
Fuel Type:
Standalone fuels dominate bunkering volumes, while synthetic and bio-variants embed into carbon accounting systems as compliance instruments.
- Low Sulfur LNG:Conventional liquefied natural gas with sulfur content below 0.1% by mass, meeting IMO 2020 marine fuel standards. Demand concentrates among deep-sea container carriers at Rotterdam seeking immediate SOx compliance without retrofit complexity.
- Bio-LNG:Liquefied biomethane produced through anaerobic digestion or thermal gasification, certified under ISCC-EU mass-balance systems. Rotterdam-based operators targeting FuelEU Maritime carbon intensity reductions drive procurement, though certificate scarcity constrains scaling.
- Synthetic LNG:E-fuels produced via power-to-gas processes using renewable hydrogen and captured carbon dioxide. Pilot volumes enter Dutch ports through demonstration projects at Amsterdam terminals.
- Others:Includes LNG-diesel blends and small-scale experimental fuels undergoing certification at Netherlands Enterprise Agency-supported test facilities.
Volume placements concentrate in Low Sulfur LNG; the faster expansion belongs to Bio-LNG.
Operation Mode:
Transfer protocols segment by time sensitivity and vessel size, with high-throughput methods commanding infrastructure priority.
- Ship-to-Ship:Direct LNG transfer between specialized bunkering vessels and receiving ships at anchorage or underway. Ultra-large container carriers at Rotterdam Maasvlakte terminals minimize port stay hours through this mode, driving capital allocation toward dedicated bunker vessel fleets.
- Port-Based:Shore-side truck-to-ship or quay-side pipeline delivery for vessels with predictable schedules. Short-sea feeders and inland waterway operators at Amsterdam and Vlissingen favor this lower-cost entry point.
- Terminal Operations:Large-scale loading from onshore storage tanks via cryogenic transfer arms. Gasunie's Gate terminal at Rotterdam anchors this segment for tanker fleets requiring full cargo-volume bunkering.
- Others:Includes mobile bunkering units and emergency supply protocols for offshore support vessels operating in Dutch North Sea zones.
Ship-to-Ship captures the highest throughput volumes; Port-Based methods are climbing the fastest as Zeeland port clusters expand access.
End User:
Customer concentration follows trade lane density, with Asia-Europe operators anchoring demand and offshore segments pursuing niche positioning.
- Shipping Companies:Container lines, tanker operators, and bulk carriers managing owned or chartered fleets. Rotterdam bunkering volumes concentrate among Asia-Europe trade lane operators securing round-voyage fuel security through long-term offtake contracts.
- Freight Forwarders:Logistics integrators contracting bunkering as part of multimodal service packages. Amsterdam port clusters attract this segment for short-sea connections to German and Belgian hinterlands.
- Offshore Operators:Supply vessel and platform service companies operating in Dutch North Sea oil and gas fields. Demand clusters at Den Helder and IJmuiden for helicopter fueling and emergency power generation.
- Others:Includes government vessels, research ships, and river cruise operators on Rhine-Maas-Scheldt delta routes.
Shipping Companies dominate contract value; Offshore Operators represent the steepest expansion trajectory as North Sea decommissioning activity intensifies.
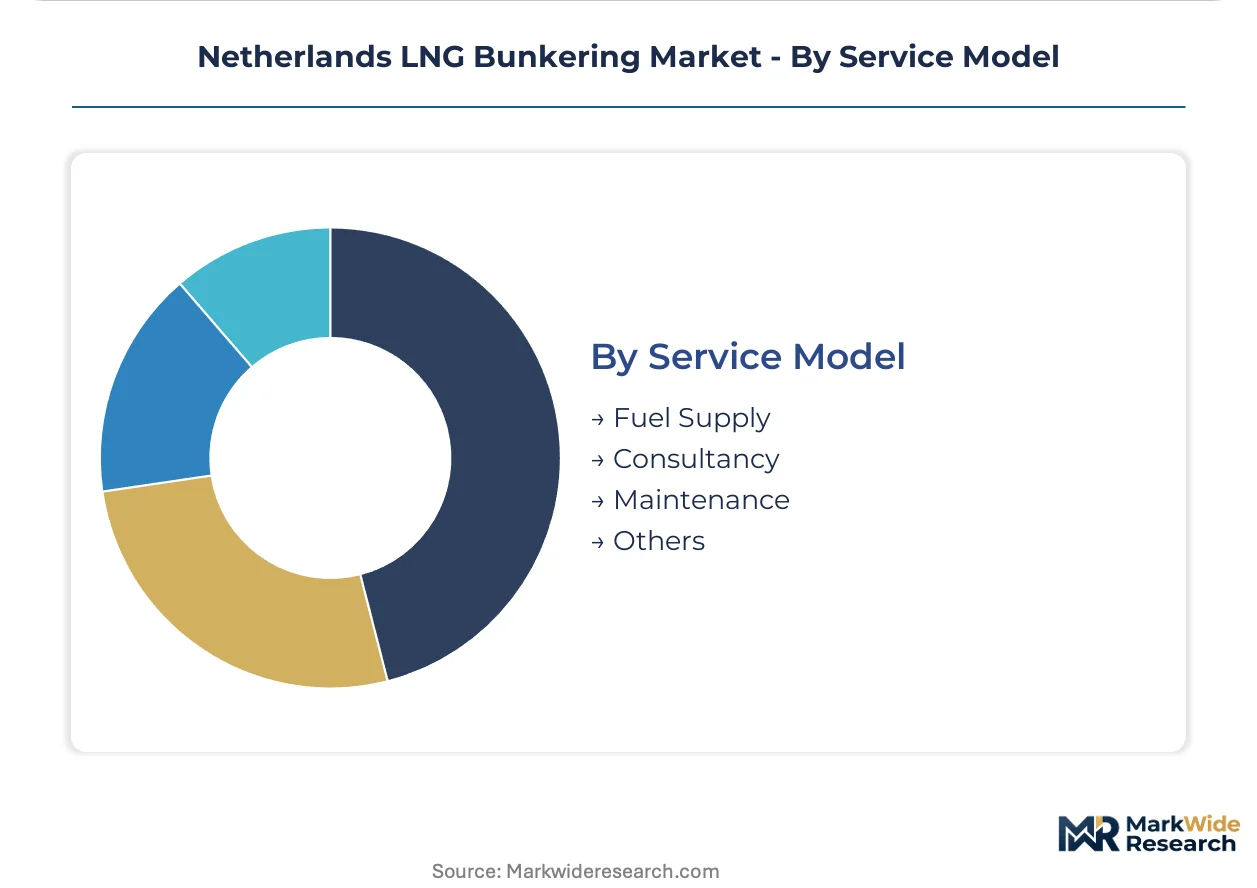
Service Model:
Revenue streams separate commodity supply from value-added services, with maintenance and consultancy gaining share as fleet complexity rises.
- Fuel Supply:Physical LNG delivery including storage, regasification coordination, and mass flow metering. Titan LNG and integrated energy majors control this segment through captive liquefaction assets at Rotterdam and Amsterdam.
- Consultancy:Regulatory compliance advisory, carbon accounting, and FuelEU Maritime strategy development. EMSA-certified training providers at Rotterdam anchor demand as shipowners navigate certification complexity.
- Maintenance:Cryogenic equipment servicing, bunkering system inspections, and dual-fuel engine technical support. Specialized technicians command premium wages, constraining scaling at new terminal sites.
- Others:Includes insurance brokerage, financing arrangements, and digital fuel tracking platform subscriptions.
Fuel Supply commands the revenue base; Consultancy services are gaining share fastest as regulatory reporting obligations multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rotterdam and Amsterdam concentrate bunker demand from Asia-Europe container lines seeking FuelEU Maritime compliance. Dutch ports anchor northwest European LNG supply chains through dense terminal clustering and integrated gas-to-liquids infrastructure.
Germany
Hamburg and Bremen ports drive demand from short-sea feeders connecting Scandinavian and Baltic markets. The German Federal Maritime and Hydrographic Agency enforces LNG bunkering safety protocols aligned with EMSA standards. Industrial concentration clusters along the Lower Elbe where dual-fuel retrofits accelerate among container feeder operators.
Belgium
Antwerp-Bruges port complex anchors cross-border bunkering demand from Dutch-registered vessels. The Flemish Environment Agency coordinates emission monitoring with Dutch regulators under the EU MRV framework. Zeebrugge terminal operations feed marine distribution networks serving North Sea offshore support fleets.
United Kingdom
Southampton and Immingham ports attract Dutch bunkering operators seeking regulatory arbitrage post-Brexit. The UK Maritime and Coastguard Agency maintains divergent safety certification requirements from EU EMSA protocols. Thames estuary clustering concentrates demand from ferry operators transitioning from residual fuel oil.
France
Dunkirk and Le Havre terminals compete with Dutch ports for English Channel transit traffic. The French Directorate General of Maritime Affairs implements FuelEU Maritime enforcement through port state control inspections. Normandy industrial corridors host pilot synthetic LNG demonstration projects competing for bio-LNG certificate flows.
Norway
Stavanger and Bergen offshore supply bases drive specialized bunkering demand from North Sea platform service vessels. The Norwegian Maritime Authority mandates stringent cryogenic handling standards that Dutch operators must match for cross-border contracts. Western fjord clustering concentrates pioneering ship-to-ship transfer protocols for LNG-fueled offshore construction vessels.
Netherlands LNG Bunkering Market Competitive Landscape
Long-term offtake contracting dominates the current landscape as container lines bypass spot markets for multi-year supply security. The vendor base stratifies between integrated energy majors controlling liquefaction assets and specialized bunkering operators managing vessel fleets. Three archetypes anchor positioning: captive upstream suppliers, independent bunkering specialists, and port authority infrastructure controllers. Competitive intensity centers on terminal access rights and bio-LNG certificate procurement rather than price alone.
Within the integrated energy tier, Royal Dutch Shell and TotalEnergies exemplify upstream-downstream bundling through Rotterdam Gate terminal offtake. Titan LNG occupies the specialist bunkering vector with dedicated small-scale liquefaction and vessel operations across Dutch and Belgian ports. Gasunie anchors infrastructure control through onshore import terminal access that feeds marine distribution networks, representing the utility-archetype competitive position.
| Leading Market Players |
|---|
| Royal Dutch Shell |
| TotalEnergies |
| Titan LNG |
| Gasunie |
| Port of Rotterdam |
| Engie |
| Houpu Clean Energy |
| Spliethoff Group |
| Broadview Energy Solutions |
| Others |
Supply & Pricing Matrix
FuelEU Maritime's carbon intensity benchmarks gate both qualified bio-LNG supply and premium-tier pricing access for Dutch terminal operators. Shipowners seeking compliance pay spreads above conventional LNG for certified biomethane, while uncertified volumes trade at commodity discounts.
Pricing Analysis
Volume trades at thin margins while certified bio-LNG commands substantial premiums. Three-tier pricing structure across certified bio-LNG, conventional low-sulfur LNG, and uncertified spot volumes reflects ISCC-EU mass-balance documentation costs. Price differentiation stems from certificate scarcity and vessel operator compliance urgency under tightening EU ETS carbon costs. Container lines at Rotterdam show least price sensitivity due to charter party pass-through mechanisms, while short-sea operators at Zeeland ports resist premium tiers.
Supply Chain Analysis
ISCC-EU certification gates access to premium supply tiers and downstream offtake contracts. Biomethane production concentrates in the Netherlands, Belgium, and Denmark where anaerobic digestion feedstocks cluster near port infrastructure. The supply chain draws from agricultural waste, sewage sludge, and dedicated energy crops as primary inputs. Single-source vulnerability runs through Rotterdam Gate terminal for large-scale LNG import. Distribution runs through integrated energy majors controlling liquefaction assets, specialized bunkering vessel operators, and truck-based last-mile delivery to Zeeland and northern ports.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Bio-LNG liquefaction capacity scarcity props pricing power for incumbent terminal operators. Small-scale production bottlenecks at Rotterdam and Amsterdam limit supply response to demand surges.
For Market Incumbents: Hedge certificate procurement exposure through long-term biomethane supply agreements with Dutch and Danish biogas producers. Titan LNG and integrated majors should expand Zeeland liquefaction capacity before hydrogen infrastructure diverts capital, locking in first-mover terminal access at Vlissingen. For New Entrants and Emerging Players: FuelEU Maritime in the European Union opens a window for specialized bio-LNG certification and carbon accounting consultancy services. Target inland waterway operators on Rhine-Maas-Scheldt delta routes with truck-to-barge bunkering solutions, leveraging Netherlands Enterprise Agency subsidy schemes to lower terminal capital barriers. For Investors and Strategic Acquirers: First-mover liquefaction investments at Terneuzen or Den Helder is the leading indicator that supply-constrained pricing will persist. Focus acquisition screening on small-scale LNG infrastructure operators with captive biomethane supply contracts and EMSA-certified cryogenic handling capabilities.| Strategic Initiative | Industry Significance |
|---|---|
| Bio-LNG Certification Investment | ISCC-EU mass-balance accreditation unlocks premium pricing tiers for Rotterdam terminal operators. |
| Zeeland Capacity Buildout | Vlissingen liquefaction assets capture underserved short-sea and inland waterway demand segments. |
| Long-term Biomethane Supply Agreement | Direct contracts with Danish and Dutch biogas producers hedge certificate scarcity risk. |
| Ship-to-Ship Bunkering Fleet Expansion | Dedicated cryogenic vessels minimize port stay times for ultra-large container carriers at Maasvlakte. |
| Dual-Fuel Engine Technical Support Capability | Wärtsilä and MAN Energy Solutions certification opens recurring maintenance revenue streams. |
Research Methodology
Independent corroboration across terminal operators, shipowners, and classification societies underwrites the qualitative findings in this study. Primary interviews with bunker procurement managers at container lines, cryogenic handling technicians, port authority infrastructure planners, and EMSA-certified safety inspectors combined with secondary validation from EU MRV emissions databases, IMO DCS filings, and Netherlands Enterprise Agency subsidy records. Bottom-up capacity assessments at Rotterdam Gate, Amsterdam, and Zeeland terminals triangulate against top-down trade lane demand projections.
Rate-of-change decomposition separates volume growth from price evolution across the projection horizon. The analytical framework models fuel type segmentation by carbon intensity tier, operation mode by transfer protocol efficiency, end user by trade lane density, and service model by value-added content share. CAGRs derive from installed dual-fuel engine fleet projections, FuelEU Maritime compliance schedule phase-ins, and bio-LNG certificate availability curves. Forecast inputs include bunker delivery note volumes from Dutch Human Environment and Transport Inspectorate records and charter party fuel specification trends.
The model assumes a particular technology adoption path; alternative pathways for hydrogen-derived e-fuels or ammonia propulsion would alter the outlook. Forecasts reflect assumptions about FuelEU Maritime enforcement consistency, biomethane production cost curves, and Rotterdam hydrogen terminal investment timing. A model refresh is warranted upon material change in EU ETS carbon price trajectories or ISCC-EU certification standard revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Oil and Gas Midstream Market
Oil & Gas
Digital Twin in Oil and Gas Market
Oil & Gas
Digital Oilfield Solutions Market
Oil & Gas
United Kingdom Oil and Gas Midstream Market
Oil & Gas
Oil and Gas Swell Packers Market
Oil & Gas
Smart Pigging Market
Oil & Gas
Europe Seismic Services Market
Oil & Gas
Coal Mining Market
Oil & Gas
Mud Logging Unit Market
Oil & Gas
Casing and Cementation Hardware Market
Oil & Gas
Perforating Gun Market
Oil & Gas
Global LNG Regasification Terminals Market
Oil & Gas
Europe Oil and Gas Drones Market
Oil & Gas
Digital Oil Rigs Market
Oil & Gas
Intelligent Well Completion Market
Oil & Gas
Thailand Oil and Gas Market