
 Pressure Gauge Market | 2026-2036
Pressure Gauge Market Size, Share, and Industry Trends Forecast 2026-2036
Pressure Gauge Market Intelligence
The pressure gauge industry is restructuring around a widening split between premium smart instruments and commodity analog units. Honeywell International leverages its sensing portfolio to dominate digital gauge architectures for critical process environments. WIKA Instruments sustains manufacturing scale across Bourdon tube and diaphragm product lines. Emerson Electric differentiates through integrated pressure-temperature transmitters that anchor its position in hydrocarbon processing.
A pressure gauge measures fluid or gas pressure through elastic deformation of sensing elements, with Bourdon tube designs handling ranges from vacuum to 100,000 psi and digital variants converting mechanical displacement into 4-20 mA or HART protocol signals for distributed control systems. Analog gauges retain volume leadership in general manufacturing maintenance budgets, while smart gauges with embedded diagnostics represent the fastest-expanding margin pool as water treatment utilities adopt predictive calibration alerts. Piezoelectric technology leads aerospace applications where miniaturization and shock resistance override cost sensitivity.
The EPA mandates calibrated pressure instrumentation for leak detection in refineries and chemical plants, while OSHA process safety management rules require documented gauge verification intervals in hazardous service. ISO 5171 and ASME B40.1 standards govern accuracy grades and dial configurations, creating compliance barriers for uncertified imports. Stakeholders must monitor how NHTSA brake system pressure specifications and FDA medical device gauge requirements reshape qualification protocols across adjacent industrial segments.
Market Dynamics
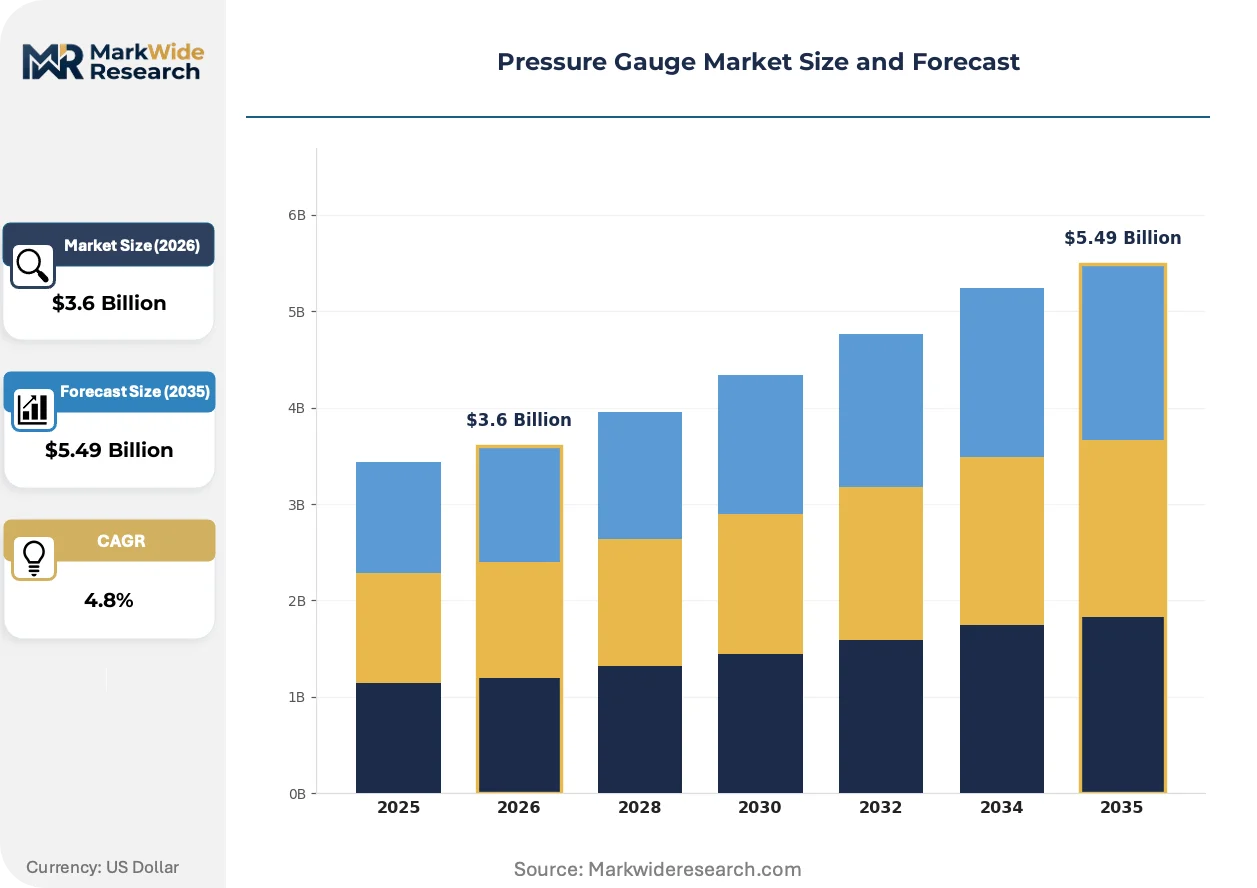
The pressure gauge market is bifurcating sharply between IIoT-enabled smart instruments and legacy analog units, with EPA emissions monitoring mandates and OSHA process safety rules forcing replacement cycles in hazardous service environments.
Growth Catalysts
- EPA leak detection mandates:Refineries and chemical plants across the United States must deploy calibrated pressure instrumentation for continuous emissions monitoring, accelerating gauge replacement schedules.
- IIoT sensor convergence:Water treatment utilities are adopting smart gauges with predictive calibration alerts, creating recurring revenue streams from diagnostics subscriptions.
- Permian Basin extraction intensity:Upstream oil and gas operators are expanding gauge deployments in high-pressure hydraulic fracturing and wellhead monitoring applications.
Market Restraints
- Bourdon tube copper alloy volatility:Input cost swings for phosphor bronze and beryllium copper constrain margin stability for analog gauge manufacturers.
- Chinese sensor module concentration:Domestic supply dependence for piezoelectric transducers creates vulnerability for aerospace gauge assemblers outside Asia.
- ASME B40.1 certification friction:Documented verification intervals for hazardous service gauges impose compliance burdens that delay procurement approvals.
Strategic Opportunities
- India water infrastructure:Municipal utilities under the Jal Jeevan Mission are specifying digital pressure gauges for rural pipeline networks, opening volume deployment potential.
- HART-Modbus convergence:Hybrid protocol gauges bridge legacy 4-20 mA systems with Ethernet-APL architectures, easing brownfield digitalization.
- EU F-Gas Regulation phase-down:Refrigeration system pressure monitoring requirements are expanding gauge attach rates in commercial HVAC retrofit markets.
Industry Challenges
- Metrology technician scarcity:Qualified calibration specialists for ISO 5171-grade verification are concentrated in aging workforce pools across industrial clusters.
- Legacy DCS integration complexity:Smart gauge deployments in hydrocarbon processing face protocol mapping friction with 1990s-era distributed control systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pressure Gauge Market |
| Market Size in 2026 | $3.6 Billion |
| Market Size in 2035 | $5.49 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Analog, Digital, Smart, Differential End User: Oil & Gas, Automotive, Aerospace, Manufacturing Technology: Bourdon Tube, Diaphragm, Capacitive, Piezoelectric Application: Industrial Processes, HVAC, Medical, Water Treatment |
| Companies Covered | Honeywell International, Dwyer Instruments, WIKA Instruments, Tecsis, Baumer Group, Ashcroft, Omega Engineering, Nuova Fima, Emerson Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pressure Gauge Market Strategic Shifts & Innovations
Wireless pressure transmitters and MEMS-based sensing elements are compressing form factors while expanding diagnostic capabilities, reshaping specification sheets across process industries and mobile equipment OEMs.
Piezoelectric thin-film pressure sensors are expanding into aerospace flight control and engine monitoring applications where gram-scale weight reduction and shock resistance override unit economics. Boeing and Airbus tier-one suppliers are qualifying solid-state gauges for next-generation narrowbody programs. This displacement of traditional Bourdon tube architectures is expanding into adjacent motorsport and unmanned aerial vehicle markets.
OSHA process safety management rules are tightening documented gauge verification intervals in hazardous chemical service, forcing maintenance departments toward automated calibration management systems. The regulation is compressing replacement cycles for analog units that lack embedded diagnostic logging. Refinery operators in Texas and Louisiana are responding by specifying smart gauges with timestamped drift alerts.
Aftermarket service unbundling is fragmenting procurement decisions as water utilities separate gauge supply from calibration contracts. Independent metrology labs are capturing recurring revenue that OEMs previously controlled through bundled warranty terms. This disintermediation is most visible in Germany's municipal water sector, where regional purchasing cooperatives now split hardware and service awards.
Pressure Gauge Market Segmentation
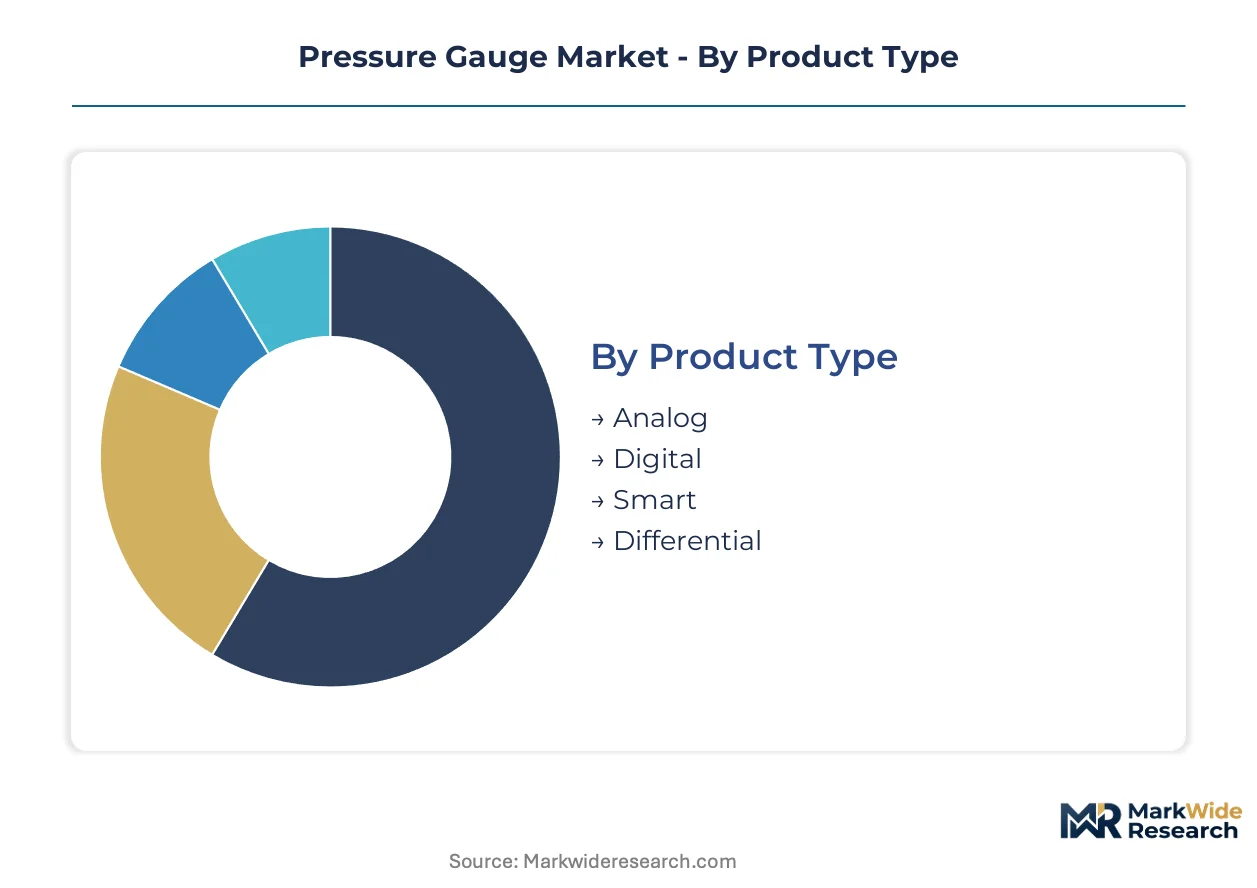
Pressure gauge procurement splits sharply between maintenance-driven replacement cycles and digital transformation budgets. Specification sheets diverge across hazardous service mandates, precision requirements, and connectivity protocols.
Product Type:
Analog gauges dominate unit volume in general industrial maintenance, while smart instruments command premium pricing through embedded diagnostics.
- Analog:Bourdon tube and diaphragm mechanical designs handle vacuum to 100,000 psi ranges. Demand concentrates in general manufacturing maintenance budgets across the United States, where capital constraints favor lowest-first-cost procurement despite higher total cost of ownership.
- Smart:IIoT-enabled gauges with predictive calibration alerts and HART protocol outputs anchor recurring revenue streams. Water treatment utilities in Germany and municipal networks in India under the Jal Jeevan Mission are specifying these for remote pipeline monitoring.
- Digital:Solid-state displays with 4-20 mA signal conversion serve brownfield digitalization projects bridging legacy analog infrastructure.
- Differential:Dual-port designs measure pressure drop across filters, heat exchangers, and flow elements in HVAC and process applications.
Mature deployment sits with Analog. Newer deployment is concentrated in Smart.
End User:
Capital intensity and regulatory exposure determine gauge specification tiers across customer verticals.
- Oil & Gas:Upstream operators in the Permian Basin deploy high-pressure gauges for hydraulic fracturing and wellhead monitoring. EPA leak detection mandates and OSHA process safety management rules force documented verification intervals that favor smart gauge adoption.
- Manufacturing:General industrial maintenance represents the highest unit volume segment, with analog gauges dominating spare parts procurement.
- Aerospace:Piezoelectric thin-film sensors are displacing traditional architectures in Boeing and Airbus flight control and engine monitoring programs where gram-scale weight reduction overrides unit economics.
- Automotive:NHTSA brake system pressure specifications and EV thermal management requirements reshape qualification protocols for tier-one suppliers.
Volume leadership sits with Manufacturing. Technology migration is accelerating fastest in Aerospace.
Technology:
Sensing element selection trades mechanical robustness against miniaturization and signal fidelity requirements.
- Bourdon Tube:C-shaped or spiral metallic tubes exploit elastic deformation for pressure-to-displacement conversion. Refinery operators in Texas and Louisiana specify these for ASME B40.1 hazardous service where proven field history outweighs smart features.
- Piezoelectric:Quartz or ceramic crystals generate charge proportional to applied stress. Aerospace and unmanned aerial vehicle markets prioritize shock resistance and form factor compression.
- Diaphragm:Corrugated metallic membranes suit low-pressure and corrosive media applications in chemical processing.
- Capacitive:MEMS-based designs enable sub-millimeter form factors for medical device and portable instrumentation integration.
Installed base concentration sits with Bourdon Tube. Steepest expansion trajectory is in Piezoelectric.
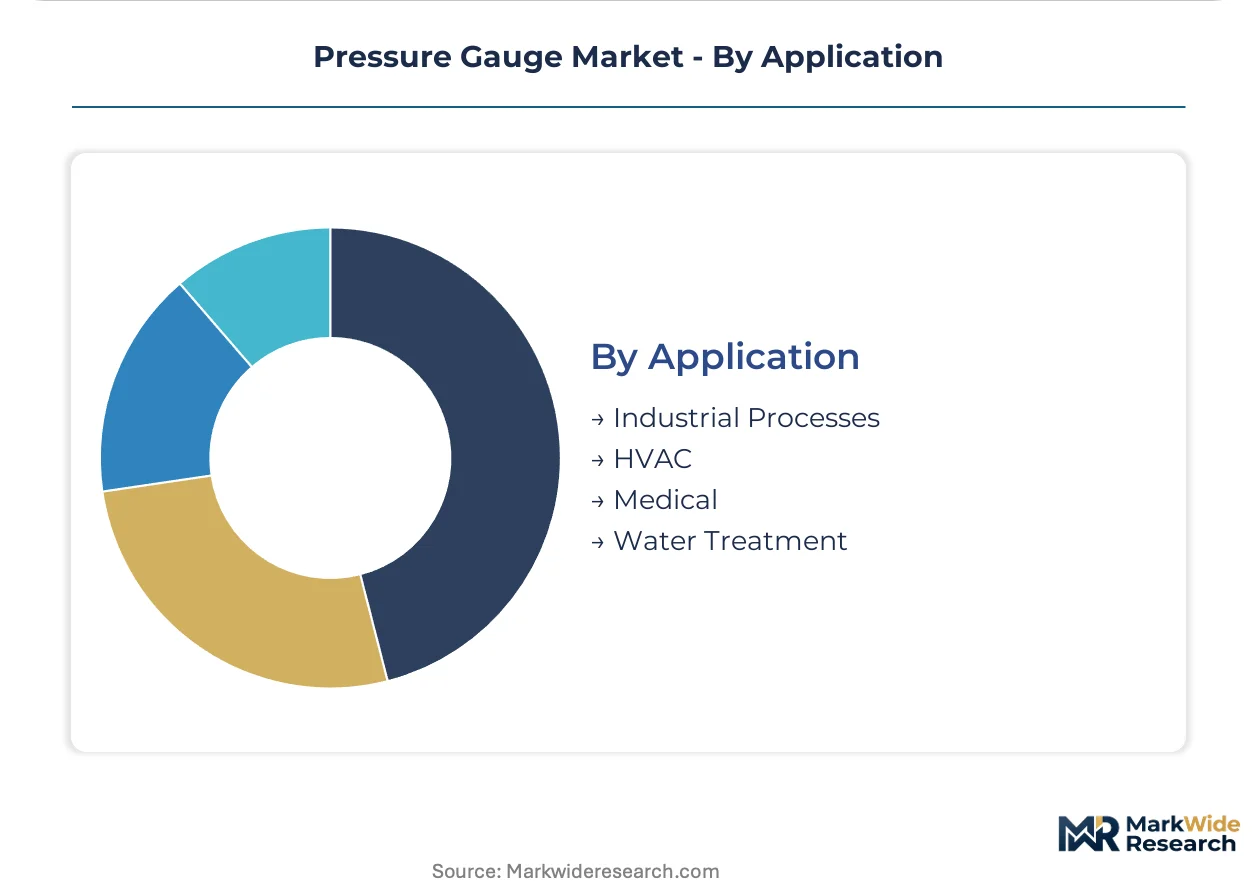
Application:
Regulatory mandates and infrastructure investment cycles reshape gauge attach rates across use cases.
- Industrial Processes:Hydrocarbon processing, chemical plants, and refineries drive specification complexity through EPA emissions monitoring and ISO 5171 accuracy grade requirements.
- Water Treatment:Municipal utilities are unbundling gauge supply from calibration contracts, fragmenting procurement decisions and opening volume deployment in India's rural pipeline networks.
- HVAC:EU F-Gas Regulation phase-down expands pressure monitoring requirements in commercial refrigeration retrofit markets.
- Medical:FDA device gauge requirements and ISO standards govern sterilizable designs for respiratory and infusion equipment.
Specification maturity sits with Industrial Processes. Infrastructure investment is concentrating fastest in Water Treatment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Houston anchors the world's most concentrated pressure gauge procurement activity, with Gulf Coast refineries and Permian Basin operators driving specification intensity for hazardous service instruments.
United States
EPA leak detection mandates and OSHA process safety management rules force documented verification intervals across Texas and Louisiana refining clusters. Refinery operators in the Houston Ship Channel and Lake Charles corridor specify smart gauges with timestamped drift alerts. The Permian Basin extraction surge deploys high-pressure instrumentation for hydraulic fracturing and wellhead monitoring.
Germany
Municipal water utilities under the EU F-Gas Regulation phase-down expand pressure monitoring requirements in commercial HVAC retrofit markets. Regional purchasing cooperatives split hardware and service awards, fragmenting procurement decisions. The Ruhr industrial belt and Bavarian manufacturing corridors concentrate analog gauge maintenance demand alongside digital transformation budgets.
China
Domestic supply dependence for piezoelectric transducers creates vulnerability for aerospace gauge assemblers outside Asia. The Yangtze River Delta and Pearl River Delta manufacturing zones concentrate sensor module production. MIIT industrial upgrading programs accelerate smart instrument adoption in process industries.
India
The Jal Jeevan Mission specifies digital pressure gauges for rural pipeline networks, opening volume deployment potential. Municipal utilities under CEA water infrastructure mandates unbundle gauge supply from calibration contracts. Gujarat and Maharashtra industrial corridors drive manufacturing maintenance demand for analog units.
Japan
METI industrial automation roadmaps prioritize IIoT-enabled instrumentation in chemical processing and semiconductor fabrication. The Chubu-Nagoya aerospace cluster qualifies piezoelectric thin-film sensors for Boeing and Airbus tier-one supply chains. Kanto region water treatment utilities adopt predictive calibration alert systems.
Pressure Gauge Market Key Industry Players
Premium-margin players sit above commodity-margin players across certification grade and protocol complexity. The market structures around three tiers: diversified industrial conglomerates with sensing portfolios, specialized instrument manufacturers with Bourdon tube scale, and MEMS-focused technology licensors. Consolidation pressure concentrates among analog specialists facing copper alloy input volatility. Strategic moves center on backward integration into sensor element production and protocol licensing for brownfield digitalization.
Within the diversified conglomerate tier, Honeywell International and Emerson Electric exemplify premium positioning through integrated sensing architectures. WIKA Instruments anchors the specialized manufacturing tier with German-scale Bourdon tube and diaphragm production. These three occupy positions spanning hazardous service certification, IIoT protocol convergence, and aftermarket service unbundling.
| Leading Market Players |
|---|
| Honeywell International |
| Dwyer Instruments |
| WIKA Instruments |
| Tecsis |
| Baumer Group |
| Ashcroft |
| Omega Engineering |
| Nuova Fima |
| Emerson Electric |
| Others |
Cost & Logistics Intelligence
MEMS-based sensing element miniaturization is compressing production costs for solid-state gauges while concentrating supply leverage among semiconductor-grade foundries in Taiwan and Japan. This dual effect is widening margin spreads between commodity analog units and premium smart instruments across the pressure gauge industry.
Pricing Analysis
Outcome-based pricing anchors premium tiers, with smart gauge vendors capturing recurring revenue from predictive calibration subscriptions tied to uptime guarantees. Price differentiation separates ASME B40.1-certified hazardous service instruments from general industrial maintenance units. Cost compression in analog Bourdon tube segments is intensifying because phosphor bronze and beryllium copper input volatility constrains margin stability. General manufacturing maintenance buyers exhibit highest price sensitivity, while refinery operators in Texas and Louisiana prioritize certification grade over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from oil and gas majors, while independent distributors serve fragmented maintenance procurement across general manufacturing. Geographic supply concentration centers on Germany for Bourdon tube precision machining, China for piezoelectric transducer modules, and the United States for IIoT-enabled smart gauge final assembly. Raw material dependencies draw from copper alloy feedstock for analog sensing elements, silicon wafers for MEMS production, and rare earth components for piezoelectric crystals. Single-source vulnerability for Chinese sensor modules creates exposure for aerospace gauge assemblers outside Asia. Distribution runs through authorized service partners for calibration-intensive applications and direct e-commerce for spare parts procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story where EPA emissions monitoring mandates and OSHA process safety management rules erect barrier-to-entry moats for certified players against uncertified import competition.
For Market Incumbents: Hedge against copper alloy input volatility through captive supply agreements with phosphor bronze foundries or backward integration into sensing element production. Defensive consolidation of regional metrology service networks protects recurring calibration revenue streams from independent lab disintermediation. Channel control through embedded diagnostics subscriptions reinforces switching costs among water treatment utility accounts. For New Entrants and Emerging Players: Enter via India's Jal Jeevan Mission rural pipeline specifications, where digital pressure gauge deployment outpaces established vendor presence. Municipal utilities under CEA water infrastructure mandates represent the most penetrable buyer segment due to unbundled procurement separating hardware from service awards. A go-to-market angle anchored to HART-Modbus hybrid protocol gauges bridges legacy 4-20 mA infrastructure with Ethernet-APL brownfield digitalization budgets. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified industrial conglomerates seeking sensing portfolio expansion, with financial sponsor roll-ups of analog specialists facing consolidation pressure. Long-term viability favors players with backward integration into sensor element production and protocol licensing revenue streams. The signal to watch is ASME B40.1 certification backlog duration as an inflection indicator for compliant capacity scarcity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensor Elements | Captive supply of piezoelectric transducers insulates aerospace gauge assemblers from Chinese module concentration risk. |
| HART-Modbus Protocol Licensing | Hybrid gauge architectures capture brownfield digitalization budgets in 1990s-era hydrocarbon processing facilities. |
| Calibration Service Network Acquisition | Regional metrology lab consolidation recaptures recurring revenue streams fragmented by utility procurement unbundling. |
| India Water Infrastructure Partnership | Jal Jeevan Mission specifications open volume deployment potential in rural pipeline networks beyond established vendor footprints. |
| MEMS-Based Form Factor Reduction | Solid-state miniaturization qualifies next-generation gauges for Boeing and Airbus tier-one flight control programs. |
Research Approach
Document review covered SEC 10-K filings, EPA enforcement actions, and ASME certification databases, complemented by interviews with refinery maintenance directors, municipal water utility procurement officers, and aerospace tier-one supplier quality engineers. Secondary validation drew from customs trade data, ISO 5171 accreditation registries, and OSHA process safety incident reports. Bottom-up gauge shipment analysis triangulated against top-down hydrocarbon processing capital expenditure tracking.
Historical volume trajectories cross-referenced against panel input from plant engineers and aftermarket service heads informed the analytical framework across the projection horizon. Segmentation dimensions modeled include product type tier, end-use vertical, sensing element technology, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted replacement cycle analysis and infrastructure investment pipeline assessment. Industry-specific forecast inputs incorporated EPA mandate compliance deadlines and EU F-Gas Regulation phase-down schedules.
Forecast precision tightens around the base case; tail outcomes carry wider variance under tariff escalation scenarios affecting Chinese sensor module flows or copper alloy price spike conditions. Periodic stress-testing of base assumptions is recommended, particularly around IIoT adoption velocity in water treatment utilities and aerospace program qualification timelines for solid-state architectures.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Global Fluid Management Systems Market
Valves
Aerospace Valves Market
Valves
Emergency Shutdown Valves Market
Valves
Sand Control System Market
Valves
Flare Stack Monitoring Systems Market
Valves
Pinch Valve Market
Valves
Europe Electro Hydraulic Servo Valve Market
Valves
Industrial Hydraulic Filters Market
Valves
Wind Energy Fasteners Market
Valves
Valve Grinder Market
Valves
Deluge Valve Market
Valves
Pipeline Equipment Market
Valves
Global Pressure Relief Valves Market
Valves
Valve Sack Market
Valves
Pneumatic Slide Gates Market
Valves
Global Stainless Steel Control Valves Market