
 Hydrogen Furnace Market | 2026-2036
Hydrogen Furnace Market Size, Share, and Industry Trends Forecast 2026-2036
Hydrogen Furnace Market Insights
German industrial furnace OEMs is pivoting toward hydrogen-ready retrofit architectures. Linde plc leverages its gas supply infrastructure to bundle hydrogen delivery with furnace upgrade contracts. Air Liquide sustains technology leadership through proprietary burner designs optimized for high-hydrogen flame stability. Siemens Energy anchors its position with integrated electrolyzer-to-furnace system configurations for greenfield steel plants.
A hydrogen furnace is a thermal processing system that uses hydrogen as a fuel or protective atmosphere, operating at temperatures from 400°C to over 1,200°C with controlled dew points to prevent oxidation of metal workpieces. These systems serve primarily to anneal, sinter, or braze sensitive alloys where reducing atmospheres eliminate surface defects. Continuous furnace architectures dominate capital deployment in high-volume automotive and aerospace component lines, while batch configurations retain margin pools in specialty alloy and research applications. Green hydrogen fuel type segments attract premium pricing tied to renewable energy certificates, though gray hydrogen still occupies the majority of installed base retrofits due to near-term cost differentials.
EPA emissions standards for industrial heat sources and the EU Green Deal carbon border adjustment mechanism are tightening allowable CO2 intensity for imported treated metals, directly shaping furnace replacement cycles in export-oriented manufacturing. Japan's METI hydrogen roadmap and South Korea's Hydrogen Economy Implementation Plan establish certification pathways that determine which furnace fuel configurations qualify for national subsidies. Stakeholders must monitor evolving hydrogen purity standards and carbon accounting methodologies to align capital commitments with compliance-ready system architectures.
Market Dynamics
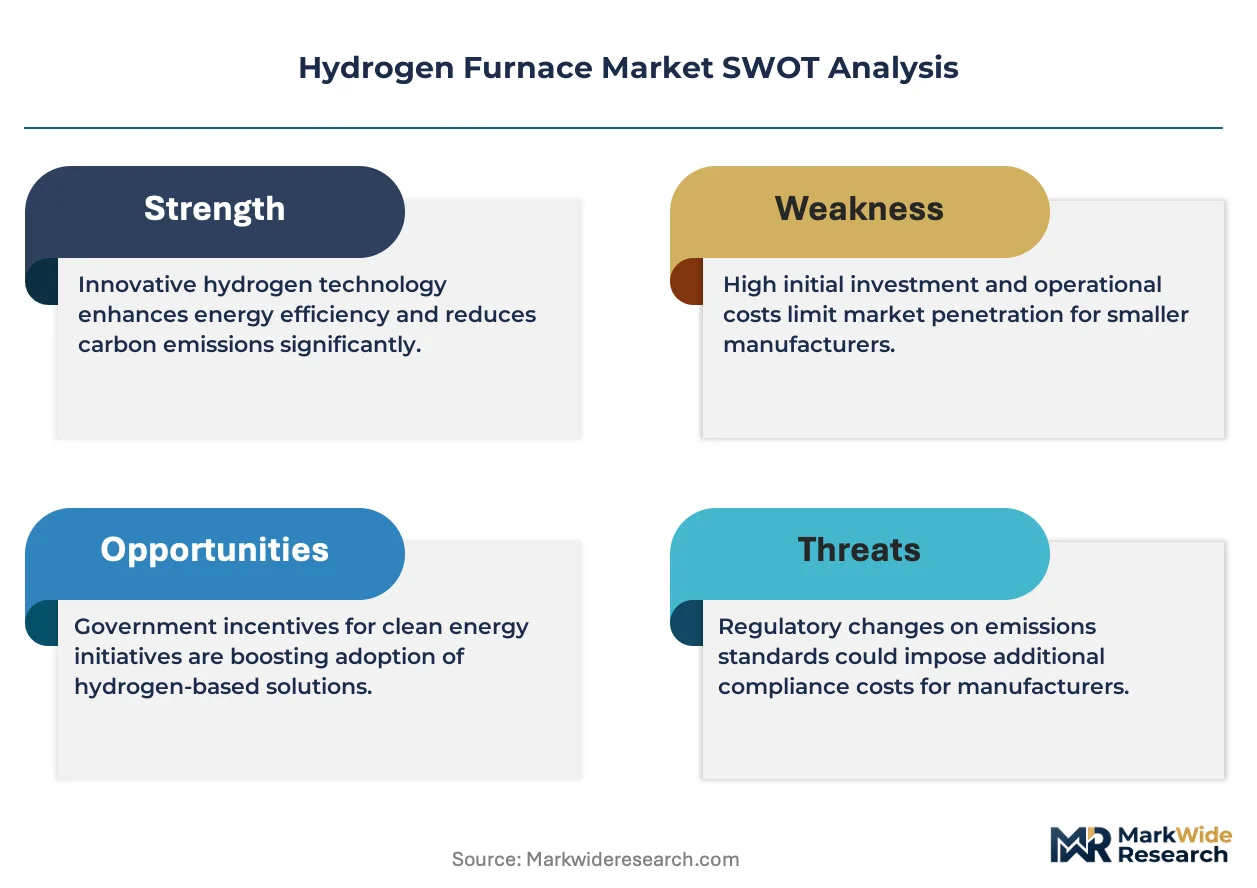
The EU ETS carbon pricing mechanism is compressing furnace replacement cycles as steelmakers face escalating costs for natural gas combustion, forcing capital allocation toward hydrogen-ready thermal systems before 2030 compliance deadlines.
Growth Catalysts
- EU Green Deal CBAM:The carbon border adjustment mechanism penalizes CO2-intensive imported metals, compelling export-oriented German and Italian manufacturers to retrofit hydrogen furnaces for compliance.
- Automotive lightweighting:Electric vehicle battery enclosure producers in South Korea require hydrogen annealing for high-strength aluminum alloys to meet crash safety specifications.
- Green hydrogen certification:Renewable energy certificate schemes in Japan and Germany create premium fuel tiers that justify furnace upgrade investments through operational carbon accounting.
Market Restraints
- Electrolyzer supply concentration:Proton exchange membrane stack production clusters in specific East Asian manufacturing corridors, creating feedstock delivery bottlenecks for furnace operators.
- Flame stability limitations:High-hydrogen combustion exhibits narrower flammability ranges than natural gas, requiring proprietary burner redesigns that extend engineering validation timelines.
- Gray hydrogen cost arbitrage:Steam methane reforming hydrogen retains significant near-term price advantages over electrolytic alternatives, slowing greenfield green hydrogen furnace commitments.
Strategic Opportunities
- India's PLI scheme:Production-linked incentives for specialty steel manufacturing create first-mover advantages for hydrogen furnace OEMs establishing local assembly partnerships.
- Electrolyzer-furnace integration:On-site green hydrogen generation paired with captive thermal processing eliminates transport costs and certificate fragmentation for integrated steel plants.
- Aerospace superalloy demand:Hydrogen sintering of nickel-based turbine blades for next-generation jet engines represents an underpenetrated application with stringent atmosphere purity requirements.
Industry Challenges
- Combustion engineering talent scarcity:Specialized expertise in high-hydrogen flame dynamics remains concentrated among a limited pool of thermal systems engineers, constraining deployment velocity.
- Retrofit integration complexity:Existing continuous furnace lines require extensive refractory, control system, and safety infrastructure modifications to accommodate hydrogen fuel switching.
- Certification timeline compression:Evolving ISO hydrogen purity standards and national safety codes force simultaneous compliance tracking across multiple regulatory frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hydrogen Furnace Market |
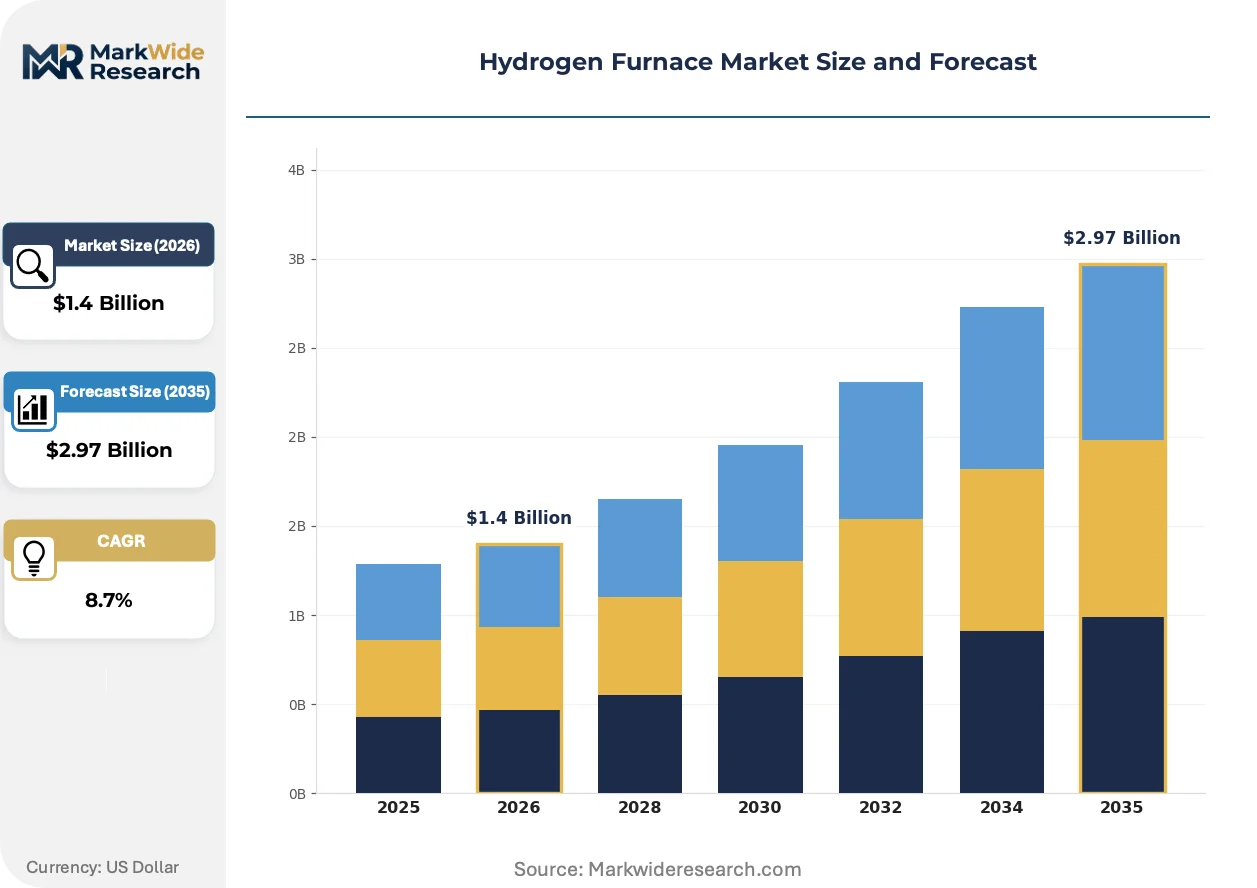
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.97 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Batch Furnaces, Continuous Furnaces, High-Temperature Furnaces, Laboratory Furnaces End User: Manufacturing, Metallurgy, Glass Production, Chemical Processing Fuel Type: Hydrogen Gas, Renewable Hydrogen, Gray Hydrogen, Green Hydrogen Technology: Direct Fired, Electric Arc, Induction Heating, Radiant Tube |
| Companies Covered | Linde plc, Air Liquide, Air Products and Chemicals, Inc., Chart Industries, Siemens Energy, Cummins Inc., Plug Power, ITM Power, McPhy Energy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hydrogen Furnace Market Trends and Innovations
Active research into flame stabilization architectures and modular electrolyzer coupling is compressing the technical validation window for industrial hydrogen combustion, accelerating the transition from pilot installations to production-scale deployment.
Recuperative burner technology with preheated hydrogen combustion air is expanding into high-volume automotive heat treatment lines. Tier-1 suppliers in Germany and Japan are deploying these systems for continuous annealing of electrical steel laminations. The technology is expanding into applications previously reserved for electric furnaces by demonstrating comparable temperature uniformity at lower operational carbon intensity.
The EU F-Gas Regulation phase-down is eliminating hydrofluorocarbon-based atmosphere alternatives for sensitive alloy processing. Industrial heat treaters must now certify hydrogen-based reducing atmospheres for aerospace and medical component specifications. European furnace operators are responding by accelerating burner validation programs to meet 2025 refrigerant transition deadlines.
Buyer consolidation among automotive OEMs is compressing supplier qualification timelines for hydrogen furnace subcontractors. Tier-2 heat treatment service providers in eastern China and South Korea face consolidated procurement panels that demand unified carbon accounting across equipment fleets. Steel component suppliers in these corridors are consolidating furnace maintenance contracts under single-source hydrogen infrastructure providers to meet customer audit requirements.
Hydrogen Furnace Market Segmentation
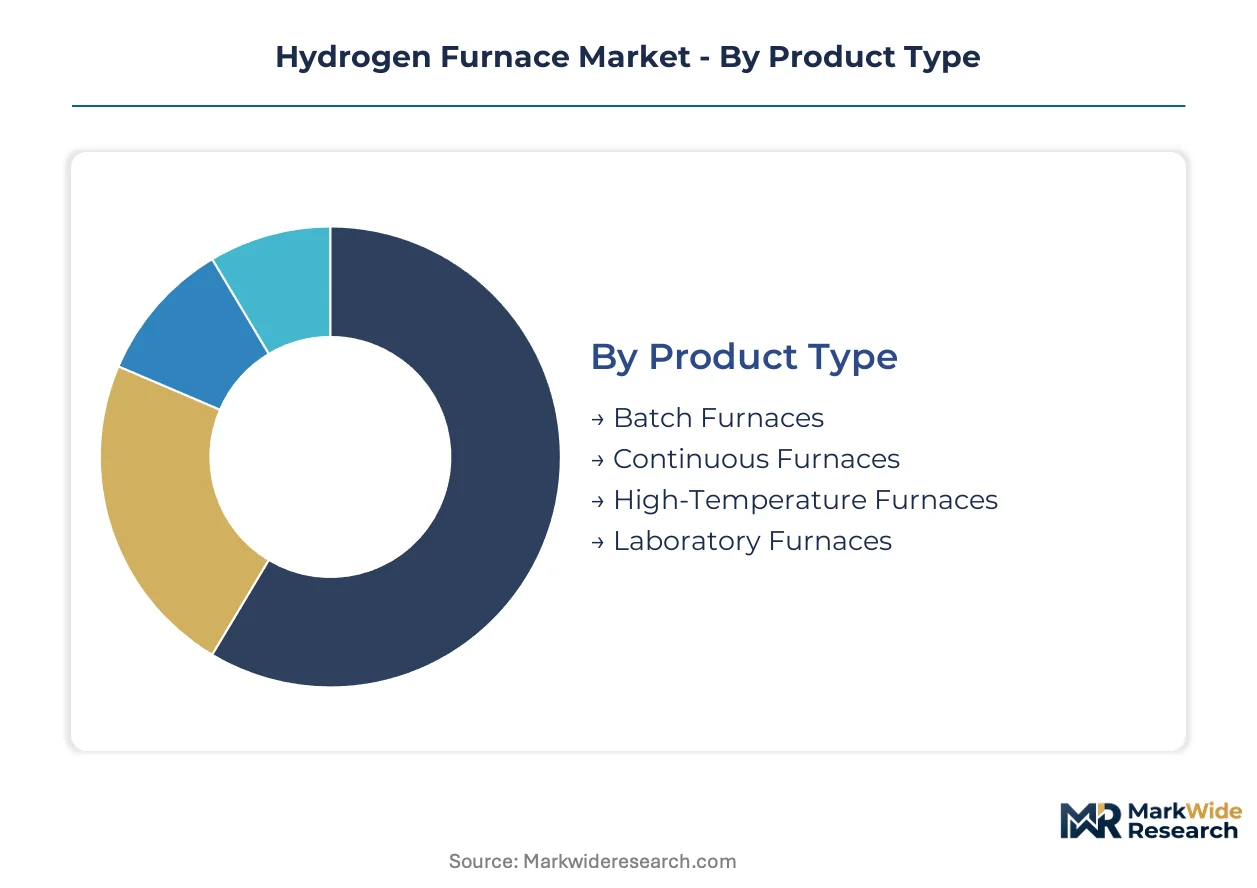
Hydrogen furnace segmentation reveals distinct capital deployment patterns across thermal system architectures and fuel certification tiers. Equipment configuration and hydrogen purity grade together determine compliance eligibility for carbon-accounted manufacturing.
Product Type:
Standalone furnace units dominate high-volume deployment, while integrated thermal processing lines embed hydrogen combustion within continuous production architectures.
- Batch Furnaces:Enclosed chamber designs process discrete workpiece loads with programmable atmosphere cycles, achieving precise dew point control for specialty alloy annealing. German aerospace component suppliers specify these systems for nickel superalloy heat treatment where atmosphere integrity outweighs throughput velocity.
- Continuous Furnaces:Conveyor-based architectures move workpieces through sequential heating zones with minimal thermal cycling, optimizing energy efficiency for automotive electrical steel laminations. South Korean battery enclosure manufacturers deploy these lines to meet consolidated OEM procurement panels demanding unified carbon accounting across supplier fleets.
- High-Temperature Furnaces:Refractory-lined systems exceed 1,200°C for ceramic sintering and powder metallurgy applications requiring extreme thermal envelopes.
- Laboratory Furnaces:Compact benchtop units serve research institutions and pilot-scale alloy development with rapid atmosphere changeover capabilities.
Continuous Furnaces lead volumes today; Laboratory Furnaces are gaining share fastest.
End User:
Cost tier stratification separates capital-intensive integrated steel plants from fragmented subcontract heat treatment service providers.
- Manufacturing:Tier-1 automotive and aerospace component producers operate captive hydrogen furnaces for supply chain control over critical heat treatment stages. Japanese electrical steel laminations for EV motors drive concentrated demand in Nagoya industrial corridors.
- Metallurgy:Integrated steelmakers retrofit existing reheat furnaces with hydrogen-ready burners to comply with EU ETS carbon pricing mechanisms before compliance deadlines. German producers face the most compressed replacement cycles due to escalating natural gas combustion costs.
- Glass Production:Container and flat glass manufacturers evaluate hydrogen melting trials for furnace fuel switching.
- Chemical Processing:Catalyst regeneration and petrochemical crackers require controlled reducing atmospheres for process efficiency.
Metallurgy commands the premium tier; Manufacturing shows the steepest expansion trajectory.
Fuel Type:
Maturity gradients separate established gray hydrogen infrastructure from emerging green hydrogen certification pathways.
- Hydrogen Gas:Undifferentiated industrial hydrogen supply serves early retrofit installations where carbon accounting granularity remains unspecified. Chinese eastern corridor steel plants consume the largest volumes through bundled pipeline delivery arrangements.
- Green Hydrogen:Electrolytic production tied to renewable energy certificates commands premium pricing for export-oriented manufacturers facing EU Green Deal CBAM compliance. German and Japanese subsidy qualification pathways determine which furnace configurations access national support programs.
- Renewable Hydrogen:Biomass-derived hydrogen offers intermediate carbon intensity for jurisdictions with limited electrolyzer infrastructure.
- Gray Hydrogen:Steam methane reforming supply retains near-term cost advantages, slowing greenfield commitments despite carbon intensity penalties.
Hydrogen Gas dominates installed base volumes; Green Hydrogen is climbing the fastest.
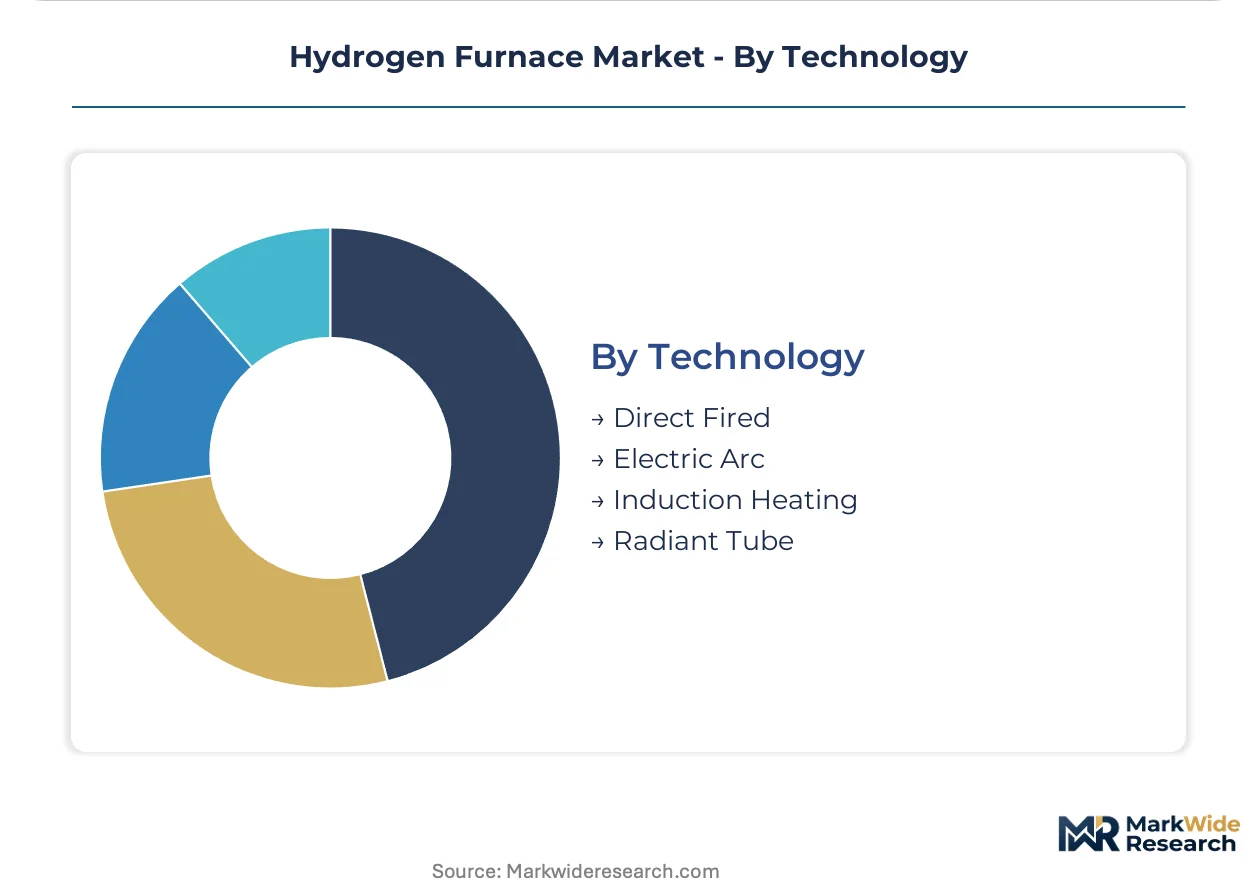
Technology:
Supply concentration in burner engineering expertise shapes competitive positioning across combustion architectures.
- Direct Fired:Open flame hydrogen combustion with preheated air recuperation delivers thermal efficiency for high-volume automotive lines. German OEMs validate these systems for continuous electrical steel annealing previously reserved for electric furnaces.
- Radiant Tube:Indirect heating through alloy tubes separates combustion products from workpiece atmosphere, essential for aerospace superalloy specifications requiring extreme purity. Limited engineering talent pools constrain deployment velocity for these specialized configurations.
- Electric Arc:Plasma-based heating supplements hydrogen combustion in hybrid thermal systems for extreme temperature applications.
- Induction Heating:Electromagnetic workpiece excitation eliminates combustion atmosphere requirements for specific alloy classes.
Direct Fired anchors current deployment; Radiant Tube is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting hydrogen furnace investment toward jurisdictions where carbon border costs and domestic subsidy programs create favorable compliance economics. German and Japanese steelmakers face the steepest retrofit timelines, while Indian and South Korean producers exploit first-mover positioning in emerging certification schemes.
Germany
EU ETS carbon pricing and the Green Deal CBAM are compressing furnace replacement cycles for Ruhr Valley steelmakers. The national hydrogen roadmap channels public finance toward electrolyzer-to-furnace integration projects. Industrial clusters in North Rhine-Westphalia host concentrated pilot deployments of radiant tube architectures for specialty alloy processing.
Japan
METI's hydrogen roadmap establishes certification pathways that determine furnace fuel eligibility for national subsidies. Electrical steel laminations for EV motors drive concentrated demand in Nagoya industrial corridors. Chubu region manufacturers are retrofitting continuous annealing lines to meet consolidated automotive OEM procurement requirements.
South Korea
The Hydrogen Economy Implementation Plan governs which furnace configurations qualify for state support in battery enclosure manufacturing. Ulsan and Gyeonggi Province host tier-1 supplier clusters demanding unified carbon accounting across heat treatment fleets. Domestic steelmakers are bundling hydrogen infrastructure contracts to meet compressed qualification timelines.
China
Dual carbon goals and provincial emissions trading pilots are accelerating furnace upgrades in eastern industrial corridors. The Yangtze River Delta concentration of automotive component producers is driving continuous furnace deployment for high-volume electrical steel processing. Shanghai and Jiangsu Province regulators are tightening hydrogen purity standards for export-oriented manufacturers.
India
The PLI scheme for specialty steel creates procurement incentives for hydrogen furnace OEMs establishing local assembly partnerships. Maharashtra and Gujarat industrial zones are emerging as early adoption corridors for batch furnace retrofits in aerospace component subcontracting. Central government hydrogen mission guidelines are shaping state-level implementation timelines.
Hydrogen Furnace Market Competitive Landscape
German industrial equipment specialists anchor one tier; East Asian electrolyzer-furnace integrators hold emerging positions. The vendor base clusters around gas supply infrastructure bundling, proprietary burner engineering, and captive green hydrogen generation. Three archetypes dominate: industrial gas majors leveraging distribution networks, furnace OEMs pivoting toward hydrogen-ready architectures, and electrolyzer specialists pursuing forward integration. Competitive moves concentrate on strategic partnerships for electrolyzer-furnace coupling and geographic expansion into subsidy-rich jurisdictions.
Among the industrial gas tier, Linde plc and Air Liquide occupy positions exemplifying infrastructure-led market presence. Siemens Energy anchors the integrated systems archetype through electrolyzer-to-furnace configurations. These three entities represent distinct competitive vectors: gas supply bundling, proprietary combustion technology, and captive renewable hydrogen generation.
| Leading Market Players |
|---|
| Linde plc |
| Air Liquide |
| Air Products and Chemicals, Inc. |
| Chart Industries |
| Siemens Energy |
| Cummins Inc. |
| Plug Power |
| ITM Power |
| McPhy Energy |
| Others |
Pricing and Supply Chain Analysis
EU Green Deal CBAM compliance gates both qualified supply and premium-tier pricing access for hydrogen furnace deployments, as German and Japanese steelmakers face escalating carbon border costs that bifurcate equipment procurement between gray hydrogen retrofits and certified green hydrogen systems. This regulatory filter concentrates pricing power among electrolyzer-furnace integrators who bundle renewable energy certificates with thermal system contracts.
Pricing Analysis
Direct-to-OEM discount structures dominate high-volume automotive and steel industry procurement, with project-based pricing for integrated electrolyzer-furnace configurations commanding substantial premiums over standalone equipment sales. Price differentiation hinges on green hydrogen certification tier and burner technology complexity, with radiant tube architectures for aerospace superalloy processing carrying the steepest markups. Cost compression in gray hydrogen retrofits is intensifying because steam methane reforming supply retains near-term cost advantages, making Tier-2 heat treatment service providers in eastern China the most price-sensitive buyer segment while integrated German steelmakers absorb premium pricing for compliance-ready systems.
Supply Chain Analysis
Dual-sourcing requirements from consolidated automotive OEM procurement panels are forcing Tier-1 battery enclosure manufacturers in South Korea to qualify multiple hydrogen furnace suppliers simultaneously. Geographic supply concentration centers on Germany for burner engineering expertise, Japan for electrical steel processing equipment, and China for high-volume continuous furnace fabrication. Raw material dependencies include proton exchange membrane stacks for electrolyzer coupling, specialty refractory alloys for high-temperature zones, and precision control systems for atmosphere regulation. Single-source vulnerability in PEM stack production creates supply chain risk. Distribution runs through bundled gas supply infrastructure contracts led by industrial gas majors with established hydrogen delivery networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EU ETS carbon pricing differentials between German steelmakers and Indian specialty steel producers under the PLI scheme create divergent capital deployment timelines and equipment specification requirements.
For Market Incumbents: Cement technology leadership in radiant tube burner architectures before electrolyzer specialists achieve forward integration into thermal system engineering. Defend against emerging Chinese furnace OEMs by locking in long-term service contracts with German automotive Tier-1 suppliers facing compressed qualification timelines. Prioritize certification investment in ISO hydrogen purity standards to maintain compliance-ready positioning across evolving regulatory frameworks. For New Entrants and Emerging Players: The price-point gap between premium green hydrogen-certified systems and economy gray hydrogen retrofits creates entry space for modular electrolyzer-furnace coupling solutions targeting mid-scale Indian specialty steel producers. India's PLI scheme corridors in Maharashtra and Gujarat represent the most penetrable geography for batch furnace assembly partnerships. Pursue joint venture structures with established industrial gas distributors to bypass captive infrastructure requirements. For Investors and Strategic Acquirers: Roll-up economics work for specialized combustion engineering boutiques because flame dynamics expertise remains concentrated among a limited talent pool with decade-long validation track records. Five-to-ten year viability hinges on electrolyzer cost curves and green hydrogen certificate standardization. Target acquisition archetype: German or Japanese burner technology specialists with established aerospace qualifications. The signal to watch is EU F-Gas Regulation enforcement velocity accelerating hydrogen atmosphere adoption timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Electrolyzer-Furnace Integration | On-site green hydrogen generation eliminates transport costs and certificate fragmentation for integrated steel plants. |
| Radiant Tube Burner Validation | Proprietary flame stabilization designs unlock aerospace superalloy specifications with stringent atmosphere purity requirements. |
| Local Assembly Partnerships | India's PLI scheme creates procurement incentives for OEMs establishing captive manufacturing in Maharashtra industrial zones. |
| Green Hydrogen Certification | Renewable energy certificate bundling justifies premium pricing for export-oriented manufacturers facing EU CBAM compliance. |
| Retrofit Architecture Development | Hydrogen-ready designs for existing continuous furnace lines address compressed replacement cycles for German steelmakers. |
Research Methodology
Multiple input streams — furnace OEM technical documentation, electrolyzer producer supply agreements, and regulatory filing analysis — were reconciled against primary interviews with thermal systems engineers, steel plant procurement directors, and industrial gas supply specialists. Secondary validation drew from EU ETS compliance databases, METI hydrogen roadmap implementation reports, and SEC filings from listed industrial equipment manufacturers. Bottom-up equipment deployment counts were triangulated against top-down carbon pricing impact modeling.
Historical capacity installation patterns were cross-referenced against expert panel assessments of electrolyzer cost trajectory and green hydrogen certificate market development. The analytical framework segmented deployments by furnace architecture, fuel certification tier, end-use industry, and regional regulatory cluster across the projection horizon. CAGRs were derived from equipment replacement cycle compression under escalating carbon border costs and subsidy program eligibility windows. Industry-specific forecast inputs included automotive electrical steel demand curves and aerospace superalloy processing specifications.
The model assumes a particular technology adoption path; alternative pathways for flame stabilization architectures or electrolyzer-furnace coupling configurations would alter the outlook. Deviation in EU Green Deal CBAM enforcement timelines or hydrogen purity standard harmonization would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Alternative Fuels
Green Diesel Market
Alternative Fuels
Aviation Biofuels Market
Alternative Fuels
Synthetic Fuel Market
Alternative Fuels
Green Ammonia Gas Market
Alternative Fuels
Global Cellulosic Ethanol Market
Alternative Fuels
Corn-Based Renewable Fuel Market
Alternative Fuels
Renewable Aviation Fuel Market
Alternative Fuels
Alternate Marine Power Market
Alternative Fuels
Green Fuels Market
Alternative Fuels
United States Propane Market
Alternative Fuels
Bio-LNG Market
Alternative Fuels
Lignocellulosic Feedstock-Based Biofuel Market
Alternative Fuels
E-Fuel Market
Alternative Fuels
Alternative Fuels Market
Alternative Fuels
Green Ammonia Market
Alternative Fuels
Renewable Natural Gas Market