
 Greece Wind Energy Market | 2026-2036
Greece Wind Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Greece Wind Energy Market Foresight
Project finance with non-recourse debt structures is narrowing the field of viable developers to those with balance-sheet depth or long-term power purchase agreements. TERNA Energy leverages its integrated construction and operations platform to control project timelines from permitting to grid connection. PPC Renewables anchors its pipeline through state-backed land access and existing transmission relationships. Iberdrola Rokas competes by importing Spanish offshore expertise into early-stage Aegean projects.
Greece wind energy encompasses the conversion of kinetic wind resources into electrical power through horizontal or vertical axis turbines, typically sited at hub heights of 80-120 meters to capture stronger, more consistent wind regimes above surface friction layers. Onshore systems dominate installed capacity, though offshore systems represent the fastest-growing technology segment as deeper-water floating foundations mature. Utility scale applications lead value creation, while distributed generation segments attract agricultural and island communities seeking energy autonomy. Independent power producers now drive the majority of new capacity additions, displacing traditional utility-led procurement models.
The Regulatory Authority for Energy, Waste and Water (RAE) administers competitive auction rounds that set reference prices and allocate grid capacity, while the Greek grid operator IPTO manages interconnection queues that directly throttle project commissioning timelines. Compliance with EU Green Deal national binding targets and ESEK renewable trajectories shapes licensing velocity and public land access protocols. Stakeholders must monitor auction design changes and transmission investment schedules to align development calendars with regulatory windows.
Market Dynamics
The Greek wind energy sector is being fundamentally restructured by the convergence of EU Green Deal binding targets with the National Energy and Climate Plan's accelerated auction schedule, which compresses development timelines and rewards developers with pre-secured grid interconnection rights.
Growth Catalysts
- ESEK Auction Mechanism:Competitive rounds administered by RAE establish transparent price discovery and allocate scarce transmission capacity, drawing independent power producers into project origination.
- IPTO Grid Expansion:The national grid operator's investment in mainland transmission corridors unlocks wind-rich zones in Thessaly and the Peloponnese for utility-scale development.
- Floating Foundation Maturation:Deeper-water platforms are opening Aegean offshore sites previously inaccessible to fixed-bottom turbines, creating a new technology frontier.
Market Restraints
- Interconnection Queue Bottleneck:IPTO's grid connection backlog extends commissioning timelines by 18-36 months, freezing capital in pre-operational projects.
- Domestic Turbine Supply Concentration:Greece lacks indigenous nacelle manufacturing, exposing developers to euro-denominated import volatility and OEM delivery scheduling.
- Permitting Fragmentation:Archaeological clearance requirements under the Ministry of Culture and regional spatial planning approvals create multi-layered regulatory friction.
Strategic Opportunities
- Cyclades Island Electrification:Non-interconnected island systems offer premium tariffs for wind-diesel hybrid configurations serving tourism and desalination loads.
- Agrivoltaic Wind Pairing:Agricultural landholders in central Greece are leasing marginal terrain for turbine siting while retaining crop cultivation rights beneath access roads.
- Green Hydrogen offtake:The EU Hydrogen Bank and national hydrogen roadmap are creating anchor demand for dedicated wind-to-hydrogen projects in Thrace.
Industry Challenges
- Specialized Installation Labor Scarcity:Crane operators certified for 120-meter hub heights and geotechnical specialists for mountain foundation work command premiums that inflate EPC costs.
- Grid Code Compliance Complexity:IPTO's evolving frequency response and voltage ride-through requirements demand repeated turbine control software upgrades during commissioning.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Greece Wind Energy Market |
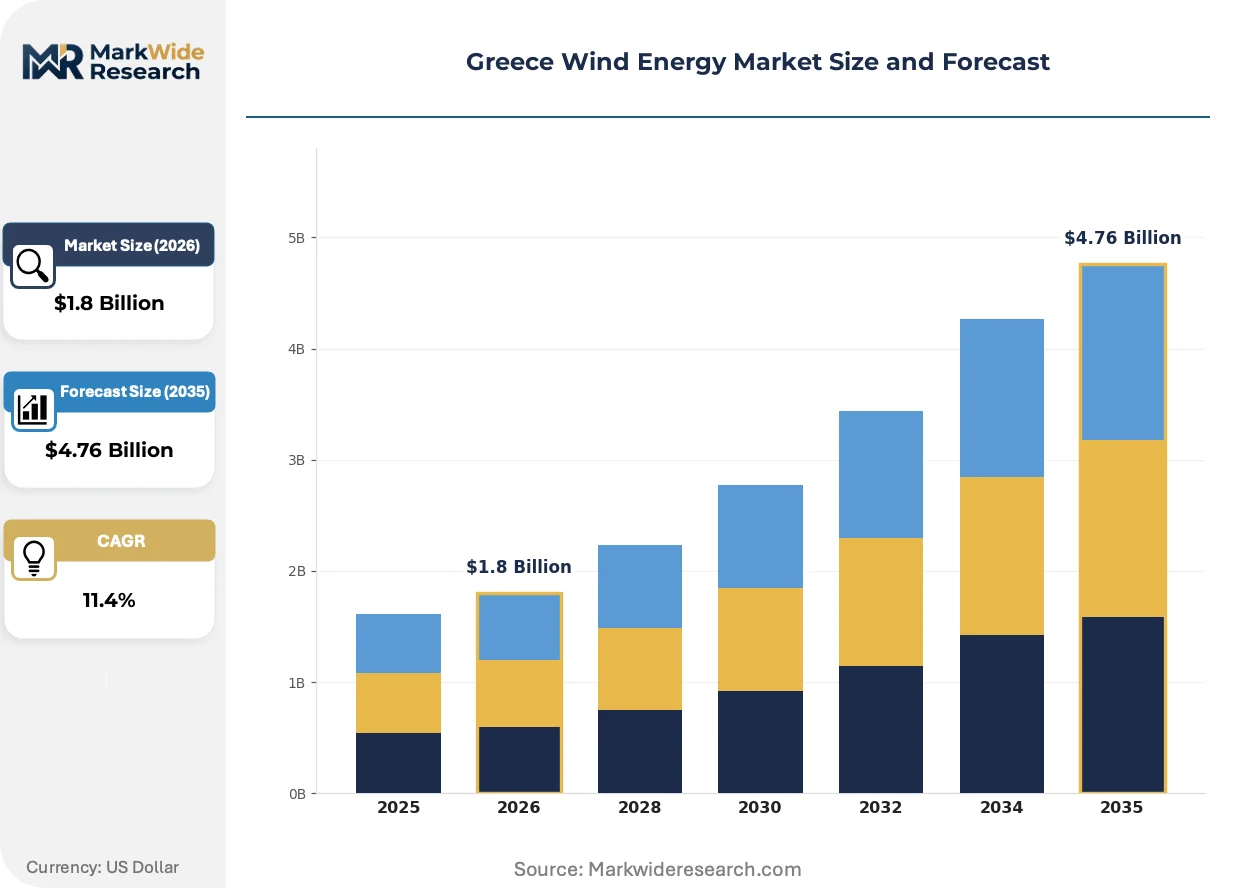
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Horizontal Axis Turbines, Vertical Axis Turbines, Offshore Systems, Onshore Systems Application: Utility Scale, Distributed Generation, Hybrid Systems, Community Wind End User: Utilities, Independent Power Producers, Government, Industrial Users Capacity: Small Scale, Medium Scale, Large Scale, Extra Large Scale |
| Companies Covered | Principia, Total Energies, TERNA Energy, METLEN, EDF Renewables, MORE, PPC Renewables, Jasper Energy, Iberdrola Rokas, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Greece Wind Energy Market Shifts & Advancements
Digitalization and modular system architectures are compressing development cycles and reshaping competitive advantage around data-driven asset management rather than pure scale economics.
Direct-drive permanent magnet generators are collapsing the operations and maintenance cost structure for onshore fleets by eliminating gearbox failure modes. Independent power producers with existing Greek portfolios are retrofitting early-stage geared turbines with this architecture during mid-life overhauls. The technology is collapsing the historical advantage of vertically integrated European OEMs in aftermarket service capture.
The EU Green Deal's national binding targets are accelerating licensing velocity through streamlined environmental assessments for renewable projects. Greece's transposition of the revised Renewable Energy Directive compresses spatial planning approval timelines from 48 to 24 months. Developers are responding by front-loading archaeological and ornithological surveys to secure advance site eligibility certificates.
Corporate renewable energy procurement is displacing traditional utility offtake as the dominant demand formation mechanism. Industrial consumers in aluminum smelting and cement manufacturing are executing direct power purchase agreements with wind developers to hedge against wholesale price volatility. This pattern is most pronounced in the industrial zones of Boeotia and Phthiotis, where energy-intensive plants cluster near transmission substations.
Greece Wind Energy Market Segmentation
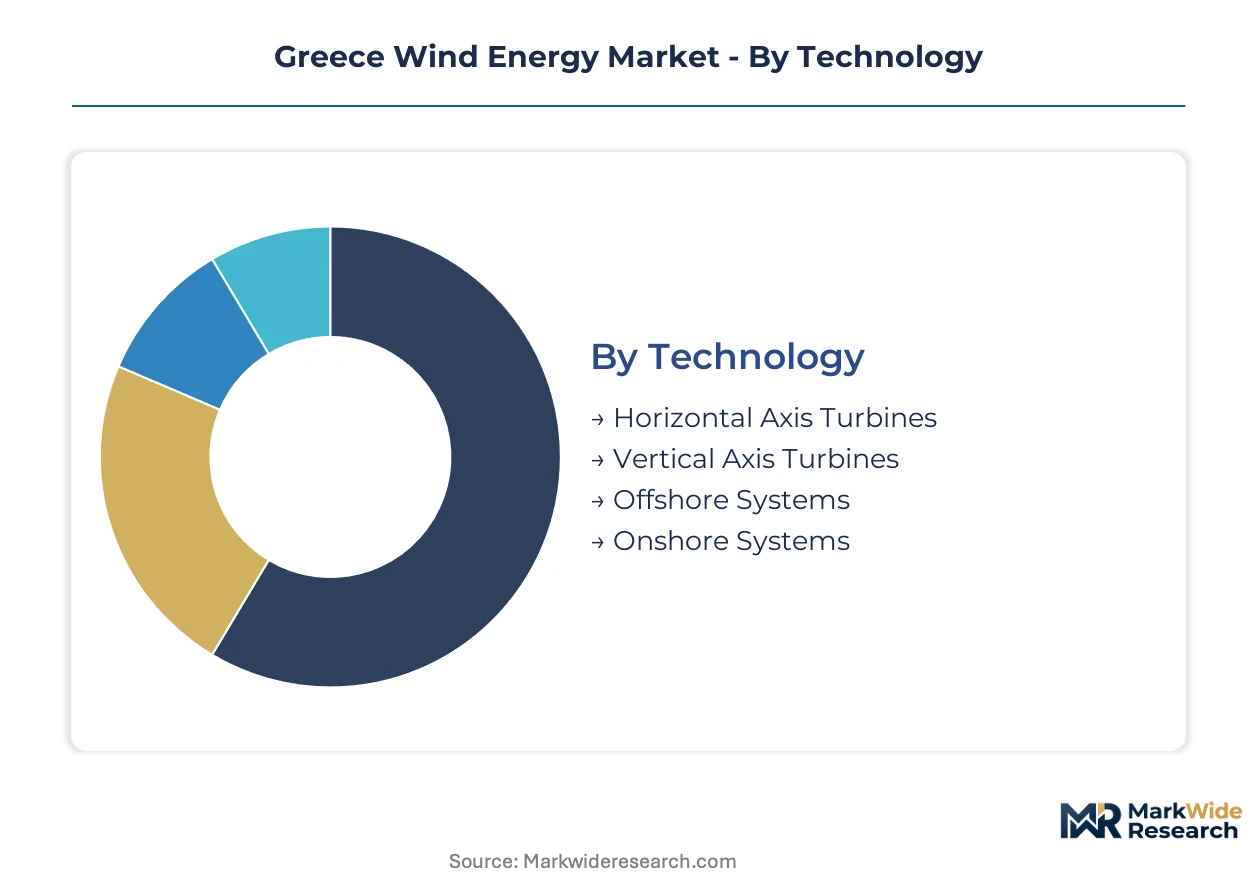
Segmentation in the Greece wind energy market reveals how technology choices, application scales, and customer types distribute capital deployment across mainland and island geographies. Understanding these divides clarifies where auction mechanisms, grid constraints, and financing structures concentrate competitive advantage.
Technology:
Technology selection spans the use-case spectrum from proven onshore architectures to experimental floating platforms requiring specialized marine engineering.
- Horizontal Axis Turbines:Three-blade upwind configurations dominate Greek installations, with hub heights of 80-120 meters capturing stronger wind regimes above surface friction layers. Demand concentrates in Thessaly and the Peloponnese, where IPTO transmission expansion unlocks utility-scale procurement by independent power producers seeking non-recourse debt structures.
- Offshore Systems:Fixed-bottom and floating foundation technologies target Aegean sites with water depths exceeding 50 meters. Development clusters around Cyclades and Crete, driven by EU Hydrogen Bank alignment for wind-to-hydrogen export projects in Thrace.
- Vertical Axis Turbines:Darrieus and Savonius designs serve distributed generation niches in agricultural and island communities. Lower efficiency limits deployment to demonstration projects and educational installations.
- Onshore Systems:Conventional land-based turbines anchor installed capacity, benefiting from established EPC supply chains and faster permitting under ESEK streamlined assessments.
Established volume favors horizontal axis turbines; emerging adoption favors offshore systems.
Application:
Application segmentation tracks how project scale determines offtake structure and regulatory pathway.
- Utility Scale:Projects exceeding 50 MW capacity connect to IPTO's national transmission network, securing RAE auction reference prices. These developments concentrate in central Greece, where grid corridors and wind resource overlap.
- Distributed Generation:Sub-1 MW installations serve agricultural cooperatives and island municipalities. Premium tariffs in non-interconnected systems drive deployment for tourism and desalination loads in the Cyclades.
- Hybrid Systems:Wind-diesel and wind-battery configurations optimize capacity factors for island grids. The Ministry of Culture archaeological clearance requirements add complexity to siting.
- Community Wind:Cooperative ownership models engage local stakeholders in profit-sharing arrangements. Regulatory frameworks under ESEK support participatory structures in marginal agricultural zones.
Capital deployment tilts toward utility scale for auction access; hybrid systems expand most quickly in island electrification.
End User:
End user categories reflect shifting procurement authority from state utilities to private capital.
- Independent Power Producers:Private developers originate projects through direct power purchase agreements with aluminum smelting and cement manufacturing facilities in Boeotia and Phthiotis. Balance-sheet depth determines auction participation viability.
- Utilities:PPC Renewables anchors pipeline development through state-backed land access and existing transmission relationships. Grid code compliance requirements favor incumbent operational experience.
- Government:Public sector procurement supports research installations and demonstration projects under national hydrogen roadmap alignment.
- Industrial Users:Energy-intensive manufacturers execute corporate renewable PPAs to hedge wholesale price volatility, displacing traditional utility offtake.
Procurement authority concentrates with independent power producers; industrial direct contracting climbs the fastest.
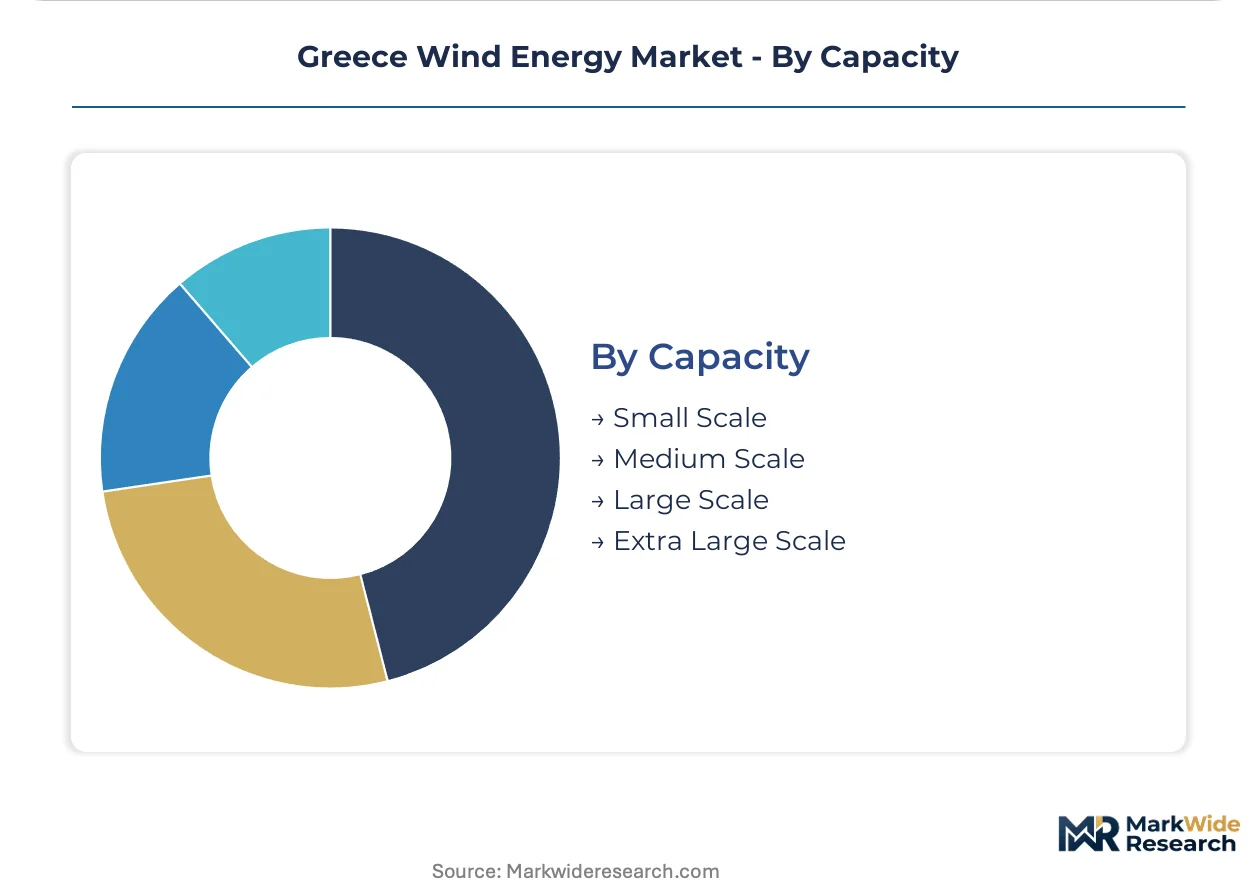
Capacity:
Capacity tiers align project economics with grid connection voltage levels and financing structures.
- Large Scale:50-200 MW developments optimize turbine count against transmission substation capacity. These projects dominate RAE auction rounds and IPTO interconnection queues.
- Extra Large Scale:Exceeding 200 MW, these installations require dedicated transmission infrastructure and multi-year development timelines. Floating offshore platforms in deeper Aegean waters target this tier.
- Medium Scale:10-50 MW projects suit regional distribution networks and agrivoltaic wind pairings on marginal agricultural terrain.
- Small Scale:Below 10 MW, these installations serve community wind and distributed generation segments with simplified permitting.
Grid investment schedules favor large scale capacity; floating foundation maturation drives extra large scale development.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power across Greek wind development tilts sharply toward mainland grid corridors, where IPTO transmission access commands auction premiums, while island projects absorb interconnection cost penalties that compress developer margins.
Thessaly
Wind-rich plains around Larissa and Karditsa attract utility-scale independent power producers seeking 50-200 MW developments. The ESEK auction mechanism administered by RAE allocates scarce transmission capacity through competitive price discovery. TERNA Energy and PPC Renewables concentrate development teams in Trikala to exploit overlapping grid corridors and agricultural land leasing protocols.
Peloponnese
Mountain wind regimes above surface friction layers drive hub heights to 120 meters across Arcadia and Corinthia prefectures. Streamlined environmental assessments under EU Green Deal transposition compress spatial planning timelines from 48 to 24 months. Aluminum smelting facilities in Boeotia execute direct power purchase agreements with Peloponnese developers to hedge wholesale volatility.
Cyclades Islands
Non-interconnected island systems command premium tariffs for wind-diesel hybrid configurations serving tourism and desalination loads on Mykonos and Santorini. The Ministry of Culture archaeological clearance requirements add regulatory friction to siting decisions. Jasper Energy targets this segment with distributed generation portfolios under 10 MW capacity.
Thrace
EU Hydrogen Bank alignment and national hydrogen roadmap implementation create anchor demand for wind-to-hydrogen export projects near Alexandroupoli. Floating foundation maturation opens deeper-water Aegean sites previously inaccessible to fixed-bottom turbines. EDF Renewables positions early-stage developments to capture green hydrogen offtake contracts.
Central Greece
Phthiotis and Evrytania host the densest concentration of grid interconnection queue activity, with IPTO backlogs extending commissioning timelines 18-36 months. Cement manufacturing clusters execute corporate renewable PPAs displacing traditional utility offtake. Iberdrola Rokas imports Spanish offshore expertise into pipeline origination for future floating platform deployment.
Greece Wind Energy Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in the supply chain. The Greek wind sector exhibits moderate consolidation around developers with balance-sheet depth to secure non-recourse project finance. Three archetypes dominate: integrated construction-to-operations platforms, state-affiliated utilities leveraging land access, and international entrants importing offshore expertise. Competitive moves center on auction pre-qualification through grid interconnection rights acquisition and strategic land leasing ahead of regulatory windows.
Among integrated platform operators, TERNA Energy exemplifies the construction-through-operations archetype, while PPC Renewables anchors state-backed development through transmission relationships. Iberdrola Rokas occupies the international specialist tier, representing Spanish offshore technology transfer into Aegean markets. These three entities collectively illustrate how capital structure and regulatory access determine auction participation viability.
| Leading Market Players |
|---|
| Principia |
| Total Energies |
| TERNA Energy |
| METLEN |
| EDF Renewables |
| MORE |
| PPC Renewables |
| Jasper Energy |
| Iberdrola Rokas |
| Others |
Supply & Pricing Matrix
Euro-denominated nacelle import volatility compresses developer margins across all three pricing tiers while simultaneously reshaping procurement toward long-term OEM framework agreements and local EPC capability builds. This currency exposure dictates both the premium commanded by balance-sheet-strong developers and the supply chain's migration toward euro-hedged contracting structures.
Pricing Analysis
Industrial OEM buyers anchor contract-based long-term offtake structures that dominate Greek wind development, with pricing stratifying across premium, standard, and economy tiers based on turbine hub height certification and after-sales service bundling. Premium tiers capture 120-meter hub height installations with comprehensive O&M contracts, while economy tiers absorb older geared turbine retrofits with limited warranty coverage. Cost compression in the standard tier is intensifying because Iberdrola Rokas and TERNA Energy are front-loading archaeological surveys to accelerate site eligibility, compressing development timelines and passing savings through competitive auction bids. Cement manufacturers in Phthiotis exhibit the highest price sensitivity due to thin commodity margins, whereas aluminum smelters in Boeotia prioritize grid stability over tariff minimization.
Supply Chain Analysis
Permanent magnet rare earth feedstock draws from Chinese processing facilities and Australian mining operations, with nacelle assembly concentrated in Germany, Denmark, and Spain. Blade manufacturing rests on epoxy resin and carbon fiber imports, while tower steel production sources from Turkish and Italian rolling mills. Single-source vulnerability concentrates in Chinese rare earth separation capacity, exposing developers to export quota disruptions. Distribution runs through Piraeus port logistics corridors and overland heavy-haul routes to Thessaly and Peloponnese project sites, with IPTO grid connection queues acting as the final downstream chokepoint.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Procurement authority is concentrating among independent power producers with balance-sheet depth, fragmenting traditional utility-led demand formation and shifting price-setting power toward developers with pre-secured interconnection rights.
For Market Incumbents: Harden auction participation viability through captive control of geotechnical specialist labor pools and crane operator certification programs, addressing the specialized installation labor scarcity that inflates EPC costs. Deepen backward integration into grid interconnection rights acquisition by pre-leasing transmission capacity ahead of RAE auction windows, neutralizing the 18-36 month IPTO queue bottleneck that freezes competitor capital. For New Entrants and Emerging Players: Cyclades island electrification offers the most penetrable white-space target, where wind-diesel hybrid configurations for tourism and desalination loads command premium tariffs outside national auction mechanisms. Non-interconnected systems in the Aegean bypass IPTO queue congestion entirely. Agrivoltaic wind pairing on marginal Thessaly agricultural terrain provides a second entry vector through cooperative land-leasing structures with lower archaeological clearance friction. For Investors and Strategic Acquirers: Construction-through-operations platform operators with integrated EPC capabilities represent the optimal acquisition archetype, capturing margin that otherwise leaks to third-party contractors. Long-term viability hinges on exposure to floating foundation maturation and green hydrogen offtake alignment in Thrace. Monitor EU Hydrogen Bank disbursement velocity as the inflection indicator for dedicated wind-to-hydrogen project finance availability.| Strategic Initiative | Industry Significance |
|---|---|
| Grid Interconnection Rights Pre-Acquisition | Secures IPTO queue position ahead of RAE auction rounds, compressing development timelines for TERNA Energy and PPC Renewables. |
| Floating Foundation Technology Licensing | Transfers Spanish offshore expertise into Aegean deep-water projects, positioning Iberdrola Rokas for extra large scale developments. |
| Green Hydrogen offtake Partnership | Creates anchor demand for Thrace wind-to-hydrogen exports under EU Hydrogen Bank alignment, de-risking project finance. |
| Archaeological Survey Front-Loading | Accelerates site eligibility certification under ESEK streamlined assessments, cutting spatial planning timelines from 48 to 24 months. |
| Direct-Drive Retrofit Service Capture | Collapses historical OEM aftermarket advantage by retrofitting geared turbines with permanent magnet generators during mid-life overhauls. |
Research Methodology
The analysis maps horizontal axis turbine deployments, offshore floating platforms, and distributed generation systems, each validated through IPP project developers, EPC contractors, IPTO grid planning officers, and RAE regulatory affairs specialists. Primary interviews with utility procurement leads and aluminum smelter energy managers combined with secondary validation against IPTO interconnection queue databases, RAE auction round results, EU Green Deal national target filings, and ESEK policy transposition documents. Bottom-up project pipeline aggregation triangulates against top-down national renewable capacity targets.
Assumptions held fixed include EU Green Deal binding target trajectories and ESEK auction mechanism continuity, while variables included IPTO transmission investment pacing and floating foundation cost decline curves. The modeling framework segments by technology type, application scale, end-user procurement authority, and capacity tier, with CAGRs derived from project finance closure velocity and grid connection commissioning rates. Forecast inputs incorporated turbine OEM delivery schedules and euro-denominated equipment import cost trajectories.
Practitioners should monitor IPTO grid expansion budget allocations and EU Hydrogen Bank disbursement schedules for early signals of capacity deployment acceleration or deceleration. Forecasts reflect held assumptions about regulatory mechanism stability and currency hedging availability. Cross-checking against IEA national renewable statistics and WindEurope installation databases is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wind Energy Systems
Wind Turbine Gearbox Vibration and Condition Monitoring Test Platforms Market
Wind Energy Systems
Wind Turbine Tower Market
Wind Energy Systems
Wind Turbine Gearbox Market
Wind Energy Systems
Quiet Wind Turbine Market
Wind Energy Systems
Global Wind Power Equipment Market
Wind Energy Systems
Spain Wind Energy Market
Wind Energy Systems
Wind Turbine Pitch Systems Market
Wind Energy Systems
Wind Tower Market
Wind Energy Systems
Bladeless Wind Turbines Market
Wind Energy Systems
Wind Turbine Cables Market
Wind Energy Systems
Wind Blades NDT Market
Wind Energy Systems
Global Marine Wind Turbine Market
Wind Energy Systems
Wind Speed Alarm Market
Wind Energy Systems
Global Small Wind Market
Wind Energy Systems
Belgium Wind Energy Market
Wind Energy Systems
Wind Turbine Gearbox and Direct Drive Systems Market