
 Actuators and Valves Market | 2026-2036
Actuators and Valves Market Size, Share, and Industry Trends Forecast 2026-2036
Actuators and Valves Market Analysis
The actuators and valves supply base is pivoting between precision-engineered smart systems and cost-optimized commodity hardware. Emerson Electric Co. leverages its automation platform to anchor premium positioning in integrated process control. Flowserve Corporation competes through specialized severe-service valve portfolios for oil and gas extremes. Rotork plc differentiates via electric actuator leadership in hazardous-environment applications.
Actuators and valves are electromechanical or fluid-power devices that modulate, isolate, or regulate process flows through torque-rated stem movement, pressure-rated sealing surfaces, and position-feedback instrumentation, serving critical functions across energy, chemical, and built-environment systems. Electric actuators now lead technology investment as facilities prioritize precise digital positioning over pneumatic alternatives. Control valves capture concentrated margin pools in process control applications where leakage tolerance approaches zero. Automated systems are displacing manual technology fastest in power generation retrofits where remote operability reduces outage exposure.
The EPA enforces methane leak detection and repair mandates that compel valve replacement cycles in US hydrocarbon infrastructure. REACH and the EU F-Gas Regulation impose material and emissions standards that reshape European product specifications and supplier qualification requirements. Stakeholders must weigh regulatory compliance timelines against the capital cost of smart actuator migration.
Market Dynamics
The actuators and valves sector faces a structural pivot as electric actuator architectures displace pneumatic systems across process-intensive facilities, compressing maintenance cycles while elevating precision requirements for stem positioning and feedback instrumentation.
Growth Catalysts
- EPA methane mandates:Leak detection and repair rules compel valve replacement cycles across US hydrocarbon gathering and transmission infrastructure.
- Germany's industrial corridor:Automation retrofits in chemical processing and power generation concentrate capital deployment for smart actuation systems.
- Digital positioning protocols:Electric actuators with integrated diagnostics enable predictive maintenance, reducing unplanned outage exposure in continuous-process plants.
Market Restraints
- Stainless steel input volatility:Fluctuations in nickel and chromium prices compress margin stability for severe-service valve manufacturers.
- Specialized foundry concentration:High-grade casting capacity clusters in select European and East Asian supplier bases, creating chokepoints for critical valve bodies.
- REACH material compliance:Restrictions on certain sealing compounds and coatings force reformulation cycles that extend product qualification timelines.
Strategic Opportunities
- Carbon capture integration:Supercritical CO2 handling requirements create specification gaps that actuator and valve suppliers can fill with corrosion-resistant designs.
- Hydrogen infrastructure buildout:Embrittlement-resistant materials and high-pressure sealing technologies open new product categories for energy transition projects.
- Remote operability unbundling:Cloud-based actuator monitoring services create recurring revenue streams separate from hardware sales.
Industry Challenges
- Mechatronics talent scarcity:Cross-functional engineers fluent in both mechanical sealing and embedded electronics command premium compensation, constraining R&D throughput.
- SIL certification timelines:Safety integrity level validation for hazardous-environment electric actuators extends development cycles by months.
- Legacy system integration:Retrofitting smart positioners onto existing pneumatic infrastructures without process disruption demands specialized field engineering.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Actuators and Valves Market |
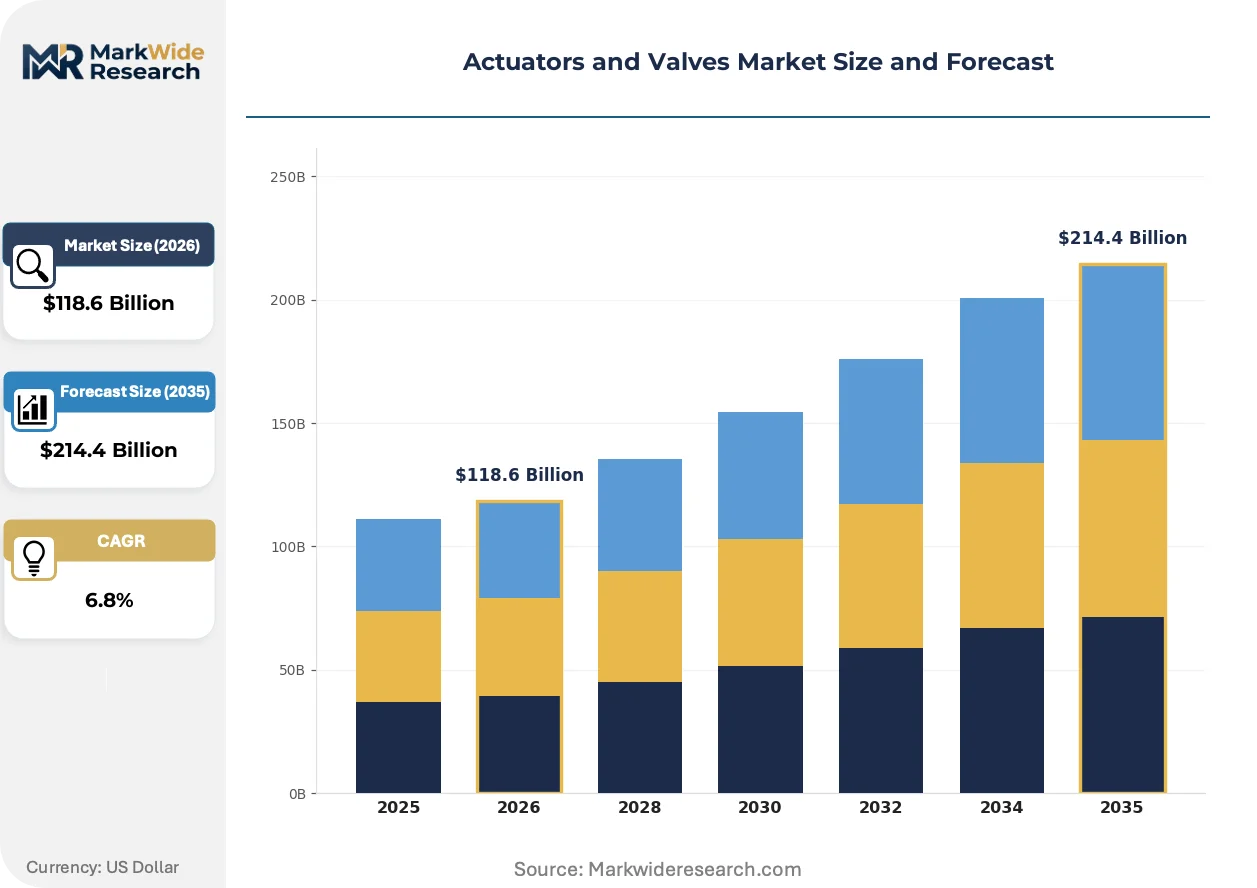
| Market Size in 2026 | $118.6 Billion |
| Market Size in 2035 | $214.4 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pneumatic Actuators, Electric Actuators, Hydraulic Actuators, Control Valves End User: Aerospace, Automotive OEMs, Oil & Gas, Chemical Processing Technology: Smart Technology, Manual Technology, Remote Control, Automated Systems Application: Process Control, Fluid Handling, HVAC Systems, Power Generation |
| Companies Covered | Emerson Electric Co., Flowserve Corporation, IMI plc, Crane Holdings, Co., Rotork plc, Schlumberger Limited, Parker-Hannifin Corporation, Alfa Laval AB, Metso Oyj, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Actuators and Valves Market Emerging Trajectories
Electrification of final control elements is compressing the traditional divide between mechanical valve hardware and digital automation platforms, forcing suppliers to rearchitect around data-centric value propositions.
Intelligent electric actuators with onboard edge computing is decentralizing control-loop architecture away from centralized distributed control systems. Chemical processing facilities in the US Gulf Coast are deploying these units at scale. The shift reduces wiring density while enabling faster loop response times.
REACH and the EU F-Gas Regulation are tightening material specifications for sealing technologies and refrigerant-handling valves. European process OEMs now qualify suppliers against updated substance restriction lists. The compliance burden falls heaviest on mid-tier valve manufacturers serving multiple end-use verticals.
Asset-as-a-service contracting is reshaping how operators acquire actuation systems. Energy majors in Norway and the UK North Sea now prefer performance-based agreements covering maintenance and replacement. The model transfers obsolescence risk to suppliers while locking in multi-year revenue visibility.
Actuators and Valves Market Segmentation
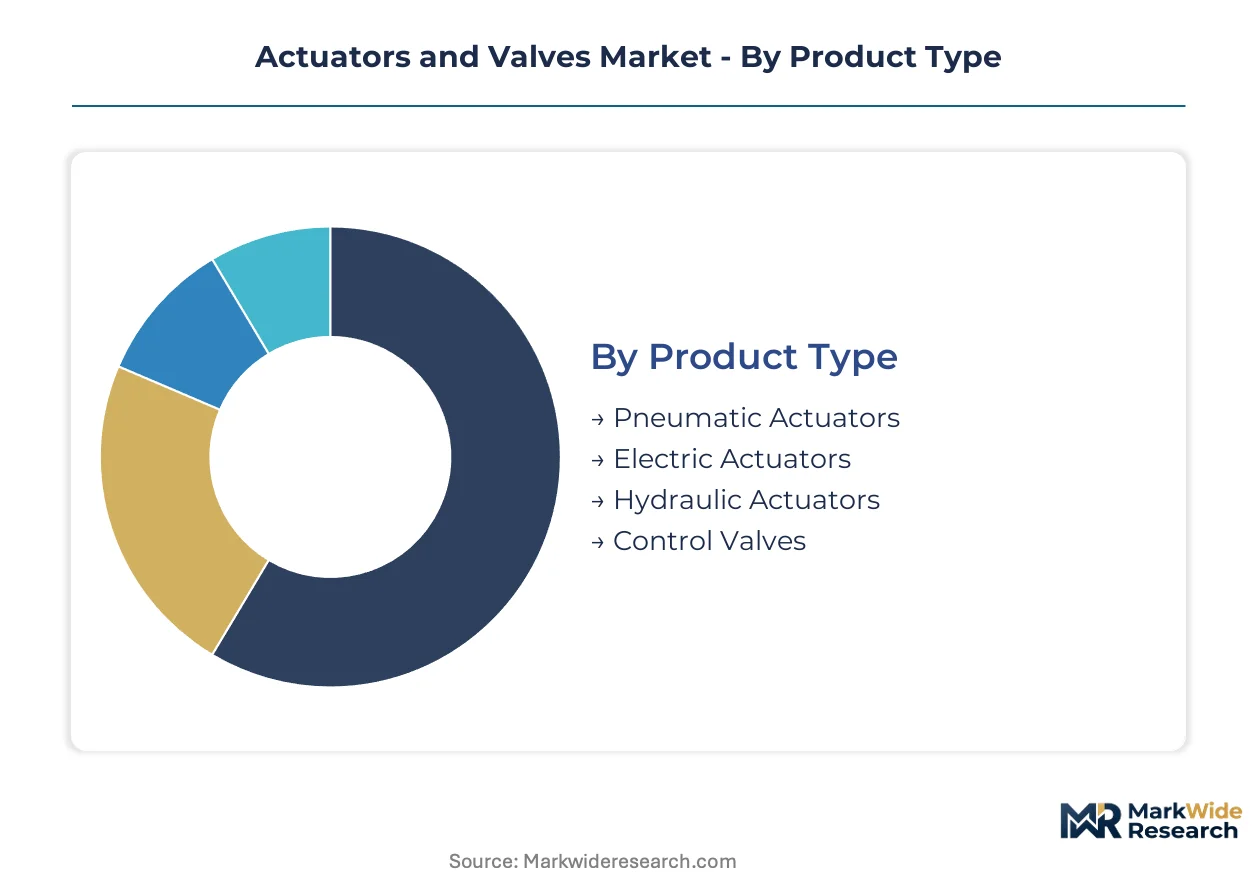
Segmentation in actuators and valves reveals how upgrade cycles and replacement timelines vary sharply across hardware architectures and end-use environments. Facility operators map capital deployment against process criticality, creating divergent demand patterns within each category.
Product Type:
Replacement cycles differ fundamentally between pneumatic legacy infrastructure and digitally integrated electric architectures, with upgrade decisions hinging on maintenance burden versus precision requirements.
- Electric Actuators:These units combine brushless DC motors with absolute encoders and integrated variable frequency drives, enabling closed-loop positioning accuracy within 0.1% of full stroke. Demand clusters in Germany's chemical processing corridor where automation retrofits prioritize predictive maintenance capabilities and reduced compressed air dependency.
- Pneumatic Actuators:Diaphragm and piston designs using instrument air at 20-100 psi dominate established installations requiring simple on/off or modulating control without electrical classification complexity. Oil and gas gathering systems across US shale basins sustain replacement demand as EPA methane rules force valve cycling upgrades on existing pneumatic infrastructures.
- Hydraulic Actuators:High-force linear and quarter-turn designs utilizing mineral oil or synthetic fluid power serve subsea and severe-service applications requiring torque outputs exceeding electric motor practical limits.
- Control Valves:Globe, butterfly, and ball configurations with characterized trim designs modulate flow coefficients across pressure differentials, anchoring process control loops in continuous manufacturing.
Volume placements concentrate in Pneumatic Actuators; the faster expansion belongs to Electric Actuators.
End User:
Capital intensity and regulatory exposure create tiered purchasing patterns, with process industries outspending discrete manufacturing on a per-facility basis.
- Oil & Gas:Upstream production, midstream transmission, and downstream refining operations deploy severe-service valves and explosion-proof actuators across wellheads, compressor stations, and fractionation trains. US Gulf Coast infrastructure faces accelerated replacement timelines under federal methane monitoring mandates.
- Chemical Processing:Continuous reactors, distillation columns, and material handling systems require corrosion-resistant alloys and tight shutoff classifications. German Rhineland petrochemical complexes drive specification intensity for smart positioners with FOUNDATION Fieldbus or PROFIBUS integration.
- Aerospace:Fuel systems, environmental controls, and flight surface actuation demand lightweight titanium or aluminum constructions with MIL-SPEC qualification and traceable material certification.
- Automotive OEMs:Paint shop robots, stamping press hydraulics, and engine test stands utilize standardized pneumatic and electric actuators with automotive industry delivery reliability requirements.
Procurement volumes peak in Oil & Gas; Chemical Processing claims the steepest technology upgrade trajectory.
Technology:
Control architecture migration from centralized to edge-computing models reshapes how operators specify intelligence distribution across valve populations.
- Smart Technology:Embedded microprocessors, non-intrusive diagnostics, and digital position feedback enable condition-based maintenance and automatic configuration. Norwegian North Sea operators specify these for unmanned platform applications where remote monitoring reduces helicopter logistics.
- Automated Systems:Integrated valve-actuator packages with safety instrumented system compatibility execute emergency shutdown sequences within specified safety integrity level time constraints.
- Remote Control:Hardwired or wireless actuator command interfaces extend operator reach into hazardous or inaccessible process areas without local presence.
- Manual Technology:Handwheels, levers, and gear operators provide fallback operation and cost-minimized isolation for non-critical utility services.
Installed base dominance rests with Manual Technology; Smart Technology gains share fastest through brownfield digitization projects.
Application:
Process criticality determines specification grade, with continuous operations commanding premium materials and redundancy features absent in intermittent service.
- Process Control:Throttling services with high-rangeability trim designs maintain loop stability across varying load conditions, capturing concentrated margin pools where leakage tolerance approaches zero. US specialty chemical manufacturers prioritize these for batch reactor temperature control.
- Power Generation:Steam conditioning, feedwater regulation, and turbine bypass systems require rapid stroking speeds and high-temperature metallurgy. Combined cycle plant retrofits in Germany's industrial heartland displace manual isolation with motor-operated valves to reduce outage exposure.
- Fluid Handling:Transfer, loading, and unloading operations utilize standardized on/off valves with moderate pressure ratings and commodity sealing technologies.
- HVAC Systems:Building automation damper actuators and hydronic balancing valves prioritize energy efficiency compliance and BACnet integration over industrial-grade ruggedization.
Revenue concentration sits with Process Control; Power Generation retrofits are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's Rhineland industrial corridor concentrates the heaviest automation retrofit spending, with chemical processors replacing pneumatic infrastructures at scale. The EPA's methane rules are forcing parallel upgrade cycles across US Gulf Coast hydrocarbon infrastructure. Japanese precision manufacturers are advancing electric actuator architectures for semiconductor fabrication tools.
United States
Upstream shale operators and midstream pipeline companies face compressed replacement timelines under EPA methane leak detection mandates. The Infrastructure Investment and Jobs Act directs capital toward modernized compressor stations and gathering systems. Texas Permian Basin facilities are deploying smart positioners with wireless feedback to reduce manual inspection rounds.
Germany
Chemical processing complexes along the Rhine prioritize predictive maintenance capabilities and reduced compressed air dependency in automation retrofits. REACH substance restrictions force reformulation of sealing compounds and coatings, extending supplier qualification timelines. BASF and Bayer Ludwigshafen sites are standardizing on FOUNDATION Fieldbus-integrated electric actuators for distillation column control.
China
Petrochemical expansion in Zhejiang and Jiangsu provinces drives specification intensity for severe-service valves in continuous reactor applications. The Ministry of Ecology and Environment enforces emissions monitoring standards that elevate smart actuator penetration in state-owned refinery upgrades. Ningbo Zhoushan port storage terminals are automating crude transfer operations to reduce outage exposure.
Japan
Semiconductor fabrication equipment manufacturers specify sub-micron positioning accuracy for wafer handling actuators in Kyushu and Hiroshima production hubs. METI's carbon neutrality roadmap accelerates facility electrification, displacing pneumatic systems in precision manufacturing. Yokohama-based process OEMs are qualifying domestic suppliers against updated material traceability protocols.
United Kingdom
North Sea energy majors prefer performance-based service contracts covering actuator maintenance and replacement, transferring obsolescence risk to suppliers. The North Sea Transition Authority mandates emissions reduction plans that drive valve upgrade cycles on aging offshore platforms. Aberdeen supply chain clusters are pivoting toward hydrogen infrastructure qualification services.
Actuators and Valves Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across the actuators and valves sector, with integrated automation platforms anchoring premium positioning while specialized component suppliers capture severe-service niches. The vendor base stratifies into three tiers: full-suite automation houses, dedicated valve or actuator specialists, and regional fabrication shops serving maintenance-repair-overhaul demand. Dominant competitive moves include portfolio diversification into adjacent flow control technologies and geographic expansion through local assembly partnerships to circumvent foundry capacity constraints.
Among diversified automation platforms, Emerson Electric Co. and Flowserve Corporation exemplify contrasting strategic archetypes—one leveraging software-anchored integration, the other competing through specialized hardware depth. Rotork plc occupies a distinct position in electric actuator leadership for hazardous-environment applications. These three represent the strategic poles around which mid-tier specialists and regional fabricators organize their competitive responses.
| Leading Market Players |
|---|
| Emerson Electric Co. |
| Flowserve Corporation |
| IMI plc |
| Crane Holdings, Co. |
| Rotork plc |
| Schlumberger Limited |
| Parker-Hannifin Corporation |
| Alfa Laval AB |
| Metso Oyj |
| Others |
Supply Flow & Price Mechanics
Certification-grade divergence between SIL-validated electric actuators and commodity pneumatic hardware manifests in both margin structures and sourcing footprints. Premium-tier suppliers anchor pricing to uptime guarantees and predictive maintenance outcomes, while commodity producers compete on unit economics tethered to foundry capacity in East Asia.
Pricing Analysis
Uptime-based performance contracting anchors value capture for integrated automation platforms serving North Sea energy majors. Three-tier pricing structure across premium, standard, and economy levels separates FOUNDATION Fieldbus-integrated systems from basic modulating actuators and manual isolation valves. Cost compression in standard-tier electric actuators is intensifying because brushless DC motor commoditization erodes hardware differentiation. Chemical processors in Germany's Rhineland corridor exhibit lowest price sensitivity given process-criticality mandates, while fluid handling utilities in emerging markets drive volume at thin margins.
Supply Chain Analysis
Refurbishment flows for severe-service valve bodies create secondary material loops that offset raw nickel and chromium exposure. High-grade casting capacity clusters in Germany, Italy, and Japan, drawing from nickel laterite feedstocks and specialty steel scrap streams. Single-source vulnerability concentrates in European foundries qualified for hydrogen embrittlement-resistant alloys. Distribution runs through OEM-direct channels for project-scale deployments and authorized distributor networks for maintenance-repair-overhaul demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market consolidates around suppliers capable of absorbing REACH compliance costs and SIL certification timelines that exhaust mid-tier balance sheets. Regulatory qualification burdens function as structural filters, forcing asset-light competitors toward niche service roles or exit.
For Market Incumbents: Hedge margin exposure by securing captive foundry capacity in Italy or Japan before nickel price volatility deepens. Prioritize backward integration into high-grade casting rather than relying on spot-market alloy procurement. Defensive patenting around edge-computing actuator architectures limits encroachment from industrial software entrants.
For New Entrants and Emerging Players: Systems integrators serving brownfield digitization projects represent the most penetrable channel for smart positioner penetration without direct manufacturing investment. Target carbon capture retrofit specifications where corrosion-resistant material expertise creates qualification gaps incumbent valve houses fill slowly. White-space exists in cloud-based actuator monitoring services decoupled from hardware ownership.
For Investors and Strategic Acquirers: Re-rating potential sits with electric actuator specialists holding hazardous-area certifications given EPA methane mandates accelerating replacement cycles. Five-to-ten year viability favors suppliers with demonstrated SIL 3 validation pipelines and recurring revenue from asset-as-a-service contracts. Watch for inflection when North Sea operators standardize performance-based contracting terms across platform populations.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into High-Grade Casting | Captive foundry capacity insulates margin stability against nickel and chromium price swings. |
| Edge Computing Actuator Development | Onboard diagnostics enable predictive maintenance contracts with Norwegian North Sea operators. |
| REACH-Compliant Sealing Reformulation | Extended qualification timelines with ECHA create defensive moats against mid-tier competitors. |
| Asset-as-a-Service Contracting | Performance-based agreements transfer obsolescence risk while locking multi-year revenue visibility. |
| Hydrogen Infrastructure Qualification | Embrittlement-resistant material certification opens specification gaps in energy transition projects. |
Methodological Framework
Document review covered EPA enforcement actions, ECHA substance restriction updates, and customs trade flows for valve and actuator classifications, complemented by interviews with plant maintenance directors at German chemical processors, procurement leads at US Gulf Coast midstream operators, and aftermarket service heads at UK North Sea supply bases. Secondary validation drew from FERC infrastructure filings, BASF and Bayer Ludwigshafen automation retrofit disclosures, and Norwegian Petroleum Directorate emissions reports. Bottom-up unit economics triangulated against top-down capital expenditure tracking across the analysis window.
Historical replacement cycle data cross-referenced against panel input from automation engineering directors informed the projection framework. Segmentation dimensions modeled include actuator architecture type, end-use process criticality, technology integration level, and regional regulatory stringency. CAGRs derived from installed base turnover rates and upgrade penetration curves, with specific inputs from methane detection mandate compliance timelines and REACH substance restriction phase-in schedules.
Caveats apply where EPA enforcement intensity or ECHA substance list expansions could materially shift the outlook for replacement demand and supplier qualification burdens. Forecasts reflect assumptions about nickel price stability and foundry capacity expansion that may not hold. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Valves
Global Thermostatic Radiator Valve Market
Valves
Explosion Proof Solenoid Valves Market
Valves
North America Industrial Valves Market
Valves
Europe Industrial Valves Market
Valves
Subsea Valves Market
Valves
Global Globe Valve Market
Valves
Hybrid Valve Market
Valves
Float Traps Market
Valves
Europe Butterfly Valve Market
Valves
Directional Control Valves Market
Valves
Pneumatic Slide Gates Market
Valves
Cathodic Protection Market
Valves
Pneumatic Positioner Market
Valves
Pneumatic Needle Valves Market
Valves
Electrohydraulic Servo Valves (Ehsvs) Market
Valves
Choke and Kill Manifold Market